
 United States Data Center Storage Market | 2026-2036
United States Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
United States Data Center Storage Market Insights
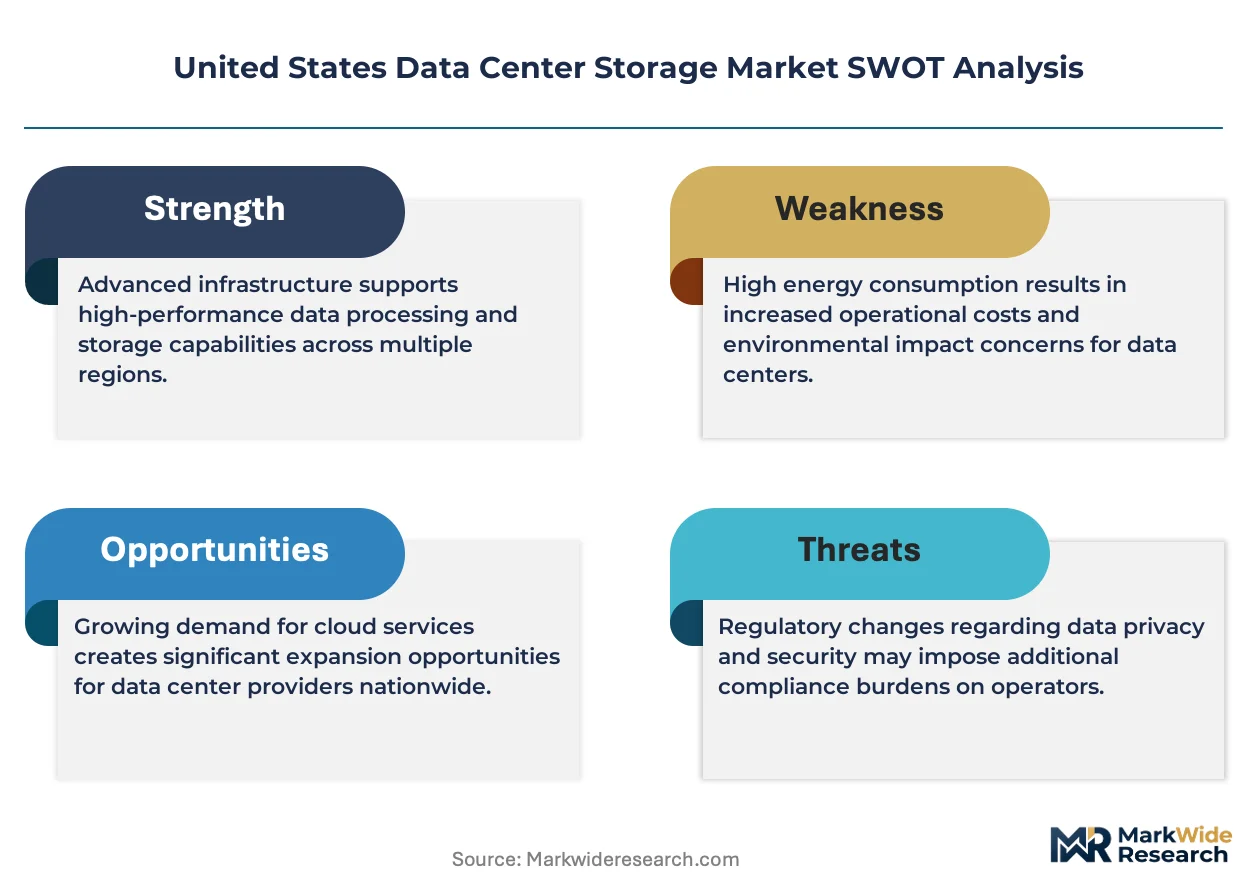
Enterprise procurement channels for data center storage is narrowing as hyperscalers and co-location providers consolidate vendor lists around certified integration partners. Dell Technologies leverages its PowerMax and PowerStore lines to sustain direct relationships with federal integrators. Pure Storage competes through its Evergreen subscription model, while NetApp anchors mid-market hybrid cloud deployments with its ONTAP software-defined stack.
United States Data Center Storage encompasses solid-state, magnetic, and tape-based media systems engineered for 99.999% uptime in climate-controlled facilities, with NVMe-oF fabrics now enabling sub-100-microsecond latency for real-time analytics workloads. Object Storage and NVMe-based arrays represent the fastest-expanding technology segments as AI training pipelines demand exabyte-scale unstructured repositories and flash-tier performance. HDD retains cost dominance in cold-archive tiers where tape libraries face renewed competition from shingled magnetic recording drives.
NIST, FERC, and state-level public utility commissions shape data center storage demand through efficiency mandates, critical infrastructure classification, and grid-interconnection rules that govern power density per rack. The SEC's climate disclosure requirements for publicly traded operators further steer procurement toward energy-efficient SSD and NVMe platforms with verified carbon accounting. Stakeholders must monitor evolving state data privacy laws and EPA carbon intensity benchmarks as these will determine which storage architectures qualify for federal and enterprise contracts.
Market Dynamics
Hyperscale cloud operators in Northern Virginia and Texas are consolidating procurement around certified integration partners, compressing vendor access for mid-tier storage suppliers while federal buyers prioritize NIST-compliant architectures.
Growth Catalysts
- AI Training Clusters:Enterprise demand for exabyte-scale unstructured repositories is pulling NVMe-based flash arrays into hyperscale facilities across Northern Virginia.
- NIST Cybersecurity Framework:Federal integrators now mandate certified storage architectures, creating qualified demand pipelines for compliant vendors.
- State Clean Energy Mandates:Public utility commissions in Texas and California are accelerating procurement of energy-efficient SSD platforms through grid-interconnection rules.
Market Restraints
- NAND Flash Supply Concentration:Fabrication capacity for high-density flash remains concentrated among Asian foundries, exposing buyers to geographic supply risk.
- Power Density Limitations:FERC interconnection standards cap rack-level power draw, constraining deployment of high-performance storage clusters in legacy facilities.
- Tape Archive Substitution:Shingled magnetic recording drives are displacing tape libraries in cold-tier applications, eroding incumbent vendor maintenance revenue.
Strategic Opportunities
- Edge AI Inference Nodes:Latency requirements for real-time analytics are creating distributed storage demand in secondary Texas and Arizona markets.
- SEC Climate Disclosure Alignment:Publicly traded operators must verify carbon accounting for storage infrastructure, favoring vendors with transparent supply chain emissions data.
- NVMe-oF Convergence:The fusion of NVMe fabrics with software-defined storage is opening retrofit opportunities in enterprise data centers running legacy SAN architectures.
Industry Challenges
- Legacy SAN Integration Complexity:Enterprises face protracted migration timelines when bridging fiber-channel storage with modern NVMe-oF fabrics.
- Federal ATO Certification Delays:Storage vendors report 12-18 month authorization timelines under FedRAMP and DoD Impact Level frameworks.
- Specialized Firmware Engineering Talent:The scarcity of engineers fluent in flash translation layer optimization is constraining product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Data Center Storage Market |
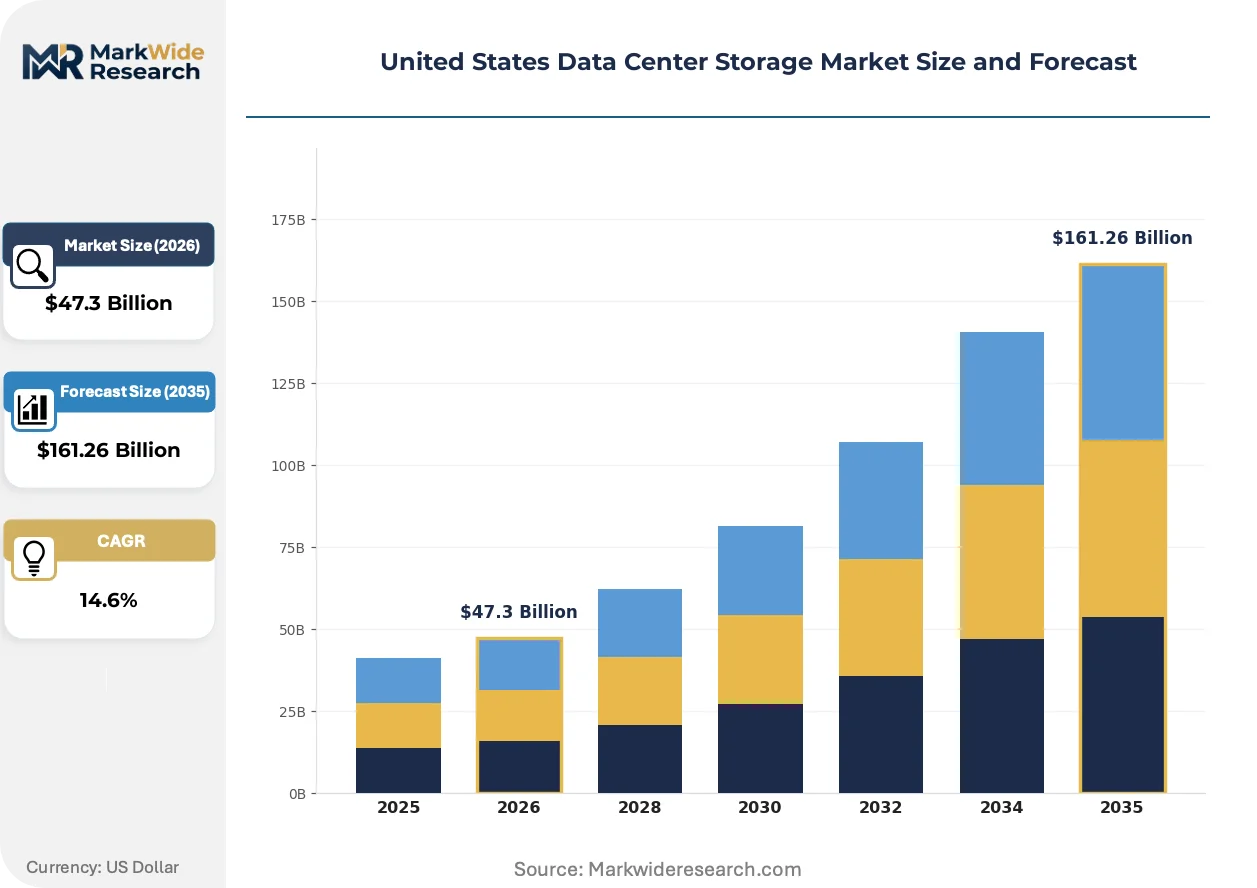
| Market Size in 2026 | $47.3 Billion |
| Market Size in 2035 | $161.26 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Storage Type: DAS, NAS, SAN, Object Storage Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge End User: SMBs, Enterprises, Government, Educational Institutions Technology: HDD, SSD, NVMe, Tape Storage |
| Companies Covered | Dell Technologies, Hewlett Packard Enterprise, NetApp, Hitachi Vantara, Pure Storage, IBM Corporation, Lenovo Group, Cisco Systems, Seagate Technology, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Data Center Storage Market Trends and Innovations
Storage architectures are fragmenting across performance tiers as AI workloads force a bifurcation between sub-100-microsecond flash tiers and exabyte-scale object repositories. This polarization is compressing the middle market for general-purpose arrays.
Computational storage drives with embedded processing capabilities are virtualizing data reduction and encryption functions that previously consumed host CPU cycles. Hyperscale operators in Northern Virginia are deploying these devices at rack scale to reclaim server resources for AI training workloads. The shift is virtualizing traditional host-side storage software stacks into firmware-resident functions.
EPA carbon intensity benchmarks and state-level clean energy mandates are forcing storage procurement toward verified low-carbon SSD supply chains. Federal facility managers must now document embodied emissions for storage hardware under SEC-adjacent disclosure frameworks. The compliance burden falls heaviest on cold-archive tiers where tape and shingled magnetic recording compete on total cost of ownership.
Enterprise buyers are consolidating vendor relationships around subscription-based consumption models that bundle hardware refreshes with operational support. Co-location providers in Texas are displacing traditional capital purchase arrangements with capacity-as-a-service contracts. The pattern is most pronounced among mid-market enterprises lacking dedicated storage engineering staff.
United States Data Center Storage Market Segmentation
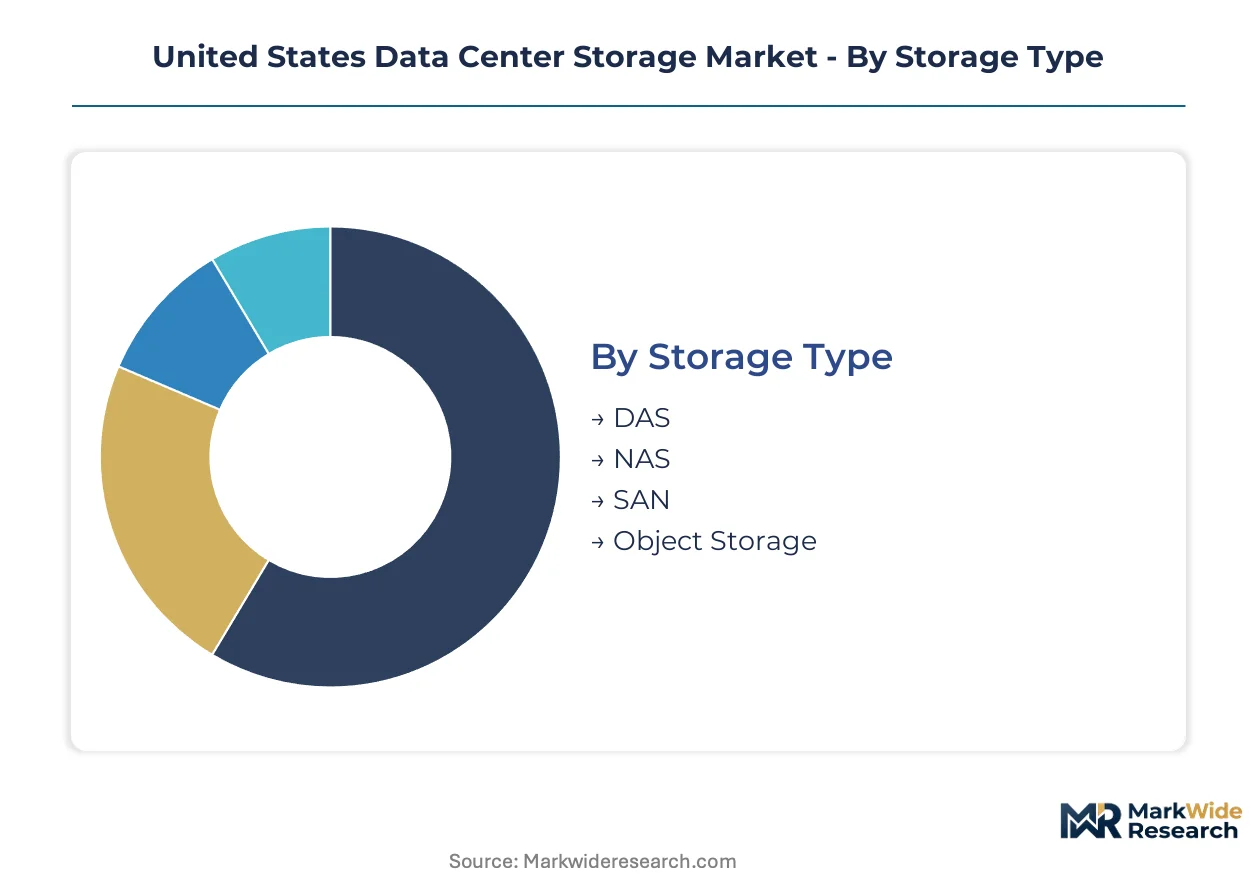
Storage procurement in the United States fragments across architectural, operational, and technological dimensions. Each segmentation axis carries distinct margin profiles, certification requirements, and vendor engagement models that reshape competitive positioning across federal, enterprise, and hyperscale channels.
Storage Type:
After-sales-service intensity varies sharply across storage architectures, with direct-attached systems demanding minimal ongoing support while object storage deployments require continuous software-layer optimization.
- DAS:Direct-attached configurations attach storage media directly to individual servers without network abstraction. Federal AI training clusters in Northern Virginia favor DAS for training node scratch storage where latency tolerance is minimal and cost per terabyte dominates procurement criteria.
- NAS:Network-attached storage delivers file-level access across standard Ethernet fabrics. SMBs and educational institutions in secondary Texas markets deploy NAS for shared research datasets and administrative file services where IT staffing constraints favor plug-and-operate simplicity.
- SAN:Storage area networks provision block-level access through dedicated fiber-channel or iSCSI fabrics. Legacy enterprise data centers maintain SAN investments for transactional databases requiring deterministic I/O performance.
- Object Storage:Flat-namespace architectures scale to exabyte capacity for unstructured data lakes. Hyperscale operators expanding in Northern Virginia and Texas anchor AI training pipelines on object repositories where metadata-rich indexing supports petabyte-scale dataset curation.
DAS holds the largest share; momentum sits with Object Storage.
Deployment Model:
Deployment architecture determines capital flow timing, with on-premises installations consuming upfront balance sheet capacity while cloud-based consumption shifts storage to operational expenditure.
- On-Premises:Owned infrastructure residing in enterprise or colocation facilities. Federal agencies mandate on-premises storage for classified workloads under NIST-controlled unclassified information frameworks, constraining cloud migration for defense and intelligence contracts.
- Cloud-Based:Capacity provisioned through hyperscale provider APIs without physical hardware ownership. Mid-market enterprises lacking dedicated storage engineering staff are consolidating procurement around cloud-based object tiers.
- Hybrid:Synchronized architectures spanning owned and rented infrastructure. Financial services firms deploy hybrid models to retain transaction logs on-premises while bursting analytics workloads to cloud compute.
- Edge:Distributed storage nodes positioned proximal to data generation. Real-time inference requirements in Arizona and Texas secondary markets are pulling NVMe-based edge deployments for manufacturing quality control and autonomous vehicle testing.
Cloud-Based configurations are expanding most quickly; On-Premises retains the revenue base.
End User:
Customer type dictates procurement sophistication, with government buyers imposing certification barriers that filter vendor participation while SMBs prioritize price-optimized bundles.
- SMBs:Organizations below 500 employees with limited IT specialization. These buyers concentrate in standardized NAS and cloud-based tiers where channel partners deliver integrated hardware-support packages.
- Enterprises:Large corporations with dedicated infrastructure teams. Enterprise procurement in Northern Virginia prioritizes NVMe-oF fabrics for AI training clusters while maintaining tape archives for compliance retention.
- Government:Federal, state, and local agencies with mandated security frameworks. NIST cybersecurity compliance and FedRAMP authorization timelines filter vendor access, creating qualified demand pipelines for certified integrators.
- Educational Institutions:Universities and research consortia with grant-funded procurement cycles. These buyers balance cost sensitivity against requirements for petabyte-scale research data repositories in atmospheric modeling and genomics.
Enterprises command the revenue concentration; Government contracts are climbing the fastest.
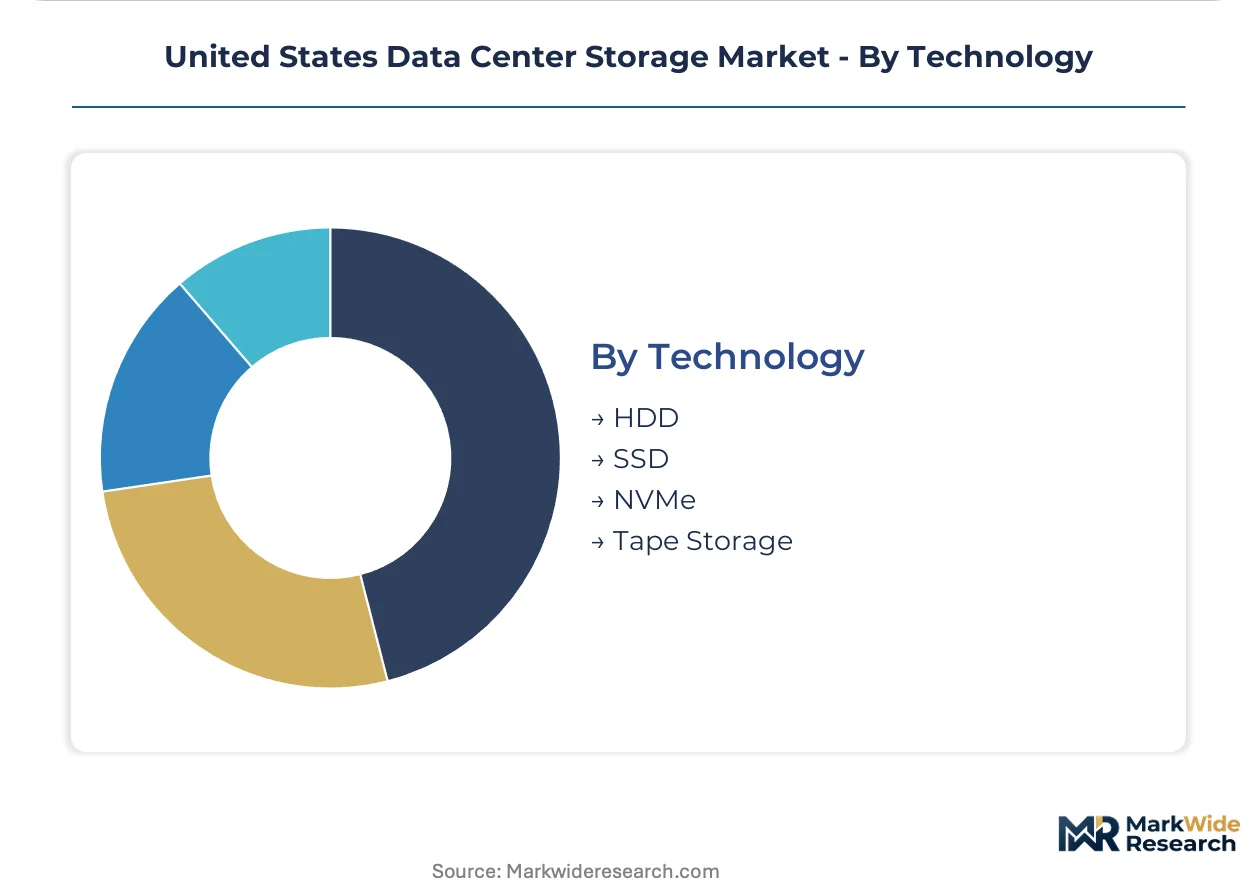
Technology:
Media technology segmentation polarizes between performance-optimized flash tiers and cost-minimized archival media, compressing the middle market for general-purpose hard disk deployments.
- HDD:Shingled magnetic recording and conventional magnetic storage for capacity-optimized tiers. Cold-archive applications in federal records retention favor high-density HDD over tape where retrieval latency requirements exceed robotic library performance.
- SSD:SATA and SAS-interface flash for mainstream enterprise workloads. State clean energy mandates in California and Texas are accelerating SSD procurement through grid-interconnection rules that penalize high-wattage storage deployments.
- NVMe:PCIe-attached flash delivering sub-100-microsecond latency. Hyperscale AI training facilities across Northern Virginia standardize on NVMe for feature extraction pipelines where I/O wait time directly constrains model convergence speed.
- Tape Storage:Linear tape-open and enterprise tape formats for offline air-gapped archives. EPA carbon accounting requirements are eroding tape's historical TCO advantage as vendors struggle to document supply chain emissions for legacy media manufacturing.
HDD retains volume leadership; NVMe is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FERC interconnection standards and state-level clean energy mandates are redirecting data center storage investment toward jurisdictions with favorable grid capacity and renewable energy access. This policy-driven relocation pattern concentrates procurement in states offering streamlined permitting and carbon-compliant power.
Northern Virginia
Hyperscale cloud operators dominate NVMe-based flash procurement for AI training clusters across Loudoun and Prince William counties. State data privacy laws complement federal NIST frameworks in shaping vendor certification requirements. Ashburn-Dulles corridor facilities account for the densest concentration of exabyte-scale object storage deployments in North America.
Texas
ERCOT grid dynamics and Public Utility Commission interconnection rules are accelerating energy-efficient SSD procurement in Dallas-Fort Worth and Austin markets. State-level property tax abatements for data center construction reduce total cost of ownership for flash-tier deployments. Secondary Houston and San Antonio markets are emerging for edge AI inference nodes requiring sub-millisecond latency.
California
California Energy Commission efficiency mandates and CPUC carbon intensity benchmarks steer procurement toward verified low-carbon storage supply chains. Bay Area hyperscale facilities prioritize NVMe-oF fabrics for real-time analytics workloads. Los Angeles basin co-location providers are displacing capital purchases with subscription-based capacity contracts.
Arizona
Desert climate and available land position Phoenix-Tucson corridor for water-efficient cooling designs supporting high-density storage racks. State tax incentives for renewable energy procurement reduce operational expenditure for flash-tier deployments. Edge storage nodes for autonomous vehicle testing and manufacturing quality control are concentrating in Greater Phoenix.
Pacific Northwest
Hydroelectric power access and EPA-favorable carbon intensity ratings attract cold-archive tier deployments across Oregon and Washington. State-level clean energy mandates align with federal procurement preferences for low-emission storage hardware. Portland-Seattle corridor facilities specialize in tape-to-disk migration services for federal records retention contracts.
United States Data Center Storage Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: full-stack infrastructure vendors with federal integration credentials, flash-native specialists with subscription consumption models, and component suppliers with manufacturing scale. Hyperscale procurement compression favors vendors with certified NIST architectures and documented carbon accounting. Dominant competitive moves include strategic partnerships with cloud operators and portfolio diversification into computational storage.
Within the federal-certified tier, Dell Technologies and Hewlett Packard Enterprise occupy positions anchored by direct relationships with defense and intelligence integrators. Pure Storage exemplifies the flash-native archetype through its Evergreen subscription model targeting mid-market enterprises lacking dedicated storage engineering staff. NetApp sits within the hybrid cloud specialist category, anchoring software-defined deployments across financial services and research institutions. These three represent the competitive vectors reshaping vendor access as hyperscalers narrow approved supplier lists.
| Leading Market Players |
|---|
| Dell Technologies |
| Hewlett Packard Enterprise |
| NetApp |
| Hitachi Vantara |
| Pure Storage |
| IBM Corporation |
| Lenovo Group |
| Cisco Systems |
| Seagate Technology |
| Others |
Pricing and Supply Chain Analysis
NAND flash fabrication concentration in South Korean and Taiwanese foundries exposes procurement pipelines to geographic supply risk while simultaneously compressing pricing spreads between certified federal-grade and standard commercial storage tiers. This single-source dependency forces buyers to absorb tariff volatility and currency fluctuation directly, widening the gap between NIST-compliant architectures and commodity flash deployments.
Pricing Analysis
Certification level creates the primary spread between federal-grade and commercial storage tiers, with FedRAMP-authorized arrays commanding substantial premiums over standard enterprise configurations. Three-tier pricing structure across premium NVMe-oF fabrics, standard SAS-attached SSDs, and economy HDD cold tiers reflects performance latency requirements rather than raw capacity. Cost compression in the mid-market HDD segment is intensifying because shingled magnetic recording drives displace tape libraries in federal archive contracts. Government buyers exhibit the least price sensitivity due to mandated security frameworks, while mid-market enterprises lacking dedicated storage engineering staff drive hardest bargain on subscription-based consumption models.
Supply Chain Analysis
Flash foundry capacity concentrates in South Korea, Taiwan, and Japan, with assembly and integration operations distributed across Mexico, Malaysia, and domestic US facilities. Controller silicon and NAND wafers draw from Asian semiconductor fabrication, while power supply components and mechanical enclosures source from Chinese and Mexican contract manufacturers. Single-source vulnerability in high-density NAND supply exposes buyers to disruption from trade policy shifts or foundry yield issues. Distribution runs through certified federal integrators for government contracts and direct OEM relationships for hyperscale operators, with channel partners serving mid-market enterprises through bundled hardware-support packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Federal AI training cluster buildouts and hyperscale capacity expansion in Northern Virginia signal a cyclical recovery phase for domestic storage procurement, with NAND flash demand tightening through the analysis window.
For Market Incumbents: Build certification moats through accelerated FedRAMP and DoD Impact Level authorizations to filter competitor access to federal integrator channels. Deepen backward integration into firmware development capabilities to address scarce flash translation layer engineering talent. Consolidate vendor lists around certified integration partners before emerging computational storage specialists achieve scale. For New Entrants and Emerging Players: Pursue edge AI inference storage deployments in secondary Texas and Arizona markets where latency requirements outpace incumbent response capabilities. Target mid-market enterprises lacking dedicated storage engineering staff with subscription-based consumption models displacing traditional capital purchases. Lead with NVMe-oF fabric retrofit solutions for legacy SAN architectures in financial services data centers. For Investors and Strategic Acquirers: SEC climate disclosure requirements reshape the acquisition landscape toward vendors with verified carbon accounting and transparent SSD supply chain emissions data. Long-term viability favors flash-native specialists with recurring revenue models over capital-intensive HDD incumbents facing tape displacement. Monitor EPA carbon intensity benchmark revisions as the signal indicating which storage architectures will qualify for federal and enterprise contracts.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Acceleration | NIST-compliant certification opens qualified demand pipelines with defense and intelligence integrators. |
| NVMe-oF Fabric Convergence | Sub-100-microsecond latency enables real-time analytics workloads in Northern Virginia AI clusters. |
| Computational Storage Integration | Embedded processing reclaims server CPU cycles for hyperscale training workloads in Texas facilities. |
| Subscription Consumption Model | Capacity-as-a-service contracts displace capital purchases among mid-market enterprises lacking storage engineering staff. |
| Carbon Accounting Verification | Documented supply chain emissions data qualifies vendors for SEC-aligned federal procurement criteria. |
Research Methodology
The analysis maps hyperscale cloud, federal government, enterprise, and edge storage deployment archetypes, each validated through primary interviews with data center infrastructure executives, federal procurement officers, storage engineering directors, and colocation facility operators. Secondary validation draws from FERC interconnection filings, SEC climate disclosure submissions, hyperscaler capital expenditure disclosures, and NIST cybersecurity framework documentation. Bottom-up capacity installation tracking triangulates against top-down procurement flow analysis.
Assumptions held fixed include current FERC interconnection standards, existing NIST certification requirements, and prevailing NAND flash fabrication capacity allocations across the projection horizon. Segmentation dimensions modeled encompass storage architecture type, deployment model, end-user category, and media technology tier. CAGRs derive from installation run-rate analysis adjusted for technology substitution effects, with AI training cluster demand and state clean energy mandate compliance serving as primary volume drivers.
Macroeconomic conditions sit as an overlay; deviation in federal IT spending cycles, trade policy affecting Asian semiconductor imports, or ERCOT grid stability would shift the trajectory. Quarterly review of hyperscaler capital expenditure announcements, FedRAMP authorization timelines, and EPA carbon intensity benchmark revisions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
India Data Center Storage Market
Storage Solutions
Denmark Data Center Storage Market
Storage Solutions
Disk Based Data Fabric Market
Storage Solutions
South Africa Data Center Storage Market
Storage Solutions
Cloud Storage Gateways Market
Storage Solutions
Nigeria Data Center Storage Market
Storage Solutions
Consumer Network Attached Storage Market
Storage Solutions
Storage and Backup Software Market
Storage Solutions
Cloud Storage Market
Storage Solutions
Singapore Data Center Storage Market
Storage Solutions
Storage in Big Data Market
Storage Solutions
Automated Storage and Retrieval Systems in Laboratories Market
Storage Solutions
Europe Data Center Storage Market
Storage Solutions
Philippines Data Center Storage Market
Storage Solutions
Software Defined Storage Market
Storage Solutions
Virtual Machine Backup and Recovery Market