
 Philippines Data Center Storage Market | 2026-2036
Philippines Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Data Center Storage Market Insights
ISO 27001 certification is redrawing the competitive landscape for storage vendors serving Philippine data centers. Dell Technologies leverages its end-to-end infrastructure portfolio to anchor enterprise deployments in Manila and Clark. Huawei Technologies competes aggressively on cost-engineered flash arrays for telecom operators building edge nodes across the archipelago. IBM Corporation differentiates through software-defined storage solutions targeting banks navigating Bangko Sentral ng Pilipinas cybersecurity mandates.
Data center storage encompasses the hardware, software, and networking infrastructure engineered to retain, manage, and retrieve digital information across centralized computing facilities, typically operating with latency thresholds below five milliseconds for transactional workloads and redundancy architectures spanning N+1 to 2N configurations. Its primary commercial purpose is to ensure business continuity, regulatory compliance, and real-time analytics for organizations generating petabyte-scale data volumes. Cloud storage now captures the fastest expansion as hyperscalers and local telcos build sovereign capacity to comply with the Philippine Data Privacy Act. Software-defined storage is displacing traditional SAN architectures in government and enterprise accounts seeking elastic provisioning without forklift hardware upgrades. Hybrid deployment models dominate the mid-market, where organizations balance sensitive on-premises workloads with burst capacity from managed service providers.
The Department of Information and Communications Technology enforces cloud-first policies for national agencies, while the National Privacy Commission mandates data localization protocols that directly expand domestic storage infrastructure requirements. BIS-equivalent technical standards and the Cybercrime Prevention Act shape product certification pathways and liability frameworks for equipment suppliers. Stakeholders must monitor submarine cable route diversity and power purchase agreement structures as these variables determine where storage capacity economics break favorably against Singapore and Hong Kong alternatives.
Market Dynamics
Cloud-first mandates from the Department of Information and Communications Technology are compressing procurement cycles for enterprise storage infrastructure, forcing vendors to pre-certify solutions against BIS-equivalent technical standards before deployment in government facilities.
Growth Catalysts
- DICT Cloud-First Policy:National agencies must migrate to government-approved cloud facilities, expanding demand for ISO 27001-certified storage arrays in DICT-accredited data centers.
- Fintech transaction volumes:Digital payment platforms require sub-five-millisecond latency storage to process real-time settlements, driving all-flash array purchases in Metro Manila.
- Submarine cable landings:New cable systems landing in Clark Freeport Zone and Cebu IT Park reduce international bandwidth costs, making Philippine storage facilities cost-competitive against Singapore alternatives.
Market Restraints
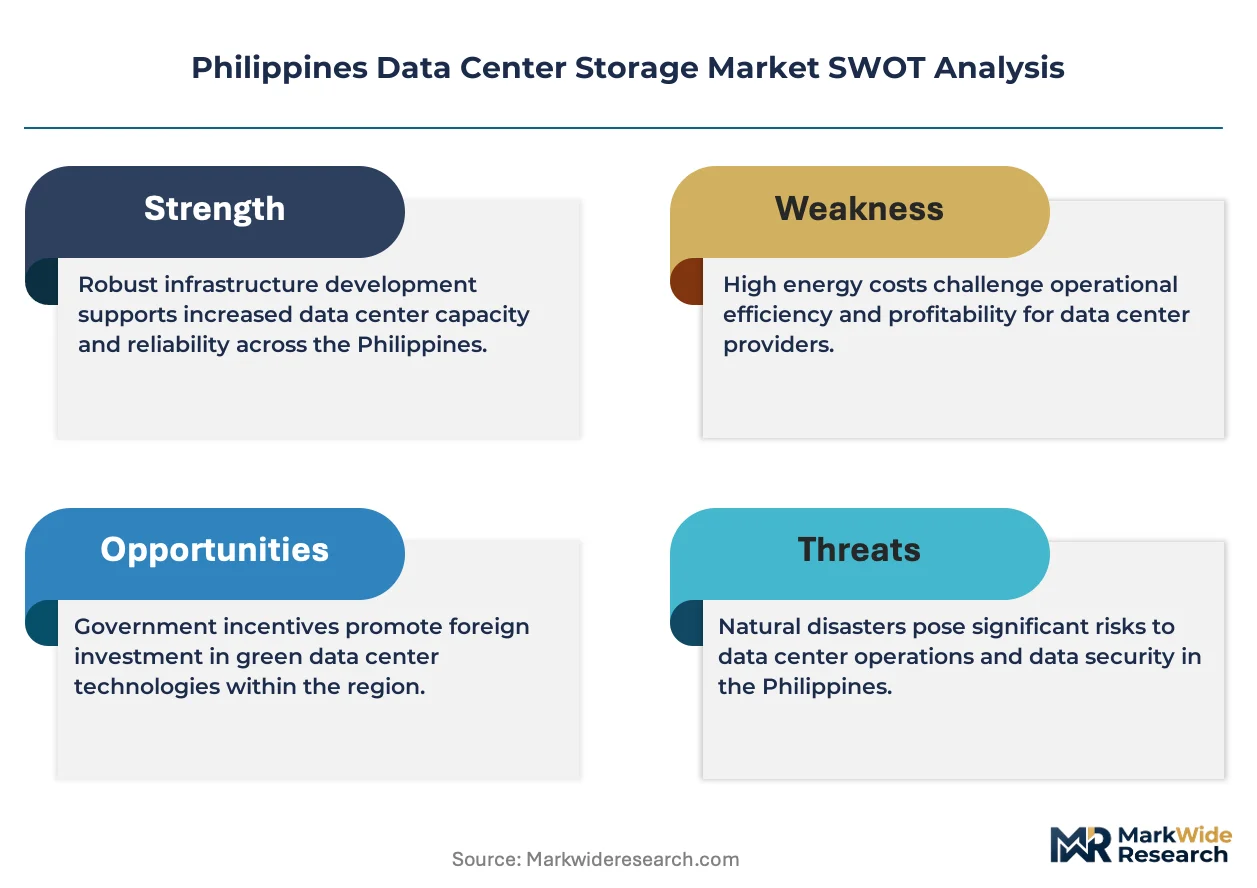
- Power cost volatility:Electricity rates in the Philippines exceed regional ASEAN averages, eroding operational margins for hyperscale storage deployments requiring 2N redundant power architectures.
- Limited domestic NAND supply:Flash memory components rely entirely on imports from South Korea and Taiwan, exposing procurement to currency fluctuation and shipping lane congestion.
- Cybercrime Prevention Act liability:Equipment suppliers face strict data breach accountability, increasing insurance and legal compliance costs for storage infrastructure vendors.
Strategic Opportunities
- Visayas island expansion:Cebu IT Park offers tax holidays under Philippine Economic Zone Authority incentives, attracting secondary storage nodes for disaster recovery replication from Luzon.
- AI training data lakes:BPO operators building machine learning capabilities require petabyte-scale object storage for unstructured voice and text analytics datasets.
- Converged edge-node architectures:Telecom operators are deploying software-defined storage on commodity servers, eliminating dedicated SAN hardware at provincial cell towers.
Industry Challenges
- Certification timeline compression:DICT accreditation requires six-month security audits, delaying revenue recognition for vendors supplying national agencies.
- Legacy SAN integration complexity:Banks maintaining decade-old IBM and EMC arrays struggle to migrate transaction logs to modern NVMe fabrics without service disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Data Center Storage Market |
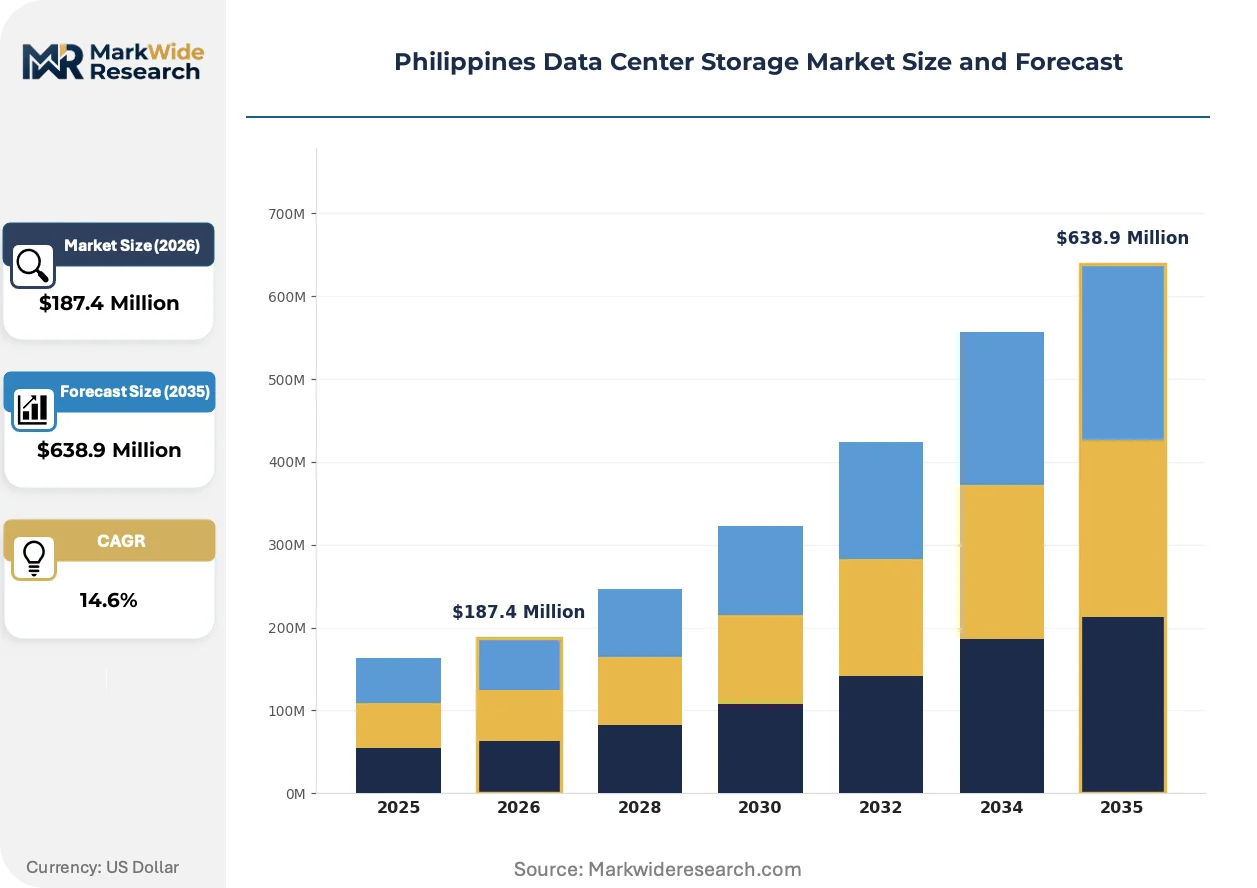
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct Attached Storage, Network Attached Storage, Storage Area Network, Cloud Storage Technology: Flash, Hard Disk Drive, Hybrid Storage, Software-Defined Storage End User: Enterprise, Government, Telecom, Healthcare Deployment Model: On-Premises, Hybrid, Offsite, Managed Services |
| Companies Covered | Dell Technologies, Hewlett Packard Enterprise, Huawei Technologies, NetApp, IBM Corporation, ePLDT, Beeinfotech PH, ST Telemedia Global Data Centres, Hitachi Vantara, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Data Center Storage Market Trends and Innovations
Software-defined storage architectures are collapsing the traditional boundary between compute and storage hardware, enabling Philippine telcos to deploy edge capacity without dedicated SAN specialists in remote provinces.
NVMe-over-Fabrics is displacing Fibre Channel as the dominant storage protocol in Manila financial data centers. Bangko Sentral ng Pilipinas-regulated institutions are adopting RDMA-capable flash arrays to meet real-time fraud detection latency requirements. This transition is compressing switch hardware refresh cycles from five years to thirty-six months.
The National Privacy Commission's data localization enforcement is mandating sovereign storage capacity for personally identifiable information. Multinational cloud operators must establish Philippine-located object storage buckets, disqualifying regional Singapore-based alternatives for healthcare and government contracts. Domestic colocation providers are capturing this compliance-driven demand.
Consumption-based financing models are replacing capital-intensive storage procurement among mid-market enterprises. Managed service providers in Clark Freeport Zone offer terabyte-month pricing with embedded disaster recovery, transferring depreciation risk from CIOs to infrastructure operators. Manufacturing firms in CALABARZON industrial zones are adopting this opex structure fastest.
Philippines Data Center Storage Market Segmentation
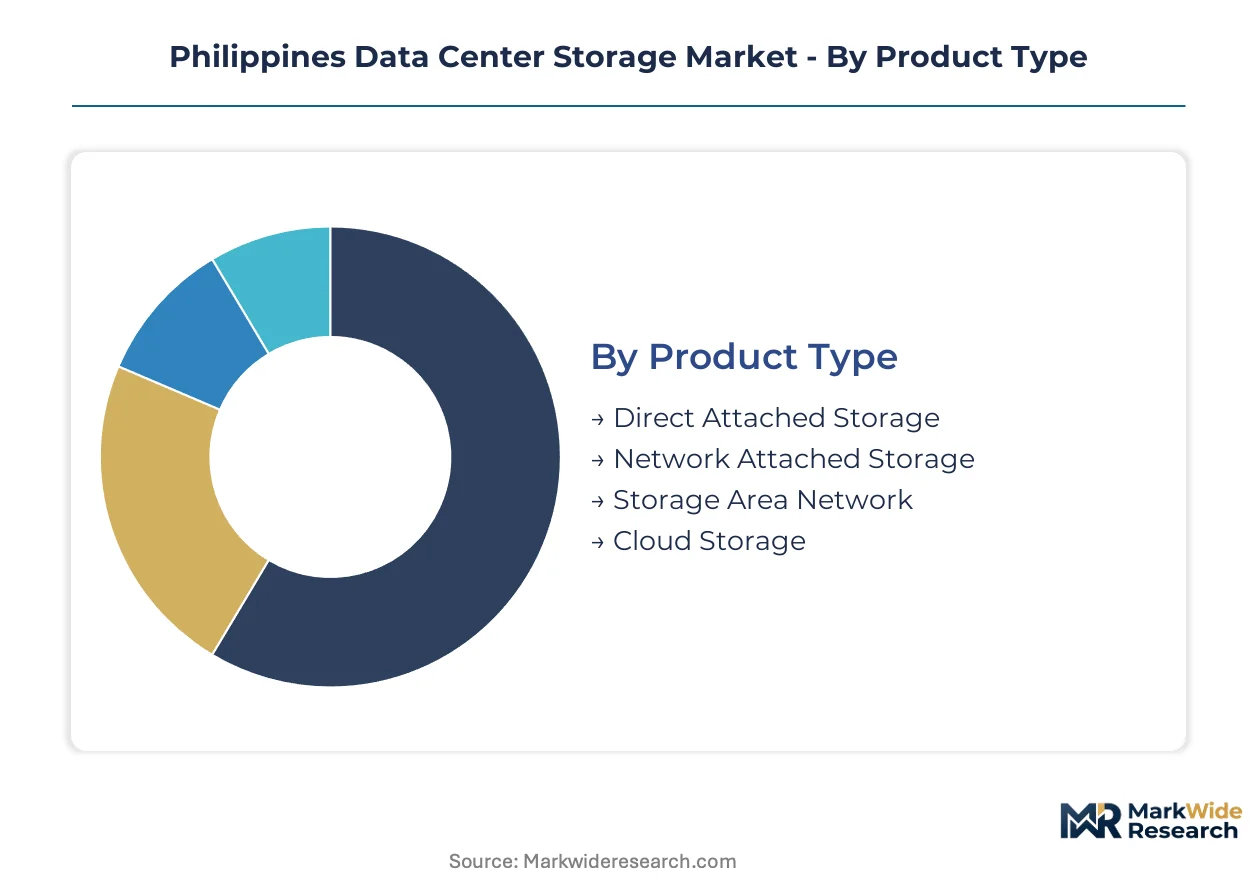
Storage procurement patterns in Philippine data centers diverge sharply across product architectures and deployment models. Regulatory mandates from DICT and the National Privacy Commission create distinct compliance tiers that reshape vendor targeting strategies.
Product Type:
Margin pools concentrate in software-enabled architectures where recurring licensing revenue compounds hardware margins.
- Cloud Storage:Object and file services delivered over IP networks with elastic capacity scaling. Bangko Sentral ng Pilipinas-regulated banks in Metro Manila are migrating core transaction archives to sovereign cloud buckets to satisfy data localization audits.
- Storage Area Network:Block-level storage fabrics using Fibre Channel or NVMe-over-Fabrics protocols. Legacy SAN arrays still anchor payment processing at Philippine National Bank and BDO Unibank, though refresh cycles are compressing to thirty-six months.
- Direct Attached Storage:Server-internal drives for single-tenant workloads.
- Network Attached Storage:File-level access protocols serving departmental shares and media repositories.
The dominant share belongs to Storage Area Network, while Cloud Storage is closing the gap fastest.
Technology:
Application latency requirements in fintech and BPO verticals determine technology selection more than cost per gigabyte.
- Software-Defined Storage:Decouples control plane from physical media, enabling commodity server deployment. PLDT and Globe Telecom are rolling out SDS at provincial cell towers to eliminate dedicated storage hardware in edge nodes.
- Flash:NAND-based solid-state media delivering sub-millisecond response times. All-flash arrays dominate new procurement at UnionBank and Maya for real-time fraud detection pipelines.
- Hybrid Storage:Tiered hot-cold architectures balancing performance and capacity economics.
- Hard Disk Drive:Rotating magnetic media for sequential-access archival and backup targets.
Software-Defined Storage commands expanding share in telecom infrastructure, while Flash arrays are gaining ground fastest in financial services.
End User:
Customer type dictates certification requirements and contract structures more than raw capacity scale.
- Government:National agencies under DICT cloud-first mandates requiring ISO 27001-accredited facilities. The Bureau of Customs and Department of Finance are consolidating storage into DICT-accredited colocation sites in Clark Freeport Zone.
- Telecom:Operators building subscriber data management and content delivery infrastructure. DITO Telecommunity is deploying petabyte-scale object storage for video streaming caches in Cebu IT Park.
- Enterprise:Manufacturing and BPO firms with mixed compliance exposure.
- Healthcare:Hospital networks navigating National Privacy Commission data localization for electronic medical records.
Government accounts anchor procurement volume through multi-year framework agreements, while Telecom operators are expanding capacity most aggressively.
Deployment Model:
Ownership economics and disaster recovery obligations shape deployment selection across Luzon, Visayas, and Mindanao.
- Hybrid:Split workloads across owned infrastructure and managed capacity bursts. Ayala Corporation subsidiaries balance sensitive ERP systems on-premises with analytics sandboxes in service provider facilities.
- Managed Services:Fully outsourced storage with embedded replication and compliance management. CALABARZON manufacturing zones favor terabyte-month pricing to convert capex to opex.
- On-Premises:Customer-operated facilities with direct capital control.
- Offsite:Dedicated capacity in third-party data centers without hybrid orchestration.
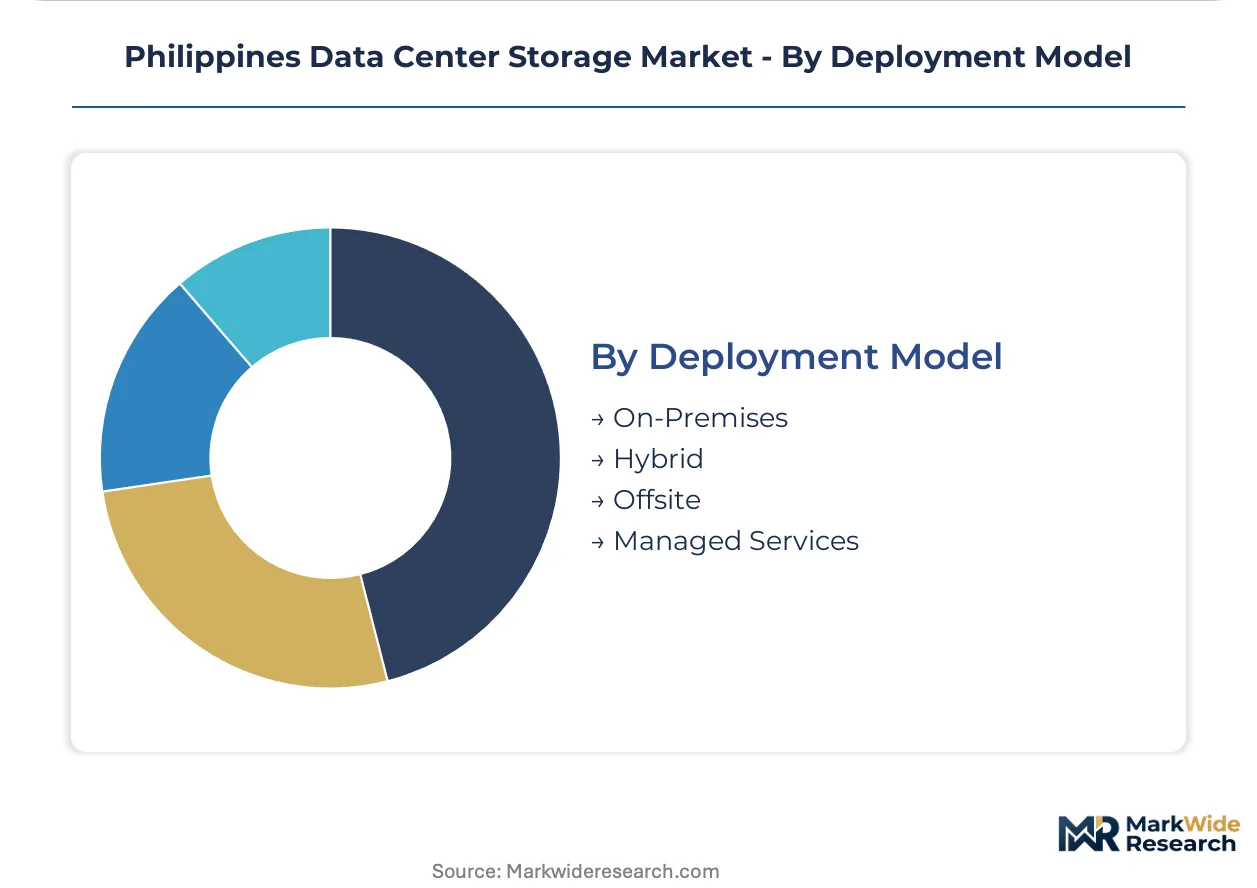
Hybrid deployments hold the largest installed base, though Managed Services is climbing the fastest as mid-market enterprises defer infrastructure ownership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Philippine Economic Zone Authority's tax holidays and the Department of Information and Communications Technology's cloud-first mandates are redistributing storage infrastructure investment toward designated technology zones.
Metro Manila
Financial institutions in Makati and Bonifacio Global City drive sub-five-millisecond latency requirements for real-time fraud detection. Bangko Sentral ng Pilipinas cybersecurity mandates compel banks to refresh legacy SAN architectures. The Makati central business district hosts the densest concentration of ISO 27001-certified colocation facilities serving fintech platforms.
Clark Freeport Zone
Submarine cable landings from Southeast Asia-Japan Cable and Asia Submarine-cable Express reduce international bandwidth costs below Singapore alternatives. The Bases Conversion and Development Authority offers income tax holidays for data center operators. PLDT and Globe Telecom are consolidating disaster recovery nodes in this former US airbase.
Cebu IT Park
Business process outsourcing operators building AI training capabilities require petabyte-scale object storage for voice and text analytics. Philippine Economic Zone Authority incentives extend to information technology enterprises locating in this Visayas hub. DITO Telecommunity deploys video streaming caches to serve central and southern Philippines.
Davao City
Mindanao's emerging status as a disaster recovery target for Luzon-based enterprises drives secondary storage node investment. The National Broadband Plan prioritizes fiber connectivity to this southern commercial center. Local telcos are testing software-defined storage at provincial cell towers to eliminate dedicated SAN hardware.
Philippines Data Center Storage Market Competitive Landscape
Listed infrastructure conglomerates compete with private specialists across certification timelines and procurement frameworks. The vendor base stratifies between end-to-end portfolio providers, cost-engineered component suppliers, and software-defined specialists. Three archetypes dominate: multinational technology conglomerates with government pre-certification, regional hyperscale operators with captive power agreements, and domestic colocation providers with sovereign compliance positioning. Competitive moves concentrate on pre-certification against BIS-equivalent standards and securing Philippine Economic Zone Authority tax holidays.
Within the multinational technology tier, Dell Technologies, Huawei Technologies, and IBM Corporation exemplify divergent positioning strategies. Dell Technologies anchors enterprise deployments through end-to-end infrastructure portfolios. Huawei Technologies occupies the cost-engineered segment for telecom edge infrastructure. IBM Corporation represents the software-defined specialization targeting regulated financial institutions navigating Bangko Sentral ng Pilipinas mandates.
| Leading Market Players |
|---|
| Dell Technologies |
| Hewlett Packard Enterprise |
| Huawei Technologies |
| NetApp |
| IBM Corporation |
| ePLDT |
| Beeinfotech PH |
| ST Telemedia Global Data Centres |
| Hitachi Vantara |
| Others |
Pricing and Supply Chain Analysis
Hyperscale capacity utilization in Clark Freeport Zone and Cebu IT Park establishes scale economies that compress unit storage costs while concentrating procurement leverage among DICT-accredited facility operators. This concentration simultaneously elevates price floors for uncertified competitors and rewards vendors achieving ISO 27001 pre-certification with premium positioning in government frameworks.
Pricing Analysis
Certification level creates the primary spread between DICT-accredited sovereign cloud deployments and standard enterprise colocation. Three-tier pricing structure separates hyperscale all-flash arrays from hybrid SAN configurations and archival HDD tiers, with Bangko Sentral ng Pilipinas-mandated sub-five-millisecond latency requirements commanding substantial premiums. Cost compression in mid-market hybrid deployments is intensifying because managed service providers in CALABARZON industrial zones are converting capex to terabyte-month opex structures. Government accounts show least price sensitivity due to cloud-first mandate compliance deadlines, while manufacturing SMEs in provincial zones exhibit highest elasticity.
Supply Chain Analysis
Strategic stockpile preferences dominate NAND flash procurement as Philippine data center operators buffer against Taiwan Strait shipping lane congestion and South Korean supplier lead time volatility. Flash memory components draw entirely from South Korea, Taiwan, and Japan, while server chassis and networking equipment sources from China and Malaysia. Single-source vulnerability concentrates in NAND wafer supply, with no domestic fabrication capacity exposing procurement to currency fluctuation. Distribution runs through Manila-based systems integrators holding DICT pre-certification, with direct vendor relationships reserved for hyperscale operators meeting volume thresholds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Philippines data center storage market represents an early-cycle expansion story where DICT cloud-first mandates are accelerating public-sector migration faster than vendor certification capacity can match.
For Market Incumbents: Compound defensive positioning by accelerating ISO 27001 pre-certification pipelines to capture multi-year government framework agreements before accreditation timelines compress further. Anchor enterprise relationships through end-to-end infrastructure portfolios that integrate legacy SAN migration services, neutralizing Huawei's cost-engineered edge node threat with superior interoperability guarantees.
For New Entrants and Emerging Players: DICT accreditation fast-tracks unlock immediate access to Bureau of Customs and Department of Finance consolidation projects in Clark Freeport Zone. White-space concentrates in Visayas island disaster recovery replication and AI training data lake object storage for Cebu BPO operators. Lead with consumption-based financing models that transfer depreciation risk from CALABARZON manufacturing CIOs.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors software-defined storage specialists with proven NVMe-over-Fabrics deployments in Bangko Sentral ng Pilipinas-regulated institutions. Long-term viability hinges on capturing the transition from Fibre Channel to RDMA-capable fabrics across Manila financial data centers. Monitor submarine cable route diversity announcements as the inflection indicator for Clark Freeport Zone capacity economics breaking favorably against Singapore alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| DICT Pre-Certification Investment | ISO 27001 accreditation compresses sales cycles for Bureau of Customs and Department of Finance migrations. |
| NVMe-over-Fabrics Platform Deployment | RDMA-capable arrays satisfy Bangko Sentral ng Pilipinas real-time fraud detection latency mandates. |
| Visayas Edge Node Expansion | Cebu IT Park tax holidays attract secondary storage nodes for Luzon disaster recovery replication. |
| Consumption-Based Financing Launch | Terabyte-month pricing converts CALABARZON manufacturing capex to opex with embedded compliance. |
| Submarine Cable Landing Partnership | Clark Freeport Zone bandwidth cost advantages position storage facilities against Singapore alternatives. |
Research Methodology
Initial hypotheses were tested against primary input from data center facility operators, storage infrastructure procurement officers at Bangko Sentral ng Pilipinas-regulated banks, DICT accreditation auditors, and telecom network planning executives, then refined against secondary validation from SEC filings of listed infrastructure conglomerates, hyperscaler capex disclosures, Philippine Economic Zone Authority incentive program documentation, and submarine cable landing records. Bottom-up capacity installation tracking and top-down regulatory mandate impact modeling were triangulated to reconcile variance.
Variance decomposition across product architecture, deployment model, technology tier, and regional zone shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level capacity buildout trajectories weighted by DICT cloud-first policy implementation phases and Bangko Sentral ng Pilipinas cybersecurity mandate compliance deadlines. Modeled inputs incorporated power purchase agreement structures, Philippine Economic Zone Authority tax holiday eligibility windows, and National Privacy Commission data localization enforcement intensity.
Underlying assumptions cover DICT accreditation timeline stability, submarine cable route diversity maintenance, and power cost volatility bands, with deviation risk concentrated in NAND flash supply chain disruption and currency fluctuation exposure. Revision becomes warranted when DICT policy implementation pace or National Privacy Commission enforcement intensity crosses thresholds that alter enterprise migration timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Storage Software Market
Storage Solutions
Vietnam Data Center Storage Market
Storage Solutions
Poland Data Center Storage Market
Storage Solutions
UK Data Center Storage Market
Storage Solutions
Nigeria Data Center Storage Market
Storage Solutions
Singapore Data Center Storage Market
Storage Solutions
Network Attached Storage (NAS) Market
Storage Solutions
Thailand Data Center Storage Market
Storage Solutions
Belgium Data Center Storage Market
Storage Solutions
Cloud Storage Market
Storage Solutions
Indonesia Data Center Storage Market
Storage Solutions
Enterprise File Sync and Share Platform Market
Storage Solutions
United States Data Center Storage Market
Storage Solutions
Disk Based Data Fabric Market
Storage Solutions
Saudi Arabia Data Center Storage Market
Storage Solutions
Multi Cloud Storage Market