
 Mexico Data Center Storage Market | 2026-2036
Mexico Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Data Center Storage Market Insights
Enterprise buyers are collapsing the traditional dominance of small and mid-sized local data center operators as hyperscale cloud providers and large IT enterprises expand their storage footprints across central Mexico. Dell Technologies leverages its integrated server-storage portfolio to capture high-margin hybrid cloud deployments. Hewlett Packard Enterprise anchors its position through composable infrastructure architectures that reduce provisioning latency for Mexican telecommunications carriers. Huawei Technologies competes aggressively on all-flash array pricing, though its presence faces scrutiny under evolving trade compliance frameworks.
Mexico data center storage encompasses electromechanical and solid-state systems engineered for persistent data retention at capacities spanning 1TB to 1PB, utilizing NAND flash, magnetic platters, or NVMe-over-Fabric protocols to deliver sub-millisecond latency for transactional and analytical workloads. These systems serve as the foundational layer for enterprise digitization, enabling regulatory compliance, disaster recovery, and artificial intelligence training pipelines. SSD and NVMe segments are capturing disproportionate margin pools as Mexican enterprises prioritize performance density over raw capacity economics. Hybrid cloud deployment models are expanding fastest among IT enterprises and telecommunications operators seeking to balance sovereignty requirements with elasticity. On-premises storage retains structural importance in government and education verticals where data localization mandates restrict off-premise migration.
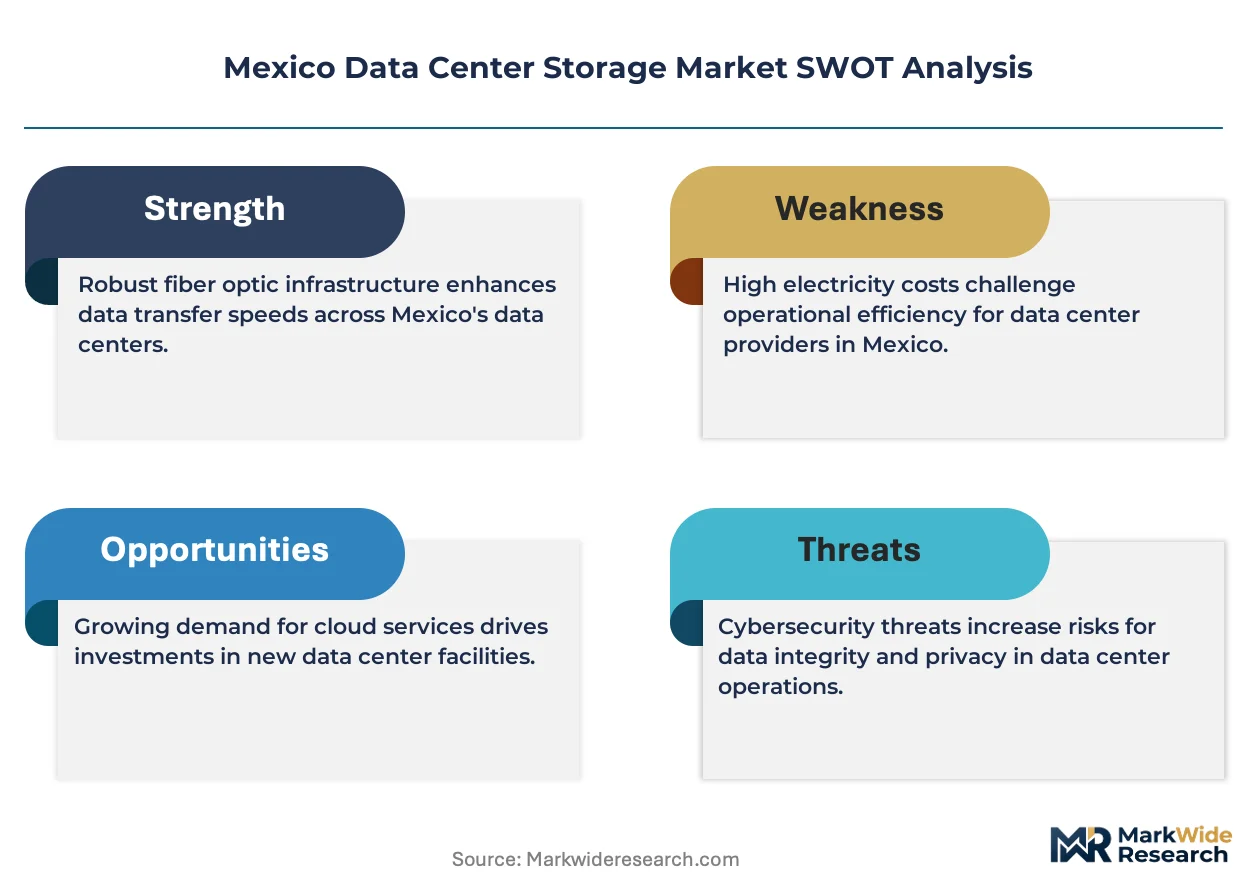
CRE, Mexico's energy regulator, shapes facility economics through electricity tariff structures that penalize inefficient power usage effectiveness ratios. NOM standards for electromagnetic compatibility and equipment safety govern product certification requirements for imported storage hardware. The national cybersecurity strategy under the National Guard and Secretariat of National Defense introduces data classification protocols that dictate encryption and access control specifications. Stakeholders must monitor how pending critical infrastructure designations reshape vendor qualification timelines and procurement authority.
Market Dynamics
Hyperscale cloud providers are consolidating storage procurement power across central Mexico, collapsing traditional distributor networks and forcing electromechanical and solid-state vendors to restructure channel economics around direct enterprise relationships.
Growth Catalysts
- IFT spectrum rules:Mexico's Federal Telecommunications Institute accelerated fiber buildouts near Querétaro and Mexico City, enabling cloud-adjacent storage deployments that reduce latency for financial services workloads.
- Real-time analytics demand:Mexican banking and insurance carriers expanded NVMe-over-Fabric installations to support regulatory data retention mandates requiring sub-millisecond transactional response.
- CRE tariff structures:The national energy regulator introduced electricity pricing that rewards power usage effectiveness optimization, incentivizing all-flash array adoption over spinning disk in new facilities.
Market Restraints
- NAND flash supply concentration:Mexican storage integrators depend on concentrated Asian memory fabrication, exposing procurement to geopolitical friction and freight cost volatility.
- NOM certification timelines:Electromagnetic compatibility and equipment safety standards impose extended product approval cycles for imported hardware, delaying revenue recognition for international vendors.
- Skilled technician scarcity:The domestic labor pool lacks sufficient density of NVMe fabric and composable infrastructure specialists, constraining deployment velocity for complex enterprise installations.
Strategic Opportunities
- Guadalajara corridor expansion:Secondary metropolitan zones outside the Mexico City-Querétaro axis offer undeveloped fiber interconnection capacity for distributed storage architectures.
- AI training pipeline demand:Emerging machine learning workloads in Mexican manufacturing and logistics sectors create white space for high-capacity object storage systems optimized for sequential read patterns.
- National Guard cybersecurity protocols:Data classification requirements under the national cybersecurity strategy mandate encryption standards that favor certified domestic system integrators over uncertified foreign direct sales.
Industry Challenges
- Legacy SAN integration complexity:Financial services incumbents operate heterogeneous storage estates that resist seamless migration to composable infrastructure without extensive professional services engagement.
- Compliance documentation burden:Secretariat of National Defense data sovereignty rules require exhaustive chain-of-custody records that extend sales cycles and inflate pre-revenue engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Data Center Storage Market |
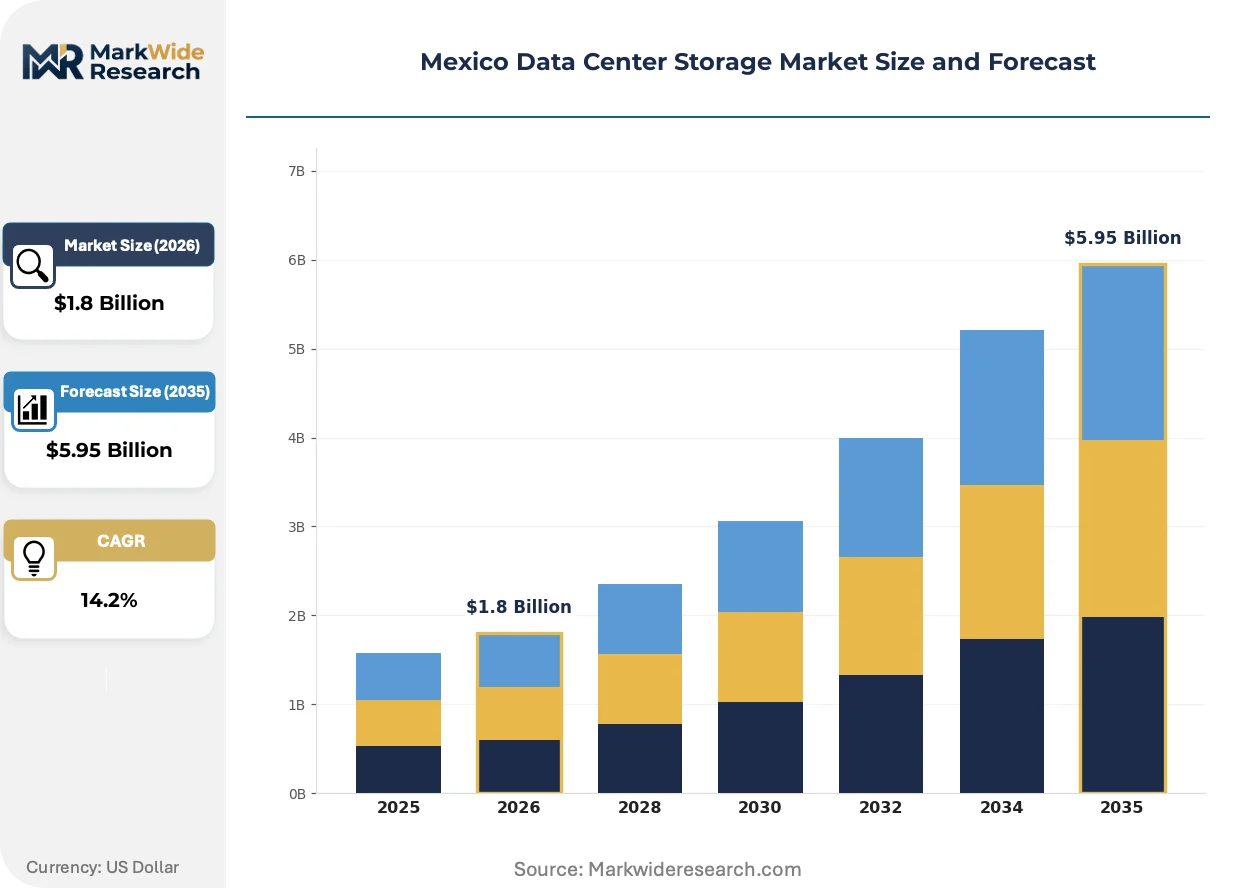
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Storage Type: HDD, SSD, NVMe, Cloud Storage Deployment Model: On-premises, Hybrid Cloud, Colocation, Off-premises End User: IT Enterprises, Telecommunications, Government, Education Storage Capacity: 1TB, 10TB, 100TB, 1PB |
| Companies Covered | Dell Technologies, Hewlett Packard Enterprise, NetApp, Huawei Technologies, Cisco Systems, IBM Corporation, Lenovo Group, Hitachi Vantara, Seagate Technology, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Data Center Storage Market Trends and Innovations
Storage architectures in Mexico are fragmenting across performance tiers as buyers reject monolithic arrays in favor of disaggregated resource pools that align capital expenditure with actual workload consumption patterns.
Composable infrastructure is decomposing traditional server-storage silos into independently scalable compute, memory, and capacity resources. Mexican telecommunications carriers adopted these architectures fastest, driven by 5G core network virtualization timelines. The technology is decomposing incumbent vendor maintenance revenue streams as buyers substitute granular cloud-style consumption for multi-year enterprise license agreements.
CRE electricity tariff reforms now penalize facilities operating above industry-standard power usage effectiveness thresholds. Data center operators responded by accelerating solid-state storage deployment ratios and consolidating electromechanical assets into dedicated archival tiers. The policy most affects Querétaro hyperscale campuses where density constraints limit mechanical cooling headroom.
Consumption-based financing displaced capital purchase for mid-market Mexican enterprises during the forecast window. System integrators and regional distributors built managed service wrappers around hardware procurement, transferring operational risk from CIOs to vendor balance sheets. This pattern concentrated among education and state government verticals where budget approval cycles conflict with technology refresh timelines.
Mexico Data Center Storage Market Segmentation
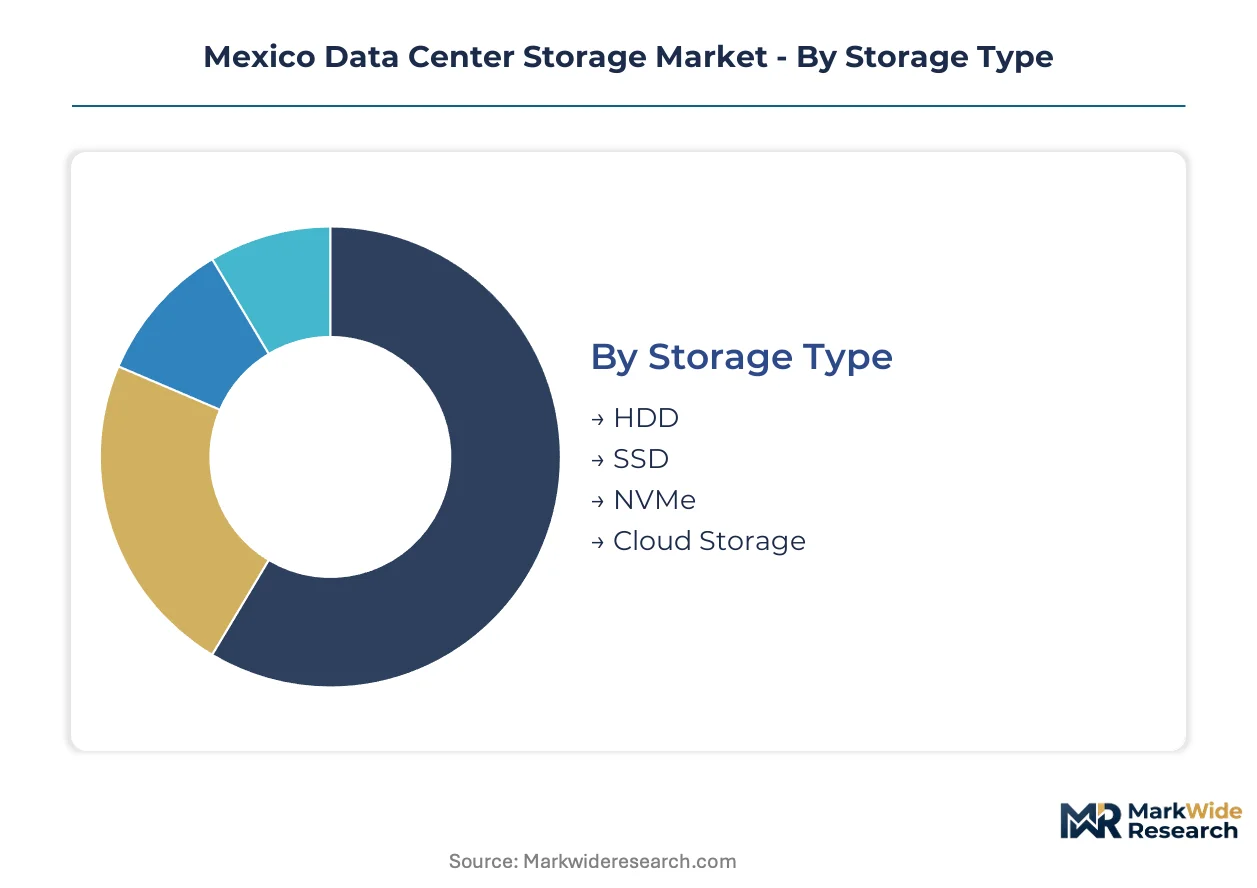
Mexico's data center storage market fragments across four dimensions that determine procurement patterns and margin distribution. Storage type and deployment model shape vendor channel strategies, while end user verticals and capacity tiers dictate pricing elasticity and service requirements.
Storage Type:
Channel economics diverge sharply between electromechanical and solid-state technologies, with distributor networks dominating HDD while direct enterprise relationships capture NVMe and high-performance SSD.
- HDD:Magnetic platter systems deliver cost-per-gigabyte economics for archival and backup workloads. Demand concentrates in Querétaro hyperscale campuses where CRE tariff penalties for power inefficiency are forcing these systems into dedicated cold storage tiers rather than primary workloads.
- SSD:NAND flash arrays balance performance density with capital efficiency for mixed transactional workloads. Mexican banking carriers in Mexico City expanded SATA and SAS SSD deployments to satisfy regulatory data retention mandates without NVMe cost premiums.
- NVMe:Sub-millisecond latency protocols over PCIe fabrics serve real-time analytics pipelines. IFT fiber buildouts near Mexico City interconnection points enable these deployments for financial services workloads requiring transactional response guarantees.
- Cloud Storage:Object and block services delivered via hyperscale provider APIs. IT enterprises leverage this model to circumvent NOM certification delays for imported hardware while maintaining sovereignty through in-country availability zones.
HDD dominates installed base. NVMe is where expansion concentrates.
Deployment Model:
Customer type and compliance burden determine whether buyers favor capital ownership or operational expenditure models.
- On-premises:Dedicated infrastructure within enterprise-controlled facilities. Government and education verticals retain this model exclusively due to National Guard data classification protocols restricting off-premise migration.
- Hybrid Cloud:Orchestrated workloads spanning owned infrastructure and hyperscale capacity. IT enterprises and telecommunications operators adopted this fastest to balance sovereignty requirements with elasticity for variable analytics demand.
- Colocation:Leased space in third-party facilities with customer-managed hardware. Querétaro and Mexico City campuses attract these deployments through CRE-optimized power tariffs and IFT-enabled fiber density.
- Off-premises:Fully outsourced storage services with no local infrastructure ownership. Mid-market enterprises displaced capital purchase with consumption-based financing through regional distributor managed service wrappers.
On-premises retains structural importance in regulated verticals. Hybrid cloud is climbing the fastest.
End User:
Vertical-specific compliance frameworks and workload characteristics fragment procurement authority across buyer types.
- IT Enterprises:Technology and services firms with heterogeneous application portfolios. These buyers collapsed traditional distributor networks by consolidating procurement power around direct vendor relationships for composable infrastructure.
- Telecommunications:Mobile and fixed-line carriers virtualizing core network functions. 5G deployment timelines in central Mexico accelerated NVMe-over-Fabric adoption to reduce provisioning latency for subscriber data management.
- Government:Federal and state agencies subject to data localization mandates. Secretariat of National Defense chain-of-custody requirements extend sales cycles and favor certified domestic system integrators.
- Education:Universities and research institutions with cyclical budget approvals. Consumption-based financing displaced capital purchase in this vertical as budget timelines conflicted with technology refresh requirements.
IT enterprises command the largest procurement volumes. Telecommunications represents the steepest expansion trajectory.
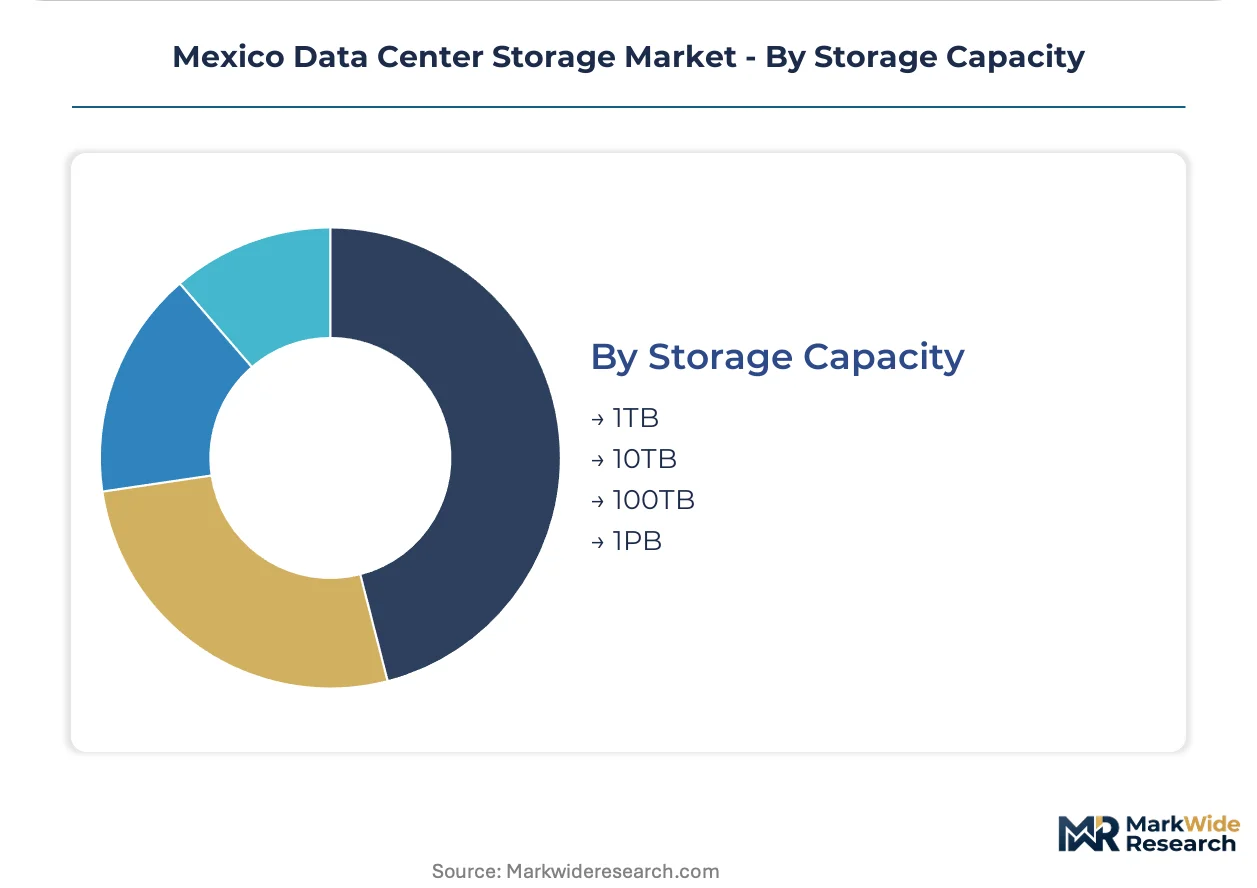
Storage Capacity:
Capacity tier selection correlates with workload performance requirements and facility density constraints.
- 1TB:Entry-level systems for departmental applications and edge deployments. Remote government offices and small educational institutions procure these through regional distributor channels with bundled support services.
- 10TB:Mid-range configurations for consolidated server virtualization. Mexican manufacturing firms in Guadalajara corridor expansion zones deploy these for ERP and operational technology integration.
- 100TB:Enterprise-scale arrays for unified primary storage. Financial services incumbents in Mexico City operate heterogeneous estates at this scale that resist seamless migration without extensive professional services engagement.
- 1PB:Hyperscale-capacity systems for AI training pipelines and analytics lakes. Emerging machine learning workloads in logistics sectors create white space for these high-capacity object storage configurations optimized for sequential read patterns.
100TB systems anchor current enterprise infrastructure. 1PB deployments are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale storage deployment concentrates along Mexico's central corridor where IFT fiber buildouts and CRE electricity tariffs create optimal facility economics. Regional differentiation reflects proximity to interconnection points, energy pricing, and compliance jurisdiction.
Mexico City Metro
Financial services carriers drive NVMe-over-Fabric demand for regulatory data retention with sub-millisecond latency requirements. The Secretariat of National Defense data classification protocols mandate encryption standards that favor certified domestic system integrators. Santa Fe and Tlalnepantla clusters host the densest hyperscale campuses near IFT-enabled fiber interconnection points.
Querétaro
Hyperscale cloud providers consolidate procurement power through direct vendor relationships bypassing traditional distributor networks. CRE tariff structures penalize power usage effectiveness ratios above industry thresholds, forcing all-flash array adoption over spinning disk. El Marqués and Corregidora municipalities anchor the Bajío Region's cloud-adjacent storage buildouts.
Jalisco
Manufacturing and logistics sectors generate emerging demand for high-capacity object storage systems optimized for AI training pipelines. State government data localization mandates restrict off-premise migration for certain agency workloads. Guadalajara corridor expansion zones offer undeveloped fiber interconnection capacity for distributed storage architectures.
Nuevo León
Telecommunications carriers virtualize core network functions through composable infrastructure architectures reducing provisioning latency. State-level procurement frameworks align with federal cybersecurity strategy requirements under National Guard protocols. Monterrey metropolitan area attracts colocation deployments through competitive electricity pricing and cross-border fiber connectivity.
Mexico Data Center Storage Market Competitive Landscape
Concentration sits with integrated infrastructure conglomerates and specialized storage vendors restructuring channel economics around direct enterprise relationships. Hyperscale cloud procurement consolidation collapses traditional distributor networks across central Mexico. Three archetypes dominate: full-stack server-storage integrators, composable infrastructure specialists, and all-flash array purveyors. Competitive maneuvering centers on hybrid cloud deployment partnerships and consumption-based financing wrappers transferring operational risk to vendor balance sheets.
Among US-based technology conglomerates, Dell Technologies and Hewlett Packard Enterprise exemplify the integrated infrastructure archetype, while NetApp occupies a position within the specialized storage tier. Huawei Technologies represents the geographically diversified competitor facing compliance scrutiny under evolving trade frameworks. These anchors illustrate how vendor qualification timelines and procurement authority reshape competitive positioning under National Guard cybersecurity protocols.
| Leading Market Players |
|---|
| Dell Technologies |
| Hewlett Packard Enterprise |
| NetApp |
| Huawei Technologies |
| Cisco Systems |
| IBM Corporation |
| Lenovo Group |
| Hitachi Vantara |
| Seagate Technology |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts between hyperscale cloud providers and NAND flash manufacturers lock in supply access while fixing price visibility across volatile memory cycles. These arrangements concentrate procurement power among Mexico City and Querétaro hyperscale campuses, compressing margin pools for regional distributors serving mid-market buyers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by performance density and certification grade under NOM electromagnetic compatibility standards. Dell Technologies and Hewlett Packard Enterprise capture premium tiers through integrated server-storage bundles, while Huawei Technologies pressures mid-market pricing on all-flash arrays. Cost compression in economy HDD tiers intensifies because CRE tariff penalties force cold storage consolidation. Education verticals exhibit highest price sensitivity due to cyclical budget constraints, whereas financial services carriers prioritize latency guarantees over unit economics.
Supply Chain Analysis
South Korea and Taiwan anchor NAND flash wafer fabrication, while China concentrates SSD controller and subsystem assembly. Mexican storage integrators draw from concentrated Asian memory fabrication for NAND flash, PCIe controllers, and NVMe fabric switches. Single-source vulnerability runs through Taiwan Strait logistics corridors, exposing procurement to geopolitical friction. Distribution runs through direct enterprise relationships that hyperscale cloud providers consolidated, collapsing traditional distributor networks across central Mexico.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hyperscale cloud procurement consolidation across Mexico City and Querétaro has shifted buyer power decisively toward IT enterprises and telecommunications carriers, fragmenting traditional distributor influence. This concentration demands strategic repositioning across all market participants.
For Market Incumbents: Fortify hybrid cloud deployment partnerships to defend against composable infrastructure specialists eroding maintenance revenue streams. Invest in NOM certification pre-approval for imported hardware to compress sales cycles against domestic system integrators favored by National Guard cybersecurity protocols. Prioritize consumption-based financing wrappers that transfer operational risk from CIOs to vendor balance sheets, particularly in education and state government verticals where budget approval cycles conflict with technology refresh timelines. For New Entrants and Emerging Players: Managed NVMe fabric deployment services represent a service-layer gap where incumbents under-serve mid-market manufacturing firms in Guadalajara corridor expansion zones. Target high-capacity object storage configurations for AI training pipelines in logistics sectors, where emerging machine learning workloads create white space. Pursue certified domestic system integrator status under Secretariat of National Defense chain-of-custody requirements to circumvent extended procurement timelines facing uncertified foreign direct sales. For Investors and Strategic Acquirers: Specialized composable infrastructure vendors with established telecommunications carrier relationships present acquisition target archetypes positioned for 5G core network virtualization demand. Monitor IFT fiber buildout announcements as inflection indicators for cloud-adjacent storage deployment velocity. Long-term viability hinges on regulatory continuity in CRE electricity tariff structures and National Guard data classification protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Cloud Partnership | Dell Technologies leverages integrated portfolios to capture high-margin deployments balancing sovereignty with elasticity. |
| NOM Certification Investment | Pre-approved hardware accelerates revenue recognition against competitors facing extended electromagnetic compatibility timelines. |
| Composable Infrastructure Development | Hewlett Packard Enterprise reduces provisioning latency for Mexican telecommunications carriers virtualizing 5G core networks. |
| Consumption-Based Financing Launch | Managed service wrappers displace capital purchase in education verticals where budget cycles conflict with refresh requirements. |
| Guadalajara Corridor Expansion | Secondary metropolitan zones offer undeveloped fiber interconnection capacity for distributed AI training pipeline architectures. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of IFT spectrum allocation records, CRE electricity tariff filings, and hyperscaler capex disclosures to establish market sizing boundaries. Interviews with data center facility operators, storage procurement officers at financial services carriers, telecommunications network engineers, and regional system integrators provided demand-side validation. Secondary sources include Secretariat of National Defense cybersecurity protocol documentation, NOM certification registries, and trade flow data for imported storage hardware. Bottom-up capacity installation tracking triangulates against top-down spend analysis across deployment models.
Segmentation dimensions modeled span storage type, deployment architecture, end-user vertical, and capacity tier across the projection horizon. The analytical framework incorporates IFT fiber buildout timelines, CRE tariff reform implementation phases, and National Guard data classification protocol adoption curves as industry-specific forecast inputs. CAGRs derive from regression analysis of historical procurement patterns against projected hyperscale facility expansion.
Forecasts assume regulatory continuity in IFT spectrum rules, CRE electricity pricing structures, and National Guard cybersecurity mandates; material policy shifts would require re-modeling deployment velocity assumptions. NAND flash supply concentration and evolving trade compliance frameworks present specific risk factors that could revise trajectory. Recalibration cycles align with material shifts in hyperscale procurement consolidation patterns and fiber interconnection capacity expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Global Data Erasure Solutions Market
Storage Solutions
Denmark Data Center Storage Market
Storage Solutions
New Zealand Data Center Storage Market
Storage Solutions
Netherlands Data Center Storage Market
Storage Solutions
Hybrid Cloud Storage Market
Storage Solutions
Asia Pacific Automated Storage and Retrieval System Market
Storage Solutions
Thailand Data Center Storage Market
Storage Solutions
Global Cloud Object Storage Market
Storage Solutions
Singapore Data Center Storage Market
Storage Solutions
Network Attached Storage (NAS) Market
Storage Solutions
Italy Data Center Storage Market
Storage Solutions
Global Enterprise File Sharing and Synchronization (EFSS) Market
Storage Solutions
Philippines Data Center Storage Market
Storage Solutions
Storage Software Market
Storage Solutions
Media and Entertainment Storage Market
Storage Solutions
Multi Cloud Storage Market