
 Medical Tricorder Market | 2026-2036
Medical Tricorder Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Tricorder Market Intelligence
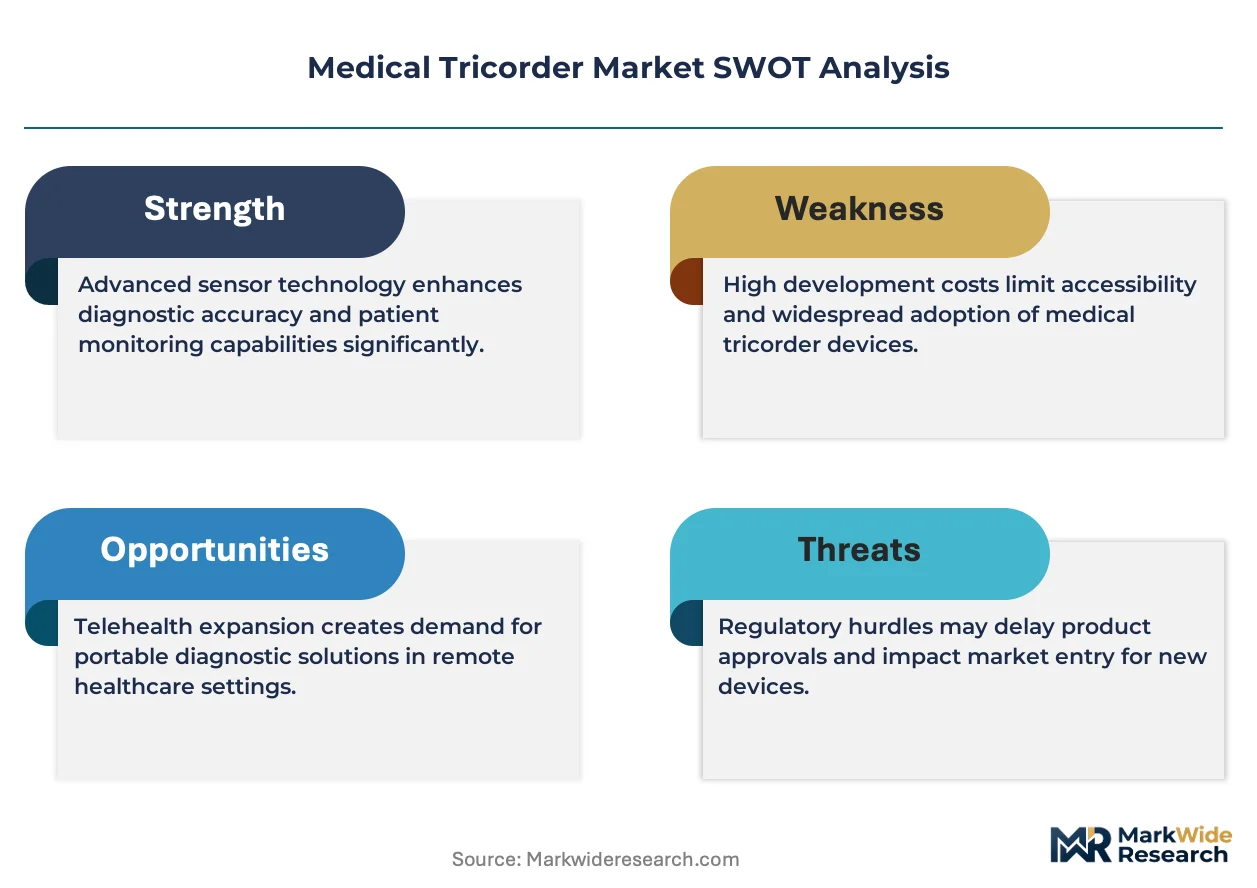
Clinical-grade diagnostic accuracy is collapsing the boundary between consumer wellness gadgets and regulated medical devices. Medtronic leverages its cardiac monitoring heritage to anchor premium positioning in ambulatory diagnostic segments. Qualcomm competes through its Snapdragon Digital Health platform, which extends semiconductor-level integration into handheld form factors. Basil Leaf Technologies specializes in AI-driven symptom analysis, differentiating its DxtER platform through multi-parameter physiological scoring rather than single-vital measurement.
A medical tricorder is a portable, multi-sensor diagnostic device that integrates non-invasive biosensing—electrocardiography, pulse oximetry, infrared thermometry, and acoustic analysis—with onboard clinical decision support algorithms to deliver rapid patient assessment outside traditional laboratory infrastructure. Diagnostic tricorders occupy the largest revenue pool currently, while multimodal tricorders represent the fastest-expanding category as sensor fusion and edge-AI processing enable simultaneous cardiac, respiratory, and metabolic evaluation in a single handheld unit. Hospitals dominate end-user procurement volumes, though home care settings are capturing disproportionate growth as post-acute remote monitoring protocols expand reimbursement eligibility for decentralized diagnostics.
FDA 510(k) premarket notification and EU MDR conformity assessment create divergent compliance burdens that favor manufacturers with established quality management systems and clinical evidence generation capabilities. HIPAA in the United States and GDPR in Europe impose stringent data governance requirements on cloud-connected tricorder architectures, particularly for machine learning models trained on patient-generated health data. Stakeholders must monitor evolving pre-certification frameworks for software-as-a-medical-device to determine whether adaptive algorithm updates will require incremental regulatory submissions or qualify for streamlined post-market change protocols.
Market Dynamics
Sensor fusion architectures are compressing the cost-performance frontier for handheld diagnostics, forcing incumbents to reconfigure R&D roadmaps around edge-AI inference rather than cloud-dependent processing pipelines.
Growth Catalysts
- EU MDR pre-certification pathways:Streamlined conformity assessment for software-as-a-medical-device is accelerating time-to-market for algorithm-driven diagnostic platforms in Germany and the Netherlands.
- Post-acute remote monitoring protocols:Home care settings in Japan are capturing expanded reimbursement eligibility for decentralized physiological assessment devices under METI-guided health technology frameworks.
- Multi-parameter sensor arrays:Integration of photoplethysmography, bioimpedance spectroscopy, and acoustic cardiography into single-chip modules is collapsing device form factors below 200 grams.
Market Restraints
- Clinical validation costs:Generation of predicate-device equivalence data for FDA 510(k) submissions consumes 18-24 months and requires multi-site trial infrastructure.
- Semiconductor supply concentration:Advanced biosensor foundry capacity clusters in Taiwan and South Korea, creating single-source vulnerability for analog front-end components.
- Optical sensor substitution:Smartphone-attachable peripherals with comparable SpO2 and heart-rate accuracy threaten standalone device volumes in consumer-adjacent segments.
Strategic Opportunities
- Rural health network penetration:India's Ayushman Bharat digital health mission is creating procurement corridors for portable diagnostic units in tier-2 and tier-3 district hospitals.
- Convergence of hyperspectral imaging with AI:Non-invasive hemoglobin and glucose estimation through tissue spectroscopy opens metabolic monitoring applications beyond cardiovascular assessment.
- Direct-to-clinic distribution:Bypassing traditional medical device distributors through specialized telehealth platform partnerships is compressing channel margins and accelerating provider onboarding.
Industry Challenges
- Embedded systems firmware talent:Scarcity of engineers with combined biosignal processing and ultra-low-power design expertise is extending product development cycles.
- HIPAA-GDPR dual compliance:Cloud-connected tricorder architectures face conflicting data residency and consent-management requirements when serving cross-border telehealth providers.
- Legacy EHR integration:HL7 FHIR interoperability gaps force custom API development for each hospital system deployment, inflating implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Tricorder Market |
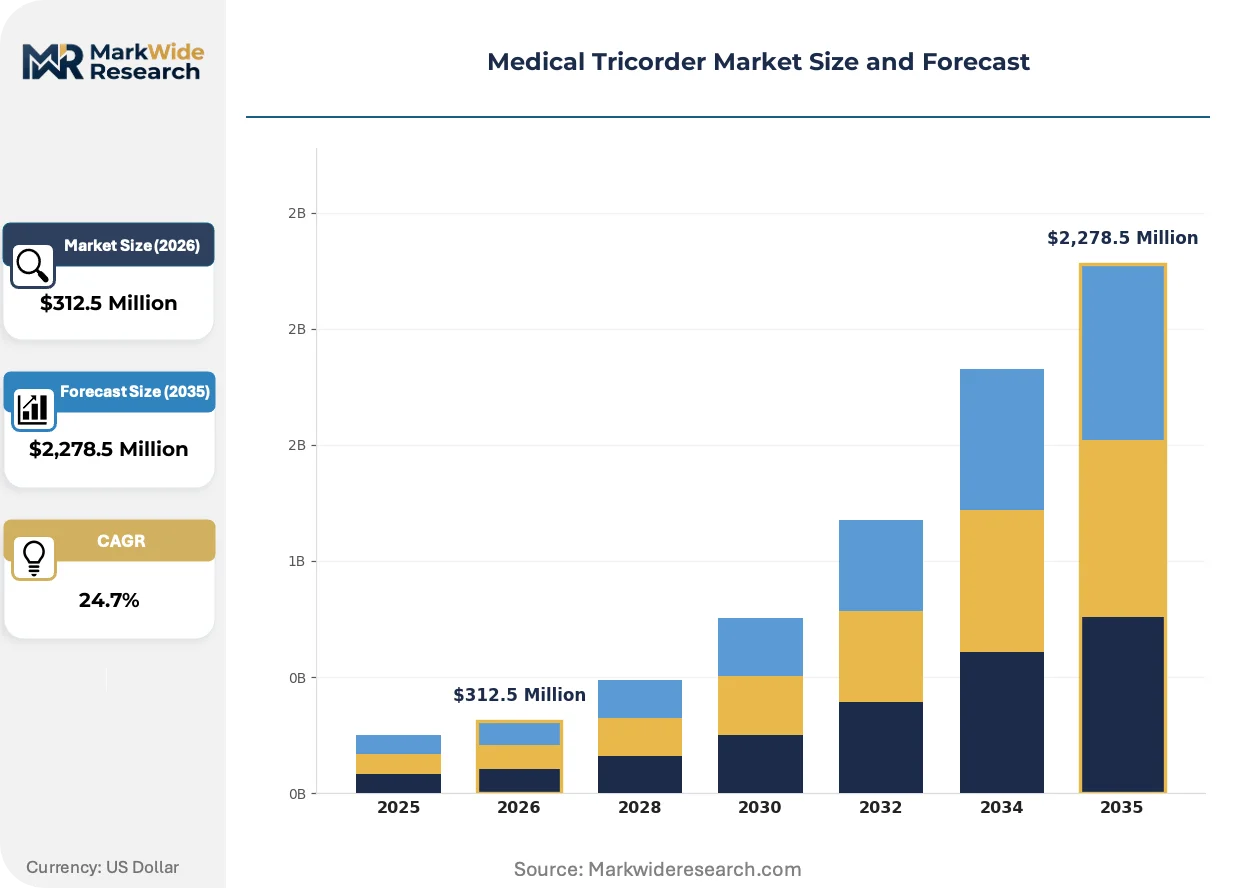
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $2,278.5 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Tricorders, Therapeutic Tricorders, Monitoring Tricorders, Multimodal Tricorders End User: Hospitals, Clinics, Home Care, Research Institutions Technology: Health Information Systems, Machine Learning, Sensor Technologies, Cloud Computing Application: Chronic Disease Management, Acute Care, Preventive Health, Emergency Response |
| Companies Covered | Medtronic, Qualcomm, Philips Healthcare, GE Healthcare, QuantuMDx Group, Cloud DX, Healthy.io, Basil Leaf Technologies, AliveCor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Tricorder Market Strategic Shifts & Innovations
Edge computing migration and algorithmic personalization are redefining where clinical decision-making occurs, shifting diagnostic intelligence from centralized servers to battery-constrained handheld units without sacrificing regulatory-grade accuracy.
Photonic integrated circuits are miniaturizing multi-wavelength optical sensing into silicon substrates previously limited to discrete component assemblies. Ambulatory surgery centers in the United States are piloting these chip-scale spectrometers for real-time tissue oxygenation monitoring during post-operative recovery. The technology is miniaturizing laboratory-grade hematology assays into palm-sized enclosures, collapsing the physical separation between centralized labs and point-of-care decision points.
FDA's pre-certification pilot for software-based medical devices is creating parallel review tracks for machine learning algorithms that adapt to patient-specific physiological baselines. Manufacturers with established quality management systems gain streamlined post-market change protocols for algorithm updates, while newcomers face full 510(k) resubmission requirements. Cardiac monitoring segments see the most pronounced divergence in regulatory velocity between incumbents and challengers.
Hospital procurement committees are unbundling diagnostic hardware from proprietary software subscriptions, demanding API-accessible data architectures that interoperate with existing clinical informatics stacks. This purchasing pattern shift pressures device manufacturers to decouple recurring revenue from captive cloud ecosystems. German hospital systems exhibit the most aggressive stance on data sovereignty and interoperability mandates.
Medical Tricorder Market Segmentation
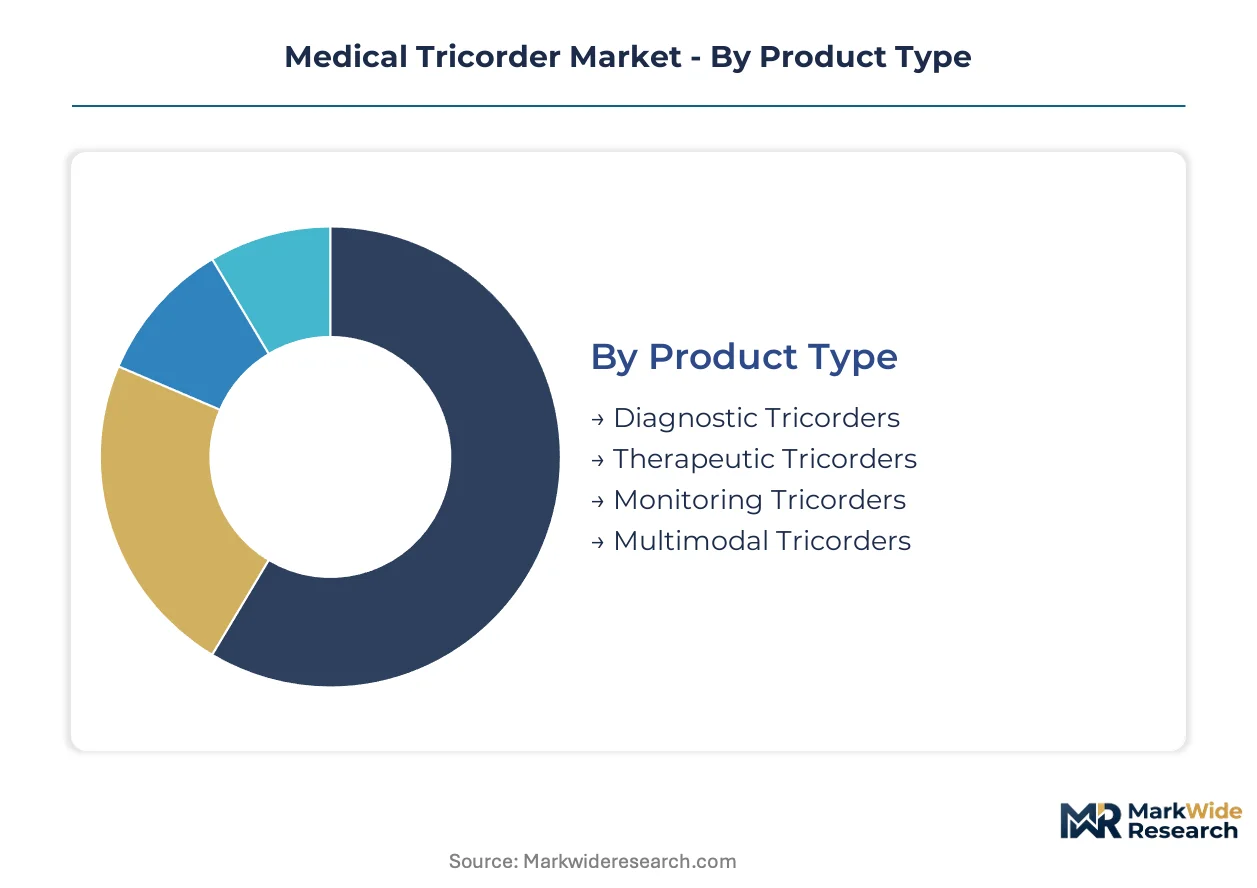
Segmentation in the medical tricorder market reveals how procurement priorities diverge across clinical settings and reimbursement models. Understanding where margin pools concentrate helps manufacturers align R&D investment with the highest-value diagnostic workflows.
Product Type:
Diagnostic tricorders command premium pricing through FDA-cleared cardiac and respiratory algorithms, while multimodal platforms capture expanding share through sensor fusion architectures.
- Diagnostic Tricorders:Single-parameter devices employing electrocardiography, pulse oximetry, or infrared thermometry for targeted physiological assessment. Hospital procurement in the United States and Germany concentrates here for point-of-care triage protocols, though reimbursement codes favor multi-parameter alternatives.
- Multimodal Tricorders:Integrated sensor arrays combining photoplethysmography, bioimpedance spectroscopy, and acoustic analysis with edge-AI inference engines. Japan's METI-guided remote monitoring frameworks and expanded home care eligibility accelerate adoption of these palm-sized units for post-acute patient surveillance.
- Therapeutic Tricorders:Devices incorporating drug delivery modules or neuromodulation capabilities alongside diagnostic sensing.
- Monitoring Tricorders:Continuous ambulatory platforms optimized for longitudinal physiological tracking rather than episodic assessment.
Diagnostic tricorders hold installed capacity. Multimodal tricorders are rotating up the share rankings.
End User:
Procurement volume concentrates in acute care facilities, though reimbursement eligibility shifts are tilting growth toward decentralized settings.
- Hospitals:Large-scale health systems in the United States deploy diagnostic tricorders for emergency department throughput optimization and pre-operative screening. German hospital networks drive interoperability demands through API-accessible data architectures that bypass captive cloud ecosystems.
- Home Care:Post-acute monitoring protocols in Japan and expanding remote patient monitoring reimbursement in the United States position this segment for steepest expansion trajectory. Devices here prioritize battery efficiency and cellular connectivity over clinical-lab precision.
- Clinics:Ambulatory surgery centers and urgent care facilities seeking rapid physiological assessment without capital-intensive laboratory infrastructure.
- Research Institutions:Academic medical centers and clinical trial operators utilizing tricorder platforms for decentralized data collection in pharmaceutical studies.
Hospitals dominate current procurement volumes. Home care is climbing the fastest in absolute growth terms.
Technology:
Cost structures stratify sharply between semiconductor-dependent sensor modules and software-centric algorithm platforms.
- Sensor Technologies:Photonic integrated circuits and multi-wavelength optical sensing fabricated on silicon substrates. Taiwan and South Korean foundry capacity constraints create supply vulnerability for analog front-end components critical to SpO2 and bioimpedance accuracy.
- Machine Learning:Adaptive algorithms trained on patient-specific physiological baselines, subject to FDA pre-certification pathways for software-as-a-medical-device. Manufacturers with established quality management systems gain streamlined post-market change protocols.
- Health Information Systems:HL7 FHIR-compliant data architectures enabling EHR integration without custom API development.
- Cloud Computing:Centralized processing pipelines facing HIPAA-GDPR dual compliance burdens for cross-border telehealth deployments.
Sensor technologies anchor hardware margins. Machine learning is displacing cloud-dependent processing for latency-sensitive diagnostic workflows.
Application:
Clinical utility and reimbursement density vary dramatically across acute versus longitudinal care models.
- Chronic Disease Management:Longitudinal monitoring of heart failure, diabetes, and COPD through daily physiological self-assessment. India's Ayushman Bharat digital health mission creates procurement corridors for portable diagnostic units in district hospital networks serving tier-2 and tier-3 populations.
- Acute Care:Emergency department triage and perioperative monitoring requiring immediate diagnostic output. United States ambulatory surgery centers pilot chip-scale spectrometers for real-time tissue oxygenation assessment during post-operative recovery.
- Preventive Health:Population-scale screening programs and wellness-focused physiological assessment outside disease-specific protocols.
- Emergency Response:Field-deployable diagnostics for paramedic and disaster relief applications prioritizing ruggedization and rapid deployment.
Acute care commands pricing premiums. Chronic disease management is expanding most quickly as reimbursement frameworks mature for decentralized monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Japan and Germany demonstrate lowest price elasticity, accepting premium hardware for regulatory-cleared diagnostic accuracy, while procurement in India and Brazil prioritizes unit cost over algorithmic sophistication.
United States
Emergency department throughput optimization and remote patient monitoring reimbursement expansion drive hospital procurement. FDA 510(k) premarket notification pathways favor established quality management systems. The Greater Boston corridor concentrates AI-driven diagnostic startups alongside academic medical centers running multi-site clinical trials.
Germany
Hospital networks demand API-accessible data architectures that bypass captive cloud ecosystems. EU MDR conformity assessment and GDPR data residency requirements reshape certification timelines. The Baden-Württemberg industrial cluster hosts precision sensor manufacturers supplying photonic integrated circuits for handheld form factors.
Japan
METI-guided health technology frameworks expand home care reimbursement eligibility for decentralized physiological assessment. PMDA consultation procedures accelerate software-as-a-medical-device approvals for adaptive algorithms. The Kanto region around Tokyo anchors domestic production of bioimpedance spectroscopy modules.
India
Ayushman Bharat digital health mission creates procurement corridors for portable diagnostic units in tier-2 and tier-3 district hospitals. CDSCO medical device rules and BIS certification requirements impose phased compliance burdens. The Karnataka-Telangana corridor in South India concentrates electronics manufacturing services for sensor assembly.
United Kingdom
NHS long-term plan targets point-of-care diagnostics for primary care network capacity relief. MHRA post-Brexit regulatory autonomy enables divergence from EU MDR timelines for software-based devices. The Oxford-Cambridge arc hosts clinical validation partnerships between academic medical centers and algorithm developers.
Medical Tricorder Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with semiconductor-integrated platforms commanding premium positioning against sensor-assembly specialists competing on unit economics. The vendor base stratifies across three tiers: diversified medical device conglomerates with cardiac monitoring heritage, digital health platform operators leveraging chipset integration, and AI-native startups differentiating through multi-parameter physiological scoring. Dominant competitive moves include strategic partnerships with telehealth platforms for direct-to-clinic distribution and in-house production of analog front-end components to reduce foundry dependency.
Within the diversified medical device tier, Medtronic and Philips Healthcare exemplify archetypes leveraging installed base relationships for point-of-care hardware deployment. Qualcomm represents semiconductor-level integration strategies, extending chipset architectures into regulated health device form factors. Basil Leaf Technologies occupies a position among AI-native specialists, differentiating through algorithmic approaches rather than sensor hardware ownership.
| Leading Market Players |
|---|
| Medtronic |
| Qualcomm |
| Philips Healthcare |
| GE Healthcare |
| QuantuMDx Group |
| Cloud DX |
| Healthy.io |
| Basil Leaf Technologies |
| AliveCor |
| Others |
Cost & Logistics Intelligence
Foundry-scale economies in photonic integrated circuit fabrication anchor both supply concentration and price floors for handheld diagnostic platforms, compressing margin structures for sensor-assembly specialists while rewarding semiconductor-integrated manufacturers with captive foundry relationships.
Pricing Analysis
FDA 510(k) clearance pathways dictate the pricing tier structure across the medical tricorder landscape, separating premium-cleared cardiac and respiratory algorithms from uncertified wellness-adjacent peripherals. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and algorithmic sophistication, with hospital procurement committees demanding API-accessible architectures that bypass captive cloud subscriptions. Cost compression in the standard tier intensifies as smartphone-attachable peripherals achieve comparable SpO2 accuracy. Home care settings in Japan exhibit lowest price sensitivity, accepting premium hardware for METI-guided reimbursement eligibility, while India's Ayushman Bharat procurement corridors prioritize unit cost over algorithmic depth.
Supply Chain Analysis
Inventory cycles for analog front-end components now stretch eighteen to twenty-four months, constraining production planning for multi-parameter sensor arrays. Advanced biosensor foundry capacity clusters in Taiwan and South Korea, with photonic integrated circuit fabrication drawing from silicon substrate suppliers in the United States and Germany. Single-source vulnerability pervades analog front-end components critical to bioimpedance spectroscopy accuracy. Distribution runs through specialized medical device distributors, though direct-to-clinic telehealth platform partnerships are compressing channel margins and accelerating provider onboarding.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical tricorder market rewards manufacturers who control embedded systems firmware talent combining biosignal processing with ultra-low-power design expertise, a capability gap extending product development cycles for challengers lacking semiconductor heritage.
For Market Incumbents: Secure in-house production of analog front-end components to reduce Taiwan and South Korean foundry dependency, while investing in FDA pre-certification quality management systems to streamline post-market algorithm update protocols. Defend against AI-native challengers by anchoring premium positioning through installed base relationships in cardiac monitoring segments and demanding API-accessible data architectures that interoperate with hospital EHR systems. For New Entrants and Emerging Players: EU MDR pre-certification pathways for software-as-a-medical-device offer the fastest regulatory velocity for algorithm-driven diagnostic platforms in Germany and the Netherlands. Target rural health network penetration in India's tier-2 and tier-3 district hospitals through Ayushman Bharat procurement corridors, positioning portable diagnostic units for chronic disease management workflows. Pursue direct-to-clinic distribution partnerships with telehealth platforms to bypass traditional medical device distributor margins. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors semiconductor-integrated platform operators over sensor-assembly specialists competing on unit economics. Long-term viability hinges on controlling edge-AI inference capabilities rather than cloud-dependent processing pipelines. Monitor FDA pre-certification pilot expansion for software-based medical devices as the inflection signal distinguishing incumbents with streamlined post-market change protocols from newcomers facing full 510(k) resubmission requirements.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pre-Certification Investment | Streamlined post-market change protocols reward established quality management systems with adaptive algorithm update pathways. |
| Photonic Integrated Circuit Integration | Silicon substrate multi-wavelength sensing collapses laboratory-grade hematology assays into palm-sized diagnostic enclosures. |
| Direct-to-Clinic Distribution Partnership | Telehealth platform alliances bypass traditional medical device distributors and accelerate hospital procurement committee onboarding. |
| EU MDR Conformity Assessment | German hospital network API-accessibility demands reshape certification timelines for cloud-connected tricorder architectures. |
| Edge-AI Inference Migration | Onboard clinical decision support displaces cloud-dependent processing for latency-sensitive diagnostic workflows in ambulatory settings. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) premarket notification databases, EU MDR conformity assessment records, hospital procurement committee documentation, and METI-guided health technology framework filings. Primary interviews engaged biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs leads at algorithm-driven diagnostic platform developers. Bottom-up triangulation across product-type unit economics and top-down validation against reimbursement framework expansion patterns ensure analytical consistency.
Segmentation dimensions modeled span diagnostic versus multimodal versus therapeutic versus monitoring tricorder platforms, acute care versus home care versus clinic versus research institution end users, and sensor technology versus machine learning versus health information systems versus cloud computing technology stacks. CAGRs derive from patient monitoring reimbursement eligibility trajectory analysis and semiconductor foundry capacity utilization projections across the modeling period. Forecast inputs incorporate HL7 FHIR interoperability adoption curves and post-acute remote monitoring protocol expansion rates.
Underlying assumptions cover FDA pre-certification pilot program continuity, EU MDR software-as-a-medical-device pathway stability, and Taiwan-South Korean foundry capacity allocation patterns, with deviation risk concentrated in HIPAA-GDPR dual compliance burden escalation and legacy EHR integration cost inflation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Insulin Pumps Market
Medical Devices
Continuous Bladder Irrigation Devices Market
Medical Devices
Latin America Biomedical Sensors Market
Medical Devices
North America Electrophysiology Market
Medical Devices
Brachytherapy Afterloaders Market
Medical Devices
Gel Implants Market
Medical Devices
Knee Reconstruction Devices Market
Medical Devices
Peripheral Interventions Market
Medical Devices
Liver-On-Chip Market
Medical Devices
Global Smart Wearable Healthcare Devices Market
Medical Devices
Human Enhancement Market
Medical Devices
Ehealth Devices Market
Medical Devices
Minimally Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Operating Room Integration Market
Medical Devices
Toe Fixation System Market
Medical Devices
United States Anesthesia Devices Market