
 Coating Pigments Market | 2026-2036
Coating Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Coating Pigments Market Analysis
Multi-source procurement for titanium dioxide feedstock is restructuring supply economics across the coating pigments value chain. BASF SE leverages its integrated petrochemical network to secure precursor supply for organic pigment synthesis. Tronox Holdings Plc anchors chloride-route TiO2 capacity in North American and Australian mineral corridors. Kronos Worldwide, Inc. competes on sulfate-process scale, sustaining cost positions in regions with constrained chloride feedstock access.
Coating pigments are finely dispersed colorants—organic, inorganic, or special-effect particles typically ground to 0.1–5.0 microns—that impart opacity, hue, durability, or functional properties to liquid, powder, or paste coating vehicles. Their primary purpose is to protect substrates while delivering controlled aesthetic and performance outcomes across industrial, decorative, and protective applications. Inorganic pigments, led by titanium dioxide and iron oxide chemistries, dominate volume due to their thermal stability and exterior durability, though margin pools concentrate in special effect pigments where interference and metallic optical properties command formulation premiums. Organic pigments are gaining share in automotive and consumer goods applications where saturated chroma and regulatory-compliant heavy-metal-free formulations displace legacy lead and cadmium systems.
EPA VOC regulations and OSHA workplace exposure limits constrain solvent-borne pigment dispersion practices in the United States, while REACH registration and EU Green Deal carbon-border adjustments tighten chemical transparency and embodied-carbon accountability across European supply chains. China's MEE environmental enforcement and GB standards on hazardous substance limits in coatings are accelerating domestic pigment producer consolidation and cleaner-process investment. Stakeholders must monitor how divergent regional compliance timelines reshape formulation R&D allocation and cross-border pigment trade flows.
Market Dynamics
Waterborne coating conversion across automotive OEMs is compressing solvent-borne pigment demand while restructuring formulation R&D priorities toward dispersant-surfactant compatibility and reduced-VOC grind systems.
Growth Catalysts
- REACH Phase-Out Mandates:EU restrictions on heavy-metal pigments are accelerating cadmium and lead chromate substitution with high-performance organic alternatives in industrial coatings.
- Automotive Electrification:Battery enclosure and thermal management coatings require specialized ceramic and IR-reflective pigments that command formulation premiums.
- China Domestic Scale:Concentrated architectural coating production in Jiangsu and Guangdong provinces is absorbing expanded local TiO2 and iron oxide capacity.
Market Restraints
- Chloride-Route Feedstock Concentration:Synthetic rutile and slag supply from Australian and South African mineral corridors exposes TiO2 producers to bulk shipping rate volatility.
- MEE Enforcement Burden:China's environmental inspections impose intermittent production halts on sulfate-process pigment plants lacking wastewater treatment upgrades.
- Interference Pigment Technical Ceiling:Thin-film optical stack deposition remains limited to substrate geometries compatible with physical vapor deposition chambers.
Strategic Opportunities
- India Industrial Coating Expansion:PLI scheme incentives for domestic manufacturing are creating localized pigment blending and distribution infrastructure gaps.
- Photocatalytic Functionalization:TiO2 surface modification for air-purifying and self-cleaning coatings converges with architectural green building certification requirements.
- Direct-to-Formulator Digital Channels:Specialty pigment producers are bypassing distributor markups through color-matching software platforms integrated with coating company R&D workflows.
Industry Challenges
- Colorimetric Specialist Scarcity:Formulation chemists with expertise in multi-pigment grinding and flocculation control are concentrated among legacy coating companies.
- Cross-Border Registration Complexity:Divergent REACH, TSCA, and China NMPA new chemical notification timelines delay specialty pigment commercialization by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coating Pigments Market |
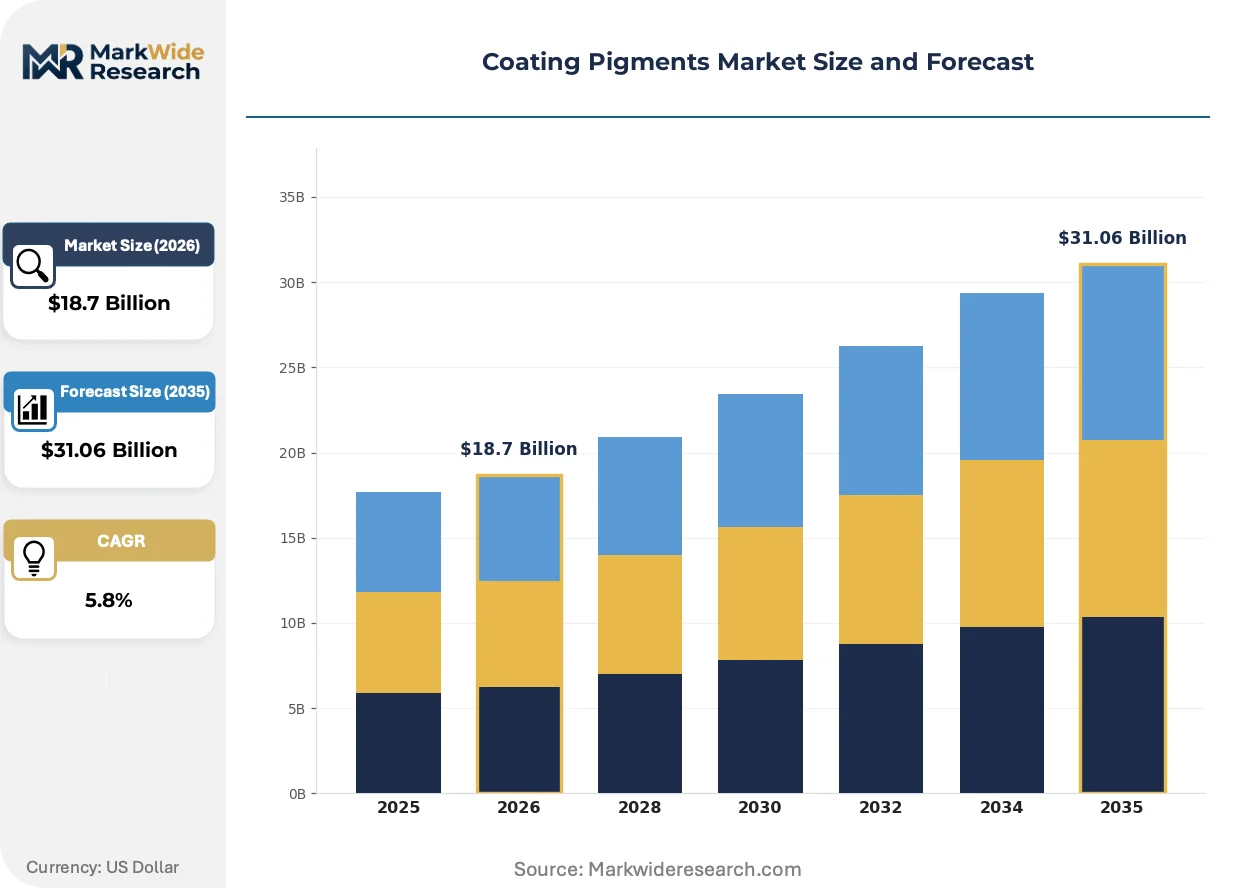
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Organic Pigments, Inorganic Pigments, Special Effect Pigments, Transparent Pigments End User: Automotive, Construction, Aerospace, Consumer Goods Application: Decorative Coatings, Industrial Coatings, Wood Coatings, Protective Coatings Form: Powder, Liquid, Paste, Granules |
| Companies Covered | PPG Industries Inc., AkzoNobel NV, The Sherwin-Williams Company, BASF SE, Tronox Holdings Plc, Kronos Worldwide, Inc., DIC Corporation, Venator Materials PLC, Heubach GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coating Pigments Market Emerging Trajectories
Digital color specification tools and predictive dispersion modeling are compressing traditional trial-and-error formulation cycles while enabling remote technical service delivery.
Encapsulated organic pigment technologies with engineered polymer shells are modularizing colorant handling across waterborne automotive basecoat lines. Tier-1 automotive coaters in Germany and the US Midwest are adopting these systems to eliminate dust exposure and reduce cleaning solvent consumption. The technology is modularizing pigment supply relationships by allowing just-in-time colorant sequencing rather than bulk inventory positions.
EU Green Deal carbon-border adjustment mechanisms are embedding embodied-carbon documentation requirements into pigment procurement specifications. Coating formulators must now trace TiO2 process emissions from ilmenite mining through chloride or sulfate upgrading. Architectural coating producers serving EU export markets are prioritizing suppliers with verified low-carbon process routes.
Coating manufacturers are consolidating pigment supplier rosters to reduce qualification overhead and secure volume commitments. Large industrial coaters in China and the US are shifting from 15-20 approved pigment vendors to 5-7 strategic partnerships with integrated dispersion and color-matching services. This concentration is most visible in automotive refinish and coil coating segments where color consistency requirements are stringent.
Coating Pigments Market Segmentation
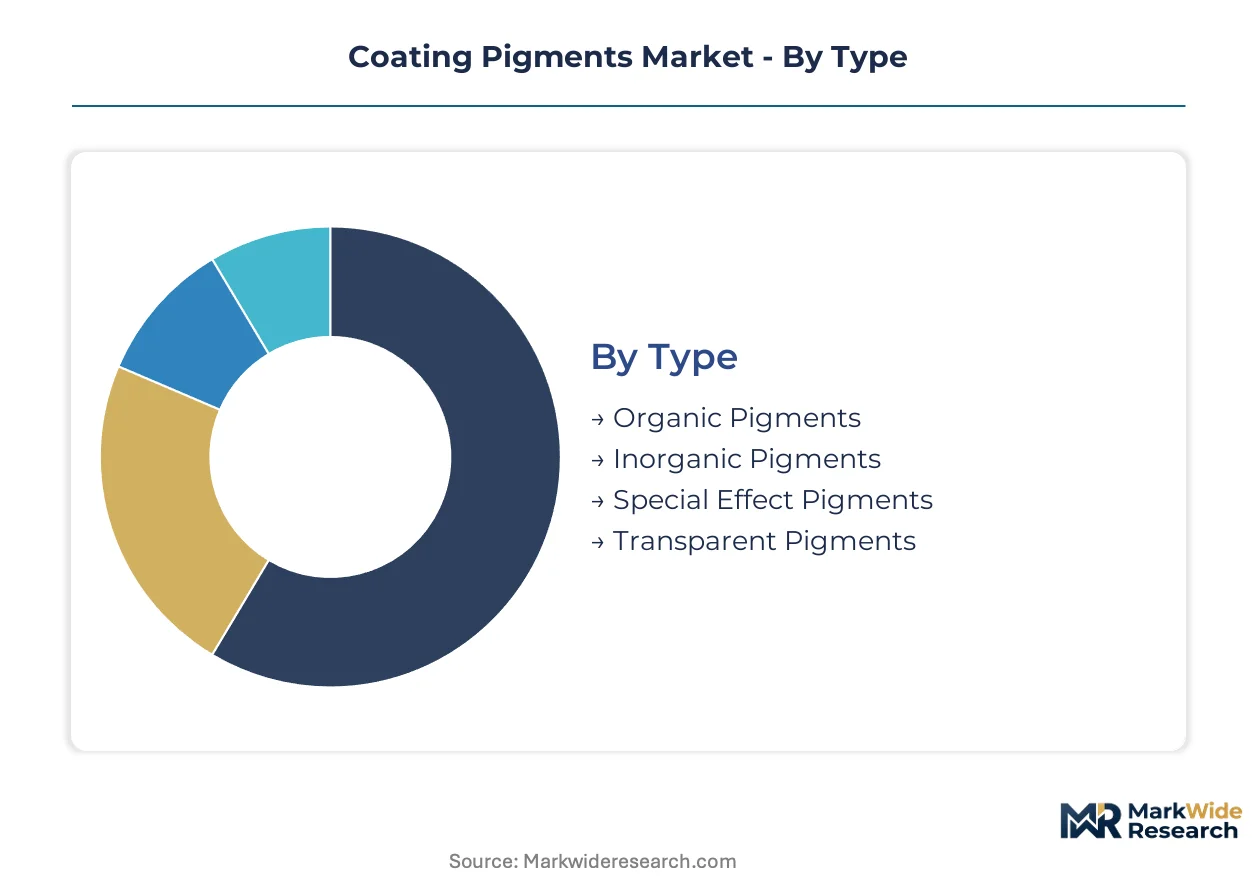
Coating pigment segmentation reveals how formulation requirements diverge across substrate protection needs, regulatory constraints, and application-specific performance thresholds. Understanding these divides enables suppliers to align R&D investment with margin concentration and procurement consolidation trends reshaping buyer-supplier relationships.
Type:
Integration depth varies sharply: inorganic pigments function as standalone opacity engines across formulations, while special effect pigments embed within complex optical systems requiring precise substrate alignment.
- Inorganic Pigments:Titanium dioxide and iron oxide chemistries deliver thermal stability and exterior durability through refractive index engineering. Demand concentrates in Chinese architectural coating clusters where domestic sulfate-process TiO2 capacity expansion is displacing import dependency. EPA VOC rules and MEE wastewater standards constrain sulfate-process plant economics, favoring chloride-route producers with integrated mineral supply.
- Organic Pigments:Azo and phthalocyanine structures provide saturated chroma with heavy-metal-free compliance for automotive basecoats and consumer goods. REACH cadmium and lead chromate phase-outs are accelerating substitution programs across German and French industrial coating sectors. Formulators prize these pigments for dispersibility in waterborne grind systems where solvent-borne compatibility is diminishing.
- Special Effect Pigments:Interference and metallic optical stacks command formulation premiums through physical vapor deposition manufacturing.
- Transparent Pigments:Nanoscale particle distributions enable tinted clearcoats with maintained substrate visibility.
Inorganic pigments lead volumes today; organic pigments are gaining share fastest.
End User:
Cost tier stratification separates specification-intensive OEM applications from price-sensitive maintenance coating buyers with divergent technical service requirements.
- Automotive:OEM basecoat and clearcoat systems demand batch-to-batch colorimetric precision within ΔE 0.3 tolerance. Waterborne conversion across US Midwest and German assembly plants is restructuring pigment dispersion R&D toward surfactant compatibility and reduced-VOC grind systems. Electrification is creating specialized demand for ceramic pigments in battery enclosure thermal management coatings.
- Construction:Architectural coating producers prioritize TiO2 opacity efficiency and iron oxide weathering stability across exterior emulsion systems. Chinese Jiangsu and Guangdong production clusters absorb expanded domestic pigment capacity while EU Green Deal carbon-border adjustments embed embodied-carbon documentation into procurement specifications.
- Aerospace:Chromate-free pretreatment and topcoat systems drive qualified pigment supplier rosters with extensive OEM certification timelines.
- Consumer Goods:Appliance and electronics coatings emphasize heavy-metal-free compliance with saturated color performance.
Construction leads volumes today; automotive is climbing the fastest.
Application:
Volume concentration sits with high-throughput decorative coating production, while margin pools concentrate in protective coatings requiring specialized corrosion resistance.
- Decorative Coatings:Architectural emulsions and enamels consume bulk TiO2 and iron oxide volumes through opacity and tinting strength requirements. Chinese domestic production scale is compressing import pigment market share while accelerating local producer consolidation under MEE environmental enforcement.
- Industrial Coatings:Coil and general industrial finishes balance cost efficiency with durability specifications across metal substrate protection. REACH heavy-metal restrictions and OSHA workplace exposure limits are constraining legacy pigment systems while opening substitution opportunities for high-performance organic alternatives.
- Wood Coatings:Furniture and flooring applications emphasize transparency and UV stability through nanoscale pigment dispersions.
- Protective Coatings:Infrastructure and marine systems require specialized zinc-rich and micaceous iron oxide formulations for cathodic protection.
Decorative coatings lead volumes today; protective coatings are expanding most quickly.
Form:
Supply concentration favors integrated dispersion producers with captive milling and surface treatment capabilities serving just-in-time coating manufacturing.
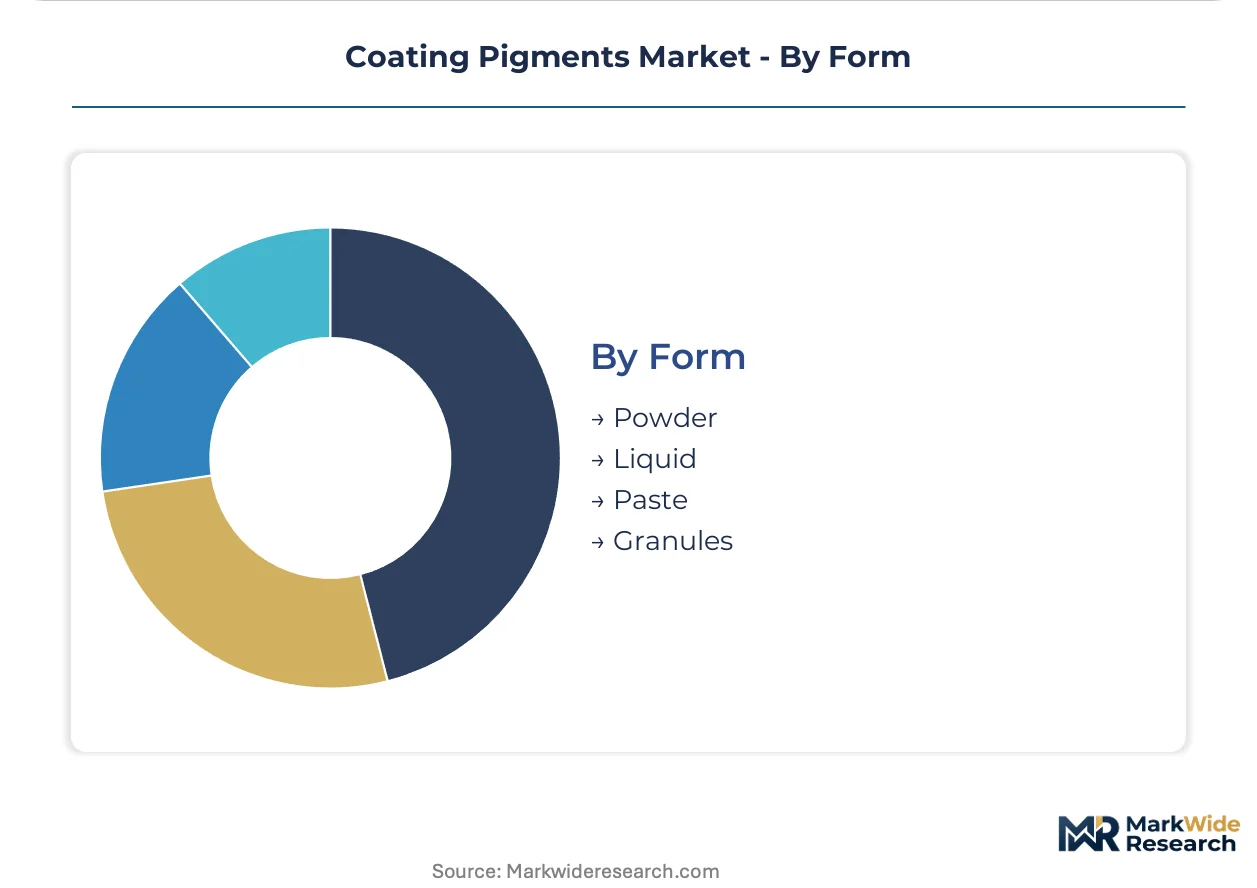
- Powder:Dry pigment concentrates require downstream dispersion equipment but enable flexible formulation blending across coating production scales. German and US automotive refinish sectors are consolidating supplier rosters toward powder pigment partners with integrated color-matching software platforms.
- Liquid:Predispersed pigment concentrates eliminate dust exposure and reduce cleaning solvent consumption through encapsulated organic pigment technologies with engineered polymer shells. Tier-1 automotive coaters are adopting these systems for just-in-time colorant sequencing.
- Paste:High-solids dispersions target specific coating vehicle chemistries with optimized rheology control.
- Granules:Low-dust handling formats serve powder coating manufacturers with direct extrusion integration.
Powder leads volumes today; liquid is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Guangdong provinces concentrate coating pigment consumption through architectural coating production clusters serving domestic construction demand. Regional regulatory divergence is reshaping formulation standards and procurement specifications across manufacturing geographies.
China
Domestic TiO2 and iron oxide capacity expansion in Jiangsu and Guangdong is displacing import dependency across architectural emulsion systems. MEE environmental inspections enforce GB standards on hazardous substance limits, triggering plant consolidation among sulfate-process producers lacking wastewater treatment upgrades. Shanghai-based coating manufacturers are prioritizing suppliers with verified low-carbon process routes to meet EU export documentation requirements.
Germany
Automotive OEM basecoat programs in Stuttgart and Munich are accelerating waterborne conversion, restructuring pigment dispersion R&D toward surfactant compatibility. REACH cadmium and lead chromate phase-outs constrain legacy industrial coating formulations, opening substitution opportunities for high-performance organic alternatives. BASF SE anchors organic pigment synthesis through its integrated Ludwigshafen petrochemical network.
United States
EPA VOC regulations and OSHA workplace exposure limits constrain solvent-borne pigment dispersion practices across Midwest automotive assembly plants. Tier-1 coaters in Michigan and Ohio are consolidating supplier rosters toward powder pigment partners with integrated color-matching platforms. Chloride-route TiO2 producers leverage North American mineral corridor access to sustain cost positions against sulfate-process competitors.
India
PLI scheme incentives for domestic manufacturing are creating localized pigment blending infrastructure gaps across Maharashtra and Gujarat industrial zones. BIS standards on coating composition are tightening formulation transparency requirements for construction and automotive applications. Mumbai-based coating producers are absorbing expanded local iron oxide capacity while qualifying specialty organic pigment imports for automotive refinish segments.
Japan
Automotive electrification is creating specialized demand for ceramic pigments in battery enclosure thermal management coatings across Kanto manufacturing clusters. METI industrial standards emphasize heavy-metal-free compliance in consumer goods applications, favoring phthalocyanine and azo pigment systems. Osaka-based electronics coaters are adopting encapsulated organic pigment technologies to eliminate dust exposure in waterborne basecoat lines.
Coating Pigments Market Vendor Landscape
Global majors compete with regional champions across feedstock integration depth and dispersion technology capabilities. Market structure tilts toward consolidated supply relationships in automotive and coil coating segments where color consistency requirements are stringent, while architectural coating procurement retains fragmented multi-vendor patterns. Three archetypes dominate: integrated petrochemical networks securing precursor supply, mineral-corridor-anchored chloride-route producers, and specialty dispersion specialists with captive milling capabilities. Capacity expansion and strategic partnerships represent the dominant competitive moves as formulators consolidate approved vendor rosters.
Within the integrated chemical network tier, BASF SE and DIC Corporation exemplify backward control over organic pigment synthesis precursors. Tronox Holdings Plc occupies a position among mineral-corridor-anchored producers leveraging Australian and North American synthetic rutile access. Among specialty dispersion specialists, Heubach GmbH represents the European archetype of integrated color-matching and technical service capabilities serving just-in-time automotive manufacturing requirements.
| Leading Market Players |
|---|
| PPG Industries Inc. |
| AkzoNobel NV |
| The Sherwin-Williams Company |
| BASF SE |
| Tronox Holdings Plc |
| Kronos Worldwide, Inc. |
| DIC Corporation |
| Venator Materials PLC |
| Heubach GmbH |
| Others |
Supply Flow & Price Mechanics
Ilmenite and synthetic rutile price indices cascade through chloride and sulfate process routes into tiered pigment pricing structures, with automotive OEMs absorbing premium grades while architectural coating producers in China negotiate on domestic sulfate-process scale.
Pricing Analysis
Input-cost pass-through from titanium feedstock volatility stratifies pricing across premium chloride-route TiO2, standard sulfate-process grades, and economy iron oxide alternatives. Price differentiation hinges on carbon-intensity certification and volume scale commitments, with EU Green Deal documentation requirements widening spreads between verified low-carbon and conventional process routes. Cost compression in architectural-grade sulfate TiO2 intensifies as Jiangsu capacity expansion outpaces demand absorption. Tier-1 automotive coaters exhibit lowest price sensitivity, while regional Chinese emulsion producers drive hard bargaining on iron oxide tinting pastes.
Supply Chain Analysis
Single-source vulnerability sits with Australian and South African synthetic rutile corridors feeding chloride-route TiO2 producers. Geographic supply concentration clusters in China for sulfate-process TiO2 and iron oxides, Germany for organic pigment synthesis, and the United States for chloride-route mineral processing. Raw material dependencies span ilmenite, petroleum-derived pigment precursors, and engineered polymer encapsulation resins. Tariff exposure on bulk mineral shipments from South African slag producers compounds logistics chokepoint risks at Rotterdam and Singapore transshipment hubs. Distribution runs through integrated dispersion specialists with captive milling capabilities serving just-in-time automotive manufacturing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder anchored by irreversible regulatory mandates that phase out heavy-metal pigments and mandate carbon disclosure across EU export supply chains.
For Market Incumbents: Anchor market position through backward integration into synthetic rutile supply corridors and captive dispersion capacity expansion in German and US Midwest automotive clusters. Defend against emerging Chinese sulfate-process scale by securing REACH pre-registration dossiers for specialty organic pigment portfolios. Prioritize certification investment in ISO 14064 carbon accounting to meet EU Green Deal procurement specifications. For New Entrants and Emerging Players: Regional Indian industrial coating blenders represent the most penetrable buyer archetype, with Maharashtra and Gujarat infrastructure gaps creating first-mover opportunities. Target photocatalytic TiO2 functionalization for architectural green building certification programs as a differentiated entry wedge. Deploy direct-to-formulator digital color-matching platforms to bypass established distributor networks. For Investors and Strategic Acquirers: Asymmetric upside sits with specialty dispersion specialists possessing integrated technical service capabilities and automotive OEM qualification rosters. Long-term viability over the coming decade rests on regulatory compliance depth rather than commodity scale. Monitor chloride-route feedstock contract renewal cycles as inflection indicators for TiO2 producer margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Rutile | Tronox and Kronos secure Australian mineral corridor access against shipping rate volatility. |
| Encapsulated Organic Pigment Scale-Up | BASF and Heubach eliminate dust exposure for German Tier-1 automotive waterborne lines. |
| Photocatalytic Surface Modification | TiO2 producers align with LEED and BREEAM air-purifying coating certification requirements. |
| Direct-to-Formulator Digital Channel | Specialty pigment vendors bypass distributor markups through integrated color-matching software. |
| Carbon-Intensive Process Route Divestment | EU Green Deal documentation pressures sulfate-process plant consolidation in China. |
Methodological Framework
Bottom-up coating formulation modeling reconciled against top-down pigment production tracking forms the analytical core of this study. Primary interviews with technical R&D directors at automotive OEM coaters, procurement leads at architectural emulsion producers, plant managers at TiO2 manufacturing facilities, and distribution channel partners in European and Asian markets combined with secondary validation from customs trade data, SEC 10-K filings, and ECHA REACH registration databases. Top-down supply-side verification against bottom-up demand segmentation ensures cross-dimensional consistency.
Historical trendline analysis across pigment consumption patterns, process route capacity additions, and regulatory compliance timelines informed the projection framework. Segmentation dimensions modeled include pigment chemistry type, end-use industry vertical, application format, and regional production hub clustering. CAGRs were derived through regression analysis of volume trajectories against macroeconomic drivers and policy implementation schedules. Forecast inputs incorporated automotive electrification content shifts, MEE enforcement intensity scenarios, and EU carbon-border adjustment mechanism phase-in assumptions.
Underlying measurement precision varies by segment; automotive OEM and coil coating demand carries tighter precision than fragmented architectural maintenance markets. Forecasts reflect documented assumptions regarding regulatory timeline adherence, feedstock price continuity, and technology substitution elasticities. MEE inspection intensity variability, shipping rate volatility on South African mineral corridors, and REACH authorization delays for legacy pigments represent specific revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Antimicrobial Coil Coating Market
Coatings
Soft Touch Polyurethane Coatings Market
Coatings
Insulation Coating Market
Coatings
Global Polyaspartic Coatings Market
Coatings
Wood Preservative Coatings Market
Coatings
Global Cellulosic Fire Protection Intumescent Coatings Market
Coatings
Marine Nanocoating Market
Coatings
Global Nanocoatings Market
Coatings
BPA-Free Coatings Market
Coatings
Global Intumescent Coatings Market
Coatings
Asia-Pacific Radiation Curable Coatings Market
Coatings
North America Anti-Friction Coatings Market
Coatings
Global Solar Panel Coatings Market
Coatings
2K Protective Coatings Market
Coatings
Global Powder Coating Market
Coatings
Fire Retardant Coatings Market