
 Europe Gelatin Market | 2026-2036
Europe Gelatin Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Gelatin Market Foresight
Collagen peptides is pivoting toward pharmaceutical-grade applications as hydrolyzed variants displace regular gelatin in high-margin capsule formulations. PB Leiner leverages its Belgian rendering network to sustain regional supply security for pharmaceutical clients. Gelita AG anchors German production capacity with specialized bone-sourced gelatin lines. Rousselot competes through porcine-to-bovine substitution expertise aligned with halal and kosher certification requirements.
Europe gelatin comprises denatured collagen extracted from mammalian or piscine connective tissues through acid or alkaline processing, yielding gels with Bloom strengths ranging from 50 to 300 grams for food binding, capsule formation, and cosmetic stabilization. Collagen peptides commands premium positioning as the fastest-expanding product type due to bioactive peptide demand in functional nutrition. Pharmaceutical grade concentrates margin pools where endotoxin limits and traceability requirements filter out commodity producers. Nutraceuticals application outpaces food and beverages growth as aging demographics drive joint-health and skin-elasticity formulations.
EMA pharmaceutical excipient guidelines and EU Green Deal circular-economy mandates shape product standards by enforcing traceable sourcing and reduced rendering waste discharge. REACH chemical registration and EFSA novel food assessments govern market access for fish-derived and recombinant collagen alternatives entering European supply chains. Stakeholders must monitor ECHA biomass sustainability criteria and national rendering capacity constraints as bovine spongiform encephalopathy-era sourcing rules tighten across member states.
Market Dynamics
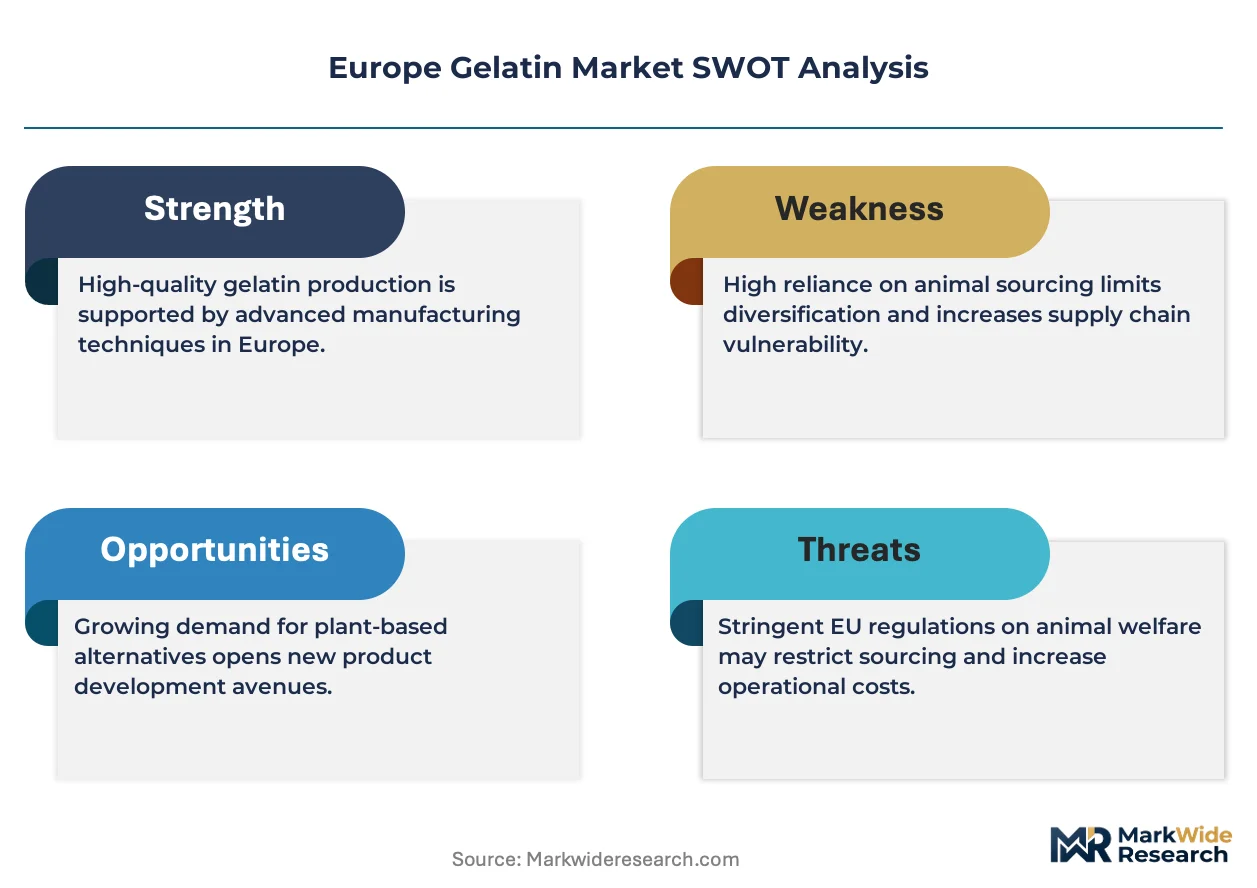
EMA pharmaceutical excipient guidelines and EU Green Deal circular-economy mandates are compressing supplier margins while rewarding traceable sourcing investments across rendering networks.
Growth Catalysts
- Pharmaceutical capsule demand:German and French manufacturers are expanding gelatin procurement as endotoxin-compliant sourcing becomes mandatory for EU market access.
- REACH chemical registration:Fish-derived collagen alternatives face streamlined approval pathways, accelerating novel ingredient commercialization.
- Hydrolyzed peptide bioactivity:Functional nutrition formulators in Italy, Spain, and the Netherlands are driving nutraceutical application expansion.
Market Restraints
- Bovine spongiform encephalopathy-era sourcing rules:Member-state rendering capacity constraints limit bovine-derived gelatin availability for pharmaceutical-grade production.
- Porcine supply concentration:Belgian and Dutch rendering network dominance creates single-point vulnerability for regional pharmaceutical clients.
- Recombinant collagen substitution:Precision fermentation alternatives threaten commodity gelatin positioning in cosmetic stabilization applications.
Strategic Opportunities
- Halal and kosher certification gaps:Spain and Poland present underpenetrated demand pools for porcine-to-bovine substitution expertise.
- EMA novel excipient pathways:Accelerated assessment frameworks reward early movers in pharmaceutical-grade hydrolyzed variants.
- Rendering waste-to-collagen valorization:EU Green Deal biomass sustainability criteria create circular-economy premium positioning for compliant suppliers.
Industry Challenges
- Endotoxin testing capacity:Pharmaceutical-grade certification timelines extend 12-18 months due to laboratory bottleneck concentration in Germany and Switzerland.
- Legacy acid-alkali processing retrofit:Bone-sourced gelatin lines require capital-intensive modernization to meet EFSA traceability requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Gelatin Market |
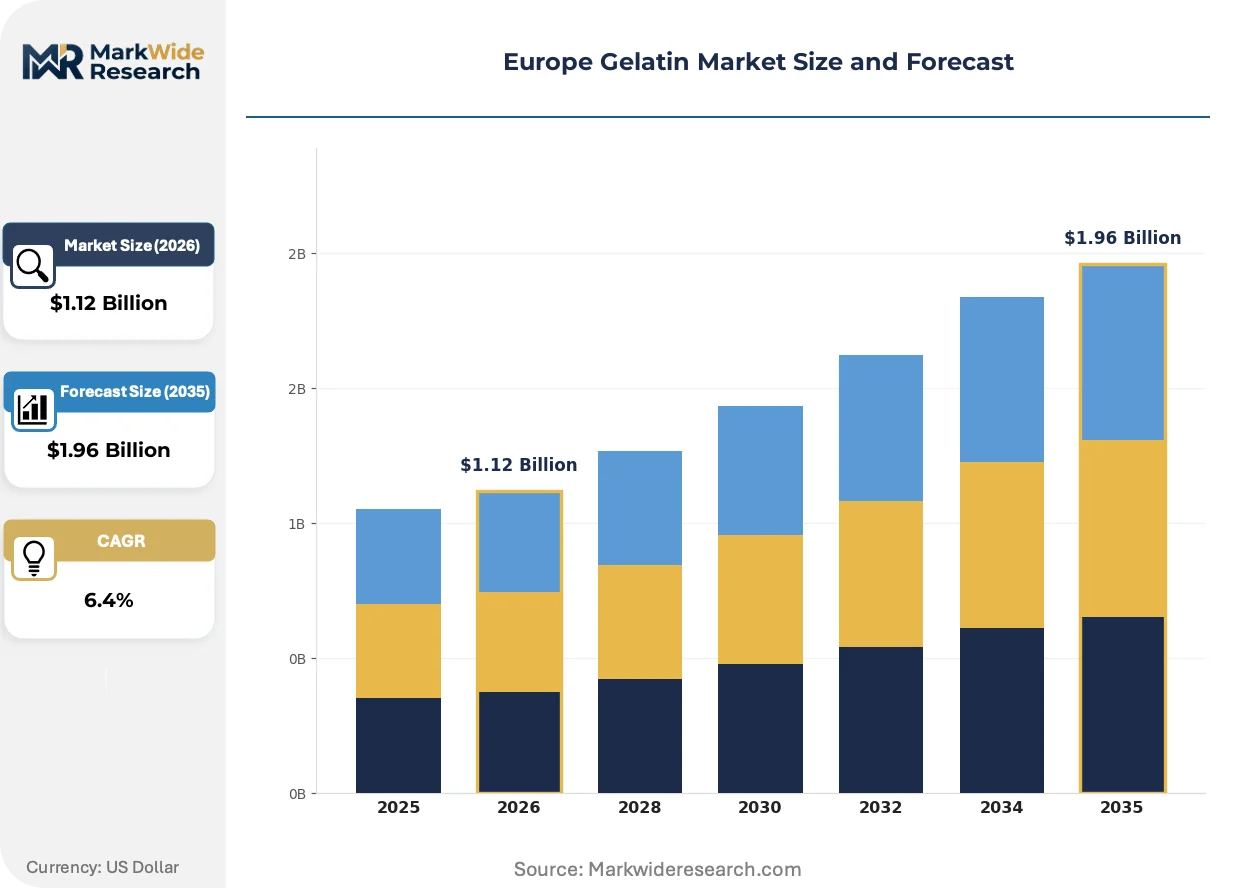
| Market Size in 2026 | $1.12 Billion |
| Market Size in 2035 | $1.96 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular Gelatin, Hydrolyzed Gelatin, Collagen Peptides, Fizzing Gelatin Application: Pharmaceuticals, Food & Beverages, Cosmetics, Nutraceuticals Grade: Food Grade, Pharmaceutical Grade, Technical Grade, Industrial Grade Form: Powder, Granules, Sheets, Capsules |
| Companies Covered | Italgelatine, PB Leiner, Gelita AG, Juncà Gelatines, Rousselot, Gelatines Weishardt, Lapi Gelatine, Trobas Gelatine, Ewald-Gelatine GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Gelatin Market Shifts & Advancements
Processing technology and regulatory compliance frameworks are compressing the supplier base while elevating bioactive peptide positioning across functional nutrition channels.
Enzymatic hydrolysis is consolidating control over peptide molecular weight distribution for joint-health formulations. Nutraceutical contract manufacturers in the Netherlands and Italy are adopting continuous-flow reactor systems to reduce batch-to-batch variability. This consolidation is compressing toll-processing margins while rewarding in-house enzymatic capability investments.
EU Green Deal rendering waste discharge regulations are mandating closed-loop water recovery systems at production facilities. The industrial consequence is capital barrier elevation for mid-scale producers without integrated wastewater treatment. Pharmaceutical-grade concentrate manufacturers in Germany and Belgium are responding by consolidating rendering partnerships under long-term offtake agreements with traceability guarantees.
Direct-to-brand procurement is displacing traditional ingredient distributor intermediation for collagen peptide volumes above 50 metric tons annually. Sports nutrition and beauty-from-within formulators are establishing captive supply relationships with Belgian and German producers. This pattern is most visible in Dutch and Spanish markets where brand-owned product development teams negotiate specification directly.
Europe Gelatin Market Segmentation
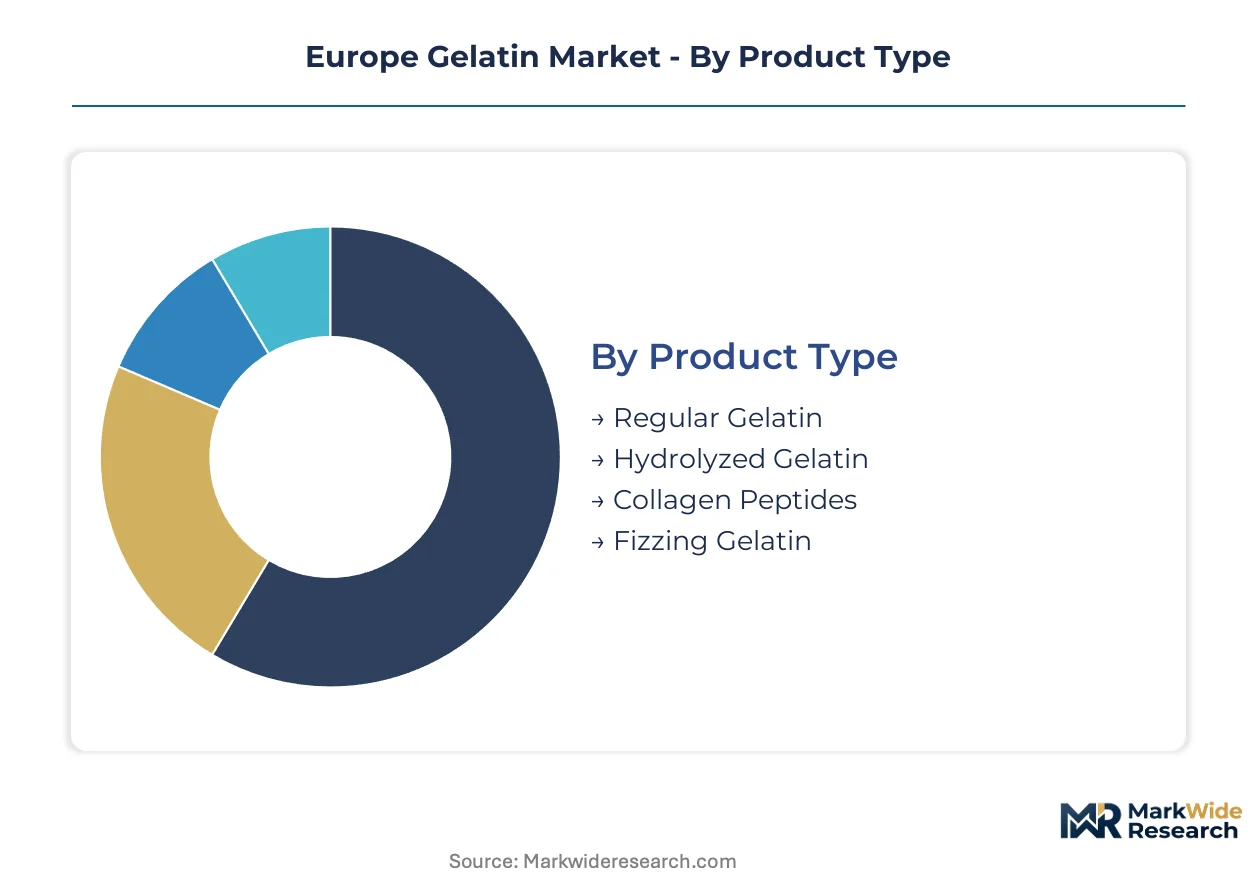
Segmentation in the Europe gelatin market reflects divergent technical specifications and regulatory burdens across end-use channels. Pharmaceutical and nutraceutical applications impose endotoxin limits and traceability requirements that commodity food-grade production cannot satisfy.
Product Type:
Standardization dominates at the commodity end with Bloom-strength gelatin, while hydrolyzed variants command premium positioning through enzymatic precision.
- Regular Gelatin:Denatured collagen with Bloom strengths from 50 to 300 grams serves food binding and conventional capsule formation. Demand concentrates in German and French pharmaceutical manufacturing where EMA excipient guidelines enforce consistent gelling properties.
- Hydrolyzed Gelatin:Enzymatic cleavage reduces molecular weight for enhanced bioavailability in functional nutrition formulations. Italian, Spanish, and Dutch nutraceutical contract manufacturers are driving procurement expansion for joint-health and skin-elasticity applications.
- Collagen Peptides:Bioactive peptide fractions with specified molecular weight distributions command pharmaceutical-grade margins.
- Fizzing Gelatin:Carbonation-reactive formulations for effervescent delivery systems in sports nutrition and antacid applications.
Most installed capacity flows through Regular Gelatin. Expansion is steepest in Collagen Peptides.
Application:
Margin pools concentrate where regulatory certification creates supply scarcity, separating pharmaceutical and nutraceutical channels from commodity food processing.
- Pharmaceuticals:Hard and soft capsule manufacturing demands endotoxin-compliant sourcing with full batch traceability. German manufacturers are expanding procurement under tightened EU Green Deal rendering regulations.
- Nutraceuticals:Functional nutrition formulators in the Netherlands and Italy specify hydrolyzed variants for joint-health positioning. Aging demographics across Spain and Poland sustain demand acceleration for bioactive peptide formulations.
- Food & Beverages:Confectionery, dairy, and meat processing applications utilize standard Bloom-strength gelatin for texture modification.
- Cosmetics:Film-forming and stabilizing applications in topical formulations face substitution pressure from recombinant collagen alternatives.
Pharmaceuticals captures the highest margin per kilogram. Nutraceuticals is gaining share fastest.
Grade:
Certification tiers create pricing stratification that separates traceable pharmaceutical supply from industrial commodity flows.
- Pharmaceutical Grade:Endotoxin limits below specified thresholds and full rendering-to-capsule traceability satisfy EMA excipient guidelines. Laboratory certification bottlenecks in Germany and Switzerland extend qualification timelines.
- Food Grade:EFSA safety assessments govern specifications for direct consumption applications across confectionery and dairy processing.
- Technical Grade:Intermediate purity for photographic and adhesive industrial applications with reduced protein content requirements.
- Industrial Grade:Lowest specification tier for non-consumable binding and sizing applications.
Pharmaceutical Grade commands premium positioning. Food Grade maintains volume dominance.
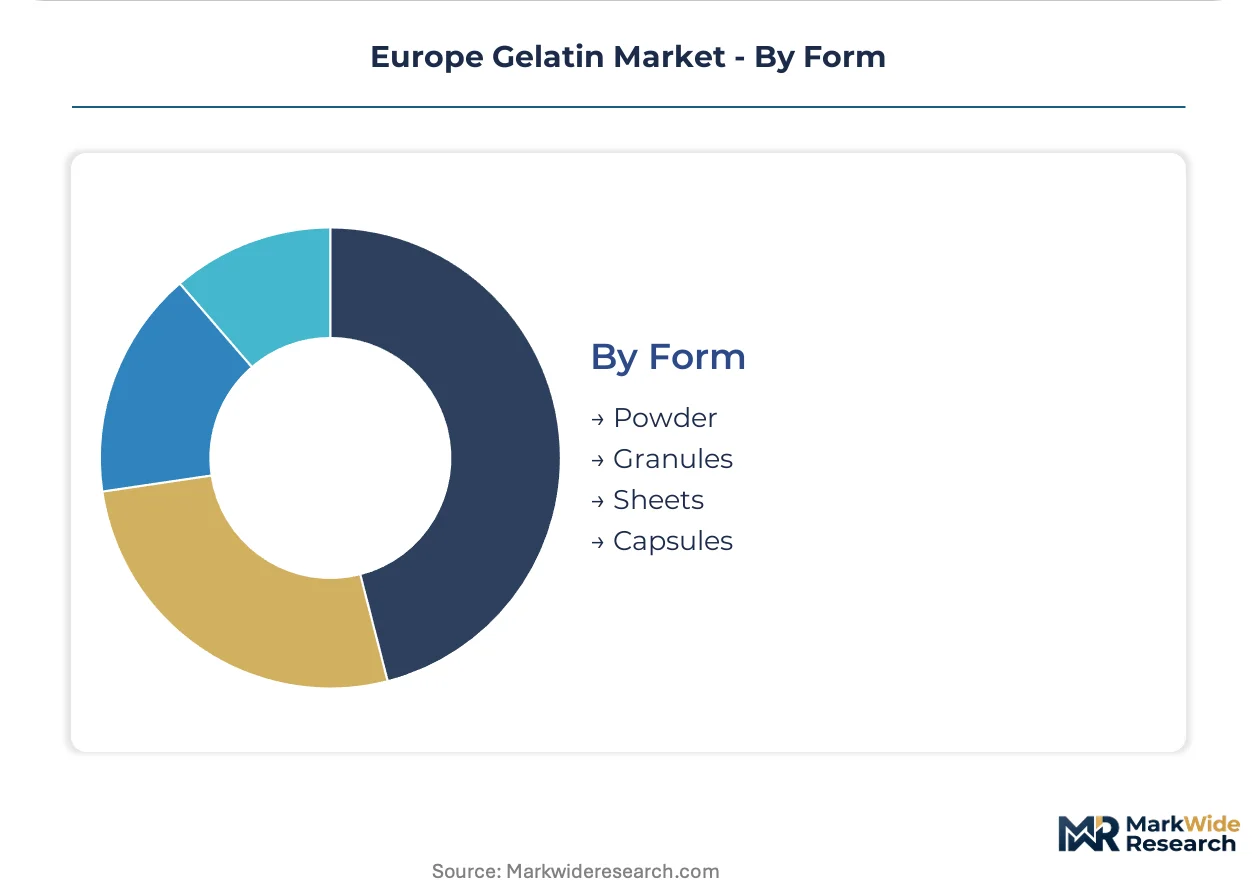
Form:
Processing convenience and dissolution kinetics determine form selection across manufacturing setups and end-use requirements.
- Powder:Fine particle size enables rapid hydration and uniform distribution in dry blend nutraceutical formulations.
- Granules:Reduced dusting and improved flow characteristics suit high-volume pharmaceutical capsule production lines.
- Sheets:Standardized thickness for professional culinary and confectionery applications requiring precise gel strength control.
- Capsules:Pre-formed two-piece hard shells and soft gel delivery systems represent value-added downstream integration.
Powder and Granules together absorb the majority of industrial throughput. Capsules deliver the highest value-add per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Belgian-Dutch rendering corridor anchors European gelatin production capacity, with pharmaceutical-grade manufacturing clustering around Ghent and Oss. EMA excipient guidelines and EU Green Deal circular-economy mandates are redrawing procurement geography across the continent.
Germany
Pharmaceutical capsule manufacturers in Baden-Württemberg and North Rhine-Westphalia are expanding gelatin procurement as endotoxin-compliant sourcing becomes mandatory for EU market access. The country's national pharmaceutical regulator enforces batch traceability requirements that filter out commodity producers. Gelita AG anchors specialized bone-sourced gelatin production in Eberbach, sustaining regional supply security for hard-shell capsule formulators.
France
Soft gel and two-piece capsule producers in the Île-de-France and Auvergne-Rhône-Alpes regions are driving demand for porcine-derived pharmaceutical grades. REACH chemical registration creates streamlined pathways for novel collagen alternatives entering French supply chains. Rousselot maintains rendering partnerships in the Lyon industrial basin to secure halal and kosher certification-compliant bovine substitution volumes.
Italy
Nutraceutical contract manufacturers in Lombardy and Emilia-Romagna specify hydrolyzed variants for joint-health and skin-elasticity formulations targeting aging demographics. EFSA novel food assessments govern market access for fish-derived collagen alternatives. Italgelatine and Lapi Gelatine concentrate enzymatic hydrolysis capability around Milan and Bologna to serve functional nutrition brand direct procurement.
Netherlands
Sports nutrition and beauty-from-within formulators in the Randstad region are establishing captive supply relationships for collagen peptide volumes above 50 metric tons annually. The country's national food safety authority enforces EFSA traceability requirements across rendering-to-capsule supply chains. Trobas Gelatine leverages continuous-flow reactor systems near Rotterdam to reduce batch-to-batch variability for Dutch toll-processing clients.
Spain
Underpenetrated demand pools for porcine-to-bovine substitution expertise are attracting certification-focused suppliers to Catalonia and Madrid. The country's national pharmaceutical regulator aligns with EMA guidelines on endotoxin limits for imported gelatin. Juncà Gelatines anchors regional production capacity in Barcelona to serve expanding Iberian nutraceutical formulation activity.
Europe Gelatin Market Competitive Landscape
Global majors compete with regional champions across certification tiers and rendering network control, producing a tiered structure where pharmaceutical-grade concentrate manufacturers sit above commodity food-grade suppliers. The vendor base fragments across enzymatic hydrolysis capability, with specialists in bioactive peptide fractionation occupying premium positioning. Three archetypes dominate: integrated rendering-to-gelatin producers, toll-processing nutraceutical specialists, and certification-focused pharmaceutical-grade concentrate manufacturers. Capacity expansion and long-term offtake agreements with traceability guarantees represent the dominant competitive moves.
Within the integrated rendering network tier, PB Leiner and Gelita AG exemplify archetypes built on captive supply security and specialized production lines respectively. Rousselot occupies a position bridging porcine-to-bovine substitution expertise with halal and kosher certification compliance. These three anchors demonstrate how Belgian, German, and French geographic origins map to distinct strategic positioning across pharmaceutical and nutraceutical demand channels.
| Leading Market Players |
|---|
| Italgelatine |
| PB Leiner |
| Gelita AG |
| Juncà Gelatines |
| Rousselot |
| Gelatines Weishardt |
| Lapi Gelatine |
| Trobas Gelatine |
| Ewald-Gelatine GmbH |
| Others |
Supply & Pricing Matrix
Enzymatic hydrolysis specialists concentrated in the Belgian-Dutch corridor command wage premiums that widen spreads between pharmaceutical-grade collagen peptides and commodity food-grade gelatin. Labor-cost differentials between Ghent-Oss rendering networks and peripheral Spanish or Polish facilities amplify tiered pricing structures across certification grades.
Pricing Analysis
Input-cost pass-through from rendering waste discharge compliance costs flows directly into pharmaceutical-grade contract pricing. Three-tier pricing structure across premium, standard, and economy levels separates endotoxin-certified pharmaceutical grades from food-grade and industrial tiers. Price differentiation centers on EMA excipient certification status and halal-kosher compliance documentation. Cost compression in standard food-grade gelatin is intensifying because Dutch and Belgian rendering network consolidation limits spot-market availability. Nutraceutical contract manufacturers in Italy and the Netherlands exhibit highest price sensitivity, while German capsule formulators prioritize traceability guarantees over unit economics.
Supply Chain Analysis
Reverse-logistics flows for bone-sourced rendering waste are mandating closed-loop recovery systems under EU Green Deal circular-economy criteria. Supply concentrates in Belgium, the Netherlands, and Germany, with French and Italian secondary capacity. Raw material dependencies center on porcine and bovine connective tissue availability, acid-alkali processing chemicals, and enzymatic hydrolysis catalysts. Single-source vulnerability pervades the Belgian-Dutch rendering corridor dominance for pharmaceutical-grade bovine gelatin. Distribution runs through long-term offtake agreements with direct-to-brand procurement displacing traditional ingredient distributors above 50 metric ton annual volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe gelatin market functions as a stable compounder anchored by irreversible pharmaceutical excipient regulatory requirements that perpetually filter out commodity suppliers.
For Market Incumbents: To counter recombinant collagen substitution threats in cosmetic stabilization applications, deepen backward integration into captive rendering networks with EU Green Deal wastewater compliance certification. Prioritize enzymatic hydrolysis capability investments in continuous-flow reactor systems to compress batch-to-batch variability for Dutch and Italian toll-processing clients. For New Entrants and Emerging Players: Launch via direct-to-brand procurement relationships with Spanish and Polish nutraceutical formulators seeking porcine-to-bovine substitution expertise. White-space concentration sits in halal and kosher certification-compliant hydrolyzed variants for underpenetrated Iberian joint-health applications. Target EMA novel excipient pathway early-mover positioning for accelerated pharmaceutical-grade assessment frameworks. For Investors and Strategic Acquirers: Pharmaceutical capsule manufacturers are the most active acquirer in this space, consolidating backward into rendering-to-gelatin integrated supply security. Five-to-ten year viability rests on endotoxin testing capacity scarcity and EMA traceability mandate permanence. Acquisition target archetype: mid-scale enzymatic hydrolysis specialists with established Italian or Dutch nutraceutical contract relationships. Monitor ECHA biomass sustainability criteria tightening as inflection signal for circular-economy premium positioning value capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rendering Networks | Captive supply security insulates against Belgian-Dutch corridor concentration risks under EMA guidelines. |
| Enzymatic Hydrolysis Capability Investment | Continuous-flow reactor adoption reduces batch variability for Lombardy and Emilia-Romagna contract manufacturers. |
| Halal and Kosher Certification Expansion | Spain and Poland present underpenetrated demand pools for bovine substitution expertise compliance. |
| Long-term Offtake Agreement Structuring | Traceability guarantees satisfy German and French pharmaceutical capsule manufacturer procurement mandates. |
| EU Green Deal Wastewater Compliance Retrofit | Closed-loop water recovery systems create capital barriers filtering mid-scale commodity competitors. |
Research Methodology
Bottom-up nutraceutical and pharmaceutical procurement modeling reconciled against top-down rendering capacity and gelatin production tracking forms the analytical core of this study. Primary interviews with pharmaceutical procurement managers, nutraceutical contract manufacturing executives, rendering plant operations directors, and EMA regulatory affairs specialists combined with secondary validation from EFSA novel food assessment databases, ECHA biomass sustainability filings, EU customs trade data, and national pharmaceutical regulator guidance documents. Triangulation across these sources ensures supply-side and demand-side figures converge.
Historical trendline analysis of pharmaceutical-grade pricing spreads and food-grade volume trajectories informed projection framework construction across the analysis window. Segmentation dimensions modeled include product type tier, application channel, certification grade, and form factor, crossed with regional production hub concentration. CAGRs derive from endpoint anchoring against documented capacity expansion announcements and regulatory mandate implementation schedules. Forecast inputs incorporate EMA excipient guideline revision timelines and EU Green Deal rendering waste discharge enforcement intensity assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt ECHA biomass sustainability criteria tightening or bovine spongiform encephalopathy-era sourcing rule reinstatement. Practitioners should monitor EMA novel excipient pathway assessment velocity and recombinant collagen fermentation scale-up announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Fermented Rennet Market
Ingredients
Volatile Fatty Acids Market
Ingredients
Native Starch Market
Ingredients
Corn-Based Ingredients Market
Ingredients
Chickpea Fiber Market
Ingredients
Resistant Starch Market
Ingredients
Fonio Flour Market
Ingredients
Global Dietary Fibers Market
Ingredients
Bovine Gelatin Market
Ingredients
US Vegetable Oil Market
Ingredients
Europe Whey Protein Ingredients Market
Ingredients
Asia-Pacific Bakery Ingredients Market
Ingredients
South America Fruit and Vegetable Ingredients Market
Ingredients
Carob Powder Market
Ingredients
Dry Malt Products Market
Ingredients
France Sodium Reduction Ingredients Market