
 Asia-Pacific Whey Protein Ingredients Market | 2026-2036
Asia-Pacific Whey Protein Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Whey Protein Ingredients Market Outlook
The FSSAI fortification mandate for nutritional supplements is consolidating procurement standards across India, forcing ingredient suppliers to recalibrate purity thresholds. Fonterra Co-operative Group Limited anchors its Asia-Pacific whey supply through New Zealand dairy processing scale and long-term contracts with Chinese sports nutrition brands. Glanbia plc differentiates via specialized isolate production for high-performance applications, while Morinaga Milk Industry Co Ltd leverages its Japanese manufacturing base to serve clean-label demand across Southeast Asian markets.
Asia-Pacific whey protein ingredients comprise milk-derived protein fractions separated during cheese manufacturing, typically containing beta-lactoglobulin and alpha-lactalbumin fractions with protein concentrations ranging from 34% in concentrates to 90% in isolates. These ingredients function primarily as emulsifiers, gelling agents, and complete protein sources across food systems. Whey isolate commands premium positioning due to lower lactose and fat content, while hydrolysate segments gain traction among infant formula and clinical nutrition manufacturers seeking reduced allergenicity. Powder form dominates industrial procurement channels, though ready-to-drink applications are expanding fastest among urban consumers seeking convenience.
China's SAMR enforces GB standards for dairy protein labeling and adulteration detection, while Japan's FSSC 22000 certification requirements shape export eligibility for regional suppliers. Australia's TGA regulates therapeutic claims on protein supplements, creating compliance complexity for cross-border e-commerce channels. Stakeholders must monitor divergence between national fortification policies and harmonized Codex standards as formulation decisions increasingly determine market access velocity.
Market Dynamics
China's SAMR enforcement of GB standards for dairy protein labeling is compressing formulation flexibility across the Asia-Pacific whey protein ingredients market, forcing suppliers to rebuild certificate-of-analysis workflows around adulteration detection protocols.
Growth Catalysts
- FSSAI fortification guidelines:India's tightening label requirements for nutritional supplements are consolidating procurement standards and elevating purity thresholds among ingredient suppliers serving the subcontinent.
- Infant formula manufacturers:Hydrolysate segments gain traction among clinical nutrition formulators seeking reduced allergenicity for pediatric applications across Southeast Asian markets.
- Tier-one city concentration:Gym penetration and premium dairy consumption overlap most densely in Shanghai, Beijing, and Guangzhou, anchoring isolate demand.
Market Restraints
- New Zealand supply concentration:Fonterra's processing scale dominance creates single-source vulnerability for Chinese sports nutrition brands dependent on long-term contracts.
- Lactose intolerance prevalence:Southeast Asian populations exhibit higher rates of dairy malabsorption, limiting concentrate adoption relative to isolate grades.
- Australia's TGA therapeutic claims:Cross-border e-commerce channels face compliance complexity when positioning protein supplements for muscle recovery benefits.
Strategic Opportunities
- Clean-label demand in Japan:Morinaga's manufacturing base positions suppliers to capture Southeast Asian markets seeking minimal processing claims.
- Ready-to-drink convenience:Urban consumers in Chinese megacities are accelerating format diversification beyond powder-dominant procurement channels.
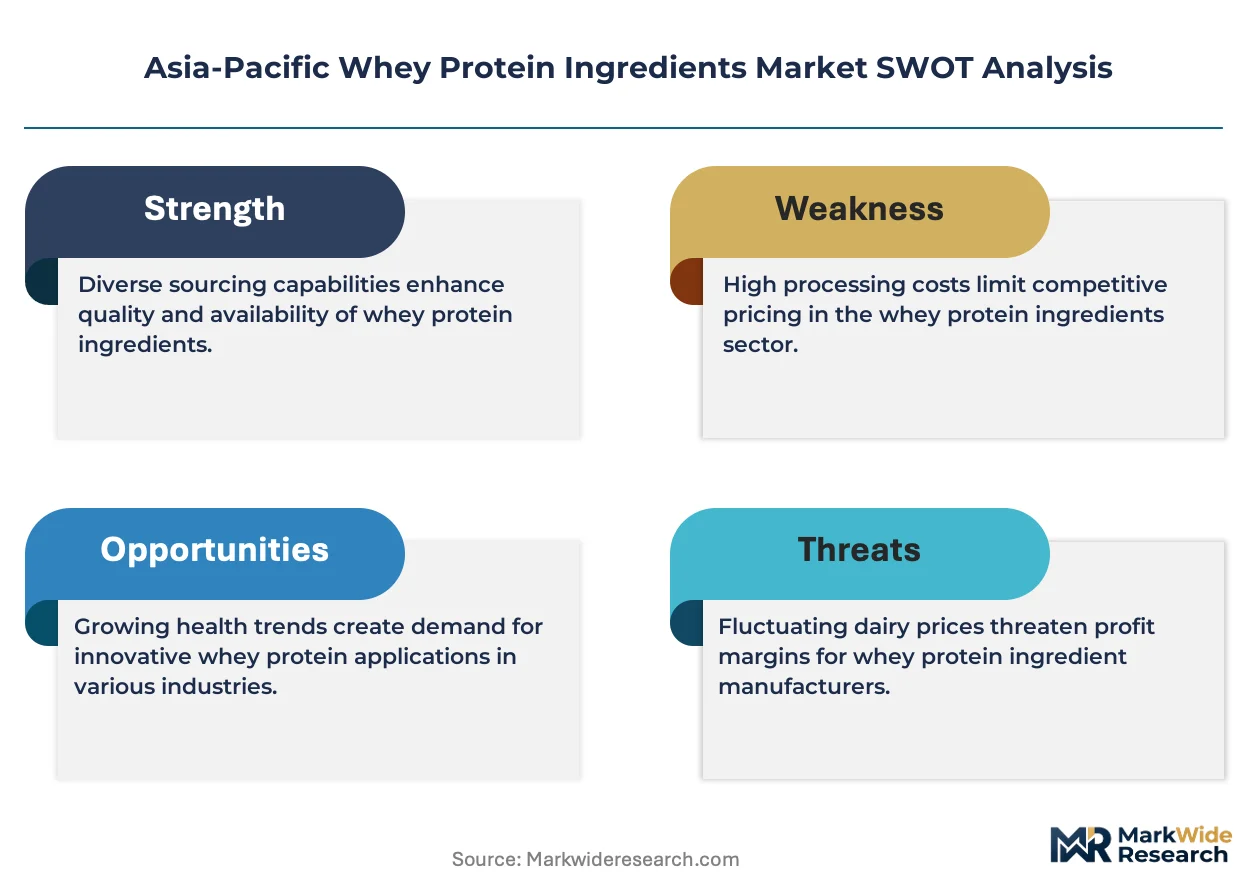
- FSSC 22000 certification:Japanese export eligibility requirements create a regulatory moat for suppliers investing in hazard analysis protocols.
Industry Challenges
- ISO 17025 testing capacity:Third-party laboratories face backlog pressures as GB standard enforcement expands batch-level verification requirements.
- Legacy ERP integration:Certificate-of-analysis data formats vary across China's SAMR, Japan's METI, and Australia's TGA, complicating unified quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Whey Protein Ingredients Market |
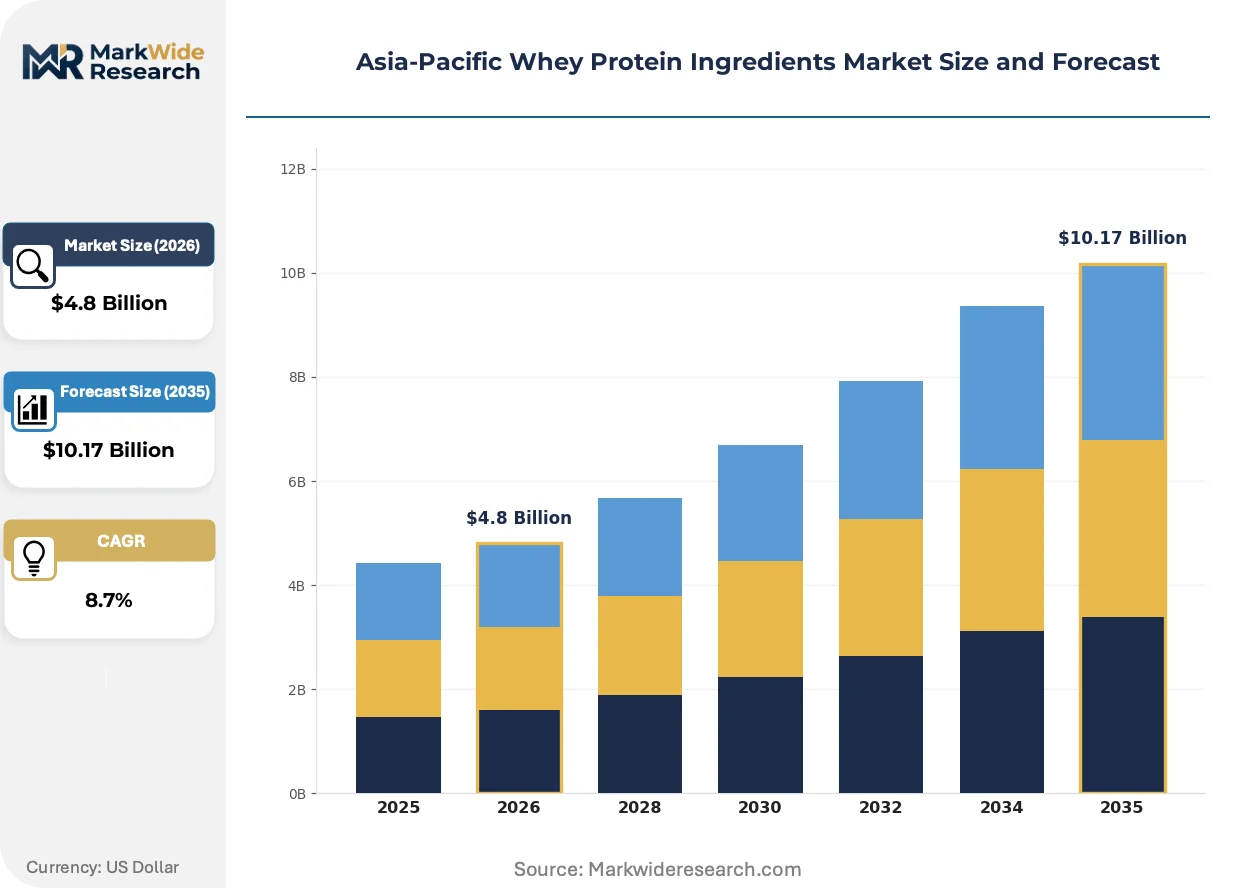
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrate, Isolate, Hydrolysate, Blend Application: Nutritional Supplements, Food & Beverage, Bakery, Confectionery Form: Powder, Liquid, Ready-to-Drink, Granule End User: Dietary Supplement Manufacturers, Sports Nutrition Companies, Food Processors, Retailers |
| Companies Covered | Koninklijke FrieslandCampina N.V., Hilmar Cheese Company, Fonterra Co-operative Group Limited, Morinaga Milk Industry Co Ltd, Kerry Group plc, Glanbia plc, Cargill, Lacto Japan Co Ltd, Arla Foods amba, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Whey Protein Ingredients Market Strategic Shifts
Membrane filtration advances and enzymatic processing are reconfiguring protein fractionation economics across Asia-Pacific dairy processing. Formulators now prioritize functional properties over commodity protein content.
Cross-flow microfiltration is overtaking traditional cold-pressed whey separation in high-capacity plants serving Chinese sports nutrition brands. Infant formula manufacturers in Japan and South Korea are accelerating adoption of this technology to achieve superior alpha-lactalbumin retention. The shift is compressing capital recovery timelines for isolate-dedicated facilities while raising barriers for concentrate-dependent processors.
Japan's FSSC 22000 certification requirements are reshaping export eligibility protocols for regional suppliers seeking access to Southeast Asian markets. Manufacturers must now document hazard analysis critical control point systems across raw milk sourcing through finished ingredient release. Australian suppliers targeting ASEAN markets are responding by dual-certifying facilities under both FSSC 22000 and local HACCP equivalency agreements.
Urban Chinese consumers are fragmenting procurement channels through direct-to-gym distribution partnerships that bypass traditional ingredient distributors. Sports nutrition brands in tier-one cities now contract directly with New Zealand processors for isolate supply, compressing margin layers. This disintermediation is most visible in Shanghai and Beijing, where gym chains operate captive retail networks with dedicated protein SKUs.
Asia-Pacific Whey Protein Ingredients Market Segmentation
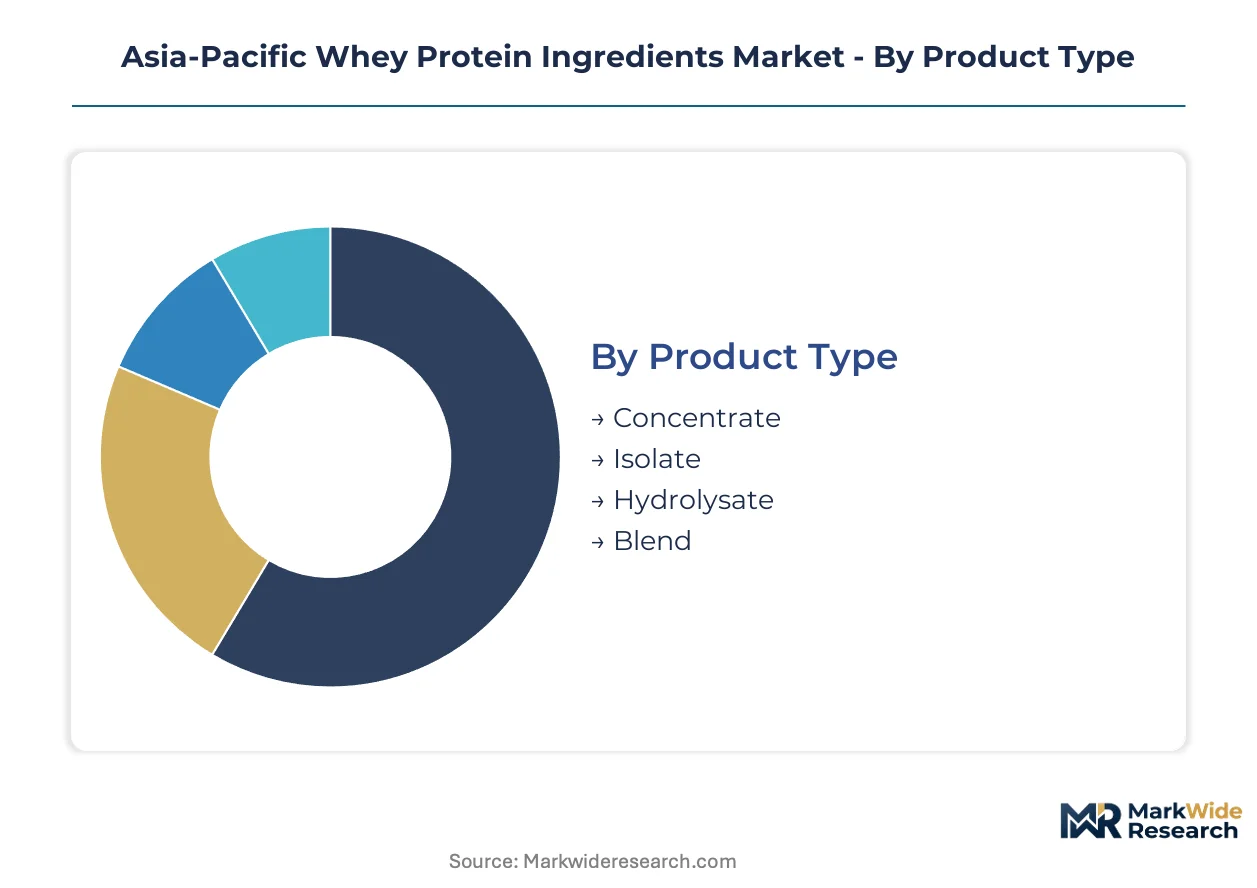
Whey protein ingredient procurement across Asia-Pacific stratifies sharply between commodity-grade concentrates and premium isolates, with formulation decisions increasingly governed by national fortification mandates rather than price alone. Segment boundaries are blurring as Chinese sports nutrition brands demand isolate specifications at concentrate-adjacent volumes, while Japanese infant formula manufacturers push hydrolysate purity thresholds higher.
Product Type:
Volume concentration sits with commodity-grade concentrates, while margin capture belongs to isolates and hydrolysates commanding certification premiums.
- Concentrate:Protein fractions containing 34-80% protein with retained lactose and lipid components serve cost-sensitive food processors across India and Southeast Asia. Bakery and confectionery manufacturers in Vietnam and Indonesia favor concentrate for emulsification functionality where protein purity is secondary to price stability.
- Isolate:Refined to 90% protein with minimal lactose and fat content, isolate commands procurement priority from Chinese sports nutrition companies in Shanghai and Beijing gym channels. FSSAI fortification guidelines in India are compressing concentrate adoption as supplement manufacturers reformulate for label compliance.
- Hydrolysate:Enzymatically pre-digested proteins with reduced allergenicity serve Japanese and South Korean infant formula manufacturers seeking clinical nutrition positioning.
- Blend:Custom protein matrices combining concentrate, isolate, and hydrolysate fractions target mid-tier sports nutrition brands balancing cost and performance claims.
Today's leader: Concentrate. Tomorrow's challenger: Isolate.
Application:
End-use fragmentation reflects divergent regulatory stringency across therapeutic claims, fortification mandates, and clean-label positioning.
- Nutritional Supplements:India's tightening FSSAI label requirements are elevating purity thresholds for protein powders and capsules, forcing ingredient suppliers to recalibrate certificate-of-analysis workflows. Sports nutrition companies across Chinese tier-one cities anchor isolate procurement here.
- Food & Beverage:Functional protein fortification in dairy alternatives and meal replacements concentrates in Japan's aging-consumer product development pipelines.
- Bakery:Concentrate grades dominate emulsification applications across Southeast Asian commercial baking operations where protein functionality outweighs nutritional claims.
- Confectionery:Limited adoption in premium chocolate and protein-enriched snacks, primarily serving Japanese and Australian clean-label confectioners.
Supplement applications hold volume dominance. Food & beverage integration is expanding most quickly.
Form:
Industrial procurement patterns favor powder economics, while urban convenience demand is fragmenting distribution through ready-to-drink channels.
- Powder:Dominates bulk procurement from New Zealand processors serving Chinese sports nutrition brands under long-term contract structures. Warehouse-scale packaging and extended shelf stability anchor this format's industrial preference.
- Liquid:Concentrated protein solutions serve Japanese and South Korean beverage manufacturers with aseptic processing capabilities.
- Ready-to-Drink:Shanghai and Beijing gym chains are accelerating captive retail networks with dedicated protein SKUs, bypassing traditional distributors. Urban Chinese consumers fragment procurement through direct-to-gym partnerships.
- Granule:Niche positioning in instant beverage and soup applications across Japanese convenience food channels.
Powder retains supply chain control. Ready-to-drink is gaining share fastest.
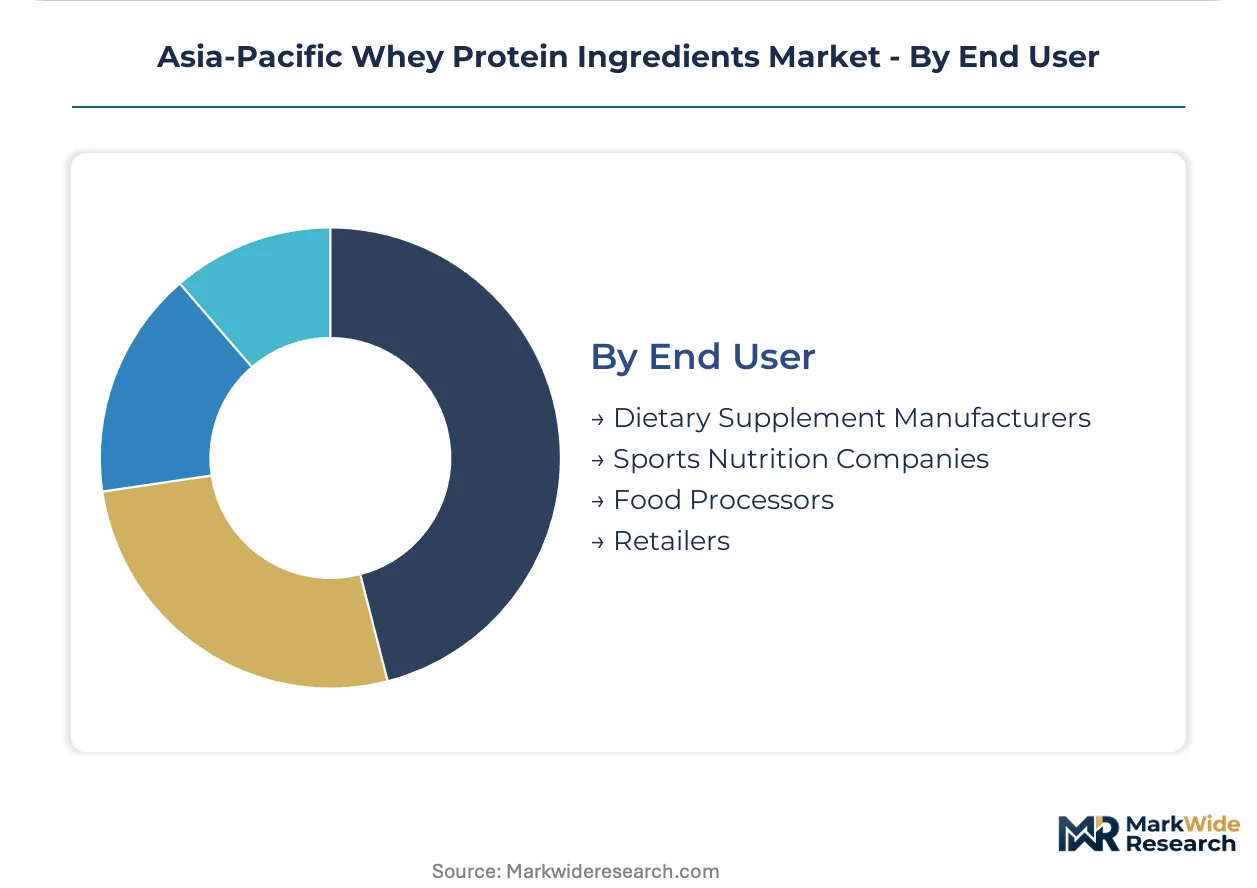
End User:
Customer type determines certification burden, with dietary supplement manufacturers facing the most stringent purity verification requirements.
- Dietary Supplement Manufacturers:India's FSSAI fortification guidelines impose batch-level verification protocols that compress formulation flexibility. These stakeholders drive hydrolysate demand for reduced allergenicity claims in pediatric and clinical segments.
- Sports Nutrition Companies:Chinese brands in tier-one cities contract directly with New Zealand processors, disintermediating traditional distributors and compressing margin layers.
- Food Processors:Southeast Asian bakery and confectionery operations prioritize concentrate grades for emulsification functionality over protein content metrics.
- Retailers:Australian supermarket chains and Japanese drugstore networks influence packaging specifications and clean-label positioning for consumer-facing SKUs.
Sports nutrition companies currently dominate isolate procurement. Dietary supplement manufacturers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asia-Pacific whey protein processing traces its commercial roots to New Zealand's dairy cooperative formation in the late nineteenth century, when butter and cheese byproduct streams first generated protein fractions for export. Industrial-scale membrane filtration arrived in the 1980s, establishing the region's current processing architecture.
China
Shanghai and Beijing gym chains anchor isolate demand through direct-to-gym distribution partnerships that bypass traditional ingredient distributors. SAMR enforcement of GB standards for dairy protein labeling compresses formulation flexibility and forces suppliers to rebuild certificate-of-analysis workflows around adulteration detection protocols. Cross-border e-commerce channels face heightened scrutiny as batch-level verification requirements expand.
India
FSSAI fortification guidelines are tightening label requirements for nutritional supplements, consolidating procurement standards and elevating purity thresholds among ingredient suppliers serving the subcontinent. Dietary supplement manufacturers drive hydrolysate demand for reduced allergenicity claims in pediatric applications. Maharashtra and Gujarat host the primary formulation clusters responding to these regulatory shifts.
Japan
Infant formula manufacturers in Tokyo and Osaka accelerate adoption of cross-flow microfiltration technology to achieve superior alpha-lactalbumin retention. FSSC 22000 certification requirements reshape export eligibility protocols for regional suppliers seeking access to Southeast Asian markets. Morinaga Milk Industry leverages its domestic manufacturing base to serve clean-label demand across ASEAN channels.
Australia
TGA regulation of therapeutic claims on protein supplements creates compliance complexity for sports nutrition brands positioning products for muscle recovery benefits. New South Wales and Victoria concentrate ready-to-drink manufacturing capacity serving urban convenience demand. Australian suppliers targeting ASEAN markets dual-certify facilities under both FSSC 22000 and local HACCP equivalency agreements.
South Korea
MFDS oversight of functional food claims shapes hydrolysate adoption among clinical nutrition formulators in Seoul and Busan. Seoul Capital Area beverage manufacturers with aseptic processing capabilities drive concentrated protein solution procurement. The country's aging-consumer product development pipelines prioritize protein fortification in dairy alternatives and meal replacements.
Asia-Pacific Whey Protein Ingredients Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification tier and isolate purity grade, with FSSC 22000 and ISO 17025 compliance separating price bands. The market structure concentrates around New Zealand dairy cooperative scale, Irish nutrition ingredient platforms, and Japanese clean-label specialists. Three archetypes dominate: scale-driven processors with backward integration into milk supply, certification-focused specialists serving infant formula channels, and diversified nutrition platforms with broad application portfolios. Competitive moves center on membrane filtration capacity expansion and direct contracting relationships with Chinese sports nutrition brands.
Within the scale-driven tier, Fonterra Co-operative Group Limited and Glanbia plc exemplify divergent strategic positions. Fonterra anchors Asia-Pacific whey supply through New Zealand dairy processing scale and long-term procurement relationships. Glanbia occupies a position emphasizing specialized isolate production for high-performance applications. Morinaga Milk Industry Co Ltd represents the clean-label specialist archetype, leveraging Japanese manufacturing credentials to capture Southeast Asian market segments prioritizing minimal processing claims.
| Leading Market Players |
|---|
| Koninklijke FrieslandCampina N.V. |
| Hilmar Cheese Company |
| Fonterra Co-operative Group Limited |
| Morinaga Milk Industry Co Ltd |
| Kerry Group plc |
| Glanbia plc |
| Cargill |
| Lacto Japan Co Ltd |
| Arla Foods amba |
| Others |
Value Chain & Pricing Dynamics
Membrane filtration technician density in New Zealand's Waikato region anchors labor-cost differentials that spread pricing-tier spreads across Asia-Pacific procurement channels. Chinese sports nutrition brands contracting directly with Fonterra processors capture isolate premiums while Southeast Asian concentrate buyers absorb lower-skill processing economics.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs Asia-Pacific whey ingredient transactions. Price differentiation centers on FSSC 22000 certification status and isolate purity grade, with certified hydrolysate commanding multiples over commodity concentrate. Cost compression in standard-tier concentrate runs through Indian FSSAI compliance investments and batch-level testing overhead. Dietary supplement manufacturers in Maharashtra exhibit highest price sensitivity, while Japanese infant formula producers demonstrate lowest elasticity for alpha-lactalbumin-retentive isolates.
Supply Chain Analysis
FSSC 22000 certification gating restricts supply eligibility for Southeast Asian market access, compressing qualified supplier pools. New Zealand, Australia, and Japan concentrate processing capacity, with raw milk supply drawing from cooperative dairy farming structures across the Tasman. Whey fractionation depends on cheese manufacturing byproduct streams, membrane filtration equipment, and enzymatic processing inputs. Single-source vulnerability concentrates around Fonterra's New Zealand processing dominance for Chinese contract volumes. Distribution runs through direct processor-to-brand contracting in Chinese tier-one cities, bypassing traditional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Chinese gym chains and sports nutrition brands are shifting procurement toward isolate specifications with certificate-of-analysis documentation, elevating purity thresholds over commodity volume plays.
For Market Incumbents: Deepen backward integration into New Zealand dairy cooperative milk supply to secure isolate-dedicated feedstock streams. Expand cross-flow microfiltration capacity in Waikato processing clusters before Chinese brands complete direct-to-processor contracting transitions. Invest in dual FSSC 22000 and ISO 17025 certification to defend margin position against emerging Japanese clean-label specialists. For New Entrants and Emerging Players: Direct-to-gym distribution partnerships in Shanghai and Beijing offer the most penetrable channel architecture for isolate supply. Target ready-to-drink format development for urban Chinese convenience demand, bypassing powder-dominant procurement channels. Position hydrolysate production for Indian pediatric nutrition applications where FSSAI fortification guidelines are elevating purity requirements fastest. For Investors and Strategic Acquirers: Japanese infant formula manufacturers are the most active acquirer in this space, seeking alpha-lactalbumin retention capabilities and ASEAN export certification. Long-term viability favors certified isolate processors with membrane filtration technology over commodity concentrate-dependent assets. Watch for SAMR batch-level verification mandate expansion as inflection signal for quality-tier repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Capacity Expansion | Cross-flow microfiltration investments in New Zealand and Australia compress capital recovery timelines for isolate-dedicated facilities. |
| FSSC 22000 Certification Investment | Japanese export eligibility requirements create regulatory moats for suppliers serving Southeast Asian clean-label demand. |
| Direct-to-Gym Distribution Partnerships | Shanghai and Beijing gym chains operating captive retail networks disintermediate traditional ingredient distributors. |
| Hydrolysate Production Scale-Up | Indian FSSAI fortification guidelines and Japanese infant formula demand elevate reduced-allergenicity protein positioning. |
| Dual-Certification Facility Development | Australian suppliers targeting ASEAN markets combine FSSC 22000 with local HACCP equivalency to unlock market access. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged dairy processing plant managers, sports nutrition brand procurement leads, infant formula regulatory affairs directors, and FSSC 22000 certification auditors across New Zealand, Australia, Japan, China, India, and South Korea. Secondary validation drew from customs and trade data, Fonterra and Glanbia SEC filings, FSSAI fortification guideline publications, and SAMR GB standard enforcement records. Bottom-up volume modeling triangulated against top-down market sizing from processor capacity disclosures.
Comparable-period anchoring linked projection assumptions to historical isolate and concentrate volume trajectories across the analysis window. Segmentation dimensions modeled include product type tier, application end-use, form factor, and end-user certification burden. CAGRs derived from processor capacity expansion announcements, gym penetration metrics in Chinese tier-one cities, and infant formula manufacturer hydrolysate adoption curves. Forecast inputs incorporated membrane filtration technology diffusion rates and FSSAI compliance cost pass-through assumptions.
The model assumes a particular technology adoption path; alternative pathways for enzymatic hydrolysis efficiency gains would alter the outlook. Forecasts reflect assumptions around SAMR enforcement intensity, FSSAI guideline implementation timelines, and Chinese consumer protein awareness trajectory. A model refresh is warranted upon material change in New Zealand dairy cooperative supply contract structures or Japanese FSSC 22000 audit failure rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Bleached Flour Market
Ingredients
Casein Glycomacropeptide Market
Ingredients
Collagen Casings Market
Ingredients
Beetroot Powder Market
Ingredients
Glucosylglycerol Market
Ingredients
Proteose Peptone Market
Ingredients
Mexico Avocado Oil Market
Ingredients
Savory Ingredients Market
Ingredients
Botanical Ingredients Market
Ingredients
Avocado Powder Market
Ingredients
Bromelain Ingredient Market
Ingredients
2'-Fucosyllactose (2'-FL) Market
Ingredients
Global Apricot Oil Market
Ingredients
India Gelatin Market
Ingredients
GCC Egg Powder Market
Ingredients
Mediterranean Marine Ingredients for Pet Health Market