
 Protein Cookie Market | 2026-2036
Protein Cookie Market Size, Share, and Industry Trends Forecast 2026-2036
Protein Cookie Market Analytics
Aftermarket personalization services is reconfiguring how protein cookie brands capture recurring revenue beyond initial purchase. Quest Nutrition leverages its direct-to-consumer infrastructure to sustain repeat subscription rates. Lenny & Larry's LLC anchors its competitive position through vegan ingredient specialization. Kodiak Cakes, LLC extends its breakfast-category credibility into high-protein snacking through whole-grain formulations.
A protein cookie is a baked snack product containing elevated protein content, typically fifteen to thirty grams per serving, achieved through whey isolate, pea protein, or collagen fortification, designed to support muscle recovery and satiety between meals. Soft-baked formats dominate consumer preference for texture parity with conventional indulgent cookies, while vegan ingredient positioning captures the fastest-growing purchaser cohort. Single-serve packaging commands premium shelf placement in convenience retail, though multi-pack configurations capture volume in club-channel environments.
The FDA governs nutritional labeling and protein content claims under Food Labeling Guide standards, while the USDA Organic certification shapes ingredient sourcing requirements for premium tier positioning. The FTC monitors advertising substantiation for performance claims, pressuring brands to validate muscle-recovery benefits through clinical documentation. Stakeholders must monitor evolving clean-label enforcement intensity and alternative protein regulatory classification decisions that could reshape formulation costs and market access barriers.
Market Dynamics
Clean-label ingredient certifications and plant-based protein innovations are compressing formulation timelines while expanding addressable segments beyond traditional sports nutrition buyers. The tension between premium positioning and mass-market accessibility defines current competitive maneuvering.
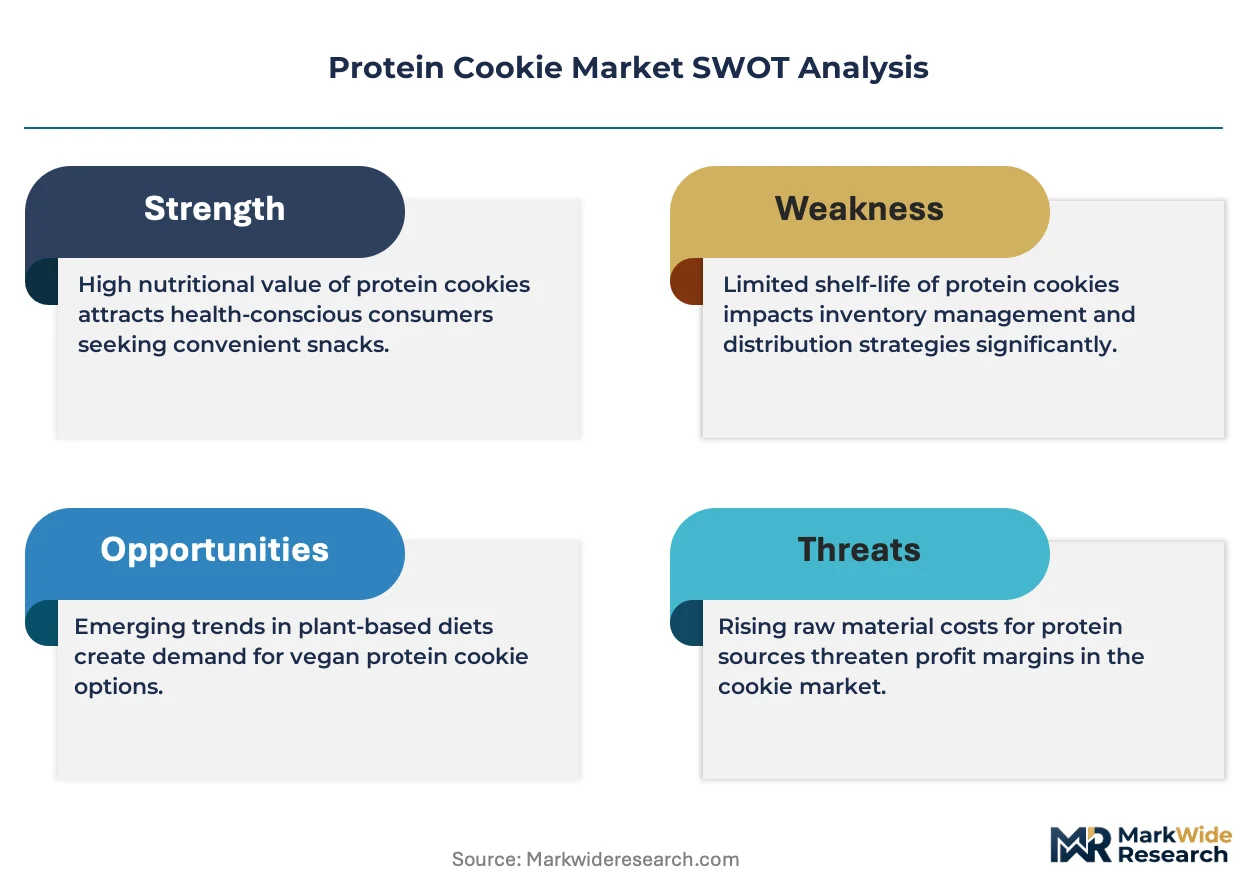
Growth Catalysts
- USDA Organic Certification:Premium tier brands leverage this designation to command shelf placement in natural retail channels and justify price premiums over conventional alternatives.
- Pea Protein Isolation:Advances in flavor-masking technology eliminate the grassy aftertaste that previously limited consumer acceptance of plant-based formulations.
- Fitness Facility Distribution:Protein cookies secure impulse placement at gym checkout counters where post-workout purchase intent peaks.
Market Restraints
- Whey Protein Concentrate Volatility:Dairy commodity price swings compress margin predictability for brands dependent on animal-derived protein sources.
- Single-Source Supply Risk:Collagen peptide production concentrates in Brazilian and Argentine rendering facilities, exposing brands to regional climate and logistics disruptions.
- Protein Claim Substantiation:FTC enforcement requires clinical documentation of muscle-recovery benefits, elevating compliance costs for performance-positioned products.
Strategic Opportunities
- India FSSAI Clean-Label Pathway:Early movers establishing domestic manufacturing can capture emerging demand from urban fitness communities in Mumbai and Bangalore.
- Subscription Commerce Infrastructure:Direct-to-consumer replenishment models lock in predictable recurring revenue and reduce customer acquisition cost burdens.
- Precision Fermentation Convergence:Partnerships with alternative protein developers enable animal-identical dairy proteins without supply chain exposure to conventional agriculture.
Industry Challenges
- Food Science Talent Scarcity:Formulation chemists capable of balancing protein fortification with shelf-stable texture remain concentrated at legacy baked goods manufacturers.
- Co-Manufacturer Certification Timelines:BRC and SQF facility audits extend new product introduction cycles by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protein Cookie Market |
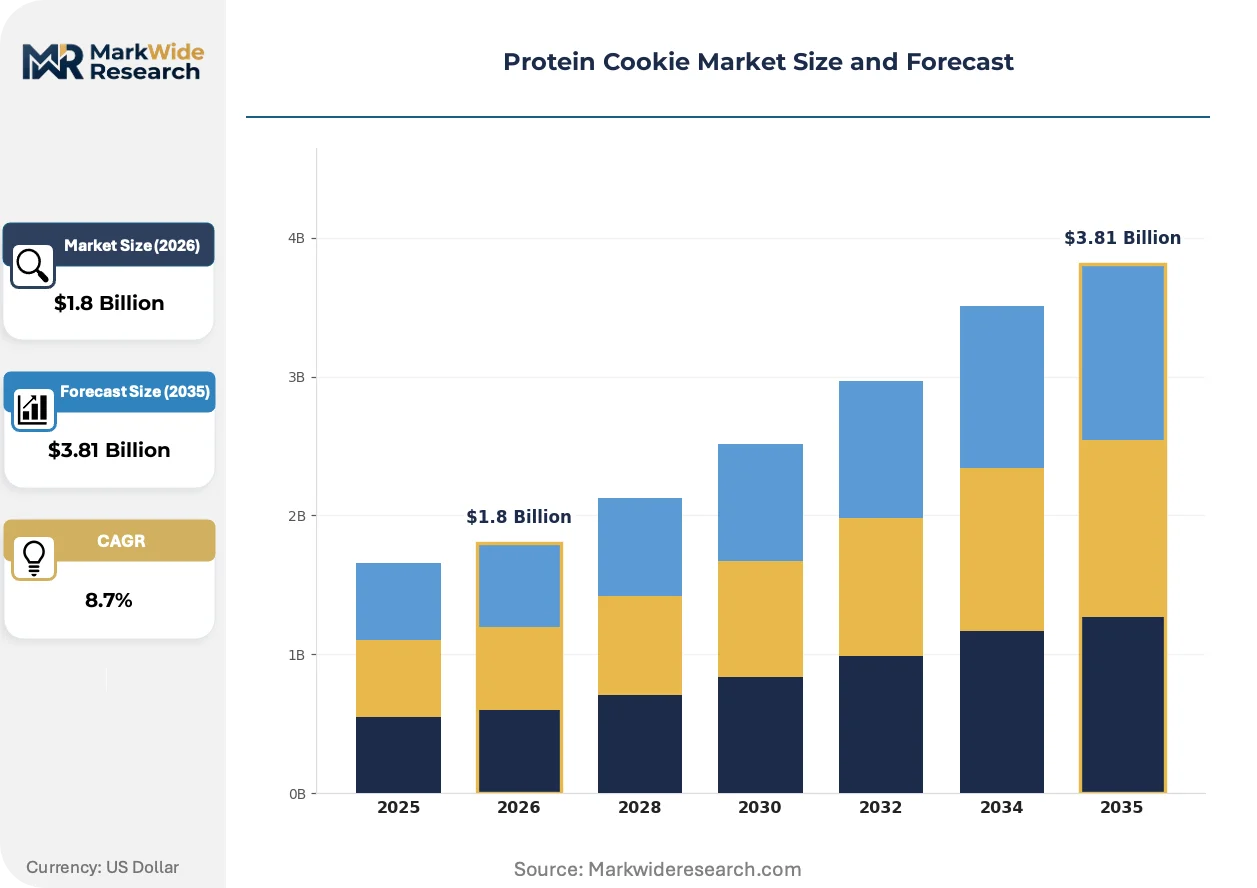
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft-Baked, Crunchy, Chewy, Protein Bar Ingredient Type: Vegetarian, Vegan, Gluten-Free, Organic Packaging Type: Single-Serve, Multi-Pack, Bulk, Resealable Consumption Occasion: Sports Nutrition, Meal Replacement, Snack, Post-Workout |
| Companies Covered | Quest Nutrition, Lenny & Larry's LLC, Munk Pack, NuGo Nutrition, Buff Bake, MuscleTech, No Cow LLC, Justine's Limited, Kodiak Cakes, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protein Cookie Market Evolving Landscape
Protein cookie formulation is pivoting from whey-dominant recipes toward diversified protein matrices that address digestive tolerance and sustainability positioning simultaneously.
Precision fermentation-derived whey proteins are rendering obsolete the supply chain constraints of conventional dairy sourcing. Clean-label brands in the United States and Netherlands are adopting these ingredients at pilot scale. This technology compresses the link between protein procurement and agricultural commodity markets.
EU Green Deal farm-to-fork sustainability mandates are reshaping ingredient sourcing requirements for brands accessing European retail. EFSA novel food approval pathways for alternative proteins extend time-to-market for innovators. German and French retailers now require carbon footprint disclosures on packaged snack labels.
Subscription-based replenishment is displacing single-unit impulse purchases among core fitness enthusiast segments. Amazon Subscribe & Save and specialized sports nutrition direct-to-consumer platforms capture recurring orders. This pattern concentrates in United States metropolitan markets with established gym culture density.
Protein Cookie Market Segmentation
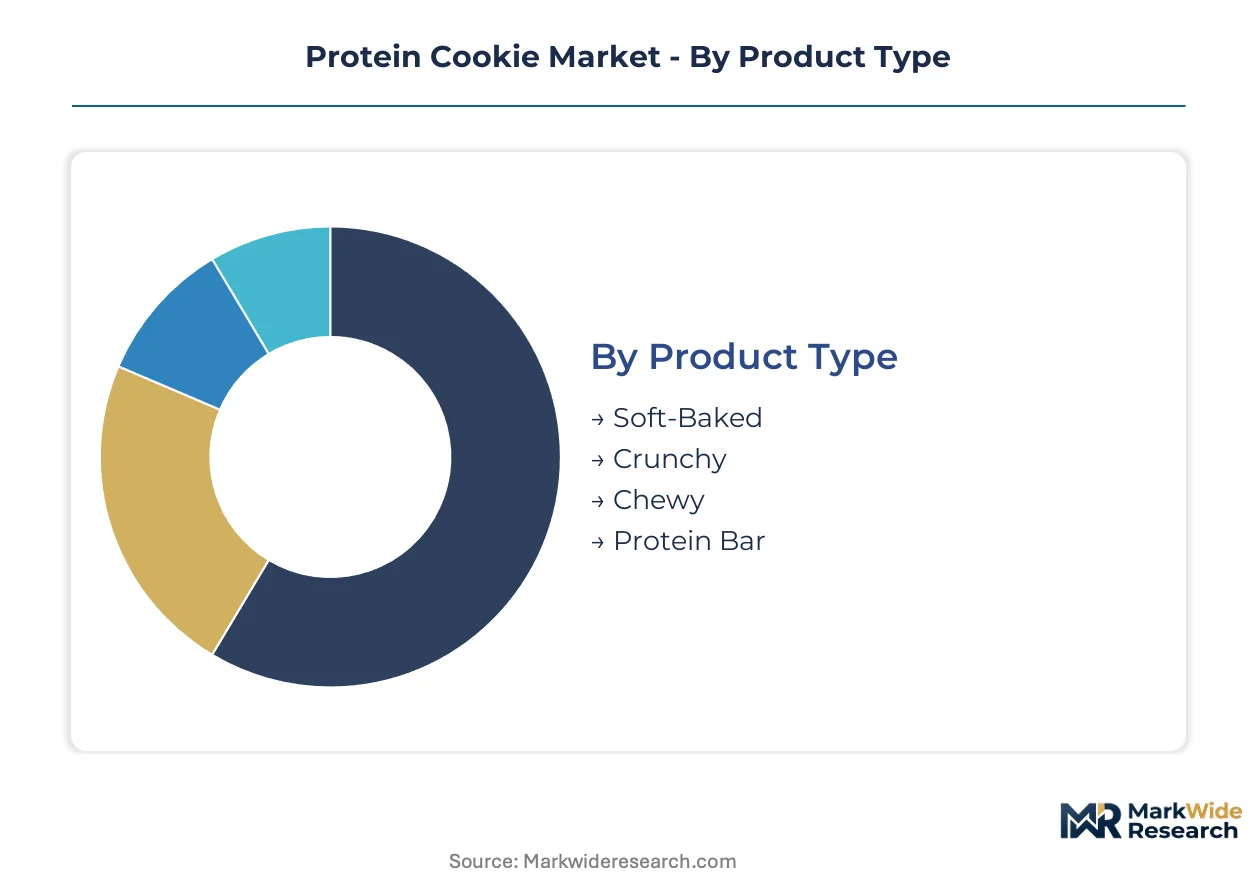
Protein cookie segmentation maps directly to purchase context and dietary identity. Manufacturers calibrate texture, certification, and pack size to match distinct usage moments from gym-bag stashing to desk-drawer replenishment.
Product Type:
The use-case spectrum runs from immediate post-workout consumption to planned meal substitution, with texture preferences varying sharply by consumption timing and portability requirements.
- Soft-Baked:Moist, cake-like interior achieved through controlled moisture retention and fat emulsion stability. Demand concentrates in United States metropolitan markets where consumers prioritize indulgence parity with conventional bakery cookies; texture tolerance for protein fortification is highest in this format.
- Crunchy:Low-moisture, extended-bake profile delivers shelf stability and clean-hand eating. Sports nutrition buyers in Germany and Netherlands favor this format for gym-bag portability where crumb control matters.
- Chewy:Intermediate moisture content with hydrocolloid stabilization for elastic bite. Compact description: Dense, taffy-like texture popular in meal-replacement contexts.
- Protein Bar:Extruded or cold-pressed format with binding systems replacing traditional cookie lamination. Compact description: Rectilinear shape optimizes wrapper efficiency and vending machine compatibility.
Established volume favors Soft-Baked; emerging adoption favors Protein Bar.
Ingredient Type:
Certification tiering separates price-insensitive ethical buyers from mainstream fitness consumers, with regulatory recognition varying by export destination.
- Vegetarian:Excludes meat and fish but permits dairy and egg proteins; whey isolate and casein dominate formulations. Compact description: Dominant certification in India FSSAI-regulated products where lacto-vegetarian norms prevail.
- Vegan:Plant-exclusive protein matrices using pea, rice, or fava bean isolates with lecithin emulsifiers. United Kingdom and Netherlands retail channels demand this certification for shelf placement in dedicated plant-based sets; EFSA novel food approvals for emerging protein sources extend formulation timelines.
- Gluten-Free:Oat flour, almond meal, or tapioca starch replace wheat protein matrices. Compact description: Required for celiac-safe positioning; oat-based systems face glyphosate residue testing protocols.
- Organic:USDA Organic or EU Organic certification mandates ingredient traceability and prohibited substance lists. Compact description: Commands premium shelf placement in natural retail; supply concentration in North American organic dairy limits formulation flexibility.
Vegetarian captures current volume leadership; Vegan is climbing the fastest.
Packaging Type:
Channel economics and consumption velocity determine pack architecture, with convenience retail and club channels demanding fundamentally different unit economics.
- Single-Serve:Individual wrapper with nitrogen flush for oxidation control; 50-80 gram unit weight. Gym checkout counters and convenience stores in United States urban markets drive placement; impulse price points face pressure from private-label competition.
- Multi-Pack:Four to six count outer carton with individual film overwrap. Compact description: Club channel standard; Costco and Sam's Club volume commitments require dedicated production lines.
- Bulk:Unwrapped or simple bagged presentation for foodservice or repackaging. Compact description: Cafeteria and corporate pantry channels; minimal branding exposure.
- Resealable:Zipper-equipped pouch with oxygen scavenger sachet for multi-day consumption. Compact description: Meal-replacement positioning; premium price justification depends on freshness claim substantiation.
Multi-Pack dominates club-channel revenue; Single-Serve is gaining share fastest in convenience retail.
Consumption Occasion:
Functional claim substantiation requirements intensify with the specificity of physiological benefit promised, separating snack-positioned products from regulated sports nutrition.
- Sports Nutrition:Explicit muscle-recovery claims requiring protein content thresholds and amino acid profile documentation. FTC enforcement in United States demands clinical substantiation; this segment bears highest compliance cost burden.
- Meal Replacement:Formulated to complete nutrition standards with vitamin and mineral fortification. Compact description: Regulated as food for specific groups in EU; micronutrient stability through shelf life is formulation challenge.
- Snack:General satiety positioning without performance claims. Compact description: Broadest addressable market; lowest regulatory scrutiny.
- Post-Workout:Time-sensitive consumption window with rapid amino acid absorption emphasis. Compact description: 30-60 minute consumption protocol; packaging emphasizes portability and immediate opening.
Snack captures mass-market volume; Post-Workout shows steepest expansion trajectory among committed fitness enthusiasts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for protein cookies varies sharply by market maturity. United States consumers absorb premium positioning with minimal volume sacrifice, while Indian buyers demand aggressive price-to-protein ratios that compress manufacturer margins.
United States
Fitness facility density and direct-to-consumer subscription infrastructure sustain premium pricing power. FDA nutritional labeling enforcement under Food Labeling Guide standards elevates compliance costs for performance claims. Los Angeles and New York metropolitan clusters concentrate venture-backed brand launches targeting post-workout consumption windows.
Germany
EU Green Deal farm-to-fork mandates reshape ingredient sourcing requirements for retail access. EFSA novel food approval pathways extend time-to-market for alternative protein formulations. Berlin and Munich anchor plant-based protein cookie development clusters serving pan-European distribution.
India
Urban fitness community expansion in Mumbai and Bangalore generates demand for clean-label positioned products. FSSAI clean-label regulatory pathways reward early domestic manufacturing establishment. Maharashtra and Karnataka industrial corridors attract contract manufacturing investment for export-ready production.
United Kingdom
Vegan certification demand from retail channels drives plant-exclusive protein matrix adoption. Trading standards enforcement pressures substantiation of protein content claims. London metropolitan area concentrates direct-to-consumer brand headquarters leveraging subscription commerce infrastructure.
Netherlands
Precision fermentation protein sourcing partnerships accelerate pilot-scale adoption among clean-label brands. EFSA regulatory frameworks govern alternative protein classification decisions. Eindhoven and Wageningen research clusters advance flavor-masking technology for pea protein isolation.
Protein Cookie Market Competitive Landscape
Specialist sports nutrition brands and legacy baked goods extensions split the market between performance-authentic positioning and mass-market accessibility. The vendor base concentrates around three strategic archetypes: direct-to-consumer subscription specialists, vegan ingredient pure-plays, and breakfast-category extenders. Dominant competitive moves include subscription commerce infrastructure buildout and precision fermentation protein sourcing partnerships.
Within the direct-to-consumer specialist tier, Quest Nutrition exemplifies subscription-driven recurring revenue models. Lenny & Larry's LLC occupies a position anchoring vegan ingredient specialization. Kodiak Cakes, LLC represents breakfast-category credibility extension into high-protein snacking applications.
| Leading Market Players |
|---|
| Quest Nutrition |
| Lenny & Larry's LLC |
| Munk Pack |
| NuGo Nutrition |
| Buff Bake |
| MuscleTech |
| No Cow LLC |
| Justine's Limited |
| Kodiak Cakes, LLC |
| Others |
Value Network & Pricing Analysis
Whey protein concentrate volatility compresses margin predictability for brands dependent on animal-derived protein sources, forcing pricing stratification across premium USDA Organic tiers, standard clean-label positioning, and economy private-label alternatives while simultaneously reshaping procurement toward diversified protein matrices and precision fermentation partnerships.
Pricing Analysis
Subscription commerce replenishment drives lifetime value capture beyond transactional unit sales. Three-tier pricing structure across premium, standard, and economy levels separates certified organic positioning from conventional clean-label and mass-market private-label alternatives. Price differentiation hinges on certification grade and volume scale, with single-serve convenience retail formats commanding shelf placement premiums. Cost compression in economy tiers intensifies because private-label competition erodes impulse price points. Mass-market fitness consumers exhibit highest price sensitivity, while committed sports nutrition buyers absorb premium positioning with minimal volume sacrifice.
Supply Chain Analysis
Upstream feedstock dependencies center on dairy protein isolates from the United States, pea protein concentrates from Canada and France, and collagen peptides concentrated in Brazilian and Argentine rendering facilities. Raw material inputs draw from whey isolate, pea protein isolate, and hydrocolloid stabilizers for texture retention. Single-source vulnerability in South American collagen peptide production exposes brands to regional climate disruptions and logistics interruptions. Distribution runs through direct-to-consumer subscription platforms, fitness facility impulse placement, and club-channel multi-pack configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The protein cookie market sits in a cyclical recovery phase driven by post-pandemic fitness facility reopening and renewed gym membership growth, creating favorable conditions for brands with established subscription infrastructure and clean-label certification portfolios.
For Market Incumbents: Insulate recurring revenue streams by deepening direct-to-consumer subscription lock-in through personalized replenishment algorithms and exclusive flavor drops. Secure backward integration into precision fermentation protein sourcing to decouple from dairy commodity volatility. Prioritize BRC and SQF facility certification investments to compress co-manufacturer audit timelines and accelerate new product introduction cycles against emerging plant-based competitors.
For New Entrants and Emerging Players: Pursue white-space opportunities in India FSSAI clean-label pathway establishment, where urban fitness community expansion in Mumbai and Bangalore outpaces domestic manufacturing capacity. Target subscription commerce infrastructure gaps in secondary United States metropolitan markets with emerging gym culture density. Deploy precision fermentation protein partnerships as differentiation anchor against incumbent whey-dominant formulations.
For Investors and Strategic Acquirers: The market sits at an expansion phase that favors brands with captive subscription revenue and alternative protein sourcing agreements. Long-term viability over the coming decade hinges on regulatory navigation capabilities across FDA, EFSA, and FSSAI frameworks. Acquisition target archetype: direct-to-consumer specialists with proven repeat purchase rates and clean-label certification portfolios. Signal to watch: EFSA novel food approval velocity for precision fermentation proteins as inflection indicator for formulation cost structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Commerce Infrastructure | Quest Nutrition's recurring revenue model locks in predictable replenishment and reduces customer acquisition costs. |
| Precision Fermentation Partnership | Clean-label brands in the Netherlands pilot animal-identical dairy proteins without conventional agriculture supply chain exposure. |
| USDA Organic Certification Investment | Premium tier brands command natural retail shelf placement and justify price premiums over conventional alternatives. |
| FSSAI Clean-Label Manufacturing Establishment | Early movers in Maharashtra and Karnataka industrial corridors capture emerging urban fitness demand and export-ready production capacity. |
| Fitness Facility Distribution Expansion | Impulse placement at gym checkout counters captures peak post-workout purchase intent in United States metropolitan markets. |
Research Methodology
A spread of perspectives from brand managers at sports nutrition companies, category buyers at club retailers, formulation chemists at baked goods manufacturers, and procurement leads at co-manufacturing facilities converged on the working assumptions driving this analysis. Primary interview insights combined with secondary validation from FDA Food Labeling Guide standards, USDA Organic certification databases, FSSAI regulatory filings, and Nielsen retail audit data. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates across the projection horizon.
Demand-supply-balance framing anchored the analytical framework, modeling consumption occasion segmentation alongside protein source diversification, texture format preferences, and certification tier adoption patterns throughout the forecast period. CAGRs derived from historical growth trajectory analysis adjusted for regulatory enforcement intensity and alternative protein approval pathways. Industry-specific forecast inputs included precision fermentation scale-up timelines and fitness facility distribution penetration rates.
Sensitivities concentrate around FTC protein claim substantiation enforcement, EFSA novel food approval delays, and whey protein commodity price volatility. Forecasts reflect documented assumptions on consumer acceptance thresholds for plant-based formulations and subscription commerce adoption curves. Cross-checking against Euromonitor packaged food sector benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food & Ingredients
Global Probiotic Ingredients Market
Functional Food & Ingredients
Brazil Flavored and Functional Water Market
Functional Food & Ingredients
Healthy Fats Low Carb Market
Functional Food & Ingredients
Vegan DHA Market
Functional Food & Ingredients
Europe Botanical Extract Market
Functional Food & Ingredients
Lovage Extract Market
Functional Food & Ingredients
Refined Functional Carbohydrates Market
Functional Food & Ingredients
Italy Protein Market
Functional Food & Ingredients
Essential Fatty Acids Market
Functional Food & Ingredients
Asia-Pacific Omega3 PUFA Market
Functional Food & Ingredients
Mediterranean Cognitive-First Ingredient Systems Market
Functional Food & Ingredients
Beta Glucan and Fucoidan Market
Functional Food & Ingredients
APAC Heart Health Functional Food Market
Functional Food & Ingredients
Low-Carb Low-Fat Meal Market
Functional Food & Ingredients
Global Medical Foods Market
Functional Food & Ingredients
South America Omega-3 PUFA Market