
 Global Probiotic Ingredients Market | 2026-2036
Global Probiotic Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Global Probiotic Ingredients Market Outlook
Buyer concentration among functional food manufacturers is rebalancing as large dairy and beverage processors consolidate strain procurement around suppliers with clinical dossiers. Chr. Hansen Holding A/S leverages its human clinical trial library to anchor premium positioning with multinational dairy processors. Lallemand Inc. competes through yeast and bacteria diversification across human and animal nutrition. Kerry Group plc extends its integrated ingredient-to-flavor portfolio to capture formulation service revenue alongside raw probiotic supply.
Probiotic ingredients comprise live microorganisms, predominantly lactic acid bacteria and bifidobacteria, delivered in powder, liquid, or encapsulated forms with specified colony-forming unit counts per gram; these cultures colonize host microbiota to confer documented health benefits in food, supplement, and feed applications. Lactic acid bacteria dominates production volume due to decades of fermentation infrastructure and GRAS familiarity, while yeast segments attract investment from animal feed formulators seeking antibiotic alternatives. Dietary supplements command margin premiums where strain-specific health claims survive regulatory scrutiny, whereas dairy applications sustain volume throughput through fermented milk and yogurt platforms.
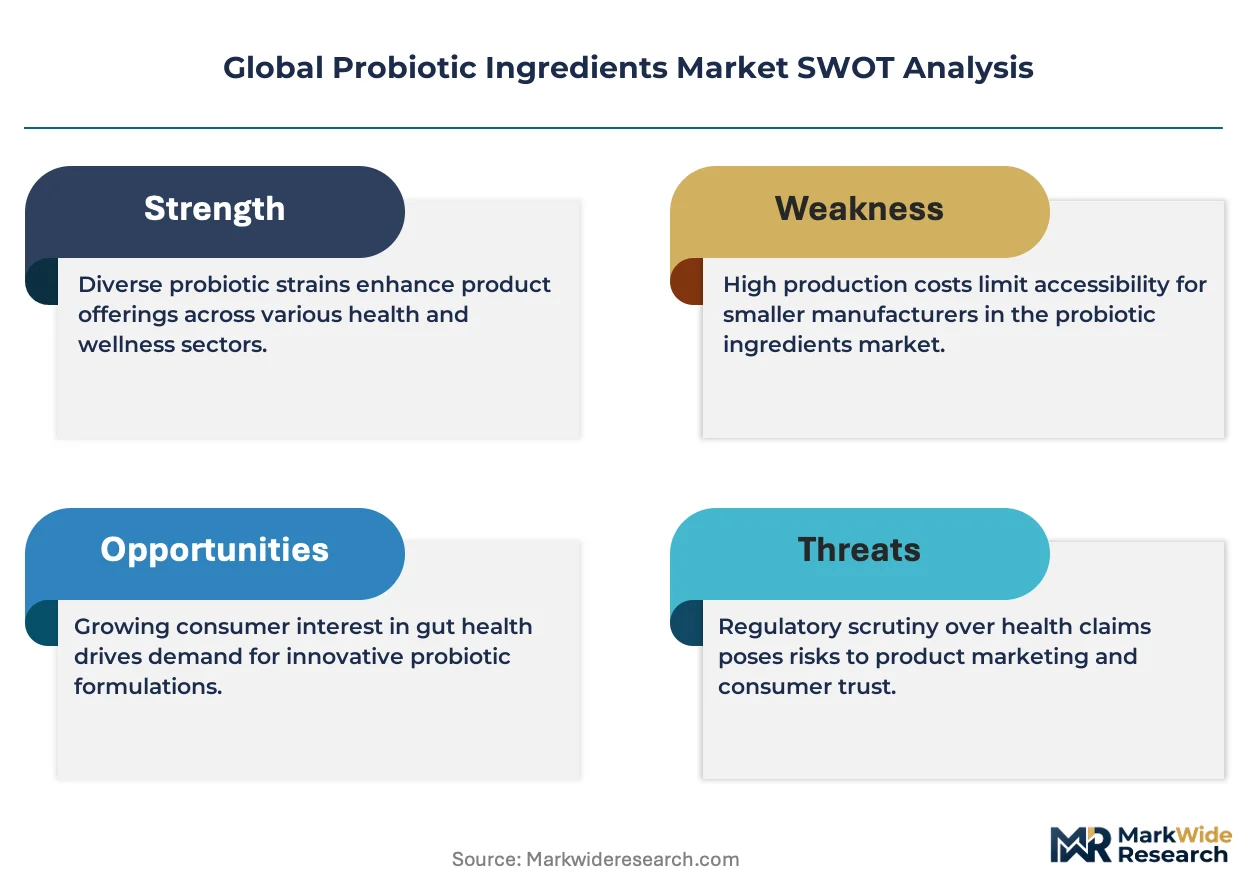
EFSA evaluates health claim substantiation under the EU Nutrition and Health Claims Regulation, while FDA exercises GRAS self-determination oversight for strains entering US food channels; China's NMPA and SAMR jointly administer novel food ingredient approvals for imported probiotic strains, extending market access timelines. Strain-level regulatory differentiation now determines which suppliers capture pharmaceutical-adjacent positioning versus commodity fermentation economics. Stakeholders must monitor evolving strain-specific approval precedents across jurisdictions to align R&D pipelines with accessible market pathways.
Market Dynamics
Strain-level regulatory differentiation is fragmenting competitive positioning across jurisdictions, forcing suppliers to build parallel clinical dossiers for EFSA, FDA, and NMPA pathways rather than leveraging single-study economies of scale.
Growth Catalysts
- EFSA Article 13.1 health claim substantiation:Dairy processors in the EU now prioritize suppliers with approved strain-specific dossiers, compressing vendor shortlists to clinically validated partners.
- China's domestic dairy consolidation:Yili and Mengniu are building captive fermentation capacity, pulling demand toward local strain development and reducing import dependency.
- Antibiotic-free animal feed mandates:Poultry and swine operations in Brazil and Thailand are substituting ionophores with Saccharomyces cerevisiae and Bacillus-based direct-fed microbials.
Market Restraints
- Freeze-drying energy intensity:Lyophilization accounts for disproportionate input cost volatility as European natural gas and electricity tariffs strain margin structures at toll manufacturers.
- Strain IP concentration in Denmark and France:Patent thickets around Lactobacillus rhamnosus GG and Bifidobacterium animalis subsp. lactis BB-12 limit new entrant formulation freedom.
- NMPA novel food ingredient timelines:China's dual-agency review extends strain approval cycles to 18-24 months, freezing market access for unregistered imports.
Strategic Opportunities
- Postbiotic metabolite platforms:Heat-killed cell fragments and fermentation supernatants bypass live-culture stability constraints in ambient beverage applications.
- India's FSSAI functional food notification pathway:Recent clarifications on probiotic strain safety documentation are opening access for established suppliers with US or EU regulatory histories.
- Precision fermentation convergence with AI-driven strain optimization:Machine learning is compressing phenotype screening cycles for next-generation psychobiotic candidates targeting stress-response pathways.
Industry Challenges
- PhD-level fermentation scientist scarcity:Industrial-scale anaerobic culture expertise concentrates in legacy dairy regions, constraining capacity expansion in emerging production clusters.
- cGMP certification timelines for pharmaceutical-adj positioning:Strain suppliers seeking drug-device pathway access face 12-18 month facility qualification delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Probiotic Ingredients Market |
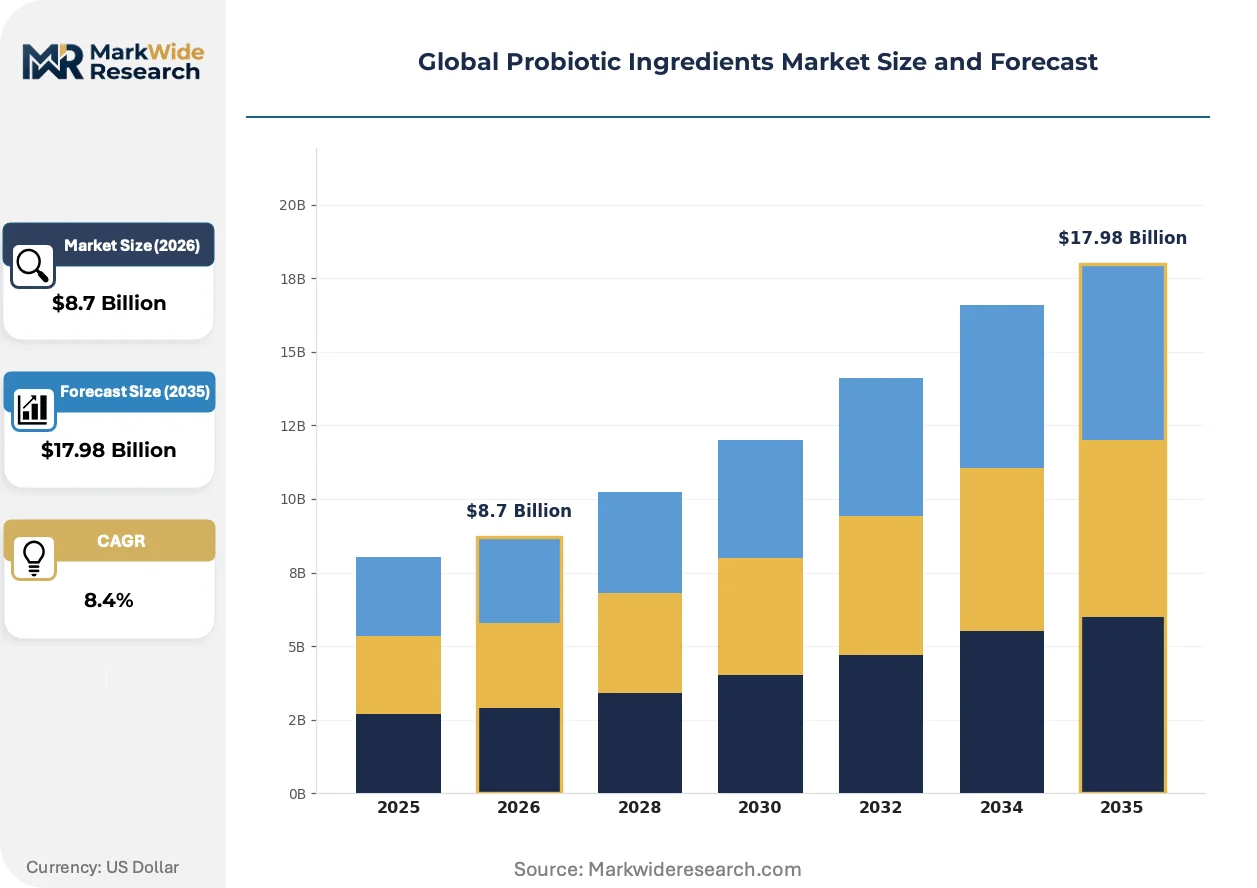
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
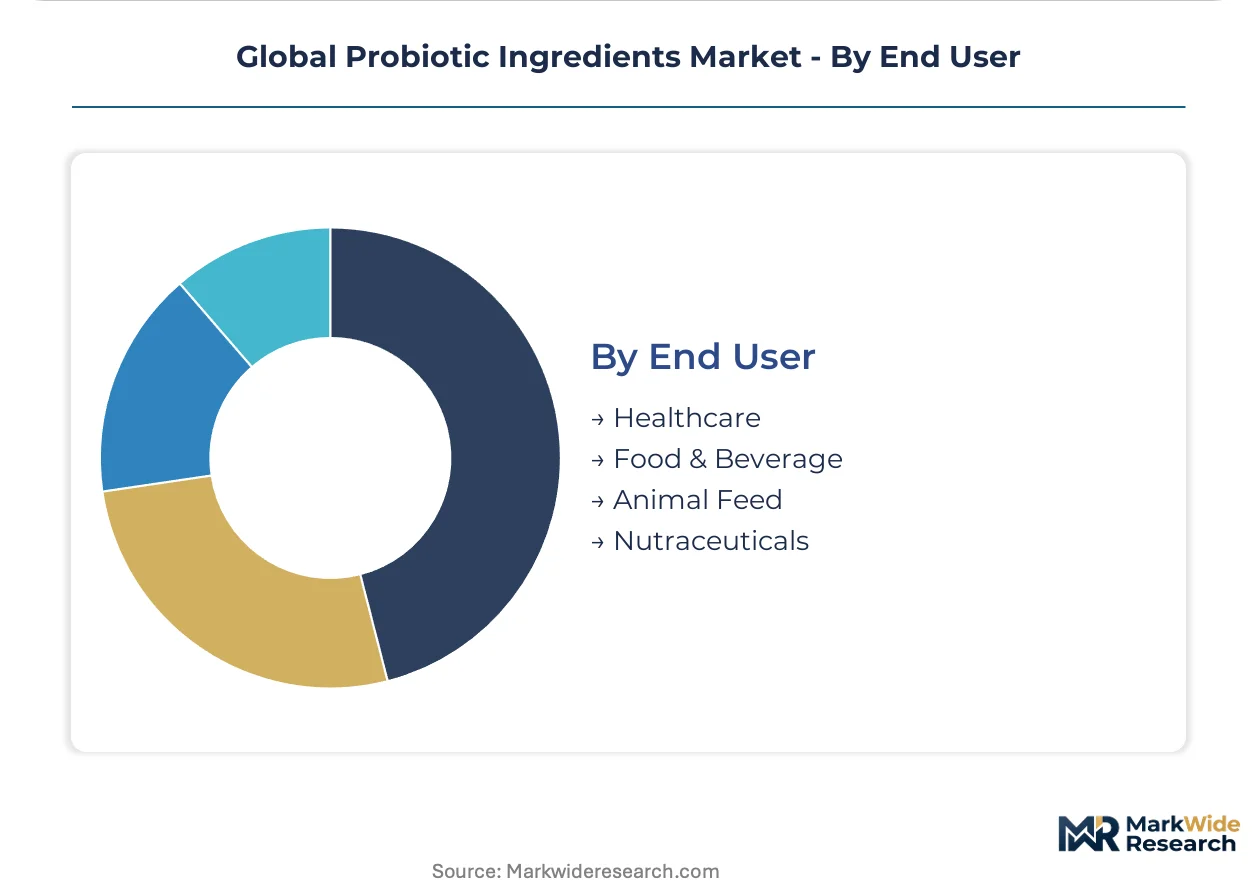
| Segmentation | Product Type: Lactic Acid Bacteria, Bifidobacteria, Yeast, Others Application: Dairy Products, Dietary Supplements, Functional Foods, Beverages Form: Powder, Liquid, Capsules, Gummies End User: Healthcare, Food & Beverage, Animal Feed, Nutraceuticals |
| Companies Covered | Chr. Hansen Holding A/S, DSM-Firmenich AG, Lallemand Inc., DuPont de Nemours, Inc., Probi AB, BioGaia AB, Kerry Group plc, Yakult Honsha Co., Ltd., Novonesis A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Probiotic Ingredients Market Strategic Shifts
Multi-omics strain characterization is displacing traditional plate-based enumeration, enabling suppliers to document mechanism-of-action with transcriptomic and metabolomic depth that satisfies both regulators and premium-positioned brand owners.
Single-cell encapsulation via spray-congealing and electrospinning is unifying shelf-stability and targeted-release functionality previously requiring separate processing steps. Infant formula and medical nutrition manufacturers in Germany and the Netherlands are adopting these formats at pilot scale. The technology is unifying what were historically incompatible supply chains for ambient and refrigerated finished goods.
EFSA's 2023-2024 guidance updates on "probiotic" as a reserved health claim term are forcing reformulation of products with insufficient strain-specific substantiation. Manufacturers are responding by removing genus-species labeling from packaging or investing in de novo clinical trials. Dietary supplement SKUs with legacy "probiotic" front-of-pack claims face the highest compliance exposure.
Direct-to-consumer genetic testing is rotating demand toward personalized microbiome modulation. Subscription platforms in the US and UK are curating strain combinations based on 16S rRNA profiling, disintermediating traditional retail pharmacy and mass-market supplement channels. This pattern is most visible among urban millennials purchasing gut-health protocols online.
Global Probiotic Ingredients Market Segmentation
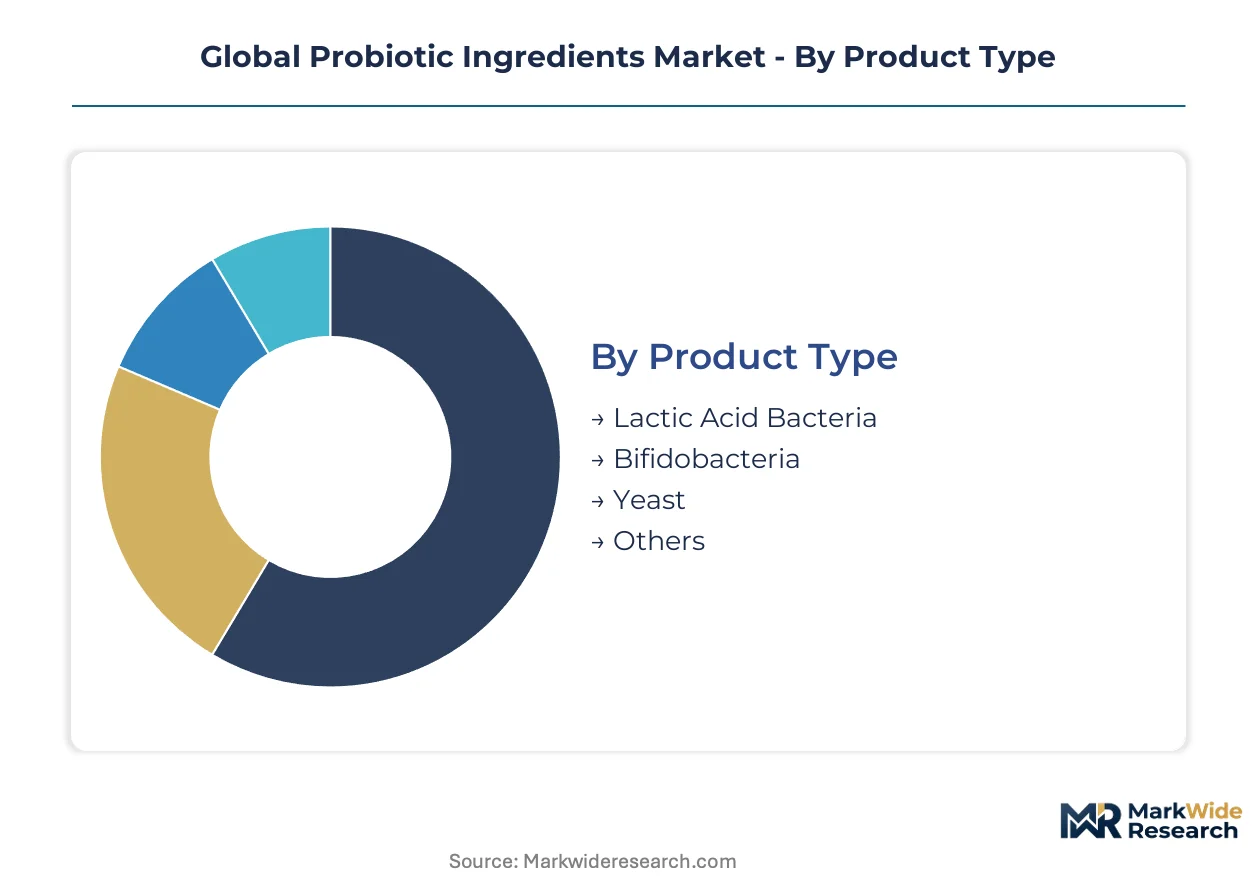
Probiotic ingredient suppliers configure production assets around strain-specific fermentation economics and finished-form stability requirements. Segmentation reveals where clinical dossiers command premiums versus where commodity scale dominates procurement decisions.
Product Type:
Strain phylogeny determines fermentation infrastructure requirements, regulatory pathway complexity, and end-use formulation compatibility across human and animal applications.
- Lactic Acid Bacteria:These Gram-positive, non-spore-forming cultures dominate industrial fermentation capacity with established GRAS status under FDA pathways and QPS recognition from EFSA. Dairy processors in Germany and the Netherlands anchor procurement volumes around Lactobacillus and Streptococcus thermophilus strains for yogurt and cheese applications, though freeze-drying energy costs compress margins at European toll manufacturers.
- Bifidobacteria:Obligate anaerobes with more complex nutritional requirements than lactobacilli, these strains colonize the infant gut microbiome and command premium positioning in medical nutrition. Formulators in Japan and South Korea concentrate demand around Bifidobacterium longum and breve species for synbiotic infant formula, with NMPA novel food approvals in China extending access timelines for unregistered imports.
- Yeast:Saccharomyces cerevisiae and S. boulardii variants serve antibiotic-free animal feed mandates in Brazil and Thailand, where poultry and swine operations substitute ionophores with direct-fed microbials.
- Others:Bacillus spore-formers and Propionibacterium strains occupy niche pharmaceutical and propionic acid fermentation applications with specialized cGMP requirements.
Lactic acid bacteria leads on scale; bifidobacteria leads on momentum.
Application:
Finished-goods shelf stability and health claim substantiation depth segment procurement priorities across ambient, refrigerated, and pharmaceutical-adjacent channels.
- Dairy Products:Fermented milk and yogurt platforms sustain volume throughput through refrigerated supply chains with live culture guarantees. EFSA Article 13.1 approved strain dossiers compress EU vendor shortlists to clinically validated partners like Chr. Hansen, while China's Yili and Mengniu build captive fermentation capacity.
- Dietary Supplements:Capsule, tablet, and sachet formats command margin premiums where strain-specific health claims survive regulatory scrutiny. US and UK subscription platforms curate combinations based on 16S rRNA profiling, disintermediating retail pharmacy channels.
- Functional Foods:Ambient-stable formats drive investment in heat-killed postbiotics and microencapsulation technologies bypassing live-culture constraints.
- Beverages:Liquid delivery encounters pH and oxygen stability challenges, constraining strain selection to acid-tolerant variants with shorter shelf-life positioning.
Dairy products anchor volume throughput; dietary supplements capture margin expansion.
Form:
Physical presentation determines supply chain temperature requirements, bioavailability engineering, and finished-goods manufacturing integration complexity.
- Powder:Standardized CFU/g specifications enable dry blending into infant formula, medical nutrition, and animal feed premixes with established pharmacopeial testing protocols.
- Liquid:Bulk fermentation supernatants and concentrated suspensions serve beverage manufacturers and direct-fed microbial applications with shorter distribution windows.
- Capsules:Enteric-coated and delayed-release variants protect acid-labile strains through gastric transit, concentrating demand in pharmaceutical and premium supplement channels.
- Gummies:Water activity and thermal processing constraints limit strain viability, positioning this format for postbiotic and heat-killed ingredient platforms.
Powder dominates manufacturing integration; capsules capture premium positioning.
End User:
Customer sophistication around clinical substantiation and regulatory compliance stratifies supplier relationships from commodity fermentation to pharmaceutical-adjacent partnerships.
- Healthcare:Hospital formulary and medical nutrition prescribers demand strain-specific mechanism-of-action documentation with multi-omics characterization satisfying both EFSA and FDA GRAS pathways.
- Food & Beverage:Multinational dairy and beverage processors consolidate procurement around suppliers with parallel clinical dossiers for EU, US, and China market access.
- Animal Feed:Brazilian and Thai poultry and swine operations drive Saccharomyces and Bacillus demand under antibiotic-free mandates with cost-per-unit-gain economics.
- Nutraceuticals:Direct-to-consumer brands and contract manufacturers prioritize formulation service capabilities alongside raw ingredient supply, favoring integrated ingredient-to-flavor portfolios.
Food and beverage commands volume concentration; healthcare drives premium trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation scientists and industrial microbiologists concentrate in legacy dairy regions of Denmark, France, and the Netherlands, anchoring strain development expertise that suppliers in emerging markets struggle to replicate.
United States
Direct-to-consumer genetic testing platforms in Boston and San Francisco rotate demand toward personalized microbiome modulation. FDA exercises GRAS self-determination oversight for strains entering food channels. Pharmaceutical-adjacent positioning concentrates in Research Triangle Park, where cGMP facility qualifications extend 12-18 months.
China
Domestic dairy processors Yili and Mengniu build captive fermentation capacity in Hohhot and Beijing, pulling demand toward local strain development. NMPA and SAMR jointly administer novel food ingredient approvals, extending access timelines to 18-24 months for unregistered imports. Yangtze River Delta biotech clusters attract precision fermentation investment targeting psychobiotic candidates.
Germany
Infant formula and medical nutrition manufacturers in Munich and Frankfurt adopt single-cell encapsulation at pilot scale. EFSA Article 13.1 health claim substantiation compresses vendor shortlists to clinically validated partners. Bavarian toll manufacturers face margin pressure from freeze-drying energy intensity as natural gas tariffs strain cost structures.
Brazil
Poultry and swine operations in São Paulo and Paraná substitute ionophores with Saccharomyces cerevisiae and Bacillus-based direct-fed microbials under antibiotic-free mandates. ANVISA regulates novel feed additives with cost-per-unit-gain economics driving procurement decisions. Southern agricultural clusters anchor Latin American demand for yeast-derived animal nutrition inputs.
India
FSSAI functional food notification pathway clarifications on probiotic strain safety documentation open access for suppliers with US or EU regulatory histories. Mumbai and Bangalore nutraceutical formulators prioritize integrated ingredient-to-flavor portfolios. Western pharmaceutical corridors near Pune attract contract fermentation capacity expansion targeting export markets.
Global Probiotic Ingredients Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across strain development, fermentation capacity, and formulation services. The vendor base stratifies into three tiers: multinational life science conglomerates with parallel clinical dossiers, mid-cap specialists with regional regulatory expertise, and toll manufacturers competing on scale economics. Dominant competitive moves include backward integration into captive strain libraries and geographic expansion through distributor partnerships in priority markets.
Within the multinational tier, Chr. Hansen Holding A/S and DSM-Firmenich AG exemplify suppliers anchoring premium positioning through human clinical trial libraries. Lallemand Inc. occupies a position bridging yeast and bacteria diversification across human and animal nutrition applications. Kerry Group plc represents the integrated ingredient-to-flavor portfolio archetype, capturing formulation service revenue alongside raw probiotic supply.
| Leading Market Players |
|---|
| Chr. Hansen Holding A/S |
| DSM-Firmenich AG |
| Lallemand Inc. |
| DuPont de Nemours, Inc. |
| Probi AB |
| BioGaia AB |
| Kerry Group plc |
| Yakult Honsha Co., Ltd. |
| Novonesis A/S |
| Others |
Value Chain & Pricing Dynamics
Multinational dairy and beverage processors anchor procurement volumes, compressing supplier margins through long-term contract structures that bundle strain supply with formulation services and regulatory dossier access. This buyer concentration forces tiered pricing stratification across premium clinically validated strains, standard fermentation commodities, and economy toll-manufactured alternatives.
Pricing Analysis
Formulation service bundling separates premium-positioned suppliers from commodity competitors. Price differentiation rests on clinical dossier depth and parallel EFSA-FDA-NMPA regulatory coverage versus single-jurisdiction approvals. Pricing pressure stems from freeze-drying energy cost volatility at European toll manufacturers. Animal feed buyers exhibit highest price sensitivity under cost-per-unit-gain economics, while medical nutrition formulators accept premium positioning for strain-specific mechanism documentation.
Supply Chain Analysis
China's domestic content mandates through NMPA novel food pathways are reshaping sourcing patterns for imported strains. Manufacturing gravity centers on Denmark, France, and the Netherlands where fermentation scientists concentrate. Supply chains draw from specialized culture media inputs, freeze-drying equipment, and cGMP-certified encapsulation capacity. Single-source vulnerability runs through European natural gas-dependent lyophilization infrastructure. Distribution runs through direct technical sales to multinational processors and distributor networks in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Probiotic Ingredients Market functions as a stable compounder underpinned by regulatory ratchets that continuously raise substantiation barriers for new entrants while locking in incumbent clinical libraries.
For Market Incumbents: To counter captive fermentation buildouts by Yili and Mengniu, deepen strain library exclusivity through de novo clinical trials targeting NMPA pathways. Anchor premium positioning by expanding cGMP pharmaceutical-adjacent capacity in Research Triangle Park and Bavarian clusters. For New Entrants and Emerging Players: Capture white space in India's FSSAI notification pathway where US and EU regulatory histories accelerate access. Target postbiotic metabolite platforms bypassing live-culture stability constraints in ambient beverage applications. Lead with precision fermentation partnerships offering AI-optimized psychobiotic screening. For Investors and Strategic Acquirers: Food and beverage conglomerates with integrated flavor portfolios are the most active acquirers in this space, seeking formulation service capabilities alongside raw strain supply. Five-to-ten year viability favors targets with parallel clinical dossiers spanning three-plus regulatory jurisdictions. Watch NMPA approval velocity for imported strains as inflection indicator for market access competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Dossier Expansion | EFSA Article 13.1 approvals compress EU vendor shortlists to validated partners. |
| Captive Fermentation Buildout | Yili and Mengniu reduce import dependency through Hohhot and Beijing capacity. |
| Postbiotic Platform Development | Heat-killed metabolites bypass live-culture constraints in ambient supply chains. |
| Precision Fermentation Investment | Machine learning compresses phenotype screening for psychobiotic candidates. |
| cGMP Facility Qualification | Pharmaceutical-adjacent positioning requires 12-18 month certification timelines. |
Study Parameters
Multiple input streams — fermentation technology assessments, regulatory pathway tracking, and procurement pattern analysis — were reconciled across primary interviews with strain development executives, regulatory affairs leads at multinational suppliers, dairy processor procurement directors, and animal feed formulators, combined with secondary validation from EFSA guidance documents, FDA GRAS notifications, NMPA novel food registries, and customs trade data, with bottom-up strain volume estimates triangulated against top-down market sizing.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include strain phylogeny, finished-form stability requirements, application shelf-life positioning, and regional regulatory cluster. CAGRs were derived from supply-side capacity expansion trajectories and demand-side procurement consolidation patterns, incorporating freeze-drying energy cost indices and clinical trial pipeline velocities as industry-specific inputs.
Regulatory approval delays, energy tariff volatility, and domestic substitution acceleration are the dominant revision risks to modeled outputs. Forecasts reflect assumptions around strain-specific health claim substantiation pathways and captive fermentation buildout timelines. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food & Ingredients
Japan Soy Protein Market
Functional Food & Ingredients
South America Prebiotic Ingredients Market
Functional Food & Ingredients
Functional Ingredients Market
Functional Food & Ingredients
Sacha Inchi Protein Market
Functional Food & Ingredients
Lovage Extract Market
Functional Food & Ingredients
Multifunctional Food Ingredients Market
Functional Food & Ingredients
Refined Functional Carbohydrates Market
Functional Food & Ingredients
Global Medical Foods Market
Functional Food & Ingredients
Vegan DHA Market
Functional Food & Ingredients
Healthy Fats Low Carb Market
Functional Food & Ingredients
North America and Europe Medical Foods Market
Functional Food & Ingredients
Europe Prebiotic Ingredient Market
Functional Food & Ingredients
Africa Algae Omega-3 Ingredients Market
Functional Food & Ingredients
Protein Cookie Market
Functional Food & Ingredients
Functional Food Ingredients Market
Functional Food & Ingredients
Prickly Pear Fruit Metabolic Health Ingredients Market