
 Italy Protein Market | 2026-2036
Italy Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Protein Market Foresight
Foodservice buyer consolidation across Italian restaurant chains and ready-meal producers is expanding procurement volumes for bulk protein ingredients. Cargill leverages its European supply network to serve industrial-scale buyers across the Po Valley. Kerry Group anchors its position through specialized dairy protein formulations for Italian bakery applications. Roquette Frères competes with pea and fava bean protein isolates targeting meat-alternative manufacturers in Bologna and Milan.
Protein encompasses nitrogenous organic compounds composed of amino acid chains, with essential variants requiring dietary intake due to human inability to synthesize them endogenously; biological value and PDCAAS scores determine nutritional quality for food fortification. Animal protein maintains volume leadership in Italian processed meats and aged cheese production, though plant protein claims the fastest expansion trajectory as pulse processing capacity multiplies in Piedmont. Dairy protein concentrates command premium positioning in infant formula and senior nutrition segments where clinical validation supports reimbursement pathways.
EFSA governs novel protein safety assessments and health claim authorizations, while EU REACH regulates chemical inputs in protein extraction processes; Italy's Ministry of Health enforces national labeling standards for protein content declarations. The EU Green Deal's protein diversification targets are redirecting CAP subsidies toward domestic legume cultivation, reducing import dependency on South American soy. Stakeholders must track evolving novel food classifications for precision-fermented and insect-derived proteins as EMA and EFSA jurisdictional boundaries crystallize.
Market Dynamics
The EU Farm to Fork Strategy under the European Green Deal is redirecting Common Agricultural Policy subsidies toward domestic legume cultivation, compressing import dependency on South American soy while forcing protein processors to reconfigure sourcing networks across the Po Valley.
Growth Catalysts
- EU Green Deal protein diversification targets:CAP subsidies now favor domestic pulse farming in Piedmont and Lombardy, expanding local raw material availability for isolates and concentrates.
- Sports nutrition formulation demand:Functional food manufacturers in Bologna and Milan are scaling whey and plant-protein portfolios for ready-to-drink applications targeting fitness demographics.
- Precision fermentation technology maturation:Novel protein startups in Emilia-Romagna are advancing biomass cultivation methods that bypass traditional agricultural land requirements entirely.
Market Restraints
- South American soy import concentration:Over half of Italy's oilseed protein supply originates from Brazilian and Argentine crushing facilities exposed to climate volatility and currency fluctuation.
- EFSA novel food authorization timelines:Safety assessments for insect-derived and precision-fermented proteins routinely extend 18-24 months, freezing commercialization pipelines.
- Dairy protein premium pricing rigidity:Whey and casein concentrates maintain cost positions 40-60% above pea isolates, constraining penetration in mass-market bakery fortification.
Strategic Opportunities
- Calabria and Sicily underpenetration:Southern Italy's food processing base lacks localized protein isolation capacity, creating greenfield investment potential for fava bean and chickpea fractionation.
- Clinical nutrition reimbursement expansion:Italy's Ministry of Health is widening protein fortification coverage in senior care and post-surgical recovery protocols.
- Hybrid meat-alternative formulations:Convergence of extruded pulse proteins with fungal mycelium enables texture profiles that single-source isolates cannot achieve alone.
Industry Challenges
- Food technologist talent scarcity:Protein formulation expertise combining extrusion science and sensory optimization concentrates in northern Italy, leaving central and southern processors dependent on external consultants.
- Organic certification timeline compression:Conversion periods for legume cultivation lock land out of premium protein sourcing for 24-36 months, mismatching with near-term contract demands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Protein Market |
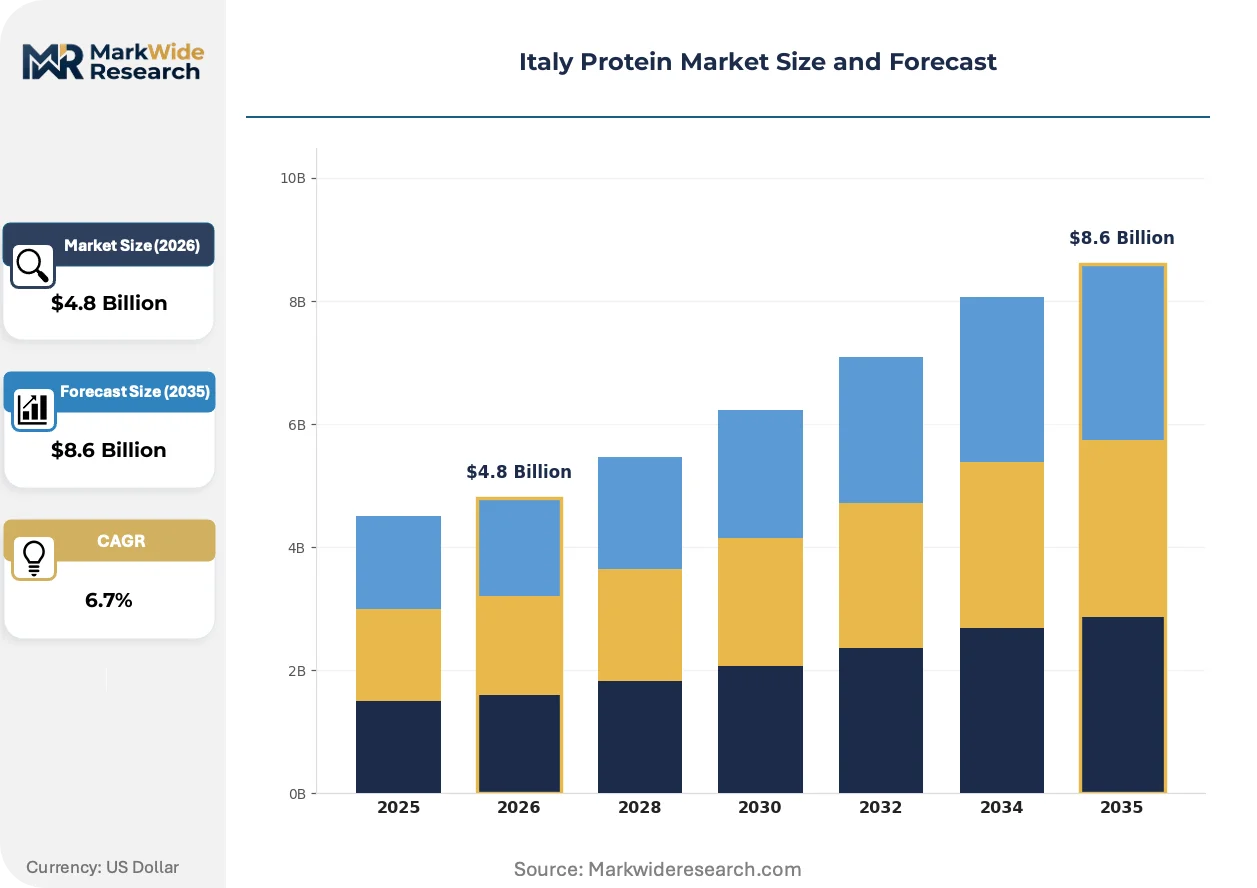
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Animal Protein, Plant Protein, Dairy Protein, Egg Protein Application: Food & Beverage, Nutritional Supplements, Animal Feed, Bakery Products End User: Health-Conscious Consumers, Fitness Enthusiasts, Athletes, General Population Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Health Food Shops |
| Companies Covered | DuPont de Nemours, International Flavors & Fragrances, Kerry Group, Roquette Frères, Koninklijke FrieslandCampina, Archer Daniels Midland Company, Darling Ingredients, Ingredion, Cargill, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Protein Market Shifts & Advancements
Protein extraction and formulation technologies are converging with sustainability mandates and shifting procurement patterns, redefining competitive advantage across Italian food manufacturing clusters.
Membrane filtration is unifying protein concentration and fractionation into single-pass operations, eliminating multi-stage precipitation steps. Dairy processors in Lombardy are retrofitting ultrafiltration skids to capture native whey proteins without denaturation, compressing energy consumption by one-third relative to traditional acid precipitation. This capability is enabling direct supply relationships with infant formula manufacturers who demand unaltered protein structures for digestibility claims.
REACH chemical registration requirements for extraction solvents are tightening purity specifications for hexane and ethanol used in oilseed processing. Italian protein isolate producers must now document supply chain compliance through ECHA-registered chemical handlers, adding documentation burden but creating competitive separation between integrated crushers and toll processors. The meat-alternative segment is absorbing these compliance costs fastest, as Bologna-based formulators export across the EU single market.
Foodservice buyers are consolidating procurement through centralized tender platforms operated by national restaurant chains and ready-meal producers. This aggregation is displacing spot-market purchasing for bulk protein ingredients, favoring suppliers with certified volume guarantees and traceability documentation. The shift is most visible in Lombardy's industrial catering sector, where three procurement cooperatives now control ingredient sourcing for over twelve thousand institutional kitchens.
Italy Protein Market Segmentation
Protein purchasing decisions in Italy diverge sharply across buyer profiles and use cases. Industrial food manufacturers prioritize functional specifications and supply security, while retail consumers respond to health positioning and channel accessibility.
Product Type:
Cost tier determines sourcing strategy for Italian protein buyers, with premium dairy isolates commanding fundamentally different procurement workflows than commodity plant concentrates.
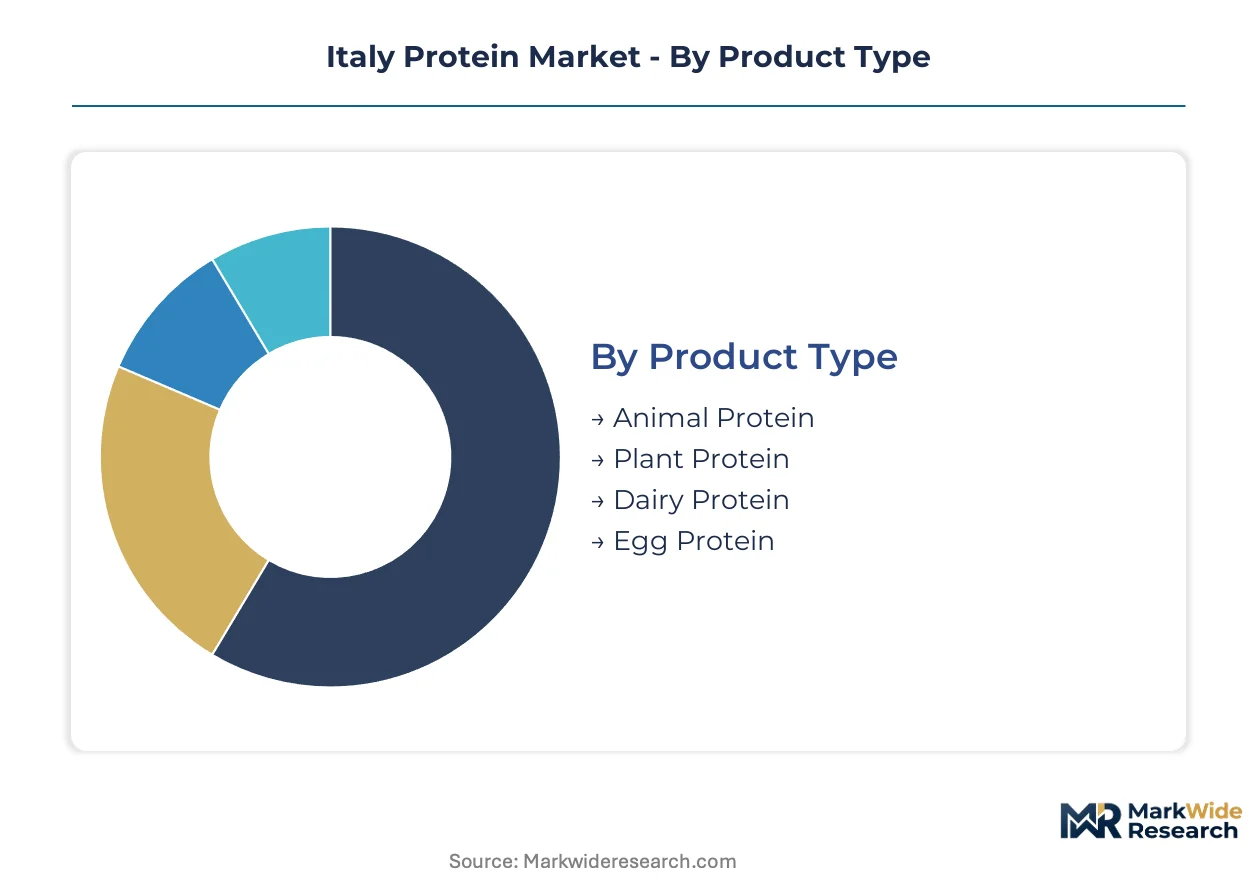
- Animal Protein:Comprises collagen, gelatin, and meat-derived concentrates with high biological value scores. Demand concentrates in Lombardy's processed meat sector where traditional salumi production requires specific protein binding properties for texture formation.
- Plant Protein:Includes pea, fava bean, and chickpea isolates with varying amino acid profiles. Bologna's meat-alternative manufacturers are scaling extruded pulse protein volumes fastest as EU Green Deal subsidies expand domestic legume crushing capacity.
- Dairy Protein:Whey and casein concentrates with superior leucine content for muscle protein synthesis. Infant formula producers in Milan pay premiums for native whey structures preserved through membrane filtration.
- Egg Protein:Albumen and whole egg powders with exceptional foaming and gelling functionality. Italian pasta and bakery applications in Emilia-Romagna sustain steady offtake despite avian influenza supply volatility.
Volume sits with animal protein; growth tilts toward plant protein.
Application:
Application maturity shapes margin structure, with established food processing segments defending price positions against emerging nutritional formats.
- Food & Beverage:Protein fortification of dairy alternatives, ready-to-drink beverages, and processed foods. Northern Italy's industrial clusters in Milan and Bologna concentrate formulation expertise for hybrid animal-plant blends.
- Nutritional Supplements:Powder and capsule formats targeting specific demographic needs. Sports nutrition brands in Lombardy are expanding whey isolate portfolios for fitness demographics with clinical validation requirements.
- Animal Feed:Soy and rapeseed meal for livestock and aquaculture nutrition. Po Valley pork and poultry producers depend on South American import flows vulnerable to currency fluctuation.
- Bakery Products:Gluten replacement and texture modification in bread and pastry applications. Italian artisan bakers prefer egg and dairy proteins for clean-label positioning against chemical emulsifiers.
Food and beverage commands installed capacity; nutritional supplements attract capital allocation fastest.
End User:
Customer type segmentation reveals divergent price elasticity and channel preferences across Italian protein consumption.
- Health-Conscious Consumers:Middle-aged demographics prioritizing protein for satiety and metabolic health. Pharmacy and parapharmacy channels in urban centers stock clinical-grade concentrates with EFSA-approved health claims.
- Fitness Enthusiasts:Regular gym attendees consuming protein for body composition goals. Ready-to-drink applications dominate this segment where convenience overrides cost sensitivity.
- Athletes:Competitive and professional sports participants with batch-tested product requirements. Italian Olympic Committee certification creates supply exclusivity for specialized whey and collagen suppliers.
- General Population:Mass-market consumers encountering protein through fortified everyday foods. Supermarket private label expansion is compressing branded premium positioning in this segment.
General population represents volume foundation; athletes sustain margin premiums through certification requirements.
Distribution Channel:
Channel concentration determines working capital intensity and traceability documentation burdens for protein suppliers.
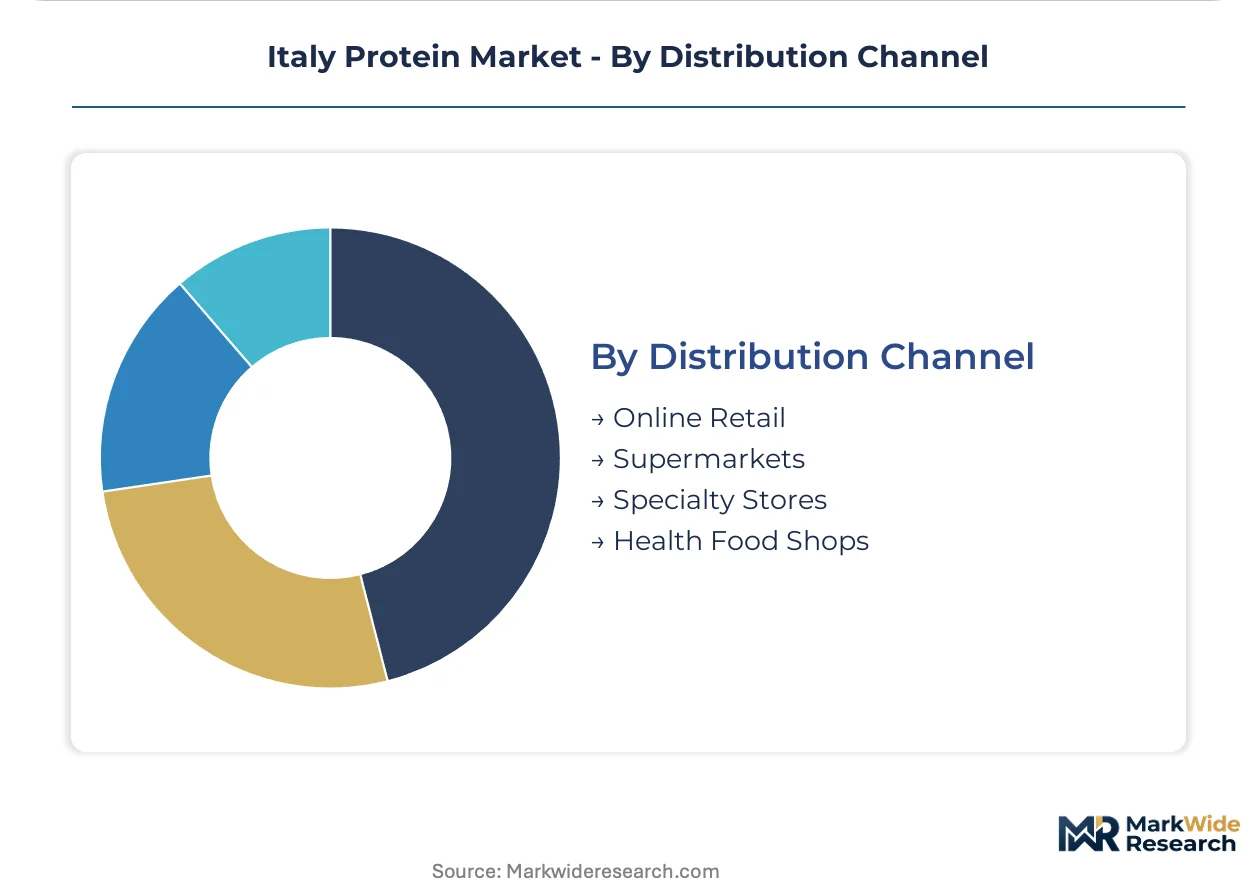
- Online Retail:Direct-to-consumer platforms with subscription mechanics and personalized nutrition bundles. Milan-based startups are capturing repeat purchase loyalty through AI-driven flavor and formulation matching.
- Supermarkets:Mass-market retail with centralized procurement and strict shelf-life requirements. Coop Italia and Conad are consolidating protein supplier bases to three certified partners per category.
- Specialty Stores:Independent health food retailers with curated premium assortments. Rome and Florence flagships emphasize Italian-origin legume proteins with organic certification.
- Health Food Shops:Pharmacy-adjacent channels with clinical credibility and practitioner recommendation networks. Post-surgical protein prescriptions in Lombardy's senior care facilities flow through this channel.
Supermarkets anchor volume throughput; online retail scales fastest through subscription mechanics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for protein ingredients in Italy concentrates in the northern industrial belt, where food processing clusters drive procurement volumes and shape supplier investment patterns across sub-regional markets.
Lombardy
Milan anchors Italy's sports nutrition formulation sector, with fitness-oriented ready-to-drink applications demanding whey isolates and hydrolysates. EFSA health claim authorizations govern product positioning in pharmacy and parapharmacy channels throughout the region. Bergamo and Brescia host membrane filtration facilities serving infant formula manufacturers with native protein structures.
Emilia-Romagna
Bologna's meat-alternative manufacturers scale extruded pulse protein volumes as EU Green Deal subsidies expand domestic legume crushing. REACH compliance requirements for extraction solvents tighten documentation burdens for oilseed processors operating across the Po Valley. Parma's aged cheese production sustains steady demand for specific dairy protein binding properties.
Piedmont
Turin-based pulse processors multiply fractionation capacity for pea and fava bean isolates targeting bakery fortification applications. CAP subsidy reallocation under the Farm to Fork Strategy accelerates domestic legume cultivation conversion. Novara's agricultural cooperatives lock land into organic certification timelines spanning 24-36 months.
Veneto
Verona's industrial catering procurement cooperatives aggregate ingredient sourcing for institutional kitchens across twelve thousand sites. ECHA-registered chemical handlers document solvent purity specifications for oilseed crushing operations. Padua's research institutions advance precision fermentation biomass cultivation methods bypassing traditional agricultural land requirements.
Lazio
Rome's specialty health food retailers curate premium Italian-origin legume protein assortments with organic certification positioning. Italy's Ministry of Health enforces national labeling standards for protein content declarations in fortified products. Post-surgical protein prescriptions flow through pharmacy-adjacent channels serving senior care facilities in the capital metro.
Italy Protein Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue novel protein formats including precision-fermented and insect-derived alternatives. The supplier base organizes around three archetypes: multinational ingredient conglomerates with European supply networks, specialized dairy and plant protein fractionators, and toll processors dependent on external raw material sourcing. Capacity expansion and strategic partnerships dominate competitive moves, with membrane filtration retrofitting and hybrid formulation development accelerating.
Within the multinational tier, Cargill, Kerry Group, and Roquette Frères occupy positions shaped by their respective supply network configurations. Cargill exemplifies the integrated crush-to-ingredient archetype through its European oilseed processing footprint. Kerry Group represents specialized dairy protein formulation capabilities anchored in regional bakery application expertise. Roquette Frères sits within the plant protein isolation segment, with pea and fava bean concentrate offerings aligned to meat-alternative manufacturer demand in northern Italian industrial clusters.
| Leading Market Players |
|---|
| DuPont de Nemours |
| International Flavors & Fragrances |
| Kerry Group |
| Roquette Frères |
| Koninklijke FrieslandCampina |
| Archer Daniels Midland Company |
| Darling Ingredients |
| Ingredion |
| Cargill |
| Others |
Supply & Pricing Matrix
Captive supply of South American soybeans through long-term offtake agreements anchors both the cost position and pricing power of Italy's largest protein processors. This backward integration into crushing capacity compresses raw material exposure while enabling premium positioning for EFSA-certified isolates in infant formula and clinical nutrition channels.
Pricing Analysis
Volume sits with commodity plant concentrates while margins concentrate in native whey structures for medical applications. Three-tier pricing structure across premium, standard, and economy levels separates membrane-filtered dairy isolates from hexane-extracted oilseed proteins and commodity feed-grade meals. Cost compression in standard-tier pulse isolates is intensifying because Roquette Frères and domestic Piedmont processors are expanding fractionation capacity simultaneously. Mass-market bakery fortification buyers exhibit highest price sensitivity; infant formula manufacturers accept 40-60% premiums for unaltered protein structures.
Supply Chain Analysis
Soybean supply rests on Brazilian and Argentine crushing facilities with Italian port discharge at Ravenna and Genoa. Fava bean and pea raw materials draw from expanding domestic cultivation in Piedmont and Lombardy under CAP subsidy reallocation. Hexane and ethanol solvent purity specifications under REACH create single-source vulnerability for toll processors lacking ECHA-registered chemical handlers. Distribution runs through Po Valley industrial clusters with Bologna and Milan anchoring formulation demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
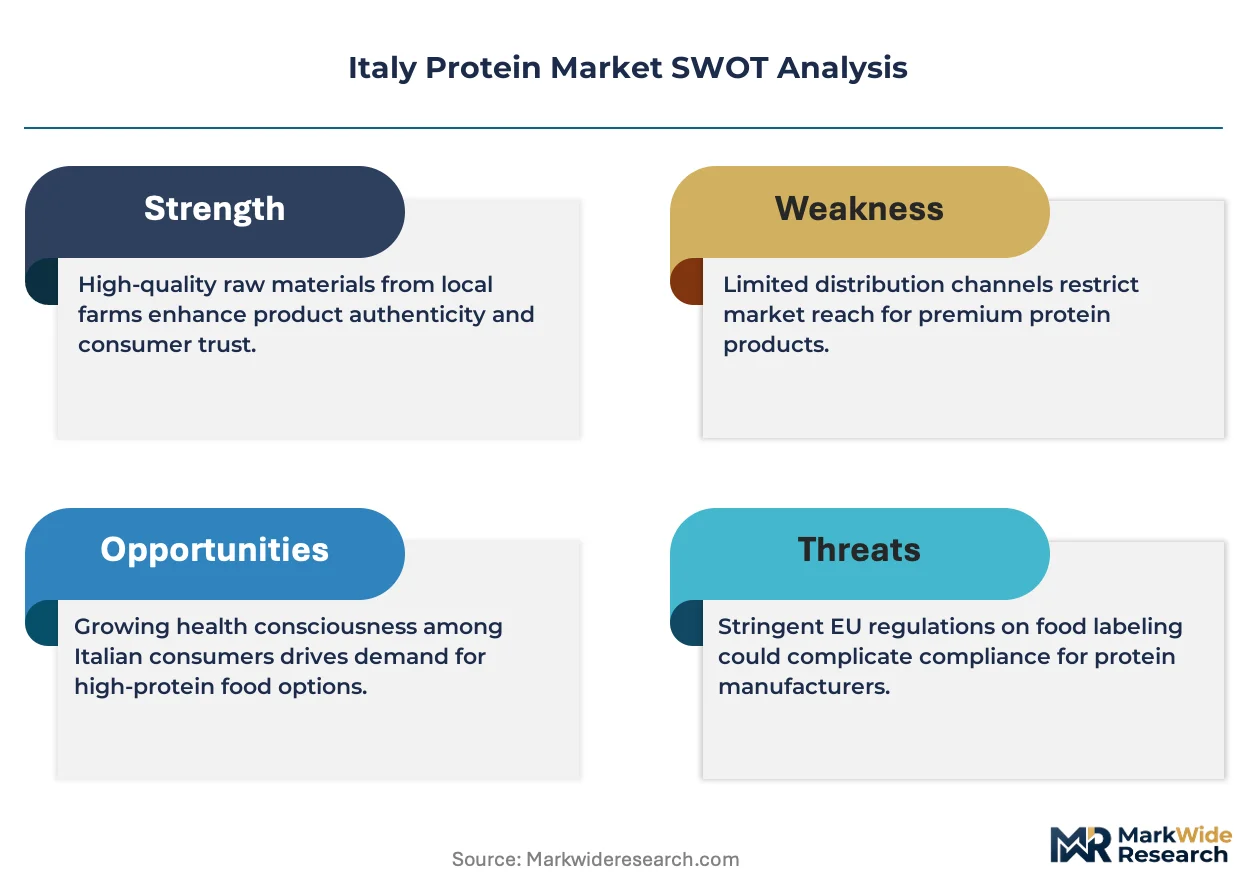
This market reads as a cost-of-compliance story where REACH chemical registration and EFSA novel food authorization timelines erect barrier-to-entry moats favoring incumbents with documented supply chain compliance.
For Market Incumbents: Acquire membrane filtration assets in Lombardy to capture native whey protein demand from infant formula manufacturers. Consolidate toll processing relationships in Emilia-Romagna before REACH documentation requirements force smaller competitors out of meat-alternative supply chains. Precision fermentation startups in Padua represent substitute technology threats requiring monitoring. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the lowest regulatory friction entry path for Calabria and Sicily protein isolation ventures. Southern Italy's underpenetrated food processing base lacks localized fava bean fractionation capacity. Partner with Novara agricultural cooperatives to secure organic-certified legume supply ahead of 24-36 month conversion timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to multinational ingredient conglomerates seeking European plant protein footprints. Five-to-ten year viability hinges on hybrid formulation capabilities combining extruded pulse proteins with fungal mycelium. Watch EFSA novel food authorization timelines for precision-fermented proteins as inflection indicator for competitive disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Retrofit | Captures native whey structures for Milan infant formula manufacturers demanding digestibility claims. |
| Domestic Legume Cultivation Expansion | Locks Piedmont farmland into organic certification under CAP Farm to Fork subsidy reallocation. |
| REACH Compliance Documentation | Creates competitive separation between integrated crushers and dependent toll processors. |
| Hybrid Protein Formulation Development | Enables texture profiles for Bologna meat-alternative manufacturers that single-source isolates cannot achieve. |
| Precision Fermentation Biomass Cultivation | Bypasses agricultural land requirements entirely for Emilia-Romagna novel protein startups. |
Research Methodology
EFSA novel food submission databases, EU CAP subsidy disbursement records, and REACH chemical registration filings formed the secondary backbone of this analysis. Primary interviews with membrane filtration plant managers, procurement leads at Bologna meat-alternative manufacturers, and pharmacy channel buyers validated supply chain configurations. Bottom-up protein isolate production estimates triangulated against top-down food processing demand across the analysis window.
Historical trendline analysis of dairy and oilseed processing capacity informed projection modeling across product type, application, and regional industrial cluster dimensions. CAGRs derived from segment-level demand elasticity and substitution dynamics between animal and plant protein formats. Forecast inputs incorporated EFSA authorization pipeline status and CAP subsidy reallocation trajectories without year-specific milestones.
The model holds under stable REACH enforcement and EFSA review timelines; deviation in novel food classification rulings or CAP funding continuity would shift capacity investment patterns. Forecasts reflect documented assumptions regarding hybrid formulation adoption rates and southern Italy infrastructure development. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food & Ingredients
Poultry Probiotic Ingredients Market
Functional Food & Ingredients
Brominated Vegetable Oil Market
Functional Food & Ingredients
Healthy Fats Low Carb Market
Functional Food & Ingredients
Refined Functional Carbohydrates Market
Functional Food & Ingredients
Omega 3 PUFA Market
Functional Food & Ingredients
Banana Leaf Extract Market
Functional Food & Ingredients
Functional Food Ingredients Market
Functional Food & Ingredients
Europe Sterol Market
Functional Food & Ingredients
South America Prebiotic Ingredients Market
Functional Food & Ingredients
Protein Cookie Market
Functional Food & Ingredients
Global Probiotic Ingredients Market
Functional Food & Ingredients
Lovage Extract Market
Functional Food & Ingredients
Mediterranean Pre-Diabetes Ingredient Concepts Market
Functional Food & Ingredients
Europe Prebiotic Ingredient Market
Functional Food & Ingredients
Mediterranean Cognitive-First Ingredient Systems Market
Functional Food & Ingredients
North America Pea Protein Ingredients Market