
 Essential Fatty Acids Market | 2026-2036
Essential Fatty Acids Market Size, Share, and Industry Trends Forecast 2026-2036
Essential Fatty Acids Market Analysis
Modular softgel configurations with variable EPA-to-DHA ratios is rebalancing how nutraceutical buyers configure contract manufacturing agreements. BASF SE leverages its German lipid chemistry infrastructure to sustain high-purity omega-3 concentrate output for pharmaceutical-grade applications. DSM-Firmenich anchors its competitive position through integrated algae-to-omega-3 fermentation platforms that reduce marine raw material dependency. Cargill Inc. competes by controlling global oilseed crushing networks that feed omega-6 and omega-9 fatty acid supply chains.
Essential fatty acids comprise polyunsaturated and monounsaturated lipid molecules—primarily omega-3 (alpha-linolenic acid, EPA, DHA), omega-6 (linoleic acid, arachidonic acid), and omega-9 (oleic acid)—that humans cannot endogenously synthesize and must obtain through diet or supplementation, typically manufactured via cold-pressing, molecular distillation, or microbial fermentation to achieve 30-90% active ingredient concentration for pharmaceutical and nutritional applications. Omega-3 dominates value generation due to cardiovascular and cognitive health evidence bases that command premium pricing in nutraceutical channels, while omega-6 maintains volume leadership through its embedded position in vegetable oil supply chains for food and beverage formulations. The cosmetics application segment represents the fastest structural expansion as topical ceramide and skin-barrier formulations incorporate omega fatty acids for dermatological positioning.
FDA pharmacopeial standards and EMA monograph requirements for EPA and DHA content verification shape product specifications and batch release protocols for omega-3 drug and supplement manufacturers. REACH chemical registration obligations in Europe and FSSAI nutraceutical labeling mandates in India further segment market access by compliance burden and analytical certification depth. Stakeholders must monitor evolving pharmacopeial harmonization between FDA and EMA omega-3 monographs to anticipate reformulation costs and specification drift.
Market Dynamics
Pharmaceutical-grade EPA and DHA concentration thresholds are tightening across FDA and EMA pharmacopeial standards, forcing manufacturers to reconfigure molecular distillation infrastructure and recalibrate batch release protocols for cardiovascular drug applications.
Growth Catalysts
- Cardiovascular drug pipelines:Formulators are expanding omega-3 active pharmaceutical ingredient sourcing as prescription indications for hypertriglyceridemia multiply.
- EMA monograph harmonization:Converging purity benchmarks between European and US regulators are reducing dual-certification burdens for cross-border suppliers.
- Algae fermentation platforms:Microbial production methods are decoupling omega-3 supply from marine ecosystem volatility and seasonal fishing constraints.
Market Restraints
- Marine raw material volatility:Peruvian anchovy catch fluctuations and El Niño patterns destabilize crude fish oil input costs for ethyl ester concentrate producers.
- Norwegian processing concentration:Bergen and Alesund harbor three-quarters of European omega-3 refining capacity, creating geographic single-point-of-failure exposure.
- REACH registration burdens:ECHA chemical dossier requirements for novel lipid derivatives impose six-figure compliance costs that freeze SME market entry.
Strategic Opportunities
- Indian nutraceutical channels:FSSAI labeling mandates are professionalizing supplement retail formats, opening branded omega-3 positioning in urban pharmacy chains.
- Topical ceramide formulations:Cosmetics laboratories are incorporating omega fatty acids into dermatological barrier-repair products for premium skincare positioning.
- Modular softgel configurations:Variable EPA-to-DHA ratio capsules allow contract manufacturers to serve personalized nutrition protocols without dedicated production lines.
Industry Challenges
- Analytical chemist scarcity:Gas chromatography and mass spectrometry specialists capable of EPA/DHA quantification to pharmacopeial standards command salaries that compress mid-tier processor margins.
- Dual certification timelines:Simultaneous FDA and EMA batch release protocols extend quality control cycles by eight to twelve weeks, straining working capital.
- Legacy ethyl ester infrastructure:Reconfiguration to free fatty acid and re-esterified triglyceride formats requires distillation column replacement capex that many independent refiners cannot finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Essential Fatty Acids Market |
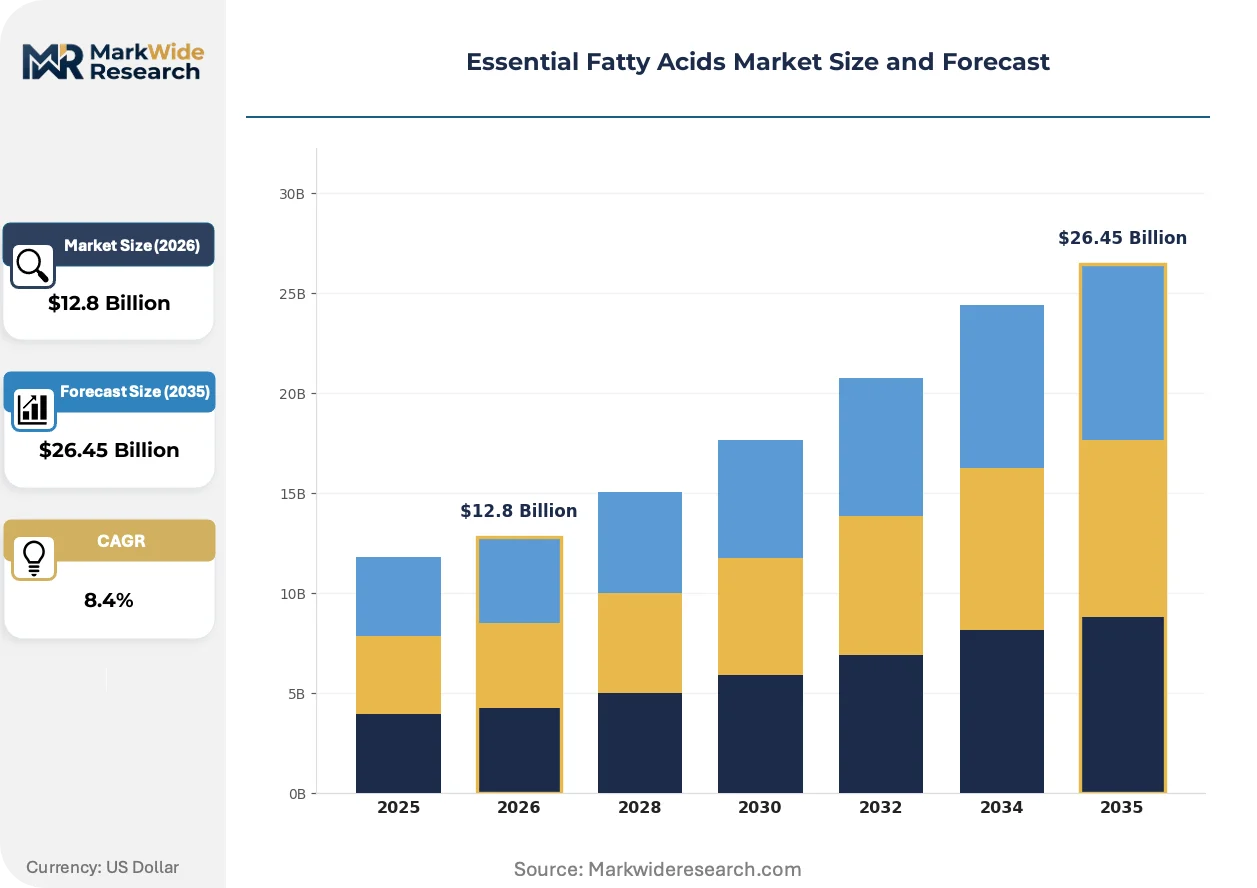
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Omega-3, Omega-6, Omega-9, Conjugated Linoleic Acid Application: Nutraceuticals, Pharmaceuticals, Food & Beverages, Cosmetics End User: Health-conscious Consumers, Athletes, Elderly Individuals, Pregnant Women Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | BASF SE, DSM-Firmenich, Cargill Inc., Croda International Plc, Aker BioMarine AS, Omega Protein Corporation, GC Rieber Oils AS, Arista Industries, Golden Omega, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Essential Fatty Acids Market Emerging Trajectories
Biotechnology-enabled production methods and tightening pharmacopeial standards are compressing traditional extraction economics while opening premium positioning for verified-sustainability supply chains.
Algae-to-omega-3 fermentation is overtaking marine oil refining as the dominant upstream technology for pharmaceutical-grade EPA and DHA production. Controlled bioreactor environments deliver batch-to-batch consistency that wild-catch fish oil cannot match. DSM-Firmenich and specialty biotechnology firms are scaling photobioreactor and heterotrophic fermentation platforms to displace crude fish oil dependency in prescription drug applications.
EMA and FDA pharmacopeial monograph convergence on EPA and DHA content verification methods is eliminating analytical protocol divergence that previously forced dual testing. European regulators are adopting USP reference standards for fatty acid methyl ester analysis, reducing certification overhead for multinational suppliers. Norwegian and German processors are consolidating quality control laboratories to serve both regulatory regimes from single facilities.
Cosmetics formulators are specifying omega fatty acids by carbon chain profile rather than generic botanical origin, forcing suppliers to certificate-of-analysis every lot for C16-C24 distribution. Premium skincare brands in France and Japan are rejecting bulk vegetable oil substitutes that lack documented ceramide precursor activity. This specification tightening is compressing commodity suppliers while rewarding lipid chemistry specialists with chromatographic verification capabilities.
Essential Fatty Acids Market Segmentation
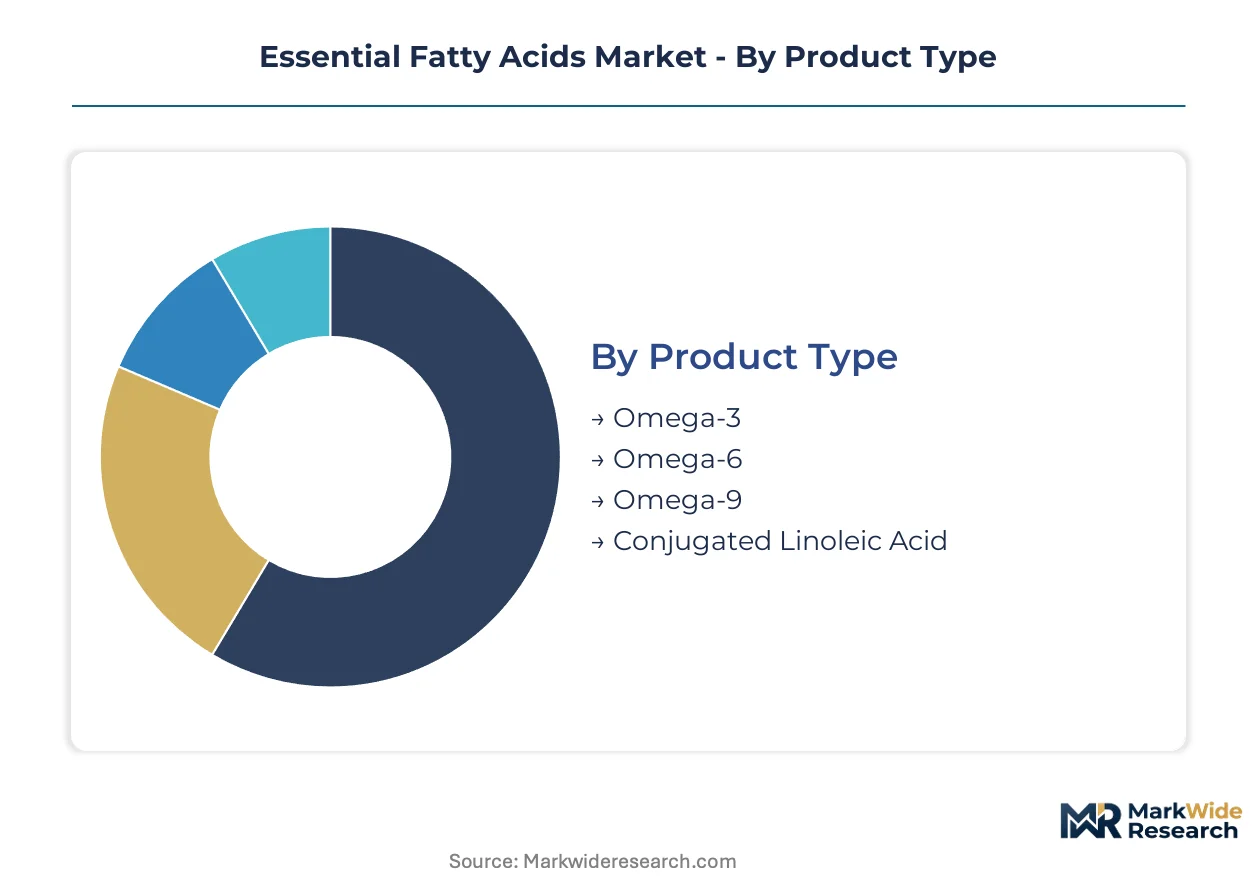
Segmentation in essential fatty acids reveals how capital allocation, regulatory pathways, and consumer access channels split value creation across markedly different investment profiles. Each dimension exposes distinct margin structures and competitive moats that determine where new entrants can realistically compete.
Product Type:
Omega-3 concentration infrastructure demands the heaviest capital commitment, with molecular distillation and chromatographic purification systems running into eight-figure installations before first commercial batch release.
- Omega-3:EPA and DHA concentrates from marine or algal sources require multi-stage molecular distillation and winterization to achieve 60-90% purity for pharmaceutical applications. Norwegian processors around Bergen dominate ethyl ester and re-esterified triglyceride output for prescription cardiovascular drugs. Demand concentrates in clinical nutrition and prescription hypertriglyceridemia therapies where FDA and EMA pharmacopeial standards enforce batch-to-batch consistency.
- Omega-6:Linoleic acid and arachidonic acid derive primarily from safflower, sunflower, and evening primrose oil through cold-pressing or solvent extraction. Cargill and ADM control crushing capacity in the US Midwest and Argentine Pampas, embedding omega-6 in commodity food oil supply chains with thin margins but massive throughput.
- Omega-9:Oleic acid from olive, canola, and high-oleic sunflower oils commands premium positioning in Mediterranean cosmetics formulations and clean-label food applications. Spanish and Italian processors leverage Protected Designation of Origin certification to sustain price premiums against commodity alternatives.
- Conjugated Linoleic Acid:CLA isomer concentrates from safflower oil require selective crystallization or enzymatic interesterification to achieve 80%+ active isomer ratios for sports nutrition positioning.
Omega-3 absorbs the bulk of installed capacity; Conjugated Linoleic Acid is expanding most quickly in personalized sports nutrition protocols.
Application:
Regulatory burden intensity—not volume—determines margin stratification across application segments, with pharmaceutical pathways extracting 3-5x the unit economics of commodity food fortification.
- Nutraceuticals:Dietary supplements in softgel, emulsion, and gummy formats dominate volume throughput, with FSSAI mandates in India and FDA 21 CFR 101 labeling rules shaping compliance architecture. Online direct-to-consumer channels and pharmacy retail split demand between convenience and clinical credibility positioning.
- Pharmaceuticals:Prescription omega-3 therapies for severe hypertriglyceridemia require Drug Master File submission, GMP-certified fermentation or marine oil refining, and bioequivalence documentation. Lovaza and Vascepa have established reimbursement pathways that generic entrants must navigate through abbreviated new drug applications.
- Food & Beverages:Microencapsulated omega-3 powders for infant formula and functional beverages compete on oxidation stability and sensory masking rather than concentration purity. New Zealand and Irish dairy processors lead algal DHA integration into milk and yogurt matrices.
- Cosmetics:Ceramide precursor applications in barrier-repair creams and anti-aging serums specify carbon chain distribution (C16-C24) with chromatographic verification, filtering out commodity vegetable oil substitutes.
Pharmaceuticals capture the steepest margin tier; Cosmetics is climbing the fastest as French and Japanese skincare brands professionalize lipid specification.
End User:
Purchasing sophistication and price elasticity diverge sharply across demographic segments, with clinical indication driving reimbursement access and self-directed wellness driving premium willingness-to-pay.
- Health-conscious Consumers:Preventive supplementation in 25-45 age brackets drives bulk omega-3 demand through subscription e-commerce and warehouse club channels, with third-party USP verification and IFOS certification serving as quality shortcuts.
- Athletes:CLA and omega-3 combinations for body composition and recovery support command 40-60% price premiums over standard potency products in specialty sports nutrition retail.
- Elderly Individuals:Cognitive health and cardiovascular maintenance indications concentrate demand in pharmacy and clinician recommendation channels, with Medicare Advantage supplemental benefits increasingly covering omega-3 testing and prescription products.
- Pregnant Women:Algal DHA for fetal neural development avoids marine contaminant concerns and dominates prenatal formulation, with DSM-Firmenich and Corbion supplying fermented sources to maternal health brands.
Health-conscious Consumers absorb the bulk of volume throughput; Pregnant Women is gaining share fastest as prenatal DHA recommendation protocols expand.
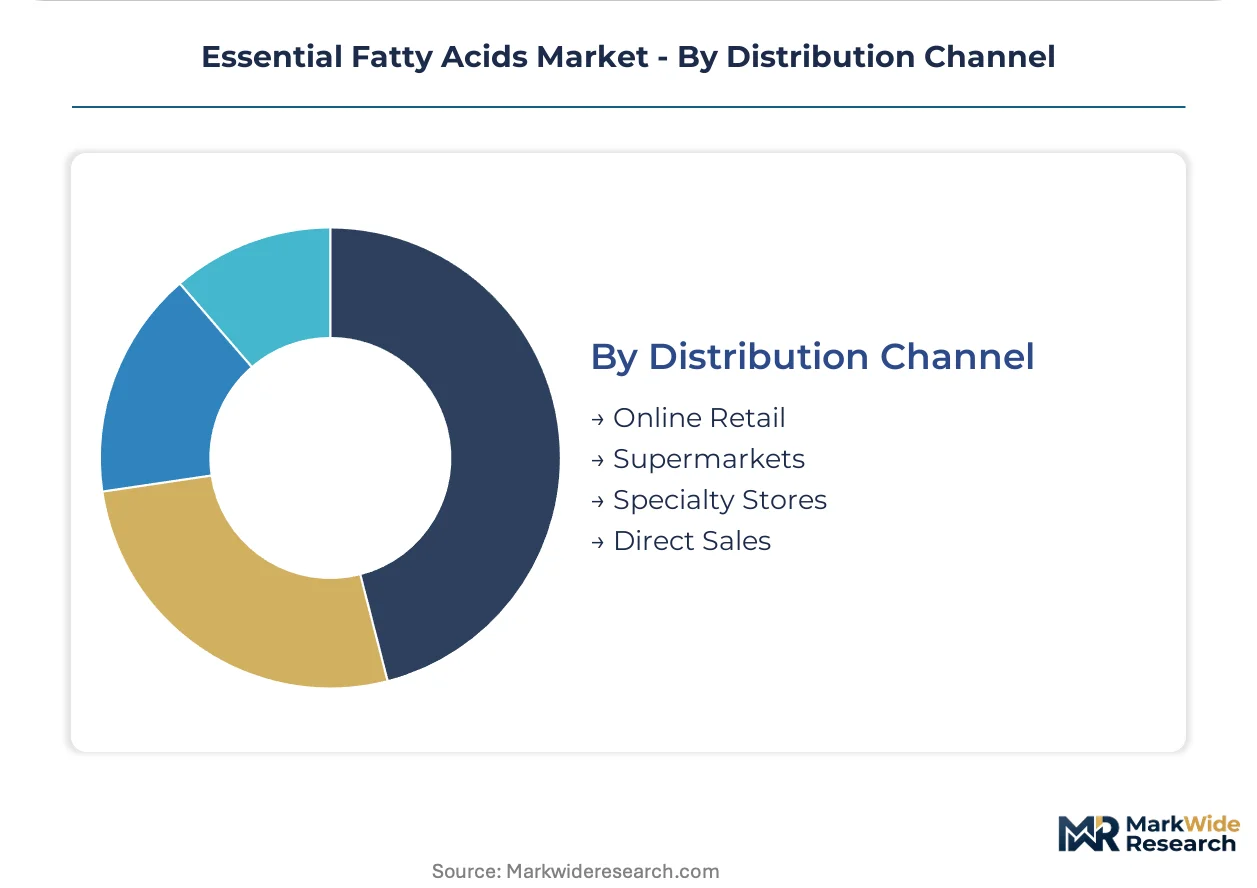
Distribution Channel:
Channel selection locks in margin structure and customer data access, with direct models capturing lifetime value and retail models purchasing shelf visibility at fixed trade spend rates.
- Online Retail:Amazon, iHerb, and brand-owned DTC sites aggregate 35-45% of omega-3 supplement volume in North America and Western Europe, with subscription models reducing churn and enabling personalized EPA/DHA ratio configurations.
- Supermarkets:Mass-market food, drug, and combination retailers (Kroger, Tesco, Carrefour) move standardized potency products with high inventory turns and thin trade margins, favoring suppliers with national distribution infrastructure.
- Specialty Stores:GNC, Vitamin Shoppe, and independent health food retailers service formulation-seeking consumers with practitioner-grade and practitioner-exclusive SKUs unavailable in mass channels.
- Direct Sales:Network marketing organizations (Herbalife, Amway) and clinician-dispensed models capture high-touch customers through personalized consultation, with compliance documentation supporting HSA/FSA reimbursement claims.
Online Retail has captured the dominant share of growth velocity; Direct Sales maintains the highest per-unit economics through relationship-based repeat purchase.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of high-purity EPA and DHA concentrates clusters in coastal processing hubs, while consumption spreads across pharmacy, nutraceutical, and cosmetics channels in major economies. This geographic split shapes trade flows and regulatory compliance burdens differently across markets.
Norway
Marine omega-3 refining dominates industrial activity, with Bergen and Alesund harboring specialized molecular distillation capacity for pharmaceutical-grade ethyl ester production. EMA pharmacopeial standards govern batch release protocols for export-bound concentrates. The country's omega-3 processing cluster supplies raw material to cardiovascular drug formulators across Europe.
United States
Prescription hypertriglyceridemia therapies drive demand for verified-sustainability omega-3 sourcing, with Medicare Advantage coverage expanding access to clinical-grade products. FDA 21 CFR 111 GMP rules structure supplement manufacturing compliance. Algae fermentation ventures in California and Massachusetts are scaling alternatives to marine oil dependency.
Germany
Lipid chemistry infrastructure supports high-concentrate omega-3 output for pharmaceutical applications, with REACH registration requirements filtering market participation. ECHA chemical dossier obligations impose six-figure compliance costs on novel lipid derivatives. BASF SE anchors production in Ludwigshafen and leverages integrated supply chains for API-grade material.
India
FSSAI nutraceutical labeling mandates are professionalizing supplement retail formats in urban pharmacy chains, opening branded omega-3 positioning. The country's central drug regulator enforces quality standards for imported concentrates. Contract manufacturers in Hyderabad and Ahmedabad are building softgel capacity to serve domestic and export markets.
Japan
Premium skincare brands specify carbon-chain-verified omega fatty acids for ceramide precursor applications, with METI standards shaping cosmetic ingredient disclosure. PMDA oversight applies to functional food and quasi-drug classifications containing EPA and DHA. Tokyo-based cosmetics laboratories drive specification tightening for dermatological barrier-repair formulations.
Essential Fatty Acids Market Vendor Landscape
The competitive structure tilts toward integrated chemical conglomerates with captive lipid processing infrastructure. Three to five multinational corporations control the bulk of high-purity concentrate capacity, while regional refiners and specialized fermentation ventures occupy niche positions. Strategic archetypes span marine oil refiners, algae biotechnology platforms, and oilseed processors with omega-6/omega-9 leverage. Dominant competitive moves include backward integration into raw material sourcing and technology licensing for fermentation-based production.
Within the integrated chemical conglomerate tier, BASF SE exemplifies European lipid chemistry capabilities, while DSM-Firmenich represents the algae-to-omega-3 fermentation archetype that reduces marine ecosystem dependency. Cargill Inc. anchors the oilseed-derived fatty acid segment through global crushing network control. These three occupy positions that reflect divergent upstream strategies—petrochemical synthesis, microbial fermentation, and agricultural commodity processing—each with distinct capital intensity and regulatory exposure profiles.
| Leading Market Players |
|---|
| BASF SE |
| DSM-Firmenich |
| Cargill Inc. |
| Croda International Plc |
| Aker BioMarine AS |
| Omega Protein Corporation |
| GC Rieber Oils AS |
| Arista Industries |
| Golden Omega |
| Others |
Supply Flow & Price Mechanics
Captive integration into Norwegian marine oil refining and German lipid chemistry infrastructure anchors both supply security and pricing power for pharmaceutical-grade EPA and DHA concentrates. Buyers face contract renegotiation cycles that track El Niño-driven anchovy catch volatility and algae fermentation capacity buildouts.
Pricing Analysis
Margin tightening in pharmaceutical-grade concentrates reflects EMA and FDA pharmacopeial standard convergence forcing dual-certification cost absorption. Three-tier pricing structure across pharmaceutical, nutraceutical, and food-grade certification levels separates batch release documentation intensity. Cost-down pressure on ethyl ester processors accelerates because algae fermentation platforms decouple supply from marine ecosystem volatility. Health-conscious consumers in subscription e-commerce channels exhibit highest price sensitivity; prescription hypertriglyceridemia patients through Medicare Advantage show lowest.
Supply Chain Analysis
Dual-sourcing qualification requirements from cardiovascular drug formulators mandate parallel marine and algal supply chain validation. Production gravity centers on Norway, Germany, and India for refining and softgel manufacturing. Raw material flows draw from Peruvian anchovy fisheries, heterotrophic fermentation bioreactors, and safflower oil crushing networks. Single-source vulnerability concentrates in Bergen and Alesund processing clusters. Distribution runs through pharmaceutical wholesalers, direct-to-consumer subscription platforms, and pharmacy retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algae-to-omega-3 fermentation is displacing marine oil refining as the upstream technology of record, compressing legacy ethyl ester processor margins while opening premium positioning for verified-sustainability supply chains.
For Market Incumbents: Deploy backward integration into heterotrophic fermentation capacity to offset marine raw material volatility. BASF SE and DSM-Firmenich demonstrate how captive bioreactor platforms reduce dependency on Peruvian anchovy catch fluctuations. Incumbents must simultaneously defend pharmaceutical-grade certification moats against emerging algae biotechnology ventures by consolidating quality control laboratories serving both FDA and EMA protocols. For New Entrants and Emerging Players: Prenatal DHA formulations for pharmacy retail in India represent the most penetrable white-space target. FSSAI labeling mandates professionalizing urban pharmacy chains create branded positioning opportunities unavailable to commodity bulk suppliers. New entrants should pursue white-label contract manufacturing for direct-to-consumer subscription brands seeking personalized EPA-to-DHA ratio configurations without dedicated production lines. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated chemical conglomerates seeking fermentation technology capabilities. Long-term viability hinges on algae biotechnology platforms achieving pharmaceutical-grade purity thresholds at scale. The signal to watch is EMA adoption of USP reference standards for fatty acid methyl ester analysis, which would accelerate regulatory harmonization and compress dual-certification cost burdens for unified facility operators.| Strategic Initiative | Industry Significance |
|---|---|
| Algae Fermentation Scale-Up | DSM-Firmenich platforms reduce marine ecosystem dependency for prescription drug applications. |
| Pharmacopeial Harmonization | EMA adoption of USP standards eliminates dual-testing overhead for Norwegian processors. |
| Modular Softgel Configuration | Variable EPA-to-DHA capsules enable personalized nutrition without dedicated production lines. |
| Indian Pharmacy Channel Entry | FSSAI mandates professionalize urban retail formats for branded omega-3 positioning. |
| Ceramide Precursor Certification | Chromatographic verification capabilities unlock premium French and Japanese skincare supply. |
Methodological Framework
Independent corroboration across molecular distillation plant managers, pharmaceutical procurement leads, nutraceutical brand managers, and algae biotechnology R&D directors underwrites the qualitative findings. Secondary validation draws from FDA Drug Master File submissions, EMA pharmacopeial monographs, FSSAI labeling guidelines, and customs trade data for fish oil and algal lipid derivatives. Bottom-up capacity modeling and top-down demand triangulation reconcile volume estimates across the analysis window.
Rate-of-change decomposition segments growth across omega-3, omega-6, omega-9, and conjugated linoleic acid product categories; pharmaceutical, nutraceutical, food and beverage, and cosmetics applications; and online retail, supermarket, specialty store, and direct sales channels. CAGRs derive from regression against historical production volumes, regulatory approval timelines, and reimbursement pathway expansion. Forecast inputs incorporate algae fermentation yield improvements and marine catch variability indices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EMA-FDA monograph divergence, El Niño frequency intensification, and algae biotechnology purity threshold achievement. Deviation in Peruvian anchovy biomass assessments or REACH registration burden escalation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food & Ingredients
Italy Protein Market
Functional Food & Ingredients
Functional Non-Meat Ingredients Market
Functional Food & Ingredients
Mediterranean Pre-Diabetes Ingredient Concepts Market
Functional Food & Ingredients
North America and Europe Medical Foods Market
Functional Food & Ingredients
Europe Botanical Extract Market
Functional Food & Ingredients
South America Prebiotic Ingredients Market
Functional Food & Ingredients
Protein Cookie Market
Functional Food & Ingredients
Poultry Probiotic Ingredients Market
Functional Food & Ingredients
Asia-Pacific Omega3 PUFA Market
Functional Food & Ingredients
Brominated Vegetable Oil Market
Functional Food & Ingredients
Prebiotic Ingredients Market
Functional Food & Ingredients
APAC Heart Health Functional Food Market
Functional Food & Ingredients
Europe Prebiotic Ingredient Market
Functional Food & Ingredients
Banana Leaf Extract Market
Functional Food & Ingredients
Omega 3 PUFA Market
Functional Food & Ingredients
Mediterranean Cognitive-First Ingredient Systems Market