
 Vegan DHA Market | 2026-2036
Vegan DHA Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan DHA Market Analysis
The gap between pharmaceutical-grade algal DHA and bulk commodity omega-3 is rebalancing as extraction purity standards diverge. Cargill Inc. leverages its agricultural supply chain to secure raw feedstock for fermentation-based DHA production. BASF SE anchors its position through specialized lipid concentration technologies that serve infant nutrition contracts. Koninklijke DSM N.V. dominates the high-purity segment with proprietary Schizochytrium strain platforms.
Vegan DHA comprises docosahexaenoic acid derived from microalgal fermentation, typically containing 35-55% DHA by weight in refined oil form, serving cognitive development and cardiovascular health applications. Algal oil leads product type revenue due to its direct incorporation into softgel supplements and infant formulas, while fortified foods represent the fastest-expanding application channel as beverage and dairy alternatives seek differentiation. Softgel and liquid forms command premium positioning in nutraceutical channels, whereas powder formats penetrate bulk functional food manufacturing where cost efficiency governs procurement.
FDA qualified health claims for omega-3 cardiovascular benefits shape US formulation decisions, while EFSA Novel Food approvals govern European market entry for new algal strains. EU Green Deal sustainability thresholds are forcing fermentation facilities to document carbon intensity across supply chains. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs fragment competitive positioning.
Market Dynamics
Fermentation-based DHA production is consolidating around proprietary strain platforms, creating a bifurcation between high-purity pharmaceutical-grade suppliers and commodity-grade bulk producers. This technical stratification is reshaping contract structures and margin pools across infant nutrition, supplements, and fortified foods.
Growth Catalysts
- EU Novel Food streamlining:The European Commission's 2023-2025 regulatory simplification for fermented biomass ingredients accelerates market entry for new algal DHA sources. German and Dutch infant formula manufacturers are expanding qualifying supplier lists.
- FDA-qualified health claims:The cardiovascular benefit framework for omega-3 fatty acids sustains formulation commitments from US supplement and functional food manufacturers seeking differentiated positioning.
- Plant-based infant nutrition:Dairy-alternative formula brands in North America and Western Europe are mandating algal DHA to match the nutritional profile of fish-oil-fortified conventional products.
Market Restraints
- Feedstock concentration:Glucose and yeast extract supply for fermentation runs through agricultural commodity markets vulnerable to corn and sugar price volatility in the US Midwest and Brazilian cane regions.
- Strain IP lock-in:Proprietary Schizochytrium and Crypthecodinium strain development remains concentrated among three established biotechnology licensors, limiting new entrant access to high-yield platforms.
- Fish oil substitution economics:Anchovy and sardine meal omega-3 from Peruvian and Chilean fisheries maintains cost advantages in pet food and aquafeed applications, capping algal DHA expansion in non-premium segments.
Strategic Opportunities
- India fortified foods mandate:The FSSAI's edible oils and dairy fortification directives create a compliance-driven demand channel for stable, vegetarian-certified DHA powder formats in mid-market consumer segments.
- Precision fermentation convergence:Integration of CRISPR-edited strains with continuous bioreactor design promises 40-60% yield improvements, potentially collapsing the cost gap with marine sources.
- Direct-to-consumer subscription channels:Supplement brands are bypassing retail pharmacy distribution through personalized nutrition platforms, capturing recurring revenue with higher-margin softgel and liquid formats.
Industry Challenges
- PhD-level fermentation scale-up:The talent pool for industrial bioprocess engineering at 100,000L+ bioreactor capacity remains thin relative to pharmaceutical and biofuel sector competition.
- Carbon accounting certification:EU Green Deal documentation requirements for Scope 3 emissions across glucose sourcing, fermentation energy, and downstream processing demand new data infrastructure investments.
- Algal oil oxidation stability:Extended shelf-life requirements in tropical distribution climates exceed current antioxidant formulation standards without flavor degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan DHA Market |
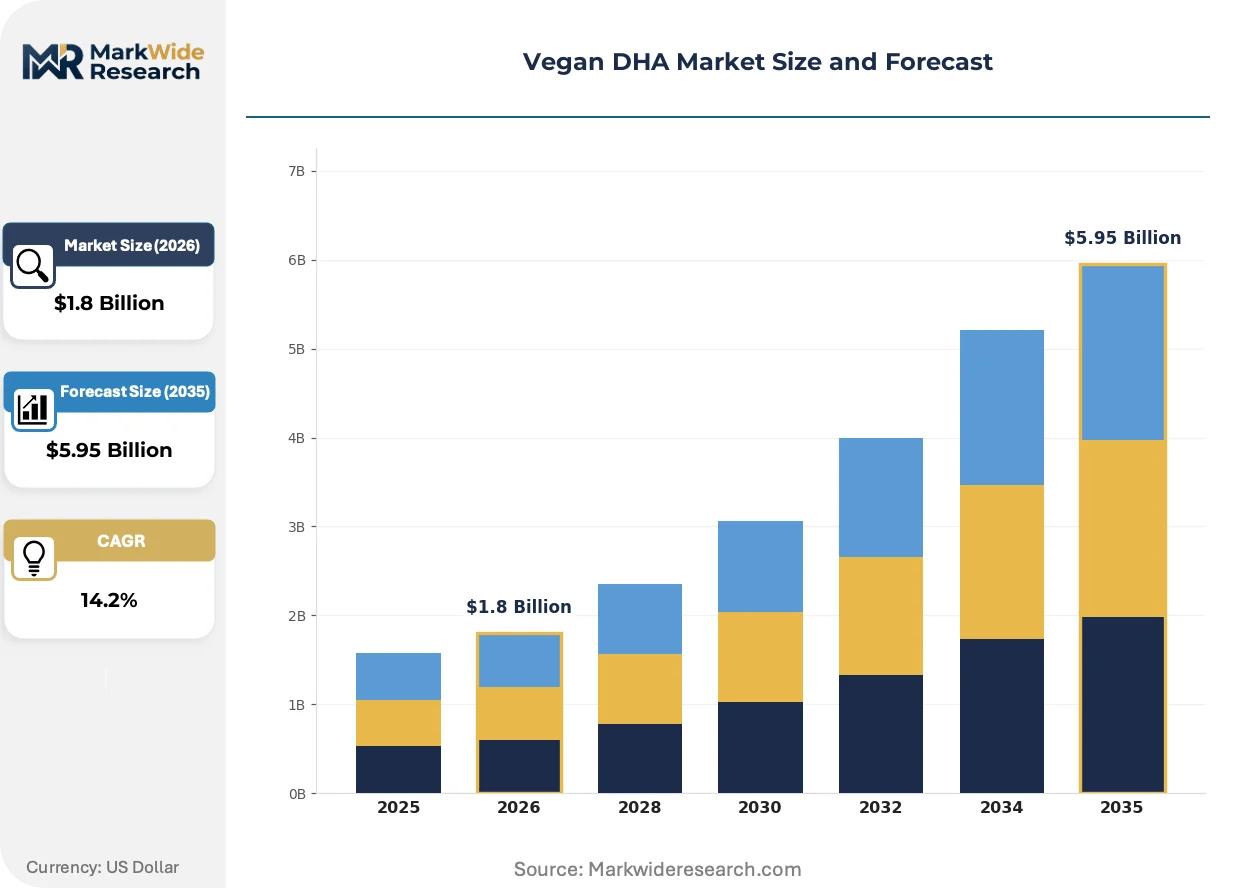
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Algal Oil, Microalgae, Supplements, Fortified Foods Form: Liquid, Softgel, Powder, Capsules Application: Dietary Supplements, Nutraceuticals, Infant Formulas, Functional Foods End User: Health-Conscious Consumers, Athletes, Vegetarians, Pregnant Women |
| Companies Covered | Cargill Inc., Arista Industries Inc., Croda International Plc., BASF SE, Koninklijke DSM N.V., Algaecytes Limited, Hero Nutritionals Inc., Roquette, Corbion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan DHA Market Emerging Trajectories
Bioprocess intensification and regulatory data infrastructure are converging to compress production economics while fragmenting competitive positioning between purity tiers and geographic supply bases.
Continuous perfusion fermentation systems are modularizing algal DHA manufacturing, replacing conventional batch processing with steady-state biomass harvesting. Contract manufacturers serving mid-tier supplement brands are adopting 10,000-50,000L single-use bioreactor trains to reduce capital intensity and contamination risk. This technology is modularizing the supply base, enabling regional production nodes that bypass centralized pharmaceutical-grade facilities.
EFSA's 2024 updated guidance on novel food safety dossiers for microbial biomass tightens toxicological data requirements while creating expedited pathways for strains with established history of use. The industrial consequence is a documentation burden favoring incumbent strain holders over new entrants. Infant formula applications in the EU are most affected, with manufacturers consolidating approved supplier lists ahead of 2025-2026 contract renewals.
Long-term offtake agreements are displacing spot purchasing in North American supplement channels, with brands committing 24-36 month volumes to secure allocation from high-purity fermentation facilities. Direct sourcing relationships are replacing distributor intermediaries for top-20 supplement brands. This pattern is most visible in the US, where FDA-qualified health claim maintenance requires consistent DHA potency documentation across production lots.
Vegan DHA Market Segmentation
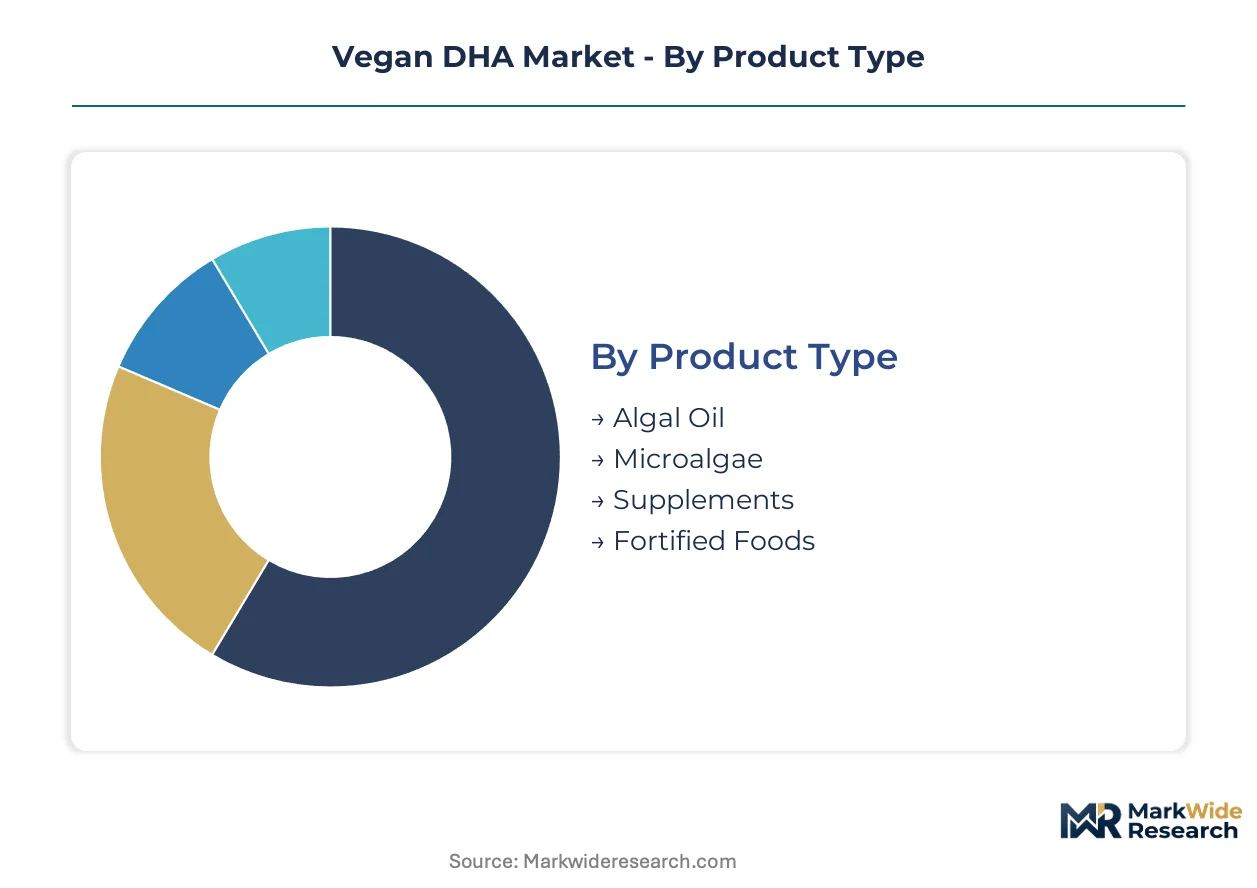
Vegan DHA segmentation reflects divergent certification burdens across infant nutrition and supplement channels. FDA-qualified health claims, EFSA Novel Food approvals, and FSSAI fortification mandates each favor distinct product formats and purity tiers.
Product Type:
EFSA Novel Food dossiers for fermented biomass ingredients impose the heaviest documentation burden on algal oil and microalgae segments, while fortified foods navigate simpler additive approval pathways.
- Algal Oil:Refined oil containing 35-55% DHA by weight serves softgel supplements and infant formulas. German and Dutch manufacturers are expanding qualifying supplier lists as EU regulatory simplification accelerates.
- Microalgae:Whole biomass formats with lower concentration but broader nutrient profiles penetrate functional food applications. India's FSSAI edible oils fortification directive creates compliance-driven demand for stable vegetarian-certified powder formats.
- Supplements:Finished dosage forms concentrate in US direct-to-consumer channels where FDA cardiovascular health claim maintenance requires consistent potency documentation.
- Fortified Foods:Beverage and dairy alternatives seek differentiation through algal DHA integration, representing the steepest expansion trajectory as plant-based positioning intensifies.
Leading the category by volume: Algal Oil. Growing fastest: Fortified Foods.
Form:
Cost tiers separate pharmaceutical-grade fermentation outputs from commodity manufacturing, with softgel and liquid formats commanding premium positioning against powder's bulk functional food penetration.
- Liquid:Direct incorporation into infant formulas and functional beverages. US supplement brands capture recurring subscription revenue with higher-margin liquid formats bypassing retail pharmacy distribution.
- Softgel:Encapsulated oil dominates nutraceutical channels. Long-term offtake agreements displace spot purchasing as top-20 brands commit 24-36 month volumes to secure high-purity allocation.
- Powder:Bulk functional food manufacturing favors cost efficiency. Tropical distribution climates challenge oxidation stability without flavor degradation.
- Capsules:Standardized dosing for health-conscious consumers and athletes. Contract manufacturers adopt single-use bioreactor trains to reduce capital intensity for mid-tier brands.
Softgel and liquid formats anchor premium revenue. Powder scales fastest in emerging market fortification programs.
Application:
Customer type determines regulatory exposure, with infant formulas facing the most stringent toxicological data requirements under EFSA's updated guidance.
- Dietary Supplements:Softgel and liquid formats dominate. US brands leverage FDA-qualified health claims for cardiovascular positioning.
- Nutraceuticals:Precision fermentation convergence with CRISPR-edited strains promises yield improvements collapsing cost gaps with marine sources.
- Infant Formulas:Algal DHA mandates from dairy-alternative brands in North America and Western Europe match fish-oil-fortified conventional product profiles. EU manufacturers consolidate approved supplier lists ahead of contract renewals.
- Functional Foods:Beverage and dairy alternatives drive fastest expansion as differentiation intensifies. Continuous perfusion fermentation systems enable regional production nodes bypassing centralized facilities.
Infant formulas command highest purity premiums. Functional foods gain share fastest through plant-based positioning.
End User:
Application context reshapes procurement, with pregnant women and infant nutrition segments demanding pharmaceutical-grade documentation while athletes and vegetarians accept broader quality tiers.
- Health-Conscious Consumers:General wellness positioning in supplements and fortified foods. Direct-to-consumer subscription channels displace traditional retail.
- Athletes:Performance-focused formulations favor higher-concentration algal oil. Recovery and cognitive support claims differentiate positioning.
- Vegetarians:Ethical and dietary compliance drives algal DHA preference over fish oil. Certification requirements vary by export market.
- Pregnant Women:Cognitive development claims for fetal and maternal health command strictest purity standards. EFSA and FDA documentation requirements govern formulation decisions.
Pregnant women and infant-linked segments drive premium tier demand. Health-conscious consumers scale fastest through subscription channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam anchors European algal DHA distribution through its specialized lipid handling infrastructure, while US demand concentrates around FDA-qualified health claim jurisdictions. German and Dutch infant formula manufacturers are expanding fermentation-based supplier networks as regulatory pathways simplify.
United States
Supplement brands leverage FDA-qualified cardiovascular health claims to differentiate softgel and liquid formulations. The agency's omega-3 fatty acid claim framework sustains long-term offtake commitments from direct-to-consumer subscription channels. Chicago and New Jersey corridor facilities handle high-purity fermentation outputs for top-20 nutraceutical brands.
Germany
Infant formula manufacturers in Bavaria and North Rhine-Westphalia are qualifying new algal DHA suppliers ahead of 2025-2026 contract renewals. EFSA Novel Food streamlining for fermented biomass accelerates dossier approvals for proprietary Schizochytrium strains. Frankfurt-Rhine-Main logistics clusters manage refined oil distribution across EU member states.
Netherlands
Dairy-alternative formula brands mandate algal DHA to match fish-oil-fortified conventional product profiles. EU Green Deal carbon accounting requirements force fermentation facilities to document Scope 3 emissions across glucose sourcing and energy inputs. Wageningen biotech corridor hosts strain development and continuous perfusion system pilots.
India
FSSAI edible oils and dairy fortification directives create compliance-driven demand for stable vegetarian-certified DHA powder formats. Mid-market consumer segments in Maharashtra and Gujarat drive procurement of bulk functional food ingredients. Mumbai-Pune industrial belt contract manufacturers adopt single-use bioreactor trains for regional production.
China
SAMR novel food approvals govern market entry for imported algal oil and domestic fermentation outputs. Precision fermentation convergence with CRISPR-edited strains targets yield improvements to collapse cost gaps with Peruvian anchovy sources. Yangtze River Delta bioprocess facilities scale 10,000-50,000L modular systems for supplement and infant nutrition contracts.
Vegan DHA Market Vendor Landscape
Premium-margin players sit above commodity-margin players across purity certification and strain IP dimensions. The supplier base stratifies between pharmaceutical-grade fermentation specialists and bulk commodity processors serving functional food channels. Three archetypes dominate: proprietary strain licensors, agricultural supply chain integrators, and precision fermentation technology developers. Capacity expansion and long-term offtake agreements represent the dominant competitive moves as brands secure allocation ahead of contract renewals.
Within the proprietary strain tier, Koninklijke DSM N.V. and BASF SE occupy positions anchored by specialized lipid concentration technologies and established EFSA approval dossiers. Cargill Inc. represents agricultural supply chain integration, leveraging feedstock security for fermentation-based production economics. These three exemplify the bifurcation between high-purity pharmaceutical-grade positioning and commodity-scale bulk manufacturing.
| Leading Market Players |
|---|
| Cargill Inc. |
| Arista Industries Inc. |
| Croda International Plc. |
| BASF SE |
| Koninklijke DSM N.V. |
| Algaecytes Limited |
| Hero Nutritionals Inc. |
| Roquette |
| Corbion |
| Others |
Supply Flow & Price Mechanics
Infant formula manufacturers in Germany and the Netherlands anchor demand concentration for pharmaceutical-grade algal DHA, locking in long-term offtake agreements that favor contract-based pricing over spot market exposure. This buyer archetype concentration sustains premium tier stability while mid-tier supplement brands face intensifying cost compression.
Pricing Analysis
Value-based pricing anchored to cardiovascular health claim maintenance and infant nutrition certification tiers stratifies the market across three levels. Pharmaceutical-grade fermentation outputs command sustained premiums through EFSA Novel Food dossier completion and FDA-qualified claim documentation, while commodity-grade bulk algal oil faces erosion from fish oil substitution economics in pet food and aquafeed channels. Price differentiation rests on purity certification and strain IP licensing status, with contract manufacturers absorbing margin pressure through single-use bioreactor adoption. Health-conscious consumers in direct-to-consumer channels exhibit lowest price sensitivity, whereas bulk functional food manufacturers in emerging markets drive procurement toward powder formats.
Supply Chain Analysis
Single-source vulnerability sits with glucose and yeast extract feedstock originating from US Midwest corn and Brazilian cane regions, exposing fermentation economics to agricultural commodity volatility. Manufacturing capacity concentrates in the Netherlands, Germany, and the United States, with Rotterdam's lipid handling infrastructure anchoring European distribution. Raw material dependencies include fermentation-grade glucose, nitrogen-rich yeast extracts, and specialized antioxidant formulations for oxidation stability. Tariff exposure on imported algal oil into China under SAMR novel food frameworks compounds supply chain risk. Distribution runs through direct sourcing relationships displacing distributor intermediaries for top-tier supplement brands, with regional production nodes emerging through modular perfusion system deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into proprietary strain platforms and captive glucose sourcing represents the dominant competitive race, as fermentation economics hinge on feedstock security and yield optimization. Players are pursuing upstream control over agricultural commodity inputs to defend margin structures against volatile corn and sugar markets.
For Market Incumbents: Cement market position through exclusive long-term offtake agreements with infant formula manufacturers ahead of contract renewal cycles, while deepening backward integration into glucose supply chains to neutralize agricultural commodity volatility. Invest in CRISPR-edited strain development to preempt precision fermentation disruption from emerging biotechnology entrants. Prioritize EFSA dossier maintenance for Novel Food approval continuity. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription channels targeting health-conscious consumers and pregnant women with differentiated liquid and softgel formats, bypassing retail pharmacy distribution concentration. Penetrate India's FSSAI-mandated fortification programs with stable vegetarian-certified DHA powder formats for edible oils and dairy applications. Exploit modular single-use bioreactor technology to establish regional production nodes without centralized facility capital intensity. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision fermentation technology developers with CRISPR-edited strain platforms in China and India, where yield improvement trajectories promise cost parity with marine omega-3 sources. Acquisition targets should demonstrate scalable continuous perfusion capabilities and established regulatory approval dossiers. Watch for SAMR novel food approval acceleration as the inflection signal for Chinese market entry viability.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Strain Platform Acquisition | Secures EFSA Novel Food dossier continuity for infant formula contracts in Germany and the Netherlands. |
| Backward Integration into Feedstock | Captive glucose sourcing from US Midwest agricultural networks insulates fermentation margins from commodity volatility. |
| Continuous Perfusion System Deployment | Modular bioreactor trains enable regional production nodes serving mid-tier supplement brands in India and China. |
| Direct-to-Consumer Channel Launch | Subscription platforms bypass retail pharmacy concentration while capturing recurring revenue from health-conscious segments. |
| EFSA Dossier Maintenance Investment | Updated toxicological data packages preserve approved supplier status for EU infant formula contract renewals. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across fermentation plant managers, infant formula procurement leads, supplement brand R&D directors, and regulatory affairs specialists at biotechnology licensors. Bottom-up triangulation validated top-down market sizing through cross-referencing EFSA Novel Food approval databases, FDA qualified health claim documentation, and FSSAI fortification compliance records with customs trade flows and company capacity disclosures.
Segment-level granularity modeled product type, application, form, and end user dimensions with regional regulatory cluster differentiation across the projection horizon. CAGRs derived from trend extrapolation of infant formula contract volumes, supplement subscription growth patterns, and fortified food penetration rates in compliance-driven markets. Industry-specific forecast inputs incorporated fermentation yield improvement trajectories from precision biotechnology pilots and EU Green Deal carbon accounting documentation requirements.
Regulatory approval delays, agricultural commodity price spikes, and precision fermentation yield shortfalls are the dominant revision risks to the outlook. Deviation in EFSA Novel Food streamlining implementation would shift competitive positioning materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food & Ingredients
Mediterranean Cognitive-First Ingredient Systems Market
Functional Food & Ingredients
Prebiotic Ingredients Market
Functional Food & Ingredients
Beta Glucan and Fucoidan Market
Functional Food & Ingredients
Africa Omega-3 PUFA Market
Functional Food & Ingredients
Functional Ingredients Market
Functional Food & Ingredients
South America Prebiotic Ingredients Market
Functional Food & Ingredients
Functional Non-Meat Ingredients Market
Functional Food & Ingredients
Asia-Pacific Omega3 PUFA Market
Functional Food & Ingredients
Omega 3 PUFA Market
Functional Food & Ingredients
Europe Sterol Market
Functional Food & Ingredients
North America Pea Protein Ingredients Market
Functional Food & Ingredients
Sacha Inchi Protein Market
Functional Food & Ingredients
Mediterranean Pre-Diabetes Ingredient Concepts Market
Functional Food & Ingredients
Global Probiotic Ingredients Market
Functional Food & Ingredients
Brazil Flavored and Functional Water Market
Functional Food & Ingredients
Healthy Fats Low Carb Market