
 Europe Botanical Extract Market | 2026-2036
Europe Botanical Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Botanical Extract Market Foresight
Buyer concentration among European pharmaceutical and nutraceutical formulators is recalibrating procurement strategies across the botanical extract value chain. Martin Bauer GmbH & Co KG anchors its position through backward integration into raw material sourcing from controlled cultivation partnerships. Symrise differentiates via specialized extraction technologies serving premium personal care accounts. Givaudan leverages its flavor science heritage to compete in food-grade botanical applications with complex organoleptic profiles.
Botanical extracts comprise concentrated bioactive compounds derived from plant matrices through mechanical, thermal, or solvent-based separation processes, standardized to specified marker compound percentages for reproducible efficacy in downstream formulations. Steam distillation and CO2 extraction methods dominate premium essential oil production due to superior terpene preservation and solvent-free certification status. The pharmaceuticals application segment leads value capture due to stringent pharmacopeial compliance requirements and prescription-grade validation protocols, while dietary supplements represent the fastest-expanding channel as self-directed wellness consumption accelerates across Nordic and Germanic markets.
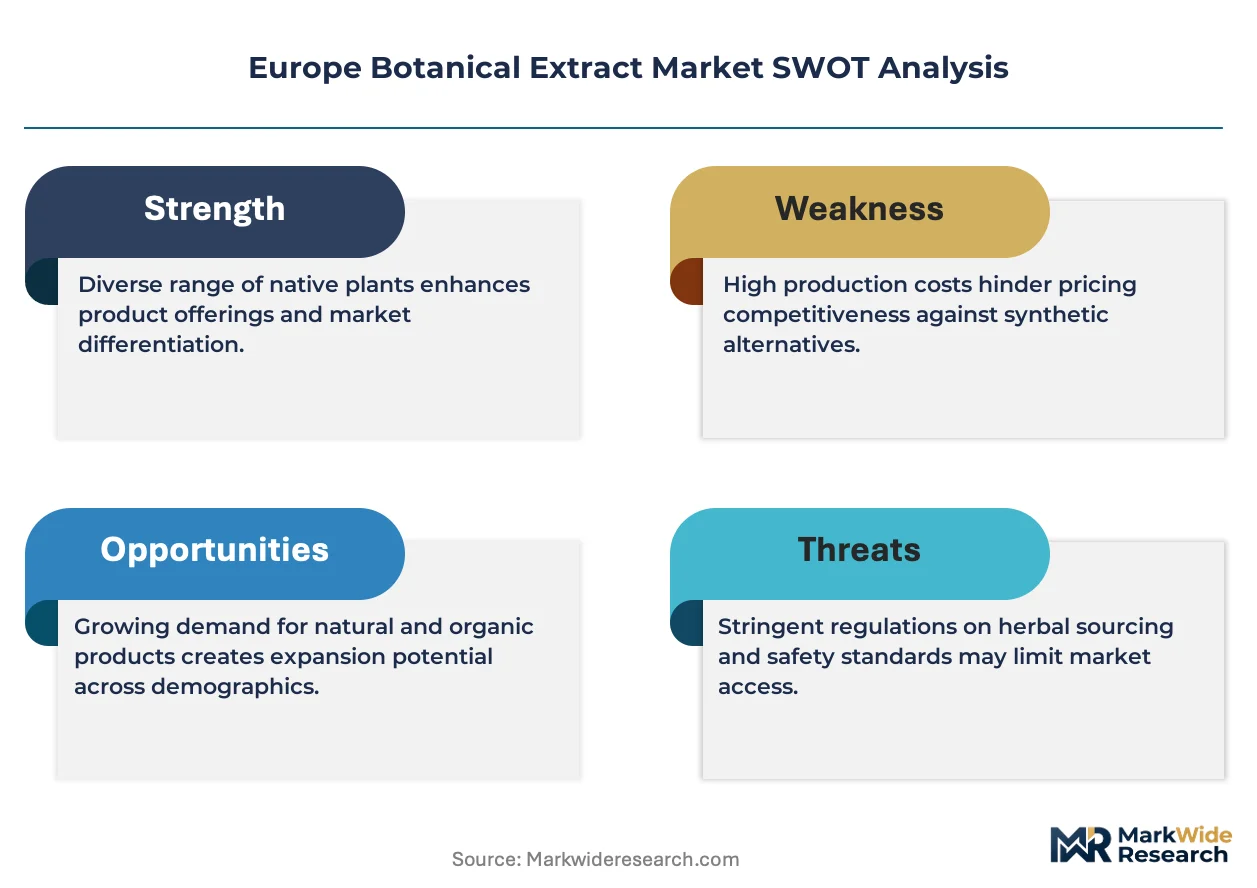
EMA pharmacovigilance guidelines and REACH chemical registration mandates govern extract purity thresholds and novel substance authorization pathways for European suppliers. EFSA Novel Food regulations constrain market access for non-traditional botanical sources, creating compliance moats around established ingredient portfolios. Stakeholders must monitor evolving ECHA substance evaluation schedules and adapt extraction method documentation to preempt regulatory reclassification risks.
Market Dynamics
Pharmaceutical manufacturers across Germany and France are consolidating procurement around standardized herbal extracts, compressing supplier margins while elevating pharmacopeial compliance requirements as the dominant market-shaping force.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Tightening pesticide residue thresholds and traceability mandates for botanical raw materials is accelerating investment in controlled cultivation partnerships across Mediterranean zones.
- Self-directed wellness consumption:Nordic and Germanic markets are expanding dietary supplement channels faster than pharmaceutical applications, pulling extract volumes toward consumer-grade formulations.
- CO2 extraction technology:Superior terpene preservation and solvent-free certification status is displacing conventional solvent methods in premium essential oil production.
Market Restraints
- Input cost volatility:Climate-induced harvest variability in rosemary and olive leaf cultivation zones creates raw material price instability for Mediterranean suppliers.
- Supply concentration risk:Premium citrus-derived extract production clusters in Spanish and Italian growing regions, exposing buyers to regional weather disruptions and logistics bottlenecks.
- EFSA Novel Food regulatory friction:Non-traditional botanical sources face extended authorization pathways, freezing market access for innovative ingredient portfolios.
Strategic Opportunities
- Underpenetrated Eastern European markets:Poland and Romania exhibit nascent nutraceutical formulator bases with limited local extract sourcing infrastructure.
- Personal care application expansion:Premium cosmetic brands are specifying complex organoleptic profiles for botanical actives, opening formulation partnerships beyond traditional pharmaceutical accounts.
- EMA pharmacovigilance guideline alignment:Early compliance with evolving purity threshold documentation creates competitive moats against later entrants.
Industry Challenges
- Analytical chemist talent scarcity:Marker compound standardization and pharmacopeial validation protocols require specialized expertise that outpaces European university pipeline output.
- Extraction equipment capex intensity:Supercritical CO2 systems demand significant capital deployment, constraining mid-scale processors from capacity expansion.
- REACH substance evaluation timeline compression:ECHA reclassification schedules force rapid extraction method documentation updates, straining regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Botanical Extract Market |
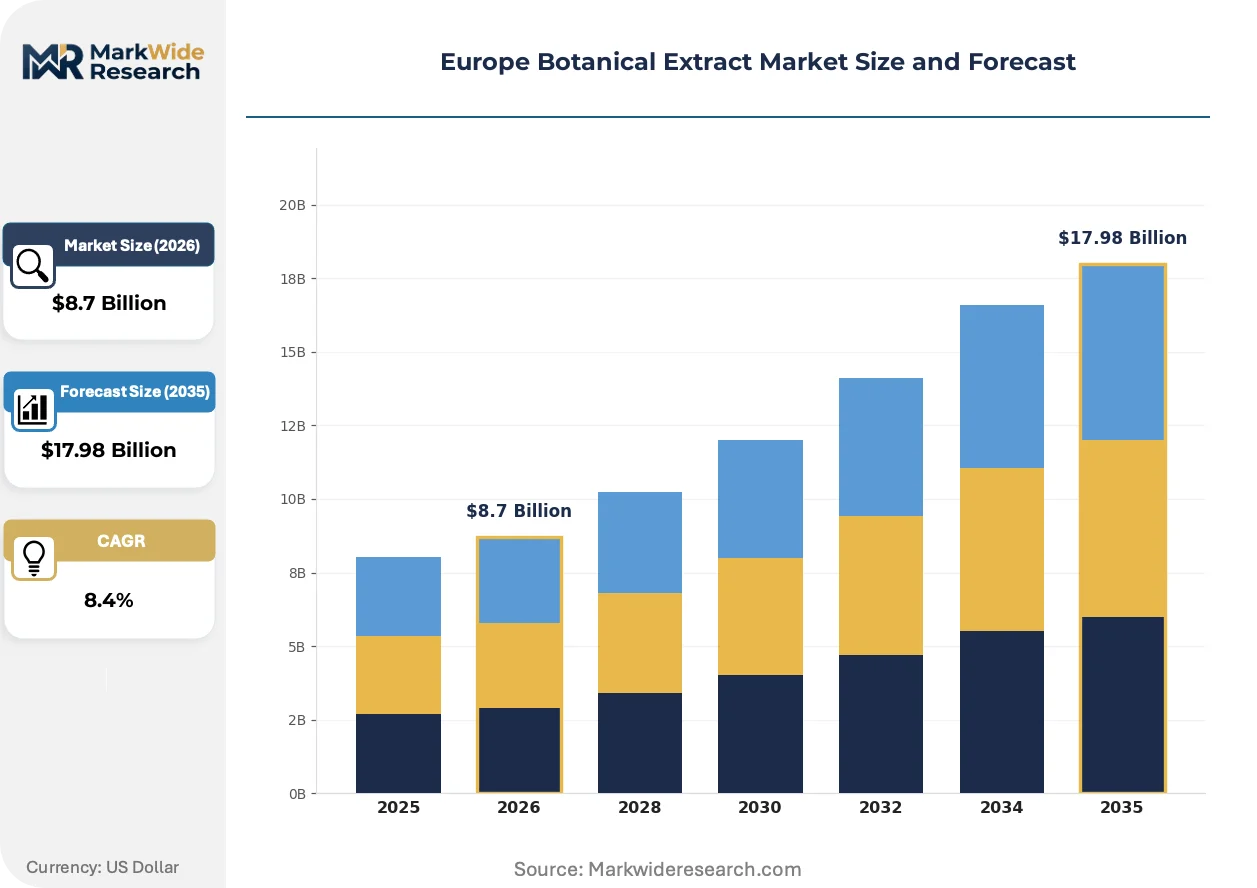
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal, Essential Oils, Tinctures, Powders Application: Pharmaceuticals, Dietary Supplements, Personal Care, Food & Beverage End User: Manufacturers, Distributors, Retailers, Consumers Extraction Method: Steam Distillation, Solvent Extraction, Cold Pressing, CO2 Extraction |
| Companies Covered | Martin Bauer GmbH & Co KG, Symrise, Givaudan, DSM, Döhler, Van Eeghen Functional Ingredients, GreenHerb Europe, NaturExtracts France, Blue Sky Botanics Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Botanical Extract Market Shifts & Advancements
Supercritical fluid extraction platforms are converging with artificial intelligence-driven process optimization, compressing batch-to-batch variability while pharmaceutical and nutraceutical formulators demand reproducible bioactive standardization.
AI-enabled extraction parameter tuning is converging with real-time chromatographic feedback systems to enable dynamic solvent flow adjustments. German pharmaceutical contract manufacturers are piloting these integrated platforms for marker compound precision. This convergence is compressing quality control cycles from weeks to hours, enabling just-in-time extract release protocols.
REACH chemical registration mandates are tightening substance evaluation schedules for botanical extracts with novel solvent residues or modified molecular profiles. Industrial consequence includes mandatory extraction method re-documentation and preemptive regulatory dossier preparation. Pharmaceutical-grade suppliers in France and Germany are responding by consolidating analytical testing partnerships to accelerate compliance turnaround.
Certification-driven procurement preferences are displacing price-primary sourcing criteria among Nordic dietary supplement distributors. Clean-label and organic certification schemes now gate distributor shelf access, compressing conventional extract volumes. This shift is most visible in Swedish and Danish markets, where retailer private-label specifications mandate third-party sustainability verification.
Europe Botanical Extract Market Segmentation
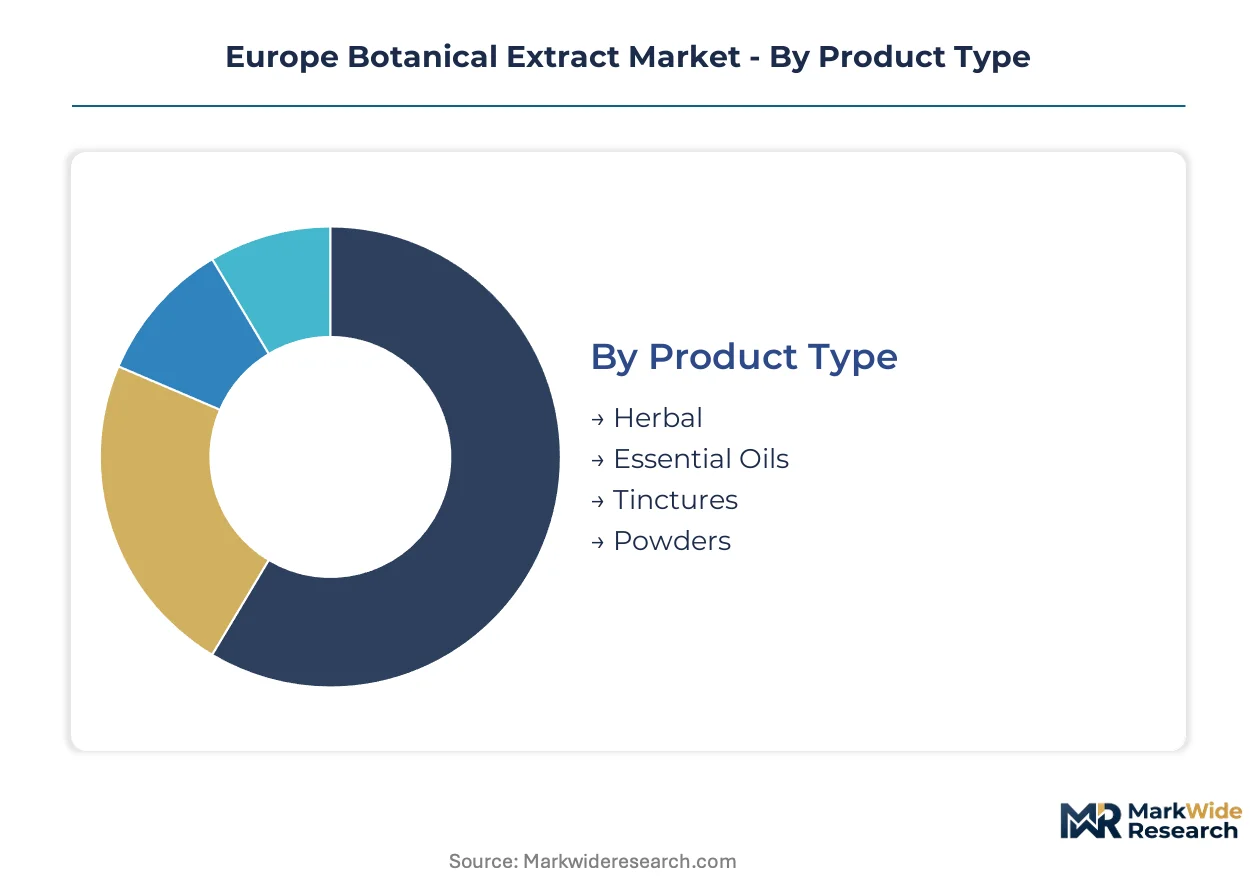
Certification requirements fragment procurement strategies across the Europe Botanical Extract Market, with pharmacopeial-grade segments demanding EMA validation while consumer-grade categories navigate EFSA Novel Food pathways. Segmentation discipline separates margin-rich pharmaceutical applications from volume-driven dietary supplement channels, each carrying distinct regulatory documentation burdens and analytical testing protocols.
Product Type:
EMA pharmacopeial compliance burdens concentrate heaviest on standardized herbal preparations, while EFSA Novel Food authorization gates non-traditional essential oil introductions into food-grade applications.
- Herbal:Standardized dry extracts and fluid extracts contain specified marker compound percentages validated against European Pharmacopoeia monographs. German pharmaceutical contract manufacturers dominate procurement of valerian root and St. John's Wort standardized preparations for prescription formulations, driven by reimbursement eligibility requirements.
- Essential Oils:Terpene-rich volatile fractions require solvent-free certification for organic labeling claims, with CO2-extracted rosemary and lavender oils commanding premium positioning in French aromatherapy and personal care channels. Spanish Mediterranean cultivation zones supply bulk volumes to flavor houses.
- Tinctures:Hydroalcoholic preparations face ethanol content labeling restrictions under EU food law when crossing into supplement applications.
- Powders:Spray-dried and freeze-dried formats serve encapsulation equipment in Polish and Romanian contract manufacturing facilities.
Herbal extracts sit at the top of the volume ranking, with essential oils climbing the fastest as clean-label personal care brands specify complex organoleptic profiles.
Application:
Margin structures diverge sharply across application tiers, with pharmaceutical-grade validation protocols extracting 3-4x analytical testing costs versus consumer-grade supplement channels.
- Pharmaceuticals:Prescription-grade botanicals require full EMA marketing authorization or traditional use registration under Directive 2004/24/EC, with German and French manufacturers consolidating procurement around controlled cultivation partnerships to secure batch-to-batch reproducibility for active pharmaceutical ingredient formulations.
- Dietary Supplements:Self-directed wellness consumption accelerates across Nordic markets, with Swedish and Danish distributors mandating third-party organic and sustainability verification as shelf-access preconditions, compressing conventional extract volumes.
- Personal Care:Premium cosmetic brands specify terpene preservation thresholds for botanical actives, opening formulation partnerships with CO2 extraction specialists.
- Food & Beverage:EFSA Novel Food regulations constrain innovative botanical introductions, freezing market access for non-traditional sources.
Dietary supplements command the steepest expansion trajectory, though pharmaceuticals retain the highest value capture per kilogram extracted.
End User:
Procurement sophistication stratifies sharply, with manufacturers demanding pharmacopeial certificates of analysis while retailers specify sustainability verification schemes.
- Manufacturers:Pharmaceutical and nutraceutical formulators in Germany, France, and Switzerland consolidate supplier bases around backward-integrated processors capable of marker compound standardization and REACH-compliant documentation.
- Distributors:Nordic supplement distributors have displaced price-primary sourcing with certification-driven procurement, mandating organic and clean-label verification.
- Retailers:Private-label specifications in Swedish and Danish markets require third-party sustainability verification, compressing conventional extract shelf space.
- Consumers:Direct-to-channel purchases concentrate in aromatherapy and wellness tincture categories with minimal regulatory friction.
Manufacturers absorb the dominant procurement volume, with distributors gaining intermediation power fastest through certification gatekeeping.
Extraction Method:
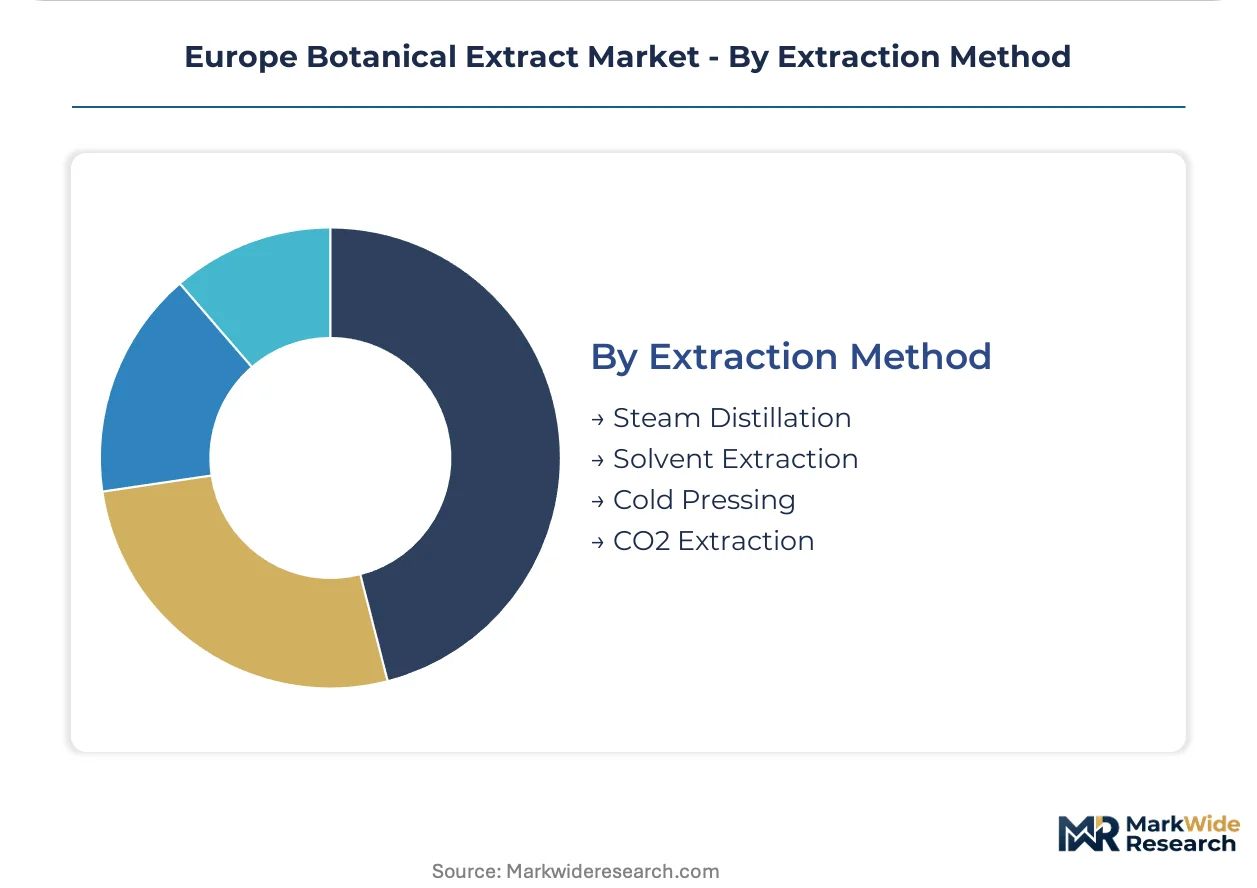
Capital intensity and certification eligibility separate extraction tiers, with supercritical CO2 systems demanding significant deployment constraints on mid-scale processors.
- Steam Distillation:Thermal separation of volatile fractions dominates essential oil production for fragrance applications, with terpene degradation risks limiting pharmaceutical-grade suitability.
- Solvent Extraction:Ethanol and hexane methods face REACH substance evaluation pressures for residual solvent thresholds, forcing method re-documentation.
- Cold Pressing:Mechanical expression preserves heat-sensitive compounds in citrus peel and olive fruit applications, concentrated in Spanish and Italian processing facilities.
- CO2 Extraction:Supercritical fluid platforms deliver solvent-free certification status and superior terpene preservation for premium essential oil and pharmaceutical-grade applications, with German contract manufacturers piloting AI-enabled process optimization to compress batch-to-batch variability.
Solvent extraction retains the largest installed base, with CO2 methods gaining share fastest on certification premiums and pharmacopeial acceptance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and France dominate pharmaceutical-grade procurement, while Mediterranean cultivation zones in Spain and Italy supply premium raw materials with distinct regulatory and climatic advantages.
Germany
Pharmaceutical contract manufacturers in Bavaria and North Rhine-Westphalia consolidate procurement around standardized valerian root and St. John's Wort extracts for prescription formulations. EMA pharmacovigilance guidelines enforce stringent purity thresholds, elevating compliance costs for active pharmaceutical ingredient suppliers. The Hamburg and Frankfurt clusters host backward-integrated processors capable of marker compound standardization and REACH-compliant documentation.
France
Aromatherapy and personal care brands in Provence-Alpes-Côte d'Azur specify terpene preservation thresholds for lavender and rosemary essential oils. ANSM enforces national pharmaceutical safety standards alongside EU-wide EMA directives. Grasse and the surrounding Mediterranean cultivation zones supply CO2-extracted oils to premium cosmetic formulators.
Italy
Cold-pressed citrus peel extract production concentrates in Sicilian and Calabrian growing regions, serving flavor houses and food-grade applications. EFSA Novel Food regulations constrain innovative botanical introductions, freezing market access for non-traditional sources. The Naples and Reggio Calabria processing corridors face climate-induced harvest variability risks.
Spain
Olive leaf and rosemary cultivation in Andalusian and Catalonian zones supplies bulk volumes to European extractors. The EU Green Deal's Farm to Fork Strategy tightens pesticide residue thresholds and traceability mandates for botanical raw materials. Seville and Barcelona host mid-scale processors investing in controlled cultivation partnerships.
Sweden
Dietary supplement distributors in Stockholm and Malmö mandate third-party organic and sustainability verification as shelf-access preconditions. Swedish Medical Products Agency regulations align with EMA guidelines for pharmacovigilance reporting. The Nordic market's certification-driven procurement compresses conventional extract volumes while accelerating clean-label segment growth.
Europe Botanical Extract Market Competitive Landscape
Mediterranean cultivators anchor the raw material tier; German and Swiss processors hold the standardized extraction tier. The vendor base stratifies across three tiers: large-scale flavor and fragrance houses with integrated supply chains, mid-cap specialists with backward integration into controlled cultivation, and regional processors serving local pharmaceutical accounts. Two dominant competitive moves define current positioning: consolidation around controlled cultivation partnerships to secure batch-to-batch reproducibility, and technology licensing for supercritical CO2 extraction platforms to capture certification premiums.
Within the backward-integrated processor tier, Martin Bauer GmbH & Co KG exemplifies the German archetype of pharmaceutical-grade standardization capability. Symrise and Givaudan occupy positions among the flavor and fragrance houses diversifying into botanical actives for personal care and food applications. These three entities represent distinct strategic postures—controlled cultivation anchoring, extraction technology specialization, and organoleptic science heritage—rather than directly comparable market positions.
| Leading Market Players |
|---|
| Martin Bauer GmbH & Co KG |
| Symrise |
| Givaudan |
| DSM |
| Döhler |
| Van Eeghen Functional Ingredients |
| GreenHerb Europe |
| NaturExtracts France |
| Blue Sky Botanics Ltd |
| Others |
Supply & Pricing Matrix
Pharmaceutical procurement consolidation across Germany and France is compressing supplier margins and forcing Mediterranean cultivators to absorb compliance cost escalation for EMA pharmacopeial documentation.
Pricing Analysis
Capacity additions in Spanish and Italian CO2 extraction facilities are reshaping price floors for premium essential oil tiers. Three-tier pricing structure across premium, standard, and economy levels separates pharmacopeial-grade certified extracts from organic-labeled consumer grades and conventional uncertified volumes. Price differentiation hinges on EMA validation status and REACH-compliant solvent residue documentation. Cost compression in standard tiers is intensifying because German pharmaceutical contract manufacturers are consolidating supplier bases around backward-integrated processors. Dietary supplement distributors in Nordic markets exhibit lowest price sensitivity due to certification-driven procurement mandates.
Supply Chain Analysis
Return flows of non-conforming botanical raw materials for reprocessing or disposal create reverse-logistics complexity for Mediterranean processors managing EU Green Deal traceability audits. Supply concentrates in Spain, Italy, and Greece for rosemary, olive leaf, and citrus peel feedstocks. Raw material dependencies rest on climate-advantaged cultivation zones, pesticide-free certification attainment, and seasonal harvest labor pools. Single-source vulnerability from Andalusian weather disruptions threatens bulk volume commitments to flavor houses. Distribution runs through controlled cultivation partnerships for pharmaceutical-grade tiers and spot-market procurement for conventional supplement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between EMA pharmacopeial compliance costs in Western Europe and nascent EFSA Novel Food pathway efficiency in Eastern European markets creates geographic repositioning incentives for extract processors.
For Market Incumbents: Extend controlled cultivation partnerships into Romanian and Polish growing zones to preempt input cost volatility from Mediterranean climate exposure. Consolidate analytical testing partnerships in Hamburg and Frankfurt clusters to accelerate REACH substance evaluation turnaround. Certification investment in dual organic-pharmacopeial status defends margin position against mid-scale CO2 extraction specialists capturing premium personal care accounts. For New Entrants and Emerging Players: Capture underpenetrated Eastern European nutraceutical formulator demand in Warsaw and Bucharest contract manufacturing corridors. White-space availability concentrates in spray-dried powder formats for encapsulation equipment serving Polish supplement distributors. Go-to-market execution should leverage EFSA Novel Food authorization expertise to bypass EMA compliance moats blocking innovative botanical introductions. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale processors possessing backward-integrated Mediterranean cultivation assets and supercritical CO2 platform technology licensing. Long-term viability through the next decade favors acquisition targets with dual certification capability spanning organic and pharmacopeial grades. Monitor ECHA substance evaluation schedule compression for early signals of regulatory affairs bandwidth strain forcing distressed divestitures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Controlled Cultivation | Secures batch-to-batch reproducibility for EMA pharmacopeial compliance in German pharmaceutical supply chains. |
| CO2 Extraction Platform Licensing | Captures certification premiums from French aromatherapy brands specifying terpene preservation thresholds. |
| EFSA Novel Food Authorization Investment | Unlocks market access for non-traditional botanical sources blocked by regulatory friction in food-grade applications. |
| AI-Enabled Process Optimization Deployment | Compresses quality control cycles from weeks to hours for just-in-time extract release protocols. |
| Eastern European Distribution Partnership | Establishes shelf-access foothold in Warsaw and Bucharest supplement channels ahead of local sourcing infrastructure maturation. |
Research Methodology
Direct dialogue with extraction technology specialists, pharmaceutical contract manufacturing procurement leads, Mediterranean cultivation cooperative managers, and EMA regulatory affairs consultants grounded qualitative findings. Secondary validation drew from EMA pharmacovigilance guideline releases, EFSA Novel Food authorization databases, REACH substance evaluation schedules, and EU Green Deal Farm to Fork Strategy implementation reports. Bottom-up volume modeling triangulated against top-down value estimates from trade flow analysis.
Segment-level outputs across the analysis window reflect disaggregation by product type, application tier, extraction method, and geographic production cluster. CAGRs were derived from logistic growth curve fitting to historical procurement volumes and forward-projected pharmaceutical formulation demand. Industry-specific forecast inputs incorporated EMA pharmacopeial compliance cost trajectories and CO2 extraction technology adoption curves.
Climate-induced harvest variability, ECHA reclassification timeline acceleration, and EFSA Novel Food authorization backlog clearance are the dominant revision risks to modeled projections. Practitioners should monitor Mediterranean weather pattern anomalies, EMA purity threshold guideline updates, and Eastern European distributor certification mandate diffusion for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food & Ingredients
Functional Ingredients Market
Functional Food & Ingredients
Superfood Powders Market
Functional Food & Ingredients
Omega 3 PUFA Market
Functional Food & Ingredients
Lovage Extract Market
Functional Food & Ingredients
Global Medical Foods Market
Functional Food & Ingredients
Prickly Pear Fruit Metabolic Health Ingredients Market
Functional Food & Ingredients
Low-Carb Low-Fat Meal Market
Functional Food & Ingredients
Functional Non-Meat Ingredients Market
Functional Food & Ingredients
South America Prebiotic Ingredients Market
Functional Food & Ingredients
Refined Functional Carbohydrates Market
Functional Food & Ingredients
Europe Omega-3 PUFA Market
Functional Food & Ingredients
Japan Soy Protein Market
Functional Food & Ingredients
Sacha Inchi Protein Market
Functional Food & Ingredients
Europe Prebiotic Ingredient Market
Functional Food & Ingredients
Asia-Pacific Omega3 PUFA Market
Functional Food & Ingredients
Global Probiotic Ingredients Market