
 Low-Carb Low-Fat Meal Market | 2026-2036
Low-Carb Low-Fat Meal Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Carb Low-Fat Meal Market Analytics
Plant-based protein isolates are displacing traditional soy concentrates in low-carb low-fat formulations, a material substitution that is realigning product economics across the category. Nestlé S.A. leverages its refrigerated supply chain to dominate European distribution of fresh-prepared formats. Unilever Plc anchors its portfolio through R&D intensity in emulsion technologies that preserve mouthfeel without fat content. General Mills Inc. competes through manufacturing scale in frozen meals, occupying shelf space across North American retail banners.
A low-carb low-fat meal contains fewer than fifteen grams of net carbohydrates and under three grams of fat per serving, achieved through controlled starch reduction, lean protein selection, and fat-replacement systems such as cellulose gels or protein-stabilized emulsions; manufacturers employ retort, blast-freezing, or modified-atmosphere packaging to preserve micronutrient density and sensory integrity across distribution. The ready-to-eat meals segment leads volume due to workplace convenience demand, while meal kits capture margin pools through subscription pricing and ingredient customization. Frozen meals remain mature in North America but show structural growth in Asian urban markets where cold-chain infrastructure is deepening.
The FDA governs nutrient-content claims and health-related labeling under the Nutrition Labeling and Education Act, while the EFSA enforces novel-food assessments for alternative proteins entering European commerce; both frameworks elevate compliance costs but simultaneously filter out unsubstantiated health claims, concentrating demand among verified formulations. The USDA Organic standard and Non-GMO Project verification create tiered market access that rewards ingredient traceability. Stakeholders must monitor evolving definitions of "low-carb" across jurisdictions, as regulatory divergence threatens to fragment formulation strategies and complicate cross-border product portfolios.
Market Dynamics
Clean-label enforcement from the FDA and EFSA is compressing additive tolerances and forcing rapid ingredient-system reformulation across the low-carb low-fat meal category.
Growth Catalysts
- Corporate wellness mandates:Employers in the United States and Germany now subsidize nutritionally verified meals for hybrid workforces, creating institutional procurement channels for ready-to-eat formats.
- EFSA novel-food pathways:Accelerated approval timelines for alternative proteins are expanding the approved ingredient toolkit available to European formulators.
- Cellulose gel stabilization:This fat-replacement technology preserves mouthfeel in retort-processed meals without caloric penalty, unlocking shelf-stable format expansion.
Market Restraints
- Pea protein isolate cost volatility:Concentrated supply from Canadian and Ukrainian growers exposes margins to crop-yield fluctuations and trade-route disruptions.
- Cold-chain infrastructure gaps:Inadequate refrigerated distribution in secondary Japanese cities limits fresh-prepared meal penetration outside Tokyo and Osaka corridors.
- Clean-label compliance burden:EFSA additive restrictions and FDA GRAS self-affirmation requirements impose dual-track testing costs for cross-border portfolios.
Strategic Opportunities
- Indian urban meal-kit expansion:Rising nuclear-family households in Bangalore and Mumbai present subscription-model white space for portion-controlled, cuisine-customized offerings.
- USDA Organic certification tier:Premium positioning through regenerative-sourced proteins commands price multiples in natural-channel retail.
- Modified-atmosphere packaging convergence:Integration with blockchain-enabled traceability systems creates differentiated shelf-life transparency for quality-sensitive buyers.
Industry Challenges
- Retort operator skill scarcity:Specialized thermal-processing expertise required for low-fat emulsion stability is concentrated among aging workforces in US Midwest manufacturing clusters.
- Dual-jurisdiction formulation drift:Divergent FDA and EFSA definitions of "low-carb" force parallel SKU development, fragmenting production runs and complicating inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Carb Low-Fat Meal Market |
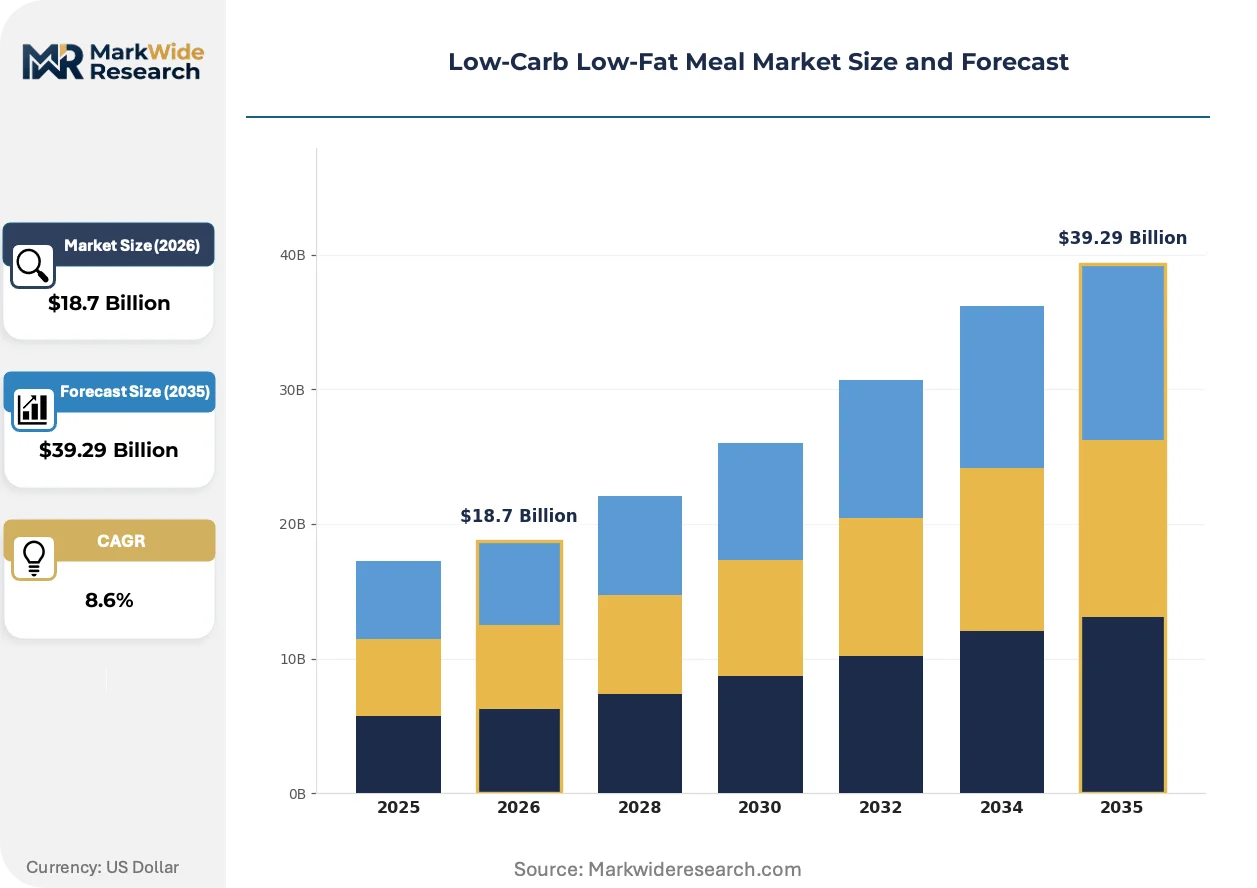
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Meal Type: Frozen Meals, Snacks, Ready-to-Eat Meals, Meal Kits Dietary Preference: Paleo, Keto, Mediterranean, Vegan Ingredient Source: Plant-Based, Animal-Sourced, Organic, Non-GMO Packaging Type: Single-Serve, Bulk, Family Pack, Eco-Friendly |
| Companies Covered | Nestlé S.A., Unilever Plc, General Mills Inc., The Kraft Heinz Company, Danone S.A., PepsiCo Inc., Conagra, Atkins Nutritionals Inc., Cargill Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Carb Low-Fat Meal Market Evolving Landscape
Formulation science and packaging engineering are converging to solve the central sensory paradox of low-carb low-fat meals: delivering satiety and palatability without traditional fat carriers or starch binders.
Precision fermentation-derived protein isolates are overtaking conventional extraction methods in premium formulation tiers. These ingredients deliver complete amino-acid profiles with neutral flavor baselines. High-frequency purchasers in corporate wellness programs are driving adoption velocity. The technology is overtaking legacy soy-concentrate supply chains in European fresh-prepared segments.
REACH chemical-registration expansions are tightening scrutiny on emulsifier classifications used in fat-replacement systems. Manufacturers face reformulation timelines to substitute cellulose-derived alternatives for legacy lecithin complexes. Frozen-meal exporters to the European Union are most affected, accelerating clean-label certification investments ahead of enforcement windows.
Subscription-based meal-kit procurement is compressing traditional retail purchasing cycles for health-conscious households. Direct-to-consumer channels are displacing conventional grocery-aisle discovery for trial-size introductions. This behavioral shift is most visible in German metropolitan markets, where digital-native entrants capture recurring-revenue pools from incumbent frozen-meal brands.
Low-Carb Low-Fat Meal Market Segmentation
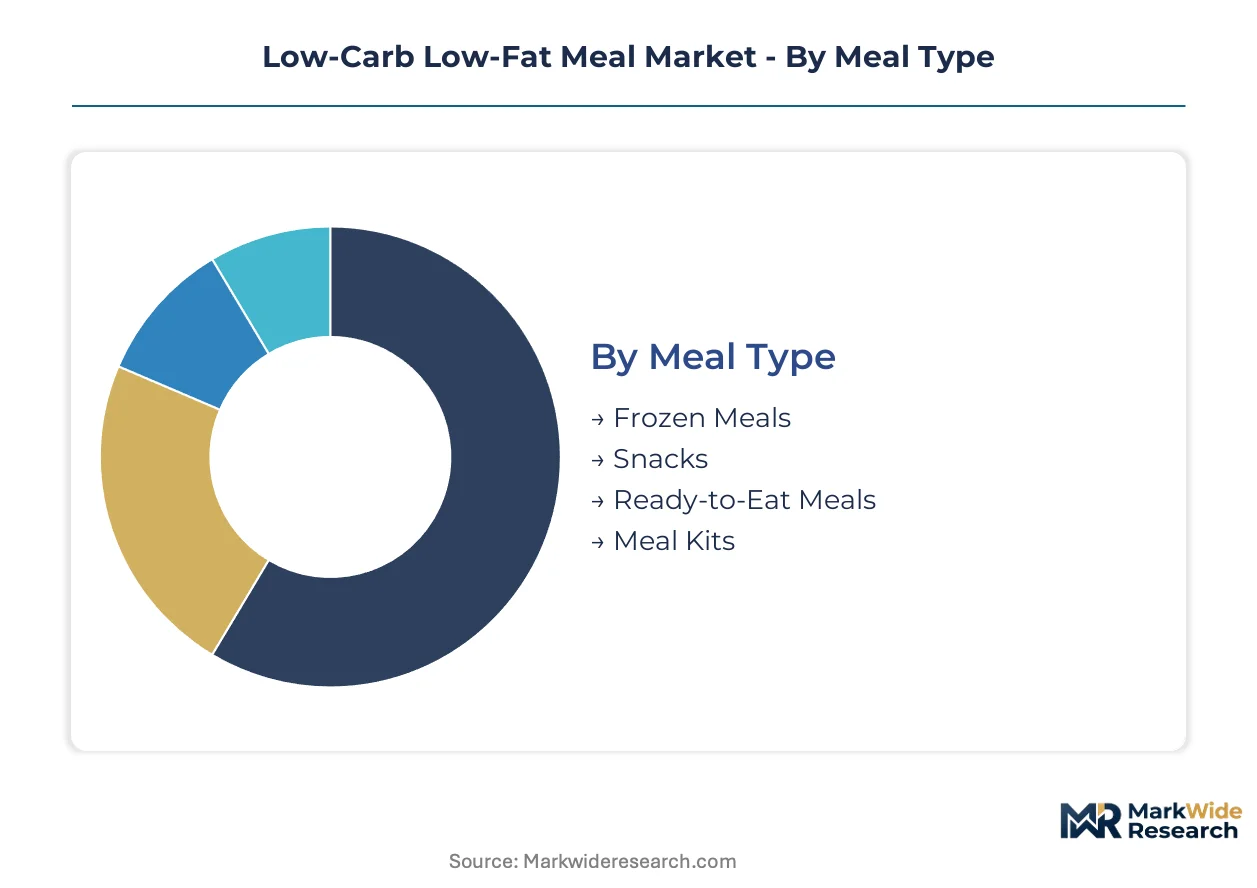
Segmentation in the low-carb low-fat meal market reveals distinct demand clusters shaped by preparation convenience, dietary adherence requirements, and ingredient provenance preferences. Manufacturers configure supply chains and formulation strategies around these divides to optimize margin capture across divergent consumer willingness-to-pay thresholds.
Meal Type:
Standalone consumption occasions dominate volume, while embedded meal-planning subscriptions command premium pricing through recurring revenue structures.
- Frozen Meals:Blast-frozen formulations preserve micronutrient density in lean-protein and vegetable-centric recipes. Demand concentrates in North American retail banners where General Mills and Conagra Brands occupy dominant shelf-space positions through manufacturing scale.
- Ready-to-Eat Meals:Retort-processed or modified-atmosphere packaged formats require no preparation and target workplace consumption. Corporate wellness programs in the United States and Germany now subsidize these products for hybrid workforces, creating institutional procurement channels.
- Snacks:Portion-controlled protein bars and savory bites fill inter-meal gaps for carb-restricted consumers.
- Meal Kits:Pre-portioned ingredients with preparation instructions capture subscription pricing and customization premiums.
Frozen meals lead volumes today; ready-to-eat formats are gaining share fastest.
Dietary Preference:
Cost tiers stratify around macronutrient stringency and ingredient complexity, with ketogenic formulations commanding the highest per-serving premiums.
- Keto:Formulations restrict net carbohydrates below fifteen grams per serving through controlled starch reduction and fiber enrichment. European demand concentrates in Germany where EFSA novel-food approvals for alternative proteins expand formulation flexibility.
- Paleo:Grain-free and dairy-excluded recipes emphasize whole-food ingredient lists. United States natural-channel retail rewards these products with premium shelf positioning and regenerative-sourcing certifications.
- Mediterranean:Olive oil replacement systems and lean fish proteins align with cardiovascular health positioning.
- Vegan:Plant-protein isolates displace animal ingredients, requiring emulsion technology investments to preserve mouthfeel.
Keto formulations command the steepest price premiums; Mediterranean options show the broadest demographic appeal.
Ingredient Source:
Supply concentration and certification burden determine margin structure, with organic and non-GMO tiers requiring traceability infrastructure that excludes smaller formulators.
- Plant-Based:Pea and fava protein isolates displace legacy soy concentrates in European fresh-prepared segments. Canadian and Ukrainian crop-yield volatility exposes margin pressure from concentrated supply geography.
- Animal-Sourced:Lean poultry and white fish proteins anchor conventional low-fat formulations with complete amino-acid profiles.
- Organic:USDA Organic and EU Organic certifications require regenerative sourcing and restricted input lists. Natural-channel retail in the United States commands price multiples for verified supply chains.
- Non-GMO:Project verification creates tiered market access separate from organic standards.
Animal-sourced proteins retain volume leadership; plant-based isolates are climbing the fastest.
Packaging Type:
Volume scale and sustainability positioning create divergent manufacturing investments across format sizes.
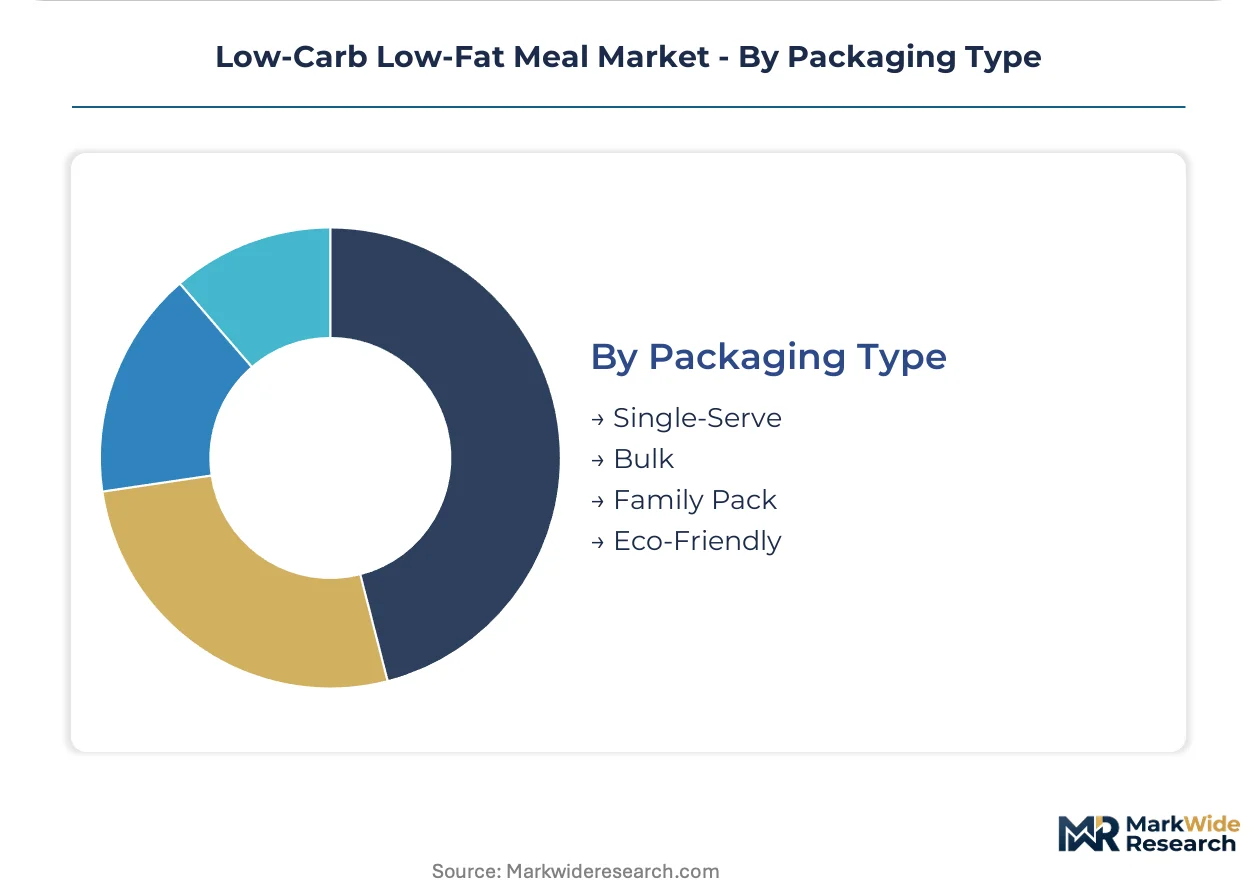
- Single-Serve:Individual portions target workplace and travel consumption with modified-atmosphere or retort packaging. Japanese urban corridors show concentrated demand where cold-chain infrastructure supports fresh-prepared distribution.
- Eco-Friendly:Compostable or recyclable materials respond to EFSA and FDA clean-label enforcement tightening additive and material scrutiny. European exporters face accelerated reformulation timelines ahead of REACH chemical-registration expansions.
- Family Pack:Multi-portion formats reduce per-serving packaging cost for household consumption.
- Bulk:Food-service and institutional channels require portion-controlled delivery systems.
Single-serve formats dominate retail velocity; eco-friendly packaging shows the steepest investment acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate wellness programs in Germany and the United States are reshaping procurement patterns for nutritionally verified meal formats. Cold-chain infrastructure gaps in secondary Japanese cities constrain fresh-prepared distribution beyond Tokyo and Osaka corridors. Regulatory divergence between FDA and EFSA definitions of "low-carb" complicates cross-border product portfolios.
United States
Employer-subsidized meal programs for hybrid workforces drive institutional procurement of ready-to-eat formats. FDA nutrient-content claims under the Nutrition Labeling and Education Act elevate compliance costs but filter unsubstantiated health claims. Midwest manufacturing clusters concentrate retort-processing expertise for shelf-stable emulsion stability.
Germany
Corporate wellness mandates in Berlin and Munich expand demand for nutritionally verified workplace meals. EFSA novel-food assessments for alternative proteins accelerate approved ingredient toolkit expansion. Bavarian food-tech clusters develop precision fermentation-derived protein isolates for premium formulation tiers.
Japan
Urban professionals in Tokyo and Osaka demand single-serve modified-atmosphere packaged meals for convenience consumption. METI standards govern food-labeling accuracy and additive disclosure requirements. Cold-chain infrastructure investments in Nagoya and Fukuoka aim to extend fresh-prepared distribution beyond primary metro corridors.
India
Nuclear-family households in Bangalore and Mumbai present subscription-model white space for portion-controlled meal kits. FSSAI regulations tighten nutritional labeling and health-claim substantiation requirements. Maharashtra food-processing zones attract clean-label manufacturing investments targeting urban middle-class demand.
United Kingdom
Digital-native meal-kit entrants capture recurring-revenue pools from incumbent frozen-meal brands in London metropolitan markets. EFSA-aligned post-Brexit regulatory frameworks maintain additive scrutiny and novel-food assessment pathways. Southeast England logistics hubs facilitate direct-to-consumer cold-chain distribution for fresh-prepared formats.
Low-Carb Low-Fat Meal Market Competitive Landscape
Global majors compete with regional champions across refrigerated supply chain reach and emulsion technology portfolios. The vendor base stratifies between scale-driven frozen-meal manufacturers, fresh-prepared specialists with captive cold-chain assets, and ingredient-system innovators controlling fat-replacement patents. Three archetypes dominate: diversified FMCG conglomerates with R&D intensity, mid-cap clean-label specialists with regenerative sourcing certifications, and private-label suppliers with manufacturing scale. Competitive moves concentrate on backward integration into alternative protein supply and geographic licensing of shelf-life extension technologies.
Within the diversified conglomerate tier, Nestlé S.A. and Unilever Plc exemplify players leveraging refrigerated distribution infrastructure and emulsion science investments respectively. General Mills Inc. occupies a position representing scale-driven frozen-meal manufacturing across North American retail banners. These three anchors illustrate how competitive positioning separates cold-chain depth from formulation patent portfolios from manufacturing throughput.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Unilever Plc |
| General Mills Inc. |
| The Kraft Heinz Company |
| Danone S.A. |
| PepsiCo Inc. |
| Conagra |
| Atkins Nutritionals Inc. |
| Cargill Incorporated |
| Others |
Value Network & Pricing Analysis
Retort operator skill scarcity in US Midwest manufacturing clusters widens labor-cost differentials between shelf-stable and fresh-prepared tiers, compressing margins on emulsion-intensive formulations while premium cold-chain products capture wider pricing spreads.
Pricing Analysis
Input-cost pass-through from pea protein isolate volatility feeds directly into plant-based tier pricing, with Canadian and Ukrainian crop-yield fluctuations forcing margin absorption or price adjustments. Three-tier pricing structure across premium, standard, and economy levels separates USDA Organic certified SKUs from conventional clean-label and private-label economy offerings. Pricing pressure stems from EFSA additive restrictions compelling dual-track reformulation investments for cross-border portfolios. Corporate wellness procurement channels show lowest price sensitivity due to employer subsidy structures, while individual retail purchasers in Asian urban markets exhibit highest elasticity.
Supply Chain Analysis
Direct-to-retail distribution through refrigerated banners handles fresh-prepared demand in Germany and Japan, while frozen-meal volume runs through mass-market retail and food-service institutional channels across North America. Geographic supply concentration centers on Canada and Ukraine for pea protein isolates, with precision fermentation capacity clustering in Bavarian food-tech zones. Raw material dependencies include cellulose gel stabilizers, modified-atmosphere packaging films, and lean poultry proteins. Single-source vulnerability in Ukrainian crop supply exposes margin compression during trade-route disruptions. Distribution runs through captive cold-chain assets for premium tiers and third-party logistics for economy frozen formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EFSA novel-food approval timelines in Europe lag FDA GRAS self-affirmation pathways in the United States, creating formulation-cost differentials that reward dual-jurisdiction portfolio strategies.
For Market Incumbents: To counter precision fermentation-derived protein isolates displacing legacy soy concentrates, Nestlé S.A. and Unilever Plc should deepen backward integration into alternative protein supply through captive Bavarian fermentation capacity, while reinforcing cold-chain depth in Japanese secondary cities through Nagoya and Fukuoka distribution node investments. For New Entrants and Emerging Players: FSSAI regulatory tightening in India opens a window for clean-label manufacturing investments in Maharashtra food-processing zones, targeting Bangalore and Mumbai nuclear-family households with subscription-model meal kits. White-space concentration exists in portion-controlled cuisine-customized offerings where digital-native positioning bypasses incumbent frozen-meal shelf-space dominance. For Investors and Strategic Acquirers: Diversified FMCG conglomerates are the most active acquirer in this space, seeking mid-cap clean-label specialists with regenerative sourcing certifications. Long-term viability hinges on five-to-ten year cold-chain infrastructure deepening in Asian urban corridors. The signal to monitor is accelerated EFSA enforcement windows driving consolidation among formulation-technology patent holders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alternative Proteins | Captive precision fermentation capacity in Bavarian clusters secures isolate supply against Canadian crop volatility. |
| Cold-Chain Infrastructure Expansion | Nagoya and Fukuoka distribution nodes extend fresh-prepared penetration beyond Tokyo-Osaka corridors in Japan. |
| Clean-Label Certification Investment | USDA Organic and Non-GMO Project verification commands price multiples in United States natural-channel retail. |
| Direct-to-Consumer Channel Development | Subscription-model meal kits in German metropolitan markets displace incumbent frozen-meal recurring-revenue pools. |
| Emulsion Technology Patent Licensing | Cellulose gel stabilization patents unlock shelf-stable format expansion without fat-content penalties. |
Research Methodology
Bottom-up corporate wellness procurement modeling reconciled against top-down refrigerated supply chain tracking forms the analytical core of this study. Primary interviews with formulation R&D directors, cold-chain logistics operators, retail category buyers, and regulatory affairs specialists at FDA and EFSA were cross-validated against secondary sources including FDA GRAS notifications, EFSA novel-food assessment databases, USDA Organic certification records, and customs trade data for pea protein isolate flows. This dual-layer approach ensures demand-side institutional purchasing patterns align with supply-side manufacturing capacity and ingredient availability constraints.
Historical trendline analysis of frozen-meal retail velocity and ready-to-eat workplace consumption established baseline growth trajectories across the projection horizon. Segmentation dimensions modeled include meal type, dietary preference, ingredient source, and packaging format, with geographic regulatory cluster differentiation between FDA and EFSA jurisdictions. CAGRs were derived from weighted average of bottom-up segment summation and top-down macro constraint adjustment, incorporating corporate wellness mandate adoption curves and cold-chain infrastructure investment pipelines as industry-specific forecast inputs.
Revisions become necessary when EFSA additive enforcement windows accelerate, Ukrainian trade-route disruptions persist, or FDA low-carb definition divergence from EFSA thresholds widens. Forecasts reflect documented assumptions regarding employer subsidy program expansion and precision fermentation scale-up timelines. Periodic stress-testing of base assumptions against regulatory filing velocity and crop-yield reporting is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food & Ingredients
Prebiotic Ingredients Market
Functional Food & Ingredients
Africa Algae Omega-3 Ingredients Market
Functional Food & Ingredients
Brominated Vegetable Oil Market
Functional Food & Ingredients
Mediterranean Cognitive-First Ingredient Systems Market
Functional Food & Ingredients
Multifunctional Food Ingredients Market
Functional Food & Ingredients
Beta Glucan and Fucoidan Market
Functional Food & Ingredients
Europe Prebiotic Ingredient Market
Functional Food & Ingredients
Global Medical Foods Market
Functional Food & Ingredients
Africa Omega-3 PUFA Market
Functional Food & Ingredients
APAC Heart Health Functional Food Market
Functional Food & Ingredients
Superfood Powders Market
Functional Food & Ingredients
Prickly Pear Fruit Metabolic Health Ingredients Market
Functional Food & Ingredients
Functional Non-Meat Ingredients Market
Functional Food & Ingredients
Europe Omega-3 PUFA Market
Functional Food & Ingredients
South America Prebiotic Ingredients Market
Functional Food & Ingredients
Essential Fatty Acids Market