
 Healthy Fats Low Carb Market | 2026-2036
Healthy Fats Low Carb Market Size, Share, and Industry Trends Forecast 2026-2036
Healthy Fats Low Carb Market Foresight
Specialty retail shelf space is narrowing as mass-market grocers absorb premium healthy-fat SKUs into conventional aisles. Nestle leverages its global distribution infrastructure to place low-carb, high-fat products in mainstream supermarkets. Bulletproof 360 Incorporation anchors its position through MCT oil specialization and direct-to-consumer subscription models. Fat Snax competes in the baked-goods niche with coconut flour and almond flour formulations designed for ketogenic adherence.
Healthy fats low carb products encompass lipid-dense, carbohydrate-restricted food and beverage items typically formulated with medium-chain triglyceride oils, grass-fed dairy derivatives, or plant-based monounsaturated sources, manufactured through cold-pressing, clarification, or enzymatic interesterification to preserve oxidative stability and nutritional density. These products serve metabolic health applications including ketogenic dietary protocols, glycemic management, and sustained-energy nutrition. Olive oil and avocado oil dominate the product type segment due to established cardiovascular health claims and culinary versatility across cooking temperatures. Ghee concentrates margin pools in premium positioning through grass-fed and cultured differentiation, while coconut oil sustains volume leadership in baking and beverage applications. The delivery mode dimension shows online stores capturing growth from subscription replenishment models, though supermarkets retain the largest transaction volume through impulse placement and promotional stacking.
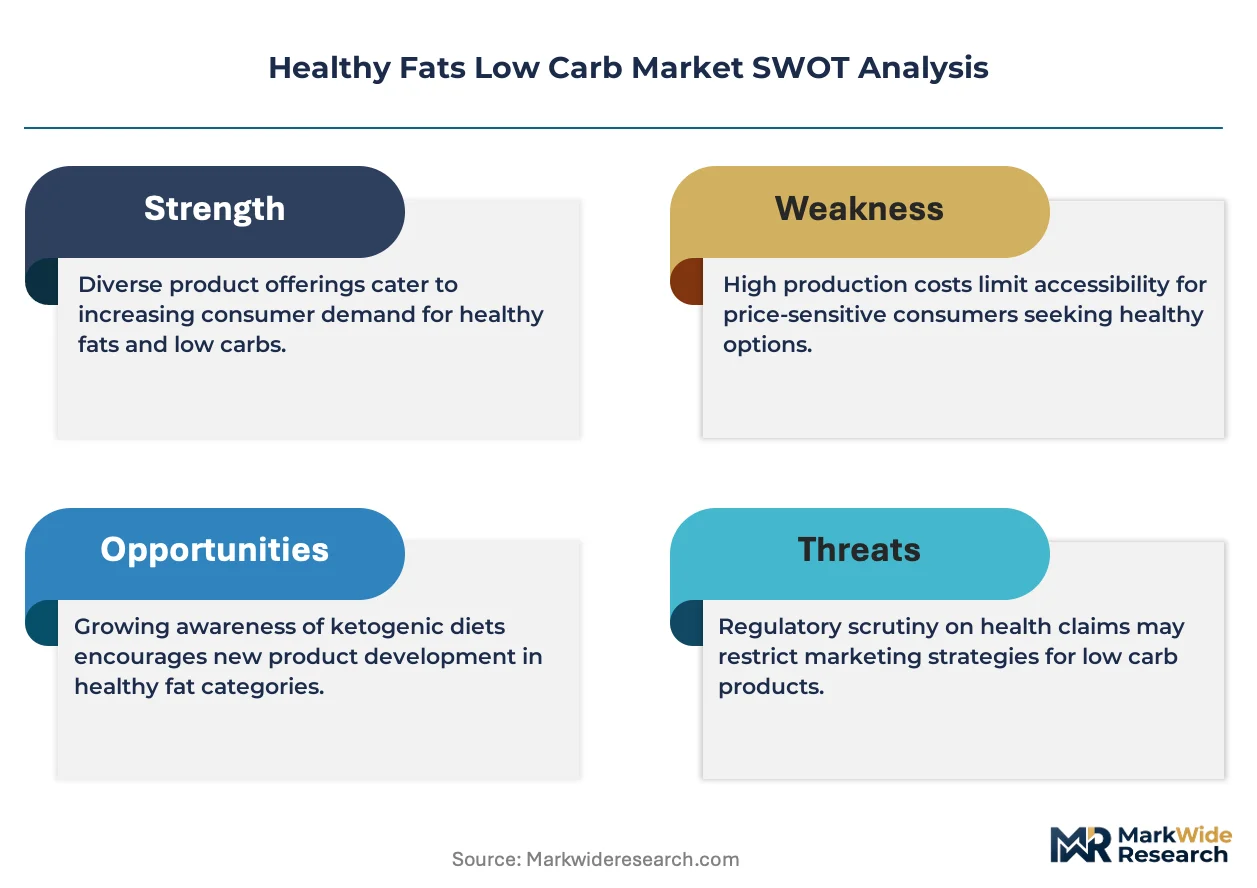
FDA nutrition labeling requirements and USDA organic certification standards shape product formulation transparency and health claim substantiation in the United States, while the FDA's evolving stance on saturated fat guidance creates compliance complexity for coconut oil and ghee marketers. EFSA health claim regulations in Europe restrict specific cardiovascular benefit language, forcing reformulation evidence dossiers for avocado oil and olive oil entrants. Stakeholders must monitor shifting regulatory thresholds for saturated fat warnings against expanding consumer acceptance of ketogenic metabolic therapies.
Market Dynamics
The FDA's evolving saturated fat guidance is compressing formulation margins while simultaneously opening positioning space for ketogenic-aligned brands. Cold-pressed extraction infrastructure and enzymatic interesterification capabilities are concentrating among contract manufacturers with USDA organic certification.
Growth Catalysts
- Ketogenic protocol expansion:Sports nutrition and metabolic health clinics in the United States are prescribing MCT oil protocols for sustained energy management. This drives bulk procurement of medium-chain triglyceride formulations.
- USDA organic certification:Grass-fed dairy derivatives command shelf-space premiums in conventional supermarkets. Clean-label fat positioning accelerates as retailers respond to consumer ingredient-panel scrutiny.
- Direct-to-consumer subscription models:Replenishment automation locks in recurring revenue for lipid-dense product manufacturers. California and Texas metropolitan clusters show highest subscription density.
Market Restraints
- Avocado oil input volatility:Mexican and Peruvian harvest cycles create price instability for monounsaturated oil processors. Climate-induced yield compression amplifies margin pressure.
- Coconut oil saturated fat warnings:FDA draft guidance on cardiovascular risk language restricts health claim substantiation. Marketers face reformulation costs or label repositioning.
- Specialty retail shelf contraction:Mass-market grocers absorbing premium SKUs narrows dedicated natural-channel distribution. Independent retailers lose exclusivity leverage.
Strategic Opportunities
- Functional beverage integration:Ready-to-drink ketogenic coffee and meal replacement formats penetrate convenience store channels. Starbucks and 7-Eleven represent untapped placement vectors.
- EFSA health claim dossier investment:European cardiovascular benefit substantiation opens olive oil and avocado oil positioning in EU markets. Reformulation evidence requirements favor capitalized entrants.
- Almond flour bakery expansion:Ketogenic baked goods capture snack aisle real estate in conventional grocers. Coconut flour formulations compete for frozen dessert applications.
Industry Challenges
- Cold-pressing technician scarcity:Oxidative stability preservation requires specialized equipment operation and quality control protocols. Training pipelines lag equipment deployment.
- Dual certification timelines:USDA organic plus non-GMO project verification extends product launch cycles by 8-14 months. Smaller brands face working capital strain.
- Legacy ERP integration:Subscription replenishment models require real-time inventory synchronization with third-party logistics providers. Direct-to-consumer brands struggle with fulfillment software migration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthy Fats Low Carb Market |
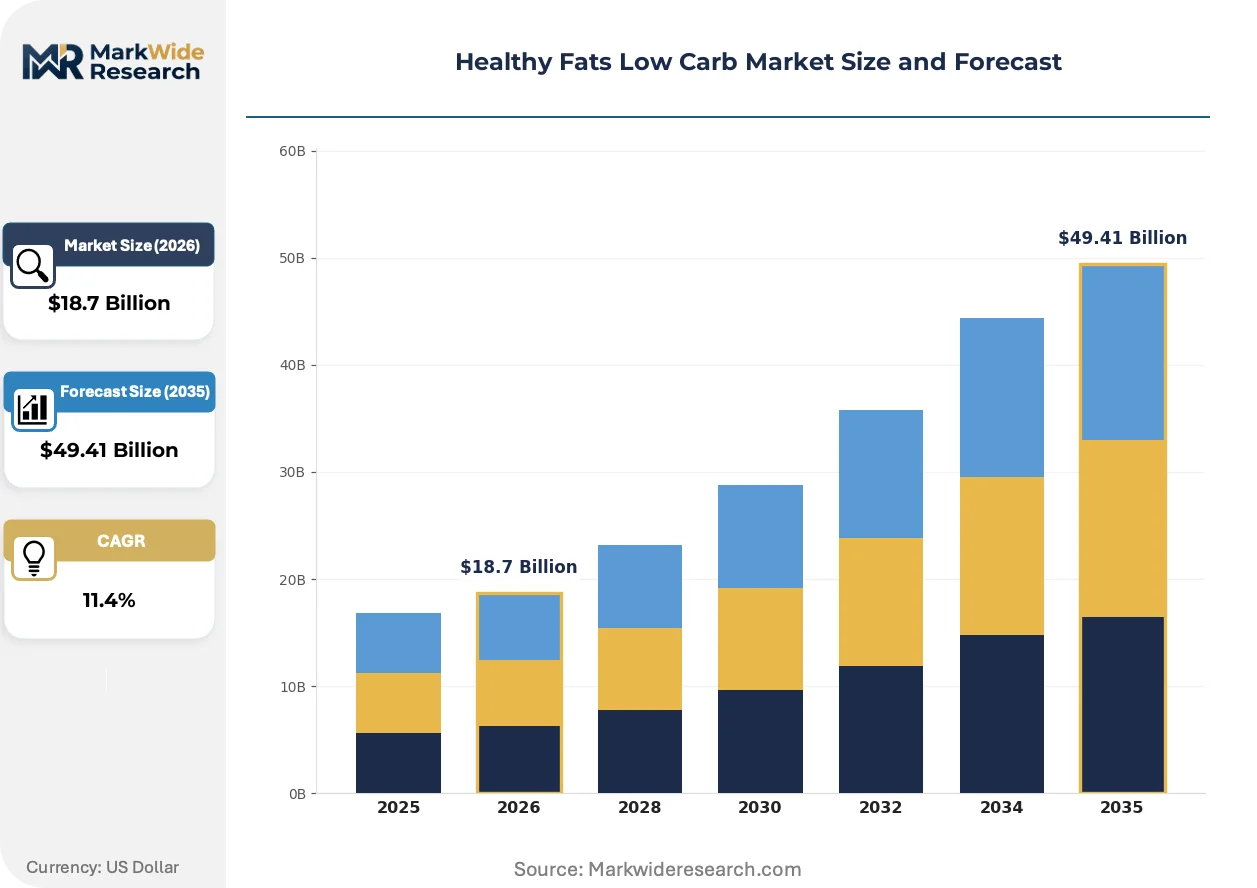
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coconut Oil, Avocado Oil, Olive Oil, Ghee End User: Health Enthusiasts, Fitness Enthusiasts, Weight Loss Seekers, Dieters Delivery Mode: Retail Stores, Online Stores, Direct Sales, Supermarkets Packaging Type: Bottles, Jars, Pouches, Sachets |
| Companies Covered | Nestle, Mission Foods, Life Cuisine, Ancient Nutrition, Halo Top Creamery, LC-Foods Corporation, La Tortilla Factory, Fat Snax, Bulletproof 360 Incorporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthy Fats Low Carb Market Shifts & Advancements
Formulation transparency and extraction technology advancement are compressing traditional processing advantages while enabling new entrant positioning. Clean-label verification systems and metabolic health protocol alignment reshape competitive differentiation.
Enzymatic interesterification is digitizing quality control workflows in medium-chain triglyceride production. Contract manufacturers serving ketogenic brands adopt automated spectroscopy for real-time oxidative stability monitoring. This compression of analytical turnaround times enables just-in-time formulation adjustments that were previously batch-dependent.
EFSA health claim regulations are restricting cardiovascular benefit language for olive oil and avocado oil marketers in European markets. Industrial consequence includes mandatory reformulation evidence dossiers and clinical trial investment for new entrants. Mediterranean-origin producers are responding by consolidating regulatory affairs capabilities in Brussels.
Subscription replenishment is displacing traditional retail replenishment cycles for MCT oil and ghee products. Direct-to-consumer brands capture California and Texas metropolitan demand while conventional supermarkets lose pantry-stocking frequency. This channel rotation concentrates customer data ownership with digital-native suppliers.
Healthy Fats Low Carb Market Segmentation
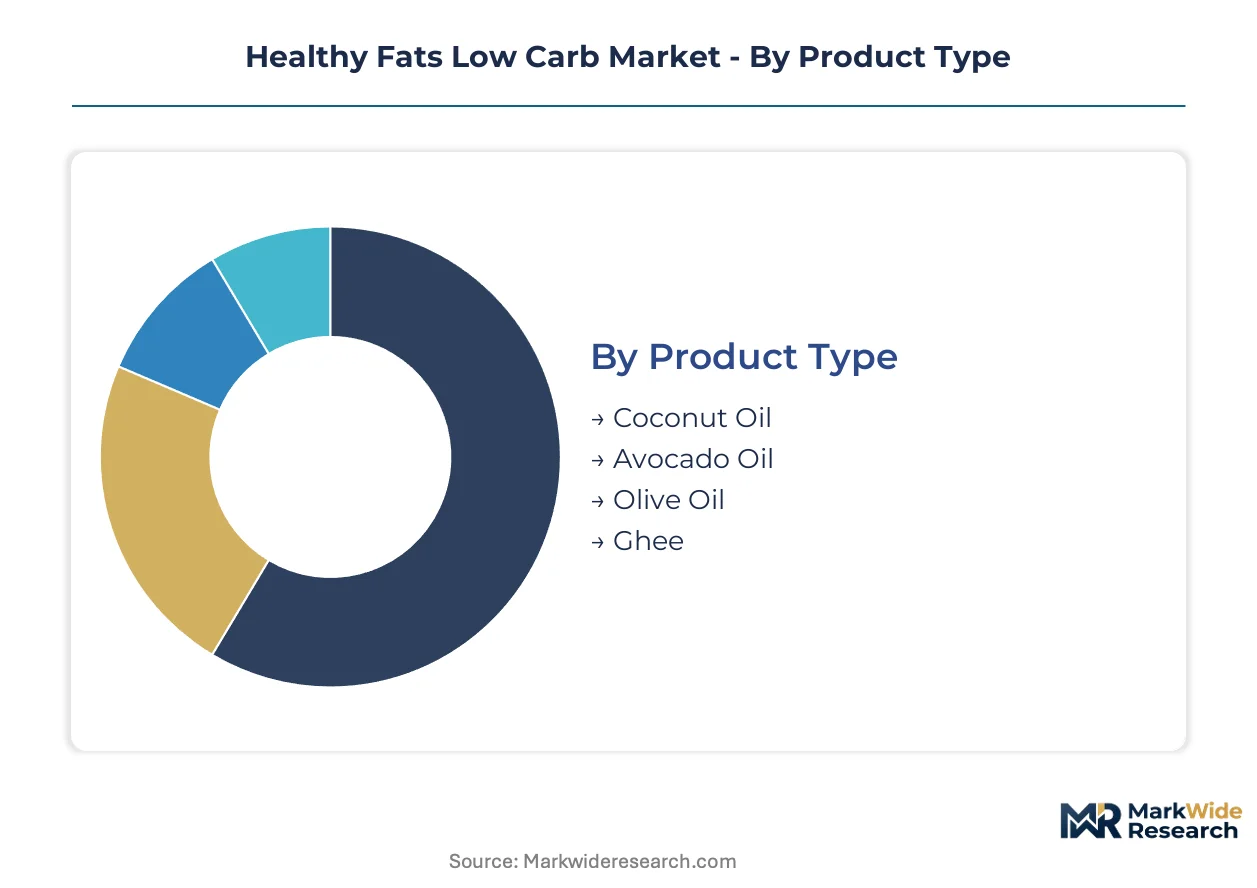
Segmentation in healthy fats low carb markets reveals how formulation specificity, channel strategy, and consumer metabolic goals intersect to determine pricing power and loyalty patterns. Each dimension carries distinct after-sales service implications, from subscription replenishment automation to certified-origin traceability systems.
Product Type:
After-sales service intensity varies sharply across lipid categories, with cold-pressed variants demanding oxidative stability monitoring and grass-fed derivatives requiring certification documentation support.
- Olive Oil:Extra-virgin grades with polyphenol content above 250 mg/kg command premium positioning through cardiovascular health substantiation. Demand concentrates in California and Texas metropolitan clusters where Mediterranean diet adherence drives pantry-stocking frequency for high-phenolic formulations.
- Avocado Oil:Cold-pressed monounsaturated oil with smoke points exceeding 270°C enables high-heat cooking applications without degradation. Mexican and Peruvian harvest volatility compresses margin stability for processors, forcing long-term supply contracting to secure clean-label positioning.
- Coconut Oil:MCT-rich lauric acid formulations serve ketogenic baking and beverage applications with established volume leadership.
- Ghee:Grass-fed and cultured differentiation concentrates margin pools in premium dairy derivatives with extended shelf stability.
Olive oil holds the largest share; momentum sits with avocado oil as high-heat culinary applications expand.
End User:
Cost tier stratification separates clinically guided protocol adherence from discretionary wellness purchasing, with metabolic health clinics driving bulk procurement at price points independent of retail premiums.
- Health Enthusiasts:Ingredient-panel scrutiny and clean-label verification dominate purchasing criteria, with USDA organic certification serving as non-negotiable entry threshold for pantry-stocking decisions.
- Weight Loss Seekers:Ketogenic protocol adherence drives MCT oil and ghee procurement through direct-to-consumer subscription models, with California showing highest replenishment automation density.
- Fitness Enthusiasts:Sports nutrition integration prioritizes sustained-energy lipid formulations for endurance applications.
- Dieters:Carbohydrate-restriction goals align with coconut flour and almond flour baked-good substitution patterns.
Health enthusiasts hold the largest share; weight loss seekers are climbing the fastest as metabolic health clinic referrals accelerate.
Delivery Mode:
Volume concentration favors impulse-placement channels, while margin accretion concentrates in subscription-automated replenishment with superior customer data ownership.
- Supermarkets:Conventional grocers absorb premium healthy-fat SKUs into conventional aisles, with promotional stacking driving transaction velocity and brand trial for ketogenic-formulated products.
- Online Stores:Direct-to-consumer platforms capture recurring revenue through replenishment automation, with real-time inventory synchronization requirements straining legacy ERP systems for emerging brands.
- Retail Stores:Specialty natural-channel distribution faces shelf-space contraction as mass-market grocers expand clean-label fat positioning.
- Direct Sales:Metabolic health clinic and sports nutrition practitioner channels enable protocol-guided bulk procurement with clinical credibility transfer.
Supermarkets hold the largest share; online stores are gaining share fastest through subscription density in Texas and California clusters.
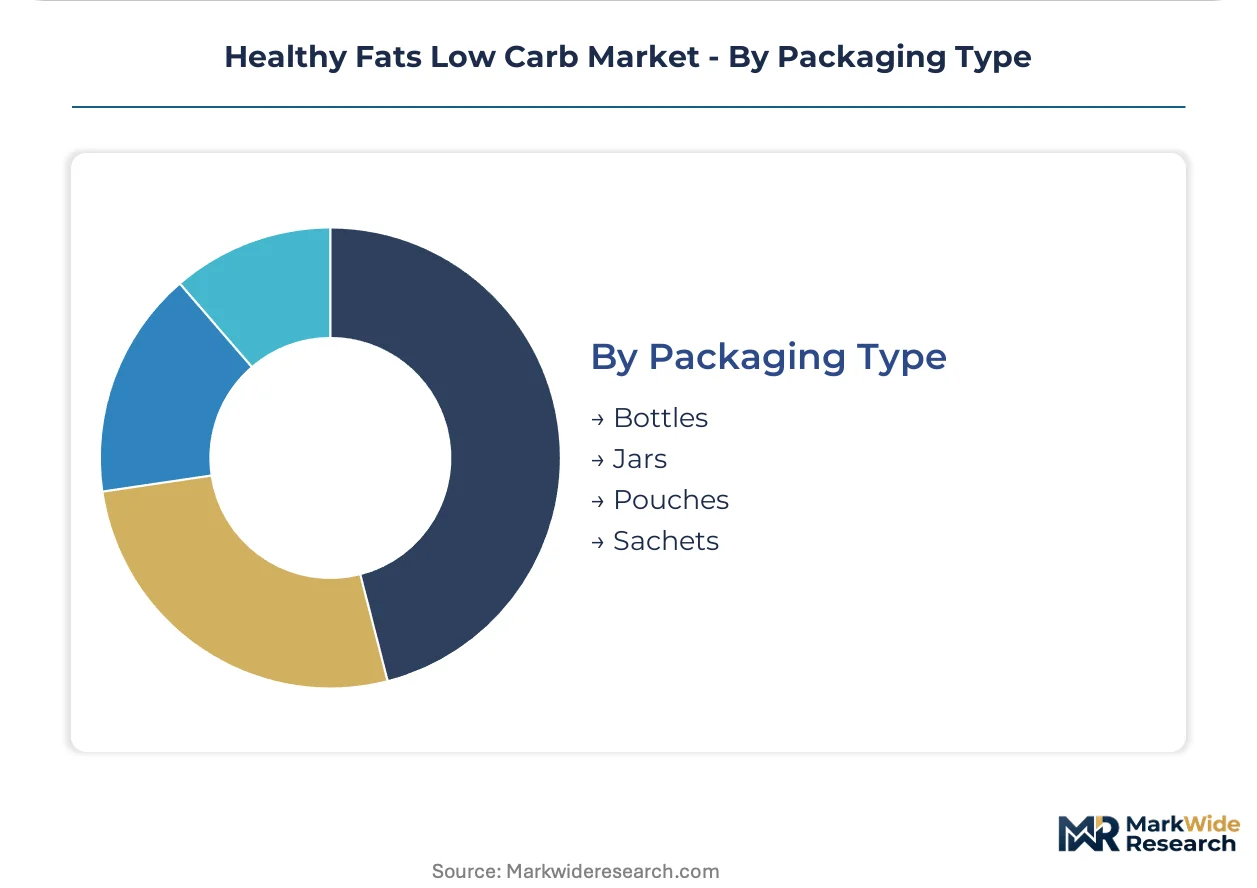
Packaging Type:
Supply concentration in cold-pressed extraction infrastructure shapes packaging material selection, with oxidative stability preservation dictating barrier property requirements and shelf-life claims.
- Bottles:Amber glass and UV-opaque PET formats dominate liquid oil categories, with oxygen transmission rates below 0.5 cc/day preserving polyphenol integrity for high-grade olive and avocado oils.
- Jars:Wide-mouth glass containers serve solid fat categories including ghee and coconut oil, enabling scoop-based portion control for ketogenic recipe formulation.
- Pouches:Flexible metallized films reduce shipping cube for direct-to-consumer fulfillment, though puncture resistance concerns limit adoption for premium positioning.
- Sachets:Single-serve formats penetrate convenience store and travel channels for MCT oil and ketogenic coffee additive applications.
Bottles hold the largest share; pouches show steepest expansion trajectory as fulfillment optimization pressures packaging economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA nutrition labeling reforms anchor the United States as the dominant geography, with metabolic health protocol adoption spreading through California and Texas metropolitan clusters. Specialty retail shelf expansion and direct-to-consumer subscription density concentrate demand in North American urban centers, while EFSA regulatory frameworks reshape European formulation strategies.
United States
Ketogenic dietary protocol expansion and sports nutrition clinic prescribing drive MCT oil procurement in California and Texas metropolitan areas. FDA draft guidance on saturated fat warnings creates compliance complexity for coconut oil and ghee marketers. Austin and Los Angeles anchor subscription replenishment automation for lipid-dense product manufacturers.
Germany
Grass-fed dairy derivative demand and clean-label verification systems accelerate ghee market penetration in Bavaria and North Rhine-Westphalia. EFSA health claim regulations restrict cardiovascular benefit language for olive oil entrants, forcing reformulation evidence dossiers. Munich-based contract manufacturers concentrate cold-pressed extraction capabilities for organic certification compliance.
United Kingdom
Health enthusiast ingredient-panel scrutiny and paleo-formulated product adoption expand avocado oil retail placement in London and Southeast England. UK Food Standards Agency labeling requirements align with evolving EU regulatory postures on fat health claims. Manchester specialty food retailers narrow shelf space as mass-market grocers absorb premium SKUs.
Australia
Fitness enthusiast sustained-energy nutrition and endurance sports applications drive medium-chain triglyceride formulation demand in New South Wales and Victoria. Food Standards Australia New Zealand (FSANZ) regulations govern metabolic health claim substantiation for ketogenic-aligned brands. Sydney direct-to-consumer platforms capture recurring revenue through replenishment automation.
Canada
Weight loss seeker ketogenic adherence and carbohydrate-restriction goals expand coconut flour and almond flour baked-good substitution in Ontario and Quebec. Health Canada nutrition labeling requirements shape clean-label fat positioning transparency. Toronto mass-market grocers absorb premium healthy-fat SKUs into conventional aisles, compressing specialty retail distribution.
Healthy Fats Low Carb Market Competitive Landscape
Global CPG conglomerates and functional food specialists split the market into distinct competitive spheres. Nestle leverages worldwide distribution infrastructure to place low-carb, high-fat products in mainstream supermarkets, while Bulletproof 360 Incorporation anchors positioning through MCT oil specialization and direct-to-consumer subscription models. Strategic moves concentrate on mass-market SKU absorption and enzymatic interesterification capability acquisition.
Within the functional food specialist tier, Bulletproof 360 Incorporation and Fat Snax occupy positions exemplifying metabolic health protocol alignment and ketogenic baked-good niche penetration respectively. Nestle represents the scale-driven archetype, leveraging global infrastructure for conventional aisle placement. Ancient Nutrition sits within the ancestral diet formulation segment. These three entities collectively illustrate how certification documentation support and subscription replenishment automation separate premium positioning from commodity lipid competition.
| Leading Market Players |
|---|
| Nestle |
| Mission Foods |
| Life Cuisine |
| Ancient Nutrition |
| Halo Top Creamery |
| LC-Foods Corporation |
| La Tortilla Factory |
| Fat Snax |
| Bulletproof 360 Incorporation |
| Others |
Supply & Pricing Matrix
Long Beach port congestion surcharges ripple through cold-pressed avocado oil shipments from Mexican and Peruvian processors, compressing margin pools for mid-tier brands while amplifying price premiums for certified-organic inventory held by vertically integrated suppliers with captive California distribution.
Pricing Analysis
Customization-premium spreads separate grass-fed ghee with full USDA organic traceability from conventional clarified butter alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with bulk MCT oil procurement for metabolic health clinics commanding contract-based long-term offtake below retail thresholds. Price differentiation stems from enzymatic interesterification capability and cold-pressing technician certification. Pricing pressure intensifies as mass-market grocers absorb premium SKUs and force promotional stacking. Weight loss seekers through direct-to-consumer channels show lowest price sensitivity; conventional supermarket shoppers exhibit highest.
Supply Chain Analysis
Contract-manufacturing concentration sits with USDA-certified organic processors in California, Texas, and Wisconsin cold-pressing infrastructure. Raw material dependencies draw from Mexican avocado harvests, Peruvian coconut plantations, and domestic grass-fed dairy cooperatives. Single-source vulnerability concentrates in Mexican monounsaturated oil supply during climate-induced yield compression cycles. Distribution runs through direct-to-consumer fulfillment centers in Austin and Los Angeles metropolitan clusters, with conventional supermarket wholesale absorbing remaining volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored in regulatory entrenchment: FDA nutrition labeling compliance and dual certification timelines create 8-14 month barriers that working-capital-constrained entrants cannot cross.
For Market Incumbents: Entrench through backward integration into cold-pressed extraction infrastructure and captive grass-fed dairy sourcing. Acquire enzymatic interesterification capabilities from distressed contract manufacturers facing technician scarcity. Channel control through direct-to-consumer subscription automation in California and Texas clusters defends against mass-market grocer private-label encroachment. For New Entrants and Emerging Players: Build out functional beverage integration targeting convenience store placement for ready-to-drink ketogenic coffee formats. White-space concentrates in 7-Eleven and Starbucks untapped vectors where protocol-guided consumers seek on-the-go lipid-dense options. Go-to-market angle: clinical credibility transfer through sports nutrition practitioner endorsements rather than retail shelf competition. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified CPG conglomerates with underperforming specialty nutrition divisions lacking subscription replenishment infrastructure. Long-term viability frames around metabolic health protocol institutionalization in clinical settings. Acquisition archetype: digital-native brands with California-Texas customer density and real-time inventory synchronization capabilities. Signal to watch: metabolic health clinic bulk procurement contract announcements as ketogenic prescription standardization accelerates.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Automation | Locks recurring revenue and captures customer data ownership from conventional retail channels. |
| EFSA Health Claim Dossier Investment | Opens European olive oil and avocado oil positioning through cardiovascular benefit substantiation. |
| Enzymatic Interesterification Capability Acquisition | Concentrates quality control digitization among ketogenic-aligned contract manufacturers. |
| Functional Beverage Convenience Store Placement | Penetrates 7-Eleven and Starbucks channels with ready-to-drink ketogenic formats. |
| Grass-Fed Dairy Backward Integration | Secures ghee margin pools through captive supply of cultured differentiation inputs. |
Research Methodology
Desk research of FDA guidance documents, USDA organic certification databases, and EFSA health claim registers preceded structured interviews with ketogenic protocol clinicians, CPG brand managers, contract manufacturing procurement leads, and specialty retail category buyers. Secondary validation drew from supermarket scanner data, direct-to-consumer platform analytics, and customs import records for avocado and coconut oil shipments. Bottom-up segment sizing triangulated against top-down category spend estimates.
Assumption sets held FDA saturated fat guidance trajectory and ketogenic dietary adherence rates fixed while varying Mexican avocado harvest yields, freight corridor cost structures, and mass-market grocer SKU absorption timing. Segmentation dimensions modeled include lipid category, end-user metabolic goal, delivery channel, and packaging format. CAGRs derived from logistic adoption curves fitted to subscription replenishment penetration patterns and metabolic health clinic referral velocity.
Stress conditions across Mexican harvest volatility, Long Beach port congestion duration, and FDA guidance finalization timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions with revision triggers tied to regulatory publication and climate-induced yield announcements. Quarterly review of metabolic health clinic prescribing volumes and subscription churn rates in California and Texas clusters is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food & Ingredients
Multifunctional Food Ingredients Market
Functional Food & Ingredients
Japan Soy Protein Market
Functional Food & Ingredients
Superfood Powders Market
Functional Food & Ingredients
Functional Ingredients Market
Functional Food & Ingredients
Europe Omega-3 PUFA Market
Functional Food & Ingredients
Vegan DHA Market
Functional Food & Ingredients
Prebiotic Ingredients Market
Functional Food & Ingredients
Banana Leaf Extract Market
Functional Food & Ingredients
Lovage Extract Market
Functional Food & Ingredients
Global Probiotic Ingredients Market
Functional Food & Ingredients
Refined Functional Carbohydrates Market
Functional Food & Ingredients
North America Omega-3 PUFA Market
Functional Food & Ingredients
Poultry Probiotic Ingredients Market
Functional Food & Ingredients
Beta Glucan and Fucoidan Market
Functional Food & Ingredients
Asia-Pacific Omega3 PUFA Market
Functional Food & Ingredients
North America and Europe Medical Foods Market