
 Refined Functional Carbohydrates Market | 2026-2036
Refined Functional Carbohydrates Market Size, Share, and Industry Trends Forecast 2026-2036
Refined Functional Carbohydrates Market Analysis
Asset-light toll manufacturing and third-party bioprocessing leases is narrowing the capital barrier for mid-tier entrants in refined functional carbohydrates. DuPont Danisco leverages its multi-region fermentation infrastructure to sustain supply continuity across nutraceutical and pharmaceutical grades. EW Nutrition anchors its competitive position through deep specialization in animal-specific oligosaccharide formulations. Lallemand competes by extending its yeast-derived beta-glucan expertise into adjacent prebiotic categories.
Refined functional carbohydrates are highly purified polysaccharide and oligosaccharide fractions, typically achieving degrees of polymerization between 2 and 20 units, manufactured through controlled enzymatic hydrolysis or solvent extraction followed by chromatographic refinement for targeted physiological activity. These ingredients modulate gut microbiota composition, enhance mineral bioavailability, and improve texture and stability in formulated products across human and animal nutrition. Oligosaccharides and inulin together command the dominant share of value generation, with resistant starch representing the fastest-expanding application base in clinical nutrition and glycemic management formulations. Dextrins retain mature, volume-driven positioning in sports nutrition and enteral feeding, where margin compression from commodity maltodextrin alternatives constrains premium capture.
EFSA novel food authorizations and REACH substance registrations shape product development timelines and market access conditions for European suppliers, while FDA GRAS self-affirmation pathways govern US commercialization speed for new oligosaccharide variants. The EU Green Deal decarbonization mandates and national packaging waste directives are pressing manufacturers toward enzymatic rather than chemical refinement routes to secure production site permits. Stakeholders must monitor evolving microbiome health claim substantiation standards across multiple jurisdictions to anticipate which functional carbohydrate categories will retain premium positioning versus commoditization pressure.
Market Dynamics
EU F-Gas Regulation and REACH compliance requirements are forcing animal feed formulators toward enzymatic refinement routes, compressing capital recovery timelines for solvent-based extraction assets and reshaping supplier qualification criteria across the value chain.
Growth Catalysts
- Regulatory phase-out of antibiotic growth promoters:The EU's ban on zinc oxide and AGPs in piglet diets accelerates prebiotic oligosaccharide substitution in compound feed formulations across Germany, Spain, and Poland.
- Enzymatic hydrolysis technology maturation:Controlled enzymatic processes now achieve degrees of polymerization precision that chromatographic methods cannot match, enabling pharmaceutical-grade purity at nutraceutical cost structures.
- Clinical nutrition demand concentration:Resistant starch applications in glycemic management formulations are expanding fastest in German hospital nutrition contracts and Dutch elderly care institutional procurement.
Market Restraints
- Chromatographic resin input cost volatility:Specialty resins for oligosaccharide fractionation face supply concentration from Japanese and Korean chemical suppliers, creating margin squeeze during petrochemical feedstock price spikes.
- EFSA novel food authorization timelines:The 18-24 month safety assessment window for new oligosaccharide variants delays commercialization and ties up R&D capital without revenue offset.
- Commodity maltodextrin substitution pressure:Sports nutrition formulators in price-sensitive segments increasingly substitute refined dextrins with unmodified maltodextrin, eroding premium positioning in volume-driven applications.
Strategic Opportunities
- Pet nutrition premiumization in Germany:Hamburg and Lower Saxony clusters of specialty pet food manufacturers seek gut microbiota modulation claims for high-margin therapeutic diets, creating white space for species-specific oligosaccharide blends.
- EU Green Deal decarbonization incentives:National packaging waste directives and production site permit conditions favor enzymatic over chemical refinement, rewarding early capital redeployment with faster regulatory approval.
- Third-party bioprocessing lease expansion:Asset-light toll manufacturing models reduce capital barriers for mid-tier entrants seeking multi-region fermentation infrastructure without captive facility investment.
Industry Challenges
- Microbiome health claim substantiation skill gaps:The intersection of clinical trial design, metagenomic analysis, and regulatory dossier preparation requires scarce cross-functional expertise that outstrips current talent pipelines.
- Legacy solvent extraction asset stranded risk:Plants configured for chemical purification face costly retrofit or write-down decisions as enzymatic routes secure preferential permitting under EU environmental mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refined Functional Carbohydrates Market |
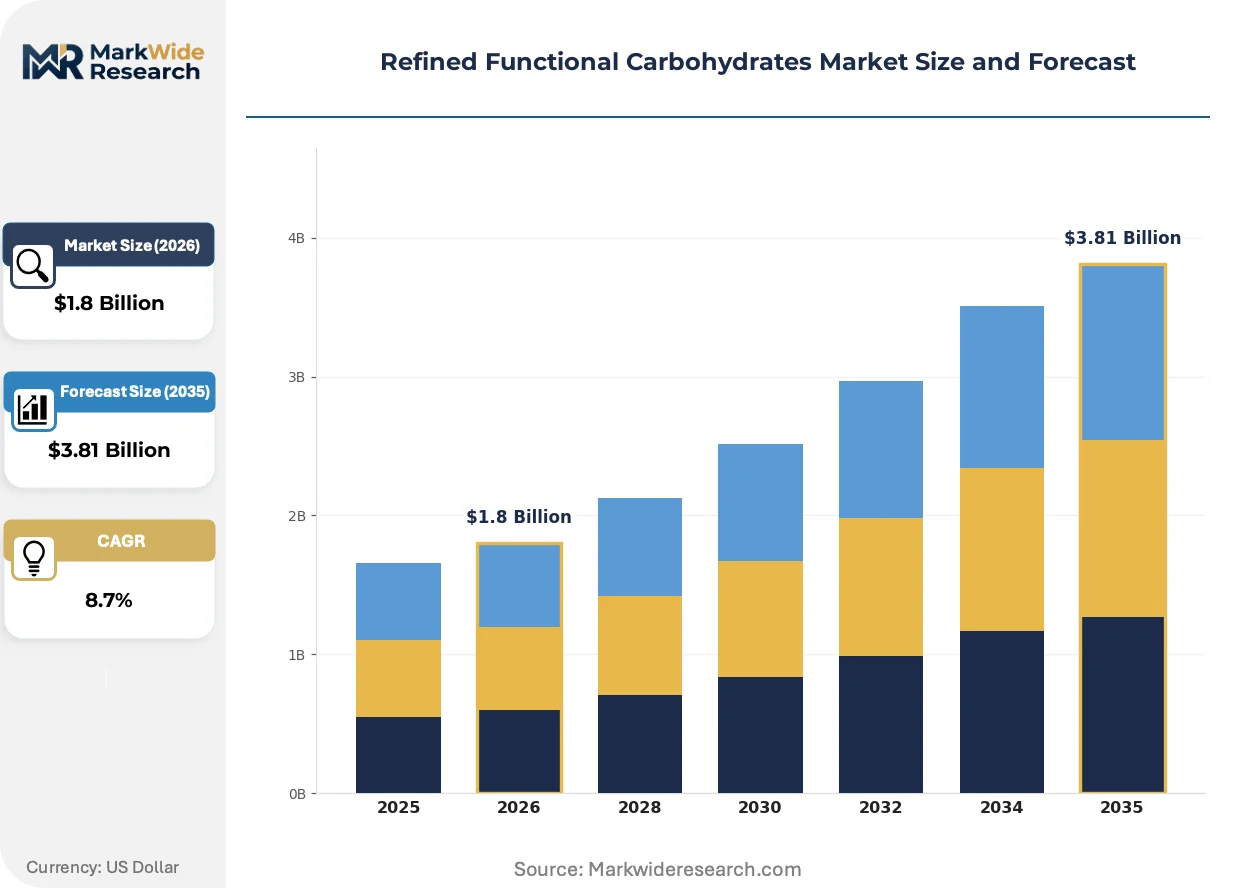
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oligosaccharides, Inulin, Resistant Starch, Dextrins Application: Food & Beverages, Nutraceuticals, Pharmaceuticals, Animal Feed End User: Food Manufacturers, Dietary Supplement Brands, Restaurants, Healthcare Institutions Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Sweet Cures, DuPont Danisco, EW Nutrition, Pet Health Solutions, Lallemand, Orffa, Super Beta Glucan, VWR Corporation, Danisco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refined Functional Carbohydrates Market Emerging Trajectories
Enzymatic refinement technologies are displacing legacy solvent extraction across pharmaceutical and nutraceutical grade production, while regulatory pressure on carbon intensity reshapes site selection and process chemistry choices.
Membrane filtration-coupled enzymatic systems is hybridizing precision bioprocessing with continuous manufacturing architectures. Pharmaceutical-grade oligosaccharide producers in Germany and Switzerland are adopting these hybrid systems at pilot scale. The technology is hybridizing batch-to-continuous transitions that compress purification cycle times from days to hours while maintaining EFSA-compliant purity thresholds.
REACH substance registration requirements are tightening purity documentation and toxicological dossier standards for imported oligosaccharide intermediates. The regulation forces non-EU suppliers to establish EU-based representative offices or joint-venture partnerships for market access. German compound feed producers are responding by consolidating supplier qualification around REACH-registered domestic and near-shore sources.
Direct contracting between oligosaccharide refiners and large animal nutrition integrators is displacing traditional distributor intermediaries in volume applications. Dutch and Danish pig and poultry integrators now negotiate multi-year supply agreements specifying enzymatic origin and carbon footprint certification. This channel compression is most visible in the Benelux region, where three feed compounders account for majority volume and have internalized technical specification authority previously held by distributors.
Refined Functional Carbohydrates Market Segmentation
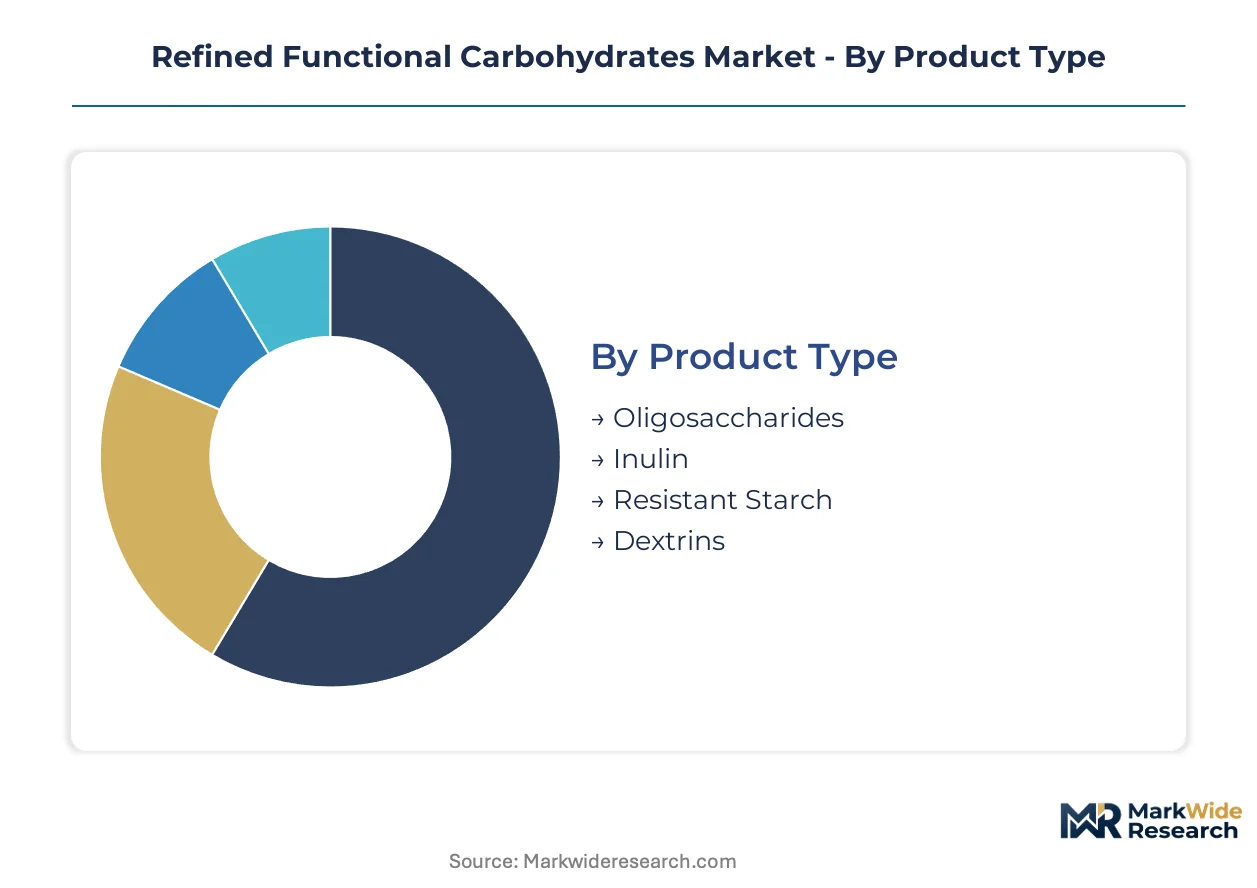
Segmentation in refined functional carbohydrates separates volume-driven commodity grades from premium pharmaceutical and nutraceutical specifications. Product chemistry, end-use performance requirements, and regulatory compliance tiers determine pricing power and supplier qualification barriers across each category.
Product Type:
Mature polysaccharide categories dominate current revenue, while enzymatically refined oligosaccharides represent the emerging technology frontier reshaping purity benchmarks.
- Oligosaccharides:Prebiotic fractions with degrees of polymerization between 2 and 10 units, manufactured through controlled enzymatic hydrolysis. German compound feed producers and Dutch clinical nutrition formulators drive demand concentration as EFSA novel food authorizations expand permissible health claim categories.
- Inulin:Long-chain fructan polysaccharides extracted from chicory root or synthesized enzymatically, valued for fat replacement and fiber fortification. Hamburg-based pet nutrition specialists and Belgian bakery ingredient manufacturers anchor procurement volumes under tightening EU Green Deal carbon accounting requirements.
- Resistant Starch:Amylose-rich fractions resisting small intestine digestion, targeting glycemic management applications.
- Dextrins:Partially hydrolyzed starch polymers serving as encapsulation matrices and rapid-energy carbohydrate sources.
Oligosaccharides handle the majority of throughput; resistant starch is the fastest mover on share.
Application:
Application segmentation tracks the divergence between regulated health claim environments and commodity food processing specifications.
- Food & Beverages:Texture modification, sugar reduction, and clean-label fiber fortification in processed foods. German bakery and dairy manufacturers represent the largest procurement base, though margin compression from maltodextrin substitution limits premium capture in volume segments.
- Nutraceuticals:Prebiotic supplements and microbiome-targeted formulations requiring EFSA-compliant substantiation dossiers. Swiss and German contract manufacturers concentrate demand for pharmaceutical-grade oligosaccharide fractions with documented degrees of polymerization precision.
- Pharmaceuticals:Excipient and active pharmaceutical ingredient applications demanding REACH-registered purity documentation.
- Animal Feed:AGP replacement prebiotics in piglet and poultry diets under EU zinc oxide and antibiotic growth promoter bans.
Animal feed commands the steepest expansion trajectory; food and beverages retains the largest volume position.
End User:
End user segmentation reflects procurement sophistication tiers, from technical specification authority in institutional buyers to price-driven spot purchasing in food service.
- Food Manufacturers:Large-scale compounders and private-label producers with internal R&D capabilities. Benelux and German integrated food companies negotiate multi-year supply agreements specifying enzymatic origin and carbon footprint certification.
- Dietary Supplement Brands:Mid-tier nutraceutical marketers dependent on toll manufacturers for formulation expertise. Direct contracting with oligosaccharide refiners is displacing traditional distributor intermediaries as technical specification authority consolidates.
- Restaurants:Limited penetration due to ingredient cost sensitivity and lack of health claim communication pathways.
- Healthcare Institutions:Hospital nutrition and elderly care procurement in Germany and the Netherlands driving resistant starch demand for glycemic management protocols.
Food manufacturers handle the majority of throughput; healthcare institutions are climbing the fastest on share.
Distribution Channel:
Channel segmentation tracks the compression of intermediary layers as large end users internalize technical specification authority.
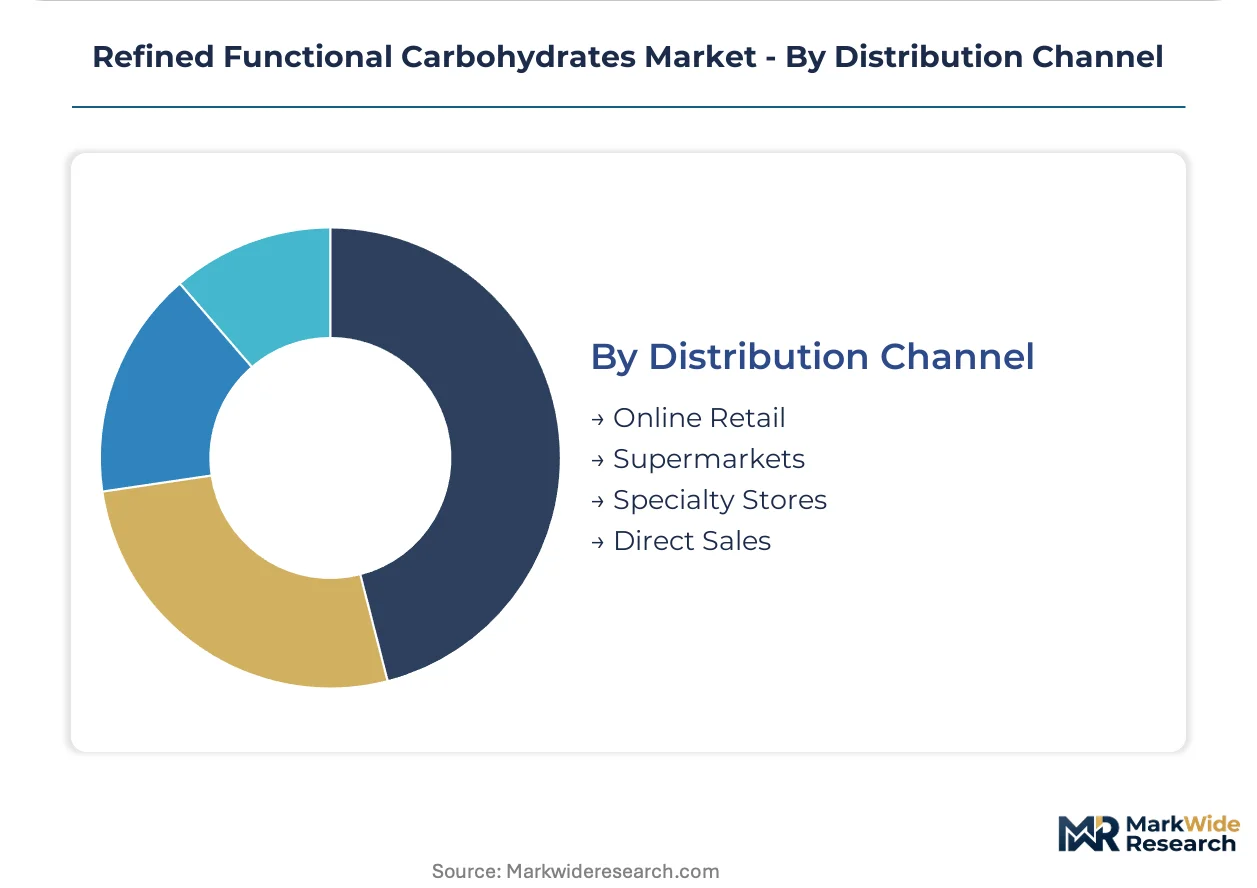
- Direct Sales:Multi-year supply agreements between refiners and large animal nutrition integrators or pharmaceutical contract manufacturers. Dutch and Danish pig and poultry integrators specify enzymatic origin and REACH registration status in procurement contracts.
- Specialty Stores:Regional ingredient distributors serving mid-tier food manufacturers without captive technical staff.
- Supermarkets:Minimal penetration for bulk refined carbohydrates; limited to small-package prebiotic supplements.
- Online Retail:Emerging channel for dietary supplement brands targeting direct-to-consumer microbiome health positioning.
Direct sales handles the majority of throughput; online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation and REACH compliance are redrawing production site economics across major manufacturing jurisdictions. National packaging waste directives and decarbonization mandates now determine where enzymatic refinement capacity expands versus where legacy solvent assets face stranded risk.
Germany
Compound feed producers around Hamburg and Lower Saxony drive prebiotic oligosaccharide procurement for piglet diet reformulation. EFSA novel food authorization standards shape product development timelines for domestic refiners. Bavarian pharmaceutical-grade manufacturers pilot membrane filtration-coupled enzymatic systems to compress purification cycles.
United States
FDA GRAS self-affirmation pathways accelerate commercialization timelines for new oligosaccharide variants versus European regulatory windows. Sports nutrition formulators in the Mountain West and Pacific Northwest substitute refined dextrins with commodity maltodextrin in price-sensitive segments. Toll manufacturing clusters in the Midwest leverage asset-light models to serve mid-tier dietary supplement brands.
China
Dual carbon goals and MEE environmental enforcement push coastal refiners toward enzymatic routes over solvent extraction. Yangtze River Delta chemical parks face permit restrictions that favor bioprocessing investments. REACH registration requirements for EU market access force establishment of representative offices in Germany and the Netherlands.
Netherlands
Dutch pig and poultry integrators negotiate multi-year supply agreements specifying enzymatic origin and carbon footprint certification. Benelux feed compounders have internalized technical specification authority previously held by distributor intermediaries. Rotterdam-area logistics hubs consolidate procurement for resistant starch applications in elderly care institutional nutrition.
Switzerland
Swissmedic pharmaceutical-grade standards attract contract manufacturers seeking documented degrees of polymerization precision. Basel-region chemical clusters host pilot-scale hybrid membrane-enzymatic systems for clinical nutrition applications. Swiss toll manufacturers serve German and French nutraceutical brands requiring EFSA-compliant substantiation dossiers.
Refined Functional Carbohydrates Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered qualification barriers. Large animal nutrition integrators and pharmaceutical contract manufacturers now hold technical specification authority that distributors previously controlled. Three archetypes dominate: multi-region fermentation infrastructure operators, species-specific formulation specialists, and yeast-derived expertise extenders. Competitive moves concentrate on strategic partnerships for REACH registration coverage and capacity expansion into enzymatic refinement routes.
Within the multi-region infrastructure tier, DuPont Danisco anchors supply continuity capabilities across nutraceutical and pharmaceutical grades. EW Nutrition occupies a position in animal-specific oligosaccharide formulation depth. Lallemand exemplifies the yeast-derived expertise extension archetype, translating beta-glucan knowledge into adjacent prebiotic positioning. These three represent distinct strategic postures rather than direct substitution competitors.
| Leading Market Players |
|---|
| Sweet Cures |
| DuPont Danisco |
| EW Nutrition |
| Pet Health Solutions |
| Lallemand |
| Orffa |
| Super Beta Glucan |
| VWR Corporation |
| Danisco |
| Others |
Supply Flow & Price Mechanics
Underutilized enzymatic refinement capacity in Germany's Lower Saxony chemical parks is compressing spot pricing for pharmaceutical-grade oligosaccharides while simultaneously accelerating contract renegotiations toward longer-term offtake structures. This utilization dynamic rewards REACH-registered domestic suppliers with pricing power over import-dependent competitors facing extended qualification timelines.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade and feed-grade oligosaccharides, with EFSA novel food authorization and REACH registration status commanding premiums of 40-60% over unregistered alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by enzymatic purity documentation and carbon footprint certification, with Dutch and Danish animal nutrition integrators least price-sensitive due to multi-year supply security requirements. Cost compression in sports nutrition dextrins is intensifying because commodity maltodextrin substitution erodes premium capture in volume-driven segments.
Supply Chain Analysis
Toll manufacturing concentration in Germany's Hamburg-Bremen corridor and Switzerland's Basel region anchors pharmaceutical-grade oligosaccharide supply, with DuPont Danisco's multi-region fermentation infrastructure and EW Nutrition's species-specific formulation facilities representing critical capacity nodes. Raw material dependencies center on chicory root inulin from Belgium, chromatographic resins from Japanese and Korean chemical suppliers, and specialty enzyme preparations from Danish biotech sources. Single-source vulnerability in chromatographic resin supply creates margin squeeze exposure during petrochemical feedstock volatility. Distribution runs through direct contracting between refiners and large animal nutrition integrators, displacing traditional distributor intermediaries in volume applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through EFSA novel food authorization and REACH substance registration constructs formidable defensive moats, as 18-24 month approval timelines and toxicological dossier requirements strand capital for unqualified competitors.
For Market Incumbents: Harden supply continuity through backward integration into captive enzyme production and multi-region fermentation redundancy, countering the threat of stranded solvent-extraction assets under EU F-Gas Regulation. Prioritize certification investment in carbon footprint documentation to capture Dutch and Danish integrator procurement specifications. For New Entrants and Emerging Players: Mid-tier pet nutrition formulators in Hamburg and Lower Saxony represent the most penetrable entry point, as species-specific oligosaccharide blends for therapeutic diets remain undersupplied relative to demand growth. Asset-light toll manufacturing partnerships with Swiss or German contract manufacturers offer the lowest-capital go-to-market angle for REACH registration coverage. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among enzymatic refinement specialists with captive pharmaceutical-grade certification, as multi-year supply agreements with animal nutrition integrators lock in offtake visibility. Long-term viability across the projection horizon favors acquisition targets with demonstrated EFSA dossier preparation capabilities and established representative offices in Germany for EU market access. The signal to watch is consolidation velocity among Benelux feed compounders internalizing technical specification authority.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Refinement Capacity Expansion | EU Green Deal decarbonization mandates favor bioprocessing investments over solvent extraction in German chemical parks. |
| REACH Registration Coverage Partnership | Joint-venture structures enable non-EU suppliers to establish EU-based representative offices for market access compliance. |
| Species-Specific Formulation Development | Hamburg pet nutrition specialists seek gut microbiota modulation claims for high-margin therapeutic diet applications. |
| Membrane Filtration Technology Adoption | Hybrid membrane-enzymatic systems compress purification cycle times from days to hours at Swissmedic-grade facilities. |
| Direct Contracting Channel Compression | Dutch and Danish integrators now negotiate multi-year agreements specifying enzymatic origin and carbon certification. |
Methodological Framework
Initial hypotheses were tested against primary input from compound feed procurement managers, pharmaceutical contract manufacturing executives, regulatory affairs specialists at EFSA-registered firms, and toll manufacturing operators in Germany and Switzerland, then refined through secondary validation against customs trade data, EFSA novel food authorization registers, REACH substance registration databases, and SEC filings of listed ingredient suppliers. Bottom-up volume triangulation across enzymatic refinement capacity and top-down value estimation through pricing tier analysis were cross-referenced for convergence.
Demand-supply-balance framing anchored the analytical approach across the analysis window, with segmentation modeled by product chemistry (oligosaccharides, inulin, resistant starch, dextrins), application tier (pharmaceutical, nutraceutical, animal feed, food and beverage), and regulatory compliance grade (EFSA-authorized, REACH-registered, commodity). CAGRs were derived from installed capacity expansion timelines and substitution elasticity estimates for antibiotic growth promoter replacement in EU piglet diets.
Macroeconomic conditions sit as an overlay; deviation in energy cost trajectories and petrochemical feedstock pricing would shift the trajectory of enzymatic versus solvent-based refinement economics. Forecasts reflect documented assumptions regarding regulatory authorization timelines and carbon accounting implementation schedules. Quarterly review of EFSA novel food authorization pipeline velocity and Benelux feed compounder consolidation indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food & Ingredients
Africa Omega-3 PUFA Market
Functional Food & Ingredients
Mediterranean Cognitive-First Ingredient Systems Market
Functional Food & Ingredients
Functional Non-Meat Ingredients Market
Functional Food & Ingredients
Brazil Flavored and Functional Water Market
Functional Food & Ingredients
Functional Food Ingredients Market
Functional Food & Ingredients
Italy Protein Market
Functional Food & Ingredients
Prebiotic Ingredients Market
Functional Food & Ingredients
APAC Heart Health Functional Food Market
Functional Food & Ingredients
Europe Botanical Extract Market
Functional Food & Ingredients
Global Whole Grain and High Fiber Food Market
Functional Food & Ingredients
Omega 3 PUFA Market
Functional Food & Ingredients
Multifunctional Food Ingredients Market
Functional Food & Ingredients
Europe Omega-3 PUFA Market
Functional Food & Ingredients
Europe Sterol Market
Functional Food & Ingredients
Africa Algae Omega-3 Ingredients Market
Functional Food & Ingredients
Mediterranean Pre-Diabetes Ingredient Concepts Market