
 Combo Chip Market | 2026-2036
Combo Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Combo Chip Market Outlook
Multi-protocol bundling in single-package connectivity solutions is realigning procurement patterns across mobile and IoT device makers. Qualcomm leverages its modem-RF integration to dominate premium smartphone sockets. Samsung Electronics anchors memory-plus-logic stacking through advanced packaging investments. Winbond Electronics Corporation specializes in low-pin-count combo solutions for cost-constrained industrial segments.
A combo chip integrates multiple semiconductor functions—such as microcontrollers, wireless transceivers, and power management—into a monolithic or multi-chip package, typically fabricated on 40nm to 7nm process nodes depending on performance targets. System on Chip variants command the widest design-in footprint across consumer electronics, while Bluetooth-plus-Wi-Fi connectivity configurations capture accelerating share in smart home and wearable applications. OEM direct procurement from foundries is displacing traditional distributor channels for high-volume automotive programs.
FCC certification requirements govern radio-frequency emissions for Wi-Fi and Bluetooth combo chips sold into the US, while REACH and RoHS frameworks restrict hazardous substance use in European-bound shipments. The EU AI Act and emerging MDR-like traceability standards for automotive semiconductors are tightening documentation burdens on Tier-1 Suppliers. Stakeholders must weigh captive foundry investments against fabless flexibility as process node transitions accelerate.
Market Dynamics
Multi-protocol integration is compressing design cycles as smartphone OEMs demand single-package solutions combining Wi-Fi, Bluetooth, and UWB radios. This consolidation is forcing foundries to retool 40nm and 28nm lines for mixed-signal density while navigating stricter EU F-Gas emissions rules on etching chemistry.
Growth Catalysts
- EU F-Gas Regulation:Semiconductor fabs in Germany and France are accelerating migration to fluorinated-gas-free etching processes, opening procurement windows for dry-etch equipment vendors serving combo chip production lines.
- Smart home device proliferation:Matter protocol certification is standardizing Thread-plus-Wi-Fi-plus-Bluetooth configurations, pulling silicon volume toward unified connectivity stacks in thermostats and lighting controllers.
- South Korea foundry corridor:Pyeongtaek and Seoul concentration of advanced packaging capacity is anchoring memory-plus-logic stacking investments for premium smartphone combo chips.
Market Restraints
- Advanced substrate cost volatility:ABF substrate pricing swings are compressing gross margins on high-I/O count fan-out packages used in automotive-grade combo modules.
- Photoresist supply concentration:Japanese chemical suppliers dominate EUV and DUV photoresist production, creating single-source vulnerability for 7nm and below combo chip tape-outs.
- Legacy node equipment scarcity:Depreciation schedules for 40nm and 28nm foundry tools are extending as demand for mature-node combo solutions outpaces new equipment installation.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for semiconductor assembly and testing are attracting packaging investments for cost-optimized Bluetooth-plus-Wi-Fi modules targeting domestic smartphone assembly.
- Automotive zonal architecture:Domain controller consolidation is creating sockets for multi-protocol combo chips replacing discrete CAN, LIN, and Ethernet transceivers in cabin connectivity modules.
- UWB-Bluetooth convergence:Precise positioning requirements in asset tracking and digital key applications are fusing ultra-wideband and Bluetooth Low Energy into single-die solutions.
Industry Challenges
- RF front-end integration complexity:Co-design of power amplifiers, filters, and switches with baseband logic is stretching analog-digital mixed-signal engineering talent pools in Taiwan and South Korea.
- Matter certification timelines:Multi-vendor interoperability testing for smart home combo chips is extending qualification cycles by four to six months versus proprietary protocol stacks.
- Legacy automotive bus migration:Tier-1 suppliers face software revalidation burdens when replacing proven discrete transceivers with consolidated combo solutions in safety-critical body electronics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Combo Chip Market |
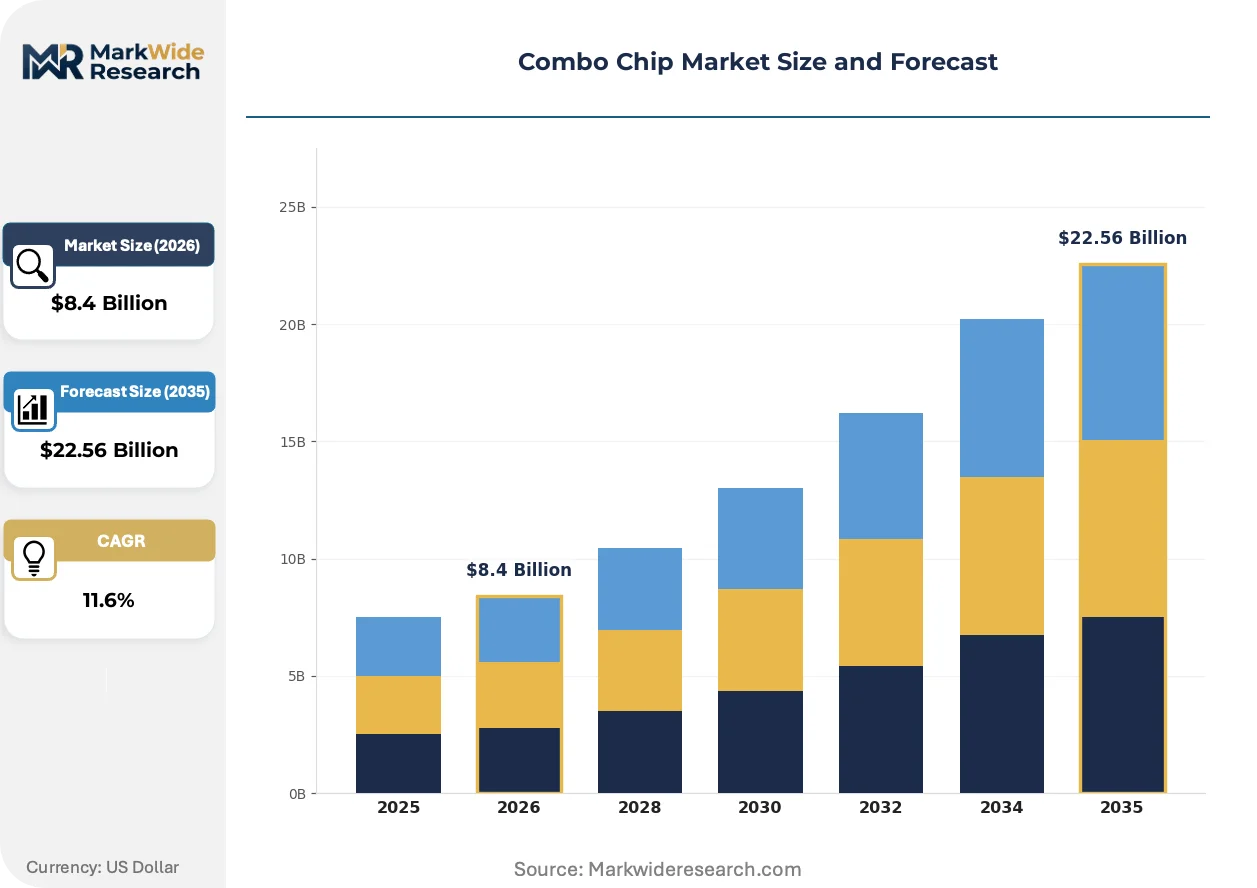
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $22.56 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontrollers, System on Chip, Digital Signal Processors, Application Specific Integrated Circuit Connectivity: Wi-Fi, Bluetooth, Zigbee, NFC Application: Consumer Electronics, Automotive, Industrial Automation, Smart Home End User: OEMs, Tier-1 Suppliers, Distributors, Aftermarket Providers |
| Companies Covered | Infineon Technologies, Integrated Silicon Solution, Kingston Technology, Macronix International, Micron Technology, Winbond Electronics Corporation, Intel, Qualcomm, Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Combo Chip Market Strategic Shifts
Silicon architecture is pivoting toward heterogeneous integration as analog, digital, and RF functions merge into unified packages. This convergence is compressing board area requirements while elevating thermal management and electromagnetic coexistence engineering to critical design priorities.
Chiplet-based disaggregation is electrifying combo chip roadmaps by separating RF transceivers, baseband processors, and memory into optimized process nodes then reassembling through 2.5D interposers. Smartphone OEMs in South Korea and China are adopting this approach for flagship models, enabling faster IP refresh cycles without full retape-outs. The structural consequence is a bifurcation between premium chipletted solutions and monolithic cost-optimized variants.
Europe's F-Gas Regulation is mandating fluorinated greenhouse gas reductions of two-thirds by 2030 from 2014 baselines, compelling foundries in Dresden and Leuven to qualify plasma etching chemistries with lower global warming potential. Equipment suppliers are responding with dry-etch process modules compatible with nitrogen trifluoride alternatives. Memory-plus-logic combo production in EU-based fabs faces the steepest compliance cost curves.
Direct foundry contracting is displacing traditional semiconductor distribution for automotive combo chip programs above one million units annually. OEMs in Germany and Japan are establishing dedicated supplier quality engineering teams at TSMC and Samsung facilities, bypassing Arrow and Avnet for volume pricing and lot traceability. This channel compression is most advanced in battery electric vehicle platforms where zonal gateway sockets require automotive-grade Bluetooth and Ethernet combo solutions.
Combo Chip Market Segmentation
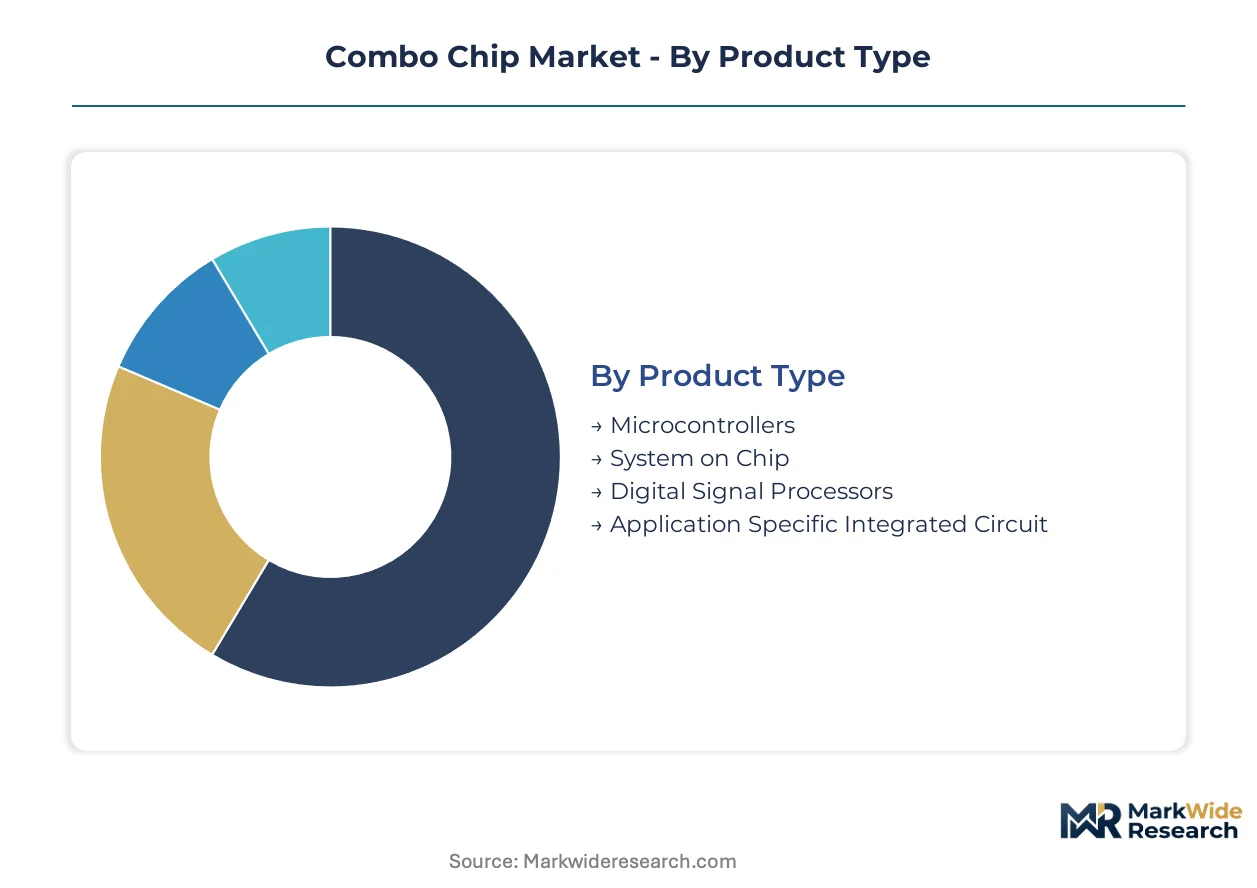
Combo chip procurement patterns diverge sharply between cost-optimized consumer volumes and performance-critical automotive sockets. Process node selection, packaging complexity, and certification requirements create distinct commercial profiles across each segment boundary.
Product Type:
Volume concentration clusters at mature nodes where analog-digital integration dominates unit economics, while premium tiers chase advanced packaging density.
- System on Chip:Integrates CPU, GPU, memory controller, and specialized accelerators onto unified die architectures fabricated at 7nm to 5nm for flagship smartphones. South Korean OEMs anchor procurement through captive foundry arrangements at Pyeongtaek facilities, though EU F-Gas compliance costs are compressing margins on European-bound shipments.
- Microcontrollers:Combine processing cores with embedded flash and power management on 40nm to 28nm nodes, optimized for deterministic real-time response in automotive body controllers. German Tier-1 suppliers are consolidating procurement through direct foundry contracts at TSMC and GlobalFoundries Dresden, bypassing traditional distribution channels for programs exceeding one million units annually.
- Digital Signal Processors:Purpose-built arithmetic engines for audio codec and sensor fusion workloads in noise-canceling wearables and industrial vibration monitors.
- Application Specific Integrated Circuit:Custom-masked logic for single-function optimization in high-volume consumer peripherals where unit cost trumps flexibility.
Mature deployment sits with Microcontrollers in legacy automotive architectures. Newer deployment is concentrated in System on Chip variants for smartphone flagship cycles.
Connectivity:
Protocol bundling density determines socket access, with dual-radio solutions commanding baseline volumes and triple-radio configurations capturing smart home standardization tailwinds.
- Bluetooth:Low-energy transceivers dominate wearable and peripheral attach rates through 2.4GHz spectrum efficiency, with Apple and Samsung driving proprietary ecosystem lock-in through codec optimization. FCC certification timelines for RF coexistence testing are extending qualification cycles by four to six months versus single-radio alternatives.
- Wi-Fi:6E and 7 implementations at 6GHz unlock bandwidth for 4K streaming and low-latency gaming in premium smartphone and tablet sockets. South Korean foundry corridors around Seoul are concentrating 7nm RF-CMOS production for flagship handset programs, though ABF substrate cost volatility is compressing margins on high-I/O fan-out packages.
- Zigbee:Mesh networking stack for utility-scale smart meter deployments and commercial lighting control systems requiring sub-GHz penetration.
- NFC:Secure element integration for contactless payment and digital key applications in automotive door handles and point-of-sale terminals.
Bluetooth anchors the highest unit volumes through peripheral proliferation. Wi-Fi 6E/7 variants are climbing the fastest through premium smartphone refresh cycles.
Application:
End-use differentiation separates consumer price sensitivity from industrial reliability premiums and automotive safety-critical compliance burdens.
- Consumer Electronics:Smartphones, tablets, and wearables drive the largest absolute silicon consumption through annual refresh cycles and multi-radio integration. Chinese OEMs are accelerating procurement of Bluetooth-plus-Wi-Fi-plus-UWB combo solutions for precise positioning in digital key and asset tracking applications.
- Automotive:Zonal architecture consolidation is replacing discrete CAN, LIN, and Ethernet transceivers with multi-protocol gateway modules. KBA documentation requirements and emerging MDR-like traceability standards are tightening qualification burdens on German Tier-1 suppliers migrating from proven discrete solutions to consolidated combo chips.
- Industrial Automation:Harsh-environment rated modules for predictive maintenance sensors and robotic motor controllers requiring extended temperature ranges.
- Smart Home:Matter protocol certification is standardizing Thread-plus-Wi-Fi-plus-Bluetooth configurations in thermostats and lighting controllers, pulling silicon toward unified connectivity stacks.
Consumer Electronics commands established procurement scale. Automotive applications are expanding most quickly through electrification platform ramps.
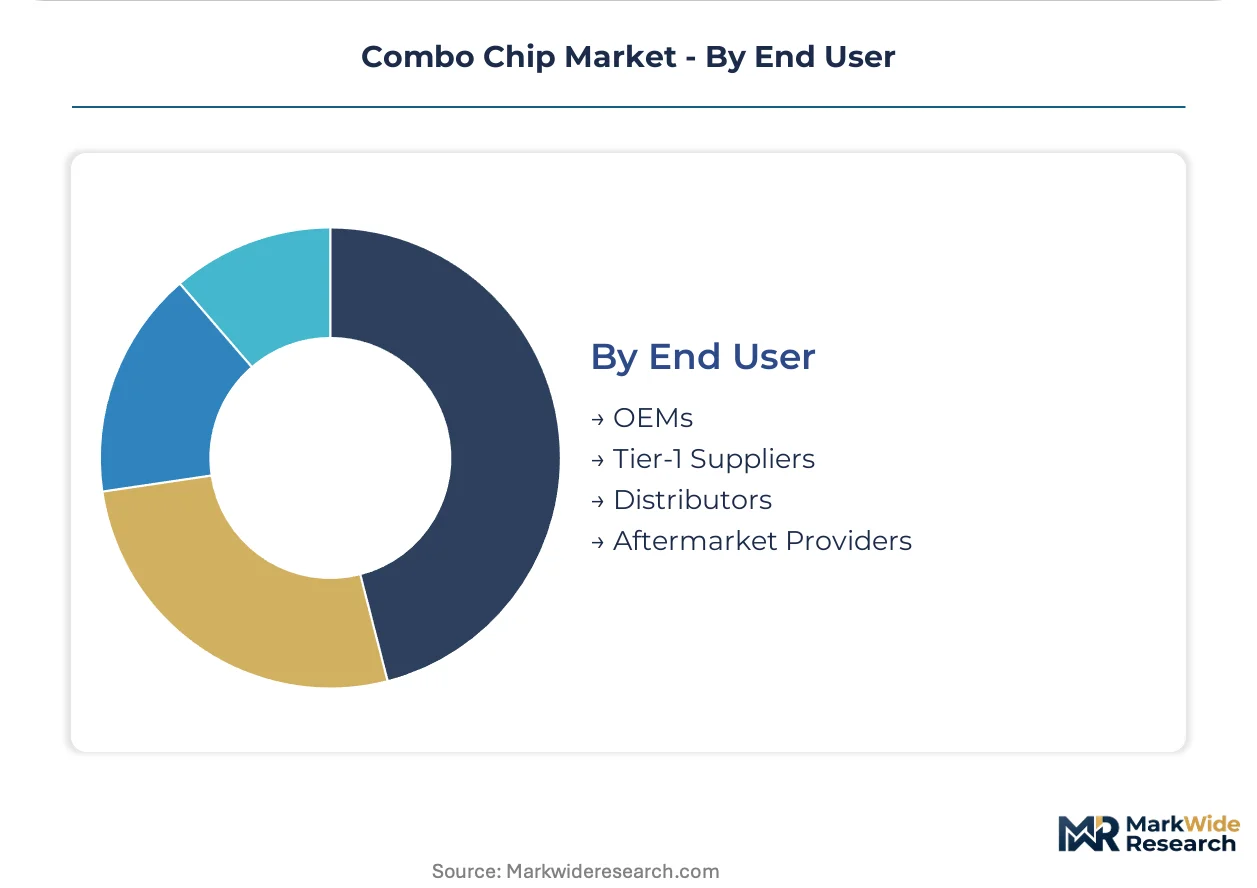
End User:
Channel structure bifurcates between high-volume direct foundry contracting and fragmented distributor-served长尾 programs.
- OEMs:Apple, Samsung, and automotive manufacturers above one million units annually are establishing dedicated supplier quality engineering teams at foundry facilities, securing lot traceability and volume pricing through bypass of Arrow and Avnet. This channel compression is most advanced in battery electric vehicle platforms.
- Tier-1 Suppliers:Continental, Bosch, and Denso face software revalidation burdens when replacing discrete transceivers with consolidated combo solutions in safety-critical body electronics, extending design-in cycles.
- Distributors:Arrow Electronics and Avnet retain relevance for mid-volume industrial and aftermarket programs below direct-foundry thresholds.
- Aftermarket Providers:Telematics retrofit and infotainment upgrade modules serving vehicle aging fleets and commercial fleet management systems.
OEM direct contracting dominates premium smartphone and high-volume automotive sockets. Distributor channels persist in fragmented industrial and aftermarket tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul's Pyeongtaek special economic zone anchors foundry concentration for memory-plus-logic stacking investments. German industrial clusters drive automotive-grade combo chip qualification cycles. Chinese smartphone OEMs accelerate procurement of multi-protocol connectivity modules for digital key applications.
South Korea
Samsung Electronics and domestic smartphone OEMs drive captive foundry demand for Bluetooth-plus-Wi-Fi-plus-UWB combo solutions. The country's national semiconductor regulator enforces traceability standards for automotive-bound shipments under KBA-aligned documentation requirements. Seoul and Pyeongtaek concentrate advanced packaging capacity for premium handset programs.
Germany
Continental and Bosch anchor Tier-1 procurement for zonal gateway modules replacing discrete CAN and LIN transceivers. The EU F-Gas Regulation mandates fluorinated-gas-free etching processes at Dresden fabs by 2030. Bavaria and Baden-Württemberg host quality engineering teams co-located with foundry partners for direct contracting above one million units annually.
United States
Apple and automotive OEMs establish dedicated supplier engineering presence at TSMC Arizona for lot traceability. FCC certification governs RF emissions for Wi-Fi and Bluetooth combo chips in smartphone and smart home sockets. Austin and Phoenix concentrate advanced packaging investments for flagship connectivity modules.
China
Xiaomi and Oppo accelerate flagship refresh cycles demanding 7nm RF-CMOS production for Wi-Fi 7 implementations. MIIT enforces GB standards for electromagnetic coexistence in multi-radio configurations. Shenzhen and Shanghai anchor fabless design houses and OSAT capacity for cost-optimized Bluetooth-plus-Wi-Fi modules.
India
Domestic smartphone assembly plants pull packaging investments for cost-optimized connectivity stacks under PLI scheme incentives. BIS certification requirements govern RF performance for Thread-plus-Wi-Fi-plus-Bluetooth Matter protocol modules. Karnataka and Tamil Nadu concentrate EMS capacity for smart home and wearable combo chip integration.
Combo Chip Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across distinct technology tiers. The vendor base stratifies between captive foundry operators, fabless connectivity architects, and memory-plus-logic integrators. Three archetypes dominate: IDMs with in-house fabrication, fabless designers leveraging TSMC and Samsung capacity, and OSATs specializing in heterogeneous integration. Competitive moves center on direct OEM contracting for high-volume programs and advanced packaging partnerships for chipletted solutions.
Within the fabless connectivity tier, Qualcomm and Intel exemplify modem-RF integration strategies for premium smartphone sockets. Samsung Electronics anchors the captive foundry archetype through Pyeongtaek-based memory-plus-logic stacking investments. Winbond Electronics Corporation occupies a position among low-pin-count specialists serving cost-constrained industrial segments.
| Leading Market Players |
|---|
| Infineon Technologies |
| Integrated Silicon Solution |
| Kingston Technology |
| Macronix International |
| Micron Technology |
| Winbond Electronics Corporation |
| Intel |
| Qualcomm |
| Samsung Electronics |
| Others |
Value Chain & Pricing Dynamics
Chiplet-based disaggregation is simultaneously elevating front-end mask costs and compressing back-end assembly margins as foundries retool for heterogeneous integration. This production-method transition concentrates pricing power with equipment vendors serving 2.5D interposer capacity while fragmenting margin capture across OSAT tiers.
Pricing Analysis
Short-lead-time premiums for ABF substrate constrained by Japanese chemical supplier concentration command fifteen to twenty percent markups over contract offtake pricing. Three-tier pricing structure across automotive-grade, industrial-temp, and consumer-temp certification levels separates sockets by reliability testing burden. Cost compression in mature-node microcontroller tiers is intensifying because depreciation schedules for 40nm tools are extending amid demand resurgence. Chinese smartphone OEMs exhibit highest price sensitivity through spot-market procurement of Bluetooth-plus-Wi-Fi modules, while German Tier-1 automotive suppliers accept premium pricing for KBA-traceable lot documentation.
Supply Chain Analysis
Automotive-grade qualification gating through AEC-Q100 stress testing and KBA documentation requirements restricts qualified supplier pools to incumbent IDMs and captive foundry operators. Taiwan, South Korea, and Germany anchor front-end fabrication for advanced-node RF-CMOS and mature-node mixed-signal production. Photoresist supply draws from Japanese chemical suppliers, ABF substrate from Taiwanese laminators, and EUV equipment from Dutch lithography specialists. Single-source vulnerability in EUV photoresist creates chokepoint exposure for 7nm and below tape-outs. Distribution runs through direct foundry contracting for high-volume automotive and smartphone programs above one million units annually, with Arrow and Avnet serving fragmented industrial tiers below threshold scale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
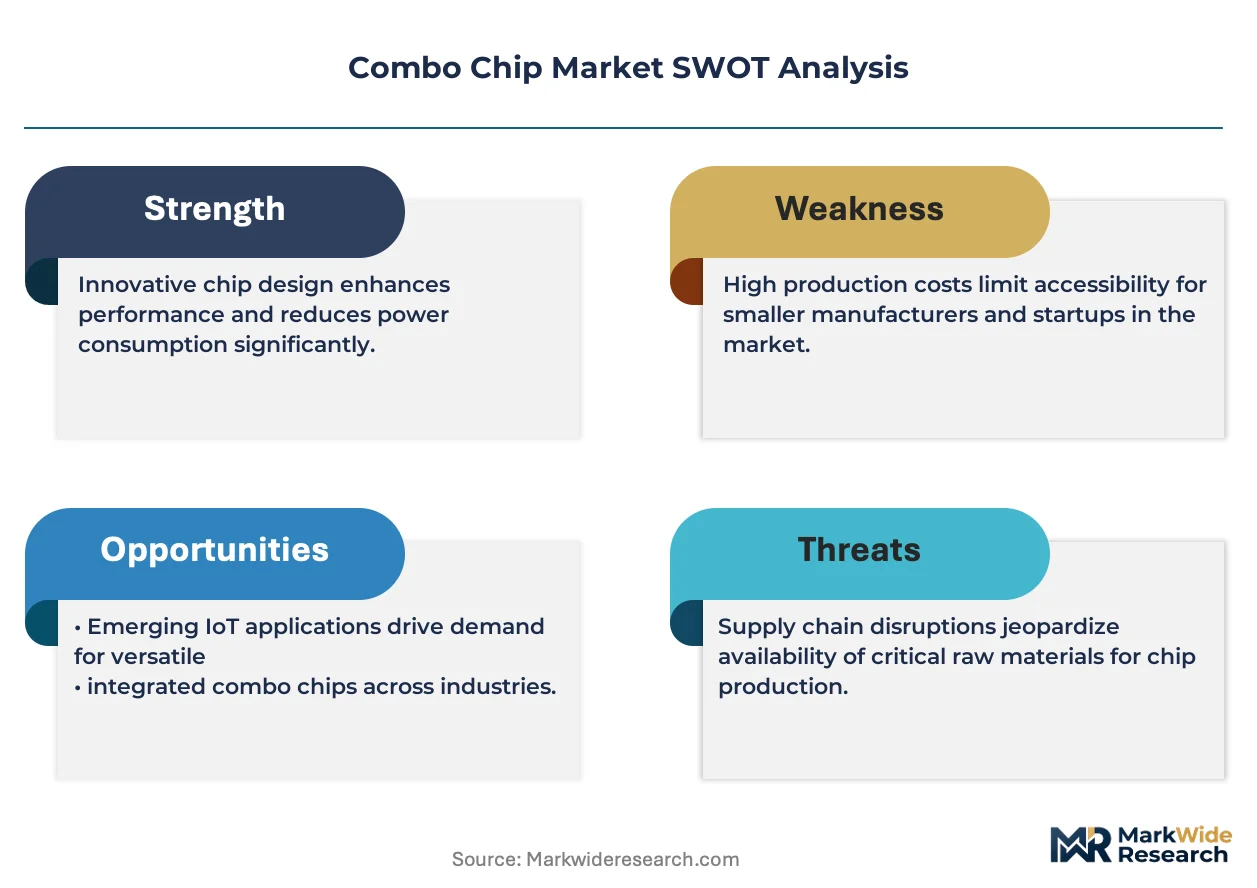
The EU F-Gas Regulation functions as a cost-of-compliance moat, elevating capital requirements for fluorinated-gas-free etching qualification and screening out undercapitalized foundry entrants from European-bound combo chip production.
For Market Incumbents: Deploy captive packaging capacity in South Korea's Pyeongtaek corridor to defend socket access against TSMC's Arizona ramp. Consolidate procurement leverage through multi-year ABF substrate offtake agreements before spot-market volatility intensifies. Reinforce automotive qualification moats by accelerating KBA-aligned traceability documentation ahead of emerging MDR-like standards. For New Entrants and Emerging Players: Mid-volume industrial automation buyers underserved by direct-foundry thresholds present the most penetrable entry vector. India's PLI-scheme packaging incentives offer tariff-advantaged assembly capacity for cost-optimized Bluetooth-plus-Wi-Fi modules. A fabless design-house model partnering with GlobalFoundries Dresden for EU F-Gas-compliant production bypasses incumbent captive foundry dominance. For Investors and Strategic Acquirers: Re-rating potential sits with heterogeneous integration specialists given chiplet architecture adoption in South Korean flagship smartphone programs. Long-term viability over a five-to-ten-year window favors OSATs with 2.5D interposer capability and automotive-grade certification infrastructure. The signal to watch is direct OEM contracting penetration rates displacing traditional distribution in battery electric vehicle zonal gateway sockets.| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Packaging Partnership | 2.5D interposer investments at Pyeongtaek secure memory-plus-logic stacking for flagship smartphone sockets. |
| Regulatory Compliance Certification | EU F-Gas-free etching qualification at Dresden fabs opens procurement windows for European automotive programs. |
| Direct Foundry Contracting | Bypassing Arrow and Avnet secures volume pricing and lot traceability for German Tier-1 suppliers above threshold scale. |
| Geographic Manufacturing Footprint | India PLI-scheme packaging investments capture cost-optimized module demand from domestic smartphone assembly plants. |
| Multi-Protocol Integration Roadmap | UWB-Bluetooth convergence addresses precise positioning requirements in digital key and asset tracking applications. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with foundry process engineers, Tier-1 supplier procurement directors, OSAT operations managers, and smartphone OEM platform architects combined with secondary validation from SEC 10-K disclosures, SEMI equipment spending reports, and EU F-Gas compliance documentation. Bottom-up unit shipment modeling and top-down value aggregation triangulated market size estimates across the analysis window.
Data-stream reconciliation across foundry capacity announcements, equipment lead times, and end-use bill-of-materials penetration rates structured the analytical framework. Segmentation dimensions modeled include product architecture, connectivity protocol bundling, application end-use, and regional production hub concentration. CAGRs were derived from slope analysis of normalized shipment trajectories, with RF front-end integration complexity and Matter certification timeline extensions serving as industry-specific forecast modifiers.
Revisions become necessary when EU F-Gas implementation timelines accelerate, ABF substrate supply disruptions materialize, or automotive zonal architecture adoption curves shift from discrete transceiver replacement forecasts. A model refresh is warranted upon material change in direct foundry contracting penetration rates or chiplet-based disaggregation adoption in premium smartphone tiers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Graphics Processing Unit (GPU) Market
Chipset and Processors
Microcontroller Unit (MCU) Market
Chipset and Processors
Optical Microcontrollers Market
Chipset and Processors
Japan Microprocessor (MPU) Market
Chipset and Processors
Automotive Battery Management System (BMS) Chip Market
Chipset and Processors
Wearable Processor Market
Chipset and Processors
Automotive Chip Market
Chipset and Processors
Hybrid Chip Market
Chipset and Processors
Nano Chip Market
Chipset and Processors
Global LCD TV Core Chip Market
Chipset and Processors
Car Chip Market
Chipset and Processors
Global Neural Processors Market
Chipset and Processors
Integrated Graphics Chipset Market
Chipset and Processors
Global ARM Microcontrollers Market
Chipset and Processors
Chiplet Technology Market
Chipset and Processors
Automotive Microcontrollers (MCU) Market