
 Artificial Intelligence (AI) Chipsets Market | 2026-2036
Artificial Intelligence (AI) Chipsets Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence (AI) Chipsets Market Intelligence
Heterogeneous computing architectures is tilting the semiconductor stack away from general-purpose processors toward domain-specific accelerators. NVIDIA Corporation dominates GPU-based training workloads through its CUDA software ecosystem. Intel Corporation leverages foundry partnerships and x86 data center installed base to defend inference market presence. Qualcomm Technologies anchors edge AI deployment with power-efficient NPU designs for on-device inference.
Artificial intelligence chipsets comprise specialized silicon—fabricated on advanced nodes such as 4nm and 3nm—engineered to execute matrix multiplication, tensor operations, and neural network inference at throughput levels unattainable by CPUs. GPU architectures currently lead training workloads due to massive parallelization capacity, while ASICs and TPUs capture hyperscaler inference demand where workload specificity permits silicon optimization. Edge computing applications represent the fastest-growing deployment vector as latency requirements push inference closer to sensors and endpoints. Deep learning technology segments command premium pricing due to computational intensity, whereas computer vision applications in smart surveillance and autonomous systems drive volume procurement from defense agencies and automotive OEMs.
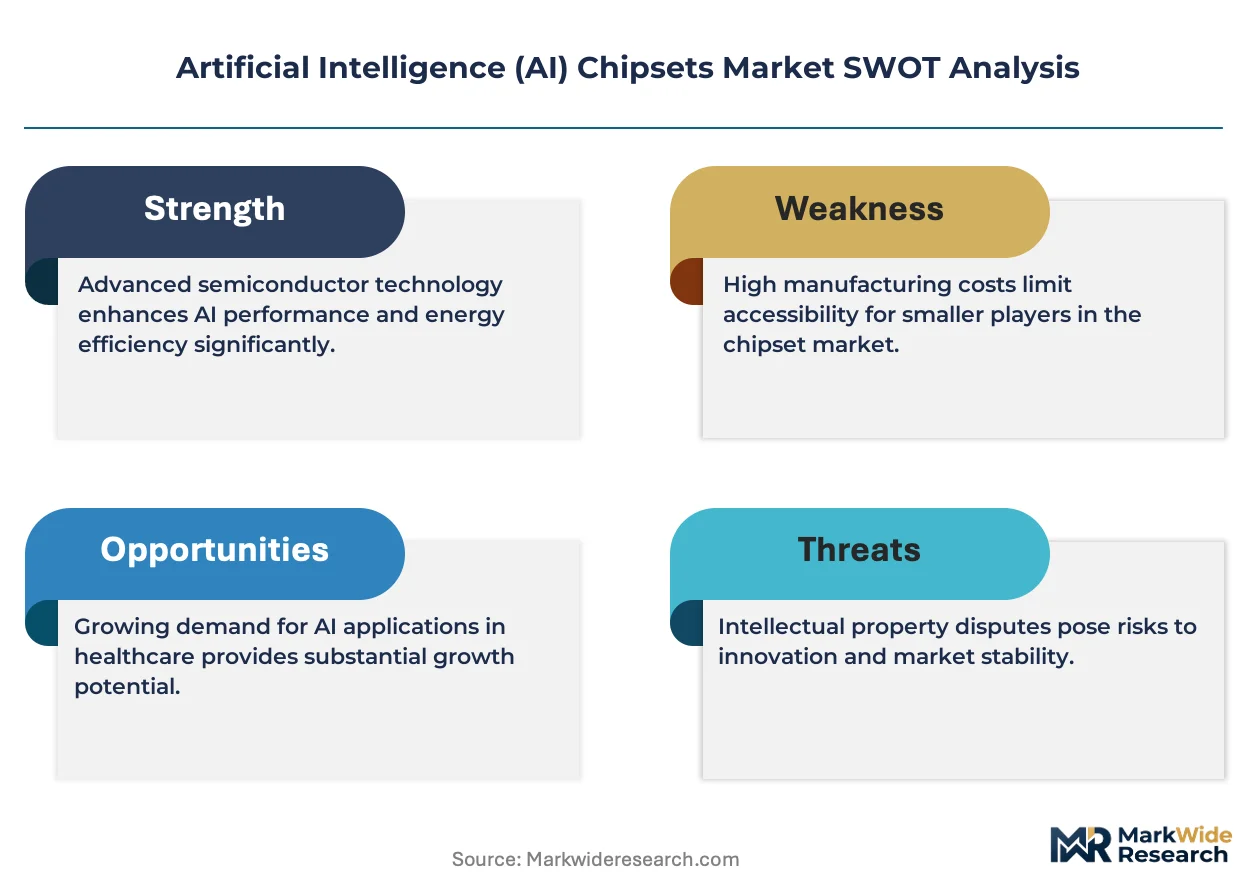
FDA oversight of AI-enabled medical devices, FCC spectrum allocations for edge connectivity, and EU AI Act conformity requirements collectively shape product roadmaps and market access conditions for chipset vendors. The SEC's disclosure mandates for AI-related risk exposure further tighten governance expectations for publicly traded technology providers. Stakeholders must monitor how export control classifications on advanced lithography equipment redirect supply chain investments toward alternative manufacturing geographies.
Market Dynamics
Hyperscaler capital allocation toward AI training clusters is compressing procurement cycles and forcing foundry capacity commitments years ahead of silicon tape-out.
Growth Catalysts
- Cloud Infrastructure Expansion:Amazon Web Services, Microsoft Azure, and Google Cloud are commissioning multi-gigawatt data center campuses in Northern Virginia and Oregon, locking in long-term silicon offtake agreements with foundry partners.
- EU AI Act Compliance Mandates:High-risk AI system classification requirements are compelling enterprise buyers to source auditable, traceable chipsets with documented training provenance and energy consumption metrics.
- 3nm Process Node Maturation:TSMC's N3E and Samsung's 3GAP processes are yielding sufficient volume to support mass deployment of dense AI accelerators with improved power efficiency over 5nm predecessors.
Market Restraints
- Advanced Lithography Equipment Access:Dutch and Japanese export controls on extreme ultraviolet lithography systems are constraining foundry expansion outside Taiwan, South Korea, and the United States.
- High-Bandwidth Memory Supply Concentration:SK Hynix, Samsung Electronics, and Micron Technology control virtually all HBM3 and HBM3E supply, creating single-source risk for training-optimized GPU and TPU configurations.
- CoWoS Packaging Bottleneck:TSMC's chip-on-wafer-on-substrate capacity is fully subscribed through 2025, throttling output of multi-die AI accelerators regardless of front-end wafer availability.
Strategic Opportunities
- Edge AI Deployment in Industrial Automation:German automotive OEMs and Japanese robotics manufacturers are specifying on-device inference chips for sub-10 millisecond latency in predictive maintenance and quality inspection workflows.
- US CHIPS Act Incentives:Department of Commerce funding awards and investment tax credits are de-risking greenfield fab construction in Arizona, Texas, and Ohio for domestic AI silicon production.
- Neuromorphic-Photonic Convergence:Research consortia in Switzerland and the Netherlands are prototyping optical interconnect layers that reduce data movement energy by orders of magnitude for transformer inference.
Industry Challenges
- Compiler and Software Stack Talent Scarcity:CUDA optimization expertise and custom kernel development for novel architectures command premium compensation, constraining second-tier accelerator vendors' time-to-market.
- Multi-Jurisdictional Certification Burden:FDA 510(k) pathways for AI-enabled medical devices, FCC Part 15 emissions testing for edge deployments, and EU AI Act conformity assessments impose overlapping timeline risks.
- Legacy Data Center Infrastructure Integration:Enterprise buyers with substantial x86 server installed bases face firmware incompatibility and thermal design power mismatches when retrofitting AI accelerators into existing racks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence (AI) Chipsets Market |
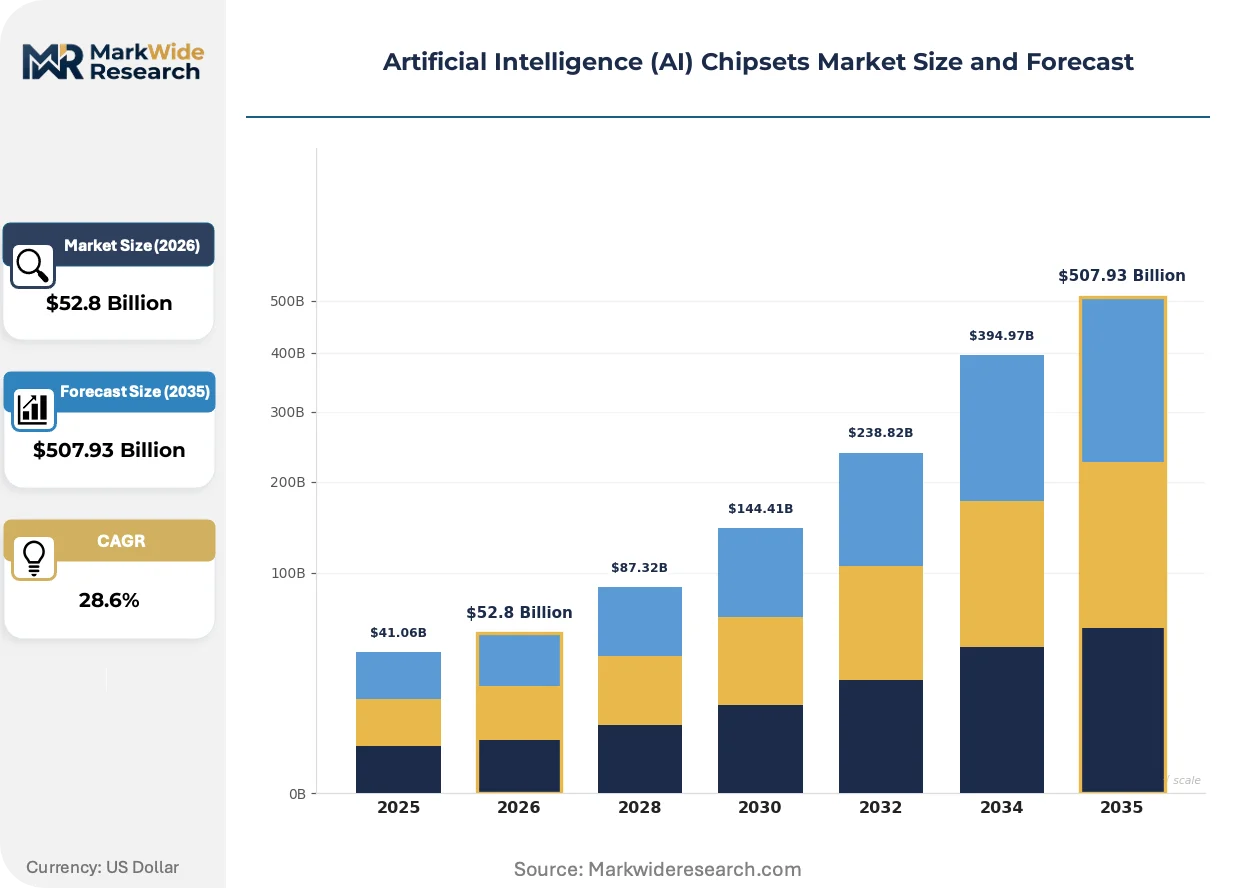
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $507.93 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GPU, TPU, FPGA, ASIC, DSP Technology: Machine Learning, Deep Learning, Neural Network, Computer Vision, Natural Language Processing Application: Data Centers, Edge Computing, Autonomous Vehicles, Robotics, Smart Surveillance End User: Technology Providers, Telecom Operators, Research Institutions, Consumer Electronics Firms, Defense Agencies |
| Companies Covered | NVIDIA Corporation, Intel Corporation, Advanced Micro Devices, Qualcomm Technologies, Alphabet, Samsung Electronics, Huawei Technologies, Micron Technology, MediaTek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence (AI) Chipsets Market Strategic Shifts & Innovations
Silicon specialization is accelerating beyond general-purpose accelerators toward workload-optimized architectures with co-designed algorithms.
Chiplet-based modular designs are rendering obsolete monolithic AI accelerators for all but the most latency-sensitive training workloads. Hyperscalers including Meta Platforms and Microsoft are adopting multi-tile configurations with standardized die-to-die interconnects. This disaggregation is compressing development costs and enabling mix-and-match compute, memory, and I/O tiles from different process nodes.
The EU AI Act's transparency and risk-classification requirements are forcing chipset vendors to embed hardware telemetry for energy monitoring and inference logging. CE marking conformity assessment bodies are expanding technical documentation review scope to include training data provenance and model card specifications. Medical device and autonomous vehicle segments are absorbing the highest compliance overhead, with some vendors delaying EU market entry pending regulatory clarity.
Buyers are consolidating procurement authority into centralized infrastructure teams with direct foundry relationships, bypassing traditional distributor and value-added reseller channels. This disintermediation is most pronounced among cloud service providers and sovereign AI initiatives in France, Saudi Arabia, and Singapore. Component vendors are responding with dedicated account engineering teams and long-term supply agreements indexed to wafer starts rather than unit shipments.
Artificial Intelligence (AI) Chipsets Market Segmentation
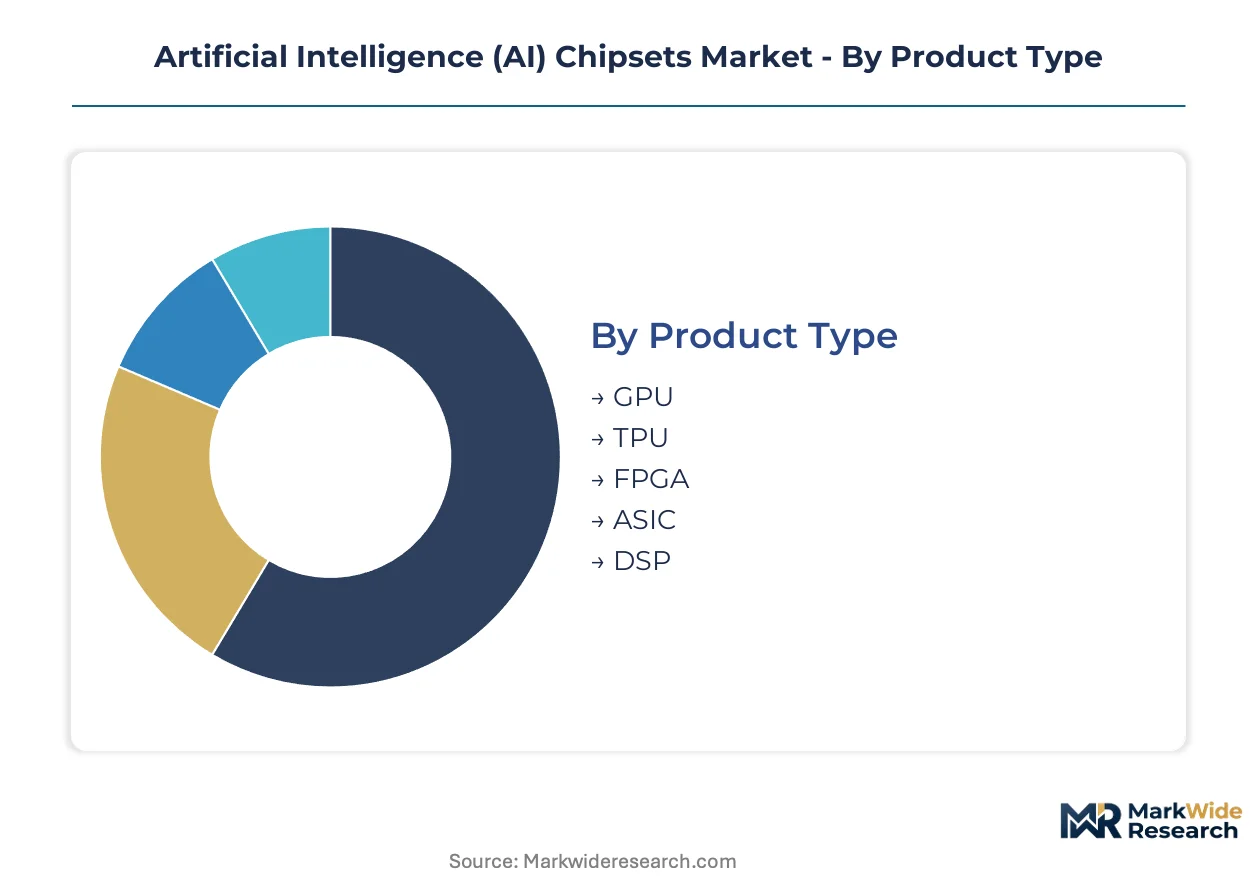
AI chipset procurement patterns diverge sharply across deployment contexts, from hyperscaler training clusters demanding maximum throughput to battery-constrained edge devices prioritizing inference efficiency per watt. Segmentation reveals how architectural specialization maps to distinct performance requirements and buyer economics.
Product Type:
Accelerator architectures span the cost-performance spectrum from programmable flexibility to workload-optimized silicon.
- GPU:Massively parallel floating-point engines dominate neural network training through CUDA-optimized software ecosystems. Hyperscalers in Northern Virginia and Oregon are locking multi-year offtake agreements for H100 and successor architectures, constrained only by CoWoS packaging capacity.
- ASIC:Custom silicon eliminates redundant logic for inference-at-scale, yielding superior TOPS-per-watt for transformer and recommendation workloads. Google Cloud's TPU v5p deployments and Amazon Web Services' Trainium2 clusters demonstrate hyperscaler appetite for captive silicon designs.
- TPU:Google's tensor processing units remain architecturally distinct through systolic array designs optimized for matrix multiplication chains.
- FPGA:Reconfigurable logic enables algorithmic agility for prototyping and low-volume defense applications with evolving threat models.
- DSP:Digital signal processors anchor audio and sensor fusion inference in automotive and industrial edge nodes.
The dominant share belongs to GPU, while ASIC is closing the gap fastest.
Technology:
Computational intensity and data requirements stratify AI workloads into distinct silicon optimization targets.
- Deep Learning:Multi-layer neural networks with billions of parameters demand high-bandwidth memory subsystems and dense tensor cores. Training clusters for large language models concentrate in Oregon and Northern Virginia, with EU AI Act energy disclosure requirements now influencing hardware telemetry specifications.
- Computer Vision:Convolutional and vision transformer architectures process pixel streams for autonomous navigation and quality inspection. German automotive OEMs and Japanese robotics manufacturers are specifying sub-10 millisecond latency requirements that push inference toward edge deployment.
- Machine Learning:Classical statistical methods with lighter compute footprints suit enterprise analytics and forecasting applications.
- Neural Network:Broad category encompassing feedforward, recurrent, and graph architectures with varying memory access patterns.
- Natural Language Processing:Transformer-based text understanding drives demand for attention-optimized accelerators with large KV-cache capacity.
Deep Learning commands the largest silicon allocation, though Computer Vision is expanding most quickly at the edge.
Application:
Deployment location determines power envelopes, thermal constraints, and connectivity requirements.
- Data Centers:Rack-scale accelerators with liquid cooling support training workloads exceeding 100kW per cluster. Cloud service providers are commissioning multi-gigawatt campuses in Northern Virginia and Oregon, with foundry capacity commitments extending through 2027.
- Edge Computing:Distributed inference nodes reduce latency for time-sensitive industrial automation and smart city deployments. Saudi Arabia's NEOM initiative and Singapore's sovereign AI programs are driving demand for thermally constrained accelerators.
- Autonomous Vehicles:Functional safety requirements and deterministic latency bounds shape NPU selection for perception stacks.
- Robotics:Power budgets under 15W restrict processor choice for collaborative robots and drones.
- Smart Surveillance:Video analytics at the camera or edge gateway demands efficient person and object detection silicon.
Data Centers absorb the dominant share of accelerator volume, while Edge Computing is gaining share fastest as latency requirements tighten.
End User:
Buyer sophistication and procurement scale create distinct channel dynamics and support requirements.
- Technology Providers:Cloud hyperscalers and platform vendors with direct foundry relationships and custom silicon roadmaps. Microsoft Azure, Amazon Web Services, and Google Cloud are bypassing traditional distribution channels for wafer-start-indexed supply agreements.
- Defense Agencies:Classified workloads and supply chain security requirements drive demand for domestic foundry sources and ITAR-compliant packaging. US CHIPS Act incentives are accelerating Arizona and Texas fab investments for trusted AI silicon.
- Telecom Operators:5G network edge and RAN virtualization create distributed inference opportunities.
- Consumer Electronics Firms:Smartphone and wearable OEMs prioritize NPU integration for on-device photography and voice assistants.
- Research Institutions:National laboratories and university consortia access accelerators through cloud credits and shared instrumentation facilities.
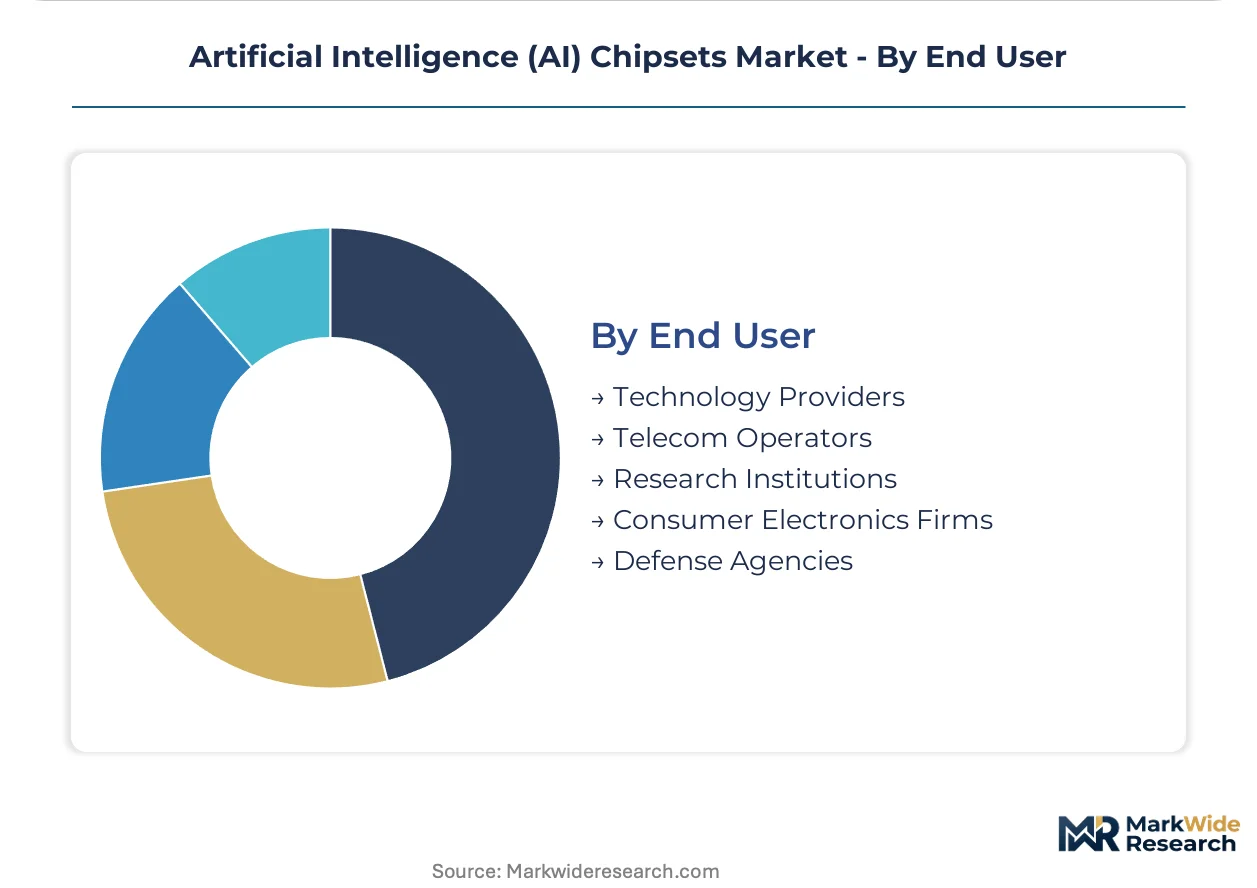
Technology Providers command the dominant procurement volume, while Defense Agencies are expanding fastest under sovereign capability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan exports advanced silicon wafers to hyperscaler campuses in Northern Virginia and Oregon, while South Korea ships high-bandwidth memory modules to cloud infrastructure operators across North America and Europe.
United States
Hyperscalers in Northern Virginia and Oregon are commissioning multi-gigawatt data center campuses with long-term foundry offtake agreements. The CHIPS Act provides Department of Commerce funding and investment tax credits for domestic fab construction in Arizona, Texas, and Ohio. Defense agencies are accelerating trusted AI silicon procurement under ITAR-compliant sourcing mandates.
China
Domestic cloud providers and AI labs are scaling training clusters despite advanced lithography equipment access constraints. MIIT and SAMR are tightening oversight of algorithmic systems and data security in high-risk applications. Yangtze River Delta fabrication hubs are redirecting investments toward mature-node accelerators and memory packaging.
South Korea
SK Hynix and Samsung Electronics control dominant shares of HBM3 and HBM3E supply for training-optimized accelerators. MFDS and METI-aligned standards are shaping medical and industrial AI device certification requirements. Seoul Capital Area foundry complexes are expanding advanced packaging capacity for multi-die configurations.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg are specifying sub-10 millisecond latency chips for predictive maintenance and quality inspection. The EU AI Act's high-risk system classification is compelling documented training provenance and energy consumption metrics. Stuttgart and Munich industrial clusters are driving edge AI deployment in robotics automation.
Japan
Robotics manufacturers in Kansai and Chubu are procuring power-efficient NPUs for collaborative automation with deterministic latency bounds. METI is coordinating sovereign AI initiatives with domestic foundry partnerships for supply chain resilience. Osaka and Nagoya precision manufacturing hubs are integrating on-device inference for sensor fusion applications.
Artificial Intelligence (AI) Chipsets Market Key Industry Players
Channel-controlling players compete with product-specialist players across a tiered structure where software ecosystem lock-in separates premium-tier vendors from commodity silicon providers. The vendor base clusters around three strategic archetypes: GPU-centric training specialists with proprietary compiler stacks, captive ASIC designers serving hyperscaler workloads, and edge-focused NPU vendors optimizing for thermal constraints. Competitive moves center on foundry capacity reservation through multi-year wafer-start agreements and vertical integration into advanced packaging operations.
Within the GPU-centric training tier, NVIDIA Corporation exemplifies ecosystem-driven market positioning through its CUDA software layer. Intel Corporation and Qualcomm Technologies occupy distinct specialization vectors, with the former leveraging x86 data center installed base and the latter anchoring edge deployment with power-efficient designs. These three entities represent the dominant competitive anchors across training, inference, and edge computing deployment contexts.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Intel Corporation |
| Advanced Micro Devices |
| Qualcomm Technologies |
| Alphabet |
| Samsung Electronics |
| Huawei Technologies |
| Micron Technology |
| MediaTek |
| Others |
Cost & Logistics Intelligence
HBM3 supply concentration among SK Hynix, Samsung Electronics, and Micron Technology determines both the pricing tier spreads across training-optimized versus inference-optimized accelerators and the geographic shape of procurement flows toward hyperscaler campuses in Northern Virginia and Oregon.
Pricing Analysis
3nm process node premiums over 5nm predecessors widen the technology-generation pricing gap between current-gen training clusters and prior-gen inference deployments. Three-tier pricing structure across premium HBM3E configurations, standard HBM3 deployments, and economy-grade GDDR6 alternatives stratifies the market by memory bandwidth requirements. Cost compression in mid-tier inference accelerators is intensifying because ASIC vendors are eliminating redundant logic for transformer workloads. Cloud service providers exhibit the lowest price sensitivity due to multi-year offtake agreements, while industrial edge buyers in Germany and Japan face acute budget constraints for sub-10 millisecond latency chips.
Supply Chain Analysis
Extended payment terms from hyperscalers to foundry partners now stretch to 180 days, compressing working capital for packaging subcontractors. Taiwan, South Korea, and the United States anchor front-end wafer fabrication, while Malaysia and Vietnam host back-end assembly and test operations. The supply chain draws from high-bandwidth memory modules, CoWoS interposers, and advanced substrate materials. Single-source vulnerability around TSMC's CoWoS capacity constitutes the dominant structural risk. Distribution runs through direct foundry relationships rather than traditional distributor channels for cloud service providers and sovereign AI initiatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against neuromorphic-photonic convergence architectures that could displace electronic inference accelerators for transformer workloads. Incumbents must navigate optical interconnect prototypes from Swiss and Dutch research consortia that reduce data movement energy by orders of magnitude.
For Market Incumbents: Insulate CUDA ecosystem lock-in through compiler optimization investments that raise switching costs for hyperscaler training workloads. Captive CoWoS capacity additions in Taiwan and Arizona defend against packaging bottlenecks throttling multi-die accelerator output. Backward integration into HBM3E supply through strategic partnerships with SK Hynix or Samsung Electronics mitigates single-source memory risk.
For New Entrants and Emerging Players: Establish a beachhead in industrial edge AI for German automotive OEMs specifying sub-10 millisecond latency chips for predictive maintenance workflows. European robotics automation and Japanese sensor fusion applications represent the most penetrable white-space targets. A certification-first go-to-market angle targeting EU AI Act conformity requirements differentiates against incumbent hardware telemetry gaps.
For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors foundry-adjacent packaging specialists with secured CoWoS allocation. Long-term viability across the projection horizon hinges on software ecosystem control rather than silicon performance metrics alone. The signal to watch is hyperscaler captive silicon roadmaps from Google Cloud and Amazon Web Services diverting procurement from merchant GPU vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| CoWoS Capacity Reservation | TSMC packaging commitments through 2025 lock in multi-die accelerator output regardless of front-end wafer availability. |
| EU AI Act Compliance Investment | Hardware telemetry for energy monitoring and inference logging enables CE marking access for medical device and autonomous vehicle segments. |
| HBM3E Supply Partnership | Long-term agreements with SK Hynix or Samsung Electronics secure memory subsystems for training-optimized configurations. |
| Edge NPU Certification Pathway | FDA 510(k) and FCC Part 15 pre-certification accelerates procurement cycles from defense agencies and telecom operators. |
| Photonic Interconnect R&D Consortium | Swiss and Dutch optical layer prototypes reduce transformer inference energy consumption below electronic baseline thresholds. |
Research Approach
A spread of perspectives from hyperscaler infrastructure executives, foundry account managers, fabless semiconductor CFOs, and edge AI system architects converged on the working assumptions underlying this analysis. Primary interviews with cloud service provider procurement teams and defense agency technology officers combined with secondary validation from SEC 10-K filings, hyperscaler capex disclosures, and foundry revenue reports. Bottom-up triangulation across accelerator unit shipments and top-down reconciliation against foundry wafer starts established volume consistency.
Demand-supply balance modeling across the projection horizon incorporated training cluster deployment schedules, CoWoS packaging capacity constraints, and HBM3E supply allocation decisions. Segmentation dimensions included accelerator architecture, process node generation, deployment location, and end-user procurement sophistication. CAGRs derived from logistic growth curves fitted to hyperscaler infrastructure investment cycles and sovereign AI program budgets. Industry-specific forecast inputs encompassed EU AI Act compliance timelines and CHIPS Act incentive disbursement trajectories.
Sensitivities concentrate around export control expansions on advanced lithography equipment, HBM supply disruptions from geopolitical events, and hyperscaler captive silicon roadmap accelerations. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Global Digital Light Processing Chipset Market
Chipset and Processors
Thailand Data Center Processor Market
Chipset and Processors
Tablet and E-Reader Application Processor Market
Chipset and Processors
Self-Learning Neuromorphic Chip Market
Chipset and Processors
Microprocessor Market
Chipset and Processors
Secure Microcontrollers/Processors Market
Chipset and Processors
India Data Center Processor Market
Chipset and Processors
Integrated Graphics Chipset Market
Chipset and Processors
Europe 8- Bit Microcontroller Market
Chipset and Processors
Americas Digital Signal Processor Market
Chipset and Processors
Global AI Processor Market
Chipset and Processors
Global Neural Processors Market
Chipset and Processors
China Microprocessor (MPU) Market
Chipset and Processors
Netherlands Data Center Processor Market
Chipset and Processors
Mobile Chipset Market
Chipset and Processors
United Kingdom Data Center Processor Market