
 Propylene Glycol Methyl Ether Market | 2026-2036
Propylene Glycol Methyl Ether Market Size, Share, and Industry Trends Forecast 2026-2036
Propylene Glycol Methyl Ether Market Outlook
Electronic-grade solvent specifications are reorganizing procurement priorities across the propylene glycol methyl ether value chain. Dow Inc. leverages integrated propylene oxide feedstock positions to secure cost-advantaged PGME supply for semiconductor cleaning applications. BASF SE anchors European demand through specialized PGMEA grades tailored to photoresist formulations. KH Neochem Co., Ltd. competes on ultra-high purity standards required by advanced display manufacturers in East Asia.
Propylene glycol methyl ether refers to a family of propylene oxide-derived glycol ethers with molecular weights ranging from 90 to 132 g/mol, manufactured via catalytic addition of methanol to propylene oxide under alkaline or acidic conditions. These solvents function primarily as active diluents, coalescing agents, and viscosity modifiers in waterborne and solvent-based coating systems. PGMEA dominates value contribution due to its irreplaceable role in photolithographic processes, while PGME sustains volume leadership across general industrial coatings. The solvents application segment concentrates margin pools where semiconductor and electronics-grade certifications command substantial premiums over standard industrial grades.
EPA volatile organic compound regulations under the National Emission Standards for Hazardous Air Pollutants constrain conventional solvent use, redirecting formulation demand toward exempt glycol ether architectures. REACH authorization requirements in Europe compel downstream users to document substitution assessments for high-concern substances, elevating compliant PGME derivatives in coatings and adhesives procurement. China's Ministry of Ecology and Environment enforces progressively stringent emissions controls around the Yangtze River Delta manufacturing cluster, reinforcing local supply chain investments. Stakeholders must monitor evolving purity thresholds at the intersection of semiconductor node shrinkage and chemical regulatory expansion.
Market Dynamics
Semiconductor node shrinkage below 7nm is compressing purity tolerances for electronic-grade glycol ethers, forcing solvent suppliers to recalibrate distillation and filtration infrastructure ahead of foundry qualification cycles.
Growth Catalysts
- EPA NESHAP compliance deadlines:Coatings manufacturers in the US are accelerating reformulation schedules to meet hazardous air pollutant limits, redirecting volume toward exempt glycol ether architectures.
- Photoresist solvent demand:Advanced lithography nodes at 5nm and below require PGMEA grades with sub-ppb metal contamination thresholds, creating specification premiums across East Asian semiconductor clusters.
- Yangtze River Delta concentration:China's Ministry of Ecology and Environment enforcement actions are consolidating solvent production into integrated petrochemical complexes with captive purification capabilities.
Market Restraints
- Propylene oxide feedstock volatility:PGME production costs track propylene oxide contract pricing, which fluctuates with refinery operating rates and propylene supply-demand imbalances.
- Specialty-grade supply concentration:Semiconductor-certified PGMEA supply concentrates among three integrated producers with dedicated super-pure distillation trains, limiting buyer switching options.
- Aqueous cleaning substitution:Some back-end semiconductor cleaning steps are transitioning to diluted aqueous chemistries, displacing solvent-based processes in select etch and strip applications.
Strategic Opportunities
- India electronics manufacturing:Production-linked incentive schemes for semiconductor assembly and display fabrication are attracting solvent distributors to establish local blending and certification infrastructure.
- EU REACH authorization pathways:Downstream users documenting substitution assessments for high-concern substances can secure preferential supply contracts for compliant PGME derivatives in coatings adhesives.
- Digital inventory platforms:Specialty chemical distributors are deploying vendor-managed inventory systems with real-time purity certification tracking, reducing working capital burdens for mid-size coatings formulators.
Industry Challenges
- Semiconductor qualification timelines:New solvent grades require 12-18 month foundry validation cycles, compressing product development returns and locking out speculative entrants.
- Cross-contamination control:Facilities producing both industrial-grade and electronic-grade PGME must maintain segregated packaging and logistics streams, elevating operational complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Propylene Glycol Methyl Ether Market |
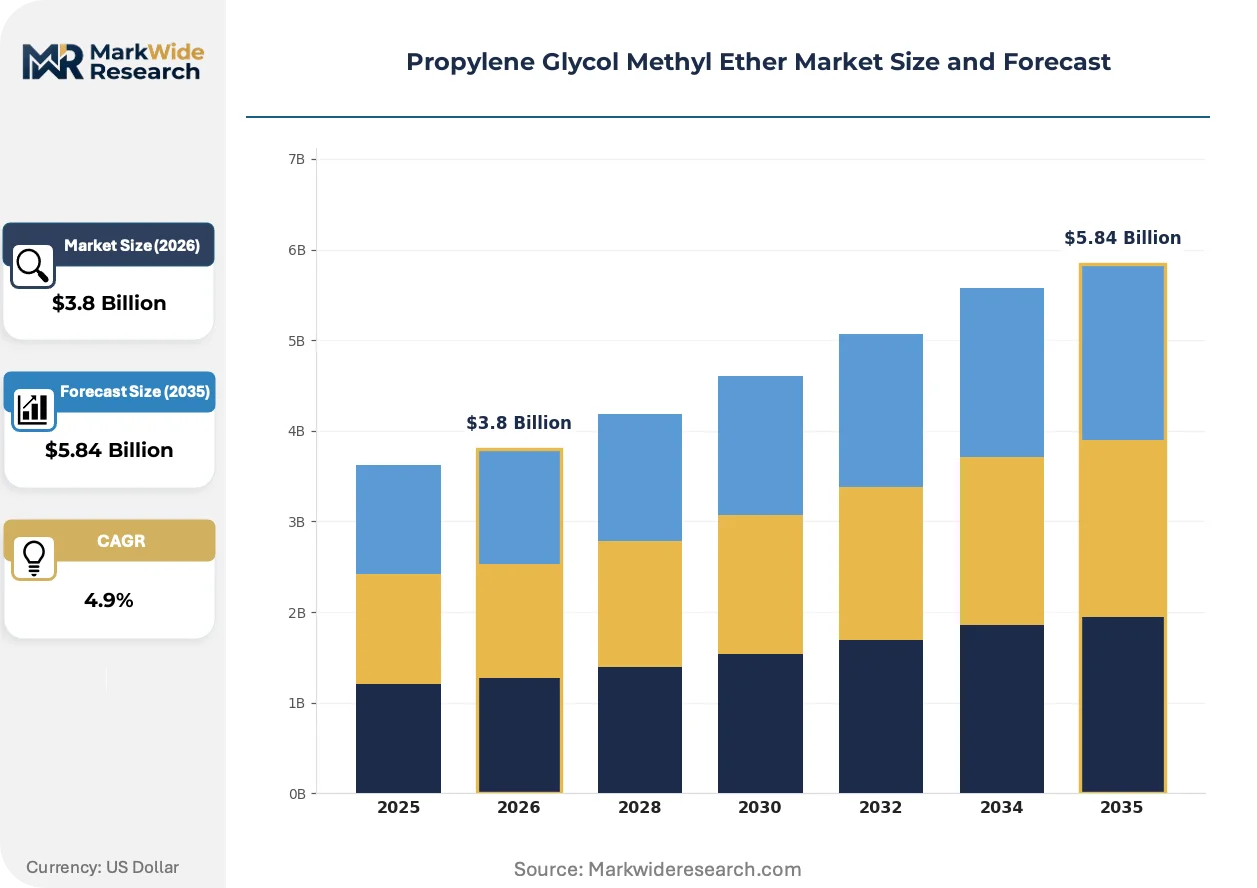
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.84 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PGME, PGMEA, PGMEAc, Others End Use Industry: Paints, Coatings, Adhesives, Pharmaceuticals Application: Solvents, Intermediate, Thinners, Cleaners Distribution Channel: Direct Sales, Distributors, E-commerce, Retail |
| Companies Covered | Dow Inc., LyondellBasell Industries, Shell Chemicals, Eastman Chemical Company, BASF SE, INEOS Group, KH Neochem Co., Ltd., Huntsman Corporation, Shinko Organic Chemical Industry Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Propylene Glycol Methyl Ether Market Strategic Shifts
Electronic-grade solvent specifications are reorganizing procurement priorities across the propylene glycol methyl ether value chain, with purity thresholds now dictating supplier selection ahead of unit economics.
Membrane filtration technology for metal ion removal is miniaturizing. Semiconductor chemical suppliers are adopting nanofiltration skids with sub-nanometer pore precision to achieve single-digit ppb sodium and potassium specifications. This capability is miniaturizing the acceptable particle size window for photoresist solvents, compressing the supplier base to facilities with advanced filtration assets.
REACH authorization requirements in Europe are compelling downstream coatings manufacturers to document substitution assessments for substances of very high concern. Industrial users are elevating compliant PGME derivatives in procurement scorecards, with formulators in Germany and the Netherlands accelerating qualification of exempt glycol ether architectures ahead of sunset date deadlines.
Specification-driven vendor consolidation is reshaping buyer behavior across solvent procurement functions. Large semiconductor foundries are reducing approved supplier lists from six to three qualified sources per solvent grade, replacing spot-market purchasing with multi-year purity-guarantee contracts. This concentration is most visible in South Korea and Taiwan, where foundry chemical managers prioritize supply security over price competition.
Propylene Glycol Methyl Ether Market Segmentation
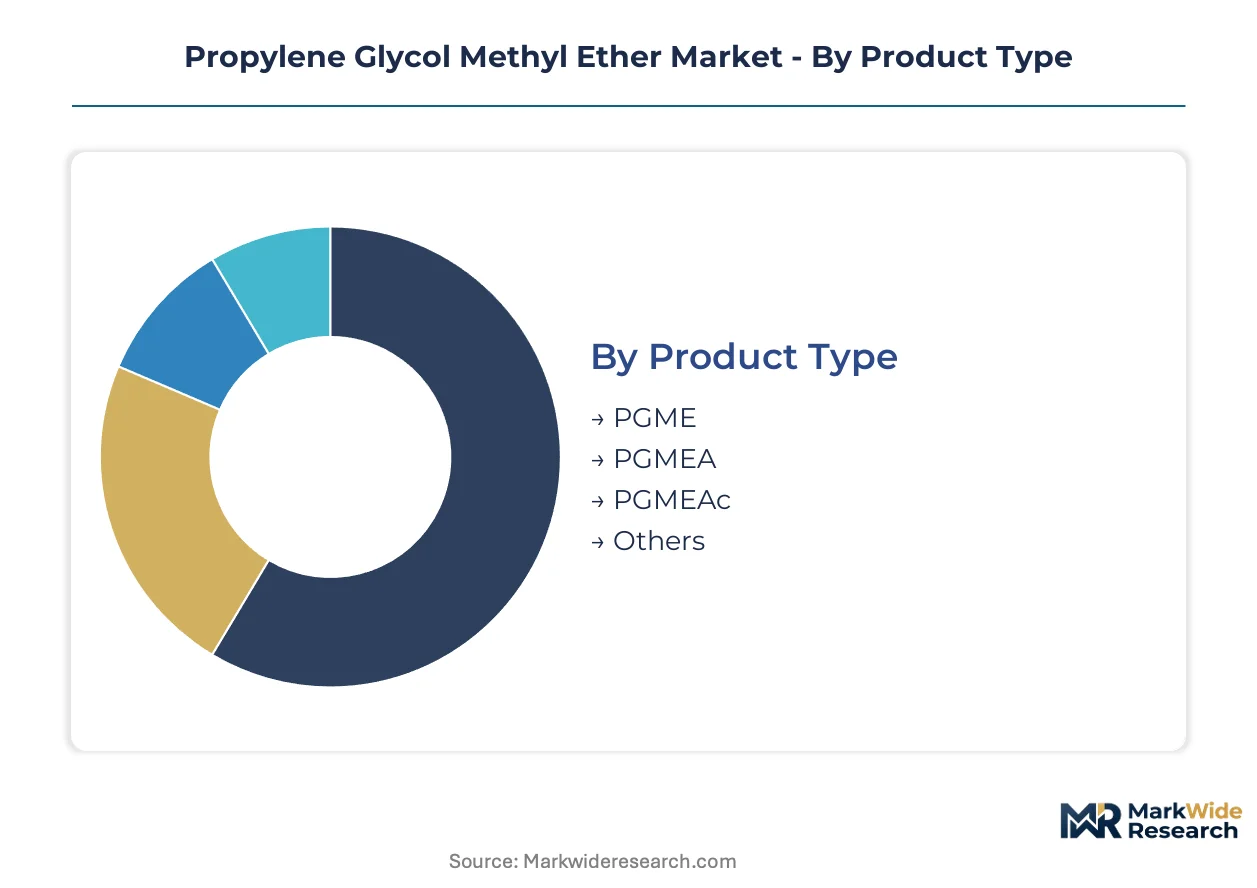
Propylene glycol methyl ether derivatives exhibit sharply divergent margin profiles depending on purity certification and end-use specifications. Semiconductor-grade PGMEA commands substantial premiums over industrial solvents, while distribution channel selection directly impacts working capital requirements and customer technical support intensity.
Product Type:
Margin pools concentrate in electronic-grade specifications where metal ion thresholds separate commodity from specialty pricing tiers.
- PGME:The foundational propylene glycol methyl ether functions as an active diluent and coalescing agent across waterborne architectural coatings. Demand from EPA-compliant reformulations in US paints manufacturing is displacing conventional solvent architectures in high-VOC jurisdictions.
- PGMEA:Photoresist solvent specifications for sub-7nm lithography nodes require sub-ppb metal contamination thresholds. East Asian semiconductor clusters in Taiwan and South Korea are concentrating procurement among qualified super-pure suppliers with dedicated distillation trains.
- PGMEAc:The acetate derivative serves electronics cleaning applications where moderate purity tolerances balance performance against unit economics.
- Others:Specialty glycol ether blends tailored to pharmaceutical synthesis and agrochemical formulation occupy niche volume positions with contract manufacturing dependencies.
PGME holds installed capacity across general industrial applications. PGMEA is rotating up the share rankings on semiconductor capital expenditure cycles.
End Use Industry:
Application-driven cost tiers separate commodity coatings consumption from value-added electronics and life science segments.
- Paints:Waterborne architectural and industrial formulations utilize PGME as exempt VOC coalescing agents under EPA NESHAP frameworks. German and Dutch formulators are accelerating qualification timelines ahead of REACH sunset dates.
- Coatings:Automotive OEM and refinish systems deploy PGMEA in high-solids clearcoats where flow control and drying balance are critical. Chinese Yangtze River Delta manufacturing clusters are consolidating solvent procurement through integrated petrochemical complexes.
- Adhesives:Reactive polyurethane and epoxy systems incorporate glycol ethers as viscosity modifiers and open-time extenders for construction and assembly applications.
- Pharmaceuticals:USP-grade PGME serves as extraction solvent and tablet coating carrier where residual solvent limits under ICH Q3C guidelines dictate supplier qualification protocols.
Coatings maintains the broadest installed capacity base. Semiconductor-adjacent electronics applications are climbing the fastest on specification premiums.
Application:
Customer type differentiation separates spot-market industrial buyers from long-term contract semiconductor foundries.
- Solvents:The dominant application by volume spans coating diluents, cleaning formulations, and chemical synthesis media where functional performance drives procurement decisions.
- Intermediate:PGME functions as a building block for pharmaceutical actives and agrochemical synthesis, with Indian chemical manufacturers expanding captive consumption under PLI scheme incentives.
- Thinners:Lacquer and enamel systems in automotive refinish and wood coatings rely on glycol ether thinners for viscosity reduction and flow optimization.
- Cleaners:Electronics-grade precision cleaning for display and semiconductor fabrication represents the highest purity application tier with multi-year supplier validation cycles.
Solvent applications hold established capacity infrastructure. Cleaner specifications are expanding most quickly on advanced node semiconductor demand.
Distribution Channel:
Supply concentration shapes channel economics, with bulk industrial volumes favoring direct relationships and specialty grades requiring technical distributor networks.
- Direct Sales:Large coatings formulators and semiconductor foundries negotiate multi-year purity-guarantee contracts with integrated producers, eliminating intermediary margins on qualified volumes.
- Distributors:Regional chemical distributors manage inventory and certification documentation for mid-size industrial accounts, with vendor-managed inventory systems reducing working capital burdens.
- E-commerce:Digital platforms are penetrating standard industrial grades where specification documentation and certificate of analysis availability satisfy procurement requirements.
- Retail:Small-volume architectural coatings and consumer adhesive applications flow through construction supply and home improvement channels with limited technical service content.
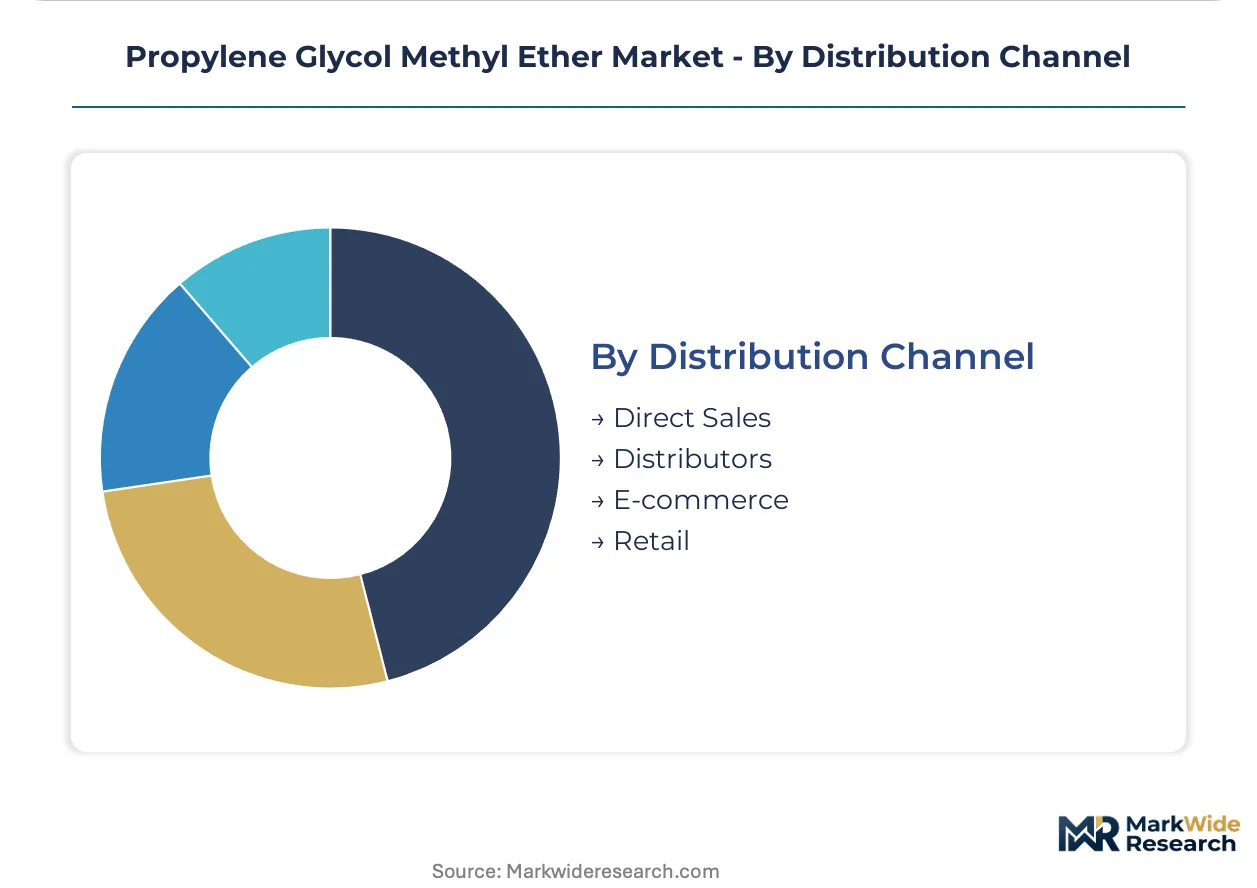
Direct sales channels anchor high-volume semiconductor and coatings procurement. Distributor relationships are gaining share in mid-market industrial segments requiring technical support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated petrochemical complexes in China, South Korea, and Germany concentrate super-pure PGMEA supply for semiconductor applications. These three countries anchor capacity expansion and consumption growth through 2035.
China
Display panel and chip fabrication demand from Yangtze River Delta clusters drives solvent consumption. MEE emissions enforcement around Shanghai and Suzhou consolidates production into captive purification facilities. Local formulators qualify exempt glycol ether architectures ahead of tightening VOC limits.
South Korea
Foundry chemical managers at Samsung and SK Hynix facilities prioritize supply security over price competition for sub-ppb PGMEA grades. KOSHA workplace chemical standards align with semiconductor customer audit protocols. Pyeongtaek and Hwaseong industrial zones concentrate multi-year purity-guarantee contracts with qualified suppliers.
Germany
Automotive OEM clearcoat formulators and photoresist distributors anchor European PGMEA demand. ECHA REACH authorization requirements compel substitution assessments for high-concern substances in coatings applications. Ludwigshafen and Marl chemical parks maintain segregated industrial-grade and electronic-grade production streams.
United States
EPA NESHAP compliance deadlines accelerate reformulation schedules for architectural and industrial coatings manufacturers. Dow's integrated propylene oxide positions on the Gulf Coast secure cost-advantaged feedstock for semiconductor cleaning grades. Texas and Louisiana petrochemical corridors supply exempt glycol ether volumes for domestic paints producers.
Japan
Advanced display manufacturers in Osaka and Nagoya prefectures require ultra-high purity standards for OLED fabrication processes. METI chemical management guidelines reinforce supplier qualification protocols for electronics-grade solvents. Domestic chemical companies maintain specialized distillation assets for photoresist formulation customers.
Propylene Glycol Methyl Ether Market Competitive Environment
Concentration sits with integrated petrochemical producers possessing captive propylene oxide supply and dedicated super-pure distillation infrastructure. Three to four qualified suppliers dominate semiconductor-grade PGMEA procurement, while industrial-grade PGME fragments across broader chemical manufacturing networks. Strategic archetypes include backward-integrated propylene oxide producers, specialty chemical purifiers with advanced filtration assets, and regional distributors managing certification documentation. Capacity expansion and multi-year purity-guarantee contracts constitute the dominant competitive moves as foundries reduce approved supplier lists.
Among integrated chemical producers, Dow Inc. and BASF SE exemplify archetypes combining feedstock control with electronics-grade certification capabilities. KH Neochem Co., Ltd. occupies a position representing ultra-high purity specialists serving advanced display manufacturers in East Asia. These three names anchor the supplier tier commanding specification premiums for sub-ppb metal contamination thresholds.
| Leading Market Players |
|---|
| Dow Inc. |
| LyondellBasell Industries |
| Shell Chemicals |
| Eastman Chemical Company |
| BASF SE |
| INEOS Group |
| KH Neochem Co., Ltd. |
| Huntsman Corporation |
| Shinko Organic Chemical Industry Ltd |
| Others |
Value Chain & Pricing Dynamics
Twelve-to-eighteen month foundry qualification cycles compress pricing power toward integrated producers with captive purification assets, while semiconductor foundries reduce approved supplier lists from six to three qualified sources per solvent grade. This inventory discipline concentrates procurement leverage among buyers with multi-year purity-guarantee contracts, elevating specification premiums over spot-market alternatives.
Pricing Analysis
EPA NESHAP compliance deadlines dictate the pricing tier structure across propylene glycol methyl ether derivatives, with exempt glycol ether architectures commanding premiums over conventional solvent formulations facing reformulation pressure. Three-tier pricing structure across semiconductor-grade, industrial-grade, and standard solvent levels separates sub-ppb metal contamination thresholds from general coatings applications. Cost compression in industrial-grade PGME is intensifying because propylene oxide feedstock volatility tracks refinery operating rates. Semiconductor foundries exhibit the least price sensitivity, prioritizing supply security and qualification status over unit economics, while mid-size coatings formulators show highest sensitivity to working capital burdens.
Supply Chain Analysis
Strait of Malacca transit vulnerability underwrites supply security calculations for East Asian semiconductor clusters dependent on propylene oxide feedstock flows. Manufacturing concentrates in China, South Korea, and Germany, with integrated petrochemical complexes anchoring super-pure PGMEA supply. Production draws from propylene oxide, methanol, and specialized filtration membrane inputs. Single-source vulnerability concentrates among three qualified suppliers with dedicated super-pure distillation trains. Distribution runs through direct sales channels for large foundries and coatings formulators, with regional distributors managing certification documentation for mid-market industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating as semiconductor foundries reduce approved supplier lists and coatings manufacturers accelerate reformulation schedules, fragmenting procurement leverage toward specification-certified integrated producers.
For Market Incumbents: Fortify qualification status through dedicated super-pure distillation train investments ahead of sub-7nm node shrinkage, while securing captive propylene oxide supply positions against feedstock volatility. Threats from aqueous cleaning substitution in back-end semiconductor processes demand countermeasures through advanced filtration asset deployment in Taiwan and South Korea clusters. For New Entrants and Emerging Players: Anchor in India's electronics manufacturing incentive schemes, where production-linked incentives for semiconductor assembly and display fabrication attract solvent distributors to establish local blending infrastructure. The most penetrable white-space target sits in mid-purity PGMEAc grades for electronics cleaning applications, with vendor-managed inventory systems offering a differentiated go-to-market angle for mid-size coatings formulators. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized super-pure distillation assets and stranded semiconductor-grade certification capabilities. Long-term viability over the coming decade hinges on positioning within advanced lithography node supply chains. The signal to watch is foundry capital expenditure allocation toward sub-5nm capacity, which dictates specification premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Oxide | Dow's Gulf Coast positions secure cost-advantaged feedstock against refinery rate volatility. |
| Super-Pure Distillation Capacity Expansion | East Asian clusters concentrate investment where sub-ppb metal thresholds command specification premiums. |
| Long-term Purity-Guarantee Contracts | Samsung and SK Hynix procurement prioritizes supply security over price competition in foundry chemical management. |
| Vendor-Managed Inventory Systems | Digital platforms with real-time certification tracking reduce working capital burdens for mid-size formulators. |
| Local Blending Infrastructure in India | PLI scheme incentives attract solvent distributors to establish certification capabilities near semiconductor assembly zones. |
Study Parameters
Initial hypotheses were tested against primary input from plant managers at integrated petrochemical complexes, procurement leads at semiconductor foundries, distribution channel partners, and technical R&D directors at coatings formulators, and refined through secondary validation against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA regulatory documentation. Bottom-up capacity and consumption estimates were triangulated with top-down market sizing across producer disclosures.
Variance decomposition across grade tier, end-use industry, regional production hub, and purity certification level shaped the analytical framework over the projection horizon. CAGRs were derived from segmented demand elasticity modeling and supply-side capacity expansion schedules. Forecast inputs incorporated semiconductor node transition timelines and coatings reformulation compliance deadlines.
Material uncertainties — propylene oxide feedstock volatility, foundry qualification timeline extensions, and REACH authorization pathway modifications — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and capital expenditure allocation patterns. Practitioners should keep alternative scenarios live as EPA NESHAP compliance deadlines and Yangtze River Delta emissions enforcement actions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Mixed Xylene Market
Solvents
Para Nitrochlorobenzene Market
Solvents
Diethylene Glycol Monobutyl Ether Acetate Market
Solvents
Solvent Recovery Systems Market
Solvents
6-Xylenol Market
Solvents
Green Solvents and Bio-Solvents Market
Solvents
Propylene Glycol Ether Market
Solvents
Global Green and Bio-Based Solvents Market
Solvents
Allyl Cyanide Market
Solvents
Trichloroacetyl Chloride Market
Solvents
Toluene Market
Solvents
Butyl Glycol Market
Solvents
Benzylamine Market
Solvents
Diethyl Ether Market
Solvents
2-Phenylethanol Market
Solvents
Phenol Derivatives Market