
 Diethyl Ether Market | 2026-2036
Diethyl Ether Market Size, Share, and Industry Trends Forecast 2026-2036
Diethyl Ether Market Analytics
China is narrowing its diethyl ether supply gap through expanded petrochemical capacity in Shandong and Jiangsu provinces. BASF SE leverages integrated ethylene oxide streams to sustain cost-advantaged output across European and Asian sites. LyondellBasell Industries Holdings BV anchors North American supply through its Channelview complex, while INEOS competes on specialty-grade flexibility for laboratory and pharmaceutical contracts.
Diethyl ether is a volatile, highly flammable organic ether with the formula (C₂H₅)₂O, boiling at 34.6°C and serving primarily as a non-polar solvent for extractions, reactions, and engine starting fluids. Industrial-grade material dominates volume flows into fuel and chemical processing, while laboratory-grade commands premium pricing due to stringent purity protocols for pharmaceutical and analytical use. Solvent applications lead absolute demand, though extractant use in natural product processing is expanding fastest as botanical and nutraceutical industries scale.
EPA oversight in the United States governs volatile organic compound emissions and workplace exposure limits under OSHA standards, while REACH in Europe mandates hazard communication and substitution assessments for reproductive-toxicity-classified solvents. India's Central Pollution Control Board enforces storage and handling norms that shape distributor compliance costs. Stakeholders must monitor regulatory divergence on ether classification between jurisdictions to anticipate reformulation mandates and regional supply reallocations.
Market Dynamics
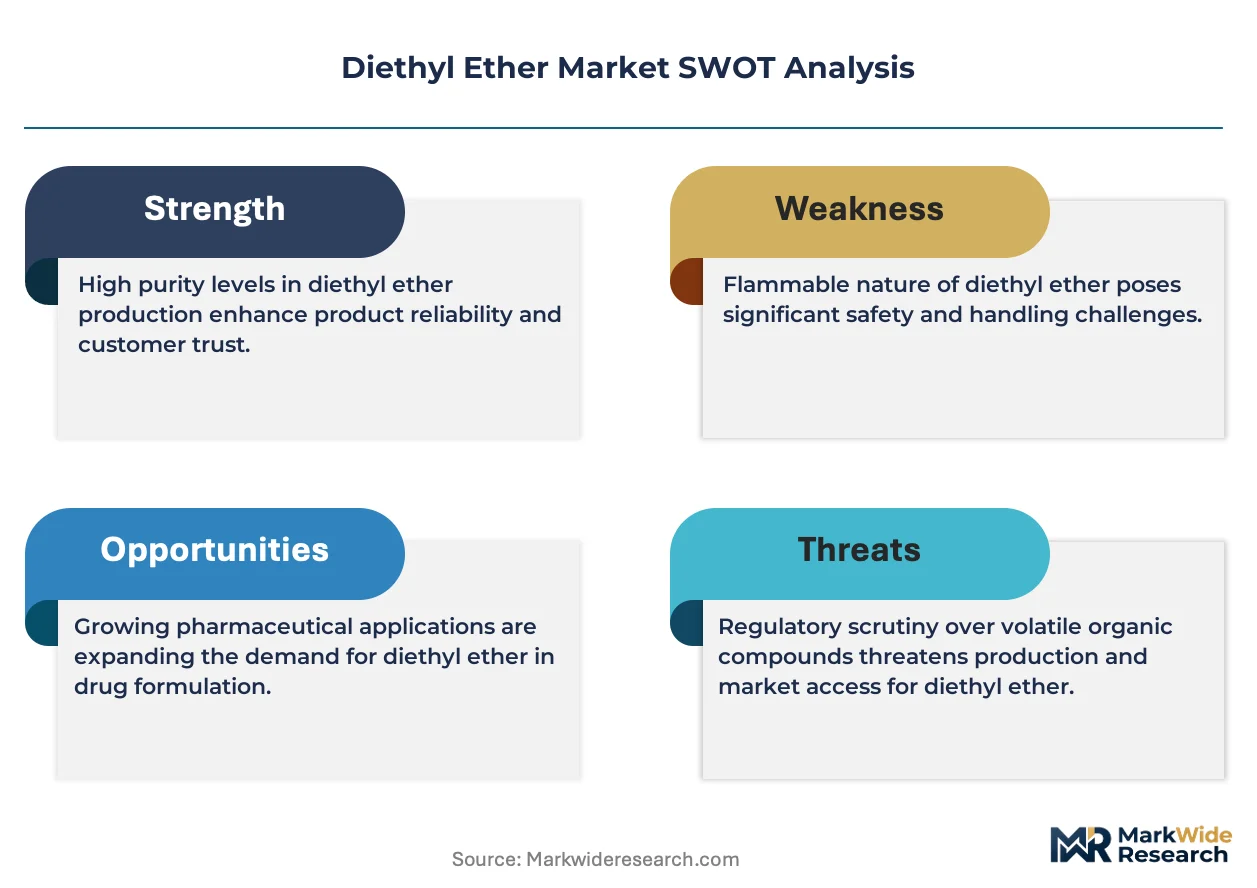
REACH compliance in Europe is compressing available supply of pharmaceutical-grade diethyl ether as purification costs rise, while India's chemical manufacturing expansion is absorbing regional solvent volumes faster than producers can expand capacity.
Growth Catalysts
- Pharmaceutical laboratory expansion:Contract research organizations in India and China are scaling solvent procurement for extraction and reaction protocols, tightening spot-market availability.
- REACH solvent substitution mandates:ECHA's reproductive-toxicity classification is pushing formulators toward diethyl ether in specific extraction applications where alternatives fail purity thresholds.
- Natural product processing boom:Botanical extract manufacturers in the United States are adopting diethyl ether for lipophilic compound isolation, outpacing ethanol demand in nutraceutical supply chains.
Market Restraints
- Ethylene feedstock volatility:Crude oil price swings directly compress margins for ethylene-oxide-derived ether production, particularly affecting non-integrated processors.
- Shandong supply concentration:China's diethyl ether capacity clusters in two provinces, exposing buyers to regional shutdown risks from environmental inspections or petrochemical maintenance cycles.
- Green solvent substitution:Supercritical CO₂ extraction systems are displacing ether in select botanical applications where capital budgets permit equipment upgrades.
Strategic Opportunities
- Domestic Indian chemical manufacturing:PLI scheme incentives for active pharmaceutical ingredient production are creating captive solvent demand that local distributors can capture through backward integration.
- Specialty-grade laboratory contracts:Pharmaceutical quality agreements now specify residue limits below standard industrial grades, enabling premium pricing for certified producers.
- Digital inventory platforms:B2B chemical marketplaces are collapsing traditional distributor layers, allowing manufacturers to serve mid-size laboratories directly with just-in-time replenishment.
Industry Challenges
- Pharmaceutical-grade certification timelines:FDA and EMA audit requirements for excipient-grade ether extend qualification cycles to 18-24 months, freezing out new entrants.
- Hazmat logistics reconfiguration:Port authorities in Rotterdam and Houston are tightening container specifications for flammable solvent shipments, forcing freight contract renegotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diethyl Ether Market |
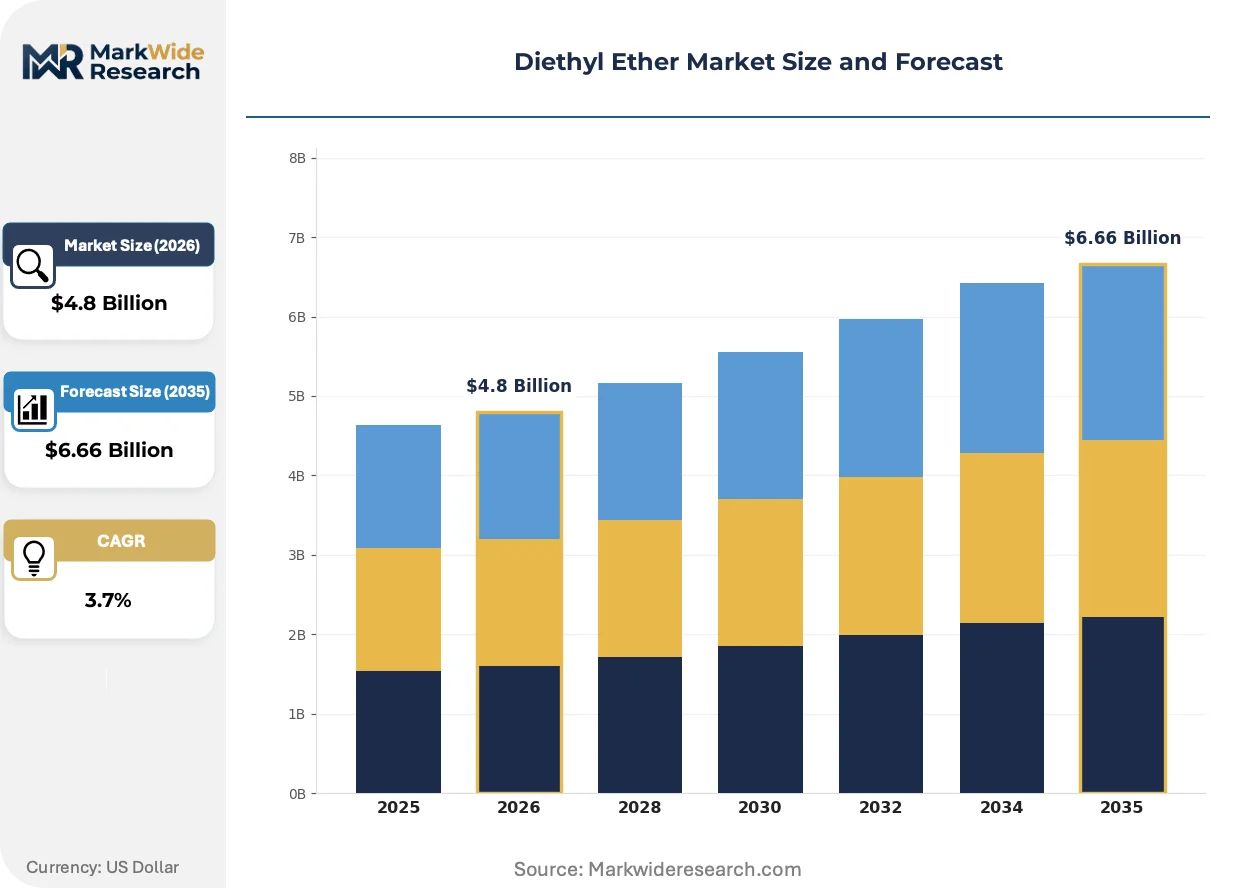
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Solvent, Fuel, Extractant, Refrigerant End User: Pharmaceuticals, Chemicals, Laboratories, Cosmetics Packaging Type: Drums, Containers, Cylinders, Bottles Grade: Industrial Grade, Purity Grade, Laboratory Grade, Commercial Grade |
| Companies Covered | BASF SE, Kishida Chemical Co.,Ltd., LyondellBasell Industries Holdings BV, Industrial Solvents & Chemicals Pvt Ltd, Shri Rajaram Chemicals & Engg, Merck KGaA, Junsei Chemical Co.,Ltd., Standard Reagents Pvt Ltd., INEOS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diethyl Ether Market Evolving Landscape
Membrane separation technology is collapsing traditional distillation economics for high-purity ether production, while regulatory divergence between EPA and ECHA is fragmenting formulation standards across Atlantic supply chains.
Advanced pervaporation membranes are collapsing energy requirements for dehydration of diethyl ether streams below 100 ppm water content. Pharmaceutical manufacturers in Germany and Switzerland are adopting these units for in-house solvent recovery, eliminating virgin ether purchases for internal循环 processes. BASF and specialty engineering firms are licensing modular skid designs that compress payback periods to under three years for high-throughput laboratories.
REACH Annex XIV authorization requirements for reprotoxic substances are forcing solvent users to document substitution assessments or secure time-limited exemptions. Chemical processors in the Netherlands and Belgium are consolidating ether-handling permits to reduce compliance overhead, concentrating volume with permit-holding distributors. The regulatory friction is diverting some botanical extraction demand toward Spain and Portugal where enforcement timelines lag northern Europe.
Laboratory procurement managers are consolidating chemical purchasing through enterprise agreements with single-source distributors rather than spot-market spot-buying. University and government research clusters in the United States are shifting to annual frame contracts with fixed pricing, displacing traditional reagent house relationships. This concentration is most visible in the NIH-funded research corridor spanning Maryland and North Carolina, where three distributors now capture majority ether volumes.
Diethyl Ether Market Segmentation
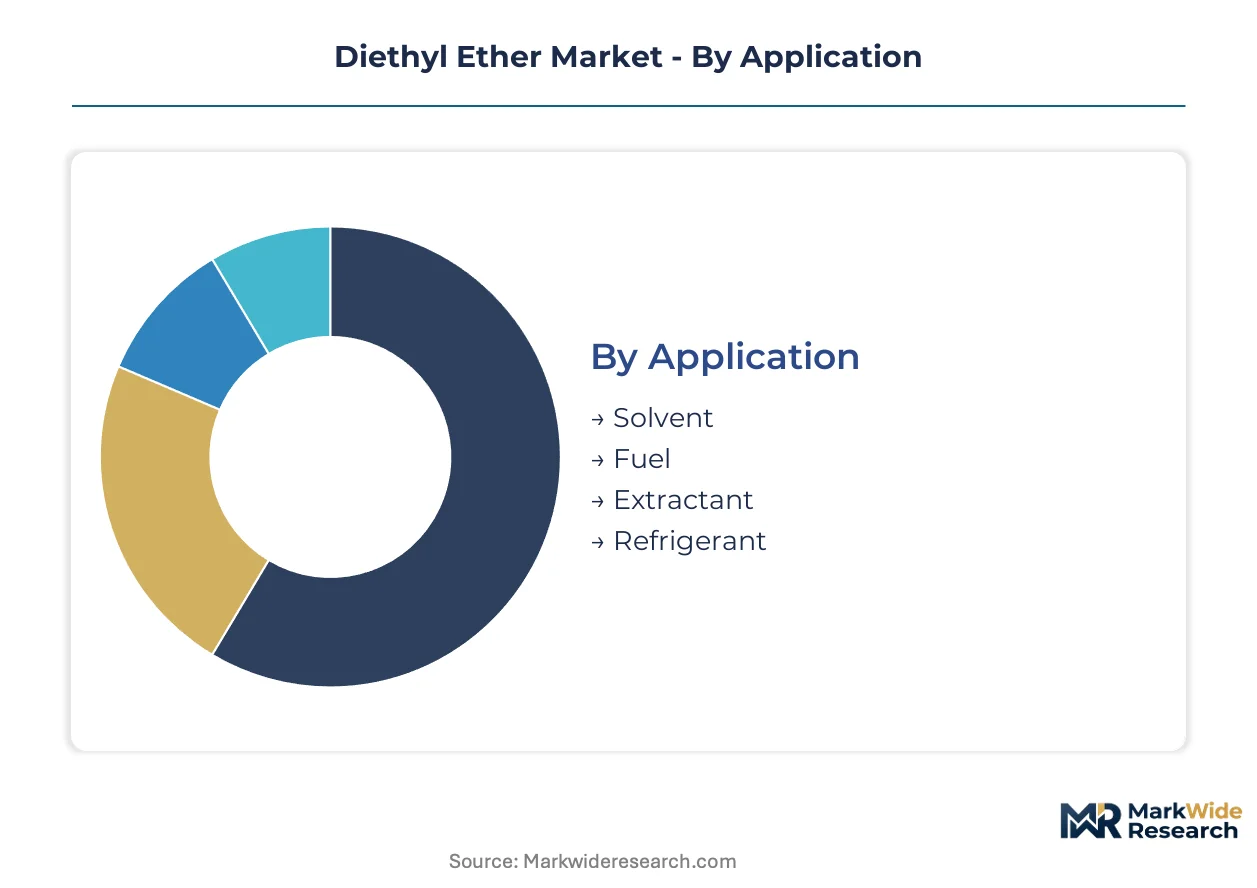
Segmentation in diethyl ether markets separates volume-driven commodity flows from precision-grade laboratory contracts where certification protocols and supply security dominate procurement decisions. Buyers across pharmaceutical, chemical, and fuel applications operate on fundamentally different technical specifications, hazard-handling requirements, and pricing tolerances that reshape competitive positioning.
Application:
After-sales service intensity varies sharply across applications, with laboratory and pharmaceutical solvent users demanding technical support for storage compliance and recovery systems that fuel buyers rarely require.
- Solvent:Non-polar solvent properties enable Grignard reactions, extractions, and crystallizations across organic synthesis workflows. Pharmaceutical manufacturers in Germany and Switzerland specify residue limits below 10 ppm for API production, tightening supply qualification. Demand concentrates in contract research organizations scaling throughput in India and China.
- Extractant:Lipophilic compound isolation from botanical matrices drives fastest expansion as nutraceutical processors adopt ether for essential oil and alkaloid recovery. United States botanical extract manufacturers are outpacing ethanol demand in hemp and specialty crop processing.
- Fuel:Engine starting fluid formulations leverage high volatility and low flash point for cold-weather ignition assistance. Automotive aftermarket distributors in North America and Europe manage seasonal inventory cycles with limited technical service requirements.
- Refrigerant:Historic use in closed-loop cooling systems persists in legacy industrial equipment where retrofit costs prohibit modern refrigerant adoption. Maintenance contractors in Japan and South Korea service installed base with diminishing replacement volumes.
Solvent commands the largest share; momentum sits with extractant as natural product processing scales.
End User:
Cost tier stratification separates pharmaceutical quality agreements with 18-24 month qualification cycles from spot-market chemical processor procurement.
- Pharmaceuticals:Excipient-grade ether for tablet coatings and API synthesis demands FDA and EMA audit trails, locking suppliers into long-term quality agreements. European manufacturers face REACH reproductive-toxicity documentation requirements that compress available certified supply.
- Chemicals:Intermediate production for pesticides, plastics additives, and specialty chemicals consumes industrial-grade volumes with flexible purity tolerances. Shandong and Jiangsu province petrochemical complexes anchor regional supply for Asian chemical processors.
- Laboratories:Analytical reagent specifications for chromatography and spectroscopy require sub-100 ppm water content with batch certification. University research clusters in Maryland and North Carolina are consolidating procurement through annual frame contracts.
- Cosmetics:Fragrance extraction and formulation use remains niche due to flammability restrictions and consumer safety perceptions. European cosmetic manufacturers face stricter volatility labeling under CLP regulation than counterparts in other regions.
Chemicals holds the largest share; steepest expansion trajectory belongs to laboratories as research funding concentrates.
Packaging Type:
Volume scale and hazard classification dictate packaging economics, with bulk drum shipments dominating chemical processor procurement while cylinder and bottle formats serve fragmented laboratory demand.
- Drums:Standard 200-liter steel drums with UN-certified closures enable efficient bulk transport to chemical manufacturers and fuel blenders. Rotterdam and Houston port authorities are tightening container specifications for flammable solvent shipments.
- Containers:Intermediate bulk containers and tote systems reduce handling costs for mid-scale pharmaceutical and botanical extract processors. Indian distributors are investing in reusable container fleets to serve domestic chemical manufacturing expansion.
- Cylinders:Pressurized metal cylinders with specialized valves serve high-purity laboratory and pharmaceutical applications requiring inert atmosphere preservation. German and Swiss pharmaceutical manufacturers specify cylinder formats for in-house solvent recovery integration.
- Bottles:Amber glass and fluoropolymer bottles in 1-liter to 20-liter capacities protect light-sensitive reagents for analytical laboratories. B2B chemical marketplaces are enabling direct manufacturer-to-laboratory distribution, collapsing traditional reagent house layers.
Drums holds the largest share; gaining share fastest are containers as mid-scale processors seek handling efficiency.
Grade:
Margin structure inverts across grades, with laboratory and purity grades commanding 3-5x industrial-grade pricing due to certification overhead and batch traceability requirements.
- Industrial Grade:95-99% purity specifications serve fuel additives, general cleaning, and non-critical chemical processing where water content tolerance exceeds 1000 ppm. Chinese petrochemical producers leverage integrated ethylene oxide streams for cost-advantaged output.
- Laboratory Grade:99.5%+ purity with comprehensive batch analysis certificates supports analytical chemistry and research applications. Membrane separation technology is collapsing energy requirements for dehydration below 100 ppm water content.
- Purity Grade:Intermediate specifications for pharmaceutical intermediate production balance cost against controlled impurity profiles. Indian API manufacturers under PLI scheme incentives are absorbing regional purity-grade volumes faster than capacity expands.
- Commercial Grade:Variable specifications for non-critical industrial applications including degreasing and parts cleaning. Green solvent substitution with aqueous and bio-based alternatives is displacing volumes in environmentally regulated jurisdictions.
Industrial grade holds the largest share; laboratory grade climbs the fastest as certification requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam-Botlek port complex anchors European ether flows through specialized solvent handling terminals that serve BASF's integrated Ludwigshafen operations. This infrastructure underwrites the continent's pharmaceutical-grade supply security despite tightening REACH compliance costs.
United States
Contract research organizations along the NIH-funded Maryland-North Carolina corridor are consolidating annual frame contracts for laboratory-grade ether. EPA oversight governs volatile organic compound emissions from Gulf Coast petrochemical sites. The LyondellBasell Channelview complex near Houston anchors North American industrial-grade supply.
Germany
Pharmaceutical manufacturers in Ludwigshafen and Leverkusen specify residue limits below 10 ppm for active pharmaceutical ingredient production. ECHA's reproductive-toxicity classification mandates substitution assessments for solvent users. BASF SE leverages integrated ethylene oxide streams across its Ludwigshafen site to sustain cost-advantaged output.
China
Shandong and Jiangsu province petrochemical complexes are narrowing the domestic supply gap through expanded ethylene oxide capacity. MEE environmental inspections periodically trigger regional shutdowns that expose buyer concentration risk. Qingdao and Ningbo port authorities handle bulk drum shipments for chemical processors across the Yangtze River Delta.
India
PLI scheme incentives for active pharmaceutical ingredient production are creating captive solvent demand that outpaces local capacity expansion. The Central Pollution Control Board enforces storage and handling norms that reshape distributor compliance costs. Gujarat and Maharashtra chemical manufacturing clusters are absorbing regional solvent volumes faster than producers can expand.
Switzerland
German and Swiss pharmaceutical manufacturers are adopting membrane separation technology for in-house solvent recovery below 100 ppm water content. Swissmedic audit requirements extend excipient-grade ether qualification cycles to 18-24 months. Basel-area pharmaceutical sites are licensing modular pervaporation skid designs from specialty engineering firms.
Diethyl Ether Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply web. The diethyl ether market structures around three tiers: integrated petrochemical majors with ethylene oxide backward integration, regional distributors with permit-holding logistics capabilities, and specialty reagent houses serving laboratory certification requirements. Competitive moves concentrate on membrane technology licensing partnerships and pharmaceutical-grade quality agreement consolidation.
Among Germany-based chemical majors, BASF SE and Merck KGaA exemplify divergent archetypes—BASF representing integrated petrochemical scale, Merck occupying the precision-grade laboratory reagent tier. INEOS and LyondellBasell Industries Holdings BV anchor the commodity-scale segment across European and North American sites respectively. Japanese specialists Kishida Chemical Co.,Ltd. and Junsei Chemical Co.,Ltd. sit within the Asia-Pacific laboratory-grade supply tier.
| Leading Market Players |
|---|
| BASF SE |
| Kishida Chemical Co.,Ltd. |
| LyondellBasell Industries Holdings BV |
| Industrial Solvents & Chemicals Pvt Ltd |
| Shri Rajaram Chemicals & Engg |
| Merck KGaA |
| Junsei Chemical Co.,Ltd. |
| Standard Reagents Pvt Ltd. |
| INEOS |
| Others |
Value Network & Pricing Analysis
Undercapacity in Indian pharmaceutical-grade ether production is compressing spot-market availability and forcing buyers into longer-term offtake commitments with integrated suppliers. This utilization squeeze simultaneously elevates supplier bargaining power and accelerates price stratification across certification tiers.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-quality agreements with 18-24 month qualification cycles from spot-market chemical processor procurement. Three-tier pricing stratification across laboratory, purity, and industrial grades reflects certification overhead and batch traceability requirements. Price differentiation hinges on residue-limit specifications and REACH compliance documentation. Pricing pressure stems from ethylene feedstock volatility affecting non-integrated processors. Fuel blenders exhibit highest price sensitivity; pharmaceutical manufacturers accept premium positioning for supply security.
Supply Chain Analysis
Extended payment terms from Shandong and Jiangsu petrochemical complexes are reshaping working capital requirements for Asian distributors. Supply concentrates in China, Germany, and India for distinct grade tiers. Ethylene oxide, sulfuric acid, and ethanol feedstock dependencies tether production to crude oil and agricultural commodity cycles. Single-source vulnerability from Shandong environmental inspection exposure concentrates buyer risk. Distribution runs through Rotterdam-Botlek solvent terminals and Houston Gulf Coast chemical corridors for Atlantic flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as REACH compliance bifurcates supply into permit-holding distributors versus spot-market traders, creating niche capture points for specialized logistics operators.
For Market Incumbents: Build certification moats through FDA and EMA excipient-grade audit trails that freeze out new entrants for 18-24 month qualification windows. BASF SE and Merck KGaA should deepen backward integration into ethylene oxide to defend margin position against feedstock volatility. Channel control through annual frame contracts with NIH-funded research clusters locks out reagent house competitors.
For New Entrants and Emerging Players: Mid-scale botanical extract processors in the United States represent the most penetrable entry point where supercritical CO₂ capital constraints preserve ether demand. Indian PLI scheme API manufacturers offer second white-space target through captive solvent partnerships. Go-to-market angle: direct B2B marketplace distribution collapsing traditional reagent house layers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among permit-holding distributors with REACH authorization and pharmaceutical quality agreements. Long-term viability centers on regulatory compliance infrastructure rather than commodity volume exposure. Signal to watch: membrane technology licensing partnerships indicating in-house recovery adoption that displaces virgin ether purchases.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | BASF SE sustains cost-advantaged output across Ludwigshafen and Asian sites. |
| Pharmaceutical-Grade Certification Investment | Merck KGaA locks suppliers into 18-24 month EMA audit qualification cycles. |
| Membrane Technology Licensing | German and Swiss manufacturers adopt pervaporation skid designs for solvent recovery. |
| Direct B2B Marketplace Distribution | Digital platforms collapse reagent house layers serving Maryland-North Carolina research clusters. |
| Permit Consolidation for REACH Compliance | Netherlands and Belgium processors concentrate volume with authorization-holding distributors. |
Research Methodology
The analysis maps solvent, extractant, fuel, and refrigerant applications, each validated through procurement managers at contract research organizations, technical directors at botanical extract processors, and logistics coordinators at Rotterdam-Botlek terminals. Primary interviews with plant managers at Shandong petrochemical complexes, pharmaceutical quality assurance leads in Ludwigshafen, and Indian distributor operations heads combined with secondary validation from customs/trade data, ECHA authorization registries, and SEC 10-K filings. Bottom-up volume modeling and top-down market sizing triangulated across grade-tier and end-use dimensions.
Assumption sets held regulatory enforcement timelines and ethylene feedstock pricing bands fixed while varying pharmaceutical laboratory expansion rates and natural product processing adoption curves across the projection horizon. Segmentation modeling incorporated grade tier, end-use industry, packaging format, and regional production hub dimensions. CAGRs derived from weighted average growth contributions across application segments. Industry-specific inputs included REACH Annex XIV authorization schedules and PLI scheme incentive disbursement patterns.
Stress conditions across ethylene oxide supply disruptions, MEE environmental inspection intensities, and supercritical CO₂ equipment cost declines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory divergence and feedstock pricing stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Electronic Cleaning Solvents Market
Solvents
Mineral Turpentine Market
Solvents
Toluene Market
Solvents
Global Solvent Dyes Market
Solvents
N-Methyl Pyrrolidone Market
Solvents
Global Solvent Evaporation Market
Solvents
1, 1-Difluoroethane Market
Solvents
Diethylene Glycol (DEG) Market
Solvents
Natural Distillates Market
Solvents
Phenol Derivatives Market
Solvents
Global Tert-Butanol Market
Solvents
2,2-Dimethylbutyryl Chloride Market
Solvents
Benzyl Alcohol Market
Solvents
Solvent Recovery Systems Market
Solvents
United States Acetonitrile Market
Solvents
Fluorinated Solvents Market