
 Solvent Recovery Systems Market | 2026-2036
Solvent Recovery Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Solvent Recovery Systems Market Outlook
Maintenance and remote monitoring subscriptions is restructuring how solvent recovery vendors monetize equipment. Veolia leverages its service network to anchor long-term contracts across European chemical parks. Sulzer competes through specialized distillation module designs that extend equipment uptime guarantees. Koch Modular Process Systems dominates North American project engineering for custom solvent recovery skids.
Solvent recovery systems are industrial equipment that separate and purify spent organic solvents through thermal distillation, adsorption, or membrane filtration, typically achieving recovery purity levels of 95-99.5% for reuse in manufacturing processes. These systems reduce virgin solvent procurement costs and hazardous waste disposal volumes for chemical, pharmaceutical, and coatings operations. Batch systems currently occupy the largest installed base due to lower capital barriers, though continuous configurations are capturing growth in high-throughput chemical processing where uninterrupted solvent loops yield superior unit economics. Membrane technology leads R&D investment as manufacturers seek energy-efficient alternatives to thermal distillation for heat-sensitive solvent streams.
EPA hazardous waste regulations under RCRA and OSHA process safety standards mandate solvent tracking and emissions controls that directly drive recovery system procurement in US manufacturing facilities. ECHA REACH restrictions on volatile organic compound releases and the EU Green Deal industrial emissions framework are tightening discharge limits across European chemical production. India's Central Pollution Control Board enforcement of hazardous waste management rules and BIS effluent standards are expanding the compliance-driven addressable market. Stakeholders must evaluate whether technology portfolios align with emerging per- and polyfluoroalkyl substance recovery requirements before committing capital to next-generation system designs.
Market Dynamics
Membrane separation technology is compressing energy intensity benchmarks for solvent purification, forcing thermal distillation incumbents to defend installed bases through hybrid system architectures that preserve capital investments while meeting tightening ECHA REACH emission thresholds.
Growth Catalysts
- EU Green Deal industrial emissions framework:Chemical manufacturers in Germany and Belgium are retrofitting solvent loops to comply with tightening volatile organic compound discharge limits, triggering replacement cycles for aging batch distillation units.
- Pharmaceutical manufacturing expansion:Active pharmaceutical ingredient producers in India are deploying recovery systems to reduce virgin solvent procurement costs and hazardous waste disposal volumes under BIS environmental standards.
- Continuous processing adoption:Specialty chemical corridors near Gujarat are shifting from batch to continuous solvent recovery configurations to achieve uninterrupted production loops and superior unit economics.
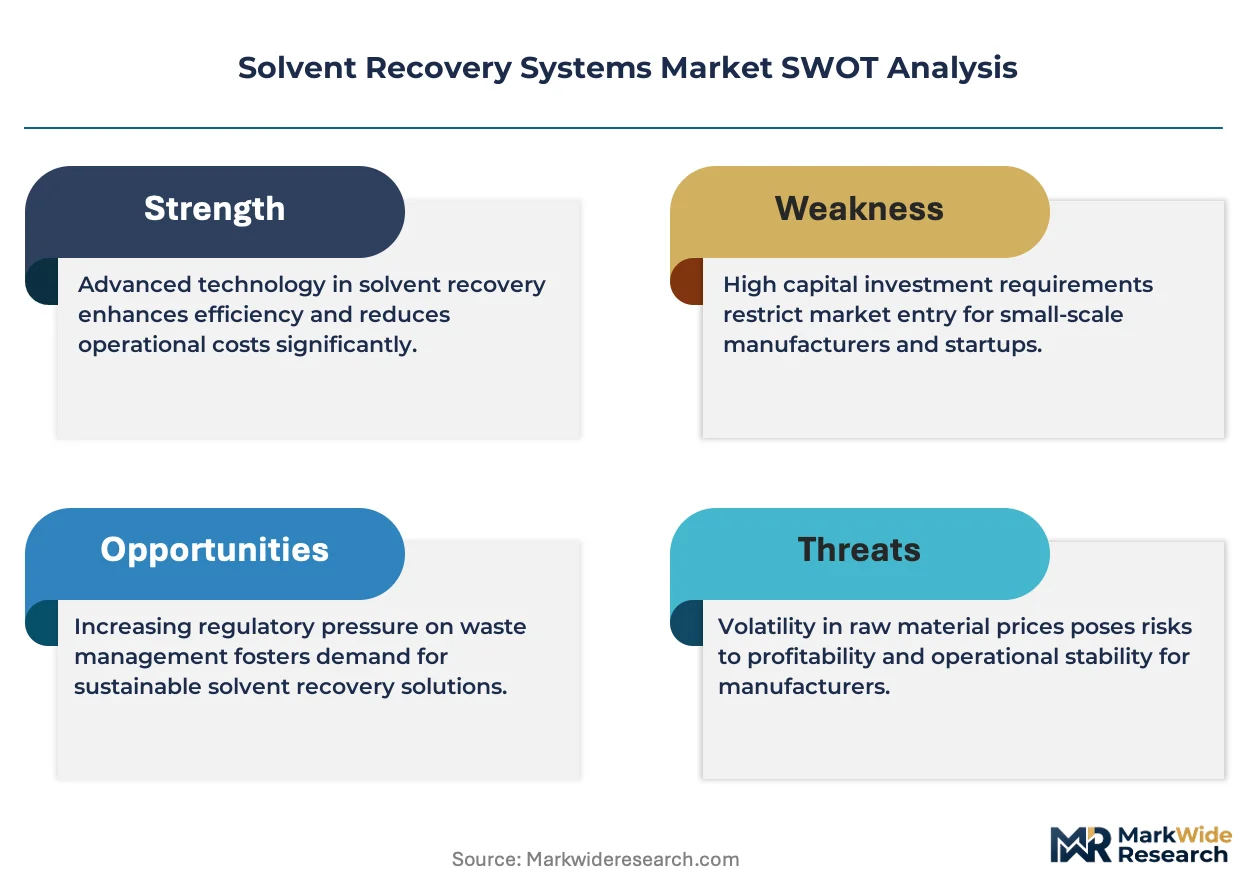
Market Restraints
- Stainless steel alloy price volatility:Distillation column construction depends on 316L and duplex stainless grades, with nickel and molybdenum input costs subject to LME trading fluctuations that compress equipment margins.
- Skilled commissioning engineer scarcity:System startups require certified technicians capable of calibrating multi-stage separation trains, with talent pools concentrated in Germany, Switzerland, and select US Gulf Coast chemical clusters.
- Legacy asset stranding risk:Pharmaceutical facilities with decade-old thermal oxidation units face write-down pressure as membrane and adsorption alternatives achieve comparable purity at lower operating expenditure.
Strategic Opportunities
- Per- and polyfluoroalkyl substance recovery:Fluorinated solvent streams from semiconductor etching operations represent an unserved technical frontier where specialized membrane-cryogenic hybrid systems could command premium positioning.
- India PLI scheme for chemical manufacturing:Production-linked incentives are accelerating capital deployment into recovery equipment across Maharashtra and Gujarat specialty chemical zones.
- Remote monitoring subscription models:Equipment vendors are unbundling hardware from predictive maintenance services, creating recurring revenue streams anchored to uptime guarantees rather than one-time system sales.
Industry Challenges
- Cross-contamination validation protocols:Pharmaceutical solvent recovery requires documented cleaning verification between product campaigns, extending commissioning timelines and demanding specialized analytical chemistry capabilities.
- Legacy distributed control system integration:Brownfield chemical plants operate on proprietary automation architectures from the 1990s, forcing costly gateway engineering to connect modern recovery skids to existing plant historians.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solvent Recovery Systems Market |
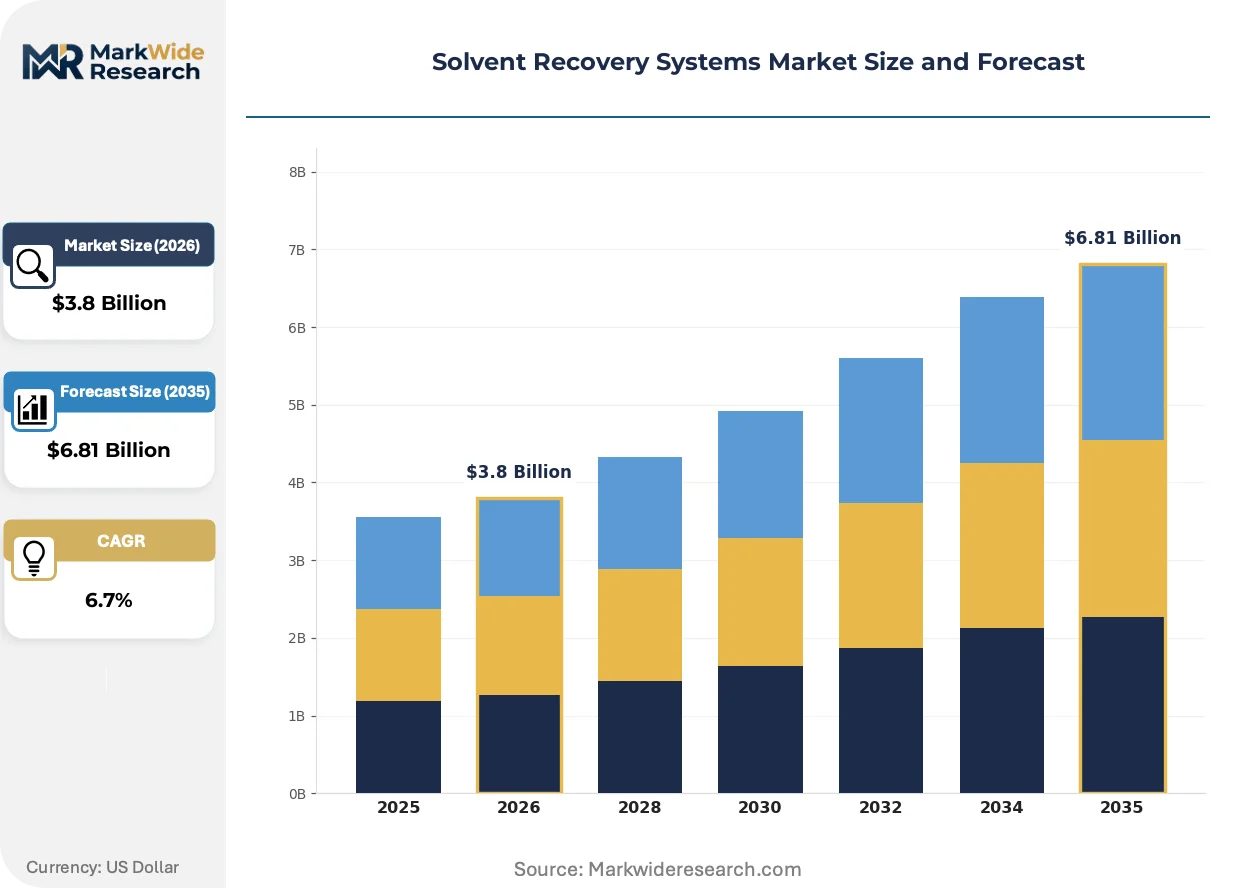
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Batch, Continuous, Hybrid, Mobile Technology: Distillation, Adsorption, Membrane, Extraction End User: Aerospace, Automotive, Pharmaceuticals, Chemicals Application: Industrial Cleaning, Paint Thinning, Waste Management, Surface Coating |
| Companies Covered | Koch Modular Process Systems, Indaver, Veolia, CBG Technologies, EPIC Modular Process Systems, Clean Harbors, Tradebe Environmental Services, Spooner AMCEC, Sulzer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solvent Recovery Systems Market Strategic Shifts
Equipment architectures are fragmenting into configurable subsystems that permit site-specific assembly without custom engineering, while regulatory pressure on carbon intensity and solvent emissions accelerates technology substitution cycles across chemical processing verticals.
Membrane pervaporation technology is modularizing solvent dehydration and impurity rejection into standardized skid-mounted units that pharmaceutical manufacturers in Switzerland and Germany are adopting for heat-sensitive active pharmaceutical ingredient streams. These systems enable distributed purification nodes within multi-building manufacturing campuses, compressing centralized utility infrastructure requirements and reducing thermal degradation risks for high-value solvents.
ECHA REACH restrictions on volatile organic compound releases are mandating closed-loop solvent management across European coatings and adhesive production, with the EU Green Deal industrial emissions framework extending monitoring obligations to smaller batch operations previously exempt from continuous emission monitoring systems. German chemical park operators are responding by centralizing recovery services through shared infrastructure models that amortize capital across multiple tenant facilities.
Service unbundling is separating equipment ownership from performance guarantees, with chemical processors in India's specialty chemical corridor contracting for recovered solvent purity outcomes rather than purchasing systems outright. This consumption-pattern shift transfers operational risk to vendors while aligning payment schedules with verified solvent recovery rates, a model most visible in Gujarat's pharmaceutical manufacturing clusters where capital discipline favors operating expenditure structures.
Solvent Recovery Systems Market Segmentation
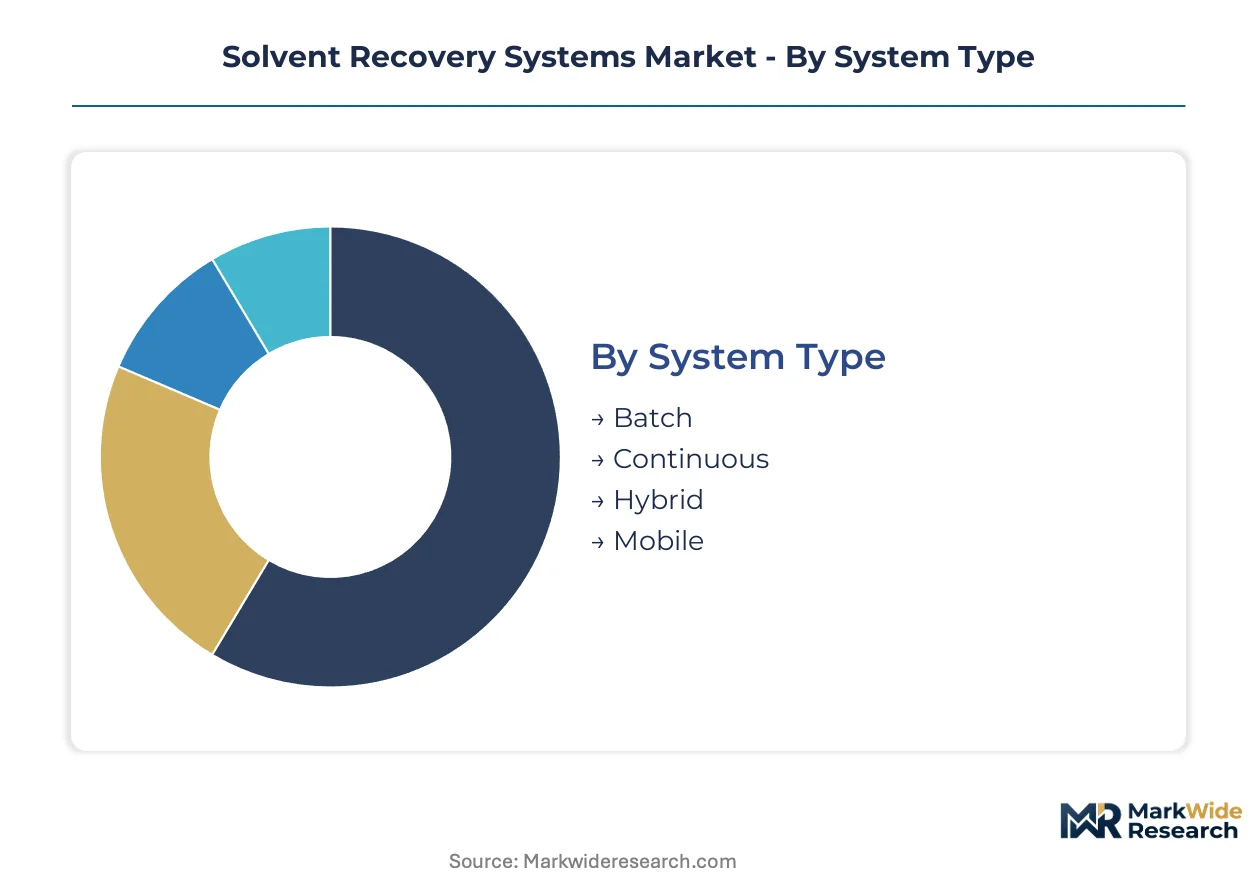
Solvent recovery systems fragment across operational configurations, purification technologies, and vertical applications. Each segmentation axis carries distinct capital intensity profiles and regulatory compliance burdens that reshape vendor positioning.
System Type:
Batch systems dominate installed base volume while continuous configurations command premium positioning through throughput economics.
- Batch:Intermittent processing cycles suit small-to-medium pharmaceutical and coatings operations with variable solvent streams. German chemical parks deploy batch units for multi-tenant flexibility where campaign changeovers demand frequent cleaning validation under ECHA REACH protocols.
- Continuous:Uninterrupted solvent loops achieve superior unit economics in high-throughput chemical processing. India's Gujarat specialty chemical corridor is shifting toward continuous configurations to maximize production uptime under BIS environmental enforcement.
- Hybrid:Combines batch flexibility with continuous efficiency modules for mid-scale operations balancing versatility against capital constraints.
- Mobile:Skid-mounted transportable units serve distributed waste collection networks and temporary manufacturing sites requiring rapid deployment.
Today's leader: Batch. Tomorrow's challenger: Continuous.
Technology:
Energy intensity and heat sensitivity requirements divide technology selection across end-use verticals.
- Distillation:Thermal separation achieves 95-99.5% purity through controlled boiling point differentiation. Established European chemical manufacturers defend installed distillation bases through hybrid architectures that preserve capital while meeting tightening EU Green Deal emission thresholds.
- Membrane:Pervaporation and nanofiltration modules reduce energy consumption for heat-sensitive solvent streams. Swiss and German pharmaceutical manufacturers are modularizing membrane units into distributed purification nodes within multi-building campuses.
- Adsorption:Activated carbon and zeolite systems capture trace contaminants in polishing applications where thermal degradation risks exclude distillation.
- Extraction:Liquid-liquid separation handles azeotropic mixtures and complex multi-component solvent blends resistant to simpler purification methods.
Thermal distillation retains volume leadership. Membrane separation gains share fastest through energy efficiency positioning.
End User:
Regulatory stringency and solvent throughput intensity determine vertical penetration depth.
- Pharmaceuticals:Active pharmaceutical ingredient manufacturing generates high-purity solvent recovery demand under FDA and EMA validation requirements. Cross-contamination protocols extend commissioning timelines but create substantial recurring service revenue for qualified vendors.
- Chemicals:Specialty and commodity chemical production represents the largest addressable volume, with Indian PLI scheme incentives accelerating capital deployment across Maharashtra and Gujarat manufacturing zones.
- Automotive:Paint shops and coating lines drive solvent recovery adoption under VOC emission controls, with continuous systems preferred for high-volume assembly plant integration.
- Aerospace:Precision cleaning operations for component manufacturing utilize specialized recovery configurations meeting stringent contamination tolerance specifications.
Chemical processing anchors current demand. Pharmaceutical verticals present the steepest expansion trajectory through regulatory compliance mandates.
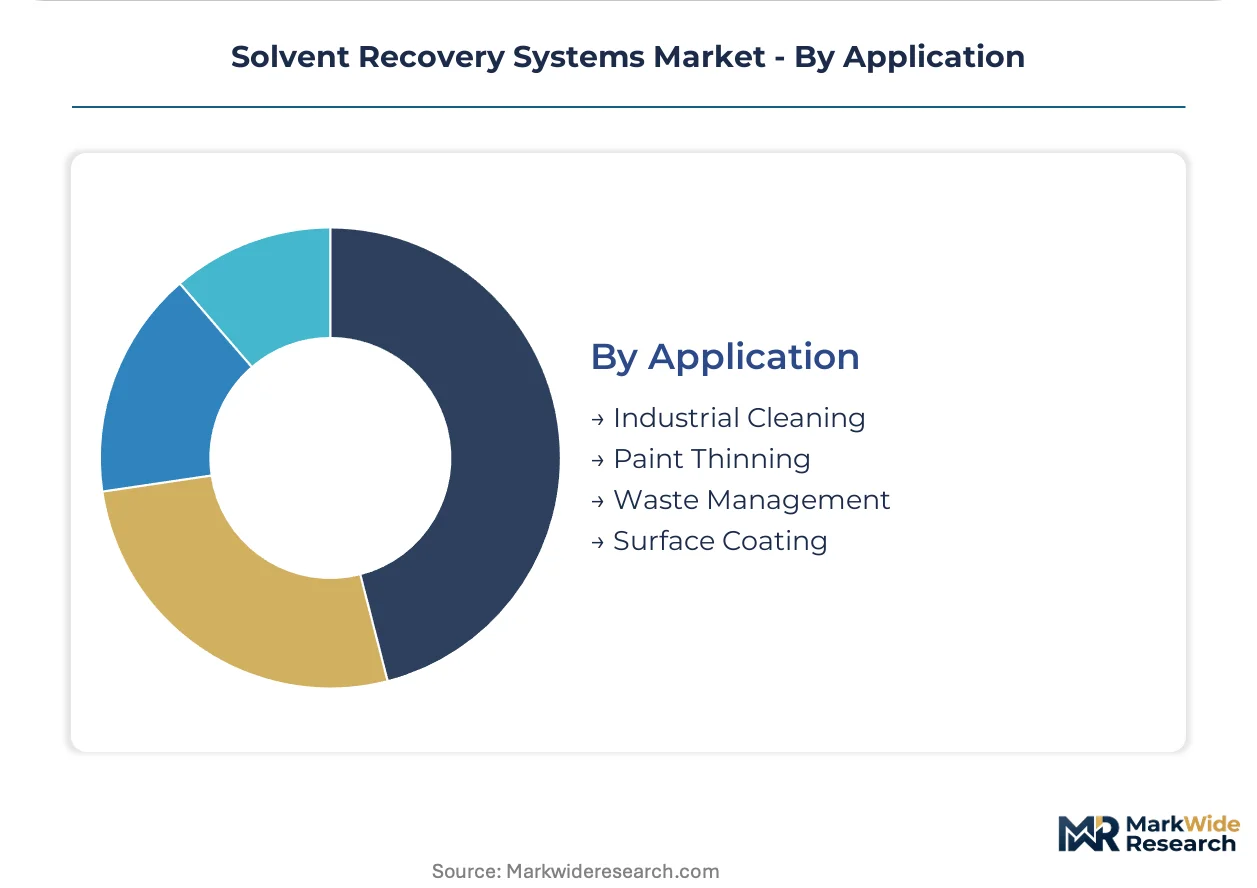
Application:
Waste stream composition and purity requirements segment application-level procurement criteria.
- Industrial Cleaning:Degreasing and parts washing operations generate mixed solvent waste streams requiring flexible recovery configurations. Batch systems predominate where cleaning chemistry varies across production campaigns.
- Waste Management:Centralized recovery services for multi-facility chemical parks amortize capital across tenant operations, a model expanding across German industrial clusters under shared infrastructure frameworks.
- Paint Thinning:Coatings manufacturing and application sites recover blending solvents under VOC regulations, with membrane dehydration modules gaining traction for moisture-sensitive formulations.
- Surface Coating:Adhesive and sealant production lines implement closed-loop solvent management to comply with ECHA REACH discharge restrictions on volatile organic compounds.
Industrial cleaning commands installed base scale. Waste management services are climbing the fastest through chemical park centralization trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the deepest installed base of solvent recovery infrastructure, while India exhibits the steepest near-term expansion trajectory through production-linked incentive schemes and environmental enforcement tightening.
Germany
Pharmaceutical manufacturers in Ludwigshafen and Leverkusen are retrofitting aging batch distillation units to meet ECHA REACH volatile organic compound discharge limits. The EU Green Deal industrial emissions framework is accelerating replacement cycles for thermal oxidation systems. Chemical park operators in North Rhine-Westphalia are centralizing recovery services through shared infrastructure models that amortize capital across multiple tenant facilities.
India
Specialty chemical producers in Gujarat and Maharashtra are deploying continuous solvent recovery configurations to maximize production uptime under BIS hazardous waste management rules. The PLI scheme for chemical manufacturing is channeling capital into membrane and hybrid system installations. Pharmaceutical API clusters near Ahmedabad and Mumbai are shifting from batch to uninterrupted solvent loops to achieve superior unit economics.
United States
Chemical processors along the Texas Gulf Coast and Ohio River Valley are expanding recovery capacity under EPA RCRA hazardous waste tracking mandates. OSHA process safety standards are driving procurement of automated distillation skids with integrated emissions monitoring. Modular equipment fabricators in Houston and Pittsburgh are capturing project engineering demand for custom solvent recovery configurations.
Switzerland
Pharmaceutical manufacturers in Basel are modularizing membrane pervaporation units into distributed purification nodes across multi-building manufacturing campuses. Swissmedic validation requirements are extending commissioning timelines for cross-contamination protocols. Precision chemical operations near Geneva are adopting energy-efficient alternatives to thermal distillation for heat-sensitive active pharmaceutical ingredient streams.
Belgium
Coatings and adhesive producers in Antwerp are implementing closed-loop solvent management to comply with ECHA REACH discharge restrictions. The Port of Antwerp chemical cluster is consolidating recovery infrastructure under shared service frameworks. Batch system retrofits are accelerating as smaller operations lose exemption from continuous emission monitoring obligations under tightening EU frameworks.
Solvent Recovery Systems Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated environmental service providers anchoring long-term contractual relationships while modular engineering houses capture project-based demand. The vendor base organizes into three strategic archetypes: diversified environmental conglomerates with service networks, specialized distillation equipment designers, and regional project engineering boutiques. Competitive positioning hardens through M&A consolidation of waste management assets and technology licensing partnerships that extend geographic reach without capital-intensive manufacturing expansion.
Among diversified environmental service providers, Veolia exemplifies the service-anchored archetype through its European chemical park penetration, while Sulzer occupies a position within specialized thermal separation technology. Koch Modular Process Systems represents the North American project engineering segment focused on custom skid fabrication. These three anchors illustrate how competitive positioning stratifies across service integration, technology specialization, and regional project execution capabilities.
| Leading Market Players |
|---|
| Koch Modular Process Systems |
| Indaver |
| Veolia |
| CBG Technologies |
| EPIC Modular Process Systems |
| Clean Harbors |
| Tradebe Environmental Services |
| Spooner AMCEC |
| Sulzer |
| Others |
Value Chain & Pricing Dynamics
Membrane pervaporation modularization is compressing thermal distillation's cost advantage while concentrating component sourcing in German and Swiss precision manufacturing clusters, creating asymmetric pricing power between hybrid system vendors and pure-play thermal equipment suppliers.
Pricing Analysis
Capacity additions in India are reshaping price floors for batch distillation units as domestic fabricators undercut European incumbents on project engineering. Three-tier pricing structure across premium, standard, and economy levels separates ECHA REACH-certified systems from BIS-compliant domestic alternatives. Cost compression in continuous configurations is intensifying because membrane module suppliers are consolidating procurement leverage. Small pharmaceutical manufacturers in Gujarat exhibit highest price sensitivity, while German chemical park operators prioritize uptime guarantees over capital expenditure.
Supply Chain Analysis
India's phased manufacturing program and domestic-content mandates for chemical processing equipment are redirecting stainless steel fabrication toward indigenous machine shops. Distillation column construction draws from German, Italian, and Indian specialty metalworking centers. 316L and duplex stainless grades, ceramic membrane substrates, and precision control valves constitute critical input dependencies. Single-source vulnerability concentrates in Swiss membrane pervaporation module suppliers. Distribution runs through regional project engineering houses that integrate skid-mounted subsystems for site-specific deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane technology substitution is expanding premium-tier margins for vendors capable of integrating hybrid thermal-membrane architectures, while commoditizing pure thermal distillation at the economy tier.
For Market Incumbents: Cement service-contract anchoring through predictive maintenance subscriptions that transfer operational risk from pharmaceutical processors. Acquire membrane technology licenses to defend against energy efficiency displacement of thermal oxidation bases. Capacity additions in India by Sulzer and Veolia threaten margin compression for European-only service networks. For New Entrants and Emerging Players: System integrators represent the fastest path to market penetration without captive manufacturing infrastructure. Target India's Gujarat specialty chemical corridor where PLI scheme capital deployment outpaces qualified vendor supply. White-space exists in PFAS recovery systems for semiconductor etching operations. Offer purity-outcome contracting rather than equipment sales to bypass capital expenditure barriers. For Investors and Strategic Acquirers: Roll-up economics work for regional project engineering boutiques because customer relationships and commissioning expertise resist commoditization. The 5-10 year viability window favors vendors with membrane technology portfolios over pure thermal distillation legacy assets. Acquire mid-scale modular fabricators with FDA and EMA validation track records. Watch ECHA REACH enforcement intensity as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Manufacturing | Captures margin from ceramic substrate suppliers while securing supply for hybrid system architectures. |
| Remote Monitoring Platform Deployment | Transforms equipment vendors into recurring revenue service providers anchored to uptime guarantees. |
| Joint Venture with Indian Fabricators | Localizes production for PLI scheme compliance while preserving European technology licensing control. |
| Green Manufacturing Certification Program | Aligns system offerings with EU Green Deal carbon intensity disclosure requirements for chemical processors. |
| Long-term Supply Agreement for Stainless Alloys | Hedges LME nickel and molybdenum volatility that compresses distillation column margins. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers at German chemical parks, procurement leads at Indian pharmaceutical manufacturers, aftermarket service heads at European vendors, and commissioning specialists in Switzerland with secondary validation through SEC filings of listed environmental service providers, ECHA REACH registration databases, BIS certification records, and customs trade data for solvent recovery equipment imports. Bottom-up installed base estimates and top-down chemical production capacity projections were triangulated against vendor shipment disclosures.
Segment-weighting applied technology type, system configuration, and end-use vertical as primary stratification dimensions, with regional regulatory cluster as an additional modeling layer across the analysis window. CAGRs were derived from regression analysis of historical equipment procurement against chemical production indices and regulatory enforcement timelines. Forecast inputs incorporated ECHA REACH amendment trajectories, India PLI scheme disbursement schedules, and stainless steel alloy price elasticity assumptions.
Revisions become necessary when membrane technology cost curves steepen beyond thermal distillation parity, ECHA REACH enforcement intensifies ahead of modeled timelines, or Indian domestic-content mandates expand to exclude licensed foreign technology. Forecasts reflect documented assumptions about regulatory compliance cost pass-through rates and pharmaceutical capital expenditure cyclicality. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
India High Purity Solvents Market
Solvents
Butyl Glycol Market
Solvents
4-Dichlorobenzyl Alcohol (DCBA) Market
Solvents
Green Solvents and Bio-Solvents Market
Solvents
Allyl Cyanide Market
Solvents
Potassium Formate Market
Solvents
Citrus Solvents Market
Solvents
Chlorobenzene Market
Solvents
Global Bio Solvents Market
Solvents
Phenol Derivatives Market
Solvents
Ortho-Xylene Market
Solvents
5-Isopropyl-M-Xylene Market
Solvents
North America Acetonitrile Market
Solvents
Pharmaceutical Solvent Market
Solvents
Diethanolamide Market
Solvents
Hydrocarbon Solvents Market