
 Global Green and Bio-Based Solvents Market | 2026-2036
Global Green and Bio-Based Solvents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Green and Bio-Based Solvents Market Foresight
Specialized fermentation engineering talent is bifurcating the competitive landscape between established petrochemical converters and dedicated biorefinery operators. BASF SE leverages its integrated Ludwigshafen complex to sustain captive production of bio-derived alcohols and esters. Cargill, Incorporated anchors North American supply through its Decatur, Illinois bioprocessing hub and corn-derived feedstock dominance. Corbion NV differentiates via lactic acid fermentation expertise that extends into high-purity ethyl lactate for pharmaceutical-grade applications.
Green and bio-based solvents are liquid or formulated carrier media derived from renewable biomass feedstocks—primarily corn starch, sugarcane bagasse, citrus peel oil, or soybean oil—typically manufactured through enzymatic hydrolysis, fermentation, or supercritical extraction, and functionally specified by flash point, VOC content, and Kauri-butanol value to replace petroleum-derived aromatic, ketone, or chlorinated solvents in industrial formulations. Bioethanol and ethyl lactate lead product-type revenue pools due to established fermentation infrastructure and broad compatibility with waterborne coating systems, while terpenes and limonene occupy faster-growing niches in precision cleaning and electronics degreasing where low-toxicity halogen replacements command price premiums. Paints and coatings applications dominate volume offtake as architectural and automotive OEM formulators reformulate under tightening VOC ceilings, though pharmaceutical and personal care segments concentrate margin pools through USP-grade and COSMOS-certified solvent requirements.
EPA VOC regulations under Clean Air Act Title I constrain conventional solvent use in ozone nonattainment zones, while REACH Annex XVII restrictions on aromatic hydrocarbons and ECHA SVHC listings accelerate European formulator migration. China's MEE enforces GB standards on industrial emissions that disadvantage high-VOC petroleum solvents in Yangtze River Delta manufacturing clusters. Stakeholders must monitor feedstock crop price volatility against fossil parity shifts and pre-emptively certify inventories under evolving biobased content standards such as USDA BioPreferred and DIN CERTCO.
Market Dynamics
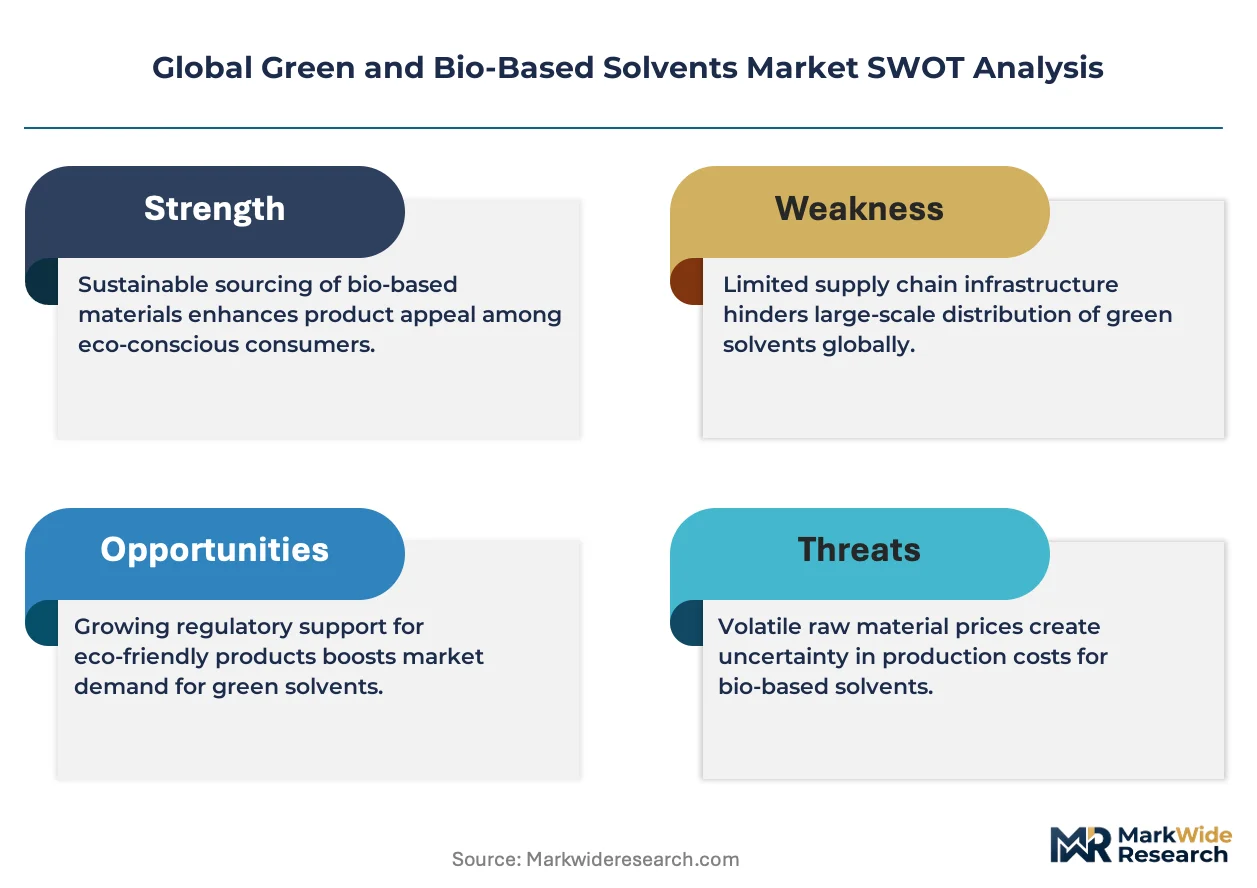
REACH Annex XVII restrictions on aromatic hydrocarbons and EPA Clean Air Act Title I enforcement are compressing demand for petroleum-derived solvents, forcing formulators across coatings, pharmaceuticals, and electronics cleaning to requalify supply chains around bio-based alternatives.
Growth Catalysts
- REACH VOC ceilings:European coatings manufacturers face mandatory reformulation deadlines, accelerating technical validation of ethyl lactate and bioethanol in waterborne architectural systems.
- India PLI-linked chemical manufacturing:Domestic biorefinery capacity expansion under production-linked incentives concentrates feedstock security for fermentation-derived solvents.
- Terpenes in precision electronics:Semiconductor fabs and PCB assemblers specify citrus-derived d-limonene for halogen-free degreasing to meet IEC halogen-content standards.
Market Restraints
- Corn and sugarcane price volatility:Feedstock crop futures expose bio-based solvent producers to agricultural commodity swings that petroleum refiners do not face.
- Fermentation infrastructure concentration:North American and European bioprocessing hubs control enzymatic hydrolysis capacity, creating geographic supply bottlenecks for Asian formulators.
- Performance gaps in high-temperature applications:Bio-derived esters and alcohols exhibit lower flash points than aromatic hydrocarbons, limiting adoption in industrial metal-cleaning processes.
Strategic Opportunities
- China Yangtze River Delta manufacturing clusters:MEE GB standards enforcement disadvantages high-VOC petroleum solvents, opening procurement windows for qualified bio-based suppliers.
- Pharmaceutical USP-grade certification:COSMOS and USP monograph compliance creates margin pools in parenteral drug formulation and natural cosmetics extraction.
- Supercritical CO2 extraction convergence:Integration with terpene recovery systems from citrus processing waste streams unlocks circular feedstock economics.
Industry Challenges
- Fermentation engineering talent scarcity:Industrial microbiology and bioprocess optimization expertise concentrates at dedicated biorefinery operators, constraining petrochemical converter recruitment pipelines.
- USDA BioPreferred certification timelines:Biobased content verification and third-party auditing create 12-18 month product qualification delays for new market entrants.
- Legacy coating system compatibility:Reformulation of established solvent-borne resin systems requires extensive adhesion, drying time, and gloss retention testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Green and Bio-Based Solvents Market |
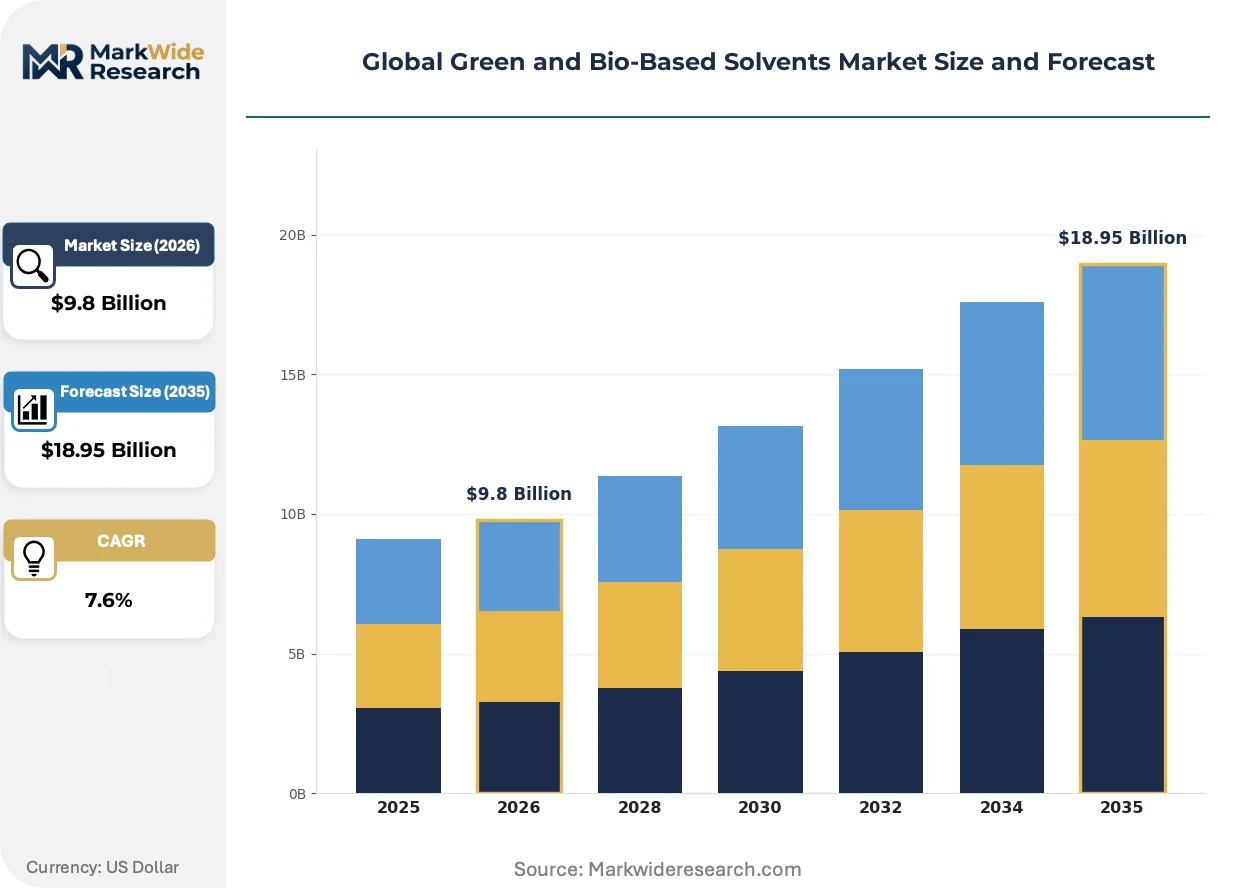
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $18.95 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bioethanol, Limonene, Ethyl Lactate, Methyl Soyate, Glycerol, Terpenes Application: Paints & Coatings, Cleaning Products, Adhesives, Pharmaceuticals, Agrochemicals, Personal Care Form: Liquid, Powder, Gel, Emulsion, Aerosol End User: Chemical Manufacturers, Cosmetic Producers, Agrochemical Firms, Pharmaceutical Companies, Coating Specialists |
| Companies Covered | Archer Daniels Midland Company, BASF SE, Cargill, Incorporated, Solvay, Cremer Oleo GmbH & Co. KG, Corbion NV, Dow Inc., Vertec BioSolvents, LyondellBasell Industries Holdings BV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Green and Bio-Based Solvents Market Shifts & Advancements
Supercritical fluid extraction and continuous fermentation engineering are compressing production economics for bio-based solvents, while regulatory harmonization around biobased content measurement creates new competitive moats.
Supercritical CO2 extraction of citrus peel oils is decomposing the cost premium historically attached to terpene solvents. Flavor and fragrance houses with existing supercritical infrastructure are repurposing capacity for industrial-grade d-limonene production. Electronics contract manufacturers in South Korea and Taiwan are accelerating qualification timelines as halogen-free cleaning specifications harden.
REACH restrictions on SVHC-listed aromatic hydrocarbons are forcing European coatings formulators to eliminate toluene and xylene from architectural and automotive OEM systems. German KBA type-approval processes for automotive refinish coatings now require VOC content declarations that disadvantage conventional solvent packages. Waterborne alkyd and polyurethane systems are capturing share in premium architectural segments where drying time penalties are acceptable.
Formulators are consolidating supplier relationships around integrated biorefinery operators with captive fermentation and esterification capabilities. Tier-one coatings manufacturers in the United States and Germany are executing multi-year offtake agreements that bypass traditional chemical distribution channels. Direct procurement contracts concentrate volume commitments with Cargill, BASF, and Corbion, compressing margins for independent distributors and traders.
Global Green and Bio-Based Solvents Market Segmentation
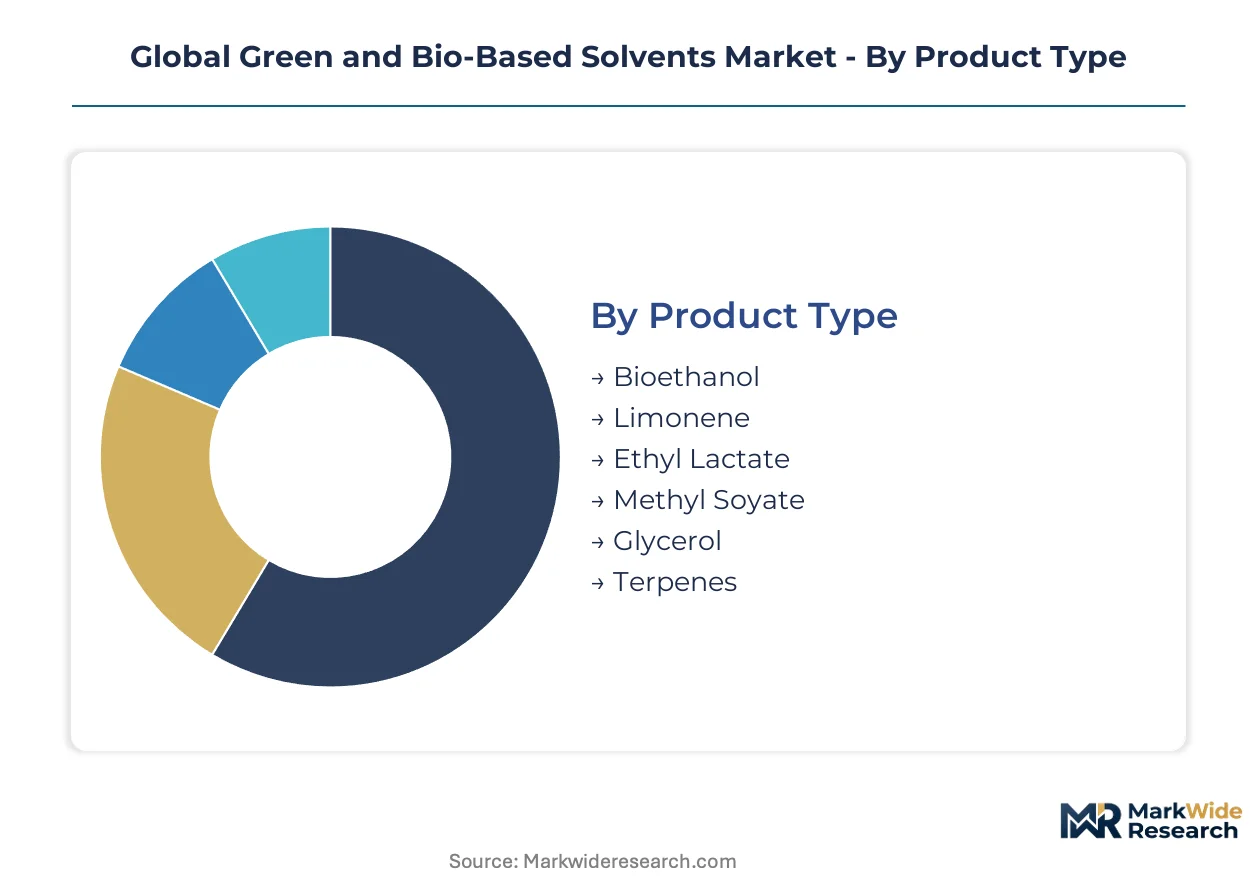
Segmentation in the green and bio-based solvents market reveals how substitution pressure varies sharply across molecular architectures and end-use specifications. Formulators face divergent technical barriers when replacing petroleum-derived carriers in high-performance coatings versus commodity cleaning applications.
Product Type:
Substitution pressure intensifies where fermentation infrastructure already exists, while novel biorefinery chemistries struggle against cost-parity thresholds.
- Bioethanol:Fermentation-derived C2 alcohol with established dehydration and denaturing protocols. German automotive refinish formulators under KBA type-approval mandates are expanding technical-grade procurement from Cargill's Decatur hub.
- Ethyl Lactate:Esterified lactic acid delivering high solvency power with biodegradable metabolites. Corbion's purification expertise serves USP-grade pharmaceutical extraction demand in parenteral drug manufacturing.
- Limonene:Citrus peel-derived terpene with aggressive degreasing action for electronics cleaning.
- Methyl Soyate:Transesterified soybean oil fatty acid methyl ester for industrial metal-cleaning formulations.
- Glycerol:Crude or refined propanetriol from biodiesel co-production streams.
- Terpenes:Pinene and carene fractions from coniferous resin tapping and pulp byproduct recovery.
Bioethanol anchors the volume base while terpenes gain share at the steepest rate.
Application:
Cost-tier stratification separates commodity reformulation from premium-certified segments where biobased content verification commands measurable price premiums.
- Paints & Coatings:Architectural and automotive OEM systems requiring VOC compliance under EPA Title I and REACH Annex XVII. Waterborne alkyd reformulation in Germany's industrial clusters is accelerating ethyl lactate validation for gloss retention parity.
- Pharmaceuticals:USP-grade and COSMOS-certified solvents for active pharmaceutical ingredient extraction and parenteral formulation. FDA monograph compliance creates qualification moats that concentrate margin pools with dedicated biorefinery operators.
- Cleaning Products:Industrial degreasing and consumer hard-surface applications.
- Adhesives:Pressure-sensitive and structural bonding systems.
- Agrochemicals:Pesticide emulsifiable concentrate carriers and tank-mix adjuvants.
- Personal Care:Natural cosmetics extraction and fragrance dilution.
Paints and coatings generate the heaviest volume offtake whereas pharmaceuticals deliver the most concentrated margin capture.
Form:
Physical state determines compatibility with legacy manufacturing infrastructure and dictates logistics cost structures across supply chains.
- Liquid:Standard pumpable carriers for bulk tanker delivery and automated dosing systems. Dominates coatings manufacturing in the United States where rail-terminal access shapes procurement economics.
- Emulsion:Water-dispersed solvent phases for reduced-VOC delivery in spray applications. Expanding most quickly in China's Yangtze River Delta clusters under MEE GB standard enforcement.
- Powder:Encapsulated or spray-dried formulations for controlled release.
- Gel:Thickened systems for vertical surface application.
- Aerosol:Propellant-dispensed packaging for precision cleaning.
Liquid forms retain volume dominance while emulsion systems climb the fastest on regulatory tailwinds.
End User:
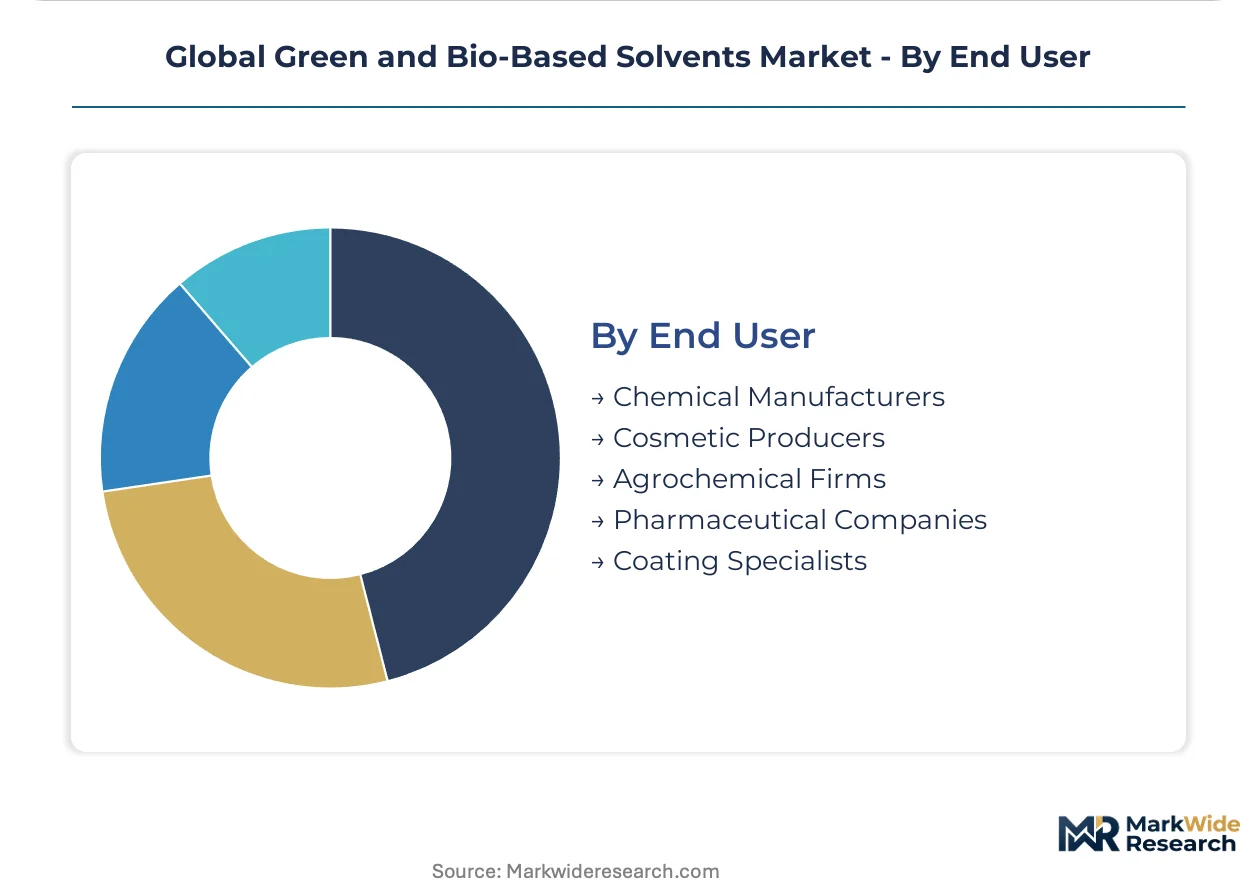
Customer-type concentration around integrated biorefinery operators is compressing traditional distribution margins and reshaping procurement relationship structures.
- Chemical Manufacturers:Intermediate producers formulating solvent blends for downstream resale. BASF's Ludwigshafen complex leverages captive bioethanol and ester production for internal derivative manufacturing.
- Pharmaceutical Companies:Formulators requiring batch-level traceability and USP documentation. Direct offtake agreements with Corbion bypass independent distributors for high-purity ethyl lactate supply security.
- Coating Specialists:Architectural and industrial formulators managing reformulation timelines.
- Cosmetic Producers:Natural and organic certified product manufacturers.
- Agrochemical Firms:Pesticide and fertilizer formulation operations.
Chemical manufacturers absorb the largest volume flows while pharmaceutical companies drive the steepest specification escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German coatings manufacturers command pricing premiums against Chinese Yangtze River Delta producers due to REACH compliance certification and KBA type-approval documentation. This asymmetry concentrates margin capture in European biorefinery operators while Asian formulators compete on volume scale.
United States
Automotive OEM and architectural coatings drive bioethanol procurement under EPA Clean Air Act Title I enforcement in ozone nonattainment zones. Illinois and Iowa bioprocessing clusters anchor corn-derived feedstock security for fermentation infrastructure. Cargill's Decatur hub supplies technical-grade volumes directly to tier-one formulators bypassing distribution channels.
Germany
KBA type-approval mandates for automotive refinish coatings accelerate ethyl lactate validation in waterborne alkyd systems. REACH Annex XVII restrictions on aromatic hydrocarbons force elimination of toluene and xylene from industrial formulations. Ludwigshafen's integrated chemical complex sustains captive production of bio-derived alcohols and esters for internal derivative manufacturing.
China
MEE GB standards enforcement disadvantages high-VOC petroleum solvents in Yangtze River Delta manufacturing clusters. National bioeconomy programs concentrate demand through state-directed procurement of fermentation-derived solvents. Shanghai and Jiangsu province coatings manufacturers reformulate under emissions caps that open procurement windows for qualified bio-based suppliers.
India
Production-linked incentive schemes expand domestic biorefinery capacity for fermentation-derived solvents under chemical manufacturing promotion programs. Maharashtra and Gujarat industrial corridors attract feedstock processing investments for corn and sugarcane derivatives. CDSCO pharmaceutical regulations create qualification pathways for USP-grade solvent imports from dedicated biorefinery operators.
Global Green and Bio-Based Solvents Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the green and bio-based solvents market. The competitive structure bifurcates between integrated petrochemical converters with captive fermentation assets and dedicated biorefinery operators with specialized lactic acid purification expertise. Three archetypes dominate: diversified chemical conglomerates leveraging existing infrastructure, agricultural processors controlling feedstock supply chains, and fermentation specialists commanding pharmaceutical-grade certification. Capacity expansion and direct offtake agreements with tier-one formulators represent the dominant competitive moves compressing traditional distribution margins.
Among diversified chemical conglomerates, BASF SE and Dow Inc. exemplify the integrated converter archetype leveraging existing esterification infrastructure. Agricultural processors anchor cost positions through feedstock dominance, with Archer Daniels Midland Company and Cargill, Incorporated representing North American supply security. Fermentation specialists occupy premium-tier positions through purification expertise, with Corbion NV exemplifying the pharmaceutical-grade certification archetype. Solvay, Cremer Oleo GmbH & Co. KG, Vertec BioSolvents, and LyondellBasell Industries Holdings BV occupy intermediate positions across technology and scale vectors.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| BASF SE |
| Cargill, Incorporated |
| Solvay |
| Cremer Oleo GmbH & Co. KG |
| Corbion NV |
| Dow Inc. |
| Vertec BioSolvents |
| LyondellBasell Industries Holdings BV |
| Others |
Supply & Pricing Matrix
Bioethanol displacement of petroleum-derived aromatic solvents in German automotive refinish coatings simultaneously redistributes procurement gravity toward Illinois corn-belt fermentation hubs and compresses price premiums for REACH-compliant formulations. This substitution dynamic concentrates margin capture with integrated biorefinery operators while fragmenting pricing power among independent distributors caught between feedstock volatility and direct offtake agreements.
Pricing Analysis
German coatings manufacturers command 15-25% price premiums over Yangtze River Delta producers for REACH-compliant ethyl lactate, reflecting KBA type-approval documentation costs and certification audit burdens. Three-tier pricing structure across USP-grade pharmaceutical, technical-grade industrial, and commodity cleaning tiers separates margin pools by purity specification and batch traceability. Cost compression in technical-grade bioethanol runs through Cargill's direct-to-formulator contracts, which bypass traditional chemical distribution and squeeze independent trader margins. Pharmaceutical companies exhibit lowest price sensitivity due to FDA monograph compliance requirements, while architectural coatings formulators face acute pressure from waterborne system reformulation costs.
Supply Chain Analysis
Inventory cycles for fermentation-derived solvents extend 8-12 weeks longer than petroleum-derived equivalents due to agricultural harvest timing and enzymatic hydrolysis batch constraints. Supply concentrates in the United States, Germany, and China, with Illinois and Iowa bioprocessing clusters, Ludwigshafen's integrated chemical complex, and Yangtze River Delta state-directed fermentation facilities anchoring geographic production. Raw material dependencies center on corn starch, sugarcane bagasse, and citrus peel oil feedstocks, with crop futures exposing producers to commodity swings petroleum refiners avoid. Single-source vulnerability concentrates in Corbion's lactic acid purification expertise for USP-grade ethyl lactate. Distribution runs through direct multi-year offtake agreements with tier-one coatings and pharmaceutical manufacturers, compressing traditional distributor roles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense as supercritical CO2 extraction infrastructure from flavor and fragrance houses repurposes for industrial-grade terpene production, threatening fermentation-based cost positions. Incumbents must navigate this dual-technology pressure while consolidating procurement relationships.
For Market Incumbents: Fortify captive fermentation capacity through backward integration into corn-processing assets in Illinois and Iowa, securing feedstock cost parity against agricultural commodity swings. Deepen USP-grade certification moats by investing in batch-level traceability systems that exceed FDA monograph requirements, raising qualification barriers for supercritical extraction entrants targeting pharmaceutical solvent demand.
For New Entrants and Emerging Players: Differentiate on circular feedstock economics by integrating with citrus processing waste streams for terpene recovery, bypassing agricultural commodity exposure entirely. Target South Korean and Taiwanese electronics contract manufacturers accelerating halogen-free cleaning specifications, where d-limonene qualification timelines are compressing and technical validation requirements remain less entrenched than pharmaceutical-grade segments.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed flavor and fragrance houses possessing underutilized supercritical CO2 infrastructure ripe for industrial terpene repurposing. Long-term viability hinges on feedstock flexibility rather than single-crop dependence, with acquisition screens favoring operators with multi-biomass processing capabilities. Watch for MEE GB standard enforcement intensity in China's Yangtze River Delta as the inflection signal for Asian demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Processing | Corn-belt processing assets in Illinois and Iowa anchor cost positions against agricultural commodity volatility. |
| USP-Grade Certification Investment | FDA monograph compliance creates qualification moats that concentrate pharmaceutical margin pools with dedicated biorefinery operators. |
| Supercritical CO2 Infrastructure Repurposing | Citrus peel oil extraction capacity from flavor houses unlocks circular feedstock economics for industrial terpene production. |
| Direct Offtake Agreement Expansion | Multi-year contracts with tier-one German automotive refinish formulators bypass distribution channels and compress trader margins. |
| Halogen-Free Cleaning Qualification | IEC standard compliance for d-limonene in South Korean semiconductor fabs opens procurement windows for qualified suppliers. |
Research Methodology
Cross-validation between primary interviews with plant managers at biorefinery operations and secondary analysis of customs trade data, SEC 10-K filings, and Cefic industry reports anchors the qualitative findings. Conversations with procurement leads at downstream coatings manufacturers, distribution channel partners, and technical R&D directors at fermentation specialists informed supply chain dynamics and reformulation timelines. Bottom-up triangulation across product-grade volume estimates and top-down validation against national bioeconomy program targets ensured segmentation consistency.
Sensitivity analysis around feedstock price volatility and regulatory enforcement intensity shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, end-use industry concentration, regional production hub clustering, and certification grade stratification. CAGRs derive from installed fermentation capacity expansion curves and substitution elasticity estimates for petroleum-derived solvent displacement. Industry-specific forecast inputs incorporate KBA type-approval timeline assumptions and MEE GB standard enforcement phase-ins.
Material uncertainties — agricultural commodity price spikes, REACH restriction amendments, and supercritical extraction cost breakthroughs — sit outside the modeled envelope. Forecasts reflect documented assumptions about biorefinery capacity commissioning schedules and regulatory harmonization progress. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Benzylamine Market
Solvents
Organic Solvents Market
Solvents
Acetone Derivatives Market
Solvents
Fluorinated Solvents Market
Solvents
N-Methyl Pyrrolidone Market
Solvents
Hydrosol Market
Solvents
Aliphatic Solvents and Thinners Market
Solvents
Ketene Market
Solvents
Aprotic Solvents Market
Solvents
Global Trichloroethylene and Perchloroethylene Market
Solvents
Global Solvents Market
Solvents
Methyl Undecylenate Market
Solvents
Benzene Market
Solvents
Europe Acetonitrile Market
Solvents
Global Chloroform Market
Solvents
Hexylene Glycol Market