
 2-Phenylethanol Market | 2026-2036
2-Phenylethanol Market Size, Share, and Industry Trends Forecast 2026-2036
2-Phenylethanol Market Analysis
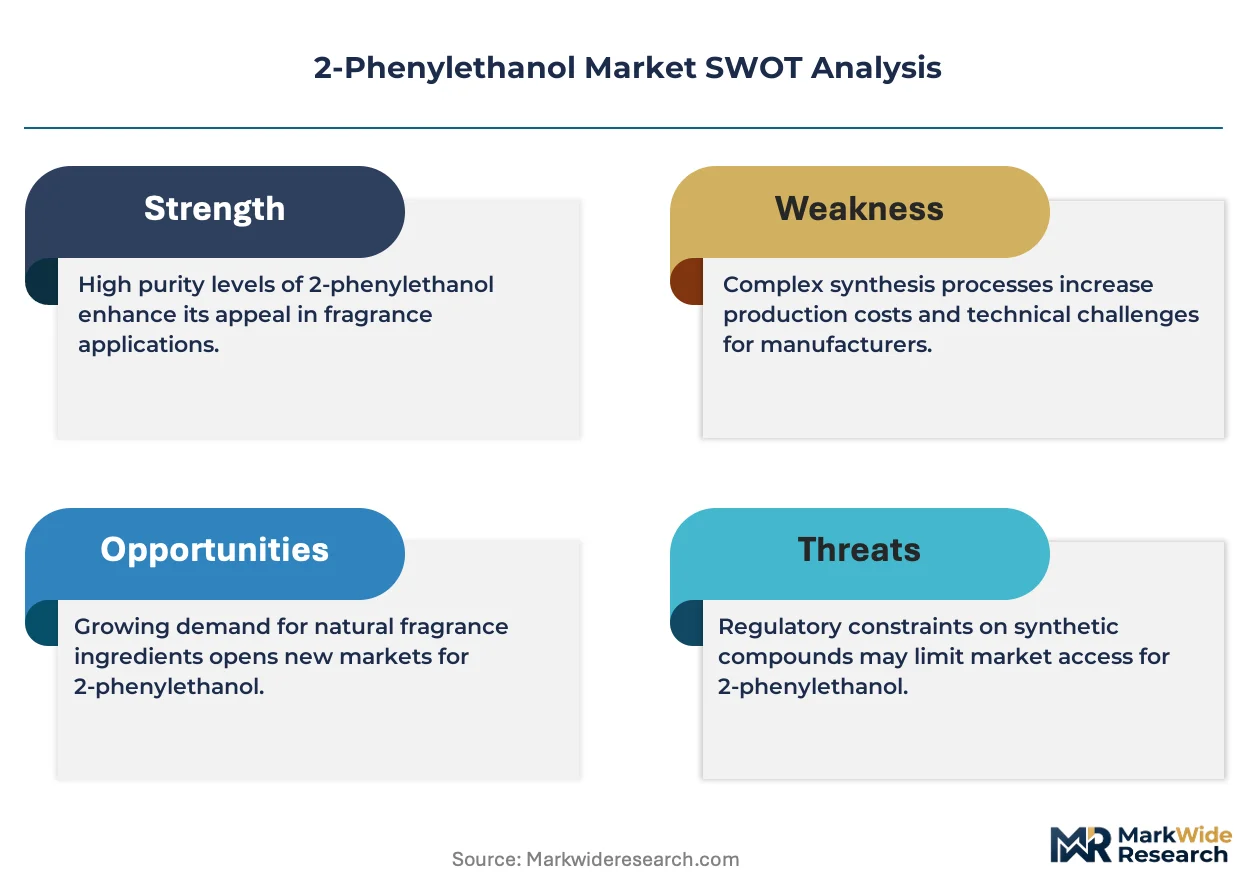
The 2-phenylethanol supply base is consolidating around a widening gap between premium natural-extraction grades and high-volume synthetic outputs. Givaudan leverages its integrated fragrance creation pipeline to secure preferential offtake of refined grades, while BASF SE anchors European supply through its petrochemical-derived production network. Symrise AG differentiates by sustaining dual-source capabilities across both biotechnology and conventional synthesis routes.
2-Phenylethanol is an aromatic alcohol with the molecular formula C8H10O, occurring naturally in rose oil and produced industrially via Friedel-Crafts alkylation of benzene or biotechnological fermentation of L-phenylalanine; it serves primarily as a fragrance ingredient, flavoring agent, and pharmaceutical intermediate valued for its sweet floral odor profile. The natural product type commands concentrated margin pools among certified clean-label suppliers, whereas the synthetic segment dominates volume throughput in mass-market fragrance compounding. Within end use industry segmentation, the fragrance category leads absolute consumption, while food and beverage applications are expanding fastest as clean-label flavor trends accelerate reformulation activity across beverage and confectionery portfolios.
REACH registration requirements in the European Union, China's GB standards administered by SAMR, and FDA food additive regulations under 21 CFR govern purity thresholds, labeling claims, and market access across the three largest demand zones. These frameworks compel manufacturers to maintain dual compliance documentation for cross-border shipments and restrict unqualified entrants from tendering into regulated fragrance and food-grade supply chains. Stakeholders must monitor tightening biotechnological process disclosure requirements in the EU and evolving green chemistry incentives in China that could restructure cost competitiveness between synthetic and fermentation-derived supply routes.
Market Dynamics
Fragrance houses face a structural squeeze between constrained natural rose oil supply and tightening purity mandates under REACH and China's GB standards, forcing dual-source qualification protocols that favor suppliers with both petrochemical-synthetic and fermentation-derived capabilities.
Growth Catalysts
- Fine perfume reformulation:European fragrance houses accelerate synthetic 2-phenylethanol procurement as natural rose oil extraction hits supply ceilings in Bulgaria and Turkey.
- REACH registration tiering:The European Chemicals Agency's differentiated registration requirements for tonnage bands create compliance moats that screen out unqualified suppliers.
- Biotechnology scale-up:China's Zhejiang province manufacturers deploy L-phenylalanine fermentation routes to capture clean-label demand from beverage and confectionery reformulators.
Market Restraints
- Benzene feedstock volatility:Petrochemical-synthetic producers face margin compression from benzene price swings tied to refinery operating rates.
- Supplier concentration in East China:Zhejiang and Jiangsu provinces host over half of global fermentation-derived capacity, creating geographic single-point vulnerability.
- Natural grade substitution ceiling:Certified natural-extraction 2-phenylethanol commands price premiums that exclude mass-market fragrance compounding.
Strategic Opportunities
- India flavor house expansion:FSSAI-aligned domestic manufacturers represent underpenetrated offtake potential as India's beverage sector formalizes.
- EU Green Deal biotech incentives:Fermentation-derived production routes gain cost competitiveness from carbon border adjustment mechanisms and green chemistry subsidies.
- Direct-to-compounder digital channels:Specialty chemical platforms bypass traditional distributor markups for mid-volume fragrance house procurement.
Industry Challenges
- Fermentation process scale-up expertise:Biotechnology-derived production requires specialized biochemical engineering talent scarce outside established pharma and enzyme manufacturing clusters.
- Dual REACH-GB documentation burden:Cross-border shipments demand parallel purity certification workflows that extend supplier qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2-Phenylethanol Market |
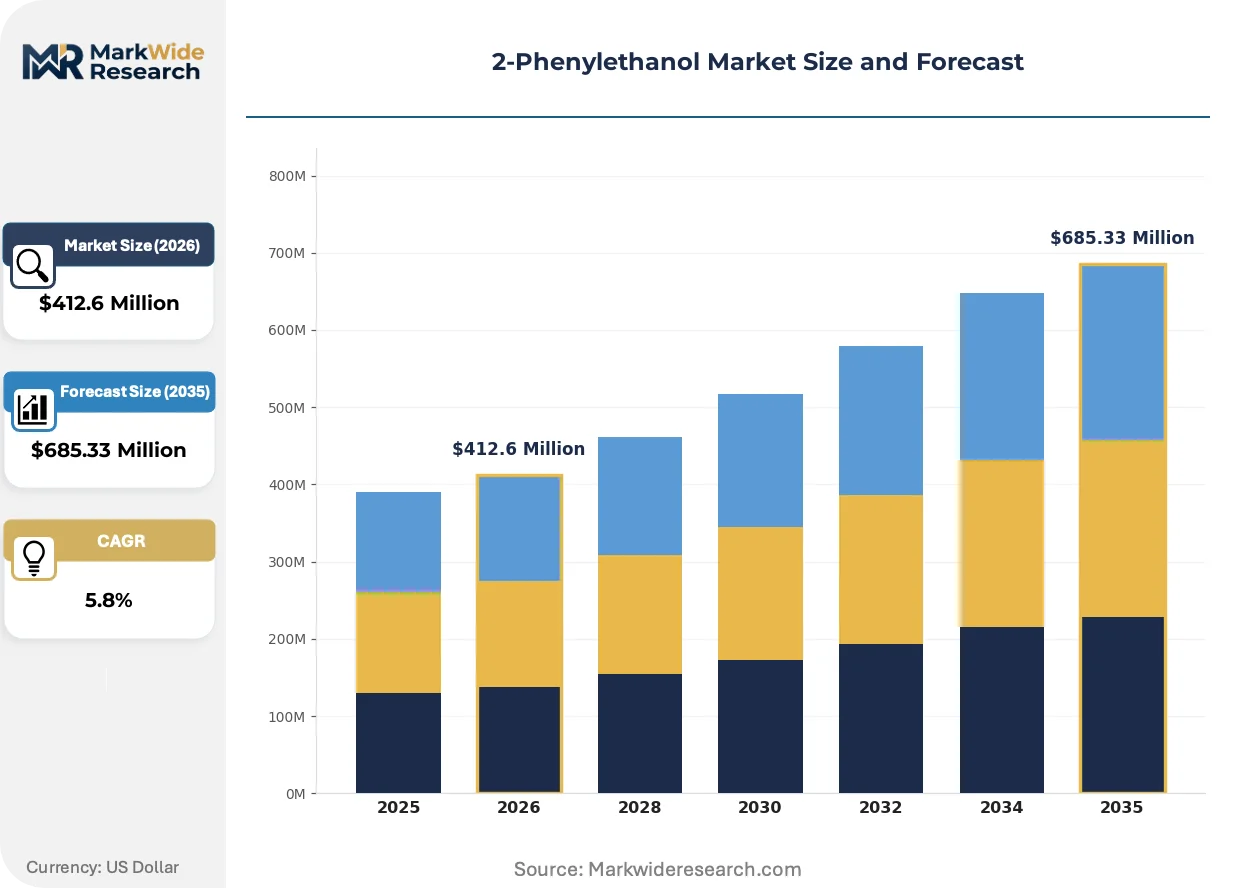
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Isomers, Blends End Use Industry: Fragrance, Food & Beverage, Cosmetics, Pharmaceuticals Form: Liquid, Powder, Crystals, Concentrated Packaging Type: Bottles, Drums, Totes, Bulk Containers |
| Companies Covered | Givaudan, Apple Flavor and Fragrance Group Co., Ltd., BASF SE, Yingyang (China) Aroma Chemical Group, LyondellBasell Industries N.V., Symrise AG, Eternis Fine Chemicals Ltd., Sigma-Aldrich Co. LLC, Firmenich SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2-Phenylethanol Market Emerging Trajectories
Production technology divergence between petrochemical synthesis and biotechnology fermentation is fragmenting supplier capabilities and recasting competitive advantage around carbon intensity disclosure and regulatory documentation depth.
Continuous processing technology for Friedel-Crafts alkylation is rewriting capital efficiency benchmarks for petrochemical-synthetic 2-phenylethanol. European and Chinese producers adopting flow chemistry reactors achieve tighter purity control with smaller footprint operations. This technology compression enables mid-scale entrants to challenge legacy batch-reactor incumbents on specification consistency.
REACH's evolving requirements for biotechnological process disclosure are tightening documentation burdens on fermentation-derived suppliers. The European Chemicals Agency now demands detailed host organism and substrate traceability for registration dossiers. Natural-grade suppliers targeting EU fragrance markets must invest in supply chain transparency systems that synthetic competitors can bypass.
Clean-label procurement criteria are displacing traditional specification-only purchasing in beverage and confectionery applications. Flavor houses now require carbon footprint documentation and non-GMO certification alongside standard purity metrics. This behavioral shift concentrates volume with suppliers offering integrated sustainability credentials rather than commodity-grade outputs.
2-Phenylethanol Market Segmentation
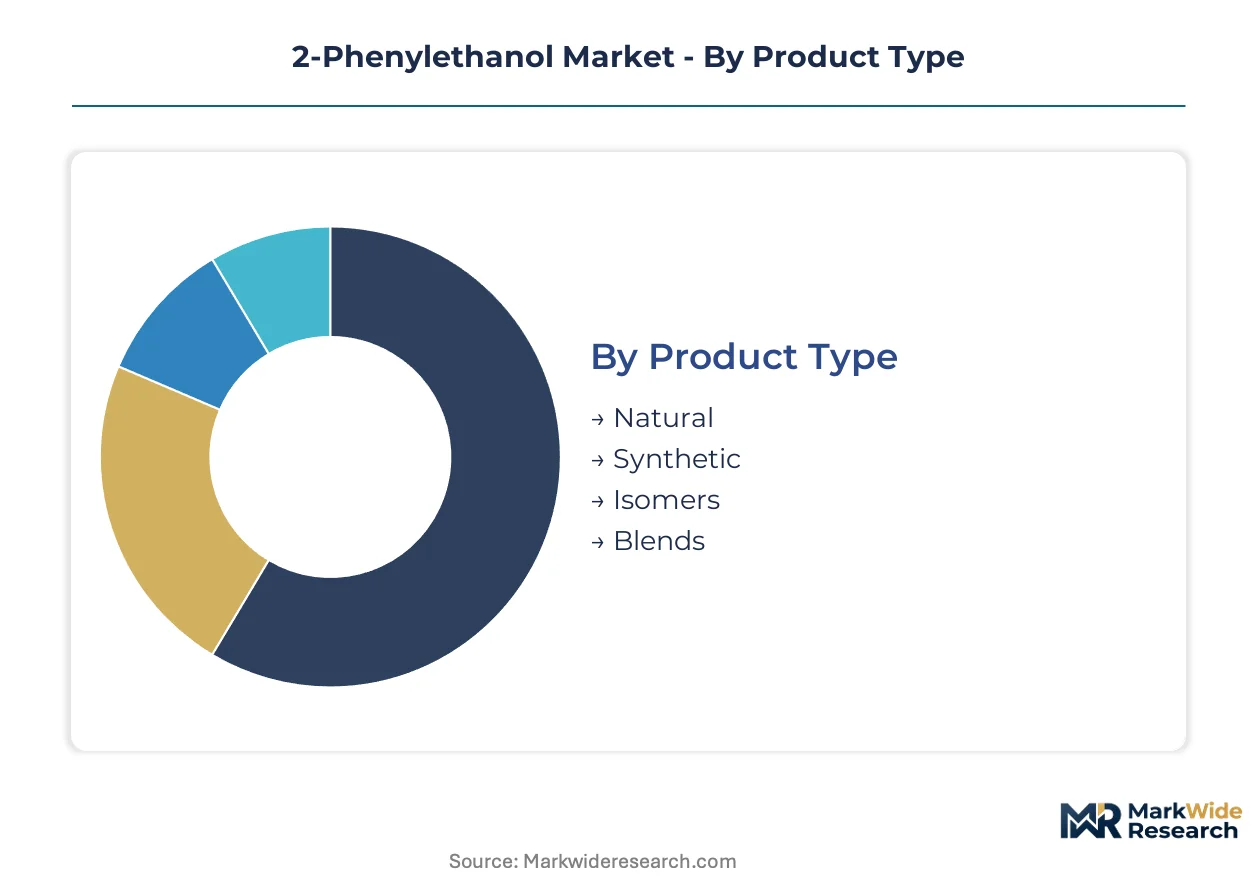
2-Phenylethanol procurement patterns diverge sharply across grade purity, end-use certification requirements, and packaging scale. Buyers in fragrance compounding, food formulation, and pharmaceutical synthesis each impose distinct specification thresholds that reshape supplier qualification and pricing architecture.
Product Type:
Buyers differentiate primarily by certification tier and carbon intensity disclosure rather than molecular specification alone.
- Natural:Extracted from rose oil or produced via L-phenylalanine fermentation with full substrate traceability. European fragrance houses and clean-label food manufacturers in Germany and France concentrate procurement here, driven by ECHA bioprocess disclosure mandates and consumer transparency demands.
- Synthetic:Manufactured through Friedel-Crafts alkylation of benzene with ethylene oxide. Mass-market fragrance compounders and industrial cleaning product formulators in China's Zhejiang province and the US Gulf Coast dominate offtake, prioritizing volume consistency over provenance documentation.
- Isomers:Separated enantiomeric forms for chiral pharmaceutical intermediates.
- Blends:Pre-formulated combinations with fixatives or diluents for direct compounding use.
Synthetic grades lead volumes today; natural extraction is gaining share fastest.
End Use Industry:
Application-specific purity mandates from FDA, ECHA, and China's SAMR create divergent compliance cost structures across buyer categories.
- Fragrance:Fine perfume houses require 99%+ purity with full allergen documentation under IFRA guidelines. European luxury brands and Middle Eastern oud blenders in Dubai and Jeddah drive premium-grade procurement, constrained by Bulgarian rose oil supply ceilings.
- Food & Beverage:Flavor houses demand FEMA GRAS or JECFA compliance with non-GMO certification for beverage and confectionery applications. China's Jiangsu province manufacturers and US natural flavor specialists expand fermentation-derived sourcing fastest.
- Cosmetics:Skincare and haircare formulators prioritize skin-safety testing data over absolute purity metrics.
- Pharmaceuticals:API manufacturers and excipient suppliers require USP-NF or EP compliance with validated impurity profiles.
Fragrance applications anchor absolute consumption; food and beverage end uses are expanding most quickly.
Form:
Physical state selection hinges on downstream formulation equipment, storage infrastructure, and active concentration requirements.
- Liquid:Standard 99% purity fluid for direct compounding into alcoholic perfumes and aqueous flavor systems. Batch processors in India's Maharashtra and Uttar Pradesh states prefer drum-scale liquid procurement for flexible formulation scheduling.
- Powder:Spray-dried or encapsulated forms for controlled-release applications in solid dosage pharmaceuticals and powdered beverage mixes.
- Crystals:High-purity solid for precise weighing in analytical standards and luxury candle manufacturing.
- Concentrated:50-80% dilutions in carrier solvents for safe handling in small-batch artisanal production.
Liquid form dominates shipment volumes; concentrated formats are climbing fastest among craft and artisanal compounders.
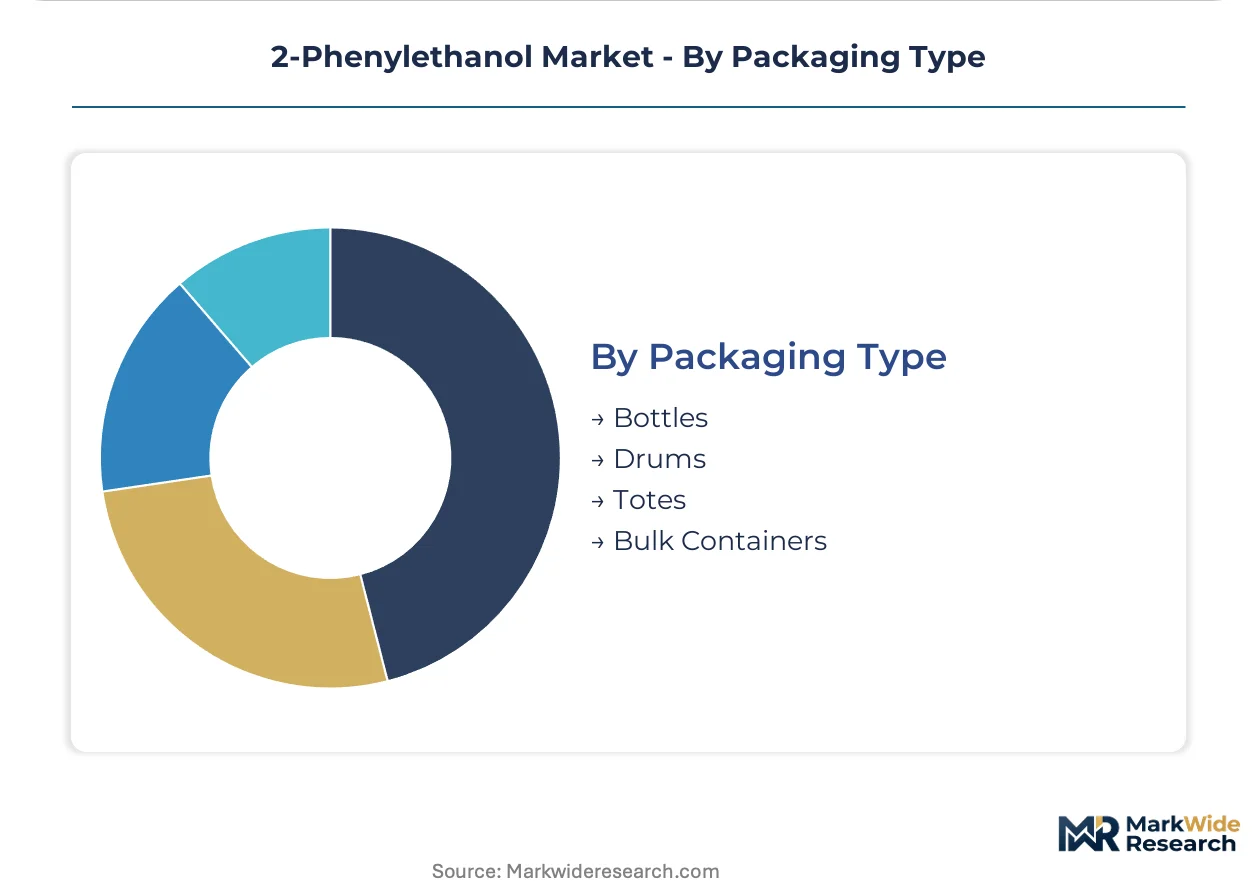
Packaging Type:
Container selection reflects order frequency, inventory turnover, and contamination risk tolerance across buyer operational scales.
- Bottles:Amber glass or fluoropolymer-lined containers for laboratory-scale sampling and high-value natural grades. Niche perfumers in Grasse, France and contract research organizations in Boston and San Diego specify bottle packaging for oxidation-sensitive lots.
- Drums:200-liter steel or HDPE containers for mid-volume fragrance house and flavor manufacturer procurement.
- Totes:Intermediate bulk containers for regional compounders with dedicated storage and handling equipment.
- Bulk Containers:ISO tanks and flexitanks for integrated manufacturers with captive consumption or direct pipeline transfer capability.
Drum packaging leads current procurement volumes; bulk containers are gaining fastest among integrated multinational fragrance houses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands fermentation-derived output volumes while Germany anchors petrochemical-synthetic production networks. Each geography imposes distinct compliance architectures that reshape supplier qualification timelines and procurement patterns.
China
Zhejiang and Jiangsu provinces concentrate over half of global fermentation-derived capacity as domestic aroma chemical manufacturers scale L-phenylalanine bioprocessing lines. SAMR-administered GB standards for flavor and fragrance chemicals tighten purity specifications and documentation requirements for cross-border shipments. Hangzhou and Ningbo industrial clusters serve both local flavor houses and export markets with integrated fermentation-to-refinement operations.
Germany
Ludwigshafen and Leverkusen chemical corridors anchor European petrochemical-synthetic production through continuous Friedel-Crafts alkylation infrastructure. ECHA REACH registration tiering for tonnage bands creates compliance moats that screen unqualified suppliers from EU fragrance supply chains. Bavarian and North Rhine-Westphalian manufacturing sites supply fine perfume houses with specification-consistent material under integrated refinery-chemical complex economics.
United States
Gulf Coast petrochemical infrastructure supports synthetic 2-phenylethanol output for mass-market fragrance compounders and industrial cleaning product formulators. FDA food additive regulations under 21 CFR govern purity thresholds for flavor applications while IFRA guidelines constrain allergen documentation for cosmetic uses. Texas and Louisiana production sites leverage ethylene oxide and benzene feedstock integration from regional refinery operations.
India
Maharashtra and Gujarat states host emerging flavor house manufacturing capacity targeting domestic beverage sector formalization. FSSAI alignment requirements for food-grade aroma chemicals extend supplier qualification timelines for international entrants. Mumbai and Ahmedabad industrial zones represent underpenetrated offtake potential as local procurement shifts from distributor-mediated to direct-compounder channels.
France
Grasse fragrance compounding cluster drives premium-grade natural-extraction procurement for luxury perfume houses constrained by Bulgarian rose oil supply ceilings. ANSM and CNIL oversight intersect with ECHA bioprocess disclosure mandates for fermentation-derived imports. Provence-Alpes-Côte d'Azur formulation laboratories require full substrate traceability documentation that concentrates volume with certified clean-label suppliers.
2-Phenylethanol Market Vendor Landscape
Top-tier vendors anchor integrated fragrance creation pipelines, while mid-scale fermentation specialists and regional petrochemical producers occupy differentiated tiers. The supply base consolidates around dual-source qualification capabilities spanning both biotechnology and conventional synthesis routes. Three archetypes dominate: integrated fragrance houses with captive offtake agreements, diversified chemical conglomerates with refinery-integrated production, and specialized aroma chemical manufacturers with fermentation scale-up expertise. Competitive dynamics center on strategic partnerships for bioprocess licensing and capacity expansion in East China manufacturing clusters.
Within the integrated fragrance house tier, Givaudan and Firmenich SA represent archetypes of downstream-controlled supply security through preferential offtake arrangements. BASF SE and LyondellBasell Industries N.V. exemplify petrochemical conglomerates leveraging refinery-chemical complex integration for feedstock cost positioning. Symrise AG occupies a position bridging both biotechnology and conventional synthesis capabilities. Apple Flavor and Fragrance Group Co., Ltd. and Yingyang (China) Aroma Chemical Group exemplify Zhejiang-based fermentation specialists capturing clean-label demand from beverage reformulators. Eternis Fine Chemicals Ltd. and Sigma-Aldrich Co. LLC represent quality-focused suppliers serving pharmaceutical and analytical standard applications with validated impurity profiles.
| Leading Market Players |
|---|
| Givaudan |
| Apple Flavor and Fragrance Group Co., Ltd. |
| BASF SE |
| Yingyang (China) Aroma Chemical Group |
| LyondellBasell Industries N.V. |
| Symrise AG |
| Eternis Fine Chemicals Ltd. |
| Sigma-Aldrich Co. LLC |
| Firmenich SA |
| Others |
Supply Flow & Price Mechanics
Clean-label procurement mandates from European fragrance houses and Chinese beverage reformulators are forcing suppliers to reconfigure production footprints and absorb certification costs that compress margins on synthetic grades.
Pricing Analysis
Capacity additions in China's Zhejiang province are reshaping price floors for fermentation-derived grades. Three-tier pricing structure across natural-extraction, fermentation-derived, and petrochemical-synthetic levels stratifies by certification depth and carbon disclosure. Price differentiation centers on REACH bioprocess documentation and non-GMO verification. Cost compression in mass-market synthetic tiers is intensifying because benzene feedstock volatility erodes fixed-contract margins. Mass-market fragrance compounders exhibit highest price sensitivity; fine perfume houses in France and the Middle East show lowest.
Supply Chain Analysis
Direct-to-compounder digital channels handle mid-volume fragrance house procurement, bypassing traditional distributor markups. Supply concentrates in China, Germany, and the United States. Raw material flows draw from benzene refinery streams, L-phenylalanine fermentation substrates, and Bulgarian rose oil extraction. Single-source vulnerability runs through East China's Zhejiang-Jiangsu corridor where over half of fermentation capacity sits. Distribution runs through integrated fragrance house pipelines, regional chemical distributors, and specialty platform direct sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications are hardening as a late-cycle demand filter, with ECHA bioprocess disclosure mandates and clean-label certification requirements concentrating procurement among dual-source capable suppliers.
For Market Incumbents: Anticipate margin compression from biotechnology scale-up in East China by securing captive fermentation capacity or preferential offtake agreements with Zhejiang-based specialists. Reinforce REACH-GB dual documentation capabilities to extend qualification timelines that screen out unqualified entrants. Prioritize carbon intensity transparency systems to defend premium positioning against synthetic competitors.
For New Entrants and Emerging Players: The price-point gap between natural-extraction and commodity-synthetic grades offers white-space entry for fermentation-derived mid-tier suppliers with partial certification. Target India's Maharashtra and Gujarat flavor house clusters where FSSAI alignment requirements have slowed international entrant qualification. Lead with direct digital channels and drum-scale packaging flexibility to bypass established distributor relationships.
For Investors and Strategic Acquirers: Asymmetric upside sits with fermentation specialists possessing validated L-phenylalanine bioprocessing scale-up expertise and existing SAMR-ECHA dual compliance infrastructure. Long-term viability hinges on biotechnology cost convergence against petrochemical routes as EU carbon border adjustments mature. Watch for bioprocess disclosure requirement tightening in EU fragrance markets as inflection signal for certification-premium durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Captures clean-label demand from beverage reformulators in China's Jiangsu province. |
| Backward Integration into L-Phenylalanine Supply | Secures substrate cost positioning against benzene-linked synthetic competitors. |
| REACH-GB Dual Certification Investment | Accelerates supplier qualification timelines for cross-border fragrance shipments. |
| Direct-to-Compounder Digital Platform Launch | Bypasses distributor markups for mid-volume European fragrance house procurement. |
| Carbon Intensity Disclosure System Deployment | Meets emerging procurement criteria from clean-label food and beverage formulators. |
Methodological Framework
Direct dialogue with fragrance house procurement directors, flavor manufacturer R&D leads, fermentation plant managers, and specialty chemical distributors anchored qualitative findings. Secondary validation drew from ECHA registration dossiers, SAMR GB standard publications, customs trade data, and SEC filings from disclosed aroma chemical producers. Bottom-up capacity modeling and top-down demand triangulation cross-checked volume estimates across natural-extraction, fermentation-derived, and petrochemical-synthetic supply routes.
Bottom-up segment modeling tracked grade tier, end-use industry, packaging format, and regional production hub dimensions across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves and capacity buildout timelines. Forecast inputs incorporated benzene price volatility assumptions and biotechnology yield improvement trajectories specific to L-phenylalanine fermentation economics.
Caveats apply where regulatory disclosure requirement shifts or feedstock cost spikes could materially shift the outlook. Forecasts reflect base-case assumptions about REACH tiering stability and Chinese dual carbon policy implementation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Meta-Xylene Market
Solvents
N-Methyl Pyrrolidone Market
Solvents
Ortho-Xylene Market
Solvents
1, 1-Difluoroethane Market
Solvents
Organic Solvents Market
Solvents
Global Solvents Market
Solvents
Nitroglycerin Market
Solvents
Chlorobenzene Market
Solvents
Aliphatic Hydrocarbon Solvents and Thinners Market
Solvents
Aliphatic Solvents Market
Solvents
Green Solvents and Bio-Solvents Market
Solvents
5-Isopropyl-M-Xylene Market
Solvents
Xylene Market
Solvents
Para Nitrochlorobenzene Market
Solvents
Global Glycol Market
Solvents
Global Solvent Dyes Market