
 Diethylene Glycol Monobutyl Ether Acetate Market | 2026-2036
Diethylene Glycol Monobutyl Ether Acetate Market Size, Share, and Industry Trends Forecast 2026-2036
Diethylene Glycol Monobutyl Ether Acetate Market Intelligence
Specialized chemical process engineering talent is unwinding capacity bottlenecks across Asian and European production hubs. BASF SE leverages integrated ethylene oxide derivative chains to sustain feedstock cost advantages in Ludwigshafen. Dow Inc. anchors North American supply through its Freeport complex, while Mitsubishi Chemical Group dominates technical-grade solvent output for Japanese electronics laminates.
Diethylene glycol monobutyl ether acetate functions as a high-boiling ester solvent with a molecular weight of 204.27 g/mol and a boiling point near 247°C, manufactured through acetylation of the parent glycol ether with acetic anhydride. Its primary purpose centers on reducing surface tension in high-solids coatings while extending flow and leveling in bake-cured industrial finishes. Solvent-grade product types lead volume shipments but coating additive formulations capture disproportionate margin pools in aerospace-qualified lines. Paints applications retain the largest consumption share, though electronics-grade inks for printed circuit boards represent the fastest-growing addressable segment as miniaturization demands tighter rheological control.
EPA VOC rules under 40 CFR 59 constrain permissible solvent content in architectural and industrial maintenance coatings, pushing reformulation toward exempt or lower-reactivity esters. REACH registration requirements and ECHA substance evaluation protocols govern market access across EU member states, while China's MEE enforces emission standards at Jiangsu and Zhejiang chemical parks. Buyers and producers must monitor evolving substance restriction timelines and qualify alternative supply sources before regulatory transition deadlines disrupt qualified supplier lists.
Market Dynamics
EPA VOC regulations under 40 CFR 59 are forcing solvent reformulation across automotive and industrial coatings, redirecting demand toward exempt ester solvents with lower photochemical reactivity profiles.
Growth Catalysts
- Waterborne system mandates:EPA 40 CFR 59 compliance deadlines in automotive refinish coatings are accelerating solvent-grade diethylene glycol monobutyl ether acetate qualification for high-solids bake systems.
- Electronics miniaturization:Printed circuit board laminates in Guangdong Province require tighter rheological control, pulling technical-grade solvent volumes for inkjet and screen-print conductive formulations.
- REACH registration completion:ECHA substance evaluation protocols now permit unrestricted EU market access for registered diethylene glycol ether acetates, removing prior supply uncertainties for coating additive formulators.
Market Restraints
- Ethylene oxide derivative concentration:Feedstock supply chains cluster around integrated petrochemical complexes in Ludwigshafen and Freeport, creating geographic concentration risk for non-integrated buyers.
- Acetic anhydride cost volatility:Acetylation reagent pricing fluctuates with acetic acid spot markets, compressing margin stability for batch-process manufacturers without backward integration.
- Propylene glycol ether substitution:Lower-toxicity glycol ether acetates from propylene-based feedstocks compete in consumer-facing applications where hazard communication requirements are tightening.
Strategic Opportunities
- Indian electronics manufacturing:PLI scheme incentives for semiconductor and PCB fabrication in Gujarat and Tamil Nadu create virgin demand for electronics-grade solvent specifications.
- Dual carbon alignment in China:Jiangsu chemical park emission standards favor high-efficiency ester solvents with lower unit VOC output per coating coverage area.
- Aerospace-qualified additive lines:MIL-PRF coating specifications for military airframe maintenance open premium-margin segments for certified solvent-grade formulations with documented batch traceability.
Industry Challenges
- Specialized chemical process engineering scarcity:Acetylation reactor design and solvent purification expertise concentrates among retiring specialists in European and Japanese production hubs.
- Multi-jurisdiction qualification timelines:Concurrent EPA SNAP, REACH Annex XIV, and China MEE registration requirements extend product launch cycles by 18-36 months for new solvent entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diethylene Glycol Monobutyl Ether Acetate Market |
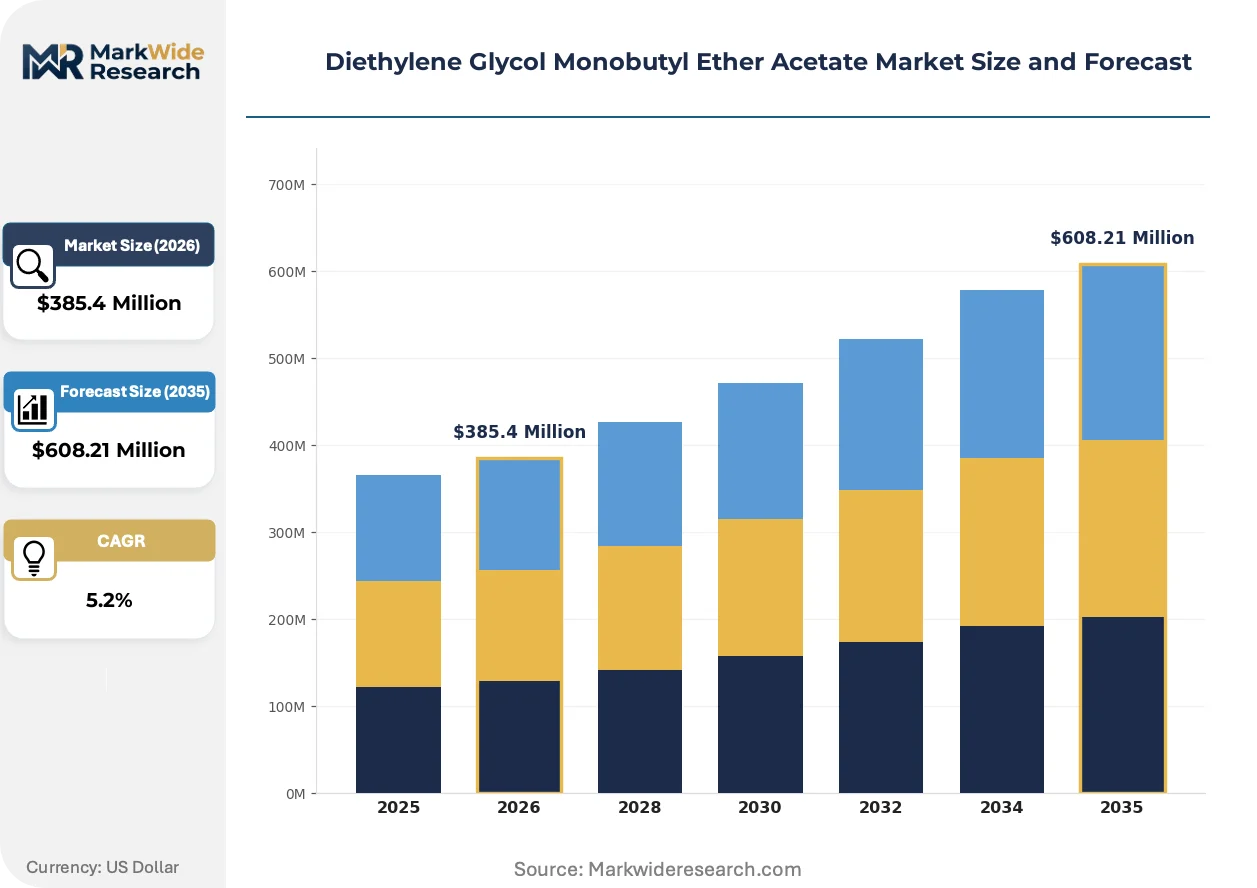
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $608.21 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
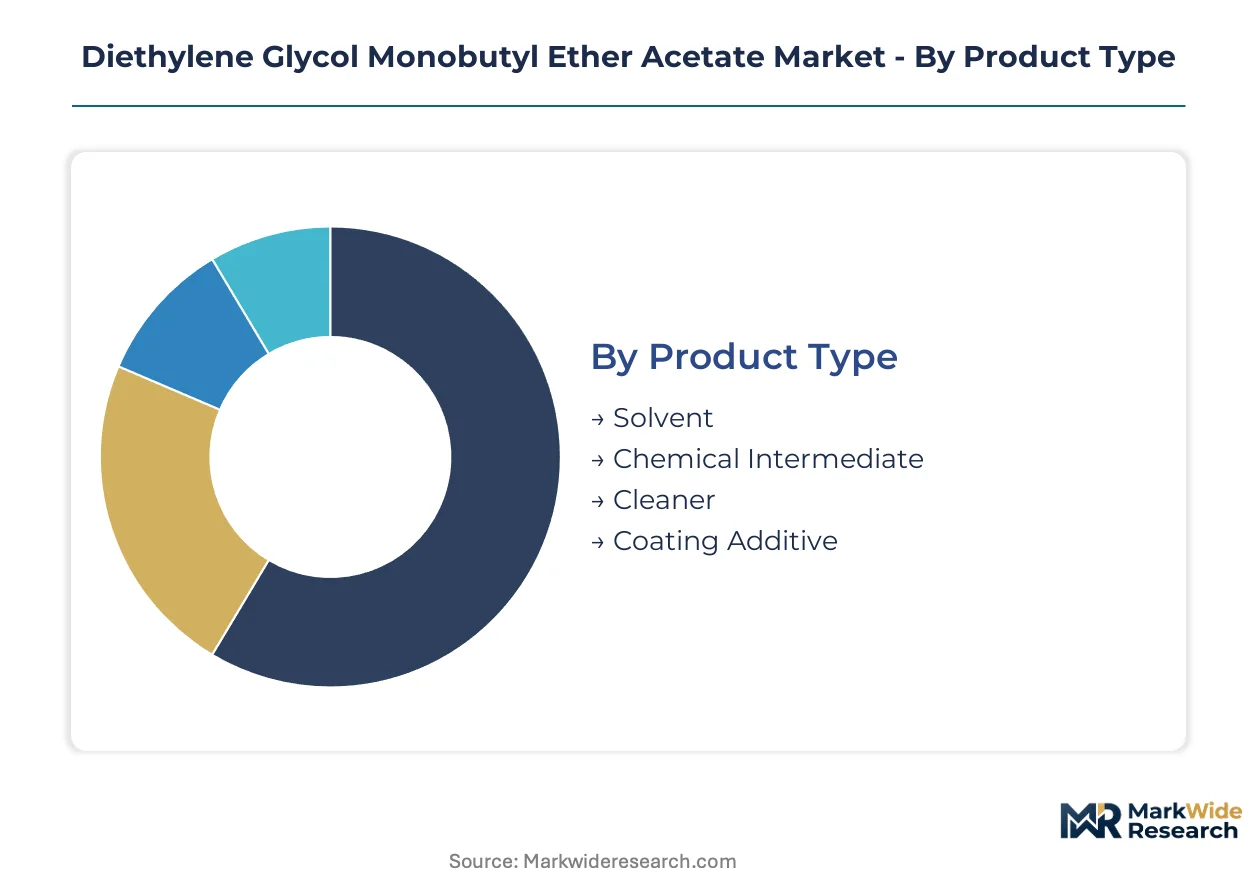
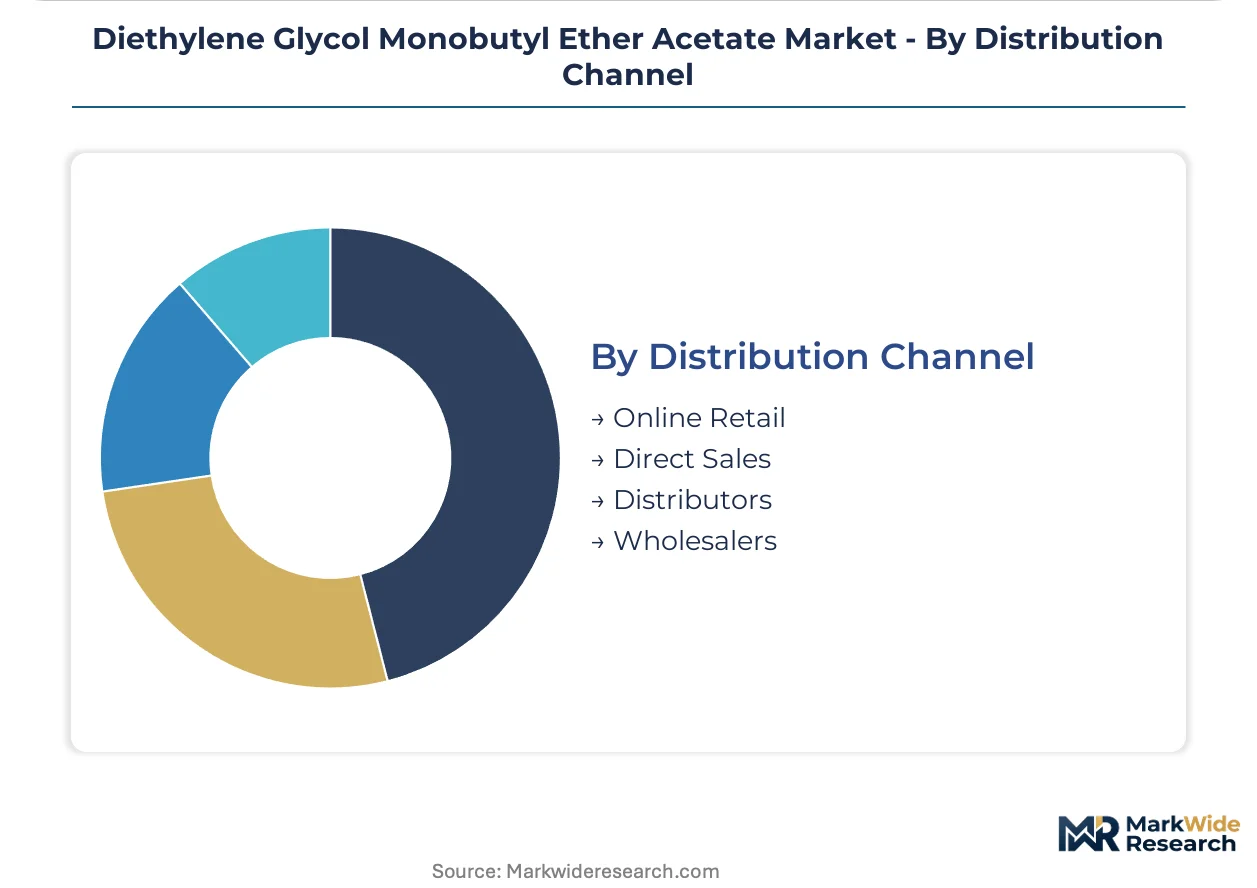
| Segmentation | Product Type: Solvent, Chemical Intermediate, Cleaner, Coating Additive Application: Paints, Adhesives, Inks, Personal Care End Use Industry: Aerospace, Automotive, Electronics, Construction Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Shell Chemicals, LyondellBasell Industries N.V., BASF SE, SABIC, Ineos Oxide, Dow Inc., Huntsman Corporation, Mitsubishi Chemical Group, Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diethylene Glycol Monobutyl Ether Acetate Market Strategic Shifts & Innovations
Reformulation chemistry is compressing solvent selection criteria toward multifunctional esters that simultaneously reduce surface tension, extend flow time, and meet exempt-status thresholds.
High-boiling ester solvent technology is miniaturizing. Electronics-grade diethylene glycol monobutyl ether acetate enables sub-50-micron line width printing in advanced PCB manufacturing. Japanese laminate producers in Nagoya and Osaka prefectures are qualifying technical-grade specifications at accelerated sampling rates. This solvent functionality is miniaturizing feature tolerances while demanding tighter moisture specification controls from suppliers.
REACH Annex XIV authorization timelines are compressing available substance windows for non-registered glycol ether derivatives. ECHA substance evaluation protocols now require updated safety dossiers for imported solvent volumes above 100 tonnes annually. Coating formulators in Germany and France are qualifying alternative supply chains ahead of 2026 evaluation deadlines for parent glycol ether precursors.
Buyer consolidation among automotive OEM refinish networks is concentrating solvent procurement through approved vendor lists. BASF and Dow direct distribution agreements with Michigan and Guangdong automotive corridor service centers are displacing independent chemical distributor channels. This channel compression is most visible in North American collision repair networks where MSO consolidation exceeds 40 percent market coverage.
Diethylene Glycol Monobutyl Ether Acetate Market Segmentation
Diethylene glycol monobutyl ether acetate serves divergent performance requirements across industrial solvents, electronic-grade formulations, and consumer-facing applications. Substitution pressures from propylene-based glycol ethers and waterborne system mandates fragment demand trajectories across product tiers. Understanding segment-specific vulnerability to reformulation chemistry directs supplier resource allocation toward defensible volume positions.
Product Type:
Solvent-grade formulations face the most acute substitution threat from exempt-status esters under tightening photochemical reactivity regulations, while specialized chemical intermediates retain structural insulation through captive supply arrangements.
- Solvent:High-boiling ester with molecular weight of 204.27 g/mol and boiling point near 247°C, manufactured through acetylation of parent glycol ether. Demand concentrates in automotive refinish corridors of Michigan and Guangdong Province where EPA VOC compliance deadlines under 40 CFR 59 force qualification for high-solids bake systems.
- Chemical Intermediate:Feedstock for downstream ester synthesis and specialty chemical manufacturing. Procurement clusters around integrated petrochemical complexes in Ludwigshafen and Freeport where backward integration into ethylene oxide derivatives sustains cost position against merchant market volatility.
- Cleaner:Precision degreasing formulations for electronics and aerospace maintenance. Japanese laminate producers in Nagoya prefecture qualify technical-grade specifications for sub-50-micron line width PCB manufacturing.
- Coating Additive:Rheology modifiers and flow control agents in aerospace-qualified lines. MIL-PRF coating specifications for military airframe maintenance open premium-margin segments requiring documented batch traceability.
Solvent anchors the volume base while coating additive gains share at the steepest rate.
Application:
Margin stratification separates industrial maintenance coatings from consumer-facing formulations where hazard communication requirements accelerate propylene glycol ether displacement.
- Paints:Industrial bake-cured finishes and automotive refinish systems retain the largest consumption share. Surface tension reduction and extended flow time specifications dominate formulation requirements in high-solids architectural coatings.
- Adhesives:Pressure-sensitive and structural bonding applications in automotive assembly. Guangdong Province electronics manufacturing corridors pull solvent volumes for laminate adhesive systems in PCB fabrication.
- Inks:Electronics-grade formulations for screen-print and inkjet conductive applications represent the fastest-climbing segment as miniaturization demands tighter rheological control in advanced PCB manufacturing.
- Personal Care:Nail polish removers and cosmetic solvent applications face intensifying propylene glycol ether substitution as hazard classification thresholds tighten in consumer product regulations.
Paints retains the volume anchor while inks demonstrates the steepest expansion trajectory.
End Use Industry:
Customer consolidation patterns concentrate procurement leverage among automotive OEM refinish networks and electronics manufacturing clusters.
- Aerospace:MIL-PRF qualified coating specifications for military and commercial airframe maintenance. Premium-margin solvent-grade formulations require certified batch traceability and documented purity specifications.
- Automotive:Refinish coatings in collision repair networks where MSO consolidation exceeds 40 percent market coverage in North America. Approved vendor lists at Michigan corridor service centers displace independent distributor channels.
- Electronics:Printed circuit board laminates and semiconductor packaging in Guangdong Province. Tighter moisture specification controls accompany qualification for sub-50-micron feature tolerances in advanced manufacturing.
- Construction:Architectural and industrial maintenance coatings constrained by EPA 40 CFR 59 VOC limits. Reformulation toward exempt ester solvents accelerates as compliance deadlines approach.
Automotive anchors the volume base while electronics gains share at the steepest rate.
Distribution Channel:
Channel compression favors direct supply relationships with consolidated end-users over fragmented wholesale networks.
- Direct Sales:Long-term supply agreements between integrated producers and automotive OEM refinish networks. BASF and Dow distribution arrangements with Michigan and Guangdong corridor service centers exemplify channel concentration.
- Distributors:Independent chemical distributors serving mid-tier coating formulators and regional maintenance operations. Margin pressure intensifies as approved vendor lists consolidate procurement authority.
- Wholesalers:Bulk volume aggregation for standard-grade solvent specifications in construction and general industrial applications.
- Online Retail:Small-volume procurement for specialty formulations and research quantities. Limited penetration in industrial-grade solvent categories due to qualification and certification requirements.
Direct sales anchors the volume base while distributor share compresses under customer consolidation pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German integrated petrochemical complexes while Chinese coastal provinces compete on volume throughput. Ludwigshafen producers capture margin premiums through captive ethylene oxide derivative chains. Guangdong manufacturing corridors absorb standard-grade volumes at compressed spreads.
United States
Automotive refinish coatings in Michigan's manufacturing corridor drive solvent-grade consumption as EPA 40 CFR 59 compliance deadlines approach. The agency's VOC limits for high-solids bake systems redirect formulation toward exempt ester specifications. Dow's Freeport complex anchors North American supply through backward integration into ethylene oxide feedstocks.
China
Printed circuit board laminates in Guangdong Province pull technical-grade volumes for sub-50-micron feature tolerances. MEE emission standards at Jiangsu and Zhejiang chemical parks favor high-efficiency esters with lower unit VOC output per coating coverage area. Dual carbon alignment goals accelerate qualification of solvent grades with documented batch traceability.
Germany
Coating additive formulators in Ludwigshafen leverage REACH registration completion for unrestricted EU market access. ECHA substance evaluation protocols now govern imported volumes above 100 tonnes annually. BASF's integrated derivative chains sustain feedstock cost advantages against merchant market volatility.
Japan
Electronics-grade specifications for Nagoya and Osaka laminate producers demand tighter moisture controls in advanced PCB manufacturing. METI industrial standards shape qualification timelines for technical-grade solvent imports. Mitsubishi Chemical Group dominates domestic output through specialized acetylation reactor capacity.
India
PLI scheme incentives for semiconductor and PCB fabrication in Gujarat and Tamil Nadu create virgin demand for electronics-grade specifications. BIS quality standards for imported industrial solvents extend product launch cycles for new entrants. Mumbai-Pune chemical processing corridors concentrate formulation demand from emerging electronics manufacturing clusters.
Diethylene Glycol Monobutyl Ether Acetate Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the diethylene glycol monobutyl ether acetate supply base. Integrated petrochemical majors with captive ethylene oxide derivative chains command feedstock economics, while specialized acetylation operators capture premium tiers through purity specifications. Three archetypes dominate: backward-integrated global chemical conglomerates, regional ester specialists with reactor design expertise, and electronics-grade purity operators serving Japanese laminate markets. Competitive moves center on capacity expansion at coastal Chinese chemical parks and strategic partnerships with automotive OEM refinish networks.
Among integrated chemical conglomerates, BASF SE and Dow Inc. exemplify the scale-driven archetype through ethylene oxide derivative integration. Mitsubishi Chemical Group occupies a specialist position within the electronics-grade purity tier. These three anchors represent divergent strategic positions: European feedstock integration, North American Gulf Coast petrochemical clustering, and Japanese technical-grade specification leadership.
| Leading Market Players |
|---|
| Shell Chemicals |
| LyondellBasell Industries N.V. |
| BASF SE |
| SABIC |
| Ineos Oxide |
| Dow Inc. |
| Huntsman Corporation |
| Mitsubishi Chemical Group |
| Eastman Chemical Company |
| Others |
Cost & Logistics Intelligence
EPA 40 CFR 59 VOC compliance deadlines gate both supplier qualification and price differentiation in diethylene glycol monobutyl ether acetate procurement. Buyers must pre-qualify exempt-status ester sources before regulatory transition dates, compressing price negotiation windows while premium tiers open for certified aerospace-grade formulations.
Pricing Analysis
Ludwigshafen commands 15-20% premiums over Guangdong spot markets for solvent-grade specifications. Three-tier pricing structure across aerospace-certified, automotive-qualified, and standard industrial grades separates buyers by documentation burden. Cost compression in standard solvent tiers stems from propylene glycol ether substitution. Tier 2 automotive refinish networks show highest price sensitivity; aerospace MIL-PRF contractors absorb premiums for batch traceability.
Supply Chain Analysis
Strait of Malacca transit underwrites ethylene oxide feedstock flows to Asian acetylation capacity. Supply concentrates in Germany, the United States, and China where integrated petrochemical complexes control ethylene oxide derivative output. Acetic anhydride and parent glycol ether feedstock dependencies expose batch-process manufacturers to spot market volatility. Single-source vulnerability concentrates in Japanese electronics-grade specifications where Mitsubishi Chemical Group dominates technical purity output. Distribution runs through direct sales agreements with automotive OEM refinish networks, displacing independent chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acetylation reactor design expertise is retiring faster than knowledge transfer systems can replace it, constraining capacity expansion timelines across European and Japanese production hubs. This capability scarcity will determine which suppliers capture premium-tier volumes in aerospace and electronics-grade segments.
For Market Incumbents: Shield qualified supplier status by accelerating EPA 40 CFR 59 pre-certification for exempt-status ester grades ahead of competitor entry. Backward integration into acetic anhydride supply insulates margin stability against spot market volatility. Channel control through direct distribution agreements with Michigan and Guangdong automotive corridor service centers locks out independent distributor competition.
For New Entrants and Emerging Players: Anchor in Indian electronics manufacturing corridors where PLI scheme incentives for Gujarat and Tamil Nadu semiconductor fabrication create virgin demand for electronics-grade specifications. Technical-grade solvent qualification for sub-50-micron PCB manufacturing offers the most penetrable white space. Partner with established Japanese laminate producers for accelerated sampling protocols.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across aerospace-certified additive lines as MIL-PRF documentation requirements expand fixed cost bases. Five-to-ten year viability favors integrated petrochemical majors with captive ethylene oxide derivative chains over merchant batch-process operators. Monitor ECHA substance evaluation timelines for parent glycol ether precursors as inflection signal for supply disruption windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive acetic anhydride production insulates BASF and Dow from spot market volatility. |
| Capacity Expansion | Jiangsu chemical park additions align with MEE emission standards favoring high-efficiency esters. |
| Long-term Supply Agreement | Direct distribution with Michigan automotive corridors locks out independent distributor competition. |
| Joint Venture | Indian PLI scheme partnerships accelerate electronics-grade qualification for Gujarat fabrication. |
| Green Manufacturing Transition | Dual carbon alignment in China favors ester solvents with lower unit VOC output per coverage area. |
Research Approach
A standing panel of acetylation reactor operators, automotive refinish procurement leads, electronics laminate technical directors, and chemical distribution channel managers provided ongoing calibration across primary interview cycles. Secondary validation drew from EPA 40 CFR 59 regulatory filings, ECHA REACH registration databases, ACC solvent market reports, and customs trade data for ethylene oxide derivative flows. Bottom-up volume modeling triangulated against top-down petrochemical capacity assessments.
Consistency checks validated segment-level outputs against external benchmarks including regional chemical park emission disclosures and OEM refinish network procurement patterns. The analytical framework modeled grade tier, end-use industry, and regional production hub dimensions across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating EPA compliance deadline phasing and electronics miniaturization trajectories.
Decision-makers should treat outputs as directional under base assumptions of regulatory timeline adherence and feedstock cost stability; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as ECHA Annex XIV authorization timelines and China MEE emission standard enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Isopropylamine Market
Solvents
N-Pentyl Chloride Market
Solvents
Methyl Acetate Market
Solvents
N-Hexane Market
Solvents
Diethylene Glycol (DEG) Market
Solvents
India High Purity Solvents Market
Solvents
1, 1-Difluoroethane Market
Solvents
Ultra-Low-VOC Methacrylate Reactive Diluents Market
Solvents
Propylene Glycol Ether Market
Solvents
Global Nitrochlorobenzene Market
Solvents
Dihydromyrcene Market
Solvents
5-Isopropyl-M-Xylene Market
Solvents
Solvent Green 7 Market
Solvents
N-Methyl Pyrrolidone Market
Solvents
Global Chloroform Market
Solvents
2-Butanone Market