
 Benzylamine Market | 2026-2036
Benzylamine Market Size, Share, and Industry Trends Forecast 2026-2036
Benzylamine Market Analysis
Buyer concentration among pharmaceutical contract manufacturers is rebalancing as large API producers consolidate procurement while specialty biotech labs fragment into smaller qualified suppliers. Mitsubishi Gas Chemical Company leverages its integrated gas-chemical platform to sustain captive benzylamine output for captive pharmaceutical demand. BASF anchors European supply through Ludwigshafen-based amine chemistry expertise and REACH-compliant product stewardship. Jiangsu Jiye Medicine & Chemical Co. Ltd. competes on cost-optimized routes from regional benzyl chloride feedstock.
Benzylamine is a primary aliphatic amine with formula C6H5CH2NH2, typically synthesized via catalytic hydrogenation of benzyl cyanide or ammonolysis of benzyl chloride, and serves as a versatile intermediate for pharmaceuticals, agrochemicals, and polymer additives. Pharmaceutical applications dominate value capture due to stringent pharmacopeial-grade requirements and validated supplier audits, while agrochemical formulations represent the fastest-expanding volume segment driven by herbicide and fungicide pipeline renewal. Plastics applications remain mature with stable demand from rubber-processing chemical manufacturers seeking anti-degradant precursors.
EPA TSCA Section 5 premanufacture notification requirements govern new benzylamine derivatives in the United States, while REACH registration dossiers under ECHA mandate toxicological and ecotoxicological data for European market access. China's MEE enforces GB standards on volatile organic compound emissions from amine production facilities, constraining small-scale producers. Stakeholders must monitor evolving pharmaceutical excipient qualification protocols and carbon-intensity disclosure rules that will reshape supplier selection criteria for benzylamine procurement.
Market Dynamics
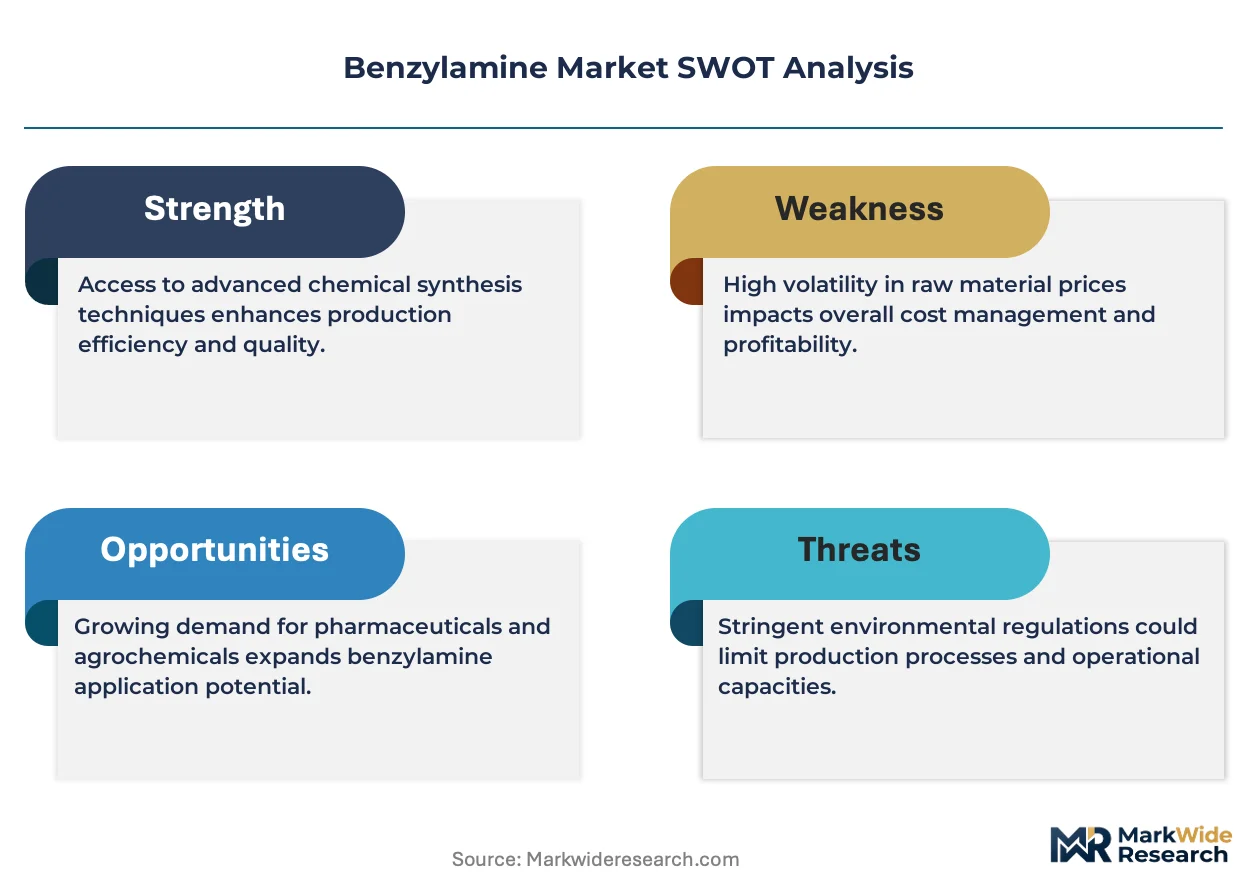
Pharmaceutical-grade benzylamine procurement is consolidating around integrated chlor-alkali-to-amine manufacturing clusters, compressing margins for standalone hydrogenation specialists while elevating purity certification barriers for market entry.
Growth Catalysts
- REACH registration dossier completion:ECHA-mandated toxicological data packages for European market access are locking in qualified suppliers and excluding marginal producers from the region's pharmaceutical value chain.
- Herbicide pipeline renewal:Agrochemical formulators are expanding benzylamine offtake for novel sulfonylurea and imidazolinone chemistries targeting resistant weed strains.
- Shandong-Jiangsu production corridor:China's integrated benzyl chloride-to-amine manufacturing clusters are achieving feedstock-cost advantages that reshape interregional trade flows.
Market Restraints
- Benzyl chloride feedstock volatility:Toluene price swings and chlorination capacity constraints transmit directly to benzylamine cost structures, squeezing hydrogenation-only operators.
- Small-scale producer attrition:China's MEE enforcement of GB volatile organic compound emission standards is shuttering sub-scale amine facilities in Hebei and Henan provinces.
- Catalytic hydrogenation yield ceilings:Palladium-on-carbon catalyst deactivation rates limit batch efficiency gains for benzyl cyanide reduction routes.
Strategic Opportunities
- Indian pharmaceutical excipient qualification:CDSCO's tightening active pharmaceutical ingredient import protocols create first-mover advantages for benzylamine producers completing BIS purity certification.
- Continuous-flow ammonolysis:Microreactor technology convergence with real-time analytics is enabling modular production scale-down for regional supply proximity.
- Carbon-intensity disclosure mandates:EU Green Deal supply-chain emissions reporting requirements favor producers with renewable hydrogen feedstock access.
Industry Challenges
- Pharmacopeial-grade validation timelines:USP and EP certification cycles for new benzylamine supply sources extend 18-24 months, freezing supplier switching.
- Specialized catalyst sourcing:Securing long-term palladium and ruthenium supply contracts amid precious metal market volatility demands working capital intensity most mid-scale producers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Benzylamine Market |
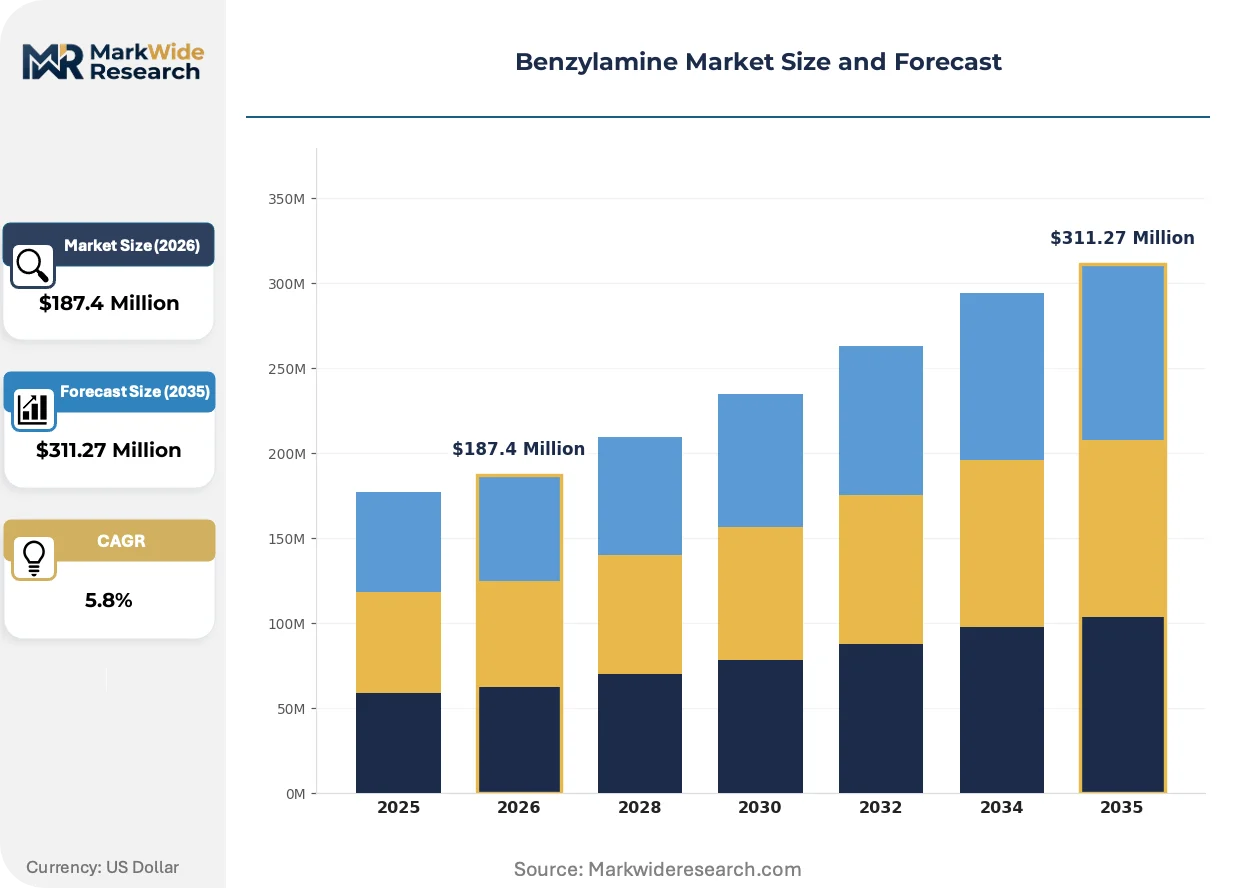
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Pharmaceuticals, Agrochemicals, Dyes, Plastics End User: Chemical Manufacturers, Research Laboratories, Biotechnology Firms, Automotive Industry Product Type: Benzylamine, Benzyl Alcohol, Benzyl Chloride, Alkylbenzene Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Shandong Yuexing Chemical Co. Ltd., Mitsubishi Gas Chemical Company, BASF, Jiangsu Jiye Medicine & Chemical Co. Ltd., Huntsman Corporation, LANXESS, Eastman Chemical Company, Changzhou Huayang Technology Co. Ltd., KOEI CHEMICAL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Benzylamine Market Emerging Trajectories
Modular production architectures and real-time quality verification systems are compressing the traditional scale-economy advantage of centralized amine manufacturing, enabling distributed supply networks.
Continuous-flow microreactor technology for benzyl chloride ammonolysis is decentralizing production economics by slashing minimum efficient scale thresholds. Regional pharmaceutical contract manufacturers are piloting 500-liter-per-day skid-mounted units. This architecture is decentralizing captive supply integration away from mega-facility dependence toward pharmacy-proximate manufacturing nodes.
REACH authorization requirements for Substances of Very High Concern are tightening purity documentation burdens on benzylamine importers. European formulators now demand full supply-chain substance identity dossiers. Specialty agrochemical blenders in Germany and France are absorbing compliance costs by consolidating procurement onto pre-registered suppliers.
Buyer consortiums among mid-tier pharmaceutical API producers are displacing individual spot-market purchasing with multi-year offtake agreements. These aggregated procurement vehicles are extracting volume-tier pricing from qualified suppliers. The shift is most visible in India, where CDSCO-registered contract manufacturers are pooling benzylamine demand to secure EP-grade supply commitments.
Benzylamine Market Segmentation
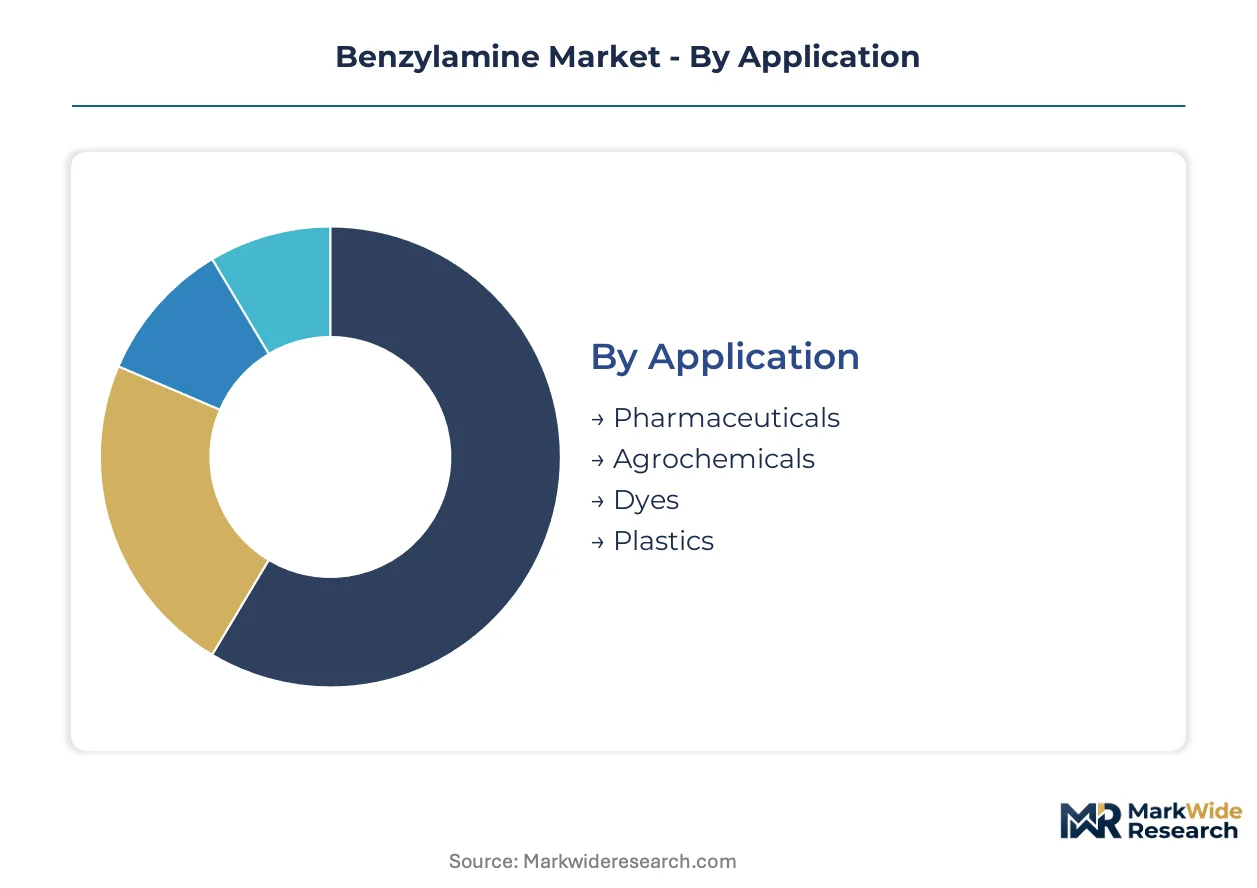
Segmentation in benzylamine markets reveals how purity grades, procurement channels, and end-use specifications fragment pricing power across supplier tiers. Buyers in pharmaceutical synthesis face radically different qualification burdens than agrochemical blenders, creating non-overlapping supply pools.
Application:
End-use purity requirements determine supplier eligibility and contract duration more than volume scale.
- Pharmaceuticals:Pharmacopeial-grade benzylamine demands USP and EP certification cycles spanning 18-24 months. API manufacturers in India and Germany consolidate procurement onto pre-qualified suppliers to avoid validation delays.
- Agrochemicals:Technical-grade material feeds herbicide and fungicide synthesis with lower purity thresholds but higher volume elasticity. Sulfonylurea chemistry renewal in Brazil and France is expanding offtake for resistant weed formulations.
- Dyes:Intermediate-grade benzylamine serves azo and anthraquinone dye precursors with stable, mature demand from textile chemical manufacturers in China and India.
- Plastics:Anti-degradant precursor applications for rubber processing chemicals show flat growth, with procurement concentrated among legacy polymer additive suppliers.
Volume sits with Pharmaceuticals; growth tilts toward Agrochemicals.
End User:
Customer scale and technical capability split the market between integrated manufacturers and fragmented laboratory consumers.
- Chemical Manufacturers:Integrated chlor-alkali and amine producers in Shandong and Ludwigshafen achieve feedstock-cost advantages that standalone hydrogenation operators cannot match. Multi-year offtake agreements dominate procurement.
- Research Laboratories:Small-volume, high-frequency orders for reagent-grade material command premium pricing. Specialty biotech labs fragment supplier relationships across multiple qualified sources to mitigate single-source risk.
- Biotechnology Firms:Contract development and manufacturing organizations require documented supply-chain substance identity dossiers under REACH authorization protocols.
- Automotive Industry:Rubber-processing chemical demand from tire manufacturers links to anti-degradant precursor consumption with stable, specification-driven procurement.
Procurement scale concentrates among Chemical Manufacturers; contract flexibility matters most to Research Laboratories.
Product Type:
Feedstock integration and derivative economics shape competitive positioning across the benzyl chemistry chain.
- Benzylamine:Primary aliphatic amine synthesized via catalytic hydrogenation of benzyl cyanide or ammonolysis of benzyl chloride. Captive demand from pharmaceutical API synthesis anchors value capture.
- Benzyl Alcohol:Solvent and preservative applications in pharmaceuticals and personal care create partially overlapping supplier bases with distinct purity specifications.
- Benzyl Chloride:Critical feedstock for benzylamine production via ammonolysis routes; integrated producers in Jiangsu province achieve cost advantages through captive chlorination capacity.
- Alkylbenzene:Surfactant intermediate with divergent end-use economics; linear alkylbenzene sulfonate demand from detergent manufacturers operates on separate pricing dynamics.
Margin capture peaks with Benzylamine; feedstock leverage concentrates with Benzyl Chloride.
Distribution Channel:
Channel selection reflects order predictability, certification documentation burdens, and geographic proximity to manufacturing clusters.
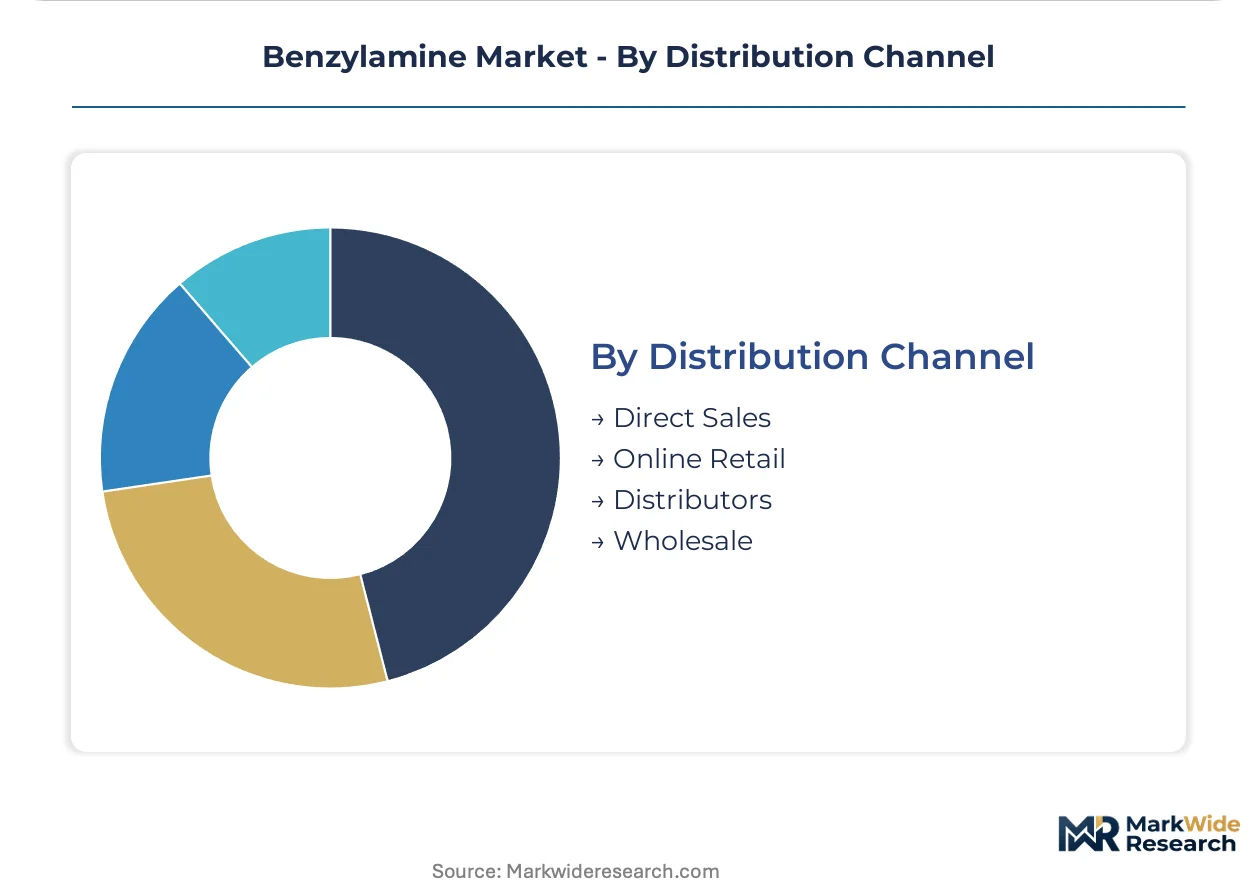
- Direct Sales:Multi-year supply agreements between API producers and integrated amine manufacturers eliminate intermediary margins. ECHA REACH registration dossiers travel directly with bulk shipments to European formulators.
- Distributors:Regional chemical distributors aggregate fragmented laboratory demand and manage import documentation for qualified suppliers. Indian CDSCO-registered contract manufacturers rely on distributor networks for EP-grade certification support.
- Online Retail:Reagent-grade and small-package benzylamine for research laboratories flows through specialized chemical e-commerce platforms with real-time inventory visibility.
- Wholesale:Bulk technical-grade material for agrochemical blenders moves through wholesale channels with volume-tier pricing and consolidated logistics.
Relationship intensity peaks with Direct Sales; coverage breadth favors Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical API manufacturers in India and Germany are consolidating benzylamine procurement onto pre-qualified suppliers, while Chinese integrated producers leverage feedstock-cost advantages to capture agrochemical volume growth.
China
Shandong and Jiangsu provinces host integrated benzyl chloride-to-amine manufacturing clusters that achieve captive chlorination economies. MEE enforcement of GB volatile organic compound emission standards is shuttering sub-scale facilities in Hebei and Henan, concentrating output among compliant operators. Regional producers supply technical-grade material for agrochemical formulators targeting resistant weed strains across Brazil and France.
Germany
BASF anchors European benzylamine supply through Ludwigshafen-based amine chemistry expertise serving pharmaceutical and agrochemical formulators. REACH registration dossiers under ECHA mandate toxicological and ecotoxicological data packages that exclude marginal producers from the region's value chain. Specialty agrochemical blenders in Germany absorb compliance costs by consolidating procurement onto pre-registered suppliers with full substance identity documentation.
India
CDSCO-registered contract manufacturers in Maharashtra and Gujarat are pooling benzylamine demand through buyer consortiums to secure EP-grade supply commitments. BIS purity certification requirements for active pharmaceutical ingredient imports create first-mover advantages for producers completing validation protocols. Regional API producers face 18-24 month pharmacopeial-grade certification cycles that freeze supplier switching and entrench incumbent relationships.
United States
EPA TSCA Section 5 premanufacture notification requirements govern new benzylamine derivatives entering commercial channels. Pharmaceutical manufacturers concentrate procurement among integrated chlor-alkali-to-amine suppliers to compress validation timelines and secure multi-year offtake agreements. Rubber-processing chemical demand from tire manufacturers in the Southeast maintains stable consumption of anti-degradant precursors.
Japan
Mitsubishi Gas Chemical Company leverages its integrated gas-chemical platform to sustain captive benzylamine output for domestic pharmaceutical demand. METI industrial policy supports precision chemical manufacturing through supply-chain resilience initiatives. Regional producers focus on high-purity grades for specialty pharmaceutical applications rather than commodity agrochemical volumes.
Benzylamine Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue modular microreactor deployment and regional supply proximity. The vendor base stratifies across integrated chemical conglomerates with captive feedstock positions, standalone hydrogenation specialists facing margin compression, and technology-driven entrants commercializing continuous-flow ammonolysis. Competitive dynamics center on backward integration into benzyl chloride feedstock and pharmacopeial-grade certification completion.
Within the integrated chemical conglomerate tier, Mitsubishi Gas Chemical Company and BASF exemplify archetypes leveraging gas-chemical and petrochemical platforms respectively. Jiangsu Jiye Medicine & Chemical Co. Ltd. occupies a position among regional Chinese producers competing on cost-optimized routes from provincial benzyl chloride feedstock. These three anchors illustrate how geographic clustering around feedstock sources and regulatory compliance capabilities determine competitive positioning.
| Leading Market Players |
|---|
| Shandong Yuexing Chemical Co. Ltd. |
| Mitsubishi Gas Chemical Company |
| BASF |
| Jiangsu Jiye Medicine & Chemical Co. Ltd. |
| Huntsman Corporation |
| LANXESS |
| Eastman Chemical Company |
| Changzhou Huayang Technology Co. Ltd. |
| KOEI CHEMICAL |
| Others |
Supply Flow & Price Mechanics
Toluene feedstock costs cascade through chlorination capacity into benzylamine pricing tiers, with captive benzyl chloride producers in Shandong extracting margin premiums that standalone hydrogenation operators in Hebei cannot match. Pharmaceutical-grade certification burdens amplify these spreads, concentrating pricing power among REACH-registered suppliers serving European API manufacturers.
Pricing Analysis
Volume concentrates with technical-grade agrochemical offtake while margin capture peaks in pharmacopeial-grade pharmaceutical supply. Three-tier pricing structure across premium, standard, and economy levels separates USP/EP-certified pharmaceutical material from technical-grade agrochemical feedstock and reagent-grade laboratory supply. Cost compression in standard-grade material is intensifying because MEE emission enforcement is shuttering sub-scale Chinese producers. Agrochemical blenders in Brazil exhibit highest price sensitivity due to commodity herbicide economics, while Indian CDSCO-registered contract manufacturers absorb premium pricing to avoid 18-24 month supplier validation delays.
Supply Chain Analysis
Freight cost differentials between bulk technical-grade shipments and temperature-controlled pharmaceutical-grade logistics widen procurement economics across buyer segments. Manufacturing concentrates in China, Germany, and India, with Shandong-Jiangsu clusters feeding agrochemical volume and Ludwigshafen-based producers anchoring European pharmaceutical supply. Raw material sourcing draws from toluene chlorination capacity, palladium catalyst supply, and ammonia feedstock. Single-source vulnerability sits with precious metal catalyst contracts amid volatile ruthenium markets. Distribution runs through direct multi-year offtake agreements for pharmaceutical API producers and regional chemical distributors aggregating laboratory demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Benzylamine supply remains structurally constrained by catalytic hydrogenation yield ceilings and precious metal catalyst sourcing bottlenecks, propping pricing premiums for qualified producers with secured palladium supply contracts.
For Market Incumbents: To counter margin compression from integrated chlor-alkali competitors, BASF and Mitsubishi Gas Chemical Company should deepen backward integration into benzyl chloride feedstock through Ludwigshafen and Kashima corridor capacity additions. Securing 10-year palladium supply offtake agreements with South African and Russian miners locks in catalyst cost advantages that standalone hydrogenation specialists cannot replicate. For New Entrants and Emerging Players: E-commerce platforms for reagent-grade benzylamine represent the lowest barrier-to-entry channel for laboratory demand aggregation. Target Indian CDSCO-registered contract manufacturers in Maharashtra and Gujarat through BIS-certified microreactor deployment offering 500-liter-per-day regional supply proximity. Continuous-flow ammonolysis technology licensing from European engineering firms provides differentiated entry without billion-dollar chlor-alkali investment. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale hydrogenation specialists with incomplete REACH dossiers in Jiangsu province facing MEE compliance upgrade costs. Five-to-ten year viability hinges on feedstock integration completion rather than standalone technology advantages. Watch for ECHA Substances of Very High Concern list expansion as inflection indicator that would accelerate supplier consolidation onto pre-registered incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Benzyl Chloride | Shandong chlor-alkali clusters achieve 15-20% feedstock cost advantages over hydrogenation-only operators. |
| REACH Registration Dossier Completion | ECHA-mandated toxicological packages lock out marginal producers from European pharmaceutical value chains. |
| Continuous-Flow Microreactor Deployment | Modular 500-liter-per-day units enable pharmacy-proximate manufacturing nodes bypassing mega-facility dependence. |
| Long-Term Precious Metal Supply Contracts | Palladium and ruthenium price volatility hedging secures catalyst cost predictability for hydrogenation routes. |
| Carbon-Intensity Certification Investment | EU Green Deal supply-chain emissions reporting favors producers with renewable hydrogen feedstock access. |
Methodological Framework
Independent corroboration across plant managers at integrated chlor-alkali facilities, procurement leads at Indian pharmaceutical API manufacturers, distribution channel partners in European chemical distribution, and technical R&D directors at agrochemical formulators underwrites the qualitative findings. Secondary validation draws from customs/trade data, Cefic amine market reports, SEC 10-K filings of listed chemical conglomerates, and ECHA registration dossier databases. Bottom-up capacity modeling across Shandong and Jiangsu production clusters triangulates against top-down pharmaceutical and agrochemical demand estimates.
Comparable historical periods anchored the forecast window to pre-pandemic baselines and post-MEE enforcement trajectories across the analysis window. Segmentation dimensions modeled include purity grade tier, end-use industry application, regional production hub clustering, and certification status under REACH and CDSCO protocols. CAGRs were derived from slope analysis of validated production capacity additions against downstream demand elasticity. Industry-specific inputs incorporated benzyl chloride feedstock cost curves and pharmacopeial-grade validation timeline distributions.
The model holds under stable precious metal catalyst supply and continued MEE enforcement intensity; deviation in ECHA SVHC list expansion timing or palladium market disruption would shift supplier competitive positioning. Stakeholders should weight assumptions against their own operating context and catalyst sourcing security.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Coating Solvents Market
Solvents
Global Furfural Solvent Market
Solvents
Global Green and Bio-Based Solvents Market
Solvents
Hydrocarbon Solvents Market
Solvents
Oxygenated Solvents Market
Solvents
Diethylene Glycol Monobutyl Ether Acetate Market
Solvents
Global Ethyl Lactate Market
Solvents
1, 1-Difluoroethane Market
Solvents
Propylene Glycol Market
Solvents
Triacetin Market
Solvents
Global Solvents Market
Solvents
Phenol Derivatives Market
Solvents
Solvent Recovery Systems Market
Solvents
3-Butylene Glycol Market
Solvents
Trifluoroethanol Market
Solvents
Chlorobenzene Market