
 Mixed Xylene Market | 2026-2036
Mixed Xylene Market Size, Share, and Industry Trends Forecast 2026-2036
Mixed Xylene Market Analysis
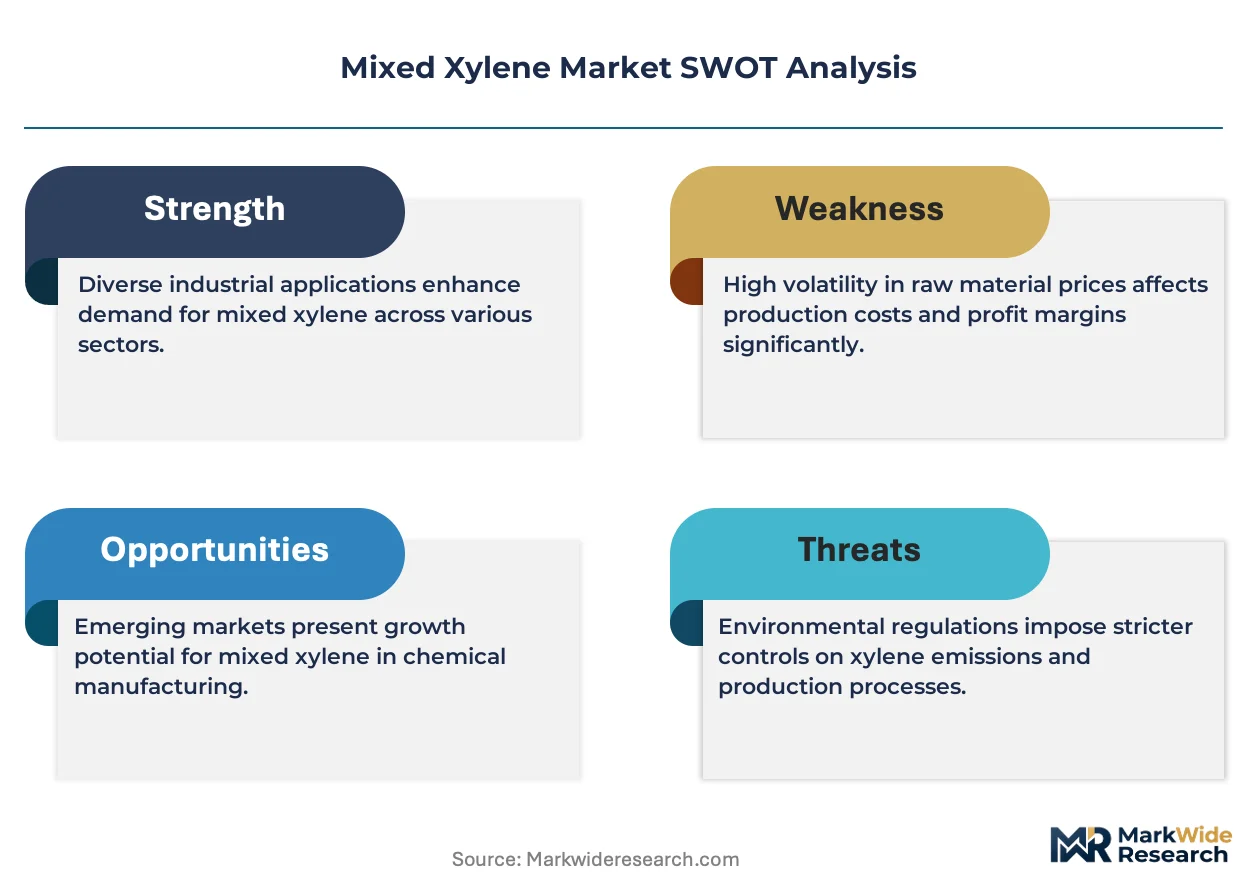
Long-term supply contracts is consolidating buyer choice across the Mixed Xylene value chain, locking processors into dedicated offtake rather than spot procurement. ExxonMobil Corporation leverages its integrated refining-petrochemical complexes on the US Gulf Coast to secure captive feedstock. Shell plc anchors European supply through its Rotterdam aromatics hub, while China Petrochemical Corporation dominates domestic distribution via pipeline-linked coastal refineries.
Mixed xylene denotes a C8 aromatic hydrocarbon blend containing ethylbenzene, para-xylene, meta-xylene, and ortho-xylene isomers, typically recovered through catalytic reforming or steam cracking of naphtha feedstocks; its primary purpose is serving as feedstock for para-xylene production, which yields purified terephthalic acid for polyester manufacturing. Chemical Grade material captures the dominant margin pool due to para-xylene extraction economics, while Solvent Grade faces structural pressure as waterborne coatings displace aromatic thinners in regulated markets. Delivery via bulk tanker dominates volume flows to integrated chemical parks, though drum packaging sustains smaller formulation customers in fragmented coatings applications.
The US EPA enforces National Emission Standards for Hazardous Air Pollutants that limit benzene and xylene fugitive emissions at refineries and downstream chemical plants, forcing capital upgrades to vapor recovery systems. China's MEE implements increasingly stringent VOC control measures under its dual carbon framework, tightening product specifications for solvent applications. REACH registration requirements in Europe constrain non-EU suppliers seeking market access, elevating compliance costs for import-dependent processors. Stakeholders must monitor regulatory divergence across these three jurisdictions to anticipate specification shifts that could strand existing inventory or open formulation substitution opportunities.
Market Dynamics
East Asian refiners are upgrading isomerization units to boost para-xylene yields, redirecting solvent-grade supply toward chemical-grade extraction as polyester feedstock demand tightens regional C8 aromatic balances.
Growth Catalysts
- Dual carbon framework:China's MEE is tightening VOC emissions rules, redirecting formulation demand toward lower-aromatic alternatives that favor high-purity chemical-grade streams.
- Petrochemical corridor clustering:South Korea's Ulsan-Yeosu industrial belt anchors derivative capacity expansion, concentrating mixed xylene offtake within integrated chemical parks.
- Naphtha reforming yields:Advanced catalytic reforming catalysts are lifting C8 aromatic recovery rates from heavy feedstocks, expanding available supply for para-xylene extraction.
Market Restraints
- Waterborne coating substitution:Architectural and industrial coatings formulators are displacing aromatic thinners with waterborne systems, compressing solvent-grade pricing power in regulated markets.
- Pipeline-linked refinery concentration:China's coastal refineries dominate domestic distribution through dedicated pipeline networks, limiting third-party processor access to spot cargoes.
- Benzene fugitive emission controls:The US EPA's National Emission Standards for Hazardous Air Pollutants mandate vapor recovery capital upgrades, elevating fixed costs for integrated producers.
Strategic Opportunities
- India's polyester capacity buildout:Reliance Industries and Indian Oil Corporation are expanding purified terephthalic acid complexes, creating new chemical-grade demand outside East Asian supply orbits.
- Biomass-derived aromatic pathways:Pyrolysis oil upgrading and lignin depolymerization technologies are converging with conventional refining, offering circular feedstock alternatives for specialty solvent applications.
- REACH registration gaps:European ECHA compliance requirements constrain non-EU suppliers, creating margin capture potential for registered importers serving coatings and adhesive formulators.
Industry Challenges
- Isomer separation expertise:Crystallization and simulated moving bed adsorption operations require specialized process engineering talent that refiners struggle to retain as petrochemical complexes automate.
- Specification requalification timelines:Shifting MEE product specifications for solvent applications strand existing inventory and force reformulation cycles that disrupt just-in-time delivery contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mixed Xylene Market |
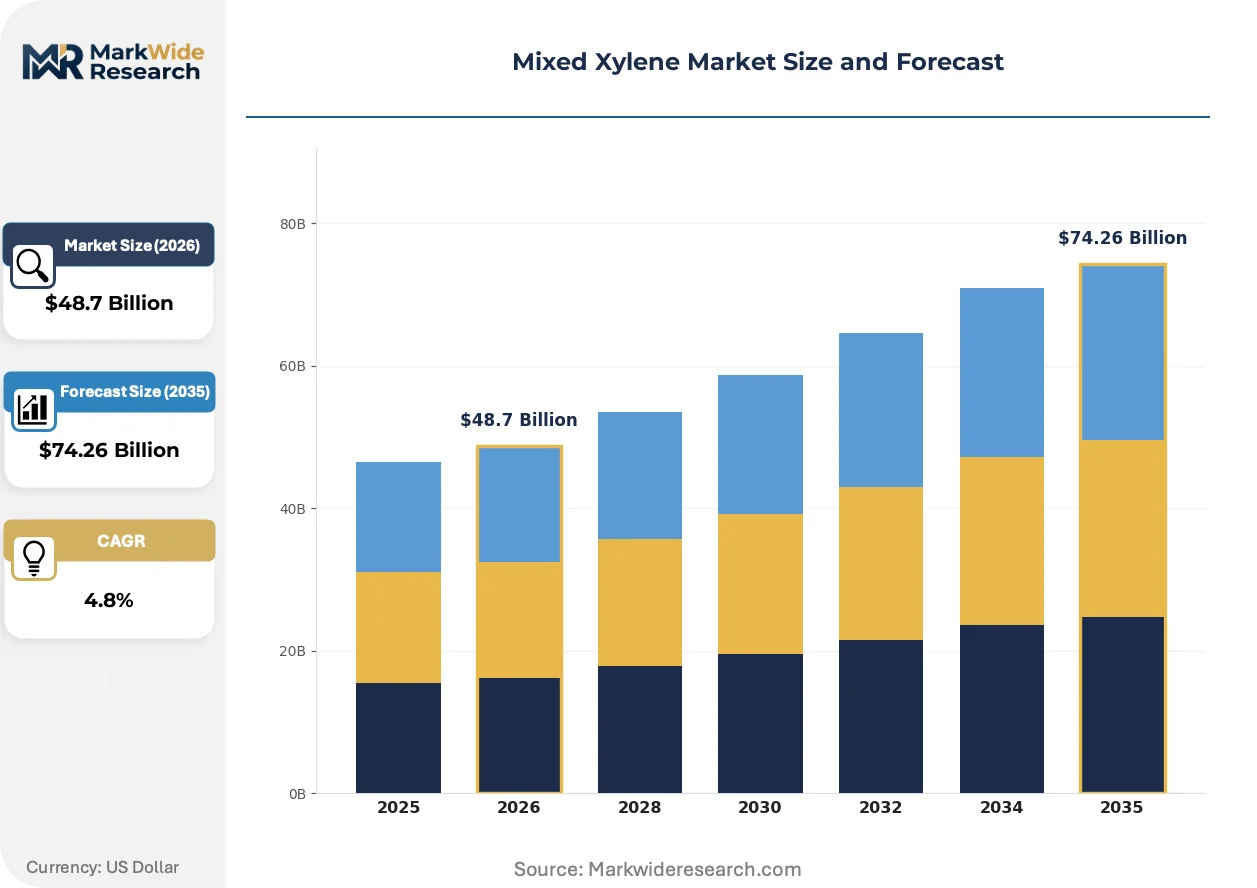
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $74.26 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent Grade, Chemical Grade, Industrial Grade, Laboratory Grade End Use: Paints, Adhesives, Coatings, Pharmaceuticals Delivery Mode: Bulk, Drums, IBCs, Containers Application: Chemical Manufacturing, Paint Thinning, Fuel Additives, Extraction |
| Companies Covered | ExxonMobil Corporation, Shell plc, Reliance Industries Ltd., China Petrochemical Corporation, Chevron Phillips Chemical Company, Lotte Chemical, China National Petroleum Corporation, Idemitsu Kosan Co. Ltd., TotalEnergies SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mixed Xylene Market Emerging Trajectories
Digital process control and emissions monitoring systems are penetrating mixed xylene production networks, compressing yield variability and enabling real-time specification compliance that manual sampling cannot match.
Advanced process control software is automating isomerization unit temperature and pressure optimization across catalytic reforming trains. Integrated refiners in the US Gulf Coast corridor deploy these systems to stabilize para-xylene precursor yields. The technology is automating yield variance reduction that previously required shift-based manual intervention, compressing off-spec volume penalties.
REACH registration requirements under ECHA jurisdiction are elevating compliance documentation burdens for import-dependent European processors. Coatings formulators face extended substance evaluation timelines that delay new product introductions. Small and mid-scale solvent distributors are consolidating to amortize registration costs, shifting procurement leverage toward larger registered importers.
Long-term offtake contracting is displacing spot market participation among derivative processors. Polyester manufacturers in South Korea's petrochemical corridor now lock multi-year supply agreements directly with refinery operators. This concentration is visible across East Asian chemical parks where pipeline-linked delivery infrastructure favors dedicated supply relationships over merchant market liquidity.
Mixed Xylene Market Segmentation
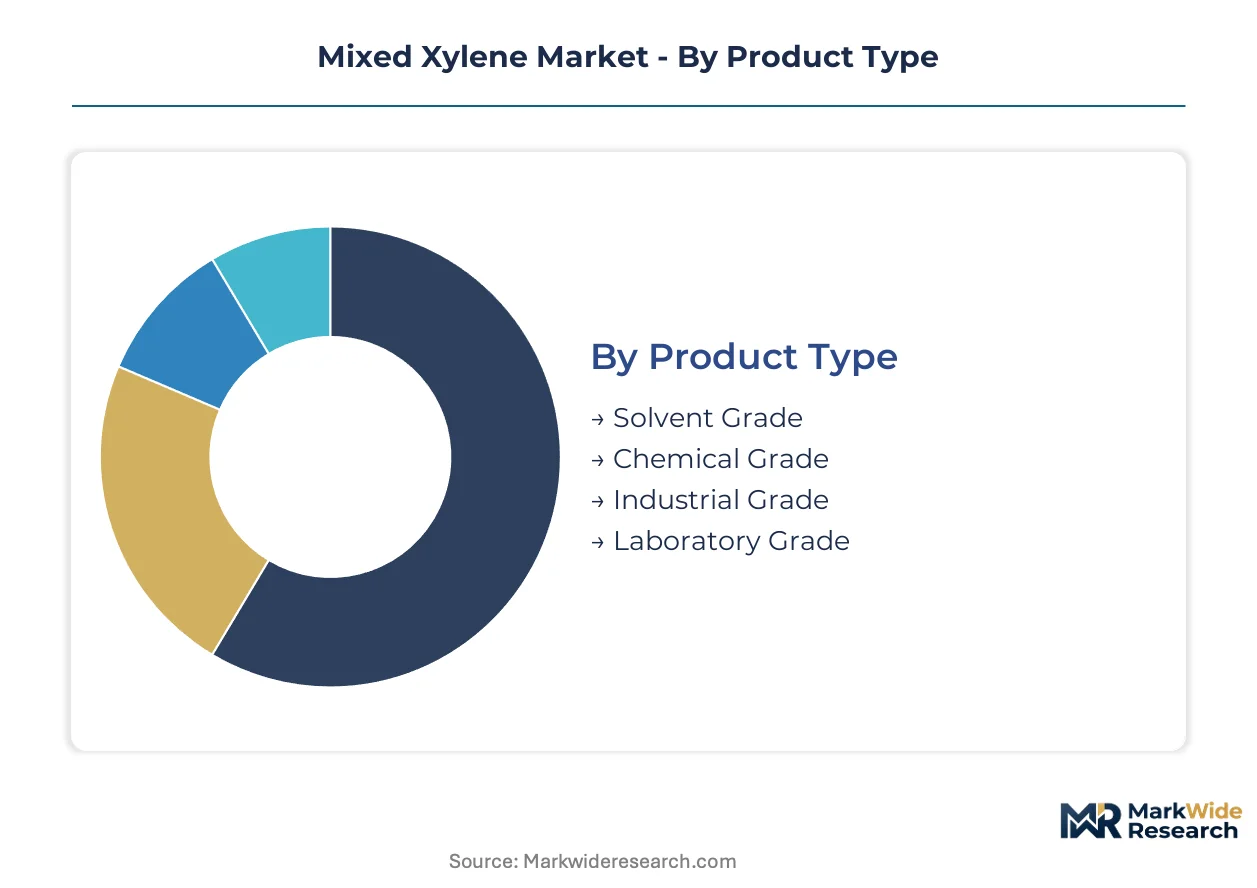
Mixed xylene segmentation reveals how value migrates between commodity solvent applications and high-purity chemical feedstock streams. Distinct product grades command margin spreads based on isomer separation depth and para-xylene extraction potential.
Product Type:
Chemical Grade material embeds directly into integrated petrochemical complexes for para-xylene extraction, while Solvent Grade circulates through fragmented coatings distributors. Industrial and Laboratory grades occupy narrower procurement channels with specialized specification requirements.
- Chemical Grade:Contains ethylbenzene, para-xylene, meta-xylene, and ortho-xylene isomers in precise ratios optimized for catalytic reforming downstream. Demand concentrates in South Korea's Ulsan-Yeosu petrochemical corridor, where Lotte Chemical and SK Group anchor purified terephthalic acid complexes that lock in multi-year offtake contracts.
- Solvent Grade:Serves as aromatic thinner in architectural and industrial coatings formulations, facing structural displacement as China's MEE tightens VOC emissions rules under its dual carbon framework. Waterborne coating substitution compresses pricing power in regulated markets, redirecting procurement toward lower-aromatic alternatives.
- Industrial Grade:Supports fuel additive blending and general-purpose cleaning applications across manufacturing sectors with moderate purity tolerances.
- Laboratory Grade:Meets stringent analytical specifications for research institutions and quality control laboratories requiring certified isomer distributions.
Volume placements concentrate in Chemical Grade; the faster expansion belongs to Laboratory Grade as analytical standards tighten across pharmaceutical supply chains.
End Use:
Coatings formulators drive spot procurement volatility, while pharmaceutical manufacturers impose rigid qualification timelines that favor dedicated supply relationships.
- Paints:Architectural and decorative coatings manufacturers represent the largest solvent-grade consumption pool, though waterborne formulation shifts are eroding traditional aromatic thinner demand in China's coastal provinces.
- Adhesives:Industrial bonding applications require controlled evaporation rates that mixed xylene blends deliver; specification requalification timelines under REACH constrain European formulator flexibility.
- Coatings:Protective and industrial finishes maintain steadier demand than architectural segments, with automotive OEM specifications driving purity requirements.
- Pharmaceuticals:Extraction and crystallization processes in active pharmaceutical ingredient manufacturing demand Laboratory Grade material with documented impurity profiles.
Adhesives procurement is concentrating within registered importer networks; Pharmaceuticals is climbing the fastest as serialization requirements expand solvent documentation burdens.
Delivery Mode:
Logistics configuration separates integrated chemical park access from fragmented distributor networks serving smaller formulation accounts.
- Bulk:Pipeline-linked coastal refineries in China dominate domestic distribution, locking processors into dedicated offtake rather than spot cargo access. Tanker delivery sustains high-volume para-xylene precursor flows to integrated petrochemical complexes.
- Drums:Smaller coatings formulators and maintenance shops rely on drum packaging that sustains distributor margins despite higher unit logistics costs.
- IBCs:Mid-scale adhesive and specialty coatings manufacturers favor intermediate bulk containers for operational flexibility.
- Containers:Export-oriented supply chains and remote manufacturing sites depend on ISO tank containers for multimodal flexibility.
Procurement leverage aggregates toward Bulk arrangements; Container logistics is gaining share fastest as India polyester capacity buildout diversifies supply orbits beyond East Asian pipeline networks.
Application:
Downstream process integration determines whether mixed xylene enters captive consumption or merchant market circulation.
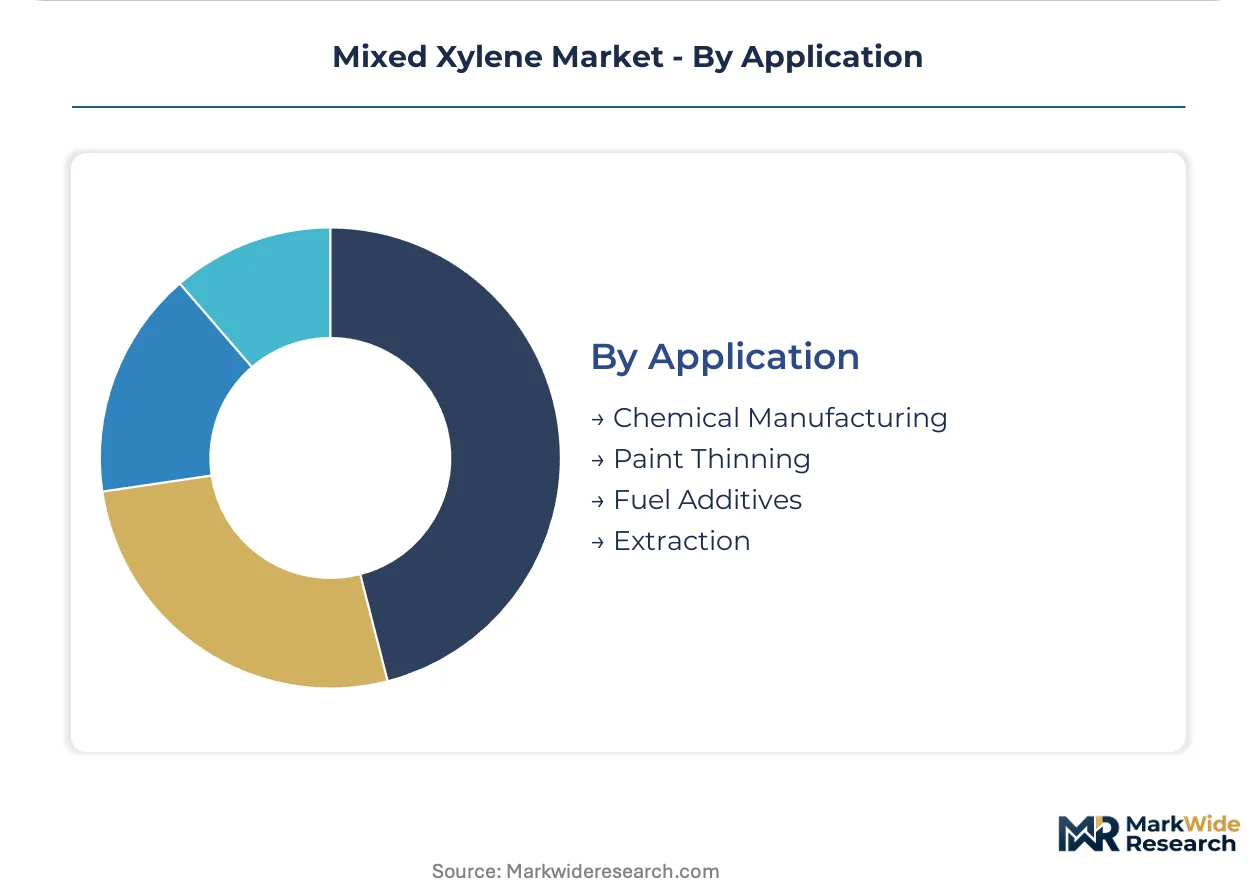
- Chemical Manufacturing:Para-xylene extraction for purified terephthalic acid production absorbs the dominant volume share, with isomerization unit upgrades across East Asian refineries redirecting solvent-grade supply toward chemical-grade recovery.
- Paint Thinning:Formulation demand faces regulatory pressure from EPA National Emission Standards for Hazardous Air Pollutants and China's MEE VOC controls, compressing growth trajectories in regulated jurisdictions.
- Fuel Additives:Octane enhancement and combustion modifier applications consume Industrial Grade material with less stringent isomer ratio specifications.
- Extraction:Pharmaceutical and agrochemical processing utilizes solvent properties for selective compound recovery, requiring documented purity certifications.
Supply commitments harden in Chemical Manufacturing; Extraction applications are expanding most quickly as biopharma capacity disperses beyond traditional manufacturing clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's coastal refineries generate surplus chemical-grade mixed xylene that outpaces domestic para-xylene extraction capacity, forcing net exports toward South Korea and India. The United States maintains balanced flows through integrated Gulf Coast complexes. Germany and Japan rely on import-dependent supply chains constrained by REACH and domestic environmental rules.
China
MEE's dual carbon framework tightens VOC emissions standards for solvent applications, redirecting formulation demand toward lower-aromatic alternatives. Coastal refineries in Shandong and Jiangsu provinces upgrade isomerization units to boost para-xylene yields. Pipeline-linked distribution from Dalian, Ningbo, and Shanghai locks processors into dedicated offtake contracts rather than spot market access.
United States
EPA National Emission Standards for Hazardous Air Pollutants mandate vapor recovery system upgrades at Gulf Coast refineries, elevating fixed costs for integrated producers. ExxonMobil Corporation leverages its Baytown and Baton Rouge refining-petrochemical complexes to secure captive mixed xylene feedstock. The Texas-Louisiana corridor concentrates derivative capacity for domestic para-xylene extraction.
South Korea
Lotte Chemical and SK Group anchor purified terephthalic acid complexes in the Ulsan-Yeosu petrochemical corridor, concentrating chemical-grade offtake within integrated chemical parks. National emissions trading schemes tighten refinery operating parameters. Multi-year supply agreements now dominate procurement, displacing spot market participation among polyester manufacturers.
Germany
REACH registration requirements under ECHA jurisdiction constrain non-EU suppliers seeking market access, elevating compliance costs for import-dependent processors. The Rotterdam-Antwerp aromatics hub channels supply into German chemical manufacturing. BASF's Ludwigshafen complex and downstream formulators face extended substance evaluation timelines that delay new product introductions.
India
Reliance Industries and Indian Oil Corporation expand purified terephthalic acid complexes in Gujarat and Maharashtra, creating new chemical-grade demand outside East Asian supply orbits. BIS certification requirements tighten product specifications for industrial applications. The Jamnagar and Vadodara refining corridors attract investment in isomerization capacity to capture growing domestic derivative demand.
Mixed Xylene Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the mixed xylene value chain, creating tiered supply relationships based on integration depth. The market structure concentrates around integrated refining-petrochemical complexes that control captive feedstock, while merchant market liquidity fragments among smaller distributors. Three archetypes dominate: global majors with Gulf Coast or East Asian refining assets, national oil companies with pipeline-linked domestic distribution, and regional specialists serving coatings formulators. Capacity expansion and long-term offtake contracting represent the dominant competitive moves, with players locking processors into dedicated supply relationships rather than spot procurement.
Within the integrated major tier, ExxonMobil Corporation and Shell plc exemplify archetypes of Gulf Coast and European hub concentration respectively. Lotte Chemical occupies a position representing East Asian petrochemical corridor clustering. These entities anchor supply security through backward integration into refining rather than merchant market participation. China Petrochemical Corporation sits within the national oil company archetype, leveraging pipeline-linked coastal refineries to dominate domestic distribution. Reliance Industries represents the emerging capacity buildout vector in India, diversifying supply orbits beyond traditional East Asian networks. The competitive dynamic favors entities with captive feedstock control over those dependent on spot cargo access.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Shell plc |
| Reliance Industries Ltd. |
| China Petrochemical Corporation |
| Chevron Phillips Chemical Company |
| Lotte Chemical |
| China National Petroleum Corporation |
| Idemitsu Kosan Co. Ltd. |
| TotalEnergies SE |
| Others |
Supply Flow & Price Mechanics
Naphtha price index movements cascade through catalytic reforming economics into tiered spreads between chemical-grade and solvent-grade mixed xylene. Pipeline-linked coastal refineries in China leverage captive feedstock control to compress delivered costs for integrated para-xylene extractors, while drum-packaged solvent shipments absorb distributor markups that widen procurement gaps for smaller coatings formulators.
Pricing Analysis
Margin tightening in solvent-grade tiers reflects waterborne coating substitution accelerating under China's MEE dual carbon enforcement. Contract-based long-term offtake dominates chemical-grade procurement, with price differentiation resting on isomer separation depth and para-xylene extraction yield. Volume scale and REACH registration status anchor premium-mid-economy pricing differentiation across European import channels. Coatings distributors exhibit highest price sensitivity as VOC regulations strand aromatic thinner inventory; integrated PTA manufacturers locked into pipeline delivery show lowest sensitivity due to captive supply security.
Supply Chain Analysis
China's domestic-content mandates through pipeline-linked coastal refinery networks are reshaping third-party processor access toward dedicated offtake relationships. Supply concentrates in China, South Korea, and the United States, with raw material dependencies drawing from naphtha feedstocks, catalytic reforming catalysts, and isomerization unit capacity. Single-source vulnerability intensifies where East Asian refinery upgrades redirect solvent-grade streams toward chemical-grade recovery. Distribution runs through bulk tanker networks to integrated chemical parks, supplemented by ISO tank containers serving India's emerging polyester corridor outside traditional pipeline orbits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from regulatory compliance cost escalation is forcing smaller solvent distributors and unregistered importers toward exit or acquisition. Long-term offtake contracting and REACH registration investments favor scaled players with backward integration into refining.
For Market Incumbents: Deploy isomerization unit upgrades to capture chemical-grade margin pools as polyester feedstock demand tightens regional C8 aromatic balances. Deepen backward integration into pipeline-linked coastal refinery networks to secure captive feedstock against spot market volatility. Lock multi-year supply agreements with South Korea's Ulsan-Yeosu petrochemical corridor processors before India's capacity buildout diversifies procurement alternatives. For New Entrants and Emerging Players: Capture REACH registration gaps in European coatings and adhesive formulator channels where compliance burdens constrain non-EU suppliers. Target India's Gujarat and Maharashtra PTA complex buildout as the most penetrable demand orbit outside East Asian supply networks. Pursue biomass-derived aromatic pathway partnerships with pyrolysis oil upgrading technology developers to differentiate circular feedstock positioning. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale registered importers in European solvent distribution facing amortization pressure from ECHA documentation burdens. Five-to-ten year viability hinges on securing pipeline-linked refinery offtake positions or isomerization expertise retention as petrochemical complexes automate. Watch for MEE specification requalification timelines as inflection indicators that strand inventory and force consolidation among unprepared formulators.| Strategic Initiative | Industry Significance |
|---|---|
| Isomerization Unit Upgrade | Boosts para-xylene yields from catalytic reforming trains at China's Shandong and Jiangsu refineries. |
| Long-term Supply Agreement | Locks Lotte Chemical and SK Group processors into dedicated chemical-grade offtake relationships. |
| REACH Registration Investment | Captures margin potential from coatings formulators facing extended ECHA substance evaluation timelines. |
| Backward Integration | Secures captive naphtha feedstock control across ExxonMobil's Baytown and Baton Rouge refining complexes. |
| Biomass-derived Aromatic Pathway | Offers circular feedstock alternatives through pyrolysis oil upgrading for specialty solvent applications. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs combining primary interviews with plant managers, procurement leads at downstream PTA manufacturers, distribution channel partners, and technical R&D directors with validation against ACC reports, SEC 10-K disclosures, and ECHA registration databases. Bottom-up volume modeling across grade tiers, end-use industries, packaging formats, and regional production hubs triangulated with top-down macroeconomic indicators.
Segmentation granularity modeled chemical-grade versus solvent-grade spreads, para-xylene extraction yields, and VOC regulatory compliance tiers across the projection horizon. CAGRs derived from historical naphtha-to-aromatic conversion economics, isomerization capacity expansion schedules, and polyester demand elasticity parameters. Forecast inputs incorporated refinery upgrade timelines, MEE enforcement intensity, and India's PTA complex commissioning patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to dual carbon policy acceleration, waterborne coating substitution velocity, and biomass aromatic technology cost curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Trifluoroethanol Market
Solvents
Methyl Acetate Market
Solvents
Industrial Solvents Market
Solvents
2-Phenylethanol Market
Solvents
Lithium-Ion Battery's Electrolyte Solvent Market
Solvents
Global Glycidol Market
Solvents
2-(4-Aminopentyl(Ethyl)Amino)Ethanol Market
Solvents
Fluid Neutralizing Market
Solvents
Glycerol Market
Solvents
Trichloroacetyl Chloride Market
Solvents
Global Tert-Butanol Market
Solvents
Sugar Dissolvers Market
Solvents
Potassium Formate Market
Solvents
1,2-Ethanedithiol Market
Solvents
Global Ink Solvents Market
Solvents
Mono Propylene Glycol Market