
 Para Nitrochlorobenzene Market | 2026-2036
Para Nitrochlorobenzene Market Size, Share, and Industry Trends Forecast 2026-2036
Para Nitrochlorobenzene Market Intelligence
Chinese bulk chemical producers is shifting capacity toward higher-purity para nitrochlorobenzene grades to serve export markets. Aarti Industries Limited leverages its integrated nitration infrastructure to sustain cost leadership across agrochemical intermediates. Jiangsu Yangnong Chemical Group Co., Ltd. anchors regional supply through captive chlorine and nitric acid sourcing. Seya Industries Ltd. competes on specification flexibility for European dye house customers.
Para nitrochlorobenzene is a nitro-aromatic compound produced via chlorination of nitrobenzene or nitration of chlorobenzene, typically yielding a product with melting point near 83°C and para-isomer purity exceeding 99% for pharmaceutical-grade applications. It functions primarily as a chemical intermediate for synthesizing p-phenylenediamine, p-aminophenol, and various azo dye precursors. The dyes application segment leads current volume absorption due to persistent textile chemical demand from South Asian fabric processors. Pharmaceutical-grade specifications command premium positioning as CDSCO and EMA tighten impurity profiling requirements for downstream active pharmaceutical ingredients. The agrochemicals channel shows structural momentum where para nitrochlorobenzene derivatives enter fungicide and herbicide synthesis pipelines.
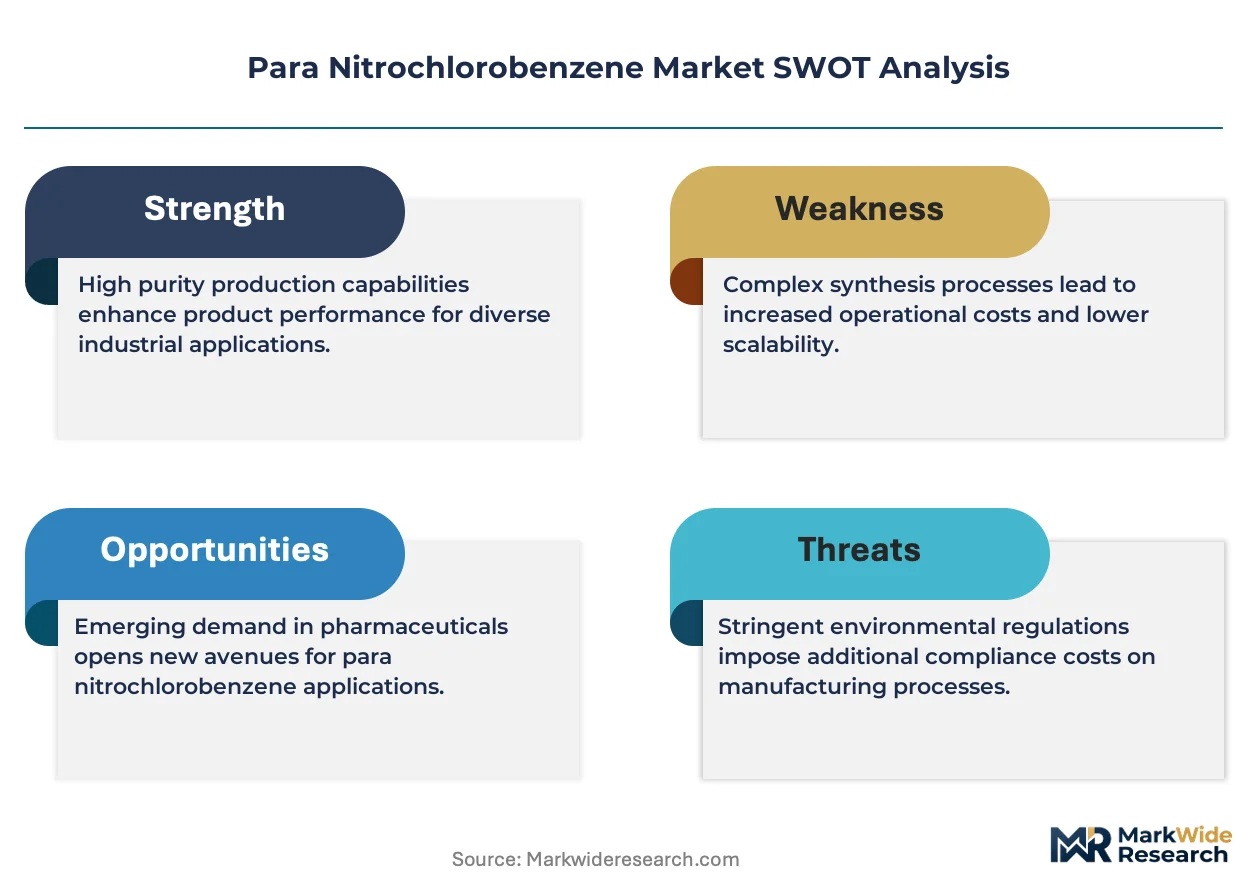
EPA oversight in the United States and REACH registration in Europe constrain market entry for non-compliant producers while elevating testing and documentation burdens. India's Central Pollution Control Board enforces effluent norms on nitration facilities operating near Gujarat and Maharashtra chemical belts. China's Ministry of Ecology and Environment monitors chlorinated aromatic emissions through updated GB standards enforcement. Stakeholders must weigh regulatory compliance investments against the margin compression risk from standardized bulk grades.
Market Dynamics
Chlorination-nitration capacity concentration in Jiangsu and Shandong provinces is tightening supply elasticity while REACH purity mandates force costly requalification cycles on marginal producers.
Growth Catalysts
- REACH registration upgrades:European dye houses now require para-isomer purity exceeding 99.5% for azo precursor synthesis, filtering out non-compliant suppliers and consolidating volume with certified nitration specialists.
- Agrochemical intermediate pipelines:Fungicide and herbicide synthesis routes are absorbing higher para nitrochlorobenzene volumes as crop protection formulators seek cost-efficient aromatic building blocks.
- Jiangsu chlorination clusters:Captive chlorine and nitric acid integration at Yangtze River Delta facilities is compressing delivered costs for export-grade material.
Market Restraints
- Chlorobenzene feedstock volatility:Benzene-chlorine cost spreads swing with crude-linked aromatics pricing, squeezing nitration margins during upstream spikes.
- MEE emission enforcement:China's Ministry of Ecology and Environment GB standard updates are forcing scrubber retrofits and wastewater treatment capex at legacy nitration plants.
- Meta-isomer substitution:Ortho nitrochlorobenzene derivatives occasionally substitute in lower-specification dye applications, capping premium pricing power for para grades.
Strategic Opportunities
- CDSCO pharmaceutical-grade certification:Indian API manufacturers are qualifying new para nitrochlorobenzene suppliers for p-aminophenol and p-phenylenediamine synthesis under tightening impurity profiling rules.
- Continuous nitration reactor adoption:Flow chemistry retrofitting at established facilities is cutting solvent waste and enabling smaller-batch pharmaceutical contract manufacturing.
- Direct mill supply contracts:South Asian textile chemical distributors are bypassing traditional trader networks to lock volume with Jiangsu producers.
Industry Challenges
- Process safety engineering scarcity:Experienced nitration hazard analysts command premium compensation as facilities expand capacity under stricter pressure-vessel codes.
- EMA impurity method validation:Six-to-nine-month certification timelines for new para nitrochlorobenzene lots are delaying API customer qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Para Nitrochlorobenzene Market |
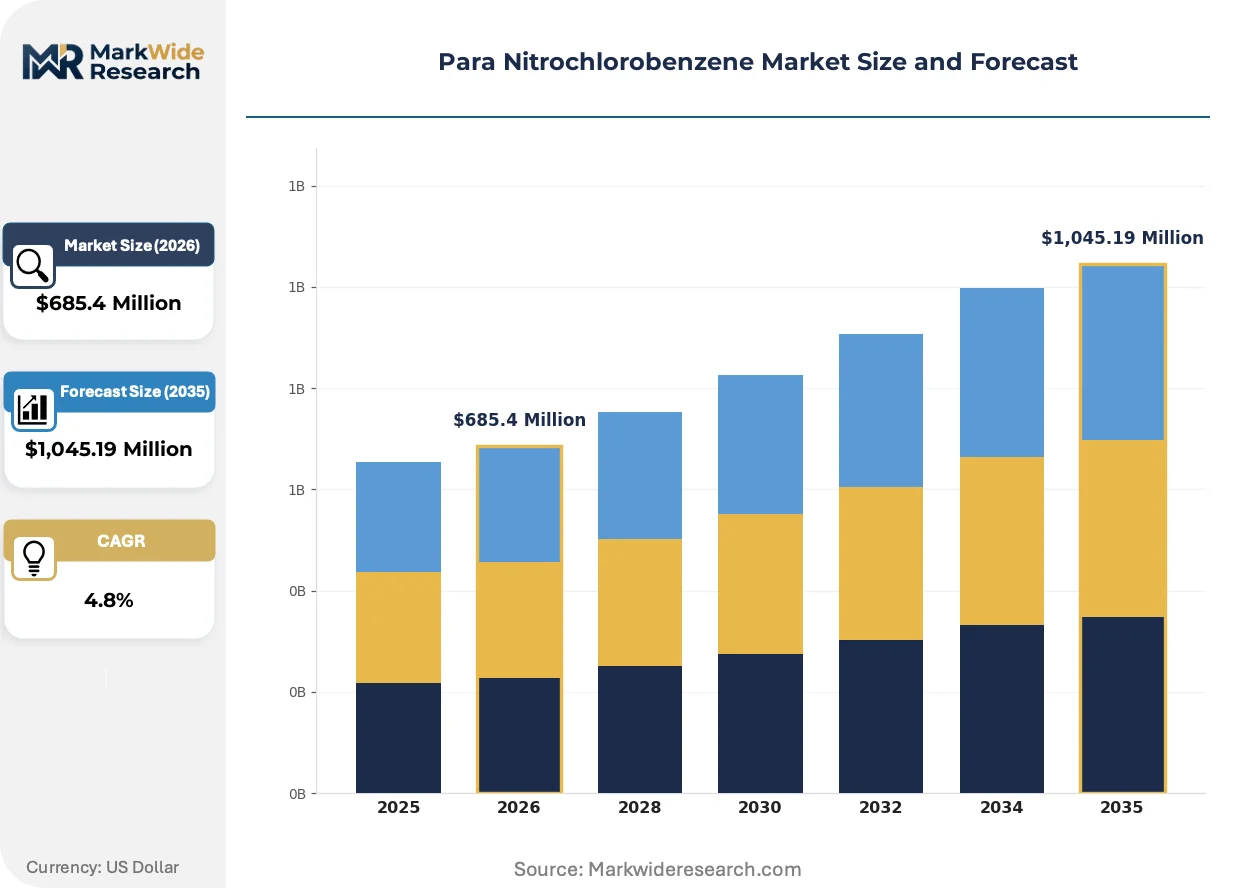
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brass, Copper, Silver, Aluminium Application: Photography, Pharmaceuticals, Dyes, Agrochemicals End User: Chemical Manufacturers, Textile Industry, Coating Companies, Electronic Manufacturers Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | Aarti Industries Limited, Hefei TNJ Chemical Industry Co., Ltd., Seya Industries Ltd., Panoli Intermediates India Private Limited, Anhui Bayi Chemical Industry Co., Ltd., Chemdyes Corporation, Sarna Chemicals, Jiangsu Yangnong Chemical Group Co., Ltd., Hemani Chemi Organic Private Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Para Nitrochlorobenzene Market Strategic Shifts & Innovations
Continuous processing technology and regulatory data integrity mandates are compressing batch cycle economics while redrawing supplier qualification barriers across dye and pharmaceutical channels.
Membrane-based para-meta separation systems are rewriting purification economics for nitration facilities. Dye intermediate producers in Gujarat and Maharashtra chemical belts are piloting these units to cut crystallization energy costs. The technology is enabling sub-99% crude grades to compete in standard pigment applications.
REACH Article 33 disclosure requirements now mandate full impurity profiling for para nitrochlorobenzene entering EU dye synthesis chains. ECHA enforcement is pushing documentation burdens onto Indian and Chinese export registrants. Pharmaceutical-grade suppliers are responding with dedicated analytical method packages.
Specification-driven procurement now dominates European dye house buying. Technical teams evaluate para-isomer purity, moisture content, and trace metal profiles before price negotiation. This behavior is most visible at Rotterdam and Hamburg port-of-entry inspections where rejected lots trigger supplier switch penalties.
Para Nitrochlorobenzene Market Segmentation
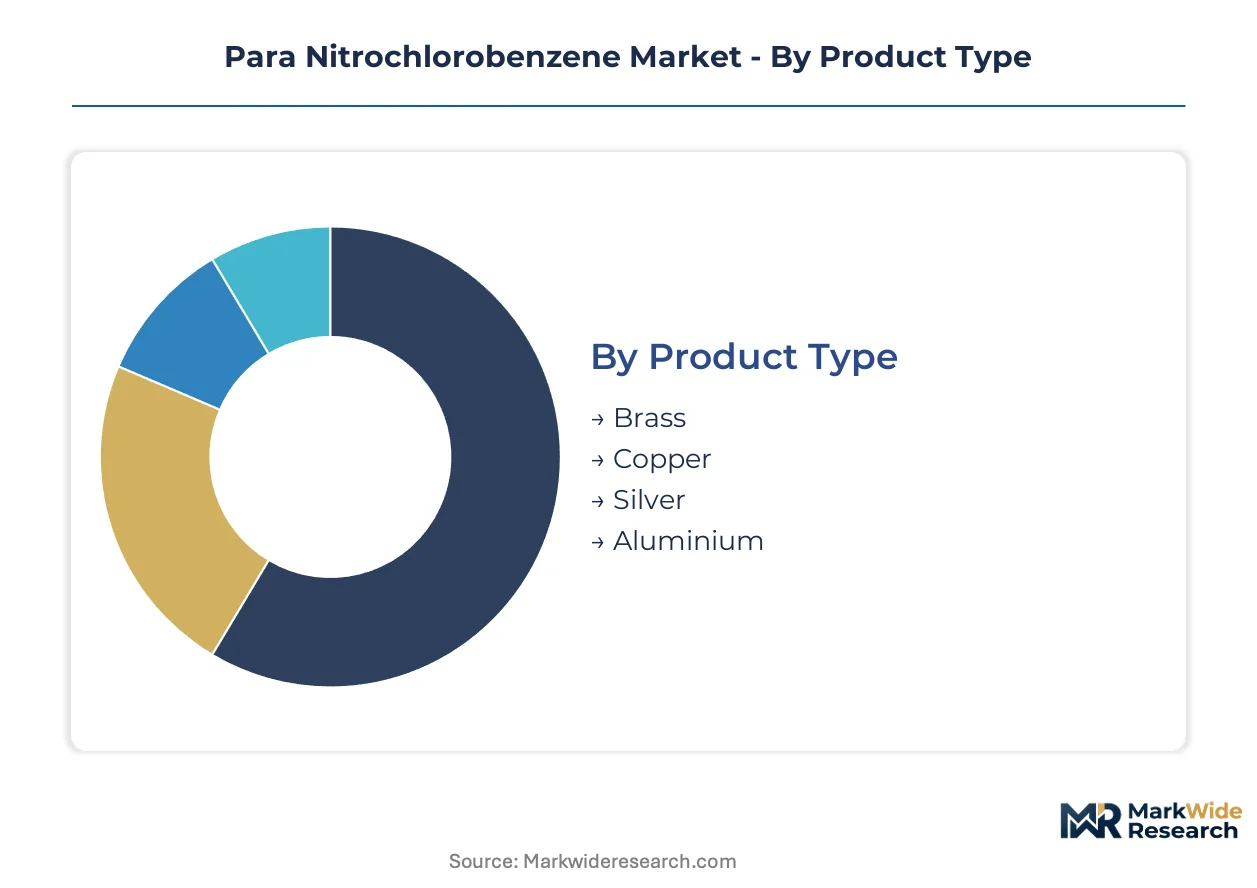
Para nitrochlorobenzene specifications vary sharply across downstream applications, with pharmaceutical and dye-grade purity thresholds forcing distinct production configurations. Buyers segment procurement by certification burden and end-use liability exposure rather than commodity pricing alone.
Product Type:
Grade selection tracks directly with the replacement cycle of downstream synthesis equipment, as higher-purity inputs reduce catalyst poisoning and extend reactor runs.
- Brass:Specialized catalyst carriers for continuous nitration reactors. Jiangsu chlorination clusters favor brass-grade specifications for captive chlorine loop integration.
- Copper:Standard industrial grade with 98-99% para-isomer content dominates bulk dye intermediate production. Gujarat chemical belt processors absorb volume for azo precursor synthesis.
- Silver:Ultra-high purity grade exceeding 99.8% para-isomer for pharmaceutical API precursors. CDSCO certification requirements in India concentrate demand among p-aminophenol manufacturers.
- Aluminium:Cost-optimized grade for pigment applications with relaxed trace metal tolerances. Maharashtra coating compounders favor this tier for price-sensitive batch operations.
Volume placements concentrate in Copper; the faster expansion belongs to Silver.
Application:
Application mix reflects margin tiering across chemical synthesis value chains, with regulatory intensity determining viable supplier pools.
- Photography:Declining traditional film chemical demand constrains this legacy channel. Remaining volume serves specialty holographic and archival applications.
- Pharmaceuticals:p-Aminophenol and p-phenylenediamine synthesis for analgesic and antihistamine APIs. EMA impurity method validation timelines stretch supplier qualification to nine months.
- Dyes:Azo dye precursor production absorbs the largest volume share. REACH Article 33 disclosure mandates now require full impurity profiling for EU-bound material.
- Agrochemicals:Fungicide and herbicide intermediate pipelines show structural momentum. Crop protection formulators seek cost-efficient aromatic building blocks for generic active ingredient synthesis.
Dyes commands current volume leadership; agrochemicals is climbing the fastest.
End User:
End-user concentration maps onto regional chemical manufacturing clusters and their respective regulatory exposure profiles.
- Chemical Manufacturers:Integrated nitration houses consuming para nitrochlorobenzene for multi-step intermediate synthesis. Aarti Industries Limited anchors Indian demand through backward integration into nitrobenzene.
- Textile Industry:South Asian fabric processors driving azo dye consumption. Direct mill supply contracts with Jiangsu producers are displacing traditional trader networks.
- Coating Companies:Pigment dispersion formulators with moderate purity requirements. Maharashtra and Gujarat industrial paint clusters source standard grades.
- Electronic Manufacturers:Niche demand for high-purity p-phenylenediamine in specialty polymer films. Specification stringency matches pharmaceutical-grade thresholds.
Chemical manufacturers hold dominant volume share; textile industry procurement is gaining share fastest.
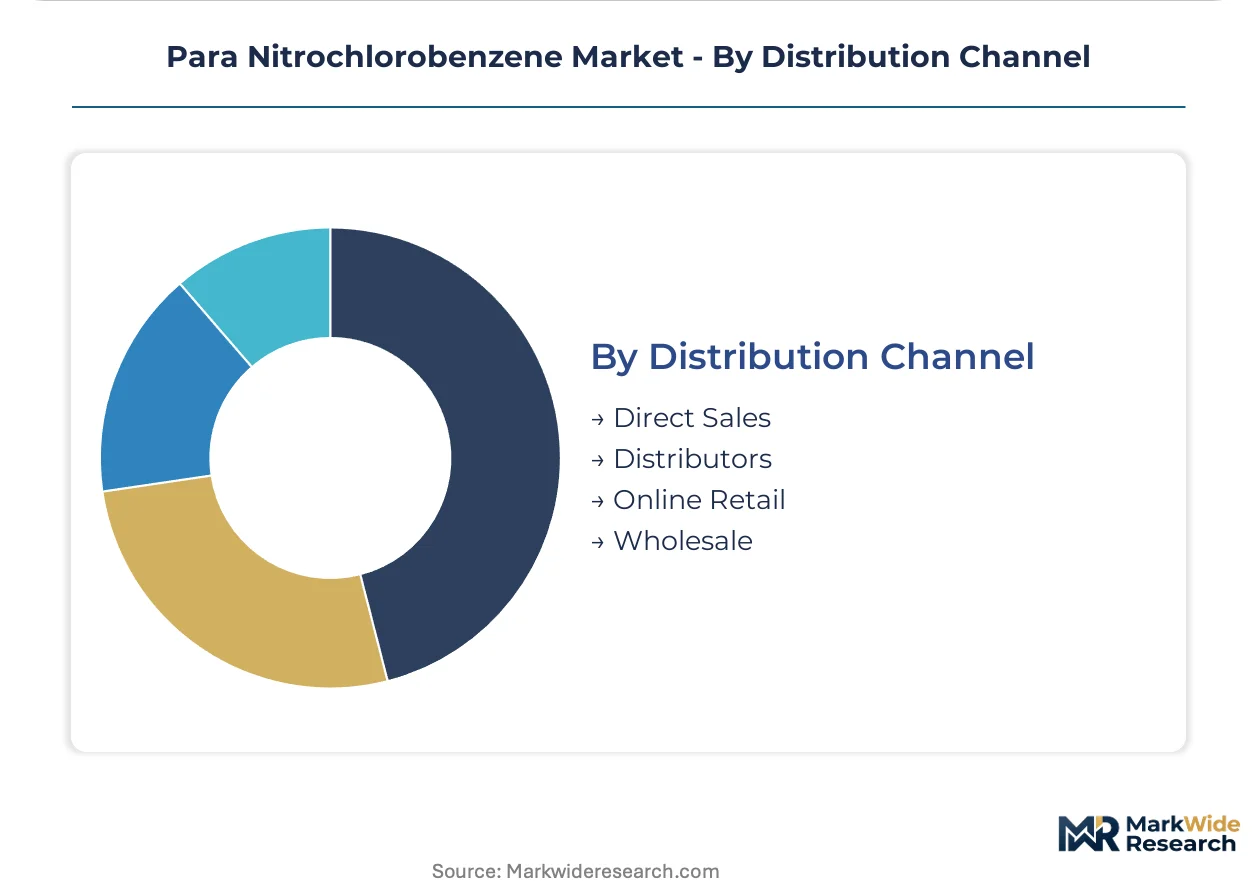
Distribution Channel:
Channel structure reflects buyer scale and the documentation burden of cross-border chemical trade.
- Direct Sales:Large-volume dye houses and API manufacturers contracting directly with Jiangsu and Shandong producers. REACH registration upgrades favor this channel for compliance traceability.
- Distributors:Regional chemical traders serving mid-tier coating and agrochemical compounders. Inventory holding costs pressure margins during benzene feedstock volatility.
- Online Retail:Limited to analytical-grade samples and small-batch procurement for research institutions. Documentation gaps restrict pharmaceutical-qualified transactions.
- Wholesale:Bulk consolidation points at Rotterdam and Hamburg for European dye synthesis chains. Port-of-entry inspections reject non-compliant lots, triggering supplier switch penalties.
Direct sales captures the largest volume flow; distributor channel expansion is steepest in emerging agrochemical markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chlorobenzene feedstock availability and nitration infrastructure density dictate regional production economics. Benzene refining corridors in East Asia, Western Europe, and the US Gulf Coast anchor manufacturing footprints. Regulatory stringency on chlorinated aromatic emissions now determines viable operating jurisdictions.
China
Jiangsu and Shandong provinces host concentrated chlorination-nitration capacity serving export-grade dye intermediates. MEE enforcement of updated GB standards is forcing scrubber retrofits at legacy Yangtze River Delta facilities. Captive chlorine and nitric acid integration at Yangnong Chemical Group compresses delivered costs for Rotterdam-bound material.
India
Gujarat and Maharashtra chemical belts absorb volume for azo precursor synthesis and agrochemical intermediates. CDSCO certification requirements for pharmaceutical-grade p-aminophenol manufacturers are extending supplier qualification timelines. Aarti Industries Limited leverages backward integration into nitrobenzene to sustain cost leadership across multi-step intermediate production.
Germany
REACH Article 33 disclosure mandates and ECHA enforcement are filtering non-compliant registrants from EU dye synthesis chains. Hamburg port-of-entry inspections now reject para nitrochlorobenzene lots lacking full impurity profiling documentation. Specialty chemical distributors in the Rhine-Ruhr region are consolidating procurement with certified nitration specialists.
United States
EPA oversight constrains market entry for non-compliant producers while elevating testing burdens on aromatic intermediate imports. Gulf Coast chlorobenzene availability supports limited domestic nitration capacity for agrochemical channel customers. Pharmaceutical-grade specifications command premium positioning as FDA-aligned impurity profiling tightens.
Japan
METI chemical safety standards and JIS purity specifications shape procurement criteria for electronic-grade p-phenylenediamine applications. Osaka-based specialty polymer film manufacturers match pharmaceutical-grade thresholds for trace metal tolerances. Domestic nitration capacity remains concentrated at Kansai-region integrated chemical complexes.
Para Nitrochlorobenzene Market Key Industry Players
Global majors compete with regional champions across certification-grade specialization and feedstock integration depth. The vendor base stratifies into three tiers: integrated nitration houses with captive chlorine sourcing, specification-flexible specialists serving European dye houses, and cost-optimized bulk producers for standard pigment applications. Dominant competitive moves include backward integration into nitrobenzene feedstock and continuous nitration reactor retrofitting for pharmaceutical contract manufacturing.
Among India-based integrated specialists, Aarti Industries Limited and Seya Industries Ltd. exemplify divergent archetypes—Aarti leverages in-house nitration infrastructure for agrochemical intermediate cost leadership, while Seya occupies a position emphasizing specification flexibility for European REACH-compliant dye house customers. Jiangsu Yangnong Chemical Group Co., Ltd. anchors the Chinese tier through Yangtze River Delta captive sourcing advantages.
| Leading Market Players |
|---|
| Aarti Industries Limited |
| Hefei TNJ Chemical Industry Co., Ltd. |
| Seya Industries Ltd. |
| Panoli Intermediates India Private Limited |
| Anhui Bayi Chemical Industry Co., Ltd. |
| Chemdyes Corporation |
| Sarna Chemicals |
| Jiangsu Yangnong Chemical Group Co., Ltd. |
| Hemani Chemi Organic Private Limited |
| Others |
Cost & Logistics Intelligence
Benzene-chlorine cost spreads transmit volatility from crude-linked aromatics into delivered para nitrochlorobenzene tiers, with Jiangsu producers compressing margins on standard Copper grades while Silver pharmaceutical specifications retain pricing power through CDSCO certification barriers.
Pricing Analysis
Certification-bundling separates quoted para nitrochlorobenzene tiers, with REACH-registered Silver grades commanding premium positioning against unbundled Copper material lacking ECHA documentation. Price differentiation rests on para-isomer purity thresholds and impurity profiling completeness, not volume scale alone. Pricing pressure intensifies in standard pigment applications where membrane-based para-meta separation enables sub-99% crude grades to compete. Agrochemical compounders show highest price sensitivity; pharmaceutical API manufacturers accept premium positioning for validated analytical method packages.
Supply Chain Analysis
Freight cost differentials from Yangtze River Delta ports to Rotterdam and Hamburg compress margins for non-integrated traders while favoring direct mill contracts. Supply concentrates in China, India, and Germany, with benzene feedstock and captive chlorine availability determining viable production economics. Raw material dependencies span nitrobenzene, chlorobenzene, and concentrated nitric acid. Single-source vulnerability runs through Jiangsu chlorination clusters exposed to MEE emission enforcement. Distribution runs through direct sales channels for large-volume dye houses and API manufacturers, with wholesale consolidation at European port-of-entry inspection points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained, with chlorination-nitration capacity concentration in Jiangsu and Shandong provinces propping pricing power for certified producers against marginal requalification failures.
For Market Incumbents: Extend REACH registration coverage to capture volume filtering from non-compliant competitors facing ECHA enforcement. Deepen captive chlorine and nitric acid integration to defend margin position against benzene feedstock volatility. Prioritize continuous nitration reactor retrofitting for pharmaceutical contract manufacturing qualification under tightening CDSCO impurity profiling timelines. For New Entrants and Emerging Players: Capture agrochemical intermediate demand in Gujarat and Maharashtra chemical belts where crop protection formulators seek cost-efficient aromatic building blocks. Penetrate the standard Aluminium grade segment for Maharashtra coating compounders with relaxed trace metal tolerances. Lead with specification flexibility and faster qualification timelines against incumbent certification backlogs. For Investors and Strategic Acquirers: EMA impurity method validation delays stretching to nine months is the leading indicator that pharmaceutical-grade capacity scarcity will persist. Position for five-to-ten year viability around integrated nitration houses with backward nitrobenzene control and existing CDSCO relationships. Watch Jiangsu MEE enforcement actions as the inflection signal for regional supply disruption and price tier widening.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nitrobenzene | Aarti Industries Limited anchors cost leadership through captive feedstock at Gujarat facilities. |
| Continuous Nitration Reactor Adoption | Flow chemistry retrofitting cuts solvent waste and enables pharmaceutical contract manufacturing qualification. |
| REACH Registration Upgrades | ECHA enforcement filters non-compliant suppliers and consolidates volume with certified nitration specialists. |
| Direct Mill Supply Contracts | South Asian textile chemical distributors bypass trader networks to lock volume with Jiangsu producers. |
| Membrane-Based Para-Meta Separation | Gujarat and Maharashtra pilot units cut crystallization energy costs for standard pigment applications. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this para nitrochlorobenzene market assessment. Primary interviews with plant managers at nitration facilities, procurement leads at downstream dye houses and API manufacturers, distribution channel partners, and technical R&D directors supplied operational validation. Secondary sources included CDSCO pharmaceutical-grade certification databases, ECHA REACH registration records, SEC 10-K filings from listed chemical producers, and ACC/Cefic industry reports. Bottom-up volume triangulation across grade tiers and applications reconciled with top-down value estimates from trade flow analysis.
Data-stream reconciliation combined production capacity surveys, import-export customs records, and end-use consumption patterns across the projection horizon. Segmentation dimensions modeled included grade tier (Brass, Copper, Silver, Aluminium), end-use industry (dyes, pharmaceuticals, agrochemicals, coatings), and regional production hub concentration. CAGRs were derived from fitted growth curves against historical volume trajectories and capacity expansion announcements. Industry-specific forecast inputs incorporated MEE enforcement timelines, REACH Article 33 disclosure implementation, and CDSCO impurity profiling rule evolution.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to benzene-chlorine cost spread volatility and regulatory enforcement intensity across China, India, and Europe. Forecasts reflect documented assumptions on capacity utilization rates, substitution elasticity for ortho nitrochlorobenzene derivatives, and qualification timeline durations. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
N-Methyl Pyrrolidone Market
Solvents
Ketene Market
Solvents
Nitroglycerin Market
Solvents
Potassium Formate Market
Solvents
United States Acetonitrile Market
Solvents
Alpha-Methylstyrene Market
Solvents
2-Phenylethanol Market
Solvents
3-Butylene Glycol Market
Solvents
Trichloroacetyl Chloride Market
Solvents
Ethane Market
Solvents
Dibutyl Ether Market
Solvents
Methyl Isopropyl Ketone Market
Solvents
Chlorobenzene Market
Solvents
Chloromethane Market
Solvents
Butyl Glycol Market
Solvents
Mono Propylene Glycol Market