
 Trichloroacetyl Chloride Market | 2026-2036
Trichloroacetyl Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Trichloroacetyl Chloride Market Analytics
Technical support and custom synthesis services are restructuring how trichloroacetyl chloride suppliers capture value beyond commodity transactions. Altivia leverages its North American chlorination infrastructure to sustain captive supply reliability for downstream agrochemical clients. CABB anchors European demand through specialized chloroacetyl chloride derivatives and tight logistics coordination with German pharmaceutical manufacturers. Daicel competes in Asia-Pacific through advanced process controls that reduce batch-to-batch variability for high-purity pharmaceutical applications.
Trichloroacetyl chloride (Cl3CCOCl) is a colorless to yellowish liquid with molecular weight 181.85 g/mol, synthesized via chlorination of acetyl chloride or oxidation of trichloroacetaldehyde, serving primarily as a potent acylating agent and intermediate in organic synthesis. Its reactivity with nucleophiles makes it indispensable for introducing trichloroacetyl groups into pharmaceutical and agrochemical active molecules. Industrial grade material dominates volume flows due to bulk agrochemical demand, while reagent grade commands premium positioning from pharmaceutical companies requiring sub-ppm impurity profiles for regulatory filings. Specialty grade segments show fastest expansion as custom synthesis houses adopt stringent specifications for complex molecule construction.
The EPA regulates trichloroacetyl chloride under TSCA Section 8, mandating reporting for significant new uses that affect exposure pathways in chemical manufacturing. REACH classification in Europe imposes strict hazard communication and safe-handling protocols, elevating compliance costs for importers and favoring regional producers with established stewardship programs. China's MEE enforces emission controls on chlorination processes that directly constrain capacity expansion timelines. Stakeholders must monitor evolving chemical inventory notifications across multiple jurisdictions to preempt supply disruptions and qualify alternative sourcing routes before regulatory thresholds tighten.
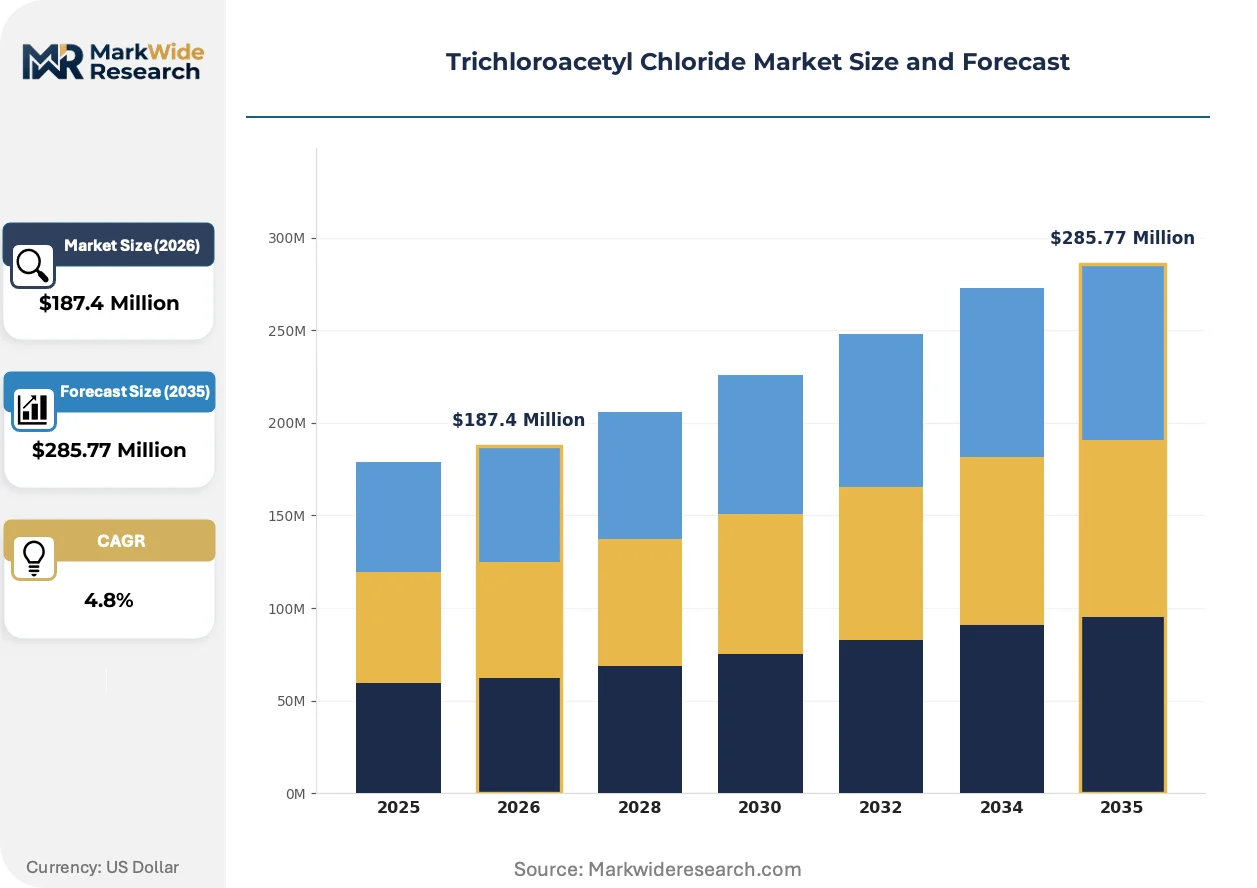
Market Dynamics
Pharmaceutical manufacturers are consolidating procurement around qualified suppliers capable of sub-ppm impurity documentation, compressing vendor pools and elevating technical service contracts over spot transactions.
Growth Catalysts
- REACH compliance mandates:European pharmaceutical manufacturers now require certified impurity profiles for regulatory filings, pulling demand toward qualified regional producers with established stewardship programs.
- Chlorination process intensification:Agrochemical active ingredient synthesis in India and China consumes industrial-grade material at expanding scale as crop protection manufacturers secure backward-integrated supply chains.
- Custom synthesis outsourcing:Contract research organizations in North America and Europe are procuring specialty-grade material for complex molecule construction, creating premium-tier demand separate from commodity flows.
Market Restraints
- Chlorine feedstock volatility:Electrochemical chlorine production costs fluctuate with regional electricity pricing, squeezing margin structures for non-integrated acylating agent manufacturers.
- Capacity concentration in East Asia:Chinese chlorination infrastructure dominates bulk supply, creating single-source vulnerability for European and North American formulators lacking alternative qualification pathways.
- Trifluoroacetic anhydride substitution:Select pharmaceutical applications are migrating to fluorinated acylating agents where milder reaction conditions reduce downstream purification burdens.
Strategic Opportunities
- Brazilian agrochemical formulation:ANVISA registration pathways for imported acylating agents remain underpenetrated relative to crop protection production growth in Mato Grosso and Paraná states.
- EPA TSCA Section 8 new-use reporting:Proactive engagement with pre-manufacture notification protocols enables first-mover positioning for novel pharmaceutical intermediates requiring trichloroacetyl group introduction.
- Digital batch documentation:Blockchain-anchored certificates of analysis are compressing qualification timelines for pharmaceutical procurement teams, rewarding suppliers with integrated quality data infrastructure.
Industry Challenges
- Chlorination process engineering expertise:Safe handling of phosgene-equivalent reactivity requires specialized operational training that aging workforce demographics in Western manufacturing bases struggle to replenish.
- Multi-jurisdiction inventory notification:Staggered chemical substance registry deadlines across China's MEE, South Korea's K-REACH, and Taiwan's TCSCA create compliance fragmentation for exporters serving Asian pharmaceutical clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trichloroacetyl Chloride Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Laboratory Grade, Reagent Grade, Specialty Grade Application: Synthesis Intermediates, Pharmaceuticals, Agrochemicals, Chemical Manufacturing End User: Chemical Industry, Pharmaceutical Companies, Research Institutions, Agriculture Distribution Channel: Direct Sales, Distributors, Online Sales, Wholesale |
| Companies Covered | Altivia, CABB, Daicel, Huaian Depon Chemical Co. Ltd., Ningxia Root Biotech Co. Ltd., Hari Orgochem Pvt. Ltd., SRF Ltd., Tokyo Chemical Industry, Shandong Xingda Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trichloroacetyl Chloride Market Evolving Landscape
Continuous flow chlorination systems and automated analytical verification are compressing batch-to-batch variability while regulatory data requirements harden across major pharmaceutical manufacturing jurisdictions.
Membrane cell chlorination technology is rewriting process economics for acylating agent production. Pharmaceutical-grade manufacturers in Germany and Switzerland are retrofitting continuous flow reactors to replace batch chlorination, cutting solvent waste generation by half. This capital-intensive transition is compressing the viable supplier base to entities with sustained engineering investment capacity.
REACH authorization candidate list expansion is tightening hazard communication obligations for chlorinated intermediates. ECHA's 2024 updates to classification and labeling requirements now mandate extended safety data sheet sections for downstream users in pharmaceutical synthesis. German and French formulators are accelerating supplier audits to preempt documentation gaps that could interrupt active ingredient filings.
Specification-driven procurement contracts are displacing commodity spot purchasing for high-purity grades. North American pharmaceutical procurement teams now embed certificate-of-analysis acceptance criteria directly into master service agreements, transferring analytical verification burden upstream. This behavioral shift concentrates volume with suppliers maintaining in-house GC-MS and titration capabilities rather than third-party testing arrangements.
Trichloroacetyl Chloride Market Segmentation
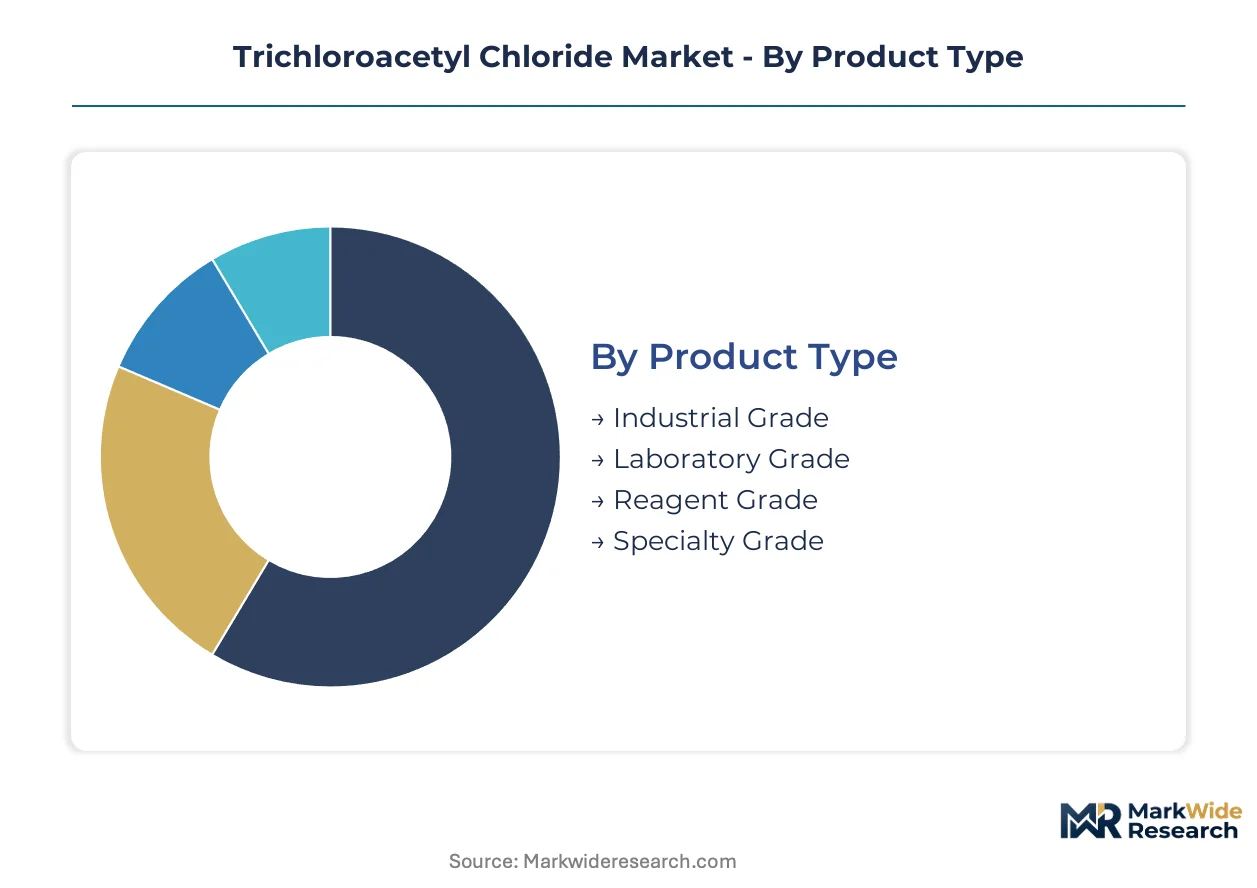
Segmentation in trichloroacetyl chloride procurement reflects divergent purity requirements and regulatory documentation burdens across pharmaceutical, agrochemical, and research end-uses. Suppliers configure production assets and certification protocols around these distinct demand profiles rather than treating the market as a homogeneous commodity.
Product Type:
Capital intensity varies sharply across grades, with pharmaceutical-specification production requiring continuous flow reactors and in-house analytical infrastructure that batch-oriented industrial producers cannot replicate without major retooling.
- Industrial Grade:Bulk material with ppm-level tolerances for chlorinated byproducts serves agrochemical active ingredient synthesis in China and India. Chlorination capacity expansions in Shandong Province and Gujarat feed this segment's volume leadership despite margin compression from electricity price volatility.
- Specialty Grade:Stringent batch-to-batch consistency protocols support complex molecule construction for contract research organizations. Custom synthesis houses in Switzerland and Massachusetts specify sub-ppm impurity profiles that command premium positioning separate from commodity flows.
- Laboratory Grade:Moderate-purity material for analytical and educational applications with standardized handling protocols.
- Reagent Grade:High-purity specification for pharmaceutical regulatory filings requiring extensive documentation packages.
Most installed capacity flows through Industrial Grade. Expansion is steepest in Specialty Grade.
Application:
Application segmentation tracks how acylating agent chemistry penetrates distinct value chains, with pharmaceutical intermediates demanding qualification-intensive supplier relationships that agrochemical bulk purchasing does not replicate.
- Pharmaceuticals:Trichloroacetyl group introduction into active pharmaceutical ingredients requires REACH-compliant documentation and sub-ppm impurity verification. German manufacturers consolidate procurement around qualified European suppliers with established stewardship programs to preempt ECHA authorization disruptions.
- Agrochemicals:Herbicide and fungicide intermediate synthesis consumes industrial-grade material at scale. Indian crop protection manufacturers in Hyderabad and Mumbai secure backward-integrated supply chains through dedicated chlorination partnerships.
- Synthesis Intermediates:General organic chemistry applications serving diversified chemical manufacturing.
- Chemical Manufacturing:Downstream chlorinated derivative production with variable purity requirements.
Agrochemicals anchor volume throughput. Pharmaceuticals command the highest unit economics.
End User:
End user structure concentrates procurement authority differently, with pharmaceutical companies embedding technical service requirements into master agreements that chemical traders cannot fulfill.
- Pharmaceutical Companies:FDA and EMA filing requirements drive specification-driven contracting with certificate-of-analysis acceptance criteria. North American procurement teams now mandate blockchain-anchored documentation to compress qualification timelines.
- Chemical Industry:Diversified manufacturers purchasing across multiple grades for derivative production and captive consumption.
- Research Institutions:Fragmented demand from universities and national laboratories with modest volume but high service expectations.
- Agriculture:Formulators and cooperatives procuring through distributor networks rather than direct supplier relationships.
Chemical Industry accounts for the broadest grade range. Pharmaceutical Companies are consolidating vendor pools fastest.
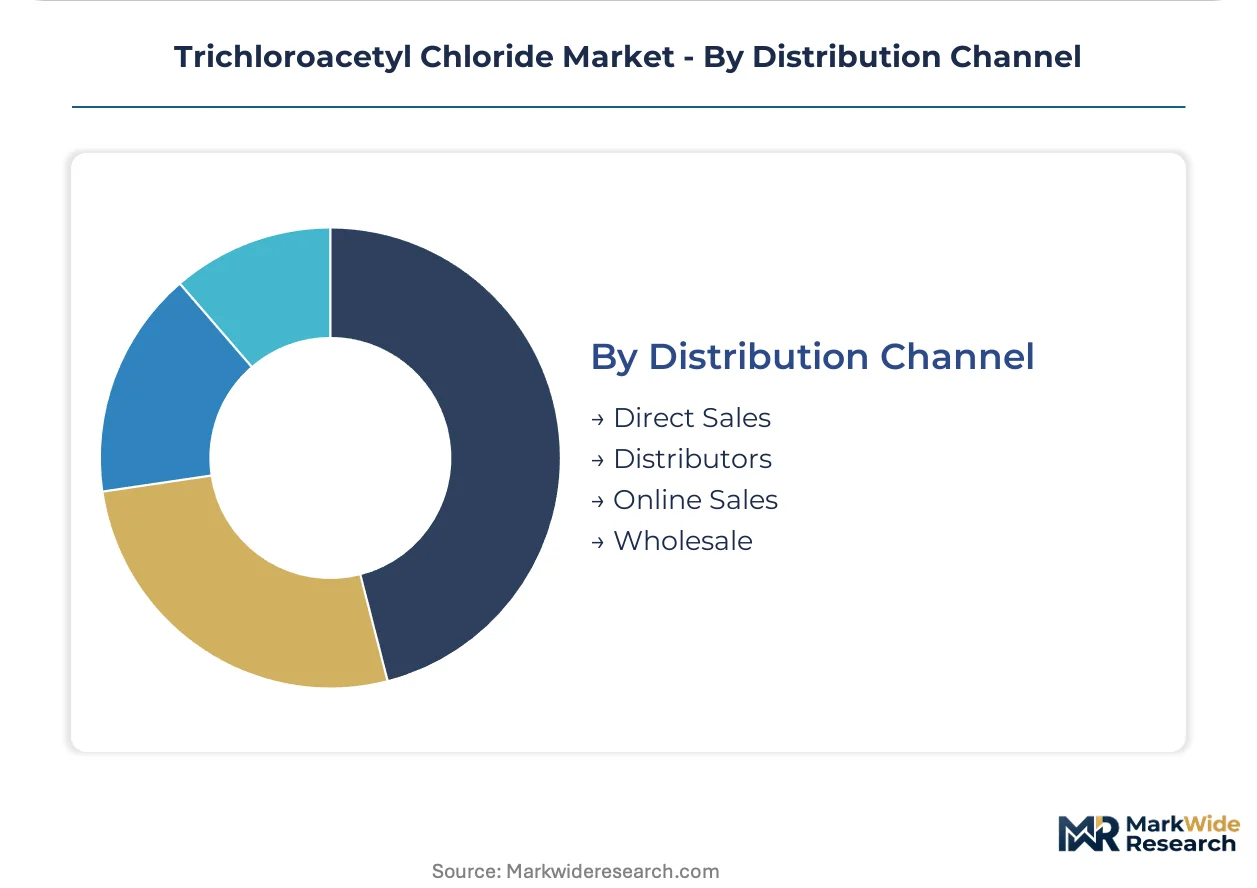
Distribution Channel:
Channel selection reflects customer scale and documentation burden, with direct relationships dominating where regulatory filing support is mandatory.
- Direct Sales:Pharmaceutical and large agrochemical manufacturers negotiate multi-year supply agreements with embedded technical service provisions. Swiss and German producers leverage direct channels to deliver batch-specific regulatory documentation.
- Distributors:Regional chemical traders serve mid-tier manufacturers lacking qualification resources for supplier audits. Indian and Brazilian formulators rely on distributor networks for import logistics and local inventory.
- Online Sales:Digital procurement platforms capture research-scale and spot purchasing with standardized specifications.
- Wholesale:Volume aggregation for industrial-grade material serving commodity-oriented chemical manufacturing.
Direct Sales carries the highest service overhead. Distributors retain relevance in regulatory-complex import markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands bulk industrial-grade production while Germany anchors pharmaceutical-specification supply, creating a bifurcated geography where purity requirements dictate sourcing patterns.
China
Shandong Province hosts the dominant chlorination capacity for agrochemical intermediates, with MEE emission controls constraining expansion timelines. Chinese manufacturers supply industrial-grade material to Indian crop protection formulators through dedicated export channels. The Yangtze River Delta concentration reflects backward-integrated supply chains serving domestic herbicide production.
Germany
Baden-Württemberg and North Rhine-Westphalia pharmaceutical clusters drive demand for REACH-compliant documentation and sub-ppm impurity verification. ECHA classification updates mandate extended safety data sheet sections, accelerating supplier audit cycles. German formulators consolidate procurement around regional producers with established stewardship programs to preempt authorization disruptions.
India
Hyderabad and Mumbai crop protection manufacturers secure captive chlorination partnerships for herbicide active ingredient synthesis. CDSCO filing requirements for pharmaceutical applications remain less stringent than European benchmarks, creating a two-tier qualification environment. Gujarat's chemical corridor expands industrial-grade consumption as domestic agrochemical formulation scales.
United States
Gulf Coast chlor-alkali integration supports acylating agent production for domestic agrochemical formulators. EPA TSCA Section 8 new-use reporting shapes procurement strategies for novel pharmaceutical intermediates requiring trichloroacetyl group introduction. Texas and Louisiana infrastructure faces margin pressure from regional electricity pricing volatility.
Switzerland
Basel pharmaceutical manufacturing clusters demand specialty-grade material with blockchain-anchored batch documentation. Swissmedic regulatory alignment with EMA standards elevates technical service requirements beyond commodity transactions. Continuous flow reactor investments in Swiss facilities compress batch-to-batch variability for complex molecule construction.
Trichloroacetyl Chloride Market Competitive Landscape
Top-tier vendors anchor pharmaceutical-grade supply with integrated analytical infrastructure, while regional chlorination specialists dominate industrial-grade flows. The vendor base stratifies around documentation capability rather than scale alone. Three archetypes prevail: integrated chlor-alkali producers with captive acylating agent output, custom synthesis houses with regulatory filing support, and commodity traders serving spot procurement. Capacity expansion and qualification-intensive technical service contracts represent the dominant competitive moves.
Among North American integrated producers, Altivia exemplifies the chlor-alkai-backed archetype with Gulf Coast infrastructure. European specialists in regulatory-intensive supply include CABB, representing the documentation-forward tier serving German pharmaceutical clusters. Daicel anchors Asia-Pacific positioning through process control investments that reduce variability for high-purity applications.
| Leading Market Players |
|---|
| Altivia |
| CABB |
| Daicel |
| Huaian Depon Chemical Co. Ltd. |
| Ningxia Root Biotech Co. Ltd. |
| Hari Orgochem Pvt. Ltd. |
| SRF Ltd. |
| Tokyo Chemical Industry |
| Shandong Xingda Chemical |
| Others |
Value Network & Pricing Analysis
Family-owned chlorination specialists in Shandong Province and Gujarat anchor industrial-grade supply, transmitting feedstock volatility directly into spot pricing while European pharmaceutical producers maintain contract premiums through captive documentation infrastructure.
Pricing Analysis
Capacity additions in Shandong Province are reshaping price floors for industrial-grade material as chlorine electrochemistry costs fluctuate with regional electricity tariffs. Three-tier pricing structure across pharmaceutical, specialty, and industrial grades reflects certification burden and analytical infrastructure investment. Cost compression in the industrial tier is intensifying because Chinese MEE emission controls constrain expansion timelines. Agrochemical formulators in India exhibit highest price sensitivity, while Swiss pharmaceutical procurement teams accept premium positioning for blockchain-anchored batch documentation.
Supply Chain Analysis
Specialized chlorination process engineering expertise shortages in Western manufacturing bases are constraining capacity expansion timelines for pharmaceutical-grade production. Bulk supply concentrates in China, India, and Germany, with Shandong chlor-alkali integration feeding agrochemical demand and Baden-Württemberg facilities serving EMA-aligned documentation requirements. Raw material flows draw from electrochemical chlorine, acetyl chloride feedstocks, and phosgene-equivalent reagent handling systems. Single-source vulnerability runs through Chinese industrial-grade dominance for European and North American formulators lacking alternative qualification pathways. Distribution runs through direct sales channels for pharmaceutical documentation requirements and regional distributors for agrochemical spot procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where sub-ppm impurity verification and REACH-compliant stewardship programs are displacing commodity spot transactions among pharmaceutical procurement teams.
For Market Incumbents: Lock in multi-year technical service contracts with embedded certificate-of-analysis acceptance criteria to preempt substitution by fluorinated acylating agents. Deepen backward integration into membrane cell chlorination technology to cut solvent waste generation and defend margin position against electricity price volatility in Gulf Coast production clusters. For New Entrants and Emerging Players: Capture Brazilian agrochemical formulation demand through ANVISA registration pathways for imported acylating agents serving Mato Grosso crop protection production. Target specialty-grade supply to North American contract research organizations with digital batch documentation capabilities that compress pharmaceutical qualification timelines. For Investors and Strategic Acquirers: Valuations sit cheapest among regional chlorination specialists with pharmaceutical-grade qualification infrastructure but limited downstream customer integration. Five-to-ten year viability hinges on continuous flow reactor adoption and ECHA authorization list navigation capabilities. Watch for EPA TSCA Section 8 new-use reporting activity as inflection indicator for novel pharmaceutical intermediate demand.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Reactor Retrofit | German and Swiss manufacturers cut solvent waste generation by half through membrane cell technology adoption. |
| Blockchain-Anchored Documentation | North American pharmaceutical procurement teams compress qualification timelines with integrated quality data infrastructure. |
| Backward Integration Partnership | Indian crop protection manufacturers in Hyderabad secure captive chlorination supply for herbicide active ingredient synthesis. |
| REACH Stewardship Program Investment | European producers preempt ECHA authorization disruptions through extended safety data sheet compliance. |
| Specialty Grade Capacity Expansion | Custom synthesis houses in Massachusetts and Switzerland command premium positioning for complex molecule construction. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at chlor-alkali facilities, procurement leads at downstream agrochemical and pharmaceutical formulators, distribution channel partners, and technical R&D directors in continuous flow process engineering with secondary validation against customs and trade data, Cefic sector reports, SEC 10-K filings from listed chemical producers, and ECHA classification updates. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic drivers.
Segment-weighting approaches applied grade tier, end-use industry, and regional production hub dimensions across the analysis window. CAGRs derived from volume trajectory modeling incorporating chlorine feedstock cost structures, regulatory compliance burden indices, and pharmaceutical filing activity patterns. Industry-specific inputs included MEE emission control implementation timelines and EMA-aligned documentation requirement diffusion rates.
Chlorine electrochemistry cost shocks, unanticipated ECHA authorization list expansions, and accelerated fluorinated acylating agent substitution are the dominant revision risks to modeled trajectories. Forecasts reflect documented assumptions about process technology adoption curves and regulatory enforcement intensity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Methyl Undecylenate Market
Solvents
Toluene Market
Solvents
Diethanolamide Market
Solvents
Diethylene Glycol Monobutyl Ether Market
Solvents
C2 Chlorinated Solvents Market
Solvents
Sugar Dissolvers Market
Solvents
Meta-Xylene Market
Solvents
Hydrophobic Solvents Market
Solvents
Ultra-Low-VOC Methacrylate Reactive Diluents Market
Solvents
Benzylamine Market
Solvents
3-Butylene Glycol Market
Solvents
Global Nitrochlorobenzene Market
Solvents
6-Xylenol Market
Solvents
Global Tert-Butanol Market
Solvents
Global Solvent Evaporation Market
Solvents
Methyl Formate Market