
 Aliphatic Hydrocarbon Market | 2026-2036
Aliphatic Hydrocarbon Market Size, Share, and Industry Trends Forecast 2026-2036
Aliphatic Hydrocarbon Market Analysis
The price-performance gap between high-purity aliphatic grades and commodity technical solvents is hardening as pharmaceutical extractors reject batch inconsistency. Chevron Phillips Chemical leverages integrated Gulf Coast feedstock access to sustain cost leadership in North American hexane supply. ExxonMobil Corporation anchors its position through catalytic reformer optimization, while Sasol competes via Fischer-Tropsch-derived specialty cuts with narrow boiling ranges.
Aliphatic hydrocarbons are saturated acyclic compounds composed solely of carbon and hydrogen, typically featuring carbon chains from C6 to C10 with boiling points between 69°C and 174°C; manufacturers refine these through crude oil fractionation or synthetic gas-to-liquid routes to serve as non-polar solvents, diluents, and chemical precursors. Hexane dominates volume consumption due to its centrality in vegetable oil extraction and polymerization processes, though high-purity grades command disproportionate margin pools from pharmaceutical and electronics cleaning applications. Technical-grade heptane and octane sustain steady demand from automotive fuel additive blenders seeking controlled volatility profiles.
EPA emissions standards and OSHA permissible exposure limits constrain volatile organic compound release in US solvent operations, while REACH registration dossiers in Europe mandate full toxicological profiling for C6-C10 imports. India's BIS certification requirements for technical solvents are tightening testing protocols for agricultural chemical diluents. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether regional formulation tailoring or unified global product platforms offer superior compliance economics.
Market Dynamics
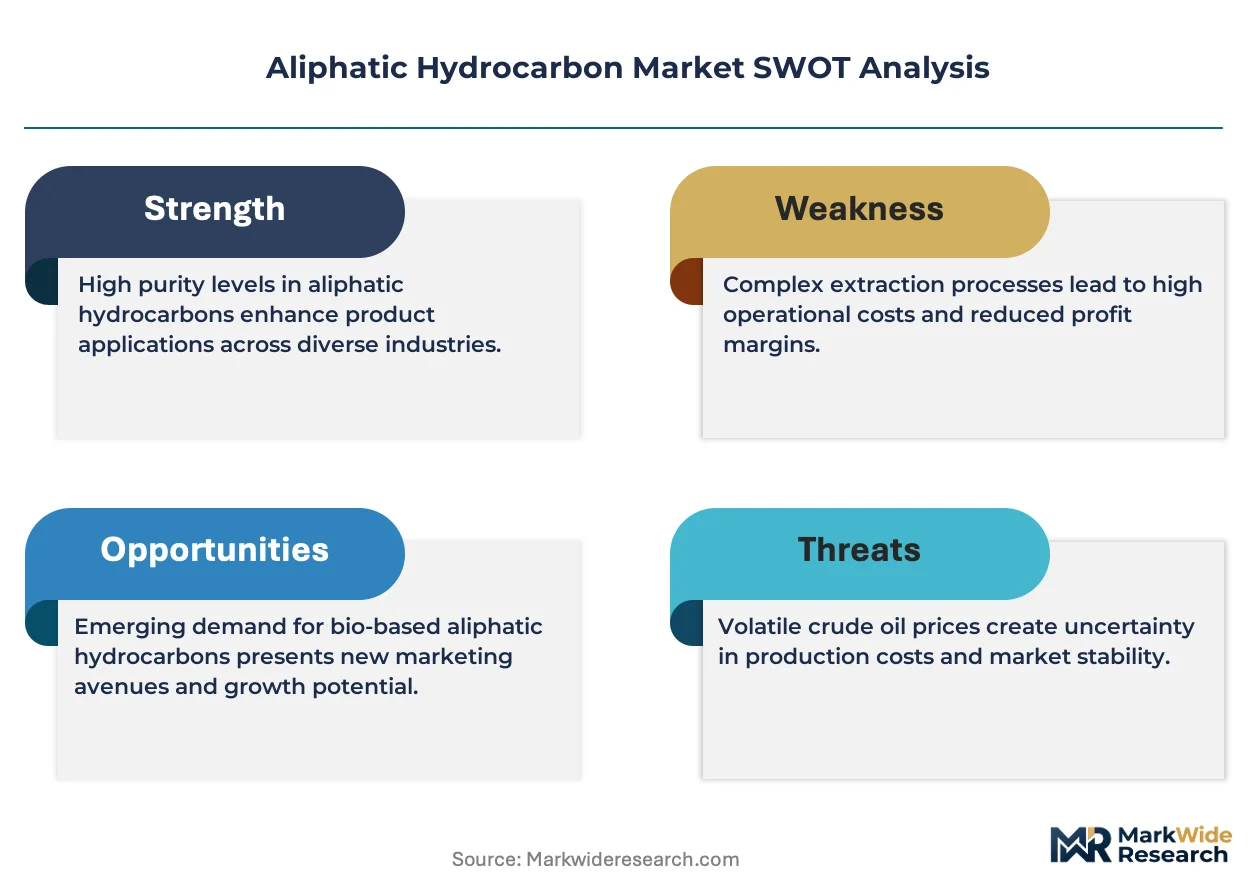
Pharmaceutical extractors are rejecting batch inconsistency in solvent supply, hardening the price-performance gap between high-purity aliphatic grades and commodity technical solvents. This quality bifurcation is restructuring procurement relationships and margin distribution across the value chain.
Growth Catalysts
- REACH and EU Green Deal compliance:Tightening purity specifications for hexane and heptane grades in Europe are forcing technical-grade producers to upgrade refining capabilities, creating premium tier demand.
- Vegetable oil extraction:Food processors in India and Brazil require consistent C6 solvent supply for edible oil production, sustaining volume consumption despite regional price volatility.
- Catalytic reformer optimization:Refiners deploying advanced catalytic technologies achieve narrower boiling range cuts, meeting pharmaceutical-grade specifications without dedicated synthetic routes.
Market Restraints
- Crude oil feedstock volatility:Naphtha and natural gas liquid prices fluctuate with energy markets, compressing margin predictability for fractionation-based producers.
- Gulf Coast supply concentration:Integrated petrochemical complexes along the Texas-Louisiana corridor control disproportionate North American hexane capacity, creating geographic vulnerability to hurricane disruptions.
- Supercritical CO2 substitution:Extraction operators in flavor and fragrance applications are piloting carbon dioxide systems to eliminate solvent residue concerns entirely.
Strategic Opportunities
- India technical-grade expansion:Reliance Industries and domestic agrochemical formulators are scaling consumption for crop protection synthesis, creating volume growth outside traditional pharmaceutical channels.
- Electronics cleaning applications:Semiconductor fabricators require ultra-high-purity C7-C9 cuts for wafer cleaning, commanding margins substantially above industrial solvent benchmarks.
- Fischer-Tropsch synthetic routes:Gas-to-liquid production yields specialty cuts with exceptionally narrow boiling ranges, opening pharmaceutical and electronics segments unreachable by crude-derived products.
Industry Challenges
- REACH dossier completion:European chemical registrants face extended toxicological profiling timelines for C6-C10 imports, delaying market access for non-EU suppliers.
- Fractionation asset specificity:Dedicated aliphatic separation units require substantial capital commitment with limited product slate flexibility, constraining producer response to demand mix shifts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aliphatic Hydrocarbon Market |
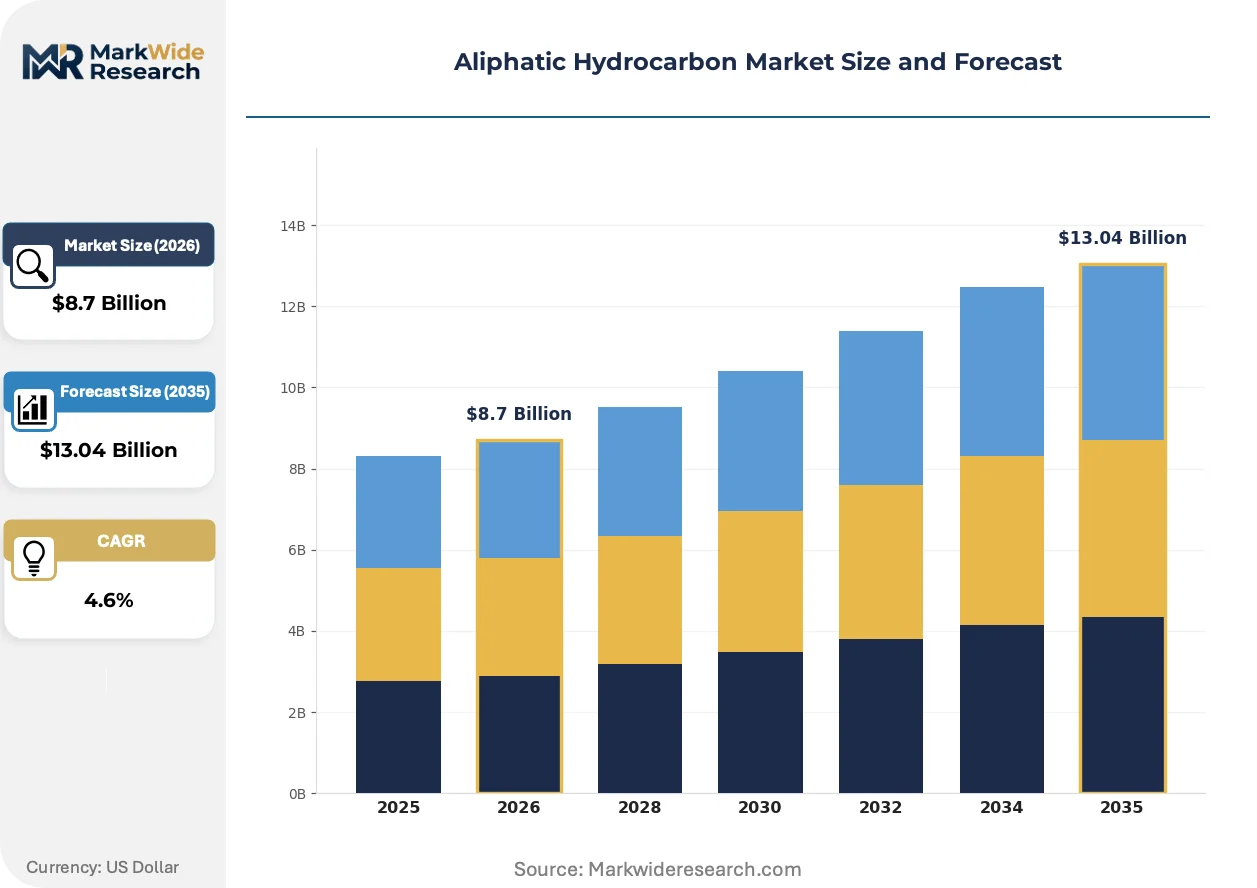
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hexane, Heptane, Octane, Decane Grade: Technical, Pure, High-Purity, Low-Purity Application: Solvents, Fuel Additives, Chemical Intermediates, Industrial Cleaning End User: Petrochemicals, Automotive, Pharmaceuticals, Agriculture |
| Companies Covered | Chevron Phillips Chemical, LyondellBasell Industries N.V., ExxonMobil Corporation, Mitsubishi Chemical Corporation, Reliance Industries Limited, Shell Global, TotalEnergies, Sasol, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aliphatic Hydrocarbon Market Emerging Trajectories
Synthetic production routes and regulatory compliance technologies are displacing conventional refining approaches in premium solvent segments. Quality certification and supply chain traceability are becoming primary competitive differentiators.
Membrane separation technology is expanding into aliphatic hydrocarbon purification, enabling producers to achieve pharmaceutical-grade specifications without energy-intensive multiple distillation passes. Specialty chemical divisions at major refiners are adopting these systems to serve electronics cleaning and active pharmaceutical ingredient extraction contracts. The technology is expanding into mid-tier solvent production previously served by commodity fractionation, compressing the addressable market for conventional technical-grade supply.
EPA emissions standards and OSHA permissible exposure limits are constraining volatile organic compound release in US solvent operations, forcing terminal operators and downstream blenders to invest in vapor recovery and closed-loop handling systems. Metalworking and coatings formulators face reformulation pressure as exposure thresholds tighten. California's South Coast Air Quality Management District has advanced the most stringent implementation timeline, creating regulatory divergence that complicates unified product platform strategies.
Consolidated procurement by multinational pharmaceutical extractors is displacing fragmented spot-market purchasing, with buyers demanding certificate-of-analysis documentation for every batch and direct supplier auditing rights. This behavioral shift concentrates volume with integrated producers capable of sustaining quality management systems. The transformation is most visible in European and North American vegetable oil and active ingredient extraction, where food safety and drug master file requirements override price sensitivity in supplier selection.
Aliphatic Hydrocarbon Market Segmentation
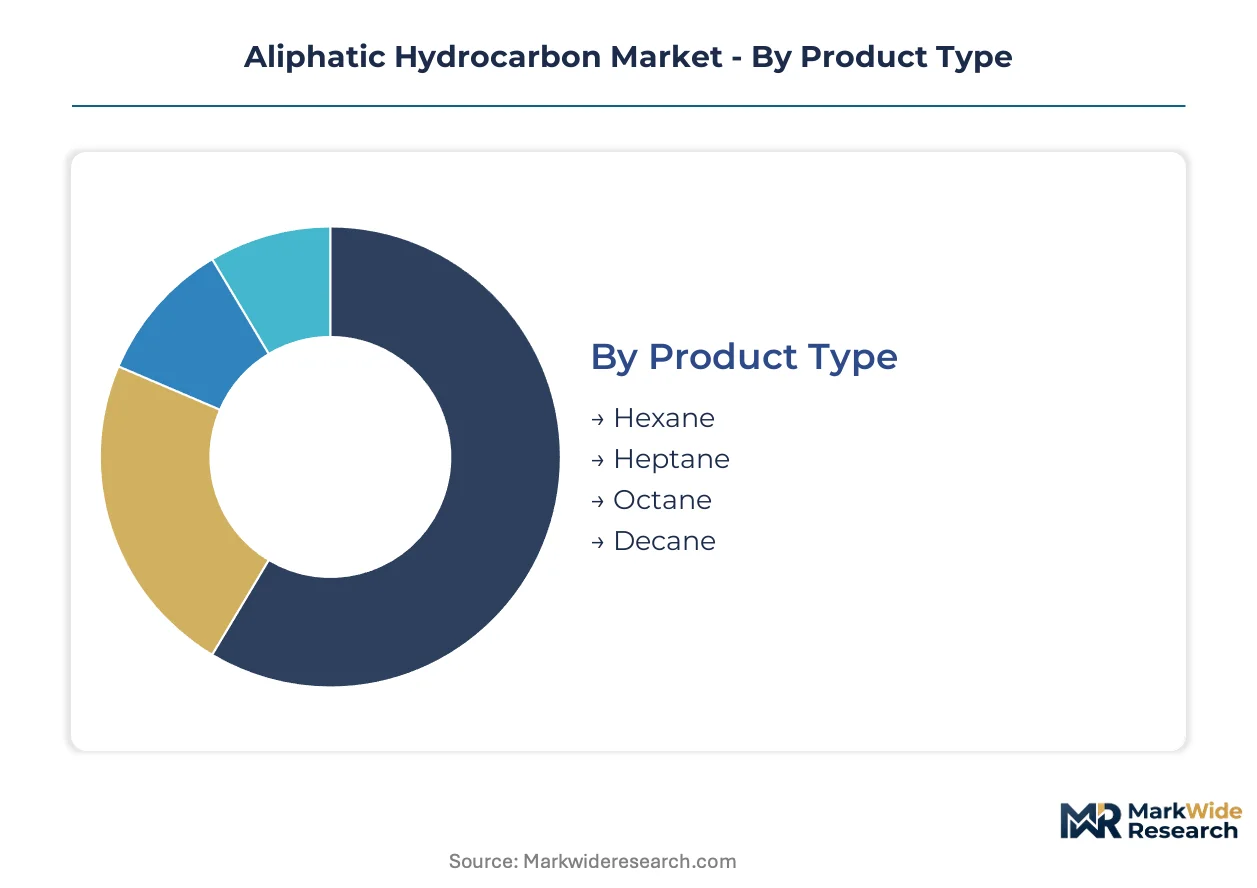
Aliphatic hydrocarbon buyers segment procurement by purity tolerance, volume scale, and regulatory exposure. Grade specifications determine whether a producer competes on cost or certificate-of-analysis premiums. Application mix shifts with substitution risks from bio-based and supercritical alternatives.
Product Type:
Volume concentration and margin capture diverge sharply across carbon chain lengths.
- Hexane:C6 saturated acyclic hydrocarbon with 69°C boiling point serves as the dominant extraction solvent for vegetable oil processing and polymerization initiation. Indian edible oil processors and Brazilian soy crushers sustain bulk consumption despite price volatility, though REACH-registered pharmaceutical grades command substantial premiums over technical specifications.
- Heptane:C7 cut with 98°C boiling range anchors electronics cleaning applications where ultra-low residue specifications apply. Semiconductor fabricators in Taiwan, South Korea, and Japan require narrow-boiling-range material for wafer surface preparation, creating demand disconnected from commodity fuel additive markets.
- Octane:C8 hydrocarbon supplies controlled volatility profiles for automotive fuel blending and laboratory reagent applications.
- Decane:C10 fraction serves specialized solvent and calibration standard uses with limited volume but stable pricing.
Hexane leads volumes today; heptane is gaining share fastest.
Grade:
Purity thresholds separate commodity refiners from specialty chemical competitors.
- Technical:Broad boiling range material meeting industrial solvent specifications without certificate-of-analysis documentation. Agrochemical formulators in India consume technical grades for crop protection synthesis where residue tolerance permits.
- Pure:Narrower distillation cuts suitable for laboratory and general chemical synthesis applications.
- High-Purity:Pharmaceutical and electronics-grade material with comprehensive impurity profiling and batch traceability. Active ingredient extractors reject supply without documented compliance to FDA and EMA drug master file requirements.
- Low-Purity:Fuel blending and bulk diluent applications where specification tolerance maximizes throughput economics.
Technical grade dominates tonnage; high-purity commands the steepest expansion trajectory.
Application:
End-use performance requirements dictate whether buyers prioritize cost or certification.
- Solvents:Non-polar dissolution media for extraction, coatings, and adhesive formulations. Vegetable oil processors in India and Brazil require consistent C6 supply, while pharmaceutical extractors demand REACH-compliant documentation.
- Fuel Additives:Octane and volatility modifiers for gasoline blending. Automotive formulators specify narrow boiling ranges to meet emissions standards without reformulation.
- Chemical Intermediates:Precursor feedstock for polymerization initiators and specialty chemical synthesis.
- Industrial Cleaning:Metalworking degreasing and equipment maintenance solvents facing OSHA exposure limit constraints.
Solvent applications anchor current demand; electronics cleaning is expanding most quickly.
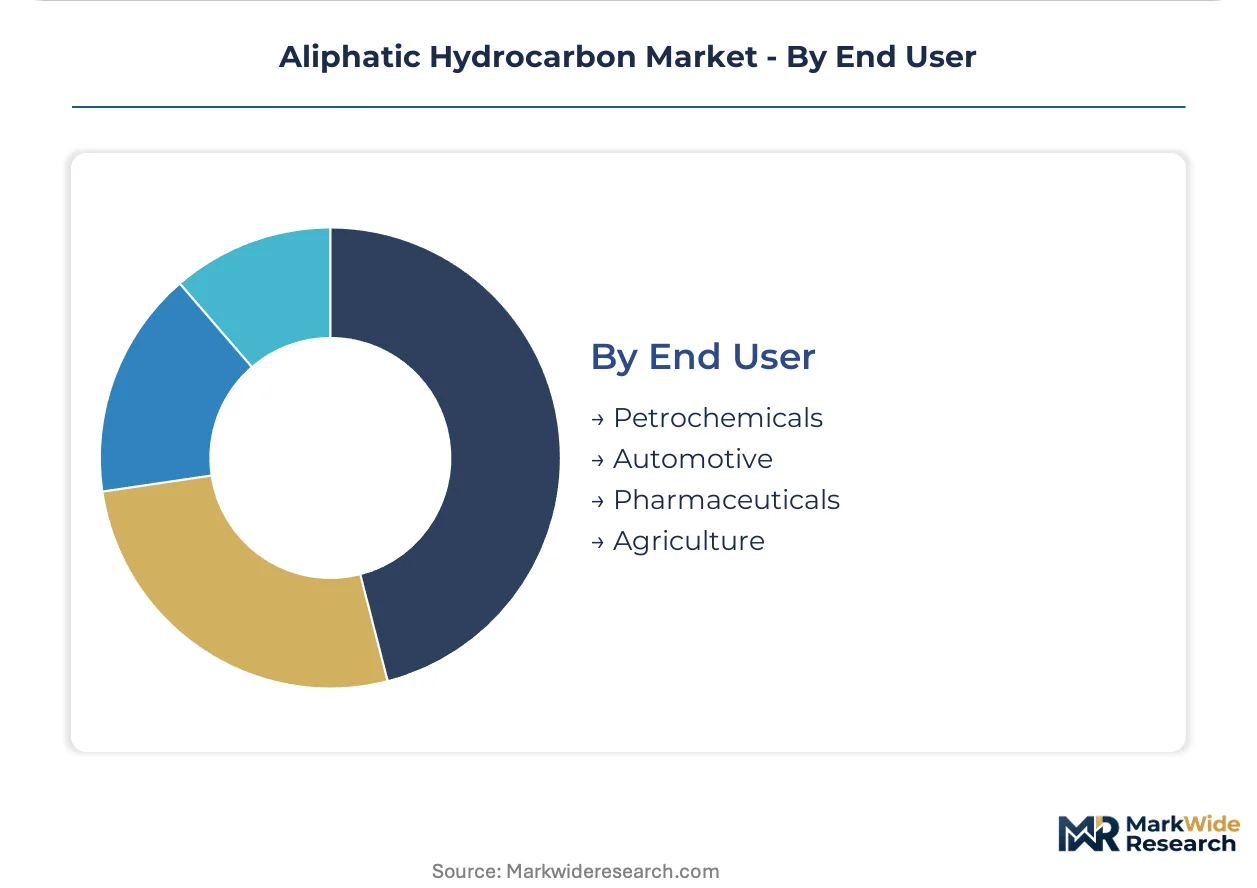
End User:
Regulatory exposure and procurement sophistication vary dramatically across buyer categories.
- Petrochemicals:Integrated producers and downstream polymerization operators consuming C6-C10 as process inputs and external supply. Gulf Coast refiners leverage fractionation integration for cost position.
- Automotive:Fuel additive blenders and original equipment manufacturers specifying volatility profiles for emissions compliance. California Air Resources Board regulations constrain formulation flexibility.
- Pharmaceuticals:Active ingredient extractors and drug manufacturers requiring drug master file support and batch-specific analysis. Consolidated procurement by multinationals concentrates volume with quality-certified suppliers.
- Agriculture:Crop protection formulators and edible oil processors. Reliance Industries and domestic Indian agrochemical producers scale technical-grade consumption for herbicide and insecticide synthesis.
Petrochemicals leads volume absorption; pharmaceuticals drives margin expansion fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's technical-grade consumption is scaling faster than Germany's pharmaceutical-grade demand, revealing how regulatory stringency and industrial application mix reshape regional solvent markets. Geographic concentration of petrochemical infrastructure and divergent compliance timelines are fragmenting procurement strategies across major economies.
United States
Gulf Coast refiners leverage integrated fractionation complexes to supply hexane for domestic vegetable oil processors and polymerization operators. EPA emissions standards and OSHA permissible exposure limits constrain volatile organic compound release, forcing terminal operators to invest in vapor recovery systems. The Texas-Louisiana corridor controls disproportionate North American hexane capacity, creating vulnerability to hurricane disruptions.
Germany
Pharmaceutical extractors and active ingredient manufacturers drive demand for REACH-registered high-purity heptane and octane grades. ECHA registration dossiers mandate full toxicological profiling for C6-C10 imports, delaying market access for non-EU suppliers. The Rhine-Ruhr industrial cluster hosts specialty chemical divisions deploying membrane separation technology to achieve pharmaceutical specifications without energy-intensive distillation.
India
Reliance Industries and domestic agrochemical formulators are scaling technical-grade consumption for crop protection synthesis and edible oil extraction. BIS certification requirements for technical solvents are tightening testing protocols for agricultural chemical diluents. The Gujarat-Maharashtra industrial corridor concentrates solvent demand from crop protection manufacturers and food processors.
China
Semiconductor fabricators in the Yangtze River Delta require ultra-high-purity C7-C9 cuts for wafer cleaning applications. MIIT standards and GB certification protocols govern solvent purity specifications for electronics manufacturing. The Pearl River Delta hosts specialty chemical producers supplying narrow-boiling-range materials for export-oriented electronics cleaning contracts.
Japan
Electronics cleaning applications in semiconductor fabrication drive demand for ultra-low residue heptane specifications. METI regulations and JIS standards constrain impurity profiles for solvents used in precision manufacturing. The Kansai region around Osaka concentrates specialty solvent refining capacity serving domestic and regional electronics supply chains.
Aliphatic Hydrocarbon Market Vendor Landscape
Top-tier vendors anchor integrated petrochemical platforms, while mid-scale specialists compete on narrow-boiling-range synthetic production. Gulf Coast refiners with captive naphtha supply dominate volume positions in North American hexane. Three archetypes define competitive positioning: integrated oil majors with fractionation assets, gas-to-liquid synthetic producers, and specialty chemical divisions serving pharmaceutical and electronics segments. Capacity expansion and catalytic reformer optimization represent the dominant competitive moves, with membrane separation technology emerging as a capability differentiator in premium grades.
Among integrated petrochemical majors, Chevron Phillips Chemical, ExxonMobil Corporation, and Sasol occupy positions spanning crude-derived and synthetic production routes. Chevron Phillips Chemical represents Gulf Coast fractionation dominance with feedstock-integrated cost structures. ExxonMobil Corporation exemplifies catalytic reformer optimization strategies serving pharmaceutical-grade specifications. Sasol anchors Fischer-Tropsch synthetic production, yielding specialty cuts with exceptionally narrow boiling ranges for electronics and pharmaceutical applications unreachable by conventional refining.
| Leading Market Players |
|---|
| Chevron Phillips Chemical |
| LyondellBasell Industries N.V. |
| ExxonMobil Corporation |
| Mitsubishi Chemical Corporation |
| Reliance Industries Limited |
| Shell Global |
| TotalEnergies |
| Sasol |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Consolidated procurement by multinational pharmaceutical extractors concentrates volume with certificate-of-analysis suppliers, forcing three-tier pricing stratification across premium pharmaceutical grades, standard industrial specifications, and economy technical solvents.
Pricing Analysis
Certificate-of-analysis bundling separates pharmaceutical-grade hexane from unbundled technical-grade spot transactions. Price differentiation rests on REACH registration status and membrane separation certification, with electronics fabricators in Taiwan and Japan showing minimal price sensitivity while Indian agrochemical formulators drive aggressive cost compression. Margins are tightening in technical-grade supply as Reliance Industries scales captive consumption.
Supply Chain Analysis
Regional distribution centers along the Texas-Louisiana corridor, Rhine-Ruhr cluster, and Gujarat-Maharashtra corridor anchor hub-and-spoke solvent logistics. Production draws from naphtha fractionation in the United States, synthetic Fischer-Tropsch routes in South Africa, and catalytic reformer optimization in Germany. Single-source vulnerability concentrates in Gulf Coast hurricane exposure. Distribution runs through integrated petrochemical terminals with vapor recovery systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between REACH-registered European supply and technical-grade Indian consumption creates geographic margin dispersion for producers with dual-hemisphere asset footprints.
For Market Incumbents: Deepen membrane separation technology deployment to defend pharmaceutical-grade margins against supercritical CO2 substitution threats. Expand catalytic reformer optimization capacity in Germany to capture ECHA-registered premium tiers. Secure backward integration into naphtha supply to offset crude feedstock volatility. For New Entrants and Emerging Players: Electronics distributors in Taiwan and South Korea offer channel access to ultra-high-purity heptane demand with minimal incumbent saturation. Target semiconductor fabricators requiring narrow-boiling-range C7 cuts with direct technical service partnerships bypassing established petrochemical majors. For Investors and Strategic Acquirers: Specialty chemical divisions of integrated oil majors are the most active acquirer in this space, consolidating Fischer-Tropsch synthetic capabilities. Long-term viability hinges on gas-to-liquid technology access for pharmaceutical and electronics segments. Watch for REACH dossier completion timelines as inflection signals for non-EU supplier market access.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Separation Technology Deployment | Enables pharmaceutical-grade certification without energy-intensive distillation passes, serving FDA and EMA drug master file requirements. |
| Catalytic Reformer Optimization | Refiners achieve narrower boiling range cuts meeting semiconductor fabricator specifications in Taiwan and Japan. |
| Fischer-Tropsch Synthetic Route Expansion | Gas-to-liquid production yields specialty cuts unreachable by crude-derived fractionation for electronics cleaning. |
| REACH Registration Dossier Completion | ECHA compliance opens European pharmaceutical extractor procurement to non-EU suppliers with toxicological profiling. |
| Backward Integration into Naphtha Supply | Gulf Coast refiners secure captive feedstock access insulating margin predictability from energy market swings. |
Methodological Framework
Multiple input streams — primary interviews with refinery operations managers, pharmaceutical procurement directors, and agrochemical formulators; secondary validation through customs trade data, ACC and Cefic industry reports, and SEC 10-K filings; plus regulatory database monitoring — were reconciled through bottom-up and top-down triangulation.
Historical volume trajectories were cross-referenced against expert panel assessments across the projection horizon. Segmentation dimensions modeled include carbon chain length, purity grade tier, end-use application, and regional regulatory cluster. CAGRs were derived from demand elasticity analysis incorporating vegetable oil processing rates, semiconductor wafer starts, and crop protection formulation activity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to crude oil price volatility, REACH regulatory amendments, and supercritical CO2 substitution adoption in flavor extraction. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petrochemicals
Anthracene Oil Market
Petrochemicals
Bioisobutene Market
Petrochemicals
Light Olefins Market
Petrochemicals
Petrochemical Feedstock Market
Petrochemicals
Global Perfluorocarbons Market
Petrochemicals
Propylene Carbonate Market
Petrochemicals
Military Propellants Market
Petrochemicals
Chemical and Petroleum Containers Market
Petrochemicals
Synthetic and Biobased Butadiene Market
Petrochemicals
Global Butadiene Market
Petrochemicals
Petrochemicals Market
Petrochemicals
Propane Market
Petrochemicals
Basic Petrochemical Market
Petrochemicals
Fossil Fuel-Based Plastics Market
Petrochemicals
Pentane Market
Petrochemicals
Oman Pyrolysis Gasoline Market