
 Hypopigmentation Disorder Treatment Market | 2026-2036
Hypopigmentation Disorder Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Hypopigmentation Disorder Treatment Market Outlook
Pharmaceutical-grade topical formulations is reorganizing competitive dynamics in hypopigmentation care. AbbVie Inc. leverages its immunology infrastructure to sustain R&D intensity across novel pigmentation pathways. Galderma anchors dermatology channel access through its integrated clinic partnerships and aesthetic medicine networks. Pierre Fabre Group differentiates via botanical-derived actives and European formulation heritage.
Hypopigmentation disorder treatment encompasses pharmacological and non-pharmacological interventions designed to restore melanocyte function or camouflage melanin-deficient skin lesions, with topical corticosteroids and calcineurin inhibitors serving as first-line modalities for inflammatory etiologies such as vitiligo and post-inflammatory hypopigmentation. Light therapy, including narrowband UVB and excimer laser systems, functions through photostimulation of residual melanocyte reservoirs in depigmented plaques. Pharmacological treatments command the largest current revenue pool given established reimbursement and clinical familiarity, while laser treatment segments exhibit the fastest structural expansion as device manufacturers improve targeting precision and reduce adverse event profiles. Combination therapy approaches capture premium positioning by addressing multiple pathogenic mechanisms simultaneously.
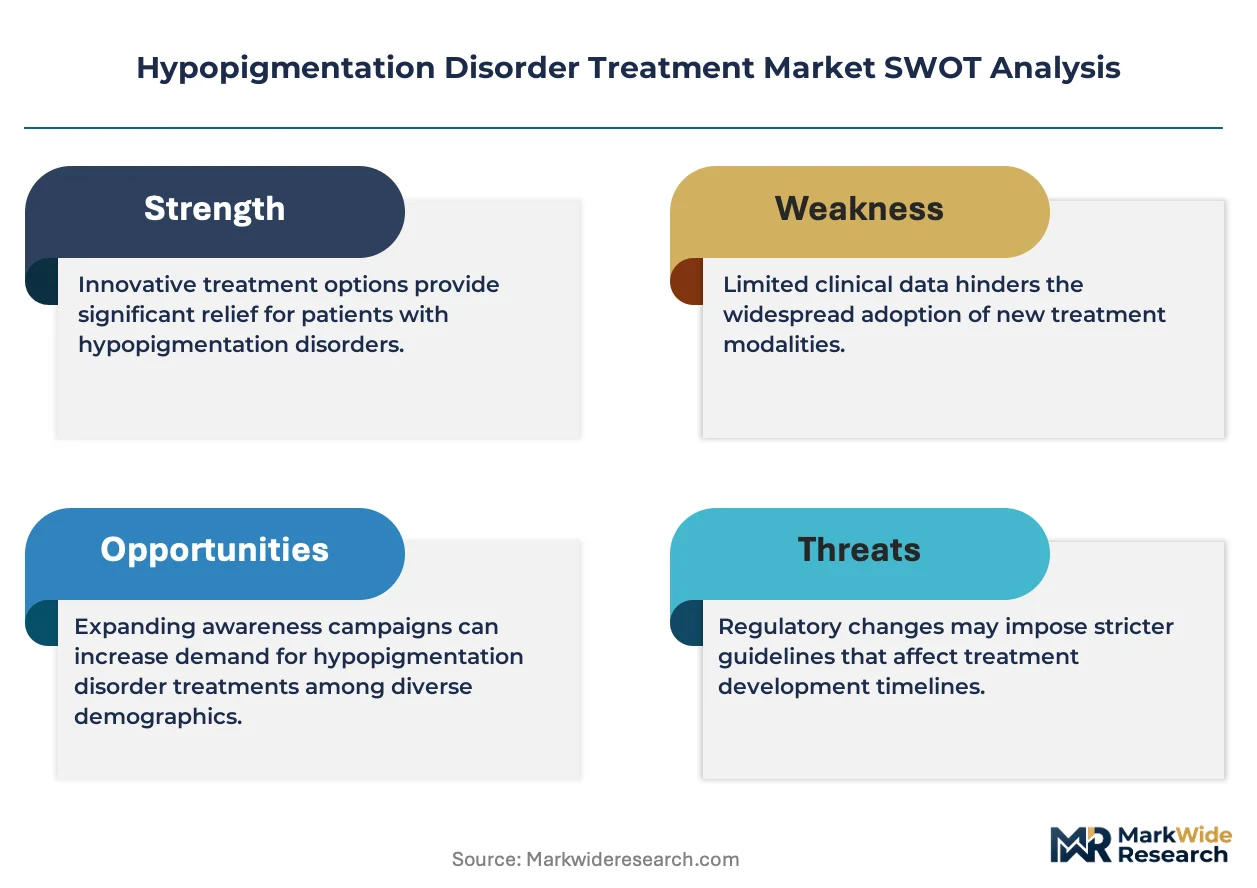
FDA oversight of topical corticosteroid potency labeling and EMA's evolving stance on hydroquinone concentration limits constrain formulation flexibility while accelerating demand for azelaic acid and glutathione alternatives. The EU Medical Device Regulation reclassifies certain laser platforms, extending compliance timelines for manufacturers serving European dermatology practices. Stakeholders must monitor regulatory divergence between FDA and EMA active ingredient thresholds to optimize regional portfolio allocation without duplicative clinical development.
Market Dynamics
FDA's evolving guidance on topical corticosteroid safety is compressing formulation flexibility across North American dermatology channels, forcing manufacturers toward alternative active ingredients and combination therapies. This regulatory pivot is accelerating R&D investment in botanical-derived and peptide-based modalities while reshaping competitive positioning among established topical players.
Growth Catalysts
- Narrowband UVB photostimulation:Dermatology clinics in the United States are expanding excimer laser installations to address residual melanocyte activation in vitiligo plaques, driving device utilization rates.
- EMA's hydroquinone concentration limits:European formulation standards are redirecting demand toward azelaic acid and glutathione alternatives, opening substitution pathways for botanical-active developers.
- Aesthetic medicine network expansion:Integrated clinic partnerships in Germany and France are consolidating patient access channels for premium pigmentation correction services.
Market Restraints
- Active ingredient supply concentration:Corticosteroid raw material production clusters in India and China, exposing formulators to API availability disruptions and quality variability.
- Device capital intensity:Excimer laser platforms require substantial upfront investment and specialized maintenance, constraining adoption among independent dermatology practices.
- Reimbursement fragmentation:Light therapy coverage varies across German statutory health insurance funds, creating access inequities and treatment abandonment.
Strategic Opportunities
- Direct-to-consumer skincare channels:Telemedicine platforms in the United States are enabling prescription topical delivery without clinic visits, capturing patient convenience premiums.
- Peptide-melanocyte convergence:α-MSH analogs combined with JAK inhibitors represent untapped mechanistic synergy for segment-specific repigmentation protocols.
- EU Medical Device Regulation compliance extensions:Reclassified laser platforms gain extended market access timelines, allowing European manufacturers to optimize certification sequencing.
Industry Challenges
- Phototherapy technician certification:Narrowband UVB protocol standardization lags across French and Italian training institutions, creating treatment outcome variability.
- Legacy EMR integration:Pigmentation tracking software requires costly adaptation to existing dermatology practice management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hypopigmentation Disorder Treatment Market |
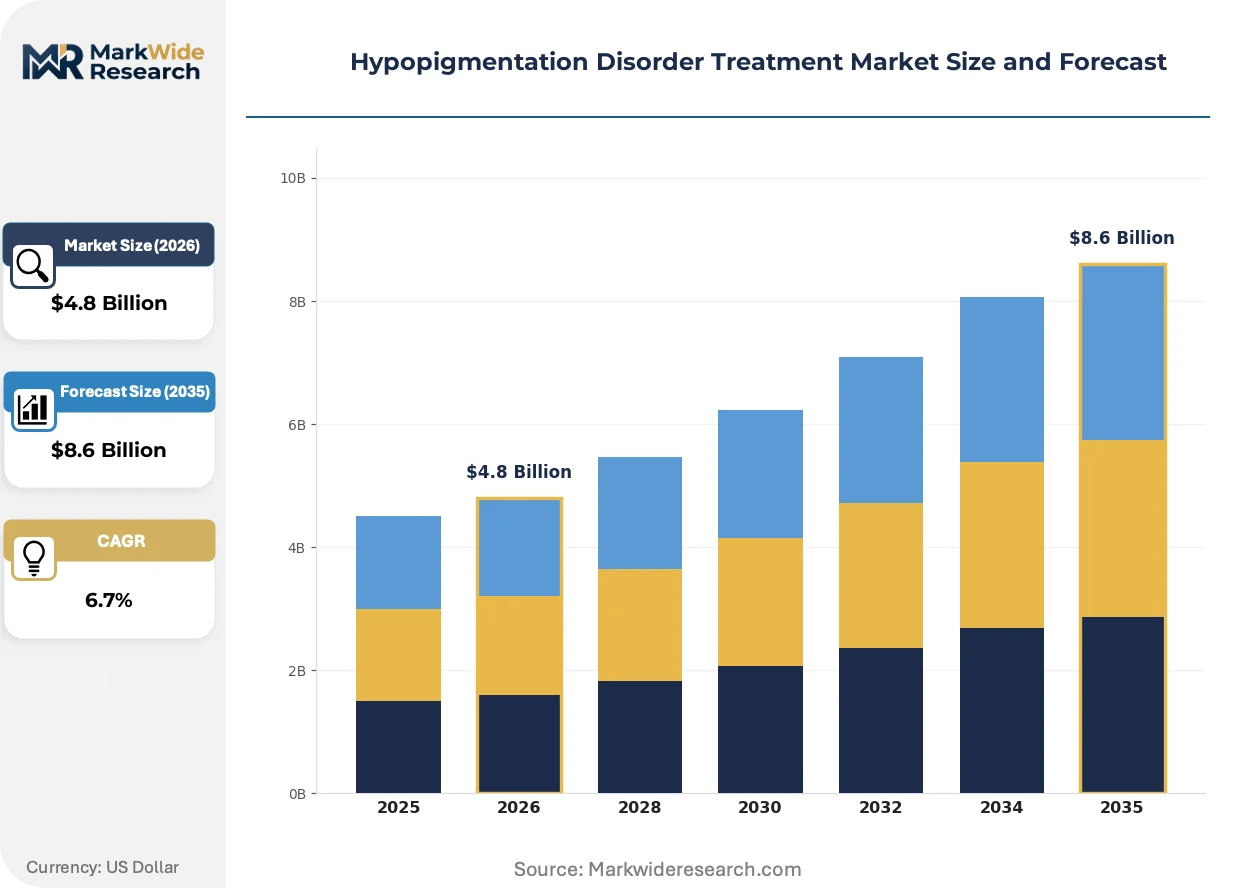
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Topical Treatments, Light Therapy, Chemical Peels Active Ingredient: Hydroquinone, Tretinoin, Azelaic Acid, Glutathione End User: Dermatology Clinics, Hospitals, Home Care, Specialty Clinics Treatment Modality: Pharmacological, Non-Pharmacological, Combination Therapy, Laser Treatment |
| Companies Covered | AbbVie Inc., Bayer AG, Galderma, Pierre Fabre Group, Novartis AG, Pfizer Inc., Aclaris Therapeutics, Inc., Incyte, Candela Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hypopigmentation Disorder Treatment Market Strategic Shifts
Photostimulation technologies are compressing treatment timelines while regulatory divergence between FDA and EMA active ingredient thresholds is fragmenting formulation strategies. These shifts are converging with channel disintermediation to reshape how patients access and pay for pigmentation correction.
Excimer laser systems with targeted 308nm delivery is displacing conventional whole-body narrowband UVB cabinets in United States dermatology clinics. Large specialty clinic networks are prioritizing precision-targeted devices to reduce per-session time and improve melanocyte activation rates in stable vitiligo plaques. This hardware transition is compressing equipment replacement cycles and elevating service pricing power for practices with capital deployment capacity.
REACH-compliant botanical extraction standards are constraining hydroquinone availability across European compounding pharmacies. EMA's evolving stance on depigmenting agent safety is accelerating azelaic acid formulation development and glutathione topical commercialization. German and French manufacturers are responding with accelerated stability testing for plant-derived tyrosinase modulators to secure preemptive market positioning.
Subscription-based topical replenishment is displacing traditional prescription refill models in United States direct-to-consumer channels. Telemedicine platforms are capturing patient cohorts previously served by brick-and-mortar dermatology practices, unbundling diagnosis from product fulfillment. This channel shift is most visible in California and Texas metropolitan markets where aesthetic medicine advertising density supports digital patient acquisition economics.
Hypopigmentation Disorder Treatment Market Segmentation
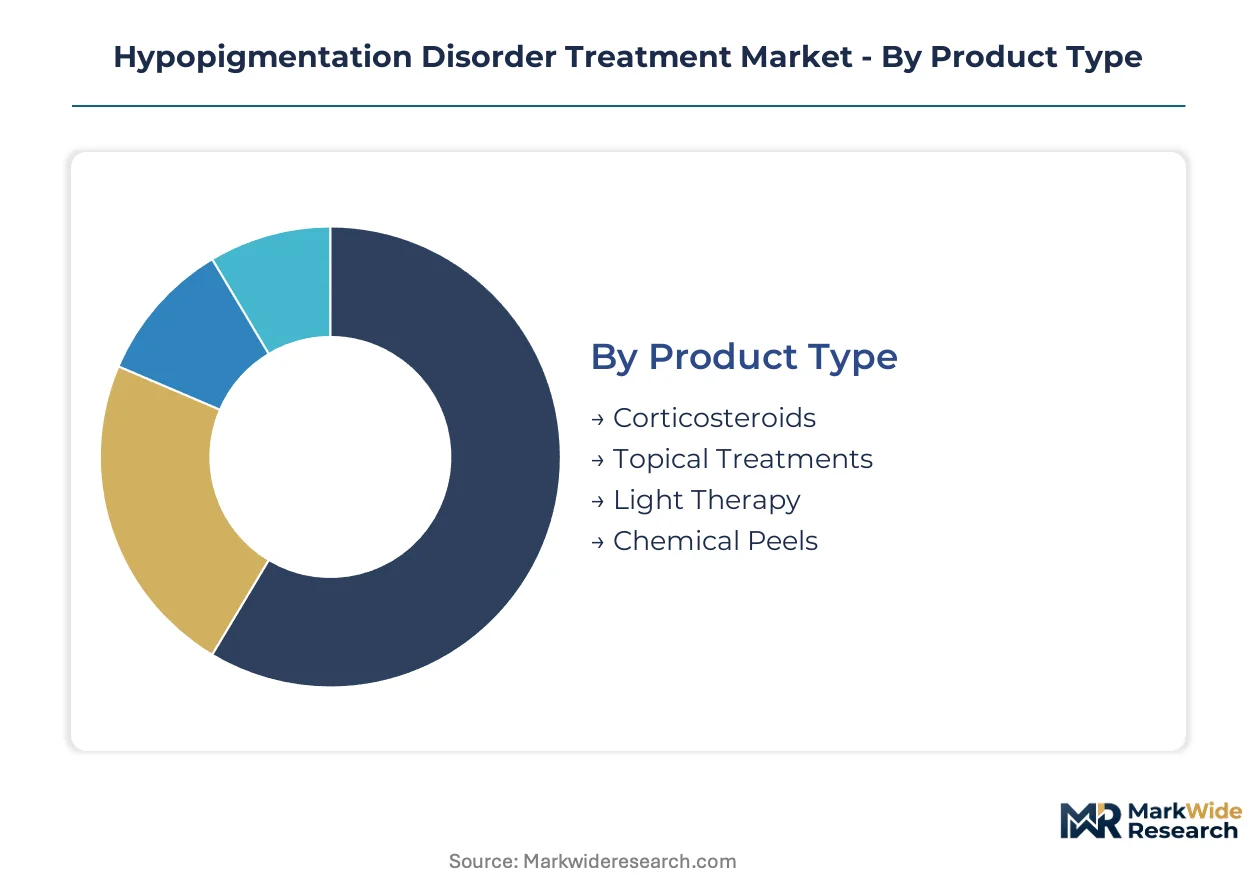
Hypopigmentation disorder treatment markets fragment across intervention mechanisms and care delivery settings. Substitution pressures from botanical actives and device-based modalities are compressing legacy pharmaceutical segments. Channel disintermediation and regulatory divergence amplify strategic importance of precise segment targeting.
Product Type:
Topical corticosteroids face the most acute substitution threat as FDA safety guidance hardens and dermatology clinics pivot toward lower-risk alternatives.
- Corticosteroids:First-line anti-inflammatory formulations suppress melanocyte destruction in vitiligo and post-inflammatory hypopigmentation. Demand concentrates in United States dermatology clinics where established reimbursement codes sustain prescribing volume despite safety warnings.
- Topical Treatments:Non-steroidal creams and ointments encompass calcineurin inhibitors, vitamin D analogs, and botanical-derived actives. German and French compounding pharmacies are expanding azelaic acid and glutathione offerings as EMA hydroquinone limits redirect formulation preferences.
- Light Therapy:Narrowband UVB and excimer laser systems photostimulate residual melanocyte reservoirs.
- Chemical Peels:Superficial and medium-depth exfoliation procedures address post-inflammatory hypopigmentation in aesthetic medicine settings.
Corticosteroids anchor the volume base while topical treatments gain share at the steepest rate.
Active Ingredient:
Cost tier stratification separates premium peptide-based development from commodity botanical extraction.
- Hydroquinone:Tyrosinase-inhibiting depigmenting agent with decades of clinical documentation. European demand is collapsing under EMA concentration limits while United States compounding pharmacies maintain restricted access for recalcitrant cases.
- Tretinoin:Retinoid accelerator of epidermal turnover combined with melanocyte migration stimulation. Dermatology clinics in California and Texas metropolitan markets bundle tretinoin with hydroquinone in prescription protocols despite regulatory headwinds.
- Azelaic Acid:Dicarboxylic acid with anti-inflammatory and tyrosinase-inhibiting properties.
- Glutathione:Antioxidant melanogenesis modulator delivered through topical and systemic routes.
Tretinoin commands premium pricing in combination protocols while azelaic acid expands most quickly as a hydroquinone substitute.
End User:
Customer type fragmentation separates institutional procurement from direct-to-consumer convenience premiums.
- Dermatology Clinics:Primary diagnosis and treatment delivery sites with integrated device and pharmaceutical dispensing. United States specialty clinic networks in Florida and New York are consolidating through acquisition to capture phototherapy service revenue.
- Hospitals:Academic medical centers and general hospitals manage severe or refractory cases requiring multidisciplinary care. German university hospitals anchor vitiligo research protocols and experimental JAK inhibitor trials.
- Home Care:Patient-administered topical regimens supported by telemedicine platforms.
- Specialty Clinics:Aesthetic medicine and cosmetic dermatology practices focusing on pigmentation correction.
Dermatology clinics capture the highest procedure volume while home care climbs the fastest through telemedicine channel expansion.
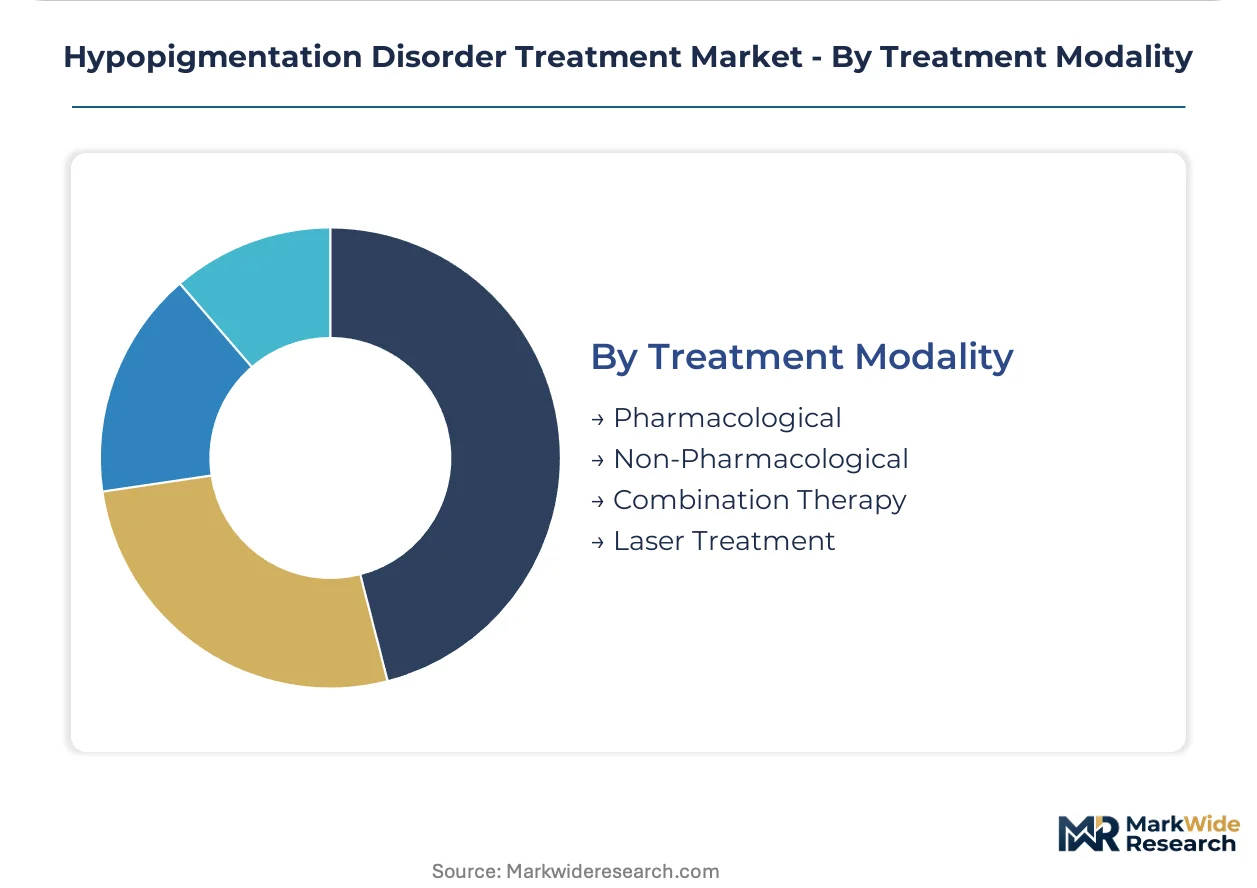
Treatment Modality:
Maturity gradients separate established pharmacological reimbursement from emerging device-based self-pay segments.
- Pharmacological:Systemic and topical drug interventions targeting melanocyte survival and function. Reimbursement familiarity in United States commercial insurance and Medicare Advantage plans sustains prescriber preference despite slower efficacy timelines.
- Non-Pharmacological:Camouflage cosmetics, micropigmentation, and dietary interventions. French and Italian aesthetic medicine clinics are expanding medical micropigmentation services for stable vitiligo patients seeking immediate visual correction.
- Combination Therapy:Simultaneous or sequential multimodal approaches.
- Laser Treatment:Targeted phototherapy devices including excimer and fractional laser platforms.
Pharmacological modalities retain the largest patient volume base while laser treatment gains share at the steepest rate through precision-targeting advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
API manufacturing for topical corticosteroids concentrates in Indian pharmaceutical clusters and Chinese chemical hubs, exposing formulators to cross-border supply variability. Dermatology device assembly localizes in German precision manufacturing zones and United States medical technology corridors.
United States
Specialty clinic networks in Florida and New York drive excimer laser adoption for vitiligo photostimulation. FDA guidance on corticosteroid potency labeling forces reformulation toward botanical-derived alternatives. California metropolitan markets anchor direct-to-consumer telemedicine channel expansion for prescription topical delivery.
Germany
University hospitals in Berlin and Munich anchor vitiligo research protocols and experimental JAK inhibitor trials. EMA hydroquinone concentration limits redirect compounding pharmacy demand toward azelaic acid formulations. Baden-Württemberg precision manufacturers supply narrowband UVB device components to European dermatology practices.
France
Aesthetic medicine clinics in Paris and Lyon expand medical micropigmentation services for stable vitiligo patients. ANSM oversight of depigmenting agent safety accelerates glutathione topical commercialization. Provence-Alpes-Côte d'Azur botanical extractors develop REACH-compliant plant-derived tyrosinase modulators.
India
Active pharmaceutical ingredient production in Gujarat and Maharashtra supplies corticosteroid raw materials to North American and European formulators. CDSCO manufacturing standards enforcement intensifies quality compliance costs for export-oriented producers. Hyderabad research institutes collaborate on peptide-melanocyte convergence therapies.
Japan
Academic medical centers in Tokyo and Osaka pioneer narrowband UVB protocol standardization for East Asian skin phototypes. PMDA review timelines for novel pigmentation pathway modulators exceed Western regulatory benchmarks. Kansai region device manufacturers develop fractional laser platforms with reduced adverse event profiles.
Hypopigmentation Disorder Treatment Market Competitive Environment
Concentration sits with immunology-focused pharmaceutical conglomerates and integrated dermatology specialists. Tier-one players control prescription topical portfolios through established reimbursement relationships. Strategic archetypes span Big Pharma immunology divisions, pure-play dermatology companies, and aesthetic medicine device manufacturers. Dominant competitive moves include clinic network acquisition in United States metropolitan markets and botanical-active formulation partnerships in European compounding channels.
Within the pharmaceutical archetype, AbbVie Inc. and Novartis AG exemplify immunology infrastructure deployment across novel pigmentation pathways. Galderma anchors dermatology channel access through integrated clinic partnerships. Pierre Fabre Group occupies a position within the botanical-heritage tier, leveraging European formulation expertise as EMA hydroquinone limits reshape ingredient preferences.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Bayer AG |
| Galderma |
| Pierre Fabre Group |
| Novartis AG |
| Pfizer Inc. |
| Aclaris Therapeutics, Inc. |
| Incyte |
| Candela Corporation |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day corticosteroid API inventory cycles in North American formulators compress pricing flexibility when Indian and Chinese supply nodes face quality audits, concentrating procurement power among vertically integrated dermatology networks while elevating botanical-active premiums.
Pricing Analysis
FDA potency labeling guidance dictates the pricing tier structure across topical hypopigmentation treatments, stratifying formulations by safety classification and reimbursement eligibility. Three-tier pricing separates prescription corticosteroids from compounded botanical alternatives and direct-to-consumer peptide serums, with certification grade and channel control as primary differentiation drivers. Cost compression in mid-tier azelaic acid formulations is intensifying because EMA hydroquinone limits redirect European demand toward substitute actives. Hospital procurement committees exhibit highest price sensitivity, while aesthetic medicine clinics absorb premium positioning for combination therapy protocols.
Supply Chain Analysis
Gujarat-Maharashtra API manufacturing clusters underwrite corticosteroid raw material availability for Western formulators, creating single-source vulnerability when CDSCO enforcement actions disrupt export certifications. Active pharmaceutical ingredient production draws from India and China, with excimer laser device assembly anchored in German precision manufacturing zones and United States medical technology corridors. Hydrocortisone base, tacrolimus powder, and narrowband UVB lamp phosphors constitute critical input dependencies. Tariff exposure on Chinese-sourced chemical intermediates elevates landed costs for European compounders. Distribution runs through integrated dermatology clinic networks in United States metropolitan markets and compounding pharmacy channels across Germany and France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hypopigmentation treatment demand cycles track dermatology clinic capital expenditure waves, with excimer laser replacement cycles and topical formulation patent cliffs converging to compress incumbent margins while opening white-space for mechanism-differentiated entrants.
For Market Incumbents: Fortify clinic network control through exclusive device-therapy bundling agreements in Florida and New York metropolitan markets, where specialty acquisition activity concentrates patient access channels. Deepen backward integration into botanical extraction capabilities to preempt EMA-compliant supply constraints. Secure JAK inhibitor pipeline positioning against emerging peptide-melanocyte convergence therapies. For New Entrants and Emerging Players: CE marking fast-track for excimer laser platforms under EU Medical Device Regulation compliance extensions enables preemptive European market positioning before incumbent certification sequencing completes. Target German university hospital research partnerships as the most penetrable entry channel for experimental pigmentation pathway modulators. Pursue telemedicine platform integration as the dominant go-to-market angle for prescription topical delivery in California and Texas. For Investors and Strategic Acquirers: Carve-out targets emerge from Big Pharma immunology divisions seeking to monetize non-core dermatology assets as pipeline prioritization shifts toward systemic autoimmune indications. Five-to-ten-year viability hinges on regulatory arbitrage capabilities across FDA and EMA divergence on active ingredient thresholds. Monitor CDSCO enforcement action frequency as the inflection indicator for API supply cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA 505(b)(2) submissions for reformulated corticosteroid alternatives accelerate market entry timelines. |
| Clinical Trial Advancement | JAK inhibitor Phase II protocols in German university hospitals establish repigmentation efficacy benchmarks. |
| Manufacturing Scale-Up | REACH-compliant botanical extraction capacity in Provence-Alpes-Côte d'Azur secures European formulation supply. |
| Licensing Agreement | Peptide-melanocyte convergence technology partnerships with Hyderabad research institutes access novel mechanisms. |
| Distribution Channel Expansion | Telemedicine platform integration in California metropolitan markets captures direct-to-consumer prescription volume. |
Study Parameters
Operator-level perspectives from dermatology clinic operators, pharmaceutical regulatory affairs leads, compounding pharmacy procurement managers, and excimer laser service technicians anchored the qualitative base for this analysis. Primary interview insights combined with secondary validation from FDA 510(k) filings, EMA marketing authorization applications, ClinicalTrials.gov protocol registries, and German statutory health insurance reimbursement databases. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Sensitivity analysis across regulatory scenario variants tested forecast robustness over the projection horizon. Segmentation dimensions modeled include treatment modality, active ingredient class, end-user channel, and regional regulatory cluster. CAGRs derived from compound growth trajectory fitting to historical procedure volume and pricing trend data. Forecast inputs incorporated excimer laser installation rates in United States specialty clinic networks and EMA hydroquinone limit implementation timelines.
The analysis sits within stated boundaries; outcomes outside maintained FDA-EMA regulatory divergence or stable corticosteroid API trade flows would require recalibration. Forecasts reflect documented assumptions regarding clinic network consolidation pace and telemedicine channel penetration ceilings. Practitioners should keep alternative scenarios live as CDSCO enforcement intensity and excimer laser technician certification standardization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Retinal Biologics Market
Specialty Medicine
Global Autism Spectrum Disorders Market
Specialty Medicine
Global Chronic Idiopathic Constipation Market
Specialty Medicine
Mucous Membrane Pemphigoid Treatment Market
Specialty Medicine
Radioimmunotherapy (RIT) Market
Specialty Medicine
Carcinoid Syndrome Diarrhea Treatment Market
Specialty Medicine
Gastrointestinal Stromal Tumor (GIST) Therapeutics Market
Specialty Medicine
Primary Hyperoxaluria Treatment Market
Specialty Medicine
Global Pheochromocytoma Market
Specialty Medicine
Hermansky Pudlak Syndrome Therapeutics Market
Specialty Medicine
Global Allergic Rhinitis Market
Specialty Medicine
Secondary Progressive Multiple Sclerosis (SPMS) Treatment Market
Specialty Medicine
Global Lung Transplant Therapeutics Market
Specialty Medicine
Combined Immune Deficiency (CID) Market
Specialty Medicine
Liver Fibrosis Treatment Market
Specialty Medicine
Benign Positional Vertigo Market