
 Europe Astrology Market | 2026-2036
Europe Astrology Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Astrology Market Insights
Demand among European consumers is consolidating around subscription-based mobile astrology platforms that blend algorithmic chart generation with personalized coaching. Sanctuary leverages proprietary AI natal chart engines to differentiate its user experience across iOS and Android ecosystems. Co-Star, Inc. anchors its European presence through localized content partnerships and multilingual horoscope delivery. Astrodienst AG sustains decades of technical authority with its Swiss-hosted ephemeris databases and precision Swiss Ephemeris calculations.
European astrology encompasses the computational and interpretive practice of mapping celestial body positions against terrestrial locations to generate personality profiles, timing forecasts, and relational compatibility assessments; practitioners rely on precise astronomical ephemerides, house system algorithms, and geocentric coordinate transformations to produce natal charts and transit analyses for individual guidance and commercial decision-support. Horoscope services dominate volume through daily content feeds and push-notification engagement models, while astrology consultations capture premium margin pools through one-to-one practitioner time. Tarot readings represent the fastest-growing segment as video-streaming integration and real-time digital card shuffling expand addressable audiences beyond traditional occult consumers.
The EU Digital Services Act and GDPR impose transparency obligations on astrology platforms processing biometric-derived psychological profiles, while national advertising standards authorities in Germany and France scrutinize unsubstantiated predictive claims in spiritual marketing. E-commerce VAT harmonization across member states simplifies cross-border subscription billing for astrology apps headquartered in lower-rate jurisdictions. Stakeholders must monitor evolving AI disclosure requirements as regulators examine whether algorithmic chart interpretation constitutes regulated advice.
Market Dynamics
The EU Digital Services Act imposes algorithmic transparency mandates on astrology platforms processing user psychological data, forcing operators to restructure content moderation and disclosure frameworks across French, German, and British markets.
Growth Catalysts
- GDPR-compliant personalization engines:European consumers demand hyper-customized natal chart interpretations that respect data sovereignty, driving investment in on-device computation and federated learning architectures.
- France:The country's advertising standards authority tolerates spiritual wellness claims more permissively than predictive health assertions, creating regulatory breathing room for astrology-as-entertainment positioning.
- Video-native tarot streaming:Real-time card reading formats on mobile platforms attract younger demographics previously unreachable through static horoscope text.
Market Restraints
- Biometric data classification uncertainty:German and French regulators debate whether facial recognition-derived astrological profiles trigger enhanced GDPR protections, chilling feature rollout timelines.
- Ephemeris database concentration:Swiss-hosted precision astronomical datasets create single-point dependency risks for algorithmic chart generation across the continent.
- Scientific skepticism in Nordic markets:Norway and Sweden maintain stronger cultural resistance to non-evidence-based guidance services, compressing addressable audience in Scandinavia.
Strategic Opportunities
- Poland and Eastern Europe:These markets show rising mobile spirituality app downloads with limited domestic platform competition, offering first-mover positioning for localized content.
- Corporate wellness integration:HR departments in Germany and the Netherlands experiment with team-building astrology workshops as employee engagement tools.
- EU AI Act disclosure pathways:Early compliance with algorithmic explainability requirements creates competitive differentiation against non-compliant foreign competitors.
Industry Challenges
- Astronomical calculation expertise scarcity:Platform operators struggle to recruit engineers fluent in both software development and classical ephemeris mathematics for precision chart generation.
- Cross-border VAT complexity:Subscription billing across 27 member states with divergent digital services tax implementations strains finance operations and margin predictability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Astrology Market |
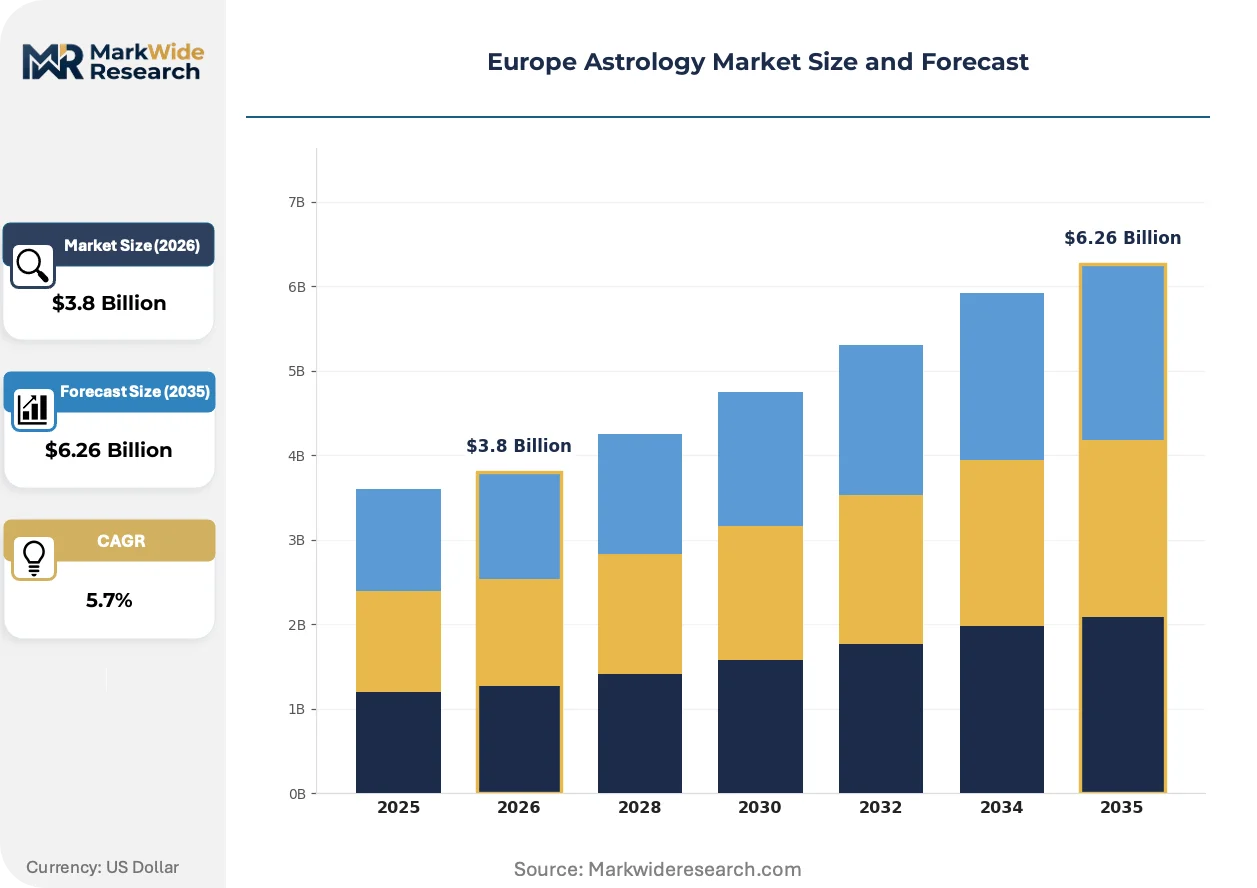
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Horoscopes, Tarot Readings, Palmistry, Astrology Consultations Distribution Channel: Online Platforms, Mobile Apps, In-Person Sessions, Social Media End User: Individuals, Businesses, Spiritual Groups, Educational Institutions Pricing Model: Subscription, Pay-Per-Session, Freemium, Bundled Services |
| Companies Covered | Sanctuary, Susan Miller’s Astrology Zone LLC, Astrodienst AG, OBRIO Limited, Horoscope.com Inc by Ingenio LLC., Moonly Tech GmbH, The Pattern Inc, Astro-Vision Futuretech Pvt. Ltd., Co-Star, Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Astrology Market Trends and Innovations
Generative AI architectures are compressing the cost structure of personalized astrological content production while raising regulatory scrutiny over algorithmic advice classification. Three developments warrant particular attention.
Proprietary natal chart engines are consolidating market share among platforms that invested early in machine learning-based house system calculations and transit pattern recognition. French and British millennials adopt these services at accelerating rates, displacing generic horoscope aggregators. The technology is consolidating competitive position around data moats built from user feedback loops on prediction accuracy.
The EU Digital Services Act's transparency obligations for recommender systems directly impact astrology apps serving German and French users, requiring disclosure of how personalized content feeds rank spiritual guidance. Platforms must now document content moderation criteria for metaphysical claims. Smaller operators face compliance costs that favor established players with dedicated regulatory functions.
Subscription fatigue among British consumers is fragmenting demand across micro-payment models for one-off readings rather than annual commitments. Tarot practitioners in London and Manchester pivot toward pay-per-session video formats. This behavioral shift concentrates revenue volatility in the United Kingdom while stabilizing recurring streams in Germany's more subscription-loyal user base.
Europe Astrology Market Segmentation
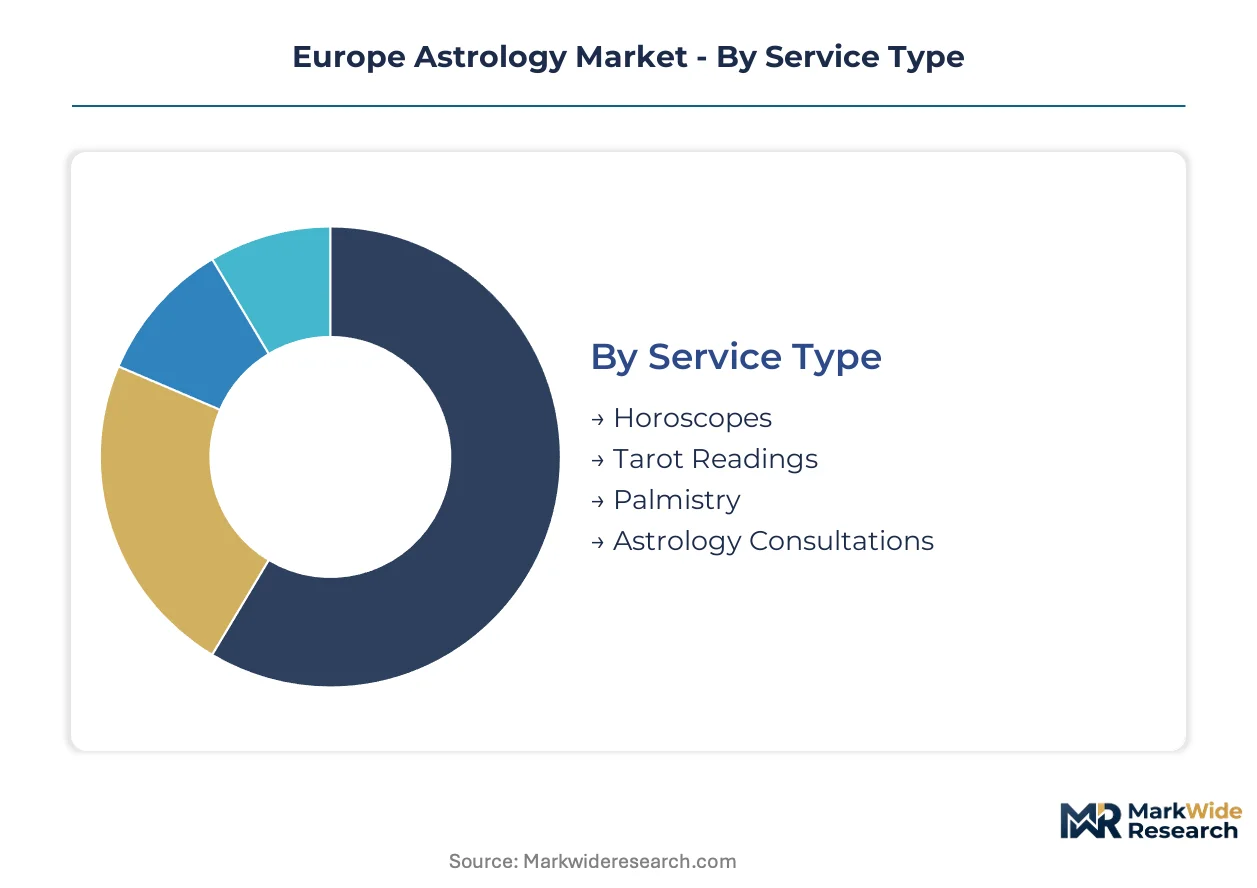
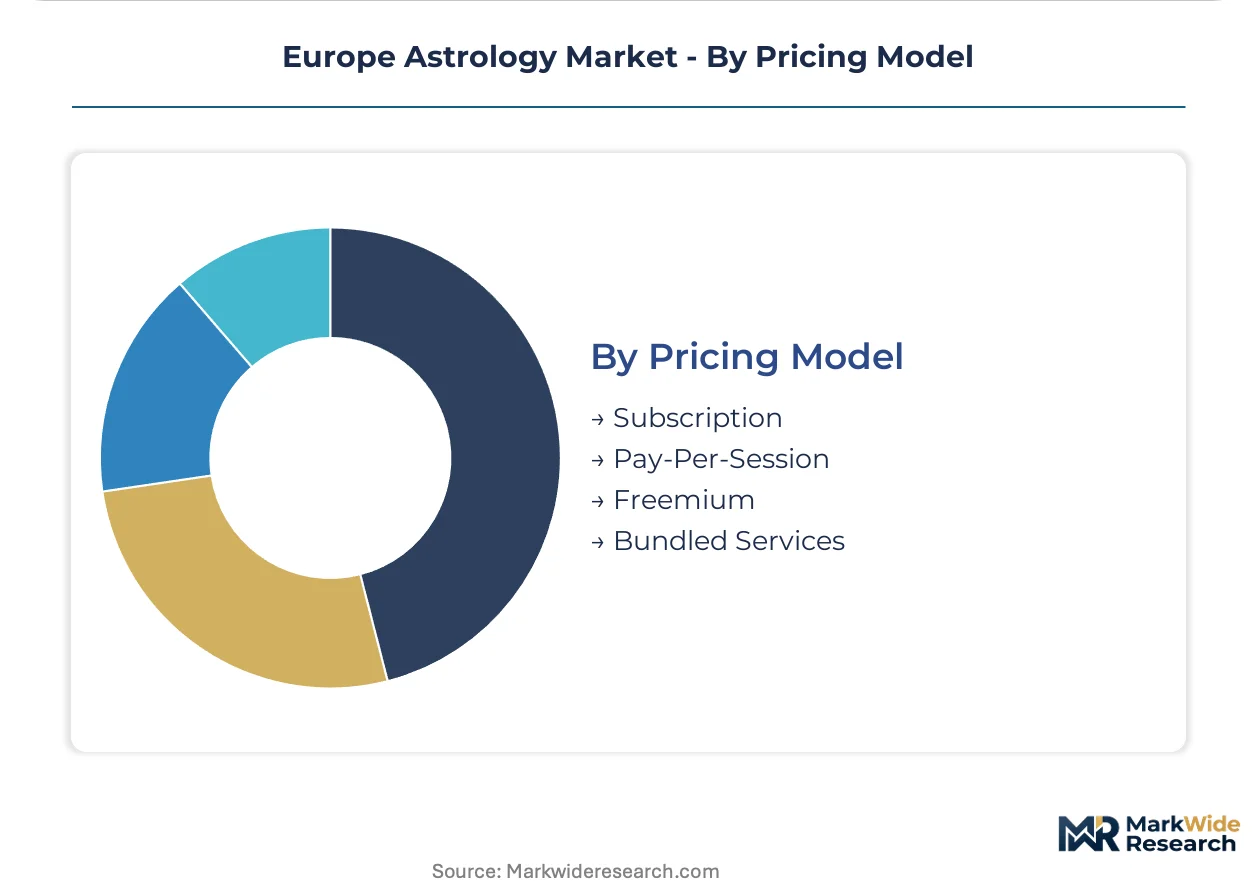
Service differentiation across the European astrology market follows distinct consumption patterns shaped by regulatory exposure and generational preference. Platform operators calibrate feature sets and compliance architecture around how users access interpretive guidance and what price mechanisms they tolerate.
Service Type:
Supply concentrates around algorithmic content generation capabilities, with technical infrastructure investments determining competitive position across interpretive modalities.
- Horoscopes:Automated daily content feeds powered by ephemeris databases and push-notification delivery systems dominate volume throughput. French and British millennials drive consumption through mobile-first engagement models that prioritize convenience over depth.
- Tarot Readings:Real-time video streaming formats with digital card shuffling algorithms attract Gen Z users previously unreachable through static content. London and Manchester practitioners pivot toward pay-per-session models as subscription fatigue fragments British demand.
- Palmistry:Biometric image analysis tools process hand photographs through AI contour recognition for automated readings. German and French regulators debate whether facial recognition-derived profiles trigger enhanced GDPR protections, chilling feature rollout timelines.
- Astrology Consultations:One-to-one practitioner time captures premium margin pools through synchronous video or audio delivery. Swiss-hosted precision astronomical datasets create single-point dependency risks for algorithmic chart generation supporting these sessions.
Horoscopes absorb the bulk of installed capacity across European platforms; tarot readings are expanding most quickly as video-native formats penetrate younger demographics.
Distribution Channel:
Cost tier differentiation separates capital-intensive platform development from low-barrier practitioner entry, with compliance burden scaling directly with user scale and data processing depth.
- Online Platforms:Browser-based subscription portals with federated learning architectures enable GDPR-compliant personalization without centralized data storage. The EU Digital Services Act imposes algorithmic transparency mandates on recommender systems serving German and French users.
- Mobile Apps:Native iOS and Android applications with on-device computation dominate millennial and Gen Z adoption. Sanctuary and Co-Star anchor European presence through localized content partnerships and multilingual delivery.
- In-Person Sessions:Physical consultation venues in Paris, Berlin, and London maintain premium positioning through tactile ritual elements irreplaceable by digital formats. Higher fixed costs limit scalability compared to automated alternatives.
- Social Media:Algorithmic content distribution through TikTok and Instagram Reels drives discovery for independent practitioners. E-commerce VAT harmonization across member states simplifies cross-border payment processing for viral creators.
Mobile apps capture the steepest expansion trajectory among distribution channels; in-person sessions retain premium pricing power despite volume constraints.
End User:
Application context determines feature complexity and regulatory scrutiny, with organizational procurement introducing compliance requirements absent from individual consumption.
- Individuals:Personal guidance seekers represent the foundational demand base across all service types. Polish and Eastern European markets show rising mobile spirituality app downloads with limited domestic platform competition.
- Businesses:HR departments in Germany and the Netherlands experiment with team-building astrology workshops as employee engagement tools, introducing B2B procurement cycles and vendor qualification requirements.
- Spiritual Groups:Collective subscription arrangements for covens and meditation communities favor bundled service pricing and multi-user administrative dashboards. Group dynamics amplify word-of-mouth acquisition efficiency.
- Educational Institutions:University wellness programs and continuing education providers integrate astrological history courses and critical thinking modules about pseudoscience. Scientific skepticism in Nordic markets compresses addressable audience for these offerings.
Individuals command the dominant share of transaction volume; businesses are gaining share fastest as corporate wellness budgets expand.
Pricing Model:
Customer type and payment psychology shape revenue predictability, with subscription loyalty varying significantly across national markets.
- Subscription:Recurring monthly or annual commitments stabilize cash flow and enable customer lifetime value optimization. Germany's more subscription-loyal user base contrasts with British fragmentation toward micro-payments.
- Pay-Per-Session:Single-transaction pricing for consultations and tarot readings concentrates revenue volatility in the United Kingdom. Tarot practitioners in London and Manchester pivot toward this format as annual commitments decline.
- Freemium:Basic algorithmic chart generation with premium upsells for detailed interpretations and practitioner access. Early compliance with EU AI Act disclosure requirements creates competitive differentiation against non-compliant foreign competitors.
- Bundled Services:Combined horoscope, tarot, and consultation packages at discounted effective rates. Cross-border VAT complexity across 27 member states strains finance operations for multi-service subscription billing.
Subscription models retain the largest installed revenue base; pay-per-session formats are climbing the fastest as British behavioral preferences shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Millennial and Gen Z consumers in France, Germany, and the United Kingdom concentrate demand for subscription-based mobile astrology platforms. These three markets absorb the majority of regional revenue. Regulatory frameworks vary significantly across jurisdictions, shaping platform compliance architecture and feature availability.
France
Parisian consumers drive premium adoption of algorithmic natal chart services through iOS and Android ecosystems. The country's advertising standards authority tolerates spiritual wellness claims more permissively than predictive health assertions, creating regulatory breathing room for astrology-as-entertainment positioning. Marseille and Lyon host emerging practitioner collectives experimenting with hybrid digital-physical consultation formats.
Germany
Berlin anchors the continent's most subscription-loyal user base, stabilizing recurring revenue streams for platform operators. German regulators debate whether facial recognition-derived astrological profiles trigger enhanced GDPR protections, chilling biometric feature rollout timelines. Hamburg and Munich sustain dense networks of independent practitioners serving corporate wellness contracts with HR departments.
United Kingdom
London and Manchester practitioners pivot toward pay-per-session video formats as subscription fatigue fragments British demand toward micro-payment models. The UK advertising standards authority scrutinizes unsubstantiated predictive claims in spiritual marketing with increasing rigor. Edinburgh maintains a distinct market for traditional in-person consultations resistant to full digitization.
Switzerland
Zurich hosts precision astronomical datasets that create single-point dependency risks for algorithmic chart generation across the continent. Swiss-hosted ephemeris databases sustain decades of technical authority through Swiss Ephemeris calculations. Geneva practitioners command premium pricing for multilingual consultation services targeting cross-border clientele.
Poland
Warsaw and Kraków show rising mobile spirituality app downloads with limited domestic platform competition, offering first-mover positioning for localized content. Polish consumers demonstrate price sensitivity favoring freemium models over annual commitments. Wrocław hosts a nascent developer ecosystem building astrology-focused mobile applications for regional export.
Europe Astrology Market Competitive Landscape
Swiss precision-data specialists anchor one tier; American mobile-first platforms hold another; German compliance-engineered services occupy a third. The market structures around technical infrastructure depth rather than brand recognition alone. Three archetypes dominate: ephemeris-database custodians, AI-native chart generators, and practitioner-network aggregators. Competitive moves concentrate on GDPR-compliant personalization architecture and multilingual content localization.
Within the precision-calculation tier, Astrodienst AG exemplifies technical authority built through decades of astronomical data stewardship. Among mobile-native platforms, Co-Star, Inc. and Sanctuary occupy positions defined by algorithmic personalization and push-notification engagement models. These three entities represent distinct strategic approaches to European market penetration.
| Leading Market Players |
|---|
| Sanctuary |
| Susan Miller's Astrology Zone LLC |
| Astrodienst AG |
| OBRIO Limited |
| Horoscope.com Inc by Ingenio LLC. |
| Moonly Tech GmbH |
| The Pattern Inc |
| Astro-Vision Futuretech Pvt. Ltd. |
| Co-Star, Inc. |
| Others |
Pricing and Supply Chain Analysis
Ephemeris mathematics specialists concentrated in Switzerland and Germany command wage premiums that compress margin spreads between automated horoscope tiers and premium consultation services. Labor-cost differentials between Zurich-based astronomical data curators and Eastern European mobile developers enable three-tier pricing architectures that separate algorithmic self-service from practitioner-mediated guidance.
Pricing Analysis
Volume concentrates in automated daily horoscope feeds while margins pool in synchronous practitioner consultations. Pricing stratifies across premium natal chart interpretations, standard algorithmic forecasts, and economy-tier generic content based on computational depth and personalization fidelity. Cost compression in the British market intensifies as subscription fatigue pushes consumers toward micro-payment models. Individual users in Poland and Eastern Europe exhibit highest price sensitivity, while German corporate wellness buyers tolerate premium pricing for team-building astrology workshops.
Supply Chain Analysis
Workforce availability for classical ephemeris mathematics draws from Swiss, German, and British academic astronomy programs with limited pipeline expansion. Raw material dependencies center on precision astronomical datasets, proprietary house system algorithms, and biometric image processing libraries for palmistry features. Single-source vulnerability concentrates around Swiss-hosted ephemeris databases that anchor algorithmic chart generation continent-wide. Distribution runs through mobile app stores, browser-based subscription portals, and social media discovery channels reaching practitioner networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe astrology market sits in a technology-transition phase as generative AI architectures displace static ephemeris-based content engines with dynamic personalized interpretation systems.
For Market Incumbents: Acquire proprietary natal chart engine intellectual property to consolidate data moats against AI-native challengers. Sanctuary and Co-Star have demonstrated that machine learning-based transit pattern recognition captures millennial retention; incumbents lacking this capability face displacement. Investment in GDPR-compliant federated learning architectures defends against regulatory fragmentation that favors established compliance functions. For New Entrants and Emerging Players: TikTok and Instagram Reels offer the lowest customer acquisition cost route for independent practitioners building viral discovery audiences. Polish and Eastern European markets present the most penetrable geography given limited domestic platform competition and rising mobile spirituality app downloads. Freemium models with premium upsells for detailed interpretations align with regional price sensitivity and enable organic growth without heavy upfront marketing spend. For Investors and Strategic Acquirers: Re-rating potential sits with AI-native chart generators given EU AI Act disclosure requirements that create competitive differentiation against non-compliant foreign competitors. Long-term viability favors platforms combining algorithmic personalization with practitioner network aggregation, as pure automation faces regulatory scrutiny over advice classification. Watch for biometric data classification clarity from German and French regulators as the inflection signal for palmistry feature rollout timelines and associated revenue recognition.| Strategic Initiative | Industry Significance |
|---|---|
| GDPR-Compliant Personalization Engine Investment | Federated learning architectures satisfy data sovereignty demands from French and German users while reducing centralized compliance burden. |
| Multilingual Content Localization Partnership | Co-Star's European expansion demonstrates that native-language horoscope delivery captures retention in non-English markets. |
| Practitioner Network Aggregation Platform | Corporate wellness procurement in Germany and the Netherlands requires vetted practitioner pools with B2B vendor qualification. |
| Biometric Data Classification Compliance | Early alignment with evolving GDPR interpretations on facial recognition-derived profiles defends feature roadmap against regulatory chill. |
| Video-Native Tarot Streaming Capability | Real-time card reading formats on mobile platforms attract Gen Z demographics unreachable through static horoscope text. |
Research Methodology
Independent corroboration across platform engineering executives, astrology practitioner collectives, and EU regulatory affairs specialists underwrites the qualitative findings in this study. Primary interviews with mobile app developers, ephemeris database curators, and advertising standards compliance officers combined with secondary validation from SEC filings of listed spirituality platforms, Sensor Tower mobile download analytics, and GDPR enforcement action databases. Bottom-up triangulation across service-type demand curves and top-down cross-check against regional digital services tax revenues anchored market sizing.
Rate-of-change decomposition across the analysis window separates volume growth in automated horoscope delivery from value expansion in practitioner-mediated consultations. Segmentation dimensions modeled include service type, distribution channel, end-user category, and pricing model, with additional granularity on algorithmic versus human interpretive modality. CAGRs were derived from fitted trend extrapolation against historical adoption curves, incorporating EU Digital Services Act implementation timelines and generational cohort penetration rates as astrology-specific forecast inputs.
The model holds under stable regulatory interpretation of algorithmic advice classification; deviation in biometric data protection rulings or AI Act enforcement intensity would shift platform investment priorities and feature availability. Forecasts reflect documented assumptions regarding millennial and Gen Z adoption persistence, GDPR compliance cost trajectories, and ephemeris database licensing continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Africa Smart Card Market
Others
Smart Card Contactless Ticketing Market
Others
United States Bean Bags Market
Others
Coriolis Meters Market
Others
Infant Fever Stickers Market
Others
Europe Polycarbonate Sheets Market
Others
US Quantum Computing Market
Others
North America Automotive LED Lighting Market
Others
8K Technology Market
Others
Safety Instrumented System (SIS) Market
Others
High-End Servers Market
Others
Solar Lighting Tower Market
Others
Shisha Tobacco Market
Others
Digital Signage Media Player Market
Others
France Location-Based Services Market
Others
Europe Smart Homes Market