
 Foldable Smartphone Market | 2026-2036
Foldable Smartphone Market Size, Share, and Industry Trends Forecast 2026-2036
Foldable Smartphone Market Intelligence
The growing emphasis on mobile gaming and high-definition content creation is repositioning foldable devices from niche gadgets to mainstream productivity tools. Samsung Electronics leverages its first-mover advantage and display manufacturing capabilities to maintain a dominant market presence. In contrast, Huawei competes fiercely in the premium segment, particularly within the Chinese market, with its distinct book-style form factors. Google positions its devices with a software-centric approach, aiming to optimize the Android experience for foldable screens.
A foldable smartphone is a mobile device featuring a flexible display, typically based on AMOLED technology, that allows the screen to bend or fold. The core functionality relies on a complex mechanical hinge and ultra-thin glass or polymer layers to provide a large, tablet-like screen that collapses into a compact form. While book-style models cater to enterprise users and content creators, the clamshell product type holds strong appeal for its compact design. AMOLED displays are the standard for this category due to their flexibility and superior color contrast, which are critical for the folding mechanism.
Device manufacturers must secure FCC certification in the United States for radio frequency emissions and comply with CE marking requirements in Europe for safety and environmental standards. In India, adherence to the Bureau of Indian Standards (BIS) compulsory registration scheme is mandatory for market access. Future profitability will hinge on balancing premium feature sets with component cost reductions to broaden consumer accessibility.
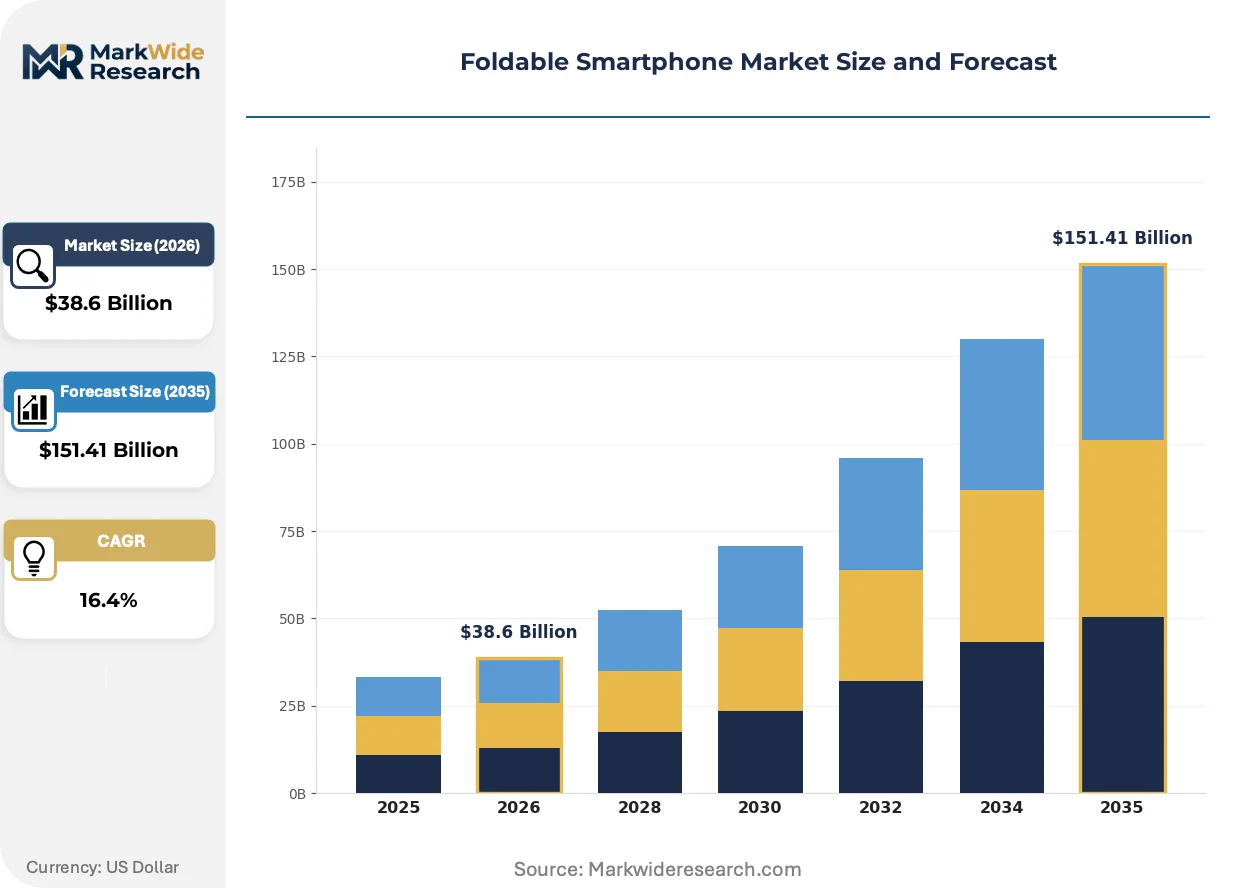
Market Dynamics
Enterprise demand for mobile productivity is the central force pulling foldable smartphones from a niche category into the mainstream. This transition relies on material science advancements in ultra-thin glass and hinge mechanisms to enable more durable designs.
Growth Catalysts
- Enterprise Productivity Demand:Enterprise users adopt foldable devices to improve mobile multitasking, consolidating phone and tablet functionality into one device.
- Material Science Innovation:Advances in ultra-thin glass and hinge mechanisms create more resilient designs, addressing early consumer concerns about screen fragility.
- Competitive Intensity in China:Domestic brands in China stimulate rapid innovation and consumer interest, creating a significant regional demand center for the technology.
Market Restraints
- Elevated Component Costs:Specialized flexible displays and intricate hinges create a high bill of materials, confining devices to the premium market segment.
- Perceived Device Fragility:Consumer concerns about the long-term durability of the folding mechanism and screen crease remain a significant purchase barrier.
- Substitution from Conventional Flagships:High-end bar-style smartphones offer comparable performance at a lower price, representing a strong alternative for many consumers.
Strategic Opportunities
- Emerging Market Penetration:Targeting markets like India with more accessible models can unlock volume growth beyond the highly competitive Chinese market.
- Optimized Gaming and Media Devices:Developing variants specifically for mobile gaming and high-definition content creation can capture dedicated and high-value user segments.
- Enterprise Software Integration:Partnering with enterprise software vendors to create bundled solutions can strengthen the value proposition for corporate fleet deployments.
Industry Challenges
- Component Supply Constraints:The limited number of suppliers for high-quality ultra-thin glass and complex hinges creates production bottlenecks and supply chain vulnerabilities for device manufacturers.
- Application Ecosystem Fragmentation:Ensuring consistent app performance and continuity across folded and unfolded states requires significant developer investment, which remains a key operational hurdle for the Android platform.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foldable Smartphone Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $151.41 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clamshell, Book Style, Hybrid, Multi-Fold Display Technology: OLED, AMOLED, Retina, Quantum Dot Use Case: Gaming, Business, Photography, Social Media, Content Creation End User: Tech Enthusiasts, Enterprise Users, Early Adopters, Mobile Professionals |
| Companies Covered | vivo, Apple, Samsung Electronics, Xiaomi, Motorola Mobility, OPPO, Honor, Google, Huawei, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foldable Smartphone Market Strategic Shifts & Innovations
The market's focus is shifting from the novelty of the folding mechanism itself toward software optimization and use-case specific design. This evolution is repositioning devices from luxury gadgets to practical tools for productivity and entertainment.
Under-display camera (UDC) technology embeds the front-facing sensor directly beneath the flexible display, eliminating the need for a notch or hole-punch. Premium device makers are adopting this innovation to provide a truly immersive, edge-to-edge viewing experience. The demand for this seamless aesthetic is overtaking the need for maximum front-camera image fidelity in the premium segment, shifting design priorities.
European Union 'Right to Repair' regulations are pressuring manufacturers to design for greater longevity and component accessibility. These rules present a substantial engineering hurdle for highly integrated foldable devices, whose sealed designs complicate repairs. Consequently, device makers active in Europe are re-evaluating assembly processes and hinge mechanisms to comply with these emerging standards.
A notable behavioral shift involves enterprise users adopting book-style foldables as their primary computing device, not just a secondary phone. This trend disrupts the traditional multi-device workflow, reducing reliance on separate tablets for tasks like document editing and video conferencing. This consolidation is particularly visible among mobile professionals in dense urban centers across Asia.
Foldable Smartphone Market Segmentation
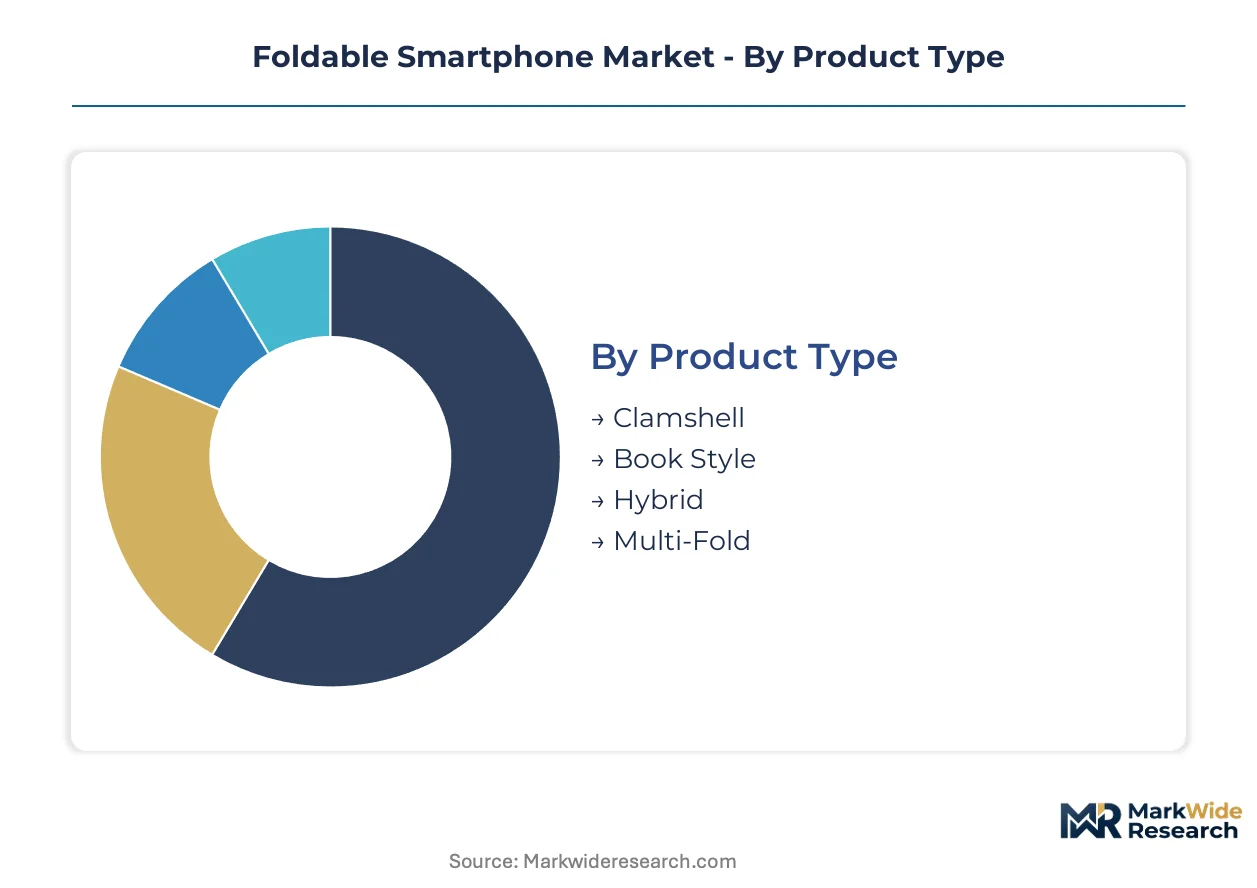
Market segmentation provides a granular understanding of the diverse factors influencing the foldable smartphone landscape. This detailed breakdown allows manufacturers to align product development with specific user needs and enables targeted marketing strategies across various consumer groups and technological preferences.
Product Type:
The upgrade and replacement cycles for foldable smartphones are increasingly influenced by the specific product form factors available to consumers.
- Clamshell:Clamshell devices feature a compact form factor that folds vertically, resembling traditional flip phones. Their smaller footprint appeals to users prioritizing portability and fashion, particularly in markets like South Korea.
- Book Style:Book-style models unfold horizontally to reveal a larger, tablet-like display, enhancing productivity and content consumption. Enterprise users in urban centers across China adopt these for multitasking capabilities.
- Hybrid:Hybrid designs explore novel folding mechanisms that blend aspects of both clamshell and book-style devices, offering unique user experiences.
- Multi-Fold:Multi-fold smartphones incorporate multiple hinges, allowing for even larger screen real estate when fully unfurled, targeting specialized power users.
Volume placements concentrate in Clamshell devices; the faster expansion belongs to Book Style models.
Display Technology:
Component cost structures significantly differentiate foldable smartphone offerings based on their display technology.
- AMOLED:Active-Matrix Organic Light-Emitting Diode (AMOLED) displays are standard for foldable devices due to their inherent flexibility, high contrast ratios, and efficient power consumption. Their widespread adoption ensures vibrant visuals across diverse models.
- OLED:Organic Light-Emitting Diode (OLED) technology provides self-illuminating pixels, enabling thinner panels and superior black levels compared to traditional LCDs. This technology underpins the visual quality of most premium foldable devices.
- Retina:Retina displays, a branding term for high pixel density screens, offer crisp visuals and are often associated with specific device ecosystems.
- Quantum Dot:Quantum Dot technology enhances color accuracy and brightness, often integrated with OLED or LCD panels to improve overall display performance.
Higher margin opportunities are present in devices leveraging AMOLED technology, while OLED remains foundational for core product lines.
Use Case:
Specific application requirements drive hardware and software optimization within the foldable smartphone ecosystem.
- Gaming:Gaming-centric foldable devices prioritize high refresh rates, powerful processors, and optimized thermal management to deliver immersive mobile gaming experiences. Demand from younger demographics in Southeast Asia is particularly strong.
- Business:Business use cases emphasize multitasking capabilities, robust security features, and seamless integration with enterprise software, supporting mobile professionals. Enterprise users in Germany value these devices for productivity.
- Photography:Photography-focused foldables integrate advanced camera systems and software, appealing to users who prioritize high-quality image capture.
- Social Media:Social media use cases leverage the larger screen for enhanced content viewing and interaction, catering to users who spend significant time on platforms.
- Content Creation:Content creation applications benefit from expansive screens for video editing, graphic design, and note-taking, attracting professional and semi-professional creators.
The fastest market expansion occurs within the Gaming segment, while Business applications underpin consistent revenue streams.
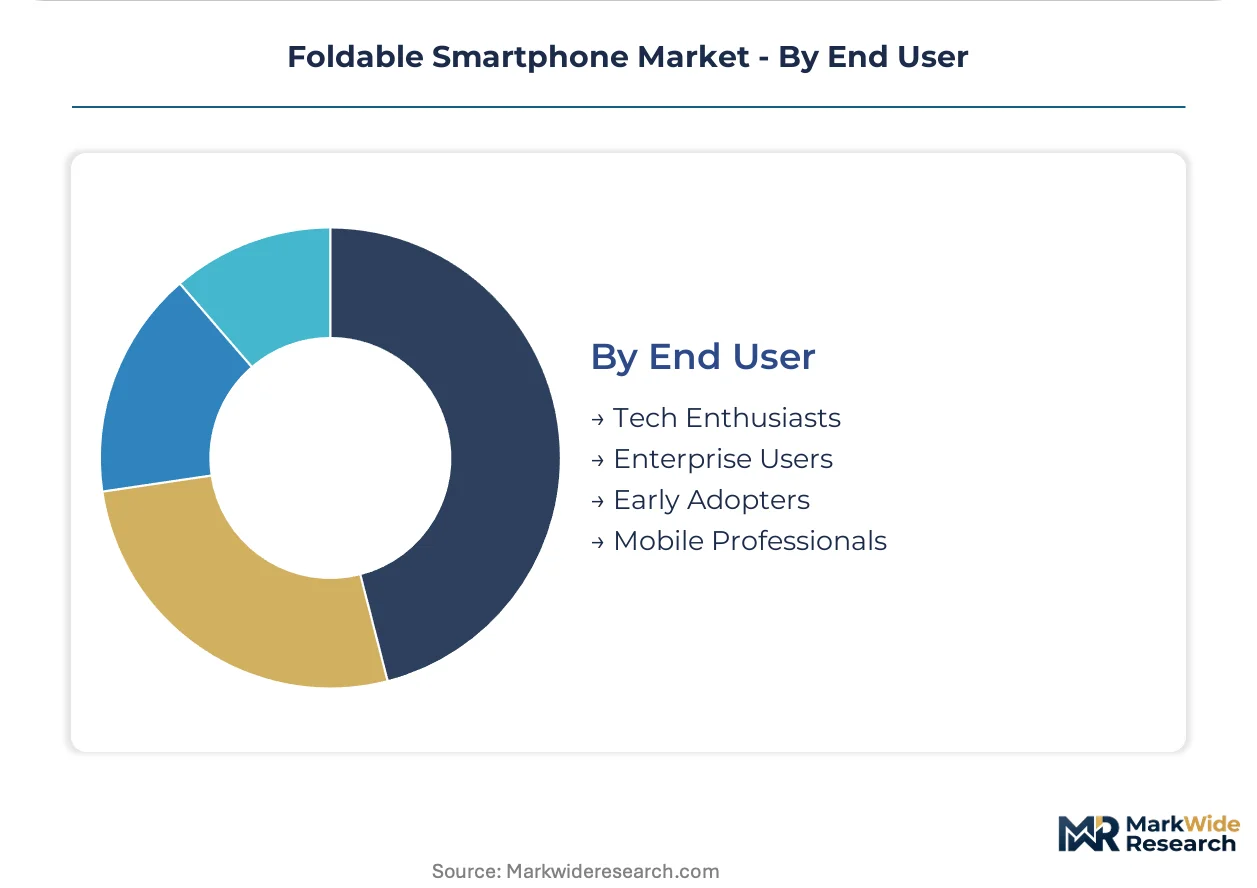
End User:
Understanding distinct customer types is critical for tailoring product features and marketing strategies in the foldable smartphone market.
- Tech Enthusiasts:Tech enthusiasts are early adopters keenly interested in cutting-edge technology and premium features, driving initial sales and product feedback.
- Enterprise Users:Enterprise users represent organizations deploying foldable devices for their workforce, seeking enhanced productivity, document management, and secure communication. Their demand is a central force pulling foldables into the mainstream, especially in the United States.
- Early Adopters:Early adopters are consumers who purchase new products shortly after launch, often willing to pay a premium for innovative features and status.
- Mobile Professionals:Mobile professionals are individual users who rely on their devices for work-related tasks while frequently on the go, valuing the large screen for multitasking and portability. This segment often overlaps with early adopters in major metropolitan areas.
The Enterprise Users segment demonstrates significant growth potential, while Early Adopters continue to drive initial product cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global foldable smartphone market exhibits a clear divide between production hubs and high-growth consumption regions. Manufacturing capabilities often concentrate in East Asia, while demand expands across diverse global consumer bases. This dynamic shapes regional investment and market access strategies.
China
China drives significant demand for book-style foldables, fueled by intense domestic brand competition and enterprise users in urban centers. Adherence to GB standards ensures product quality and market entry for new devices. The Yangtze River Delta region, including Shanghai, serves as a major hub for both design and manufacturing innovation.
India
India represents a strategic market for accessible foldable models, targeting volume growth and mobile gaming segments. The Bureau of Indian Standards (BIS) compulsory registration scheme governs market entry for all electronic devices. Bengaluru's tech-savvy consumer base demonstrates early adoption of new mobile form factors.
South Korea
South Korea shows strong consumer preference for compact clamshell foldable devices, prioritizing portability and fashion-conscious design. Manufacturers must comply with KC certification requirements for electronic product safety. Seoul's metropolitan area acts as a trendsetter for mobile technology adoption and product launches.
United States
The United States sees substantial demand from enterprise users and mobile professionals seeking enhanced productivity tools. Device manufacturers must secure FCC certification for radio frequency emissions before market release. Silicon Valley companies frequently pilot new foldable form factors for corporate fleet deployments.
Germany
Germany's enterprise sector values foldable devices for business applications, emphasizing multitasking capabilities and robust security features. All devices require CE marking to demonstrate compliance with European safety and environmental standards. Munich's strong engineering base supports the adoption of high-performance mobile computing solutions.
Foldable Smartphone Market Key Industry Players
Top-tier vendors anchor the premium foldable smartphone segment, while a growing contingent of challengers focuses on broader market accessibility. The market structure exhibits a tiered consolidation, with established electronics giants leading innovation. Strategic archetypes include integrated display manufacturers, software-centric innovators, and aggressive regional players. Companies pursue technology licensing agreements and strategic partnerships to accelerate product development and expand market reach.
On the premium-tier vector, Samsung Electronics exemplifies a vertically integrated approach, leveraging its advanced display manufacturing capabilities to maintain a dominant market presence. Huawei, a prominent Chinese OEM, occupies a strong position in the premium segment, particularly within its home market, with distinct book-style form factors. Google represents the software-centric approach, optimizing the Android experience for foldable form factors across its device ecosystem and emphasizing user experience. These companies collectively push the boundaries of design and functionality in the high-end foldable space, influencing broader market trends.
| Leading Market Players |
|---|
| vivo |
| Apple |
| Samsung Electronics |
| Xiaomi |
| Motorola Mobility |
| OPPO |
| Honor |
| Huawei |
| Others |
Cost & Logistics Intelligence
The premium-to-mid-range divergence in foldable smartphones directly influences both pricing and supply chain configurations. This stratification emerges from the high cost of specialized components for top-tier devices versus more accessible models for broader consumer adoption.
Pricing Analysis
Short lead times for cutting-edge foldable displays command a premium, reflecting the advanced manufacturing processes involved. The pricing model primarily follows a tiered premium-mid-economy structure, with higher margins for devices integrating AMOLED technology and superior hinge mechanisms. Brand premium and the inclusion of advanced features like under-display cameras also drive price differentiation. Pricing pressure stems from increased competition, particularly from domestic brands in China, which intensifies efforts to reduce component costs. Mainstream consumers in emerging markets exhibit the highest price sensitivity.
Supply Chain Analysis
Dual-sourcing requirements for critical flexible displays and advanced hinges mitigate single-vendor risks for device manufacturers. Geographic supply concentration for these highly specialized components centers on South Korea and China, which host the primary fabrication facilities. Raw material dependencies include ultra-thin glass, flexible AMOLED panels, and complex alloy hinge mechanisms. Single-source vulnerability for these specialized inputs represents a significant supply chain risk. Distribution runs through established direct-to-consumer channels and strategic partnerships with mobile network carriers across global markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The foldable smartphone market presents a vertical-integration race, with manufacturers pursuing in-house display and hinge production to secure competitive advantage and control component costs.
For Market Incumbents: Extend proprietary display and hinge technology leadership to counter emerging regional challengers. Invest in next-generation material science for enhanced durability and lighter form factors, addressing consumer concerns about screen fragility. Cultivate a robust patent portfolio around folding mechanisms and ultra-thin glass production. Leverage existing brand equity and global distribution networks to maintain premium positioning against increasing component cost erosion.
For New Entrants and Emerging Players: European Union 'Right to Repair' regulations in Europe open a window for modular designs and accessible repair services. Target the mid-range segment with more accessible models, particularly in high-volume markets like India and Southeast Asia, focusing on specific use cases such as optimized mobile gaming. A software-first go-to-market angle, emphasizing Android optimization for foldable screens, can differentiate offerings from hardware-centric competitors.
For Investors and Strategic Acquirers: Re-rating potential sits with component specialists in ultra-thin glass and advanced hinge mechanisms given expanding market demand. Focus on firms with strong intellectual property in material science and precision engineering, offering long-term viability through sustained growth in enterprise adoption and mainstream consumer segments. The signal to watch is a significant reduction in the bill of materials for flexible displays, indicating broader market accessibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Component Vertical Integration | Manufacturers gain control over critical supply and reduce reliance on external vendors. |
| Software Ecosystem Optimization | Enhances user experience and application continuity across folded and unfolded states. |
| Emerging Market Expansion | Unlocks volume growth and broadens consumer accessibility beyond premium segments. |
| Durability R&D | Addresses core consumer concerns about device longevity and screen crease visibility. |
| Enterprise Solution Bundling | Strengthens value proposition for corporate fleet deployments and mobile professionals. |
Research Approach
Multi-period observation of device sales, patent filings, and consumer sentiment anchored the trend analysis, supplemented by interviews with industry stakeholders. This involved engaging device manufacturers, display suppliers, software developers, and enterprise IT managers. Secondary validation included FCC certifications, BIS registrations, trade data, and financial reports from publicly traded companies. Bottom-up market sizing was triangulated with top-down industry reports.
An input-output matrix structured the quantitative forecast, integrating diverse market drivers and constraints across the analysis window. Segmentation dimensions modeled included product type, display technology, use case, end user, and regional adoption patterns. Compound annual growth rates were derived from historical data and projected growth factors, incorporating industry-specific forecast inputs such as material science advancements and regulatory compliance costs.
The model assumes a particular technology adoption path; alternative pathways for micro-LED displays or rollable form factors would alter the outlook significantly. Forecasts reflect assumptions regarding component supply stability and consumer preference evolution. Deviation in hinge mechanism breakthroughs or ultra-thin glass production efficiency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Post Consumer Recycled Bottles Market
Others
Deep Sea Mining Market
Others
IT Device Market
Others
Global Simulation in Healthcare Market
Others
Legal Services Market
Others
Global Extruded Plastics Market
Others
Global Tobacco Market
Others
Pickup Truck Market
Others
Digital Signage Media Player Market
Others
Land Surveying Equipment Market
Others
Telecom Transformers Market
Others
Rugged Tablet Market
Others
Heat Treatment Furnace Market
Others
Gas Holders Market
Others
Agitation System Market
Others
AC Switchgear Market