
 Video Conferencing Hardware Market | 2026-2036
Video Conferencing Hardware Market Size, Share, and Industry Trends Forecast 2026-2036
Video Conferencing Hardware Market Insights
Healthcare is rebalancing the end-use mix as telemedicine infrastructure becomes permanent across hospital networks and outpatient chains. Cisco Systems, Inc. anchors its position through deep enterprise channel control and integrated room system architectures. Yealink Network Technology Co., Ltd. competes aggressively on price-performance ratios in the mid-market segment. Logitech International S.A. leverages its consumer electronics supply chain to sustain rapid product refresh cadences.
Video conferencing hardware encompasses dedicated audiovisual endpoints purpose-built for synchronous remote collaboration, typically integrating 4K imaging sensors, beamforming microphone arrays, and DSP-optimized acoustic processing to deliver sub-150ms latency in full-duplex communication. Cameras dominate value capture due to sensor complexity and optical stabilization requirements, while cloud-based technology configurations expand fastest as enterprises shed on-premises infrastructure maintenance burdens. Control systems concentrate margin pools where Crestron Electronics, Inc. and Barco NV specialize in programmable room automation that commands premium pricing against plug-and-play alternatives.
The FCC equipment authorization process gates U.S. market entry for wireless-enabled endpoints, while CE marking under the EU Radio Equipment Directive shapes European product development roadmaps and testing budgets. Japan's MIC radio law compliance adds a third certification layer for vendors targeting METI-influenced corporate procurement frameworks. Stakeholders must monitor how AI-enabled noise cancellation and auto-framing capabilities trigger refreshed accessibility standards from the FCC and ETSI, as these will force hardware redesign cycles before codec improvements alone would justify replacement.
Market Dynamics
Enterprise migration from on-premises infrastructure to cloud-native meeting platforms is compressing refresh cycles and reshaping how hardware vendors capture lifetime value.
Growth Catalysts
- FCC Equipment Authorization:Wireless-enabled endpoints meeting Part 15 rules gain faster channel clearance in the United States, accelerating product launch velocity for certified suppliers.
- Telemedicine Infrastructure Hardening:Hospital networks and outpatient chains across Germany and Japan are embedding video endpoints into permanent clinical workflows, creating durable replacement demand.
- Beamforming Microphone Arrays:DSP-optimized acoustic processing is lowering deployment complexity in mid-market conference rooms previously served by professional AV integrators.
Market Restraints
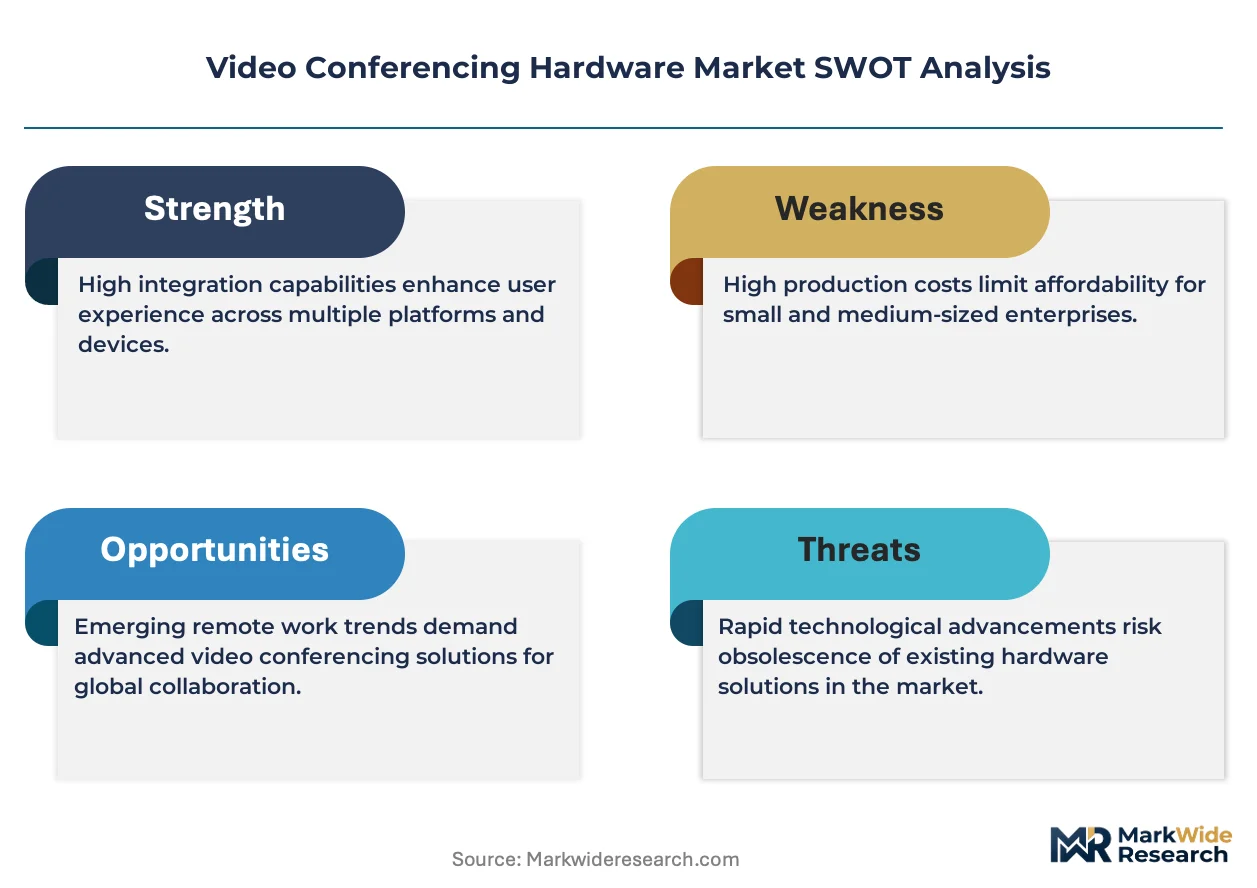
- Sensor Supply Concentration:4K imaging sensor fabrication concentrates among a limited set of Asian foundries, exposing vendors to allocation risk during capacity crunches.
- Multi-Jurisdiction Certification Burden:CE marking under the EU Radio Equipment Directive, Japan's MIC radio law compliance, and FCC authorization collectively extend product development timelines by 8-14 months.
- Software-Defined Substitution:Cloud-based virtual meeting rooms running on commodity laptops are displacing dedicated hardware in price-sensitive small-business segments.
Strategic Opportunities
- India's PLI Scheme:Production-linked incentives for electronics manufacturing are attracting contract assembly investment, creating localized supply capacity for Asia-Pacific distribution.
- AI-Enabled Accessibility Mandates:Anticipated FCC and ETSI refreshed standards for auto-framing and noise cancellation will force replacement cycles ahead of codec obsolescence.
- Control System Convergence:Programmable room automation integrating lighting, HVAC, and AV endpoints is opening premium-margin opportunities in corporate headquarters and government facilities.
Industry Challenges
- Firmware Security Certification:Meeting Common Criteria or FIPS 140-2 validation for federal procurement requires specialized engineering talent scarce among mid-tier hardware vendors.
- Legacy Codec Integration:Enterprises maintaining H.323 infrastructure demand backward-compatible endpoints, fragmenting R&D resources across multiple signaling protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Conferencing Hardware Market |
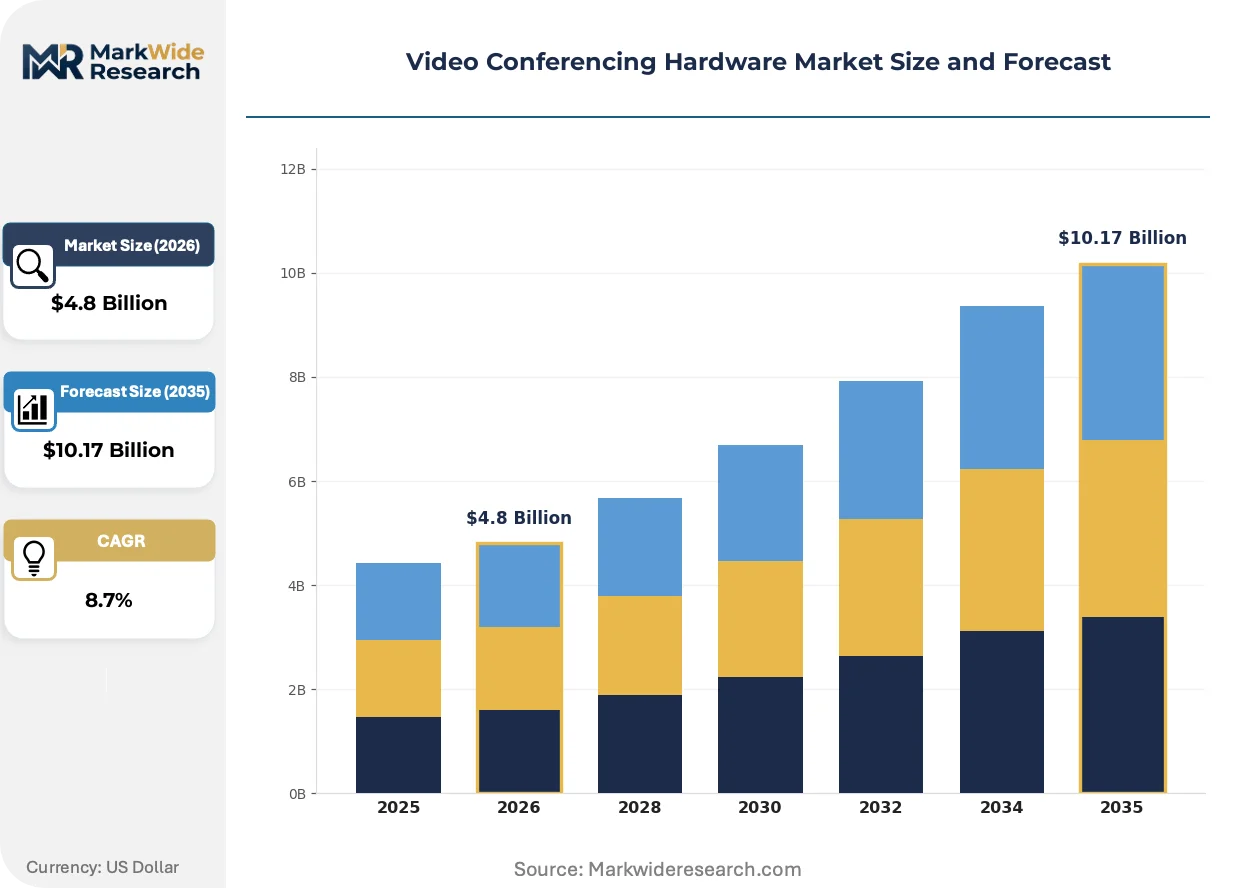
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cameras, Microphones, Speakers, Control Systems Technology: Wi-Fi, Bluetooth, Wired, Cloud-based End User: Enterprises, Educational Institutions, Government, Healthcare Installation: On-premises, Remote, Bundled Solutions, DIY |
| Companies Covered | Cisco Systems, Inc., Logitech International S.A., Huawei Technologies Co., Ltd., Yealink Network Technology Co., Ltd., EPOS Group A/S, GN Audio A/S (Jabra), Barco NV, AVer Information Inc., Crestron Electronics, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Conferencing Hardware Market Trends and Innovations
Computational imaging and edge AI are converging to redefine performance benchmarks, while regulatory accessibility mandates and procurement model evolution are reshaping how value flows through the channel.
Neural processing units embedded directly within camera SoCs is rewriting latency benchmarks for real-time auto-framing and speaker tracking. Healthcare networks in the United States and Germany are deploying these endpoints in surgical observation suites and telediagnostic pods. The compression of processing to the device edge is reducing dependency on cloud compute for real-time features, enabling offline operation in secure facilities.
The EU AI Act's risk classification framework is imposing documentation and conformity assessment burdens on biometric-enabled endpoints with facial recognition capabilities. Vendors must now maintain technical files demonstrating algorithmic transparency and bias mitigation. High-stakes corporate boardrooms and government secure facilities in France and Germany are prioritizing compliant hardware, creating certification-driven segmentation between premium and standard tiers.
Hardware-as-a-service contracting is displacing capital expenditure procurement in mid-market enterprises seeking predictable operating costs. Systems integrators and managed service providers are capturing ongoing revenue streams through bundled endpoint management, maintenance, and refresh guarantees. This model has penetrated deepest in the United States federal contractor ecosystem and United Kingdom professional services firms facing hybrid-work compliance mandates.
Video Conferencing Hardware Market Segmentation
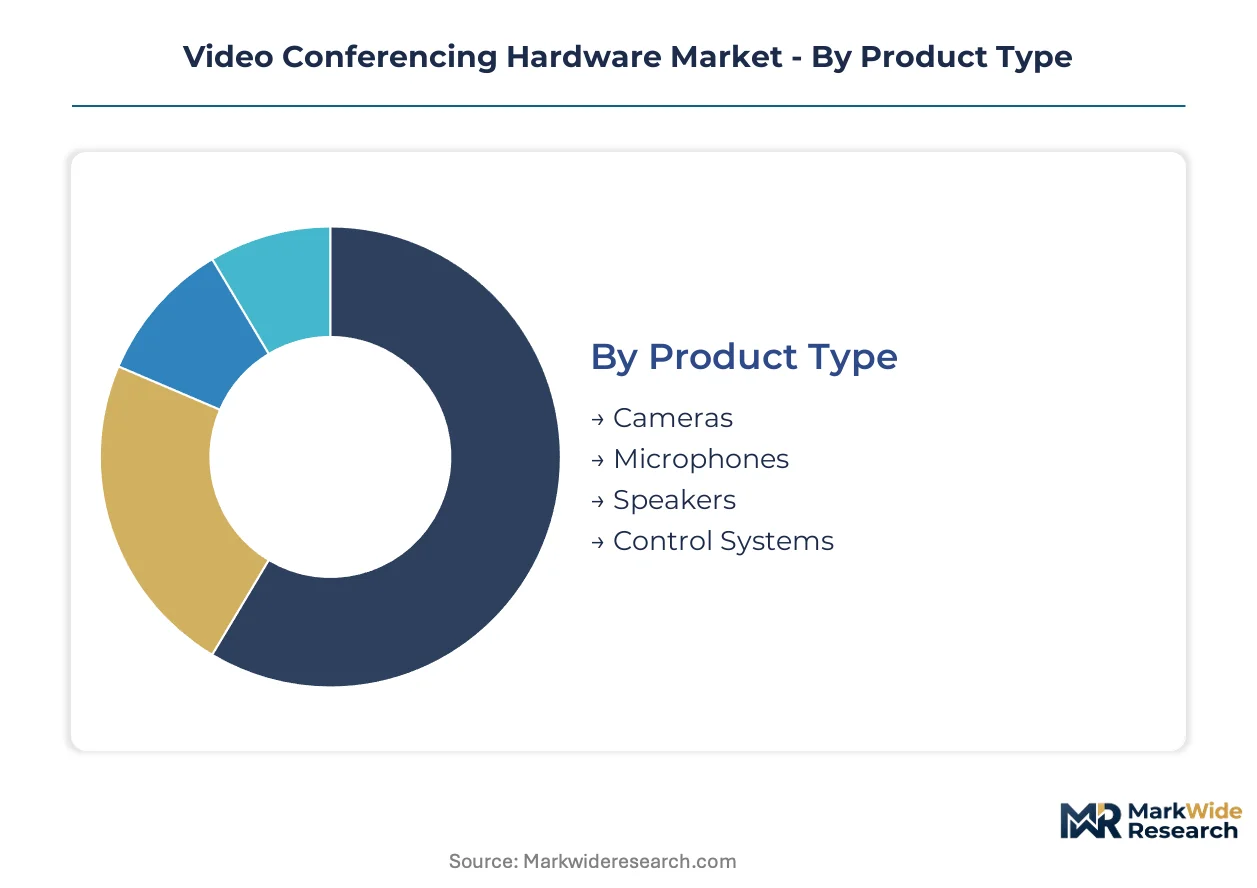
Hardware refresh cycles and cloud migration patterns create divergent demand profiles across product categories. Segment-specific procurement behaviors reveal where vendors capture recurring revenue versus one-time replacement sales.
Product Type:
Upgrade trajectories vary sharply by component complexity and failure modes, with optical systems commanding premium replacement schedules.
- Cameras:4K imaging sensors with optical stabilization and neural processing units for auto-framing dominate value capture. Hospital networks in Germany and the United States deploy these in surgical observation suites, where latency requirements below 150 milliseconds justify accelerated refresh cycles.
- Control Systems:Programmable room automation integrating lighting, HVAC, and AV endpoints commands the highest margins through Crestron and Barco architectures. Federal facilities and corporate headquarters in Washington D.C. and Frankfurt prioritize these for centralized facility management.
- Microphones:Beamforming arrays with DSP-optimized acoustic processing reduce deployment complexity for mid-market conference rooms.
- Speakers:Full-duplex audio endpoints complete the hardware stack but face commoditization pressure from integrated soundbars.
Volume placements concentrate in Cameras; the faster expansion belongs to Control Systems.
Technology:
Connectivity architecture determines where infrastructure ownership burdens fall between IT departments and managed service providers.
- Cloud-based:Endpoints offloading processing to cloud-native meeting platforms eliminate on-premises codec maintenance. Professional services firms in the United Kingdom and federal contractors adopt hardware-as-a-service models to convert capital expenditure into predictable operating costs.
- Wired:Ethernet-connected systems persist in secure facilities requiring air-gapped operation. Government SCIFs and financial trading floors in New York and London mandate these configurations for Common Criteria compliance.
- Wi-Fi:Wireless-enabled endpoints accelerate deployment flexibility but trigger FCC Part 15 authorization delays.
- Bluetooth:Peripheral pairing protocols serve huddle room and personal workspace configurations with lower complexity.
Deployment scale favors Wired infrastructure; Cloud-based configurations are climbing the fastest.
End User:
Procurement sophistication and compliance mandates segment buyer behavior across institutional categories.
- Healthcare:Telemedicine infrastructure hardening drives durable replacement demand as hospital networks embed video endpoints into permanent clinical workflows. Outpatient chains across Japan and Germany require HIPAA-equivalent and MDR-aligned certification for diagnostic-grade deployments.
- Enterprises:Hybrid-work directives sustain above-average procurement velocity, with Fortune 500 headquarters refreshing room systems on compressed three-year cycles.
- Government:FIPS 140-2 validation requirements restrict vendor pools to suppliers with specialized federal engineering talent.
- Educational Institutions:Budget constraints favor price-performance ratios over premium feature sets, with state university systems standardizing on mid-market bundles.
Enterprise accounts drive current volume; Healthcare is gaining share fastest.
Installation:
Service model selection reflects internal IT capacity and facility complexity across buyer segments.
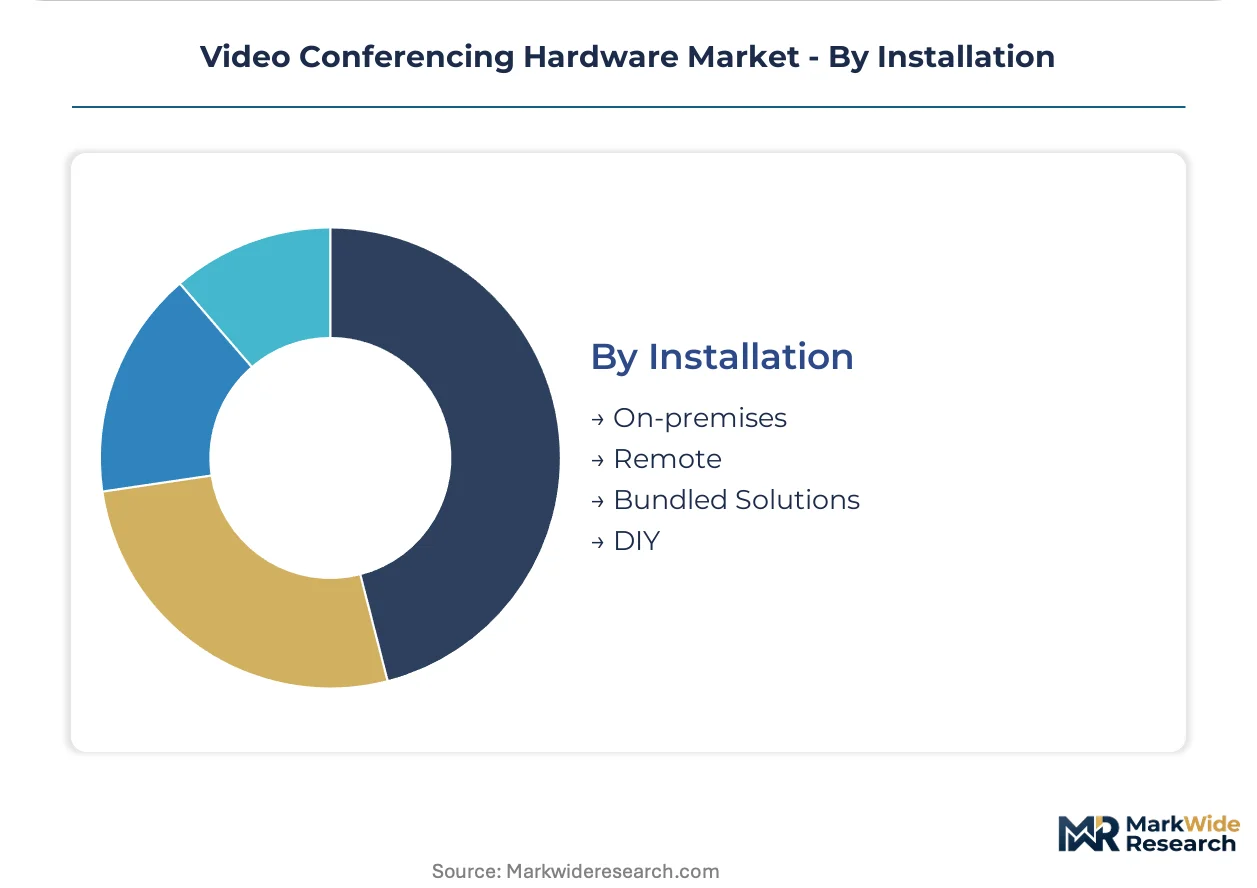
- Bundled Solutions:Systems integrators package hardware, installation, and managed services into multi-year contracts. United Kingdom professional services firms and United States federal contractors facing hybrid-work compliance mandates favor this procurement structure.
- On-premises:Traditional capital expenditure models persist where facilities teams retain AV expertise internally.
- Remote:Distributed deployment protocols accelerate rollout across multi-site organizations without travel costs.
- DIY:Self-installation options penetrate small-business segments where software-defined virtual meeting rooms on commodity hardware displace dedicated endpoints.
On-premises deployment retains volume leadership; Bundled Solutions show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Asian electronics clusters while consumption tilts toward North American and European enterprise buyers. Foundry capacity for imaging sensors and DSP silicon shapes supply availability. Regulatory certification timelines vary sharply across destination markets.
United States
Federal hybrid-work directives sustain above-average procurement velocity across Washington D.C. and corporate headquarters corridors. FCC Part 15 equipment authorization gates wireless-enabled endpoint launches, extending development timelines for uncertified suppliers. Silicon Valley and Austin technology clusters drive R&D concentration for neural processing units and edge AI features.
Germany
Hospital networks and outpatient chains embed video endpoints into permanent clinical workflows, creating diagnostic-grade replacement demand. CE marking under the EU Radio Equipment Directive shapes product development roadmaps and testing budgets for wireless configurations. Frankfurt and Munich corporate facilities prioritize programmable room automation for centralized facility management.
Japan
METI-influenced corporate procurement frameworks mandate MIC radio law compliance for wireless-enabled endpoints entering enterprise channels. Telemedicine infrastructure hardening across Tokyo and Osaka hospital networks drives durable demand for low-latency surgical observation suites. Nagoya industrial clusters supply precision optical components for 4K imaging sensor assemblies.
India
Production-linked incentive schemes for electronics manufacturing attract contract assembly investment, creating localized supply capacity for Asia-Pacific distribution. State university systems standardize on mid-market bundles under budget constraints. Bengaluru and Hyderabad technology corridors emerge as deployment hubs for cloud-native meeting platform integrations.
United Kingdom
Professional services firms facing hybrid-work compliance mandates favor hardware-as-a-service procurement structures with bundled endpoint management. London financial trading floors mandate wired Ethernet configurations for Common Criteria compliance in secure facilities. Systems integrators capture ongoing revenue streams through multi-year managed service contracts.
Video Conferencing Hardware Market Competitive Landscape
Top-tier vendors anchor enterprise channel control and integrated room system architectures, while mid-market specialists compete on price-performance ratios and rapid refresh cadences. The vendor base stratifies across three tiers: full-stack platform providers, component specialists, and regional assembly houses. Two dominant strategic archetypes emerge: deep vertical integration into optical and acoustic engineering, and hardware-as-a-service contracting to capture lifetime value. Competitive moves concentrate on M&A for DSP talent and capacity expansion in India under PLI schemes.
Among the named players in this study, Cisco Systems, Inc. and Yealink Network Technology Co., Ltd. exemplify contrasting archetypes within the enterprise tier. Logitech International S.A. occupies a position that bridges consumer electronics supply chain velocity with commercial endpoint requirements. These three anchors represent the spectrum from deep enterprise integration to rapid product refresh capabilities.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Logitech International S.A. |
| Huawei Technologies Co., Ltd. |
| Yealink Network Technology Co., Ltd. |
| EPOS Group A/S |
| GN Audio A/S (Jabra) |
| Barco NV |
| AVer Information Inc. |
| Crestron Electronics, Inc. |
| Others |
Pricing and Supply Chain Analysis
Captive supply of 4K imaging sensors and DSP silicon anchors both component security and margin capture for tier-one vendors, while outsourced assembly under India's PLI scheme enables price-competitive positioning for mid-market challengers seeking channel share.
Pricing Analysis
Short lead-time premiums for FCC-authorized wireless endpoints separate certified suppliers from competitors facing 8-14 month approval delays. Three-tier pricing structure across premium, standard, and economy levels aligns with certification grade and after-sales bundling intensity. Pricing pressure stems from software-defined virtual meeting rooms displacing dedicated hardware in small-business segments. Educational institutions exhibit highest price sensitivity, while federal facilities with FIPS 140-2 mandates show lowest.
Supply Chain Analysis
Dual-sourcing requirements for 4K imaging sensors and beamforming microphone arrays force buyers to qualify Taiwanese and South Korean foundries alongside Japanese precision optical suppliers. Component dependencies center on DSP silicon, acoustic membranes, and rare-earth magnet assemblies for speaker drivers. Single-source vulnerability concentrates in neural processing unit fabrication. Distribution runs through systems integrators and managed service providers capturing hardware-as-a-service revenue streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as multi-jurisdiction certification burdens and firmware security requirements force mid-tier vendors toward exit or acquisition, concentrating share among full-stack platform providers with federal engineering capabilities.
For Market Incumbents: To counter software-defined substitution in the small-business tier, deepen backward integration into optical sensor design and expand captive DSP engineering teams. Lock federal channel access through accelerated FIPS 140-2 validation pipelines, converting compliance scarcity into pricing power against uncertified rivals.
For New Entrants and Emerging Players: Systems integrators serving United Kingdom professional services firms represent the most penetrable channel for hardware-as-a-service market entry. Target India's state university systems with price-optimized mid-market bundles under localized PLI assembly. Secure initial scale through white-label partnerships with established managed service providers before direct brand investment.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by full-stack platform providers seeking DSP talent and federal certification capabilities. Long-term viability favors vendors with neural processing unit design autonomy and multi-jurisdiction regulatory engineering benches. Watch for FCC accessibility mandate refresh timing as replacement cycle inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FIPS 140-2 Certification Investment | Federal procurement access locks out uncertified competitors from Washington D.C. channel. |
| Neural Processing Unit Integration | Edge AI auto-framing meets anticipated FCC accessibility mandates ahead of codec obsolescence. |
| India PLI Assembly Expansion | Localized supply capacity reduces landed cost for Asia-Pacific distribution networks. |
| Hardware-as-a-Service Contracting | Predictable operating cost models displace capital expenditure procurement in mid-market enterprises. |
| Beamforming Array DSP Acquisition | Specialized acoustic engineering talent scarcity drives consolidation toward platform providers. |
Research Methodology
SEC filings, hyperscaler partnership disclosures, and FCC equipment authorization databases formed the secondary backbone, cross-referenced with primary interviews across AV systems integrators, federal procurement officers, hospital biomedical engineers, and enterprise IT directors. Bottom-up endpoint shipment analysis triangulated against top-down enterprise IT spending surveys across the analysis window.
Historical trendline analysis for imaging sensor cost curves and codec licensing patterns informed projection modeling across product type, connectivity architecture, end-user vertical, and installation service model dimensions. CAGRs derived from segmented growth rate reconciliation against aggregate market boundary conditions, with specific weighting for telemedicine infrastructure hardening velocity and federal hybrid-work directive durability.
Caveats apply where FCC accessibility mandate timing or EU AI Act biometric compliance enforcement could materially shift the outlook. Deviation in foundry capacity allocation for neural processing silicon would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Griffin Beaker Market
Others
Propanil Market
Others
Europe Digital Experience Platform Market
Others
US Mobile MRI Services Market
Others
Latin America Smart Home Market
Others
Cloud Digital Video Recorder Market
Others
Internet of Things Testing Market
Others
North America Forklift Truck Market
Others
Fibert Market
Others
Profilometer Market
Others
Air Separation Module Kit Market
Others
Middle East Paper Making Machine Market
Others
Europe Indoor Air Purification Market
Others
Infant Positioning Aids Market
Others
Football Sportswear Market
Others
US Legal Services Market