
 Professional Service Automation Market | 2026-2036
Professional Service Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Professional Service Automation Market Intelligence
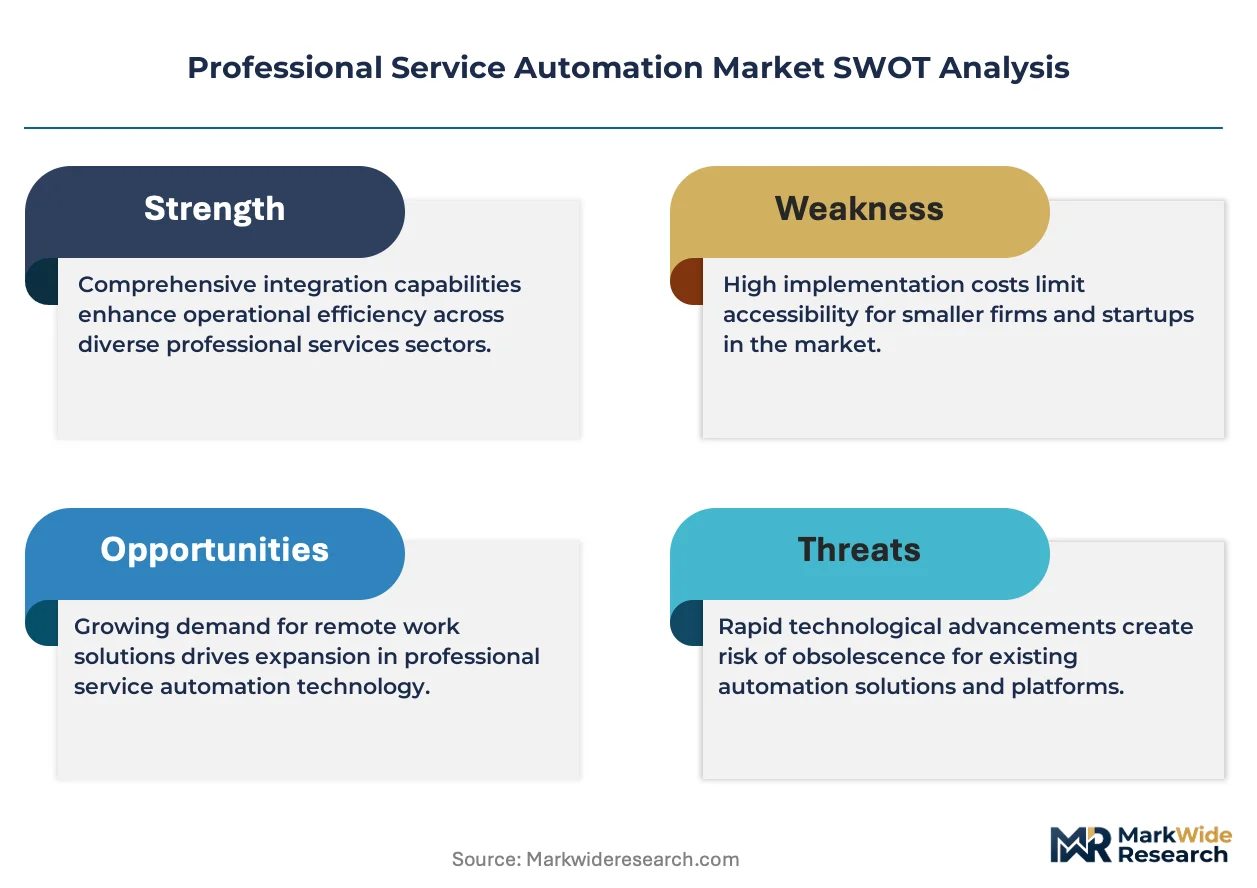
Demand for professional service automation is rotating from large corporations towards medium-sized businesses seeking scalable, cloud-based solutions. While established players like SAP SE and Oracle Corporation sustain strong positions in the large enterprise segment, other vendors are targeting this shift. ConnectWise Inc. specializes in platforms for technology solution providers and IT consultants. Meanwhile, Upland Software positions its portfolio of specialized tools to serve niche verticals like consulting agencies and marketing companies.
Professional Service Automation (PSA) software provides an integrated platform for managing the core business processes of service-based organizations. These systems create a single source of truth for key performance indicators, including project profitability and resource utilization. The primary commercial purpose is to automate the entire project lifecycle, from initial quoting and staffing to time tracking and final invoicing. Cloud-based deployment models now command the market over on-premise options. Within the solution offering, project management and resource management modules represent the core functionalities sought by most customer types.
Data governance frameworks directly impact platform design and procurement. Europe's GDPR and the US's HIPAA necessitate features that ensure client data privacy and controlled access, particularly for legal and consulting firms. Additionally, adherence to quality management standards like ISO 9001 can be a key differentiator for vendors targeting large corporations. Stakeholders must evaluate the trade-offs between adopting a single, comprehensive PSA suite versus integrating multiple best-of-breed applications to meet specific operational demands.
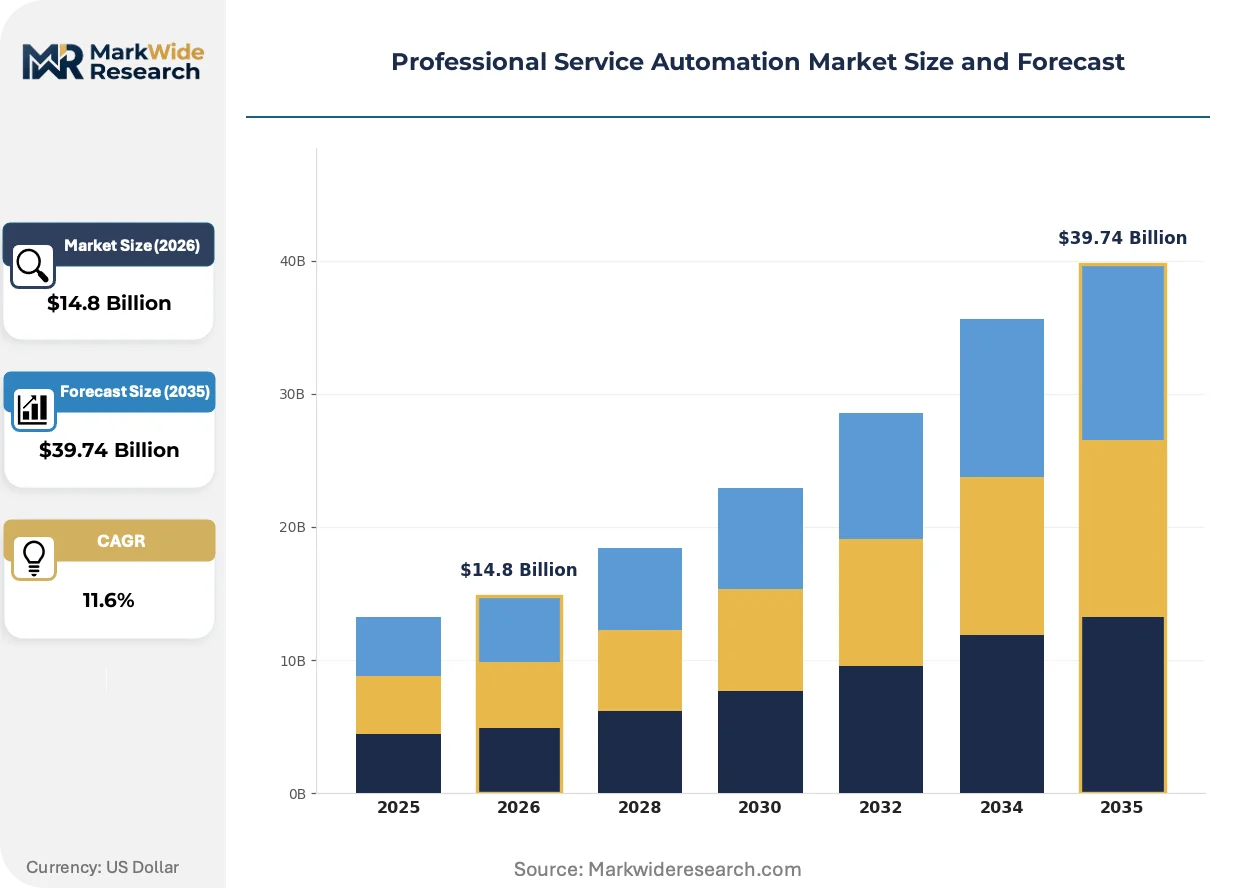
Market Dynamics
The central dynamic shaping the professional service automation market is the demand rotation from large enterprises to medium-sized businesses. This shift prioritizes scalable, cloud-native platforms over complex, on-premise systems, creating openings for specialized and agile vendors.
Growth Catalysts
- Cloud-Based Deployment:The shift to cloud models provides scalability and lower upfront costs, making PSA software accessible to medium-sized businesses and specialized consultancies that previously relied on spreadsheets.
- Regulatory Compliance Mandates:Data privacy regulations, including Europe's GDPR and the US's HIPAA, compel firms in legal and consulting verticals to adopt PSA platforms with strong data governance and access control features.
- IT Services Vertical Demand:The growing complexity of technology projects within the IT services industry requires sophisticated tools for resource utilization tracking, project profitability analysis, and integrated billing.
Market Restraints
- High Total Cost of Ownership:Beyond initial subscription fees, the costs associated with implementation, customization, data migration, and employee training can be prohibitive for smaller service organizations.
- Integration Complexity:PSA platforms must connect with a firm's existing CRM, accounting, and HR systems, and the technical challenges and costs of achieving seamless integration can deter adoption.
- Threat from Point Solutions:Businesses may opt for a combination of best-of-breed applications for time tracking, project management, and invoicing, viewing a single, comprehensive PSA suite as overly rigid.
Strategic Opportunities
- AI-Powered Analytics:Integrating artificial intelligence for predictive project outcomes, intelligent resource scheduling, and risk identification offers a significant value-add for vendors targeting mature service organizations.
- Expansion in Emerging Markets:Targeting the growing professional services sectors in countries across Southeast Asia and Latin America represents a key geographic expansion opportunity for PSA vendors.
- Vertical-Specific Modules:Developing specialized modules for niche industries, such as architectural firms, clinical research organizations, or marketing agencies, can create new revenue streams and competitive differentiation.
Industry Challenges
- Data Migration Risks:Transferring years of historical project, client, and financial data from legacy systems or spreadsheets to a new PSA platform is a complex process fraught with risks of data loss or corruption.
- Change Management Resistance:Overcoming employee resistance to new workflows, time-tracking mandates, and system-driven processes is a significant operational hurdle for firms implementing PSA software.
- Talent Scarcity:A shortage of implementation consultants and administrators with deep expertise in specific PSA platforms can delay deployments and limit a firm's ability to maximize its return on investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Professional Service Automation Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $39.74 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Hosted Solution Offering: Project Management, Resource Management, Time Tracking, Expense Management, Billing Automation, Client Collaboration Industry Vertical: Legal Firms, Consulting Agencies, Marketing Companies, Engineering Services, Architecture Firms, IT Services Customer Type: Small Enterprises, Medium-Sized Businesses, Large Corporations, Freelancers |
| Companies Covered | Autotask Corporation, ConnectWise Inc., Upland Software, Changepoint Corporation, Mavenlink, Inc., SAP SE, Microsoft Corporation, Oracle Corporation, Deltek Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Professional Service Automation Market Strategic Shifts & Innovations
Platform evolution is defined by the infusion of intelligence and specialization into core automation workflows. Vendors are moving beyond simple process automation to deliver predictive insights and configurable solutions that cater to the unique operational demands of specific professional service verticals.
Artificial intelligence and machine learning are being integrated into PSA platforms to provide predictive analytics for project budgeting and resource management. Consulting and technology firms are rapidly adopting these capabilities to improve the accuracy of profitability forecasts and optimize staff allocation. The infusion of AI is bifurcating the market into platforms offering basic workflow automation and those providing advanced, data-driven strategic planning capabilities.
Data localization requirements, exemplified by India's Digital Personal Data Protection Act, are directly influencing platform architecture and deployment options. This development compels global PSA vendors to provide in-country or regional data hosting solutions to ensure compliance. Professional services firms serving clients in India and other regions with similar laws now prioritize vendors that can guarantee data residency and demonstrate adherence to local privacy frameworks.
A notable behavioral shift involves customers moving from monolithic suite purchases to more flexible, modular subscription models. This disrupts the traditional, lengthy enterprise sales cycle, enabling mid-sized firms to adopt core functionalities like project management first and add other modules as they scale. This trend is particularly pronounced among marketing and creative agencies in North America and Europe, which value operational agility and scalable cost structures.
Professional Service Automation Market Segmentation
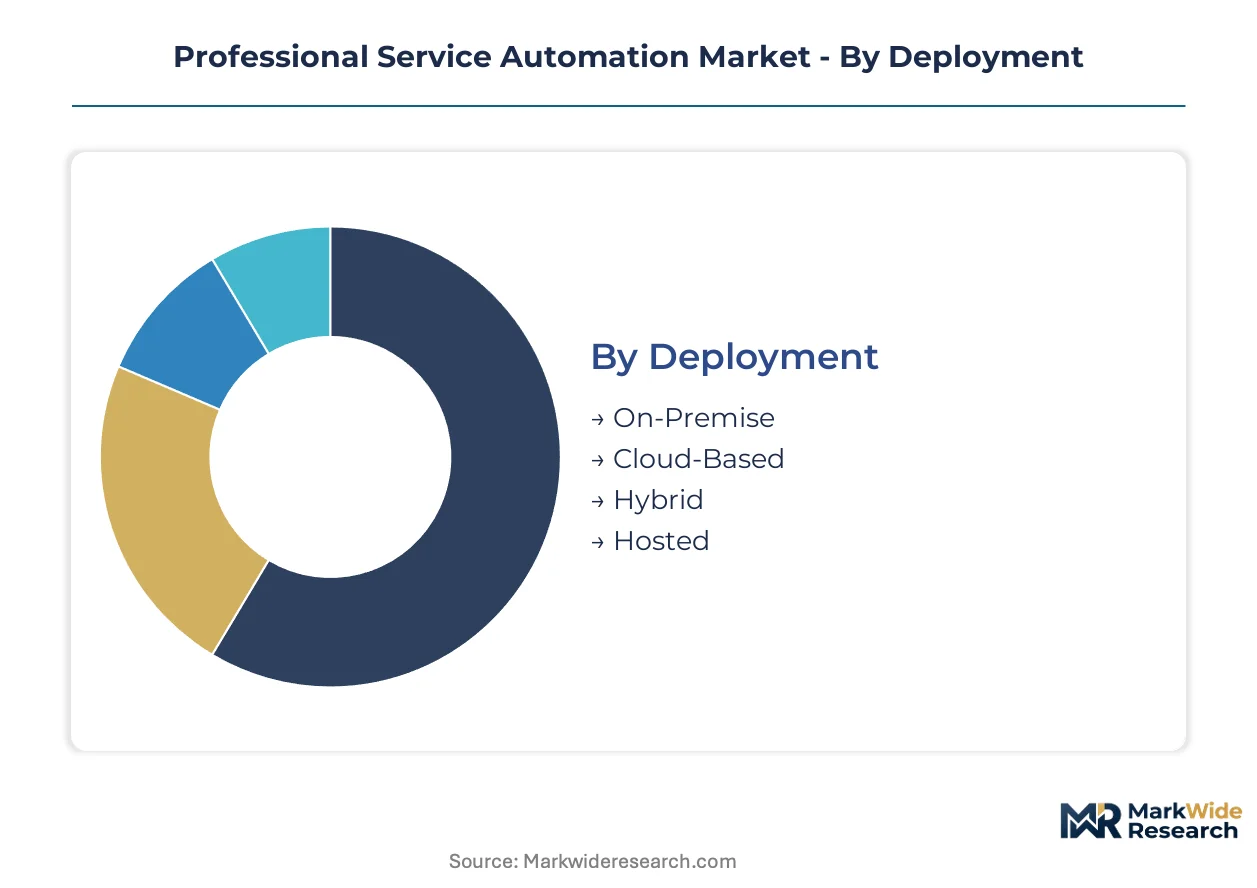
The Professional Service Automation (PSA) market segmentation reveals how diverse operational needs drive platform adoption across different business models. Understanding these distinctions helps vendors tailor solutions and identify specific growth pockets. PSA systems must adapt to varying deployment preferences, core functional requirements, industry-specific workflows, and enterprise scales to effectively serve the professional services sector.
Deployment:
Segments face varying substitution pressure, with cloud-based models aggressively displacing traditional on-premise solutions due to scalability and cost advantages.
- Cloud-Based:These platforms are hosted on remote servers and accessed via the internet, offering unparalleled scalability and lower upfront infrastructure costs. Demand is concentrating among medium-sized businesses and specialized consultancies seeking agile, subscription-based models in North America and Europe.
- Hybrid:This model combines elements of both on-premise and cloud deployment, allowing firms to retain sensitive data locally while leveraging cloud services for other functions. Legal and financial firms in the United States increasingly adopt hybrid solutions to balance data security with operational flexibility.
- On-Premise:Software is installed and run on computers located at the user's organization, providing full control over data and systems. Large corporations with stringent security requirements or legacy infrastructure still utilize on-premise deployments.
- Hosted:A third-party provider manages the software on their own servers, offering a middle ground between on-premise control and cloud flexibility. Smaller firms often use hosted solutions to offload IT management burdens.
On-Premise retains volume leadership; Cloud-Based holds the steepest expansion curve.
Solution Offering:
The application of PSA functionalities varies significantly, with project management and resource management serving as foundational components for most service organizations.
- Project Management:This module provides tools for planning, executing, monitoring, and closing projects, including task management, scheduling, and progress tracking. IT services firms in the United States and consulting agencies globally prioritize robust project management capabilities for complex engagements.
- Resource Management:This functionality optimizes the allocation and utilization of human resources across projects, managing skills, availability, and capacity. Engineering services and architecture firms in Europe leverage advanced resource management to maximize billable hours and minimize bench time.
- Time Tracking:Enables employees to record hours spent on projects and tasks, critical for accurate billing and payroll processing. Marketing companies and creative agencies universally require efficient time tracking for client invoicing.
- Expense Management:Facilitates the submission, approval, and reimbursement of business expenses incurred during project execution. All professional services firms need streamlined expense management to maintain financial transparency.
- Billing Automation:Automates the generation of invoices based on tracked time, expenses, and project milestones. Consulting and legal firms rely on billing automation to accelerate revenue cycles.
- Client Collaboration:Provides portals and tools for secure communication, document sharing, and feedback exchange with clients. Agencies and IT service providers use collaboration features to enhance client engagement.
Project Management consistently drives demand; Client Collaboration is expanding most quickly.
Industry Vertical:
Customer type influences PSA feature prioritization, with specialized requirements emerging in various professional service sectors.
- IT Services:This vertical requires advanced PSA features for managing complex technology projects, resource utilization, and integrated billing for project-based work. Global IT service providers are significant adopters of comprehensive PSA suites.
- Consulting Agencies:These firms demand flexible project accounting, resource forecasting, and client profitability analysis tools to manage diverse client engagements. Consulting agencies in North America seek platforms that support rapid project initiation and closure.
- Marketing Companies:Creative agencies require robust time tracking, project management for campaigns, and agile billing solutions to manage multiple client accounts. Marketing firms in Europe increasingly adopt modular PSA solutions.
- Engineering Services:These firms need precise resource scheduling, project costing, and compliance tracking for large-scale infrastructure and design projects. Engineering companies value PSA for its ability to optimize workforce deployment.
- Architecture Firms:Project-centric organizations like architecture firms prioritize project management, resource allocation, and document management within their PSA systems. These firms leverage PSA to streamline design and construction phases.
- Legal Firms:Data privacy, secure client collaboration, and detailed time and expense tracking for billable hours are paramount for legal practices. Legal firms in the United States require compliance-focused PSA platforms.
IT Services accounts for the largest share; Marketing Companies are gaining share fastest.
Customer Type:
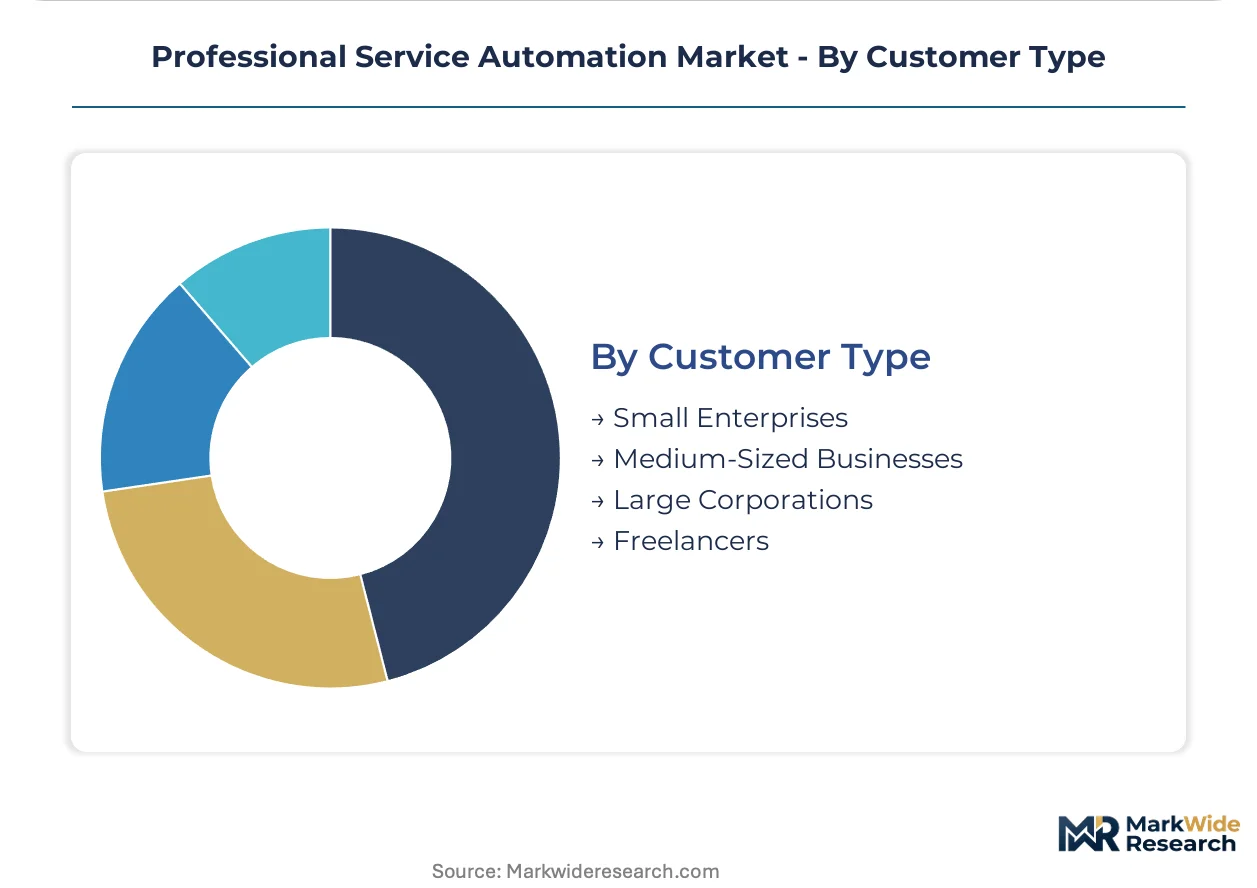
The maturity of businesses dictates the complexity and scope of PSA solutions adopted, from basic functionalities for small firms to integrated suites for large enterprises.
- Medium-Sized Businesses:These companies seek scalable, cloud-based PSA solutions that can integrate with existing systems without excessive customization. This segment is experiencing significant growth in North America and Europe.
- Large Corporations:Established enterprises typically require comprehensive PSA suites with extensive customization options, robust reporting, and enterprise-grade security features. Global corporations maintain strong positions with established PSA vendors.
- Small Enterprises:These businesses often prioritize cost-effectiveness and ease of use, opting for modular solutions that address immediate needs like time tracking and basic project management. Small professional services firms in emerging markets are exploring entry-level PSA tools.
- Freelancers:Individual professionals often use simplified PSA tools or project management software for basic task management, time tracking, and invoicing. Freelancers seek highly intuitive and affordable solutions.
Large Corporations anchor market value; Medium-Sized Businesses show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for professional service automation software flows significantly towards the United States, driven by its expansive professional services sector. European firms also exhibit strong adoption, particularly marketing companies in Europe. This concentration of demand influences global vendors to tailor solutions for specific regional requirements and compliance frameworks.
United States
Demand for PSA platforms in the United States stems from the large professional services sector, particularly IT services firms managing complex projects. HIPAA regulations mandate stringent data privacy and security features for legal and consulting firms. Major tech hubs like Silicon Valley and New York City drive innovation in cloud-based PSA solutions.
Germany
German professional services firms prioritize PSA solutions for optimizing resource utilization and project profitability. Europe's GDPR significantly influences software selection, favoring platforms with robust data protection and compliance features. The Rhine-Main region, with its strong consulting and engineering sectors, sees high adoption of integrated PSA suites.
India
India's professional services sector, especially IT and consulting, demonstrates rising demand for scalable PSA tools to manage distributed teams. The Digital Personal Data Protection Act requires vendors to provide in-country data hosting solutions. Technology centers in Bengaluru and Hyderabad are rapidly implementing AI-powered PSA for predictive analytics.
Japan
Japanese engineering and consulting firms seek PSA platforms that enhance project management efficiency and resource allocation. METI guidelines often shape procurement decisions, emphasizing reliability and data security in enterprise software. Tokyo's financial and professional services districts exhibit strong interest in modular PSA subscriptions.
United Kingdom
UK marketing and creative agencies increasingly adopt flexible, modular PSA solutions to manage diverse client campaigns. The UK's data protection laws, post-Brexit, continue to align with GDPR principles for client data. London's vibrant agency scene drives demand for agile, cloud-native platforms with strong client collaboration features.
Professional Service Automation Market Key Industry Players
Player mix skews toward established enterprise software providers alongside a growing cohort of specialized mid-market vendors. The market exhibits a tiered structure, with a few large corporations offering comprehensive suites and numerous agile players targeting specific customer segments with cloud-native offerings. Strategic archetypes include enterprise resource planning giants, cloud-native PSA specialists, and vertical-specific solution providers. Competitive moves center on portfolio diversification through strategic acquisitions, continuous technology development, and expanding geographic reach into emerging markets.
Within the enterprise software segment, SAP SE and Oracle Corporation exemplify vendors maintaining strong positions among large corporations. These German and American-based companies offer comprehensive suites designed for extensive customization and robust reporting, often serving global operations. ConnectWise Inc., an American corporation, occupies a position among specialized platforms, representing providers focused on technology solution providers and IT consultants seeking agile, cloud-based solutions. These entities collectively anchor different tiers of the professional service automation market, reflecting varied customer needs from broad enterprise functionality to niche vertical specialization.
| Leading Market Players |
|---|
| Autotask Corporation |
| ConnectWise Inc. |
| Upland Software |
| Changepoint Corporation |
| Mavenlink, Inc. |
| SAP SE |
| Microsoft Corporation |
| Oracle Corporation |
| Deltek Inc. |
| Others |
Cost & Logistics Intelligence
Cloud-based deployment aggressively displacing traditional on-premise solutions reshapes professional service automation supply geography and pricing economics. This shift concentrates demand in North America and Europe, favoring subscription models over large upfront licensing fees.
Pricing Analysis
The pricing gap between advanced AI-powered PSA platforms and basic workflow automation solutions defines market value. PSA software typically follows a SaaS-tiered subscription model, with price differentiation stemming from customization level and vertical-specific modules. Pricing softness reflects increased competition from agile cloud-native vendors targeting mid-market firms. Medium-sized businesses are most price-sensitive, while large corporations prioritize comprehensive features.
Supply Chain Analysis
Minimal physical inventory and short lead times characterize the professional service automation supply chain. Geographic supply concentration for platform development centers in the United States, Germany, and India. The sector relies on skilled software developers and robust cloud infrastructure services. Talent scarcity for implementation consultants represents a structural risk, while distribution runs through direct sales and channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The professional service automation market faces a critical constraint in specialized talent. A scarcity of expertise in AI-powered predictive analytics for project outcomes limits widespread adoption and advanced feature utilization.
For Market Incumbents:Secure existing large enterprise accounts by deepening integration with core enterprise resource planning systems. Incumbents should acquire niche AI firms to counter agile cloud-native specialists challenging their market share. Investing in R&D for intelligent resource scheduling capabilities will reinforce their value proposition. This strategy defends against new entrants offering specialized, predictive analytics.
For New Entrants and Emerging Players:Anchor in vertical-specific modules for underserved segments like marketing agencies and architectural firms. New players should target medium-sized businesses in North America with scalable cloud solutions. A modular subscription model reduces upfront costs and caters to operational agility. This approach penetrates the market by addressing unmet needs with flexible offerings.
For Investors and Strategic Acquirers:India's Digital Personal Data Protection Act reshapes the acquisition landscape for professional service automation. The market demonstrates strong growth viability over the next decade, driven by cloud adoption. Investors should target cloud-native PSA specialists with strong data residency features and compliance expertise. Consolidation among mid-market vertical solution providers serves as a key signal for strategic investment opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Launch AI-powered predictive analytics module | Enhances project profitability forecasts for IT services firms. |
| Deepen integration with CRM and ERP systems | Streamlines workflows for large corporations and reduces data silos. |
| Form strategic partnerships with regional consultancies | Expands market reach into emerging markets like Southeast Asia. |
| Acquire niche vertical-specific PSA providers | Diversifies solution offerings for marketing and consulting agencies. |
| Expand cloud infrastructure to support data localization | Ensures compliance with GDPR and India's Digital Personal Data Protection Act. |
Research Approach
Initial hypotheses were tested against primary input from CTOs, IT procurement officers, consulting firm partners, and marketing agency directors, then refined. This involved combining insights from these industry stakeholders with secondary validation from SEC filings, industry association reports, and government regulatory documents. The analysis employed both bottom-up and top-down triangulation to ensure data accuracy and market sizing integrity.
Variance decomposition isolated the impact of key market drivers and restraints across the analysis window. The model segmented the market by deployment model, solution offering, industry vertical, customer type, and integration complexity. Compound annual growth rates were derived through regression analysis on historical data and projected growth drivers. Cloud adoption rates and regulatory compliance spending served as critical industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of stable macroeconomic conditions and consistent regulatory enforcement; material deviation would warrant model refresh. Rapid shifts in AI capabilities or unforeseen global data privacy mandates represent specific risk factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
United States Donation Management Software Market
Software & Services
High Education Software Market
Software & Services
Lead Scoring Software Market
Software & Services
Global Animation Software Market
Software & Services
Workflow Management Software (WMS) Market
Software & Services
Product Analytics Software Market
Software & Services
Classified Platform Market
Software & Services
Braking Systems Software Market
Software & Services
Employee Engagement Solutions Market
Software & Services
Italy HR Payroll Software Market
Software & Services
Ccaas Software Market
Software & Services
3D Printing Medical Device Software Market
Software & Services
Telecom IT Services Market
Software & Services
Systems Administration Management Tools Market
Software & Services
Tenant Billing System Market
Software & Services
Global Data Quality Software Market