
 Ccaas Software Market | 2026-2036
Ccaas Software Market Size, Share, and Industry Trends Forecast 2026-2036
Ccaas Software Market Outlook
North American cloud infrastructure investment is broadening the addressable base for contact-center-as-a-service platforms. Genesys leverages its AI-native orchestration layer to sustain enterprise renewals across complex multi-channel environments. Five9 anchors its position through deep telephony integration with major carrier networks, while Talkdesk differentiates via vertical-specific compliance modules for regulated industries.
Contact-center-as-a-service software delivers cloud-hosted customer interaction management through voice, digital messaging, and AI-assisted routing protocols, typically operating over APIs that integrate with CRM and workforce optimization systems. Its primary purpose is to replace legacy on-premises PBX and ACD systems with elastic, subscription-based infrastructure that scales agent capacity in real time. Deployment model segmentation shows public cloud configurations capturing the majority of new seats due to faster provisioning and lower capital requirements, though hybrid cloud retains strength among financial services buyers with data residency constraints. Industry vertical segmentation reveals retail and telecommunications as the most penetrated sectors, while government and education represent emerging opportunity pools where FedRAMP and state-level certification timelines create extended sales cycles.
FCC rules on robocall mitigation and STIR/SHAKEN authentication are reshaping voice channel architecture requirements for US-based CCaaS providers. EMA pharmacovigilance reporting obligations and GDPR Article 32 security standards compel European healthcare and financial deployments toward platforms with sovereign data processing guarantees. Stakeholders must weigh the pace of AI agent rollout against evolving regulatory scrutiny of automated decision-making in consumer-facing interactions.
Market Dynamics
Cloud-native AI orchestration is compressing deployment timelines from months to weeks while forcing legacy on-premise vendors into defensive repositioning. The shift from capital-intensive PBX infrastructure to elastic subscription models is redistributing value toward software layers and API integrations.
Growth Catalysts
- EU AI Act cloud-first mandates:European enterprises must adopt certified platforms for automated customer interactions, accelerating replacement of legacy systems in Germany and France.
- STIR/SHAKEN authentication protocols:FCC rules on robocall mitigation are compelling US carriers to modernize voice channel architecture through compliant CCaaS integrations.
- Automotive manufacturer modernization:German industrial firms are unifying dealer networks and service operations onto single cloud platforms to reduce fragmentation.
Market Restraints
- Data residency compliance costs:GDPR Article 32 security standards and EMA pharmacovigilance rules force dual-region infrastructure investments for healthcare deployments.
- Telephony carrier concentration:Deep integration dependencies with major US and European network operators create switching friction and vendor lock-in.
- AI agent liability uncertainty:Evolving regulatory scrutiny of automated decision-making in consumer-facing interactions slows rollout timelines for advanced self-service.
Strategic Opportunities
- Underpenetrated government vertical:FedRAMP and state-level certification timelines have delayed public sector adoption, creating a backlog of procurement opportunities.
- API-first CRM convergence:Native integration with Salesforce, Microsoft Dynamics, and ServiceNow is displacing standalone contact center deployments in mid-market accounts.
- India BPO modernization wave:Domestic regulatory pressure and data localization requirements are pushing Indian outsourcing providers toward sovereign cloud infrastructure.
Industry Challenges
- Conversational AI talent scarcity:Shortage of prompt engineers and natural language processing specialists is constraining enterprise self-service roadmap execution.
- Legacy ACD migration complexity:Custom call routing logic and agent skill matrices built over decades resist straightforward lift-and-shift cloud transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ccaas Software Market |
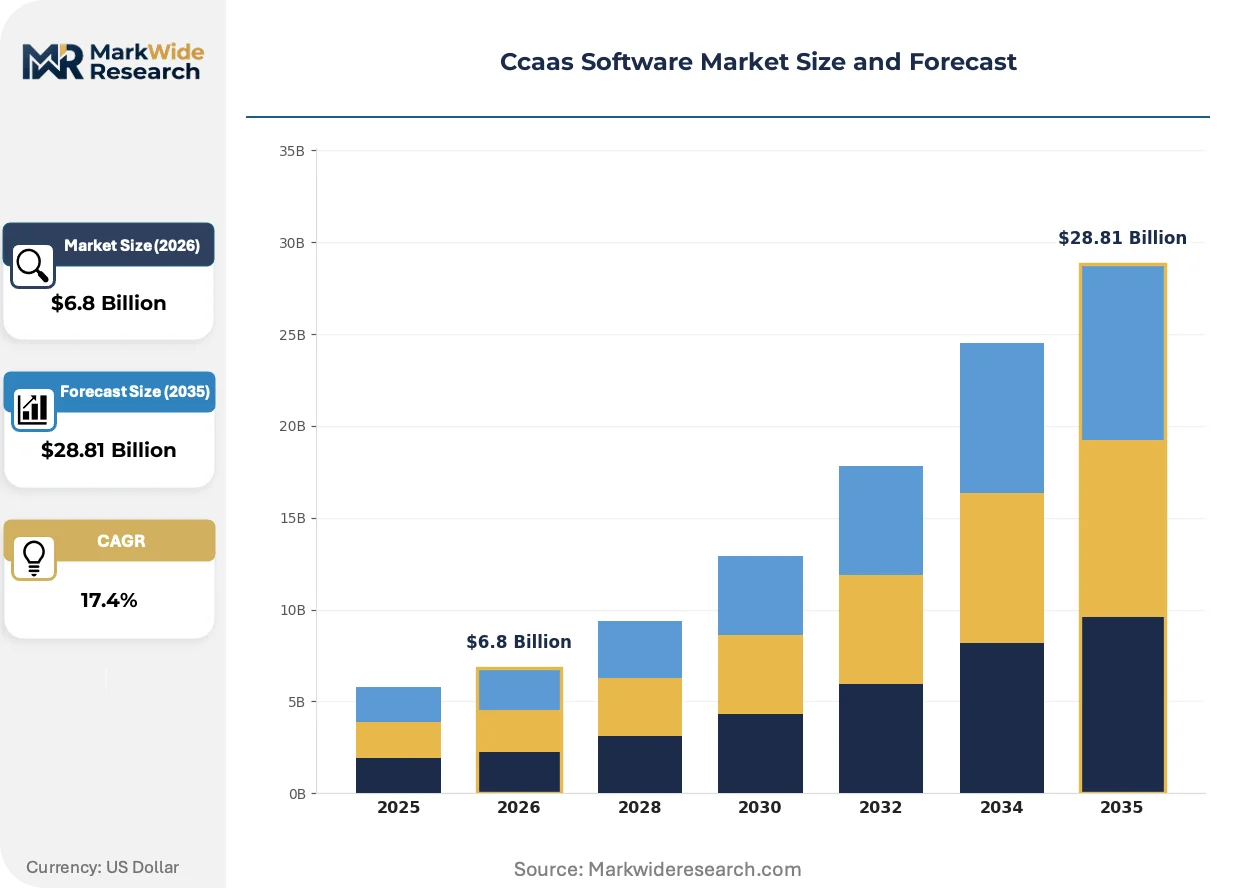
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $28.81 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Managed Services, Professional Services, Support Services, Consulting Services Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Target Audience: Small Businesses, Enterprises, Startups, Non-Profit Organizations Industry Vertical: Education, Retail, Telecommunications, Government |
| Companies Covered | Genesys, NICE CXone, Five9, Talkdesk, 8x8, RingCentral, Avaya, Cisco, Zoom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ccaas Software Market Strategic Shifts
Generative AI is collapsing the boundary between scripted chatbots and autonomous agents, forcing platform vendors to rearchitect core routing engines. This compression is accelerating consolidation around vendors with native large language model capabilities.
Real-time sentiment analysis is converging with predictive workforce scheduling to compress average handle times while preserving satisfaction scores. Retailers with seasonal volume spikes are adopting these fused capabilities fastest. The structural result is converging with traditional workforce optimization into unified performance management suites.
GDPR Article 32 and the EU AI Act are mandating algorithmic transparency logs for customer-facing automation. European healthcare and financial services deployments now require sovereign data processing guarantees with audit trails. German automotive manufacturers are responding by demanding in-region data residency certifications as a procurement prerequisite.
Subscription-based consumption models are displacing perpetual licenses across mid-market buyer segments. Channel partners are pivoting from hardware resale toward implementation and change management services. This shift is most visible in US retail and telecommunications verticals where IT capital budgets have flattened.
Ccaas Software Market Segmentation
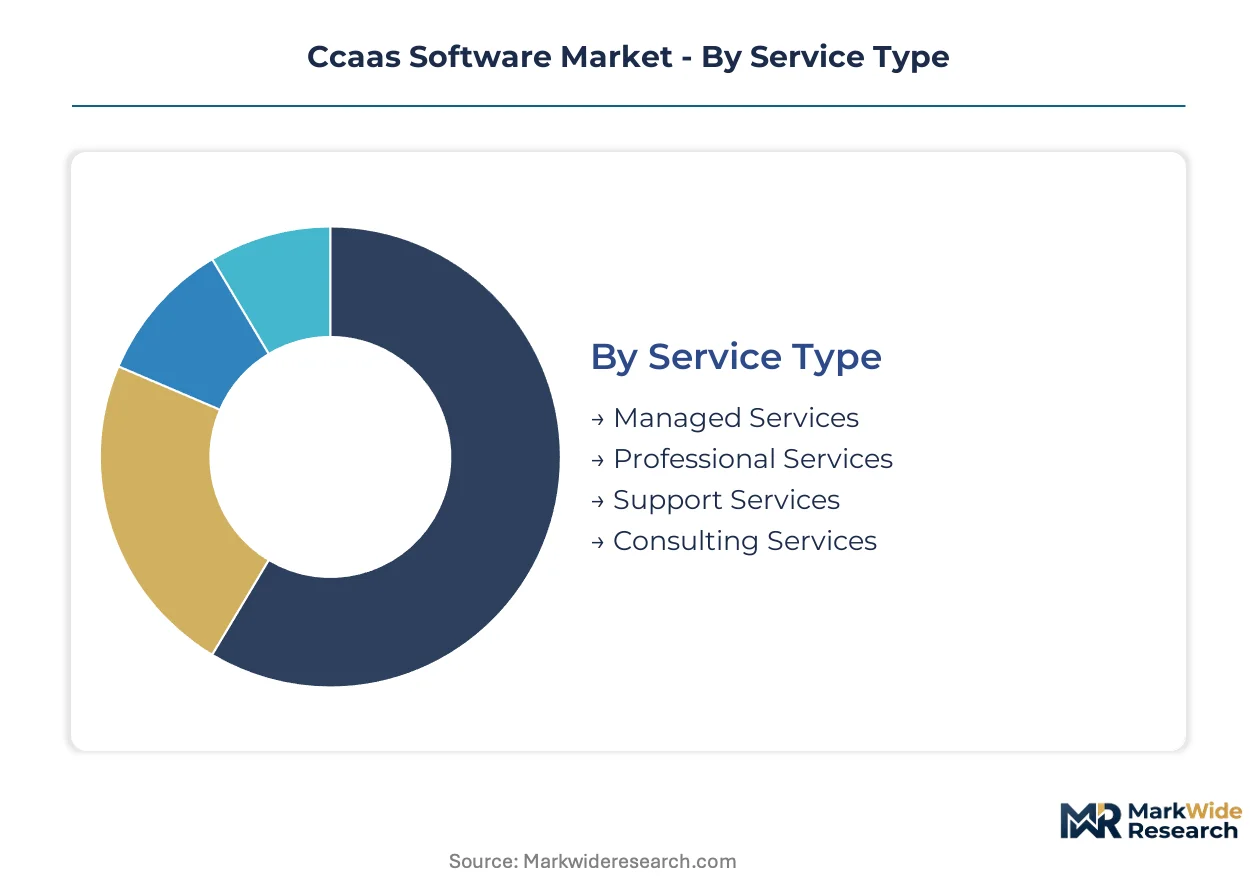
CCaaS procurement patterns diverge sharply across service tiers and infrastructure models, with compliance requirements fragmenting addressable markets. Certification burdens from HIPAA, FedRAMP, and GDPR Article 32 reshape which segments enterprises can realistically target.
Service Type:
FedRAMP authorization and HIPAA Business Associate Agreements determine which service tiers government and healthcare buyers can access, concentrating procurement among certified providers.
- Managed Services:End-to-end platform operation including agent workforce management, SLA-backed uptime guarantees, and continuous compliance monitoring. US federal agencies and German automotive manufacturers route procurement here due to bundled liability coverage and sovereign data processing guarantees.
- Professional Services:Custom implementation, integration architecture, and change management for complex multi-site deployments. Demand clusters among French banking consortiums modernizing legacy ACD infrastructure under ECB operational resilience mandates.
- Support Services:Technical break-fix and tiered escalation protocols.
- Consulting Services:Strategic advisory on cloud migration roadmaps and AI agent governance frameworks.
Managed Services sits at the top of the volume ranking, with Professional Services climbing the fastest.
Deployment Model:
Cost tier stratification separates capital-light subscription buyers from organizations bearing dual-region infrastructure investments for data residency.
- Public Cloud:Multi-tenant infrastructure with API-driven provisioning and consumption-based pricing. Retailers in the United Kingdom and telecommunications operators in Spain adopt this model for seasonal elasticity and minimal upfront commitment.
- Hybrid Cloud:Split architecture preserving sensitive interaction data on private infrastructure while routing routine traffic through public nodes. Italian financial services firms and Swiss pharmaceutical manufacturers mandate this configuration under FINMA and EMA pharmacovigilance rules.
- Private Cloud:Single-tenant dedicated infrastructure with full control over security patching and audit trails.
- On-Premises:Legacy PBX and ACD systems with perpetual licensing, now confined to classified government facilities and defense contractors with air-gapped requirements.
Public Cloud commands the largest installed base, though Hybrid Cloud gains share fastest among regulated verticals.
Target Audience:
Customer maturity and procurement sophistication determine feature bundling, with enterprise accounts demanding native AI orchestration while smaller buyers prioritize out-of-box functionality.
- Enterprises:Multi-thousand seat deployments with custom CRM integrations, workforce optimization suites, and dedicated customer success management. German industrial conglomerates and US health systems anchor this segment with three-to-five-year contractual commitments.
- Small Businesses:Rapid-deployment packages with pre-configured digital channels and pay-per-agent monthly billing. Demand concentrates among professional services firms in Australia and hospitality operators in Singapore seeking omnichannel presence without IT overhead.
- Startups:API-first consumption with minimal seat minimums and usage-based scaling.
- Non-Profit Organizations:Discounted or donated licensing through vendor social impact programs.
Enterprises dominate current revenue contribution, with Small Businesses expanding most quickly in mid-market saturation.
Industry Vertical:
Application-specific compliance modules and verticalized AI training data separate platform winners from horizontal generalists.
- Telecommunications:Carrier-grade voice infrastructure with STIR/SHAKEN authentication, robocall mitigation, and real-time network event correlation. US mobile virtual network operators and European incumbent carriers modernize here to meet FCC and BEREC quality-of-service mandates.
- Retail:Seasonal volume elasticity, unified commerce integration, and predictive workforce scheduling tied to promotional calendars. Demand concentrates among fashion retailers in France and grocery chains in the Netherlands managing peak holiday interaction surges.
- Government:FedRAMP authorization, CJIS compliance for law enforcement, and state-level procurement certification timelines.
- Education:Student information system integration, financial aid inquiry routing, and alumni engagement workflows.
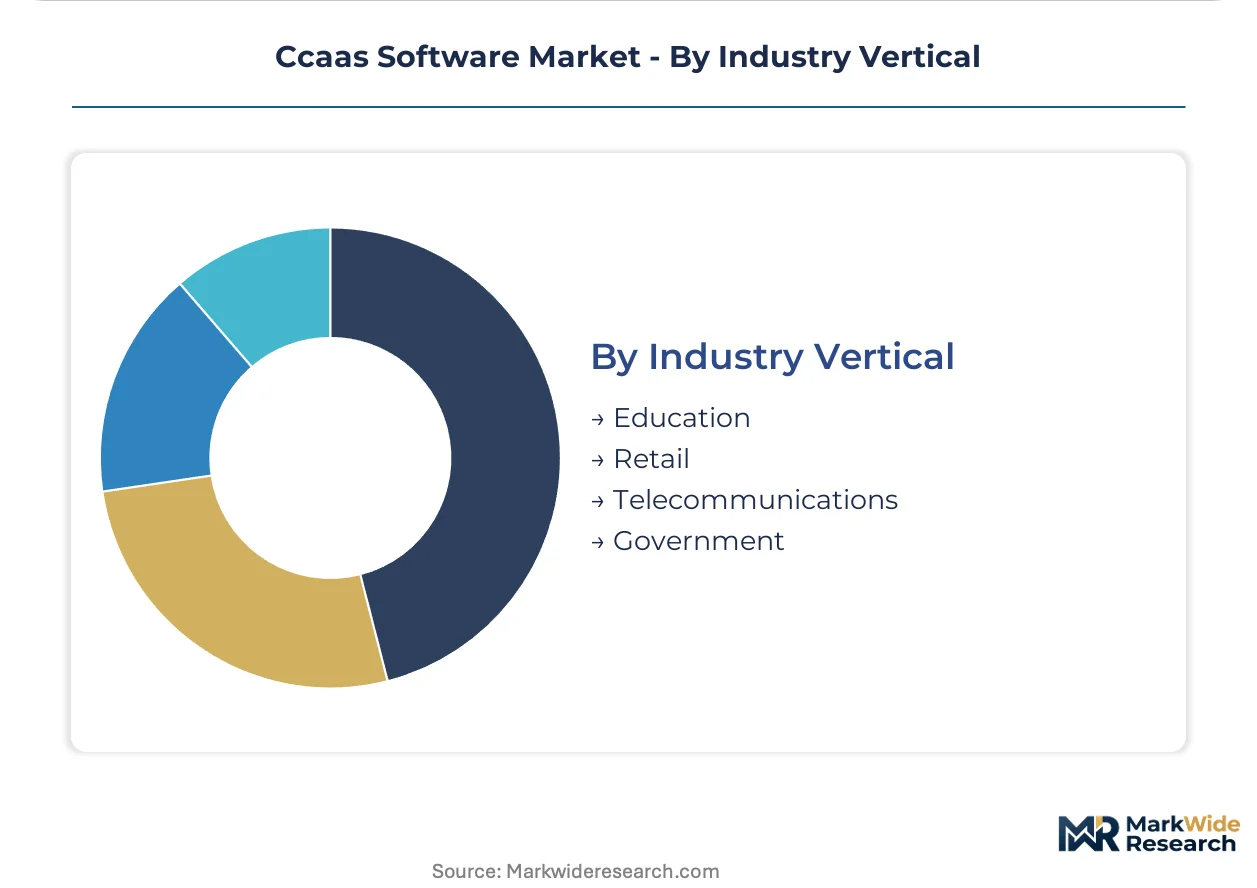
Telecommunications leads segment scale, with Retail showing the steepest expansion trajectory as seasonal AI automation penetrates mid-tier merchants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting CCaaS procurement toward jurisdictions with clearer compliance frameworks, as enterprises seek to minimize dual-region infrastructure costs while maintaining data sovereignty guarantees.
United States
FCC STIR/SHAKEN mandates and HIPAA enforcement are accelerating carrier network modernizations and healthcare contact center migrations. Federal agencies prioritize FedRAMP-authorized platforms with bundled liability coverage. Demand concentrates in Northern Virginia cloud corridors and Dallas-Fort Worth telecommunications hubs where carrier interconnection density supports low-latency voice routing.
Germany
Automotive manufacturers and industrial conglomerates are consolidating fragmented dealer service networks onto unified cloud platforms under EU AI Act cloud-first directives. KBA oversight and GDPR Article 32 standards compel sovereign data processing with full audit trails. Bavaria and Baden-Württemberg host the densest deployment clusters as OEMs modernize legacy ACD infrastructure.
United Kingdom
Retailers with seasonal volume volatility are adopting public cloud configurations for promotional surge elasticity. FCA operational resilience rules and post-Brexit data adequacy negotiations shape vendor selection criteria. London and Manchester financial services corridors drive hybrid cloud demand for trading floor adjacent customer operations requiring sub-millisecond latency.
India
Domestic BPO providers face regulatory pressure to migrate from offshore delivery models to sovereign cloud infrastructure under data localization mandates. TRAI quality-of-service frameworks and RBI financial data storage rules accelerate platform replacements. Bengaluru and Hyderabad outsourcing clusters are retrofitting multi-tenant voice architectures with in-region data residency.
Japan
Financial institutions and telecommunications operators are replacing legacy on-premises PBX systems with API-first cloud platforms under METI digital transformation guidelines. JIS security standards and sector-specific privacy codes influence procurement specifications. Tokyo-Osaka corridor enterprises lead adoption as they converge contact center operations with existing Salesforce and Microsoft Dynamics deployments.
Ccaas Software Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue vertical-specific compliance modules and AI-native orchestration layers. Market structure shows moderate consolidation around platforms with carrier-grade telephony integration, though fragmentation persists among regional specialists serving data-residency-constrained buyers. Three archetypes dominate: full-stack incumbents with deep carrier relationships, cloud-native challengers with generative AI routing engines, and hybrid specialists bridging legacy ACD migrations. Competitive intensity centers on M&A activity targeting conversational AI talent and strategic partnerships embedding contact center capabilities within major CRM ecosystems.
Within the full-stack tier, Genesys and Cisco anchor enterprise positions through multi-channel orchestration and deep network operator integration. Five9 exemplifies the cloud-native vector with carrier-telephony anchoring. NICE CXone occupies a distinct position converging workforce optimization with real-time analytics. These three represent the primary competitive anchors as the market compresses around platforms capable of spanning both legacy migration complexity and autonomous AI agent deployment.
| Leading Market Players |
|---|
| Genesys |
| NICE CXone |
| Five9 |
| Talkdesk |
| 8x8 |
| RingCentral |
| Avaya |
| Cisco |
| Zoom |
| Others |
Value Chain & Pricing Dynamics
Prompt engineering talent concentration in Bengaluru and Hyderabad drives labor-cost differentials that widen pricing-tier spreads between premium AI-native platforms and standard cloud configurations. European GDPR compliance investments and US FedRAMP certification requirements further stratify cost structures across buyer segments.
Pricing Analysis
Direct-to-enterprise subscription discounts dominate the channel-margin layer, compressing traditional distributor markups. Three-tier pricing structure across premium, standard, and economy levels separates FedRAMP-authorized managed services from public cloud self-service tiers. Price differentiation hinges on certification grade and vertical-specific AI training data depth. Pricing pressure stems from hyperscaler bundling of contact center modules with core cloud contracts. Small businesses exhibit highest price sensitivity, while German automotive manufacturers prioritize sovereign data guarantees over cost.
Supply Chain Analysis
Carrier-grade telephony infrastructure rests on deep integration partnerships with network operators in the United States, Germany, and Japan. Cloud compute capacity draws from hyperscaler regions, while conversational AI model training feeds from proprietary interaction datasets. Single-source vulnerability concentrates in legacy ACD migration tooling and specialized compliance certification auditors. Distribution runs through systems integrators and channel partners pivoting from hardware resale toward implementation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CCaaS market represents a late-cycle quality story as procurement shifts toward premium specifications demanding native AI orchestration and sovereign data residency certifications.
For Market Incumbents: Hedge against hyperscaler bundling threats by deepening carrier-telephony integration moats and accelerating EU AI Act compliance certification timelines. Prioritize vertical-specific AI training data accumulation in automotive and healthcare segments where regulatory barriers protect pricing power. For New Entrants and Emerging Players: Begin with underpenetrated government verticals where FedRAMP authorization backlogs create procurement delays for established vendors. Target state-level education agencies and municipal health departments with rapid-deployment packages emphasizing CJIS compliance and student information system integration as the primary go-to-market angle. For Investors and Strategic Acquirers: Cloud-native challengers with generative AI routing engines are the most active acquirer in this space, consolidating conversational AI talent pools. Long-term viability favors platforms spanning both legacy ACD migration complexity and autonomous agent deployment. Watch for inflection signals in Indian BPO provider sovereign cloud procurement volumes.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native Salesforce and Microsoft Dynamics embedding displaces standalone deployments in mid-market accounts. |
| Acquisition of Specialist Firm | Conversational AI talent scarcity drives consolidation of prompt engineering and NLP specialist teams. |
| Geographic Expansion | German automotive manufacturer consolidation creates demand for in-region data residency certifications. |
| Strategic Partnership | Carrier-grade voice infrastructure partnerships with Verizon and Deutsche Telekom anchor switching costs. |
| Product Launch | Real-time sentiment analysis fused with predictive workforce scheduling compresses average handle times. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with CTOs, IT procurement officers, contact center operations directors, and systems integration partners. Secondary validation draws from SEC filings, hyperscaler capex disclosures, carrier network modernization announcements, and regulatory filings with the FCC and EU AI Act certification databases. Bottom-up seat deployment estimates triangulate against top-down software spending benchmarks.
Granularity-level framing models deployment mode, organization size, vertical industry, and integration complexity at the segment level across the projection horizon. CAGRs derive from historical elasticity patterns and forward-looking adoption curves. Forecast inputs incorporate AI agent rollout timelines and carrier network modernization schedules without specifying periods.
Several conditions sit outside the modeled scope, including black-swan regulatory reversals on automated decision-making and catastrophic hyperscaler service disruptions. Forecasts reflect assumptions about sustained cloud migration momentum and stable carrier interconnection economics. A small set of named triggers warrants ongoing watch: EU AI Act enforcement intensity, STIR/SHAKEN compliance deadline adherence, and Indian data localization mandate implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Federal Government Software Market
Software & Services
Audio Editing Software Market
Software & Services
Service Resource Planning (SRP) Saas Solutions Market
Software & Services
Global Online Assessment Software Market
Software & Services
Simulation Software Market
Software & Services
Automotive Design Software Market
Software & Services
Europe Feedback Management Software Market
Software & Services
Animation Design Software Market
Software & Services
APAC Workforce Management Software Market
Software & Services
Global Polling Software Market
Software & Services
Data Conversion Services Market
Software & Services
North America Restaurant Management Software Market
Software & Services
Global Big Data Software Market
Software & Services
Ecommerce Inventory Management Software Market
Software & Services
Airline Route Profitability Software Market
Software & Services
Global Kiosk Software Market