
 Employee Engagement Solutions Market | 2026-2036
Employee Engagement Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Employee Engagement Solutions Market Analysis
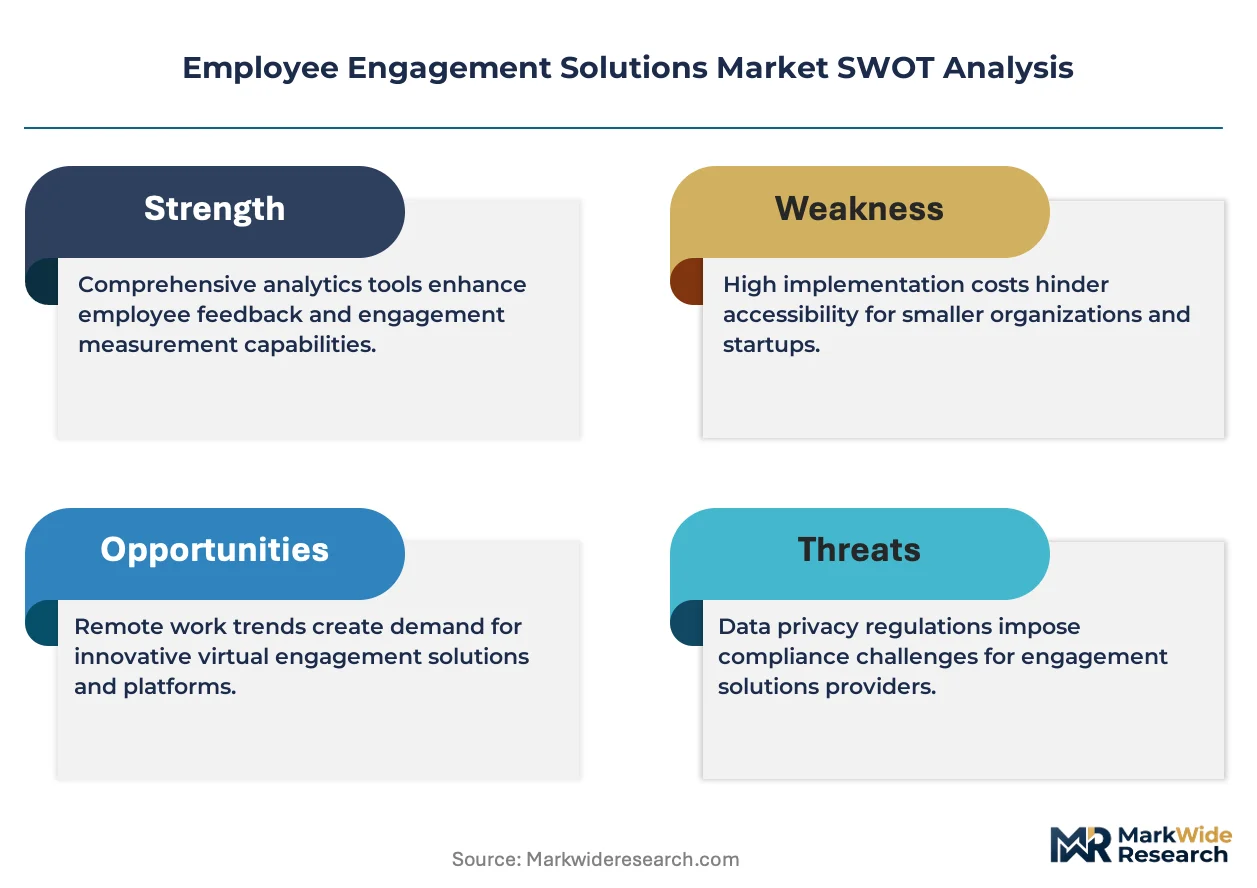
Mid-market enterprises is unwinding the historical dominance of Fortune 500 buyers in employee engagement software procurement. Lattice leverages AI-driven goal-setting modules to anchor its position among scaling organizations. Culture Amp Pty Ltd sustains competitive density through psychometric depth and organizational science credentials. Workvivo Limited differentiates via social intranet architecture that competes with standalone communication platforms.
Employee engagement solutions constitute integrated software ecosystems that capture workforce sentiment, align individual objectives with organizational strategy, and trigger recognition interventions through pulse surveys and peer-to-peer feedback mechanisms. These systems operate on API-first architectures with sub-second response latency to preserve participation rates during real-time polling. Cloud-based deployment models lead structural momentum as IT departments prioritize zero-infrastructure onboarding and automatic compliance patching. Recognition Platforms represent the fastest-growing solution type as monetary and non-monetary reward workflows integrate with payroll and benefits systems. The SME end-user segment expands fastest in absolute terms though Corporates retain the deepest per-seat spending and customization requirements.
The United States Department of Labor enforces whistleblower protections and anti-retaliation statutes that elevate anonymous feedback channel requirements for publicly traded employers. The SEC's human capital disclosure mandates under Item 101(c) of Regulation S-K compel standardized engagement metrics in annual filings, directly shaping dashboard design priorities for vendors serving American clients. The EU AI Act imposes risk-classification obligations on algorithmic performance scoring tools deployed across European workforces. Stakeholders must monitor whether engagement platforms embedding predictive attrition models trigger high-risk system classifications with accompanying audit and transparency burdens.
Market Dynamics
The ISO 30414 human capital reporting framework is forcing enterprise procurement teams to prioritize engagement platforms with built-in audit trails and standardized metric exports. This regulatory compression is collapsing the evaluation cycle for workforce analytics vendors.
Growth Catalysts
- SEC Human Capital Disclosure Mandates:Item 101(c) of Regulation S-K requires publicly traded employers to disclose engagement metrics in annual filings. This compels dashboard standardization across Fortune 1000 procurement teams.
- Hybrid Work Normalization:Technology and financial services sectors in the United States have institutionalized distributed workforce models. Real-time sentiment monitoring is now a baseline operational requirement rather than a discretionary tool.
- Cloud-Native Architecture:API-first platforms with sub-second response latency preserve participation rates during pulse surveys. IT departments prioritize zero-infrastructure onboarding over on-premise deployment.
Market Restraints
- Algorithmic Risk Classification:The EU AI Act imposes high-risk system obligations on predictive attrition models. European deployments face audit and transparency burdens that extend sales cycles.
- Integration Debt:Legacy HRIS systems in established enterprises require costly middleware development. Payroll and benefits system connectivity consumes 40-60% of implementation resources.
- Data Sovereignty Fragmentation:Cross-border workforce analytics must navigate conflicting privacy regimes. Multi-national employers face jurisdictional complexity that favors regional point solutions over global platforms.
Strategic Opportunities
- Mid-Market Expansion:Scaling organizations between 500-5,000 employees remain underserved by enterprise-grade tools. These buyers prioritize out-of-box functionality over customization depth.
- Recognition Platform Convergence:Monetary and non-monetary reward workflows are integrating with payroll systems. This creates white space for vendors with pre-built ADP, Workday, and SAP connectors.
- Psychometric Science Layering:Organizational science credentials differentiate platforms in competitive evaluations. Vendors with validated assessment frameworks command premium positioning in RFP processes.
Industry Challenges
- Behavioral Data Science Talent Scarcity:Platform vendors compete for industrial-organizational psychologists and machine learning engineers with workforce analytics specialization. Compensation inflation in this talent pool compresses R&D margins.
- Cross-System Identity Resolution:Anonymous feedback channels must reconcile with attributed performance data for longitudinal analysis. Engineering teams struggle to preserve privacy guarantees while enabling predictive modeling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Employee Engagement Solutions Market |
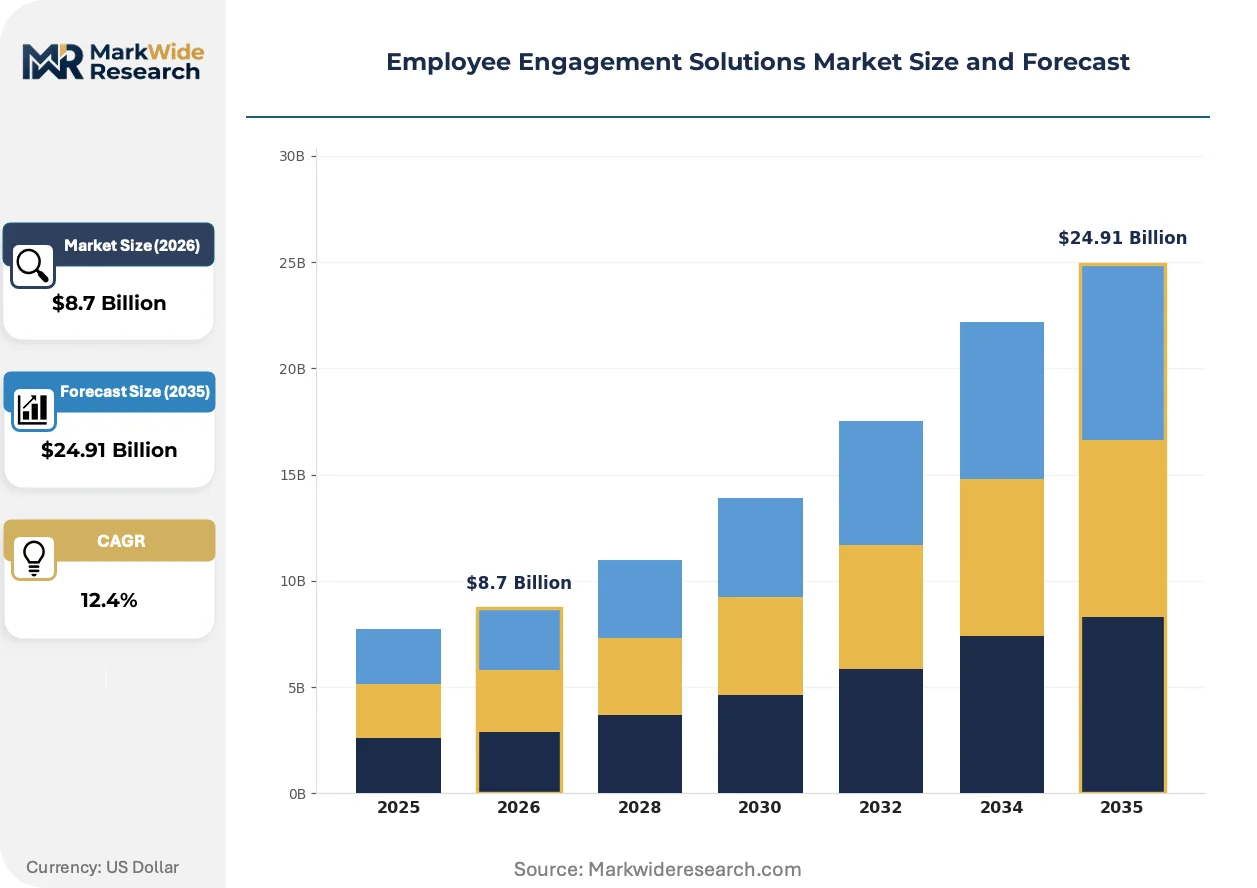
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $24.91 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Feedback Tools, Performance Management, Recognition Platforms, Survey Software Deployment Model: On-Premise, Cloud-Based, Hybrid, Software as a Service End User: Corporates, SMEs, Non-Profits, Educational Institutions Employee Category: Full-Time, Part-Time, Contract, Remote |
| Companies Covered | Lattice, Culture Amp Pty Ltd, Workvivo Limited, Leapsome GmbH, 15Five, Smartly, Inc. (Bonusly), Kudos, Inc., Workday Peakon, Vantage Circle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Employee Engagement Solutions Market Emerging Trajectories
Workforce analytics is fragmenting from monolithic suites into composable microservices. Buyers increasingly assemble engagement stacks from specialized point solutions rather than accepting bundled compromise.
Natural language processing is decomposing open-text survey responses into structured sentiment taxonomies. Mid-market enterprises adopt these tools to replace manual coding of qualitative feedback. The technology is compressing insight-to-action timelines from weeks to hours.
The EU AI Act's risk-classification framework is reshaping algorithmic deployment strategies. Vendors serving European workforces must document training data provenance and model decision logic. Performance scoring tools face heightened scrutiny in Germany and France where works councils exercise co-determination rights over automated evaluation systems.
Subscription fatigue is altering vendor relationship economics. Enterprise buyers resist seat-based pricing for sporadically used modules. Usage-based and outcome-tied contracts are displacing annual commitments in technology sector procurement, particularly among Series C and D stage companies with volatile headcount planning.
Employee Engagement Solutions Market Segmentation
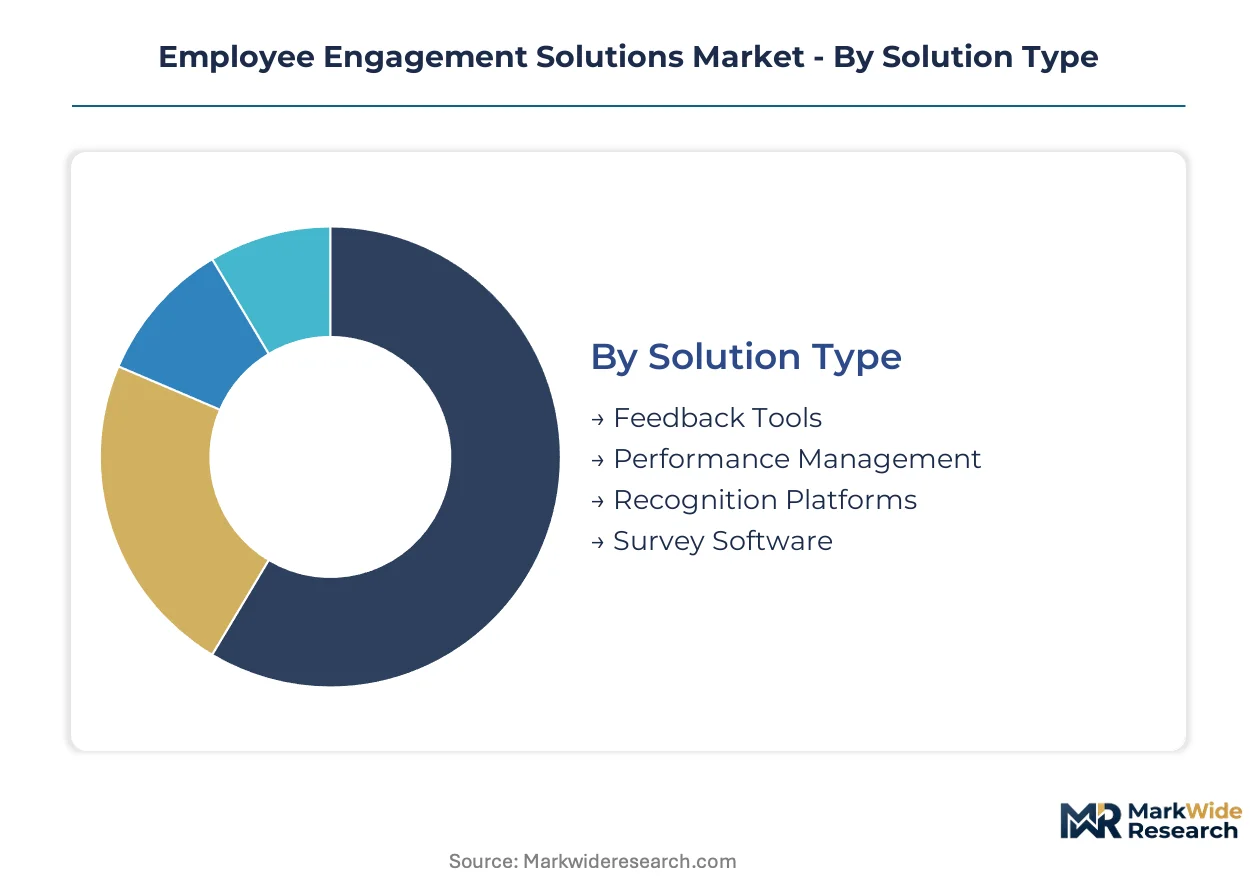
Segmentation in employee engagement solutions reveals how procurement priorities diverge across regulatory environments, technical architectures, and workforce compositions. Buyers select configurations based on disclosure mandates, IT infrastructure constraints, and labor classification complexity.
Solution Type:
SEC Item 101(c) and EU CSRD disclosure requirements create divergent demand profiles across solution categories, with audit-grade documentation becoming a non-negotiable specification.
- Recognition Platforms:Monetary and non-monetary reward workflows integrate with payroll systems through pre-built connectors to ADP, Workday, and SAP. Technology sector buyers in the United States favor these tools as retention instruments for distributed engineering teams. These platforms face the steepest expansion trajectory as reward automation displaces manual HR administration.
- Feedback Tools:Anonymous whistleblower channels satisfy OSHA anti-retaliation statutes and SEC disclosure mandates for publicly traded employers. Financial services firms in New York and Chicago deploy these systems to satisfy regulatory examination protocols. Real-time sentiment capture preserves participation rates through sub-second API response architectures.
- Performance Management:AI-driven goal-setting modules with ISO 30414 metric exports serve mid-market enterprises scaling beyond spreadsheet-based reviews.
- Survey Software:Pulse polling instruments with natural language processing decomposition compress insight-to-action timelines for qualitative feedback analysis.
Established volume favors Feedback Tools; emerging adoption favors Recognition Platforms.
Deployment Model:
IT department staffing levels and compliance patching responsibilities determine architecture selection, with zero-infrastructure onboarding becoming the dominant procurement criterion.
- Cloud-Based:API-first platforms with automatic security updates eliminate on-premise maintenance burdens. Mid-market enterprises between 500-5,000 employees prioritize these deployments for rapid rollout without dedicated infrastructure teams. The shift away from capital expenditure models accelerates procurement velocity.
- Software as a Service:Subscription contracts with usage-based pricing alternatives displace annual commitments among Series C and D stage companies with volatile headcount planning. SaaS configurations dominate technology sector procurement in Austin, Seattle, and San Francisco.
- Hybrid:Split architectures accommodate data sovereignty requirements for cross-border workforce analytics in multi-national employers.
- On-Premise:Legacy HRIS integration requirements in established enterprises sustain demand for controlled infrastructure environments.
Deployment gravity centers on Cloud-Based systems; Hybrid architectures gain share fastest among regulated multi-nationals.
End User:
Organization size dictates customization depth requirements and per-seat spending thresholds, creating distinct vendor competitive arenas.
- SMEs:Scaling organizations prioritize out-of-box functionality over configuration complexity. These buyers drive absolute segment expansion through cloud-native platform adoption. Procurement cycles compress as pre-configured templates reduce implementation timelines.
- Corporates:Fortune 1000 employers demand audit trails and standardized metric exports for ISO 30414 compliance. Deep per-seat spending sustains vendor R&D investment in advanced analytics modules.
- Non-Profits:Grant-funded operating models constrain subscription budgets and favor modular purchasing approaches.
- Educational Institutions:Academic calendar cycles and tenure-track employment structures create unique engagement measurement requirements distinct from corporate workforce models.
Corporates anchor current revenue concentration; SMEs represent the steepest adoption climb.
Employee Category:
Labor classification fragmentation complicates unified engagement platform deployment, with remote worker inclusion becoming a post-pandemic architectural requirement.
- Remote:Distributed workforce models institutionalized across technology and financial services sectors demand real-time sentiment monitoring independent of physical location. Hybrid work policies in the United States normalize continuous polling instruments for geographically dispersed teams. Platform vendors compete on mobile-first interface design for this segment.
- Full-Time:Core workforce populations retain deepest integration with performance management and career development modules. Benefits-connected recognition workflows concentrate demand among salaried employee populations.
- Contract:Contingent labor engagement measurement faces legal classification constraints that limit traditional platform applicability.
- Part-Time:Hourly scheduling complexity and high turnover rates reduce per-employee platform investment economics for this category.
Full-Time workers sustain platform utilization depth; Remote classifications expand most quickly across buyer specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based vendors export cloud-native engagement platforms to European and Asia-Pacific enterprises navigating hybrid work mandates. Cross-border procurement flows concentrate through Dublin, Singapore, and Amsterdam as regional compliance hubs.
United States
Technology and financial services sectors in Austin, Seattle, and New York Metro institutionalized distributed workforce models requiring real-time sentiment monitoring. SEC Item 101(c) of Regulation S-K compels standardized engagement metrics in annual filings for publicly traded employers. Silicon Valley vendors anchor R&D investment in AI-driven goal-setting modules for mid-market scaling organizations.
Germany
Industrial conglomerates in Bavaria and North Rhine-Westphalia deploy engagement platforms to manage co-determination rights under works council agreements. The EU AI Act imposes high-risk system obligations on predictive attrition models, extending vendor sales cycles. Berlin-based HR tech clusters specialize in psychometric assessment frameworks for ISO 30414 compliance exports.
United Kingdom
Financial services firms in London and Edinburgh prioritize anonymous feedback channels satisfying whistleblower protections under the Employment Rights Act. The Financial Conduct Authority examines engagement metric disclosures as part of operational resilience frameworks. Manchester and Birmingham technology corridors drive mid-market adoption of SaaS recognition platforms.
Japan
Manufacturing headquarters in Tokyo and Osaka integrate engagement tools with lifetime employment succession planning systems. METI guidelines on human capital disclosure accelerate dashboard standardization for listed enterprises. Nagoya automotive clusters experiment with sentiment monitoring for supplier network coordination.
India
IT services exporters in Bengaluru and Hyderabad deploy engagement platforms across delivery centers serving North American and European clients. SEBI's Business Responsibility and Sustainability Reporting mandates human capital disclosures for top-listed companies. Mumbai financial institutions pilot recognition platforms for retention of quantitative analyst talent.
Employee Engagement Solutions Market Vendor Landscape
Player mix skews toward specialized SaaS vendors with API-first architectures rather than consolidated enterprise suites. The competitive arena fragments across recognition platforms, feedback tools, performance management modules, and survey software specialists. Two strategic archetypes dominate: psychometric-science credential holders competing on organizational research depth, and social-intranet architects competing on communication platform convergence. M&A activity concentrates on payroll connector acquisitions and natural language processing capability roll-ups.
Within the science-credentialed tier, Culture Amp Pty Ltd and Lattice occupy positions anchored by validated assessment frameworks and AI-driven goal-setting modules respectively. Leapsome GmbH represents the European vendor archetype navigating EU AI Act compliance requirements. These three exemplify how vendors differentiate through either psychometric depth or workflow automation density rather than bundled suite breadth.
| Leading Market Players |
|---|
| Lattice |
| Culture Amp Pty Ltd |
| Workvivo Limited |
| Leapsome GmbH |
| 15Five |
| Smartly, Inc. (Bonusly) |
| Kudos, Inc. |
| Workday Peakon |
| Vantage Circle |
| Others |
Supply Flow & Price Mechanics
ISO 30414 human capital reporting standards gate both vendor qualification and price differentiation simultaneously, compelling enterprise procurement teams to pay premiums for audit-grade documentation while excluding point solutions lacking standardized metric exports. This regulatory compression collapses evaluation cycles and concentrates pricing power among incumbent platforms with pre-built compliance architectures.
Pricing Analysis
Cloud-native first-generation platforms command subscription premiums against legacy on-premise systems and emerging next-gen AI-native entrants still proving ROI. Three-tier pricing structure across enterprise, mid-market, and SMB levels segments buyers by customization depth and integration complexity. Pricing pressure stems from subscription fatigue among technology sector buyers resisting seat-based models for sporadically used modules. SMEs exhibit highest price sensitivity and favor usage-based contracts; Fortune 1000 employers retain lowest sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Container availability constraints on trans-Pacific trade lanes elevate inbound logistics costs for hardware-dependent edge-deployment components, though pure software vendors remain insulated. Engineering talent concentrates in the United States, Germany, and India, with industrial-organizational psychologists and machine learning specialists forming the critical input bottleneck. Supply chain risk centers on single-source vulnerability for natural language processing components licensed from hyperscaler APIs. Distribution runs through direct enterprise sales teams supplemented by systems integrator partnerships for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Employee engagement solutions constitute a defensive-moat market where switching costs lock in enterprise clients through embedded workflow integration and accumulated historical sentiment data. Regulatory entrenchment deepens these barriers as ISO 30414 and SEC disclosure mandates compound compliance-driven stickiness.
For Market Incumbents: Consolidate payroll connector capabilities through targeted acquisitions of specialist integration firms, neutralizing the 40-60% implementation resource drain that threatens renewal rates. Deepen vertical integration into psychometric assessment science by recruiting credentialed organizational psychologists, defending against AI-native entrants lacking validated frameworks. The emerging threat of algorithmic risk classification under EU AI Act compliance requirements demands proactive audit trail investments. For New Entrants and Emerging Players: Mid-market out-of-box functionality gaps represent the most penetrable white space, as scaling organizations between 500-5,000 employees remain underserved by enterprise-grade complexity. Recognition platform convergence with benefits systems offers a second entry vector through pre-built ADP and Workday connectors. A product-led growth motion targeting HR operations leaders with freemium pulse survey tools provides the most efficient go-to-market angle against incumbent sales cycles. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment models as API-first architectures eliminate infrastructure overhead, improving SaaS margin profiles. Acquisition target archetypes include natural language processing specialists with workforce analytics applications and regional compliance vendors with EU AI Act audit capabilities. The signal to watch is SEBI and METI disclosure mandate expansion accelerating dashboard standardization requirements in Asia-Pacific markets.| Strategic Initiative | Industry Significance |
|---|---|
| Payroll Connector Acquisition | Pre-built ADP and Workday integrations reduce implementation timelines and improve renewal rates. |
| Psychometric Science Layering | Validated assessment frameworks command premium positioning in Fortune 1000 RFP processes. |
| EU AI Act Compliance Investment | Audit trail documentation extends vendor viability across European works council environments. |
| Mid-Market Product Simplification | Out-of-box templates capture scaling organizations underserved by enterprise complexity. |
| Natural Language Processing Roll-up | Open-text sentiment decomposition compresses insight-to-action timelines for qualitative feedback. |
Methodological Framework
A standing panel of HR technology procurement officers, industrial-organizational psychologists, workforce analytics directors, and IT integration specialists provided ongoing calibration across primary interview phases. Secondary validation drew from SEC Item 101(c) disclosure filings, ISO 30414 implementation case studies, EU AI Act regulatory texts, and hyperscaler partnership announcements. Bottom-up vendor revenue estimates triangulated against top-down enterprise software spending benchmarks to ensure consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled deployment model, organization size, solution type, and regional regulatory cluster as primary segmentation dimensions. CAGRs were derived from trend extrapolation of adoption velocity curves and per-seat spending trajectories, with inputs including hybrid work policy institutionalization rates and whistleblower channel regulatory mandate expansion.
Forecasts assume regulatory continuity in SEC disclosure regimes and EU AI Act enforcement; material policy shifts would require re-modeling. Specific risks include algorithmic risk reclassification elevating compliance burdens and data sovereignty fragmentation favoring regional point solutions over global platforms. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Business Card Software Market
Software & Services
Parks and Playground Inspection Software Market
Software & Services
Content As a Service (Caas) Market
Software & Services
Global Sales Enablement Platform Market
Software & Services
Europe Contract Lifecycle Management Software Market
Software & Services
OCR Scanning Software Market
Software & Services
Global Online OCR Software Market
Software & Services
Website Builder Tool Market
Software & Services
Clustering Software Market
Software & Services
Global Translation Software Market
Software & Services
B2B Price Optimization and Management Software Market
Software & Services
Pay-Per-Click (PPC) Software Market
Software & Services
Global Decision Making Software Market
Software & Services
Electronic Data Interchange (EDI) Software Market
Software & Services
Tech Support Services Market
Software & Services
Digital Illustration App Market