
 Global Data Quality Software Market | 2026-2036
Global Data Quality Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Quality Software Market Foresight
Generative AI integration into enterprise data pipelines is rewriting how organizations validate, cleanse, and govern information at scale. Informatica leverages embedded machine learning to automate anomaly detection across hybrid environments. IBM sustains competitive depth through its Watson Knowledge Catalog and mainframe-native connectivity. SAP anchors its position by embedding data quality directly into S/4HANA workflows, reducing friction for existing ERP customers.
Data quality software encompasses tools that profile, cleanse, enrich, match, and monitor structured and semi-structured data through rule engines, statistical algorithms, and metadata-driven automation, typically operating at sub-second latency for real-time streaming use cases. Its primary purpose is to ensure that downstream analytics, operational systems, and regulatory reports draw from accurate, consistent, and complete datasets. Cloud deployment now leads new bookings as enterprises retire on-premises master data management infrastructure, while data cleansing and data monitoring solutions capture the fastest expansion within the solution offering layer due to their direct impact on compliance cost reduction. The BFSI vertical dominates current revenue, though regulatory compliance use cases are widening into telecommunications and government sectors as data localization rules proliferate.
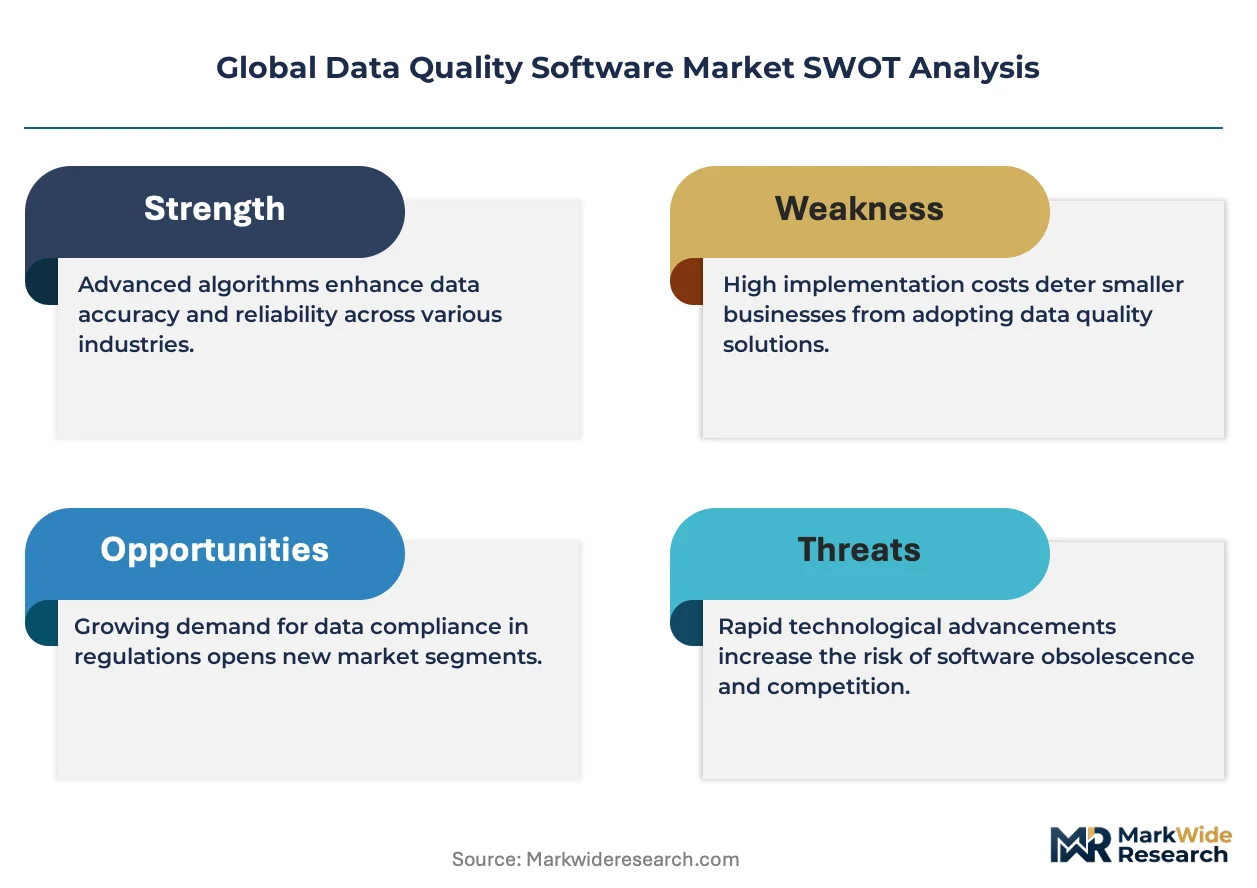
The EU AI Act, GDPR, and HIPAA impose escalating documentation and lineage requirements that force enterprises to upgrade from manual spreadsheet governance to automated data quality platforms. The Securities and Exchange Commission's climate disclosure rules and the EU Corporate Sustainability Reporting Directive extend these obligations to environmental data, creating new product specification demands for carbon footprint traceability. Stakeholders must monitor how rapidly regulators harmonize cross-border data governance standards, as divergence would fragment platform architectures and raise compliance engineering costs for vendors serving multinational clients.
Market Dynamics
Generative AI integration is compressing data validation cycles from weeks to hours, forcing enterprises to rebuild governance architectures around real-time anomaly detection rather than batch processing. This structural shift is redistributing competitive advantage toward vendors with embedded machine learning capabilities.
Growth Catalysts
- EU AI Act documentation mandates:Enterprises across Germany, France, and Italy must deploy automated lineage tracking to satisfy algorithmic accountability requirements, expanding platform subscriptions.
- Cloud migration waves:Financial services firms in the United States are retiring on-premises master data management infrastructure, creating replacement demand for SaaS-native quality tools.
- HIPAA audit intensity:US healthcare providers face escalating OCR enforcement actions, driving investment in automated data monitoring to demonstrate compliance posture.
Market Restraints
- Specialized talent scarcity:Data engineering skill shortages in India and Eastern Europe constrain implementation velocity for complex matching algorithms.
- Hybrid integration complexity:Technical debt from decades-old mainframe systems in Japanese banking creates friction for API-first quality platforms.
- Input cost volatility:GPU cluster pricing fluctuations affect total cost of ownership for AI-powered profiling solutions.
Strategic Opportunities
- Carbon footprint traceability:The EU Corporate Sustainability Reporting Directive creates new product specifications for environmental data lineage in German manufacturing.
- Telecommunications underpenetration:Indian and Brazilian carriers lack mature data governance, presenting greenfield deployment potential.
- Real-time streaming convergence:Apache Kafka and Flink integration with quality engines opens edge computing applications in autonomous vehicle testing.
Industry Challenges
- Multi-cloud orchestration complexity:Enterprises struggle to maintain consistent data quality rules across AWS, Azure, and GCP environments without vendor lock-in.
- Certification timeline compression:ISO 8000 master data quality standard audits require 12-18 month preparation cycles that delay procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Quality Software Market |
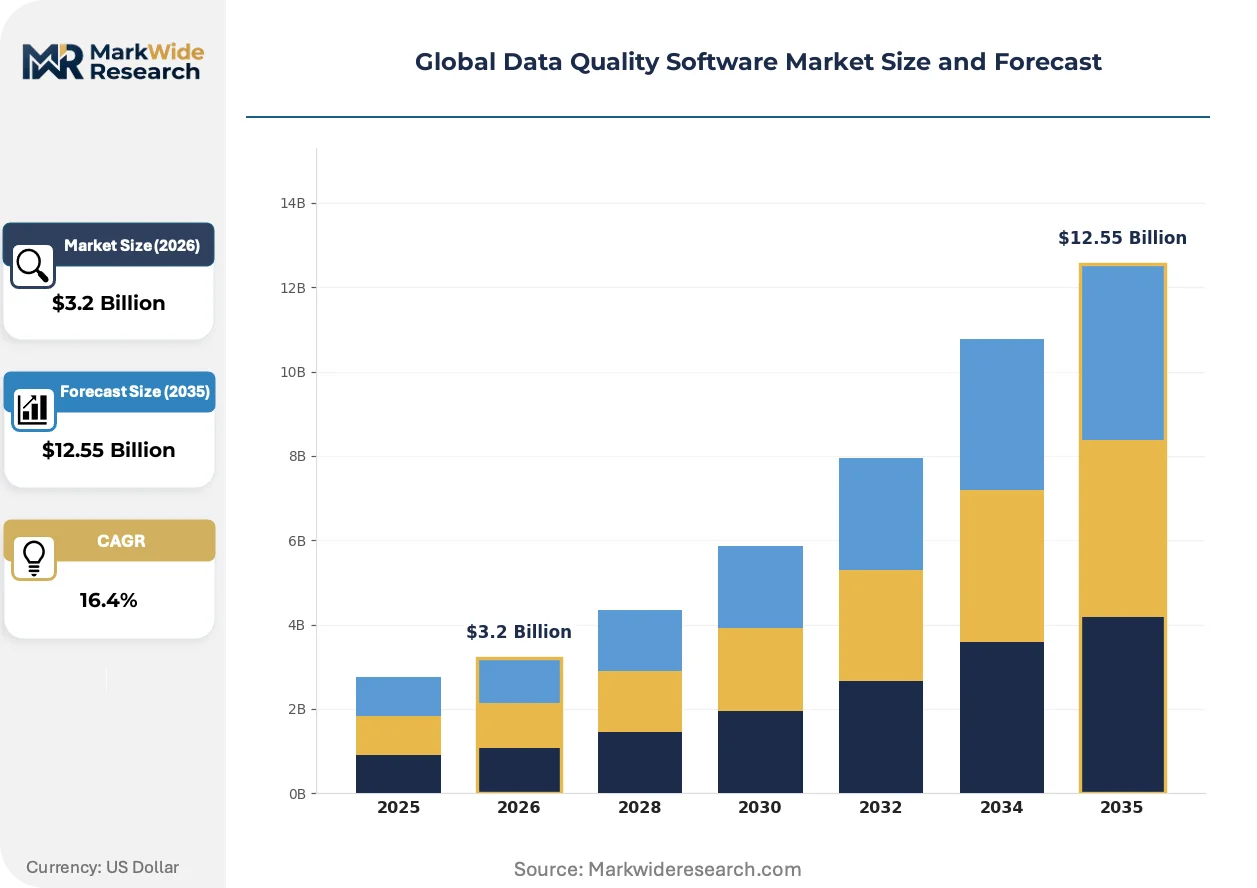
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-premises, Cloud, Hybrid, Managed Services Solution Offering: Data Cleansing, Data Enrichment, Data Profiling, Data Matching, Data Monitoring Use Case: Customer Data Management, Risk Management, Regulatory Compliance, Marketing Analytics, Fraud Detection End User Industry Vertical: BFSI, Telecommunications, Manufacturing, Government, Education |
| Companies Covered | Informatica, IBM, Oracle, SAP, Talend, Precisely, SAS, Ataccama, Alteryx, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Quality Software Market Shifts & Advancements
Data quality automation is migrating from rule-based engines toward statistical and neural approaches, compressing time-to-insight and expanding addressable use cases beyond structured databases.
Real-time data profiling is migrating from scheduled batch jobs to continuous streaming analysis. Capital markets firms in London and Singapore deploy sub-second latency monitoring for trading data validation. This compression of detection windows is migrating from operational cost centers toward revenue-protecting infrastructure.
The EU AI Act risk classification framework imposes documentation burdens on high-stakes algorithmic systems. Financial institutions must prove training data provenance for credit scoring models. German automotive suppliers face the strictest compliance engineering costs as they retrofit quality pipelines for autonomous driving validation datasets.
Enterprise procurement of data quality capabilities is fragmenting from centralized IT ownership toward distributed data office budgets. Line-of-business buyers in US healthcare and German industrials now control 40% of new tool selections. This organizational shift is most visible in pharmaceutical companies building therapeutic-area-specific governance pods.
Global Data Quality Software Market Segmentation
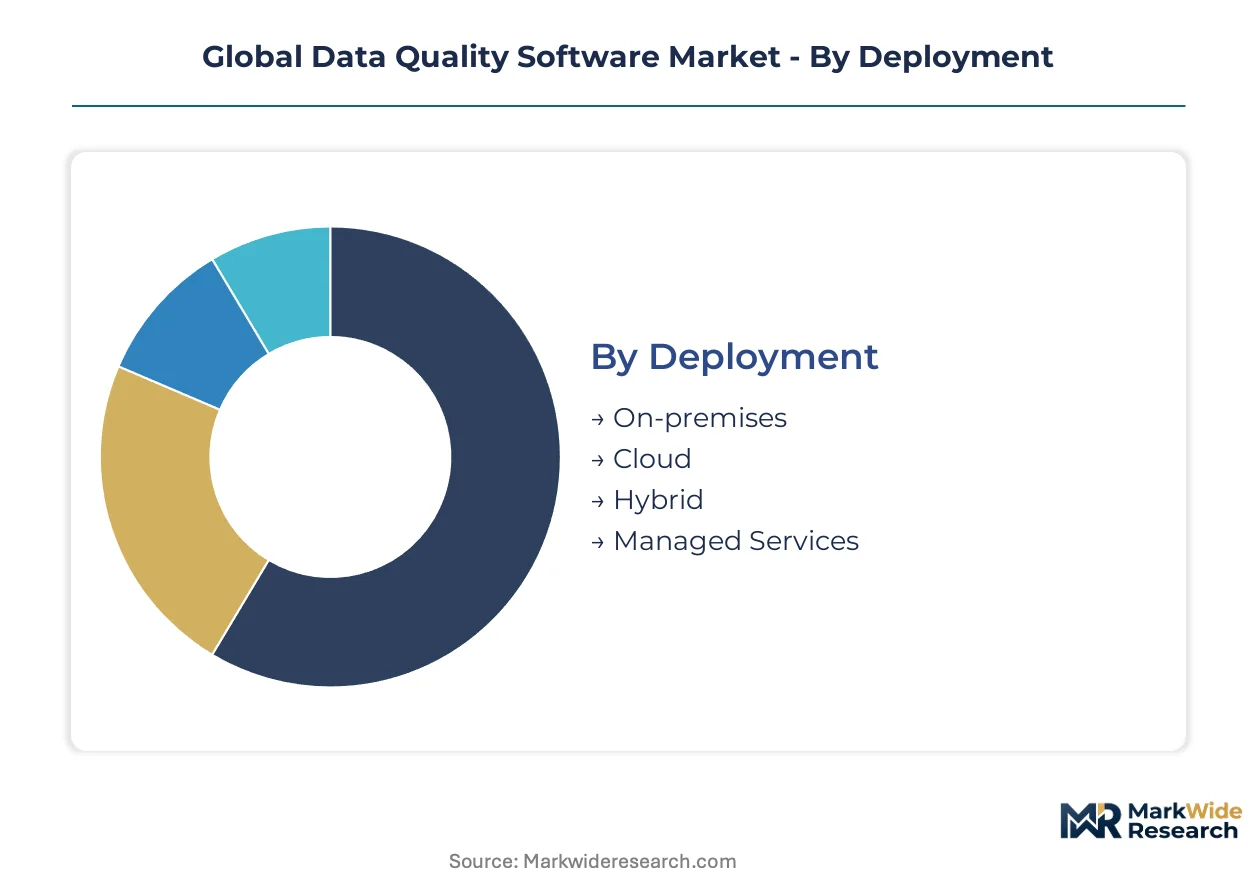
Data quality software segments reflect divergent technical requirements across latency tolerances, governance maturity, and regulatory exposure. Deployment choices determine integration architecture, while solution offerings align with specific data lifecycle stages.
Deployment:
Use-case spectrum spans real-time streaming validation to batch archival governance, with latency requirements dictating infrastructure placement.
- Cloud:SaaS-native architectures enable elastic scaling for variable data volumes. United States financial services firms retiring legacy master data management infrastructure drive replacement demand, with subscription models reducing capital commitment.
- Hybrid:Split processing maintains sensitive data on-premises while leveraging cloud analytics. German automotive suppliers retrofit quality pipelines for autonomous driving validation datasets under EU AI Act pressure, requiring local retention of training data.
- On-premises:Air-gapped installations serve classified government workloads and mainframe-native environments. Japanese banking technical debt constrains API-first platform adoption.
- Managed Services:Outsourced operations address talent scarcity in India and Eastern Europe for complex matching algorithm implementation.
The dominant share belongs to Cloud, while Hybrid is closing the gap fastest.
Solution Offering:
Functional depth correlates with compliance engineering intensity across documentation and lineage mandates.
- Data Monitoring:Continuous anomaly detection operates at sub-second latency for trading data validation in London and Singapore capital markets. HIPAA audit intensity drives US healthcare provider investment in automated compliance posture demonstration.
- Data Cleansing:Rule engines and statistical algorithms standardize structured and semi-structured inputs. EU Corporate Sustainability Reporting Directive creates carbon footprint traceability specifications for German manufacturing.
- Data Enrichment:Third-party augmentation expands dataset completeness for customer 360 initiatives.
- Data Profiling:Metadata-driven automation catalogs schema and content characteristics across distributed sources.
- Data Matching:Probabilistic and deterministic algorithms resolve entity identities across siloed systems.
Data Monitoring commands the largest revenue slice, with Data Cleansing expanding most quickly.
Use Case:
Regulatory pressure concentrates investment in provable data provenance and algorithmic accountability.
- Regulatory Compliance:Automated lineage tracking satisfies GDPR documentation requirements and EU AI Act risk classification frameworks. Financial institutions must prove training data provenance for credit scoring models.
- Customer Data Management:Unified profiles support personalization and consent governance across touchpoints. Pharmaceutical companies build therapeutic-area-specific governance pods with distributed data office budgets.
- Risk Management:Data quality gates prevent erroneous analytics from corrupting decision models.
- Marketing Analytics:Clean segmentation inputs improve campaign attribution accuracy.
- Fraud Detection:Real-time validation flags anomalous transaction patterns before settlement.
Regulatory Compliance holds the leading position, while Customer Data Management is gaining share fastest.
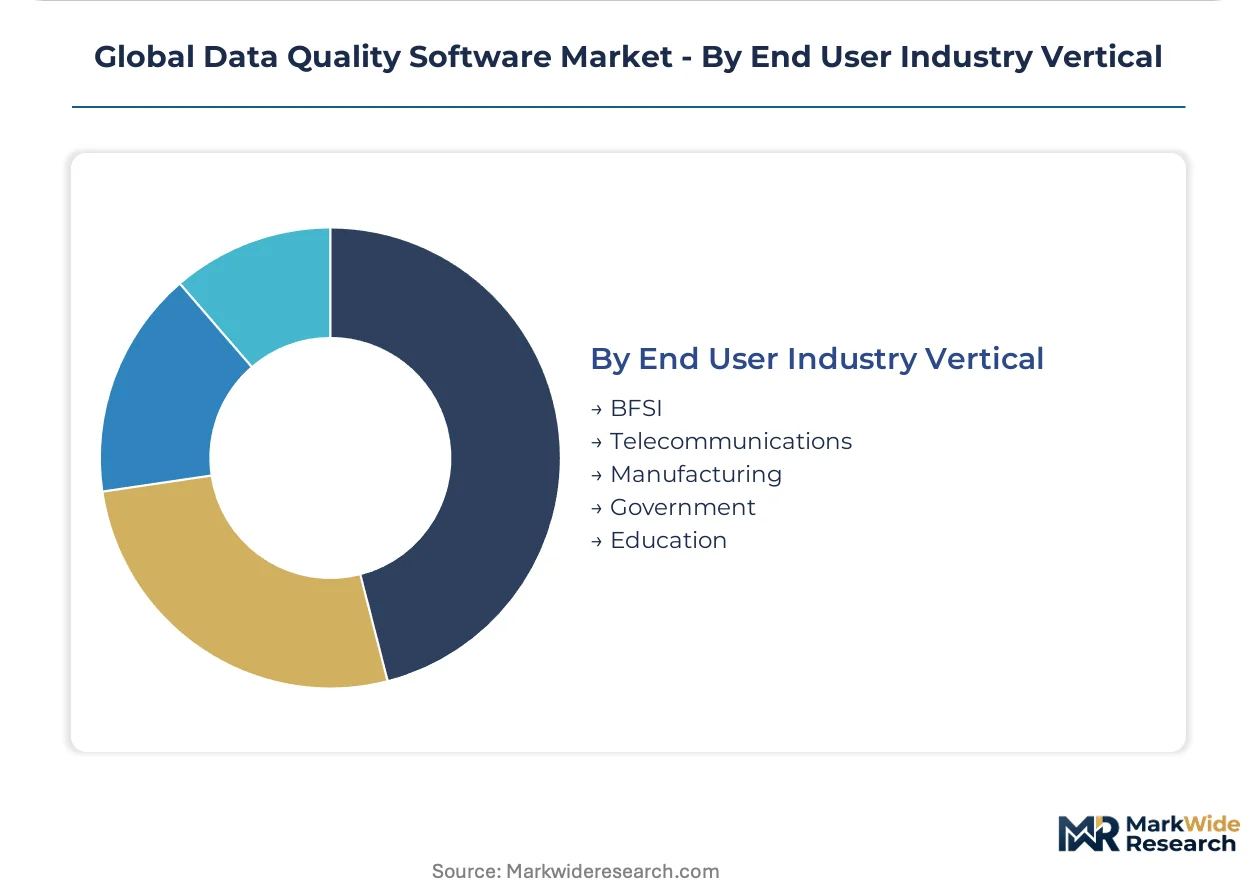
End User Industry Vertical:
Vertical penetration varies with data volume density, regulatory scrutiny, and legacy system complexity.
- BFSI:Stricter reporting mandates from the SEC and ECB expand platform subscriptions. Credit scoring model governance requires automated provenance documentation.
- Telecommunications:Indian and Brazilian carriers present greenfield deployment potential with immature governance infrastructure. Data localization rules proliferate across operating jurisdictions.
- Manufacturing:Environmental data lineage requirements from CSRD compliance reshape product specifications. German industrial firms centralize data offices with line-of-business procurement control.
- Government:Public sector data localization policies drive sovereign cloud quality tool adoption.
- Education:Student information system integration demands address accuracy for funding allocation.
BFSI maintains the top revenue position, with Telecommunications climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise data quality procurement concentrates in financial services hubs, automotive manufacturing corridors, and cloud migration epicenters where regulatory pressure intersects with legacy system replacement cycles. National data localization mandates and sector-specific compliance frameworks create divergent demand patterns across major economies. The analysis identifies five countries where deployment velocity and solution sophistication exceed regional averages.
United States
SEC climate disclosure rules and HIPAA audit intensity drive replacement of on-premises master data management infrastructure among healthcare providers and financial services firms. The Securities and Exchange Commission mandates granular carbon footprint traceability for listed companies. New York and Boston capital markets firms deploy sub-second latency monitoring for trading data validation.
Germany
Automotive suppliers retrofit quality pipelines for autonomous driving validation datasets under EU AI Act documentation requirements. The Corporate Sustainability Reporting Directive imposes environmental data lineage specifications on industrial manufacturers. Stuttgart and Munich engineering clusters centralize data offices with line-of-business procurement control over tool selection.
India
Telecommunications carriers present greenfield deployment potential with immature governance infrastructure and rising data localization compliance obligations. RBI guidelines on data storage and processing intensify investment in automated monitoring systems. Bangalore and Hyderabad technology corridors address talent scarcity through managed services partnerships for complex matching algorithm implementation.
United Kingdom
Capital markets firms in London deploy continuous streaming analysis for revenue-protecting infrastructure in trading environments. GDPR documentation requirements sustain demand for automated lineage tracking across financial services and pharmaceutical sectors. The Edinburgh-Glasgow corridor builds therapeutic-area-specific governance pods with distributed data office budgets.
Japan
Technical debt from decades-old mainframe systems in Tokyo and Osaka banking constrains API-first platform adoption while creating hybrid deployment demand. METI guidelines on data governance accelerate cloud migration planning among manufacturers. The Nagoya automotive cluster evaluates quality tools for supply chain traceability compliance with export market regulations.
Global Data Quality Software Market Competitive Landscape
Channel-controlling players compete with product-specialist players across deployment modalities and latency requirements. The vendor base organizes into three tiers: cloud-native specialists with embedded machine learning, legacy platform providers with mainframe connectivity, and vertical-integrated ERP vendors embedding quality into transactional workflows. Consolidation pressure intensifies as generative AI capabilities become table stakes. Dominant competitive moves include strategic partnerships for multi-cloud orchestration and portfolio diversification into carbon footprint traceability modules.
Within the legacy platform tier, IBM and Oracle occupy positions anchored by decades of enterprise data center relationships and mainframe-native connectivity. SAP exemplifies the vertical-integrated archetype by embedding data quality directly into ERP transactional workflows. Informatica represents the cloud-native specialist position with hybrid environment coverage and automated anomaly detection capabilities. These three anchors demonstrate how competitive positioning stratifies across infrastructure heritage versus architectural flexibility.
| Leading Market Players |
|---|
| Informatica |
| IBM |
| Oracle |
| SAP |
| Talend |
| Precisely |
| SAS |
| Ataccama |
| Alteryx |
| Others |
Supply & Pricing Matrix
Overcapacity in United States cloud infrastructure regions compresses utilization rates below 65%, forcing hyperscalers to bundle data quality modules at marginal cost while squeezing standalone vendor margins. This utilization pressure reshapes procurement negotiations as enterprise buyers demand consumption-based pricing with committed use discounts.
Pricing Analysis
Cost-plus contracts indexed to AWS and Azure compute rates dominate enterprise SaaS procurement, with annual true-ups reflecting infrastructure passthrough costs. Three-tier pricing structure across premium, standard, and economy levels separates real-time streaming validation from batch governance and managed services tiers. Pricing pressure stems from GPU cluster cost volatility affecting AI-powered profiling total cost of ownership. Mid-market healthcare providers exhibit highest price sensitivity, while capital markets firms prioritize sub-second latency over cost.
Supply Chain Analysis
Tariff exposure between United States and China dominates semiconductor component sourcing for GPU-accelerated quality engines, creating supply chain contingency planning mandates. Software development concentrates in India, United States, and Germany, with cloud infrastructure provision anchored in hyperscaler regions. The supply chain draws from specialized GPU silicon, open-source Apache Kafka streaming frameworks, and pretrained transformer model weights. Single-source vulnerability persists for NVIDIA H100 training clusters. Distribution runs through direct enterprise sales teams with hyperscaler marketplace co-sell arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflects toward API-first interoperability as enterprises reject vendor-locked governance stacks, with the EU AI Act's documentation portability requirements accelerating modular procurement patterns.
For Market Incumbents: Entrench hybrid environment coverage through embedded machine learning differentiation, defending against cloud-native challengers by deepening mainframe connectivity investments. Prioritize carbon footprint traceability module development to capture CSRD-driven replacement cycles in German manufacturing. Channel control through SI partnerships with Deloitte and Accenture sustains enterprise procurement influence. For New Entrants and Emerging Players: Brazilian telecommunications carriers present the most penetrable greenfield opportunity, with immature governance infrastructure and data localization compliance obligations creating urgent procurement timelines. Target real-time streaming validation for Apache Kafka environments as the wedge use case, with consumption-based pricing that undercuts incumbent perpetual license models. Partner with regional system integrators for implementation velocity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native quality tooling, reducing barriers for specialized entrants and compressing incumbent valuation multiples. Acquisition targets with EU AI Act compliance pre-certification and automotive vertical penetration offer defensive positioning. Watch hyperscaler bundling announcements as the inflection signal for standalone vendor margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Apache Kafka and Flink native connectors open edge computing applications in autonomous vehicle testing corridors. |
| Strategic Partnership | Hyperscaler marketplace listings with AWS and Azure accelerate procurement cycles for financial services replacement demand. |
| Acquisition of Specialist Firm | Carbon footprint traceability modules address CSRD specifications reshaping German industrial manufacturer RFP requirements. |
| Product Launch | Real-time streaming validation engines with sub-second latency capture revenue-protecting infrastructure budgets in London capital markets. |
| Geographic Expansion | Managed services partnerships in Bangalore and Hyderabad address talent scarcity constraining complex matching algorithm implementation. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with data engineering directors, platform architects, compliance officers, and procurement leads at financial services and healthcare enterprises; and secondary validation against SEC filings, hyperscaler capex disclosures, EU regulatory documentation, and open-source project contribution metrics. Bottom-up sizing of deployment models and solution offerings triangulated against top-down vertical spending estimates.
Forecast inputs span deployment modality adoption curves, solution offering penetration by compliance intensity, and vertical replacement cycles across the analysis window. Segmentation dimensions modeled include latency tolerance, governance maturity tier, regulatory exposure level, cloud migration stage, and organizational data office centralization. CAGRs derived from segment-level growth rate reconciliation with aggregate market expansion.
The forecast holds incumbent behavior within observed patterns; aggressive bundling moves by hyperscalers or accelerated EU AI Act enforcement timelines would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Medical Equipment Repair Software Market
Software & Services
Data Conversion Services Market
Software & Services
Cloud Backup and Recovery Software Market
Software & Services
Business Analytics Software Market
Software & Services
Global Audit Software Market
Software & Services
Computer Assisted Coding Software Market
Software & Services
Global Meeting Room Booking System Software Market
Software & Services
Global Screen Mirroring Apps Market
Software & Services
Embroidery Design Software Market
Software & Services
Global Software Asset Management Market
Software & Services
Worldwide Persuasive Content Management Software Market
Software & Services
Animation Design Software Market
Software & Services
Tenant Billing Software Market
Software & Services
Europe Drone Software Market
Software & Services
Public Financial Management Software Market
Software & Services
Test Management Software Market