
 Systems Administration Management Tools Market | 2026-2036
Systems Administration Management Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Systems Administration Management Tools Market Analytics
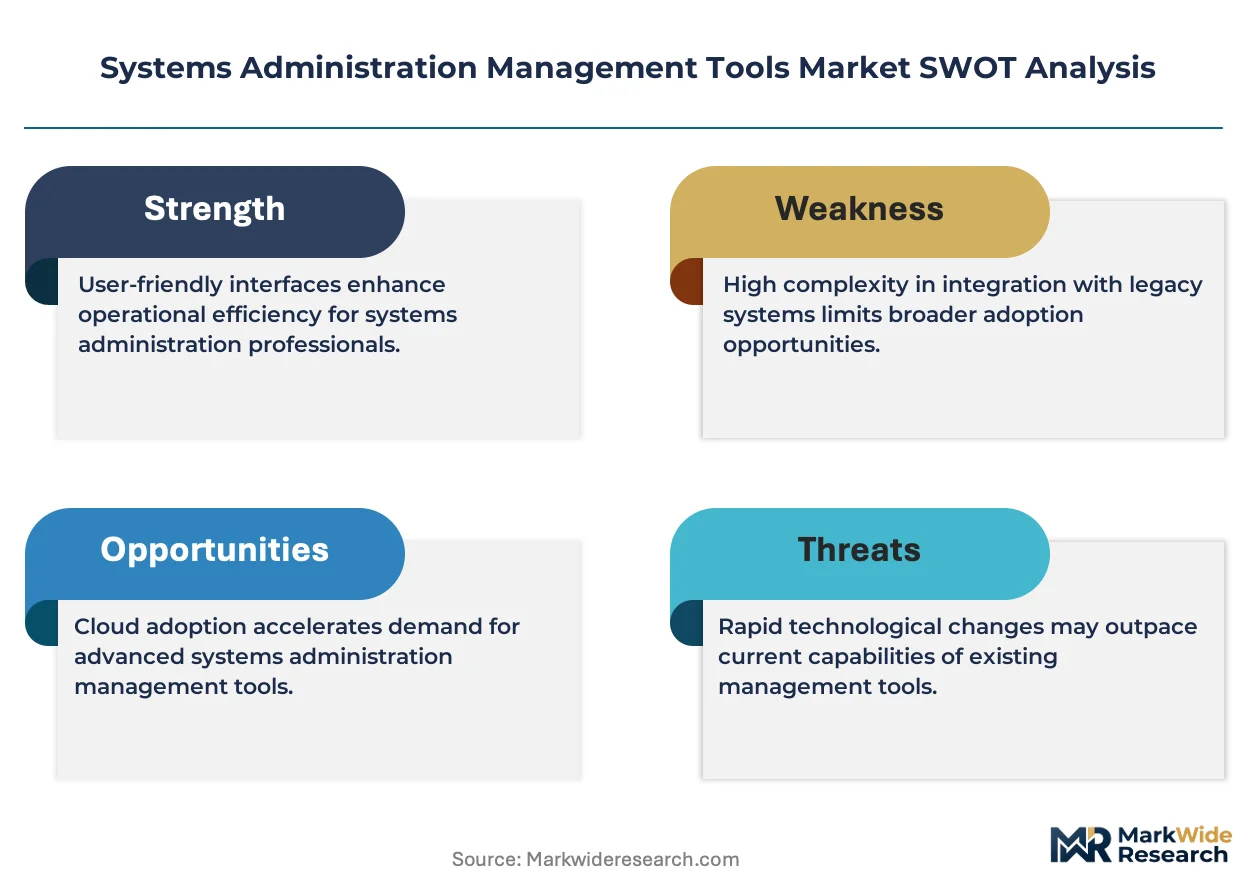
The EU CSRD is restructuring how enterprises report IT infrastructure emissions, forcing systems administration vendors to embed carbon-tracking modules. Microsoft leverages its Azure hybrid stack to anchor cloud-based deployment contracts across European regulated industries. IBM competes through mainframe-integrated management consoles that sustain high-margin services revenue. ServiceNow differentiates by positioning its workflow automation as the compliance layer for sustainability disclosures.
Systems administration management tools encompass software platforms, hardware appliances, and integrated services that monitor server health, automate patch deployment, orchestrate backup routines, and enforce security policies across heterogeneous IT estates, typically operating through agent-based or agentless architectures polling at intervals from 30 seconds to 5 minutes depending on criticality. Their primary commercial purpose is reducing mean time to resolution and preventing unplanned downtime in revenue-dependent digital operations. Cloud-based deployment is capturing the fastest expansion as enterprises retire on-premise data centers, while monitoring functionality remains the largest revenue pool due to its mandatory status in regulated sectors. SMB end users represent the most contested segment, with vendors racing to simplify pricing and reduce implementation cycles.
FDA 21 CFR Part 11, HIPAA security rules, and SEC cybersecurity disclosure requirements shape product roadmaps by mandating audit trails, access controls, and incident reporting capabilities that systems administration tools must natively support. The EU AI Act adds algorithmic transparency obligations for automated IT decision-making, pushing vendors to document how their platforms classify alerts or route tickets. Stakeholders must decide whether to build compliance modules in-house or partner with governance specialists as regulatory fragmentation between Washington and Brussels intensifies.
Market Dynamics
Cloud migration by financial services institutions is compressing deployment cycles and forcing vendors to re-architect platforms for hybrid infrastructure governance. The EU AI Act and NIS2 Directive are tightening compliance requirements simultaneously, creating dual pressure on product roadmaps.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:Automated IT decision-making now requires documented classification logic, expanding addressable market for governance-embedded platforms.
- Financial services cloud migration:Banks and insurers retiring on-premise data centers are procuring automation platforms at accelerated rates.
- German legacy modernization wave:Enterprise data center consolidation across the country is concentrating demand for orchestration tools.
Market Restraints
- Specialized talent scarcity:Shortage of engineers certified in both mainframe administration and cloud-native architectures limits implementation velocity.
- Input cost volatility in semiconductor components:Hardware appliance margins compress when chip supply tightens.
- Regulatory fragmentation between Washington and Brussels:Divergent cybersecurity disclosure requirements force dual compliance tracks.
Strategic Opportunities
- EU CSRD carbon-tracking integration:Sustainability disclosure mandates create white space for emissions-monitoring modules within administration platforms.
- SMB simplification race:Underpenetrated mid-market segment rewards vendors who reduce implementation cycles below 30 days.
- Agentless architecture convergence with zero-trust security:Combined deployment models open federal and defense procurement channels.
Industry Challenges
- Multi-generational system integration:Orchestration tools must bridge 30-year-old mainframe estates with Kubernetes clusters without service interruption.
- Compliance certification timeline compression:EU NIS2 Directive implementation deadlines outpace vendor audit completion rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Systems Administration Management Tools Market |
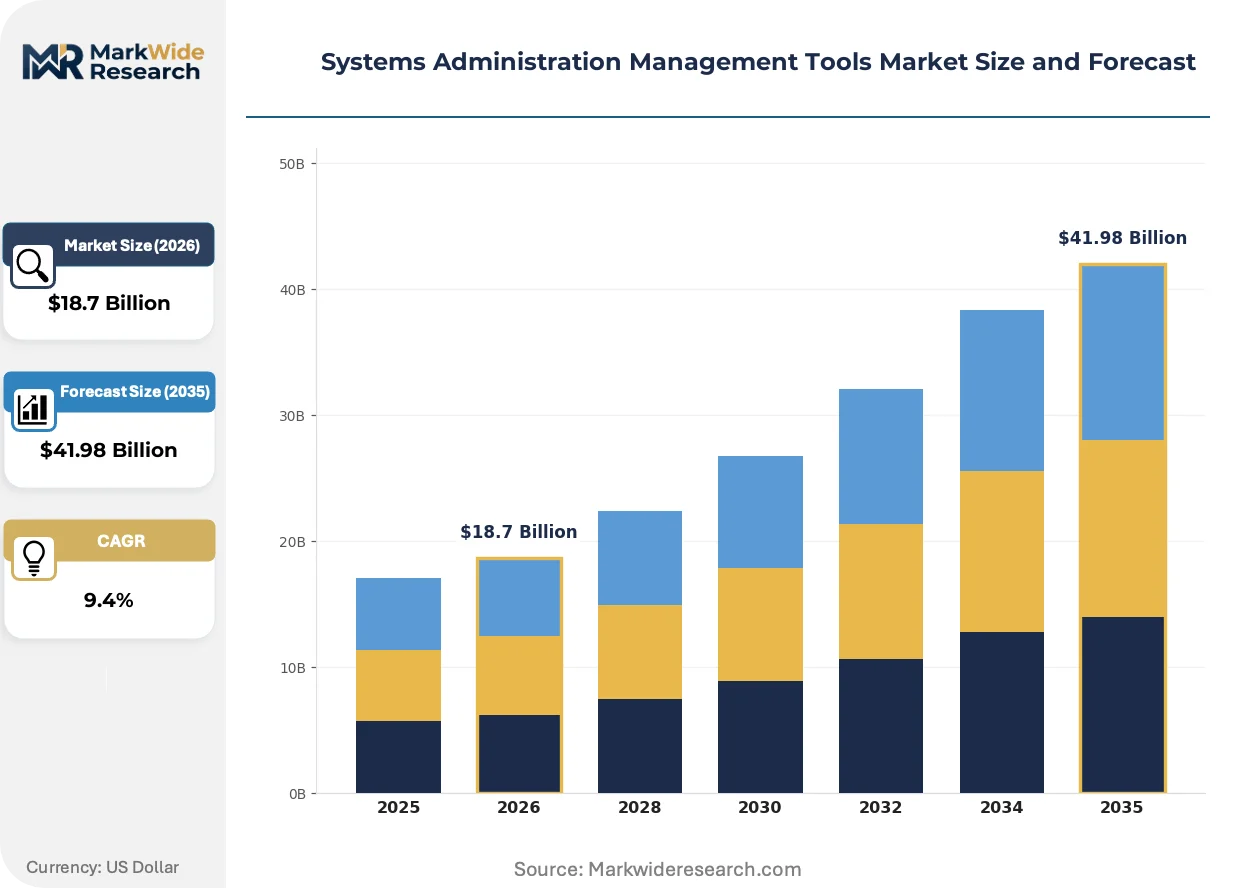
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premise, Cloud-Based, Hybrid, Managed Services End User: Enterprises, SMBs, Government Agencies, Educational Institutions Functionality: Monitoring, Automation, Backup, Security Management Product Type: Software Solutions, Hardware Appliances, Integrated Systems, Services |
| Companies Covered | VMware, Microsoft, Cisco Systems, IBM, Hewlett-Packard, ServiceNow, Atlassian, BMC Software, Broadcom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Systems Administration Management Tools Market Evolving Landscape
Artificial intelligence is rewriting how administration platforms classify alerts, route tickets, and predict failures. Three distinct vectors are reshaping competitive positioning: autonomous remediation capabilities, regulatory embedding, and procurement model transformation.
Agentless monitoring architectures are rewriting the economics of heterogeneous estate coverage. These platforms poll server health, network latency, and application performance without installed software agents. Mid-market enterprises in regulated sectors are adopting at the fastest pace. The shift is compressing total cost of ownership by eliminating agent maintenance overhead and expanding coverage to ephemeral cloud workloads previously invisible to traditional tools.
REACH chemical compliance and EU AI Act algorithmic transparency obligations are forcing vendors to document training data provenance and decision audit trails. Industrial consequence includes mandatory carbon footprint disclosure for IT infrastructure operations. German automotive and pharmaceutical manufacturers are most affected, responding by embedding governance modules directly into procurement specifications rather than retrofitting post-deployment.
Subscription consumption models are displacing perpetual license structures across the buyer base. Channel partners are unbundling implementation services from software contracts, creating direct vendor-customer relationships. This pattern is most visible in Nordic financial services, where cloud-native buyers reject multi-year lock-ins in favor of monthly scalability adjustments tied to workload volatility.
Systems Administration Management Tools Market Segmentation
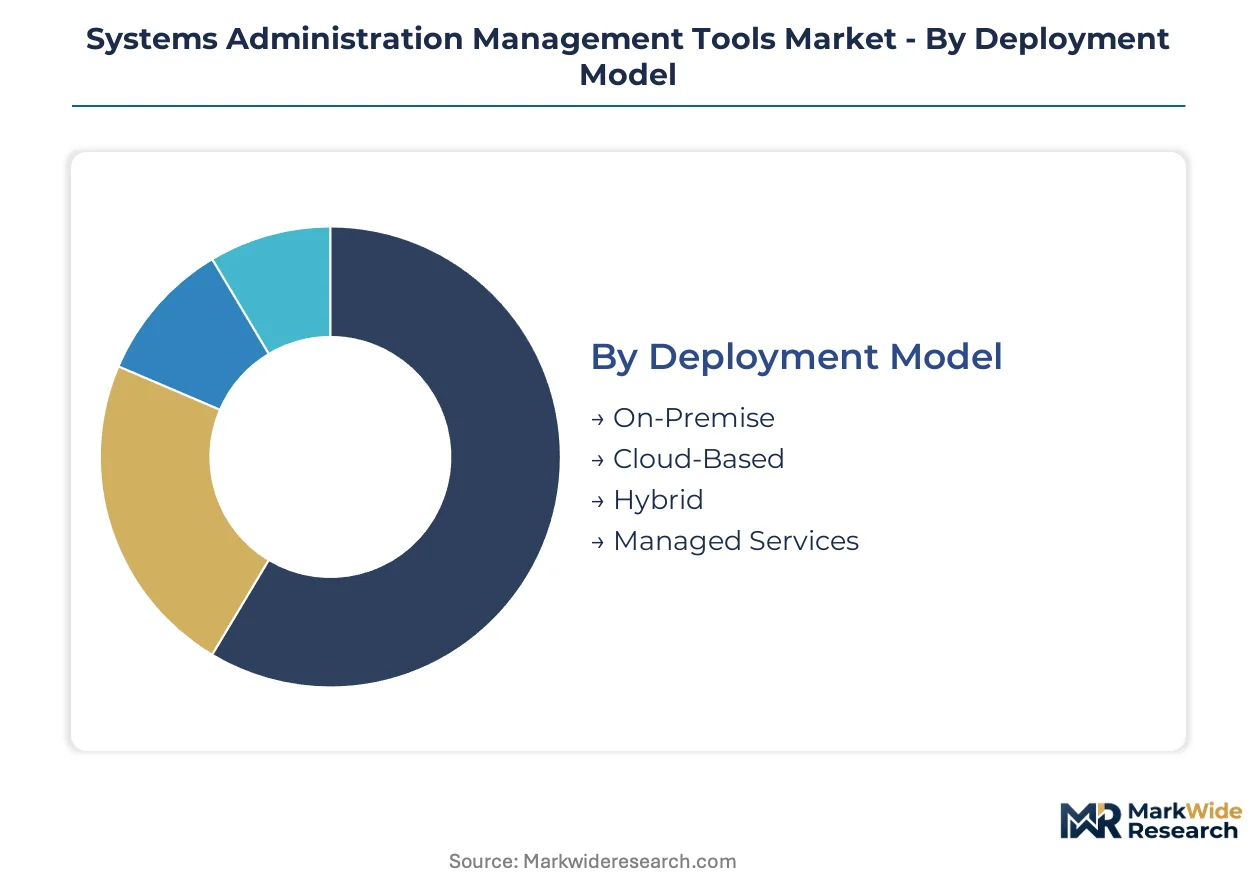
Systems administration management tools segment along four axes that determine procurement patterns, margin structures, and vendor competitive intensity. Deployment architecture dictates integration complexity and recurring revenue potential. End-user scale shapes pricing tolerance and implementation service requirements.
Deployment Model:
Architecture choice determines total cost of ownership, compliance posture, and vendor lock-in exposure for heterogeneous IT estates.
- Cloud-Based:Multi-tenant platforms with API-native orchestration eliminate data center footprint. Financial services institutions in Germany and France are retiring on-premise estates fastest, driven by EU AI Act audit trail requirements that favor centralized logging architectures.
- Hybrid:Unified control planes span on-premise legacy systems and ephemeral cloud workloads. German automotive manufacturers demand this architecture to bridge mainframe-dependent manufacturing execution systems with cloud-based supply chain analytics.
- On-Premise:Self-hosted platforms retain air-gapped operation for classified or regulated workloads. Defense contractors and national intelligence agencies mandate this deployment for FIPS 140-2 compliance.
- Managed Services:Third-party operation of administration infrastructure transfers operational risk. Mid-market enterprises in the Netherlands adopt to bypass certified engineer scarcity.
Cloud-Based leads on scale; Hybrid leads on momentum.
End User:
Organizational scale fragments pricing power, implementation timelines, and feature prioritization across the demand base.
- Enterprises:Global 2000 organizations operate multi-thousand server estates across continents. German pharmaceutical conglomerates embed carbon-tracking modules to satisfy CSRD disclosure mandates.
- SMBs:Organizations below 500 employees prioritize rapid deployment and consumption-based pricing. Nordic software startups drive fastest adoption of agentless architectures.
- Government Agencies:Public sector procurement emphasizes certified compliance and sovereign data residency. French ministries mandate ANSSI certification for security management functions.
- Educational Institutions:Universities and research consortia manage heterogeneous research computing clusters. CERN and Max Planck institutes drive demand for open-standards integration.
Enterprises dominate current revenue; SMBs are climbing the fastest.
Functionality:
Capability modules align with operational risk tolerance and regulatory minimums rather than discretionary technology preference.
- Monitoring:Real-time health polling and alerting constitutes mandatory baseline coverage. Regulated sectors in Germany and Switzerland treat this as non-negotiable infrastructure insurance.
- Automation:Policy-driven remediation and orchestration reduce mean time to resolution. Banks in Luxembourg deploy this functionality to compress NIS2 Directive compliance timelines.
- Backup:Immutable recovery point creation protects against ransomware and operational error. Healthcare providers in France align this with HDS certification requirements.
- Security Management:Access control, patch enforcement, and threat correlation integrate with zero-trust architectures. German critical infrastructure operators deploy this under BSI baseline protection mandates.
Monitoring leads on scale; Automation leads on momentum.
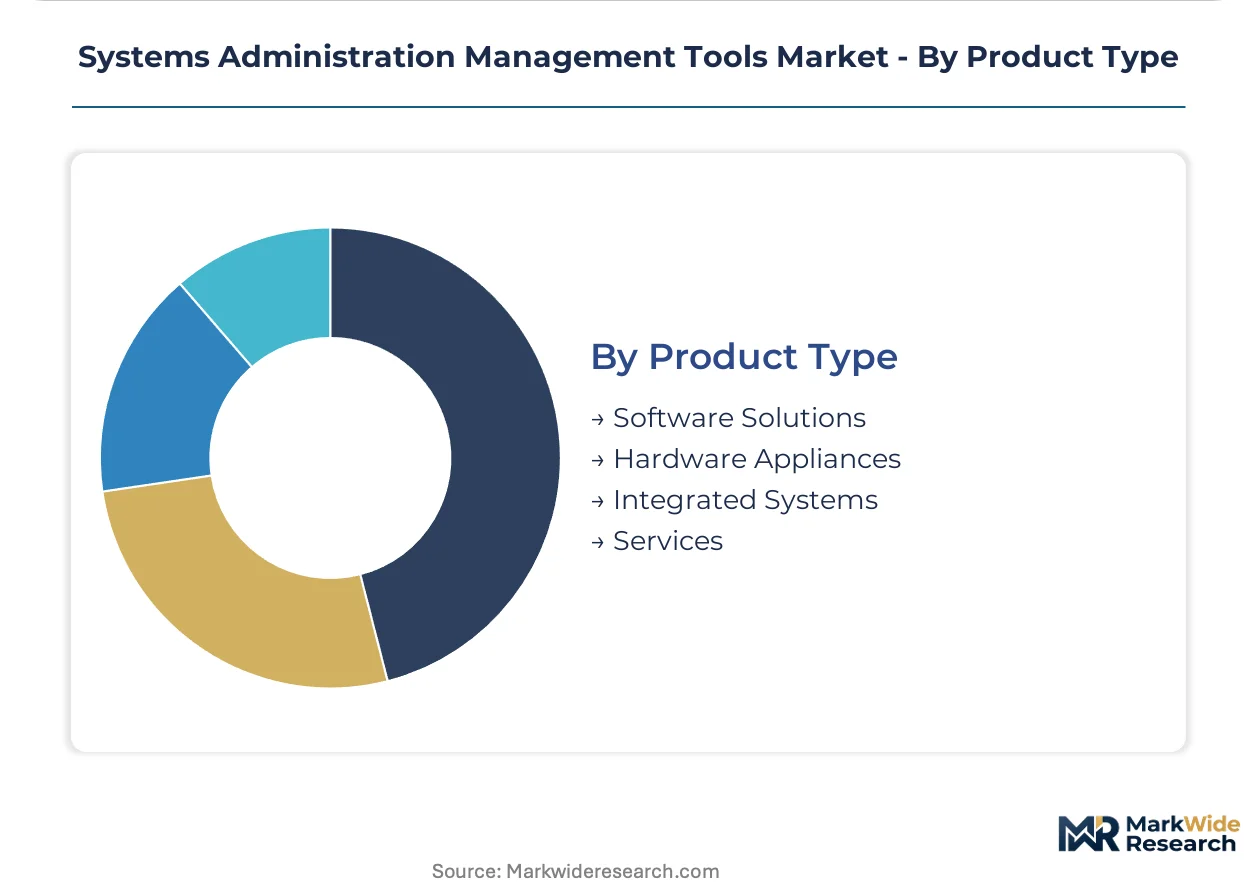
Product Type:
Commercial form factor determines margin structure, channel economics, and customer relationship durability.
- Software Solutions:Licensed or subscription platforms deliver functionality through deployable code. SaaS delivery is displacing perpetual licenses across European financial services.
- Hardware Appliances:Pre-integrated server and network equipment bundles reduce integration risk. Semiconductor input cost volatility compresses margins during supply constraints.
- Integrated Systems:Converged software-hardware stacks from single vendors simplify procurement. German automotive suppliers favor this for plant-floor deployment standardization.
- Services:Implementation, training, and ongoing operational support monetize expertise scarcity. Channel partners in the Nordics are unbundling these from software contracts.
Software Solutions leads on scale; Services leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified systems engineers cluster in Germany and the United States, anchoring demand for hybrid infrastructure governance tools. French and Dutch financial institutions accelerate cloud procurement. Japanese manufacturers sustain on-premise deployment preferences.
Germany
Automotive and pharmaceutical conglomerates drive legacy mainframe modernization alongside Kubernetes adoption. The EU NIS2 Directive mandates BSI-certified security management for critical infrastructure operators. Munich and Stuttgart manufacturing clusters embed carbon-tracking modules to satisfy CSRD disclosure timelines.
United States
Financial services institutions compress deployment cycles for hybrid cloud governance platforms. SEC cybersecurity disclosure rules mandate audit trail capabilities in procurement specifications. New York and Charlotte banking centers dominate contract volume for automation-first administration suites.
France
Luxembourg-based banks extend procurement into Paris for NIS2 compliance tooling. ANSSI certification requirements shape security management feature roadmaps. Île-de-France insurance groups deploy agentless architectures for ephemeral workload visibility.
Netherlands
Mid-market enterprises bypass certified engineer scarcity through managed services adoption. REACH chemical compliance obligations extend to IT infrastructure emissions tracking. Amsterdam fintech clusters drive subscription consumption model preferences.
Japan
Manufacturing execution systems sustain demand for on-premise deployment retention. METI guidelines on operational technology security influence product certification requirements. Nagoya automotive suppliers favor integrated software-hardware stacks for plant-floor standardization.
Systems Administration Management Tools Market Competitive Landscape
Capital-heavy infrastructure vendors compete with asset-light SaaS designers for procurement budgets across heterogeneous IT estates. Market structure tilts toward consolidated platforms with embedded compliance modules, though specialist orchestration tools retain pockets of pricing power. Three archetypes dominate: cloud-native workflow automators, mainframe-integrated legacy sustainers, and converged infrastructure stack providers. Competitive intensity manifests in strategic partnership formations and vertical capability acquisitions rather than direct price confrontation.
Within the cloud-native tier, ServiceNow and Atlassian occupy positions exemplifying workflow-centric positioning, while VMware anchors the hybrid infrastructure orchestration archetype. Microsoft represents the platform-integrated suite provider model through Azure-anchored deployment contracts. These three entities collectively illustrate how vendor selection increasingly hinges on pre-existing enterprise software relationships rather than standalone administration functionality evaluation.
| Leading Market Players |
|---|
| VMware |
| Microsoft |
| Cisco Systems |
| IBM |
| Hewlett-Packard |
| ServiceNow |
| Atlassian |
| BMC Software |
| Broadcom |
| Others |
Value Network & Pricing Analysis
Certification-tier divergence between BSI-compliant security management platforms and uncertified alternatives splits procurement budgets across German critical infrastructure operators, with premium-tier vendors capturing multi-year managed services contracts while commodity SaaS providers fight for Nordic mid-market subscriptions on compressed implementation timelines.
Pricing Analysis
Bundled implementation services versus unbundled software-only contracts now defines vendor-customer relationships across European financial services. Three-tier pricing structure across premium, standard, and economy levels tracks compliance certification depth, with EU AI Act audit-ready platforms commanding substantial premiums over baseline monitoring tools. Cost compression in the hardware appliance tier is intensifying because semiconductor input volatility erodes margins on pre-integrated server bundles. SMB buyers in the Netherlands exhibit highest price sensitivity, while German automotive conglomerates prioritize carbon-tracking integration over unit cost.
Supply Chain Analysis
Reverse-logistics flows for hardware appliance refurbishment center on Taiwan, South Korea, and Japan, where specialized semiconductor recovery operations extend equipment lifecycles for cost-conscious mid-market buyers. Critical component dependencies span advanced server processors, network interface controllers, and encryption accelerators. Single-source vulnerability concentrates in Taiwan-based foundry capacity for custom ASICs deployed in zero-trust security modules. Distribution runs through value-added resellers in Germany and France, with direct vendor relationships displacing channel intermediaries in Nordic cloud-native procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between German compliance-heavy procurement and Dutch managed services adoption creates margin expansion opportunities for vendors who modularize platform architectures to serve both regulatory stringency and cost optimization simultaneously.
For Market Incumbents: Lock in German automotive and pharmaceutical accounts through embedded CSRD carbon-tracking modules that preempt retrofit requirements. Consolidate channel control by acquiring specialist implementation partners in Stuttgart and Munich manufacturing clusters before NIS2 Directive deadlines compress vendor selection windows.
For New Entrants and Emerging Players: The mid-market pricing gap between ServiceNow-tier workflow suites and open-source alternatives opens white space for agentless architecture specialists targeting Nordic software startups. Prioritize sub-30-day implementation guarantees and consumption-based pricing to bypass entrenched vendor relationships in Amsterdam fintech clusters.
For Investors and Strategic Acquirers: Asymmetric upside sits with hybrid infrastructure orchestration specialists bridging mainframe and Kubernetes estates. Long-term viability hinges on compliance certification velocity rather than feature breadth. Watch for BSI audit completion timelines as inflection indicator for German market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Module Integration | Embedded EU AI Act transparency tools satisfy German automotive procurement specifications. |
| Agentless Architecture Launch | Eliminates maintenance overhead for ephemeral cloud workload coverage in Nordic markets. |
| Managed Services Expansion | Transfers operational risk for Dutch mid-market enterprises facing certified engineer scarcity. |
| Carbon-Tracking Partnership | CSRD-aligned emissions modules secure Munich manufacturing cluster renewals. |
| Zero-Trust Security Certification | ANSSI-validated platforms unlock French government and defense procurement channels. |
Research Methodology
Direct dialogue with systems administration vendors, IT procurement officers at German automotive manufacturers, Dutch managed services providers, and French ANSSI certification auditors grounded qualitative findings in operational reality. Secondary validation drew from SEC cybersecurity disclosure filings, EU NIS2 Directive implementation guidance, BSI technical baseline documentation, and hyperscaler capex allocation reports. Bottom-up deployment model sizing and top-down IT infrastructure spend estimates were triangulated to anchor projections.
Segment-level outputs across deployment architecture, organization scale, functionality module, and geographic adoption pattern were generated through structured modeling across the analysis window. CAGRs were derived from regression-based trending of procurement cycle compression and compliance deadline proximity. Forecast inputs incorporated cloud migration velocity at German financial institutions and mainframe modernization timelines at pharmaceutical conglomerates.
Caveats apply where EU AI Act enforcement intensity or semiconductor supply normalization could materially shift the outlook. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Conversion Rate Optimization (CRO) Software Market
Software & Services
Construction Estimating Software Market
Software & Services
PCB CAD Software Market
Software & Services
Global Embedded Database Management Systems Market
Software & Services
Search and Discovery Software Market
Software & Services
Case Management Software (CMS) Market
Software & Services
Collaborative Authoring Tools Market
Software & Services
Interactive Digital Signage Software Market
Software & Services
Global Architecture Design Software Market
Software & Services
Global Core Human Resource Software Market
Software & Services
Data Migration Software Services Market
Software & Services
Global Data Extraction Software Market
Software & Services
Service Scheduling Software Market
Software & Services
Global Programming Software Market
Software & Services
Technology CAD Software Market
Software & Services
Global Managed File Transfer (MFT) Software and Service Market