
 Product Analytics Software Market | 2026-2036
Product Analytics Software Market Size, Share, and Industry Trends Forecast 2026-2036
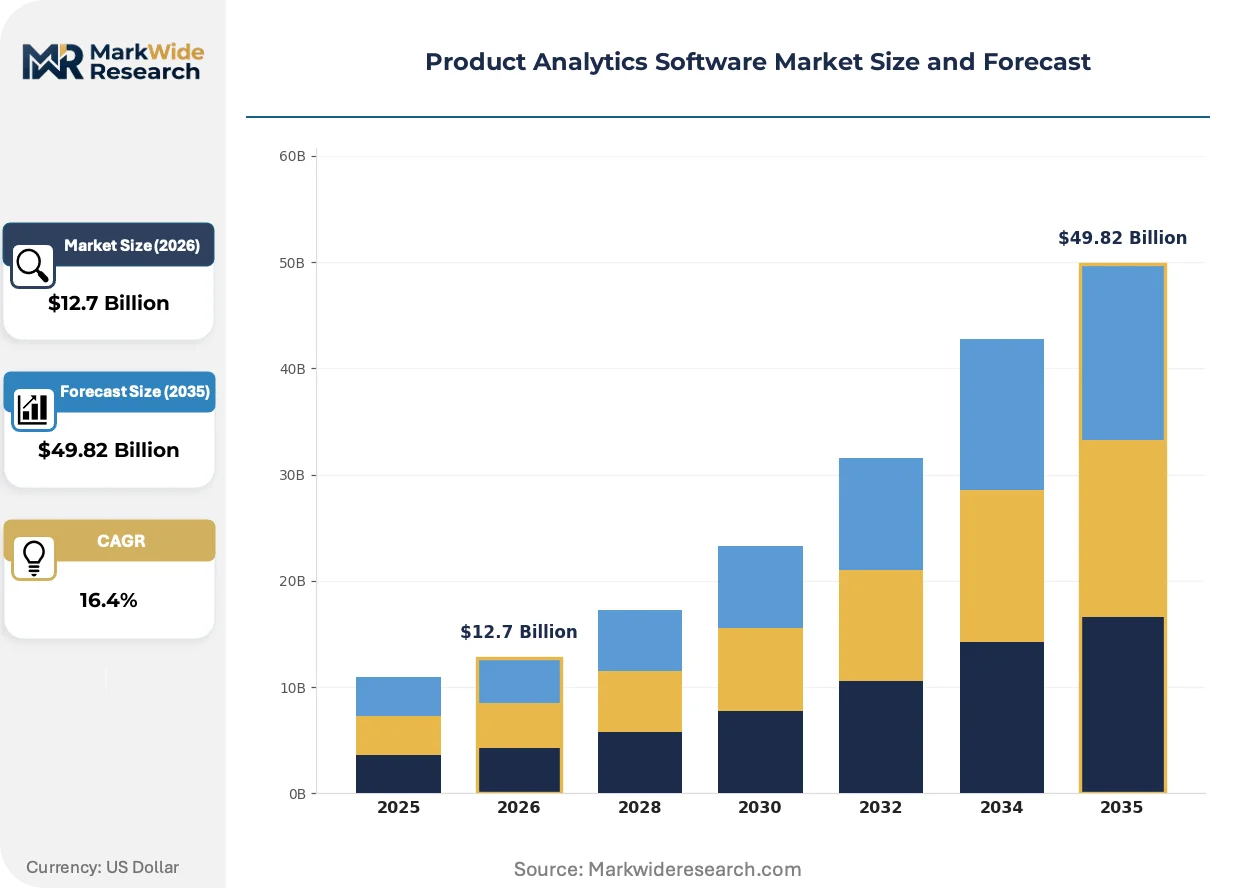
Product Analytics Software Market Outlook
The EU AI Act is rebalancing the cost-of-entry calculus for vendors serving European enterprises, forcing substantial investments in algorithmic transparency and audit infrastructure. Amplitude leverages its R&D intensity to build explainability layers that preempt regulatory scrutiny. Mixpanel sustains geographic dominance in North American mid-market SaaS by embedding consent-management workflows natively into its data pipeline architecture. Heap differentiates through automated event capture that reduces manual instrumentation burdens for compliance documentation.
Product analytics software encompasses platforms that ingest, process, and visualize user interaction data across digital touchpoints, typically employing event-stream processing engines with sub-second latency thresholds and SQL-accessible data lakes to enable product teams to optimize conversion funnels and retention mechanics. Cloud-based deployment leads structural adoption as enterprises abandon on-premises data centers for elastic compute environments, while predictive analytics represents the fastest-expanding product type as machine-learning models forecast churn and lifetime value with escalating precision. SaaS delivery models concentrate margin pools through recurring revenue structures that offset customer acquisition expenditures across extended contract horizons.
The Federal Trade Commission and HIPAA Security Rule in the United States, alongside the EU AI Act and GDPR in Europe, collectively shape demand by mandating granular data lineage, purpose limitation, and cross-border transfer safeguards that elevate procurement criteria beyond pure feature comparison. ISO 27001 certification functions as a de facto market-access threshold for enterprise buyers conducting vendor security assessments. Stakeholders must monitor evolving algorithmic accountability obligations as regulators on both sides of the Atlantic draft sector-specific guidance that could bifurcate product roadmaps and regional go-to-market strategies.
Market Dynamics
Cloud-first migration among enterprise SaaS buyers is compressing deployment timelines while elevating data sovereignty requirements, forcing vendors to re-architect ingestion pipelines for regional residency mandates.
Growth Catalysts
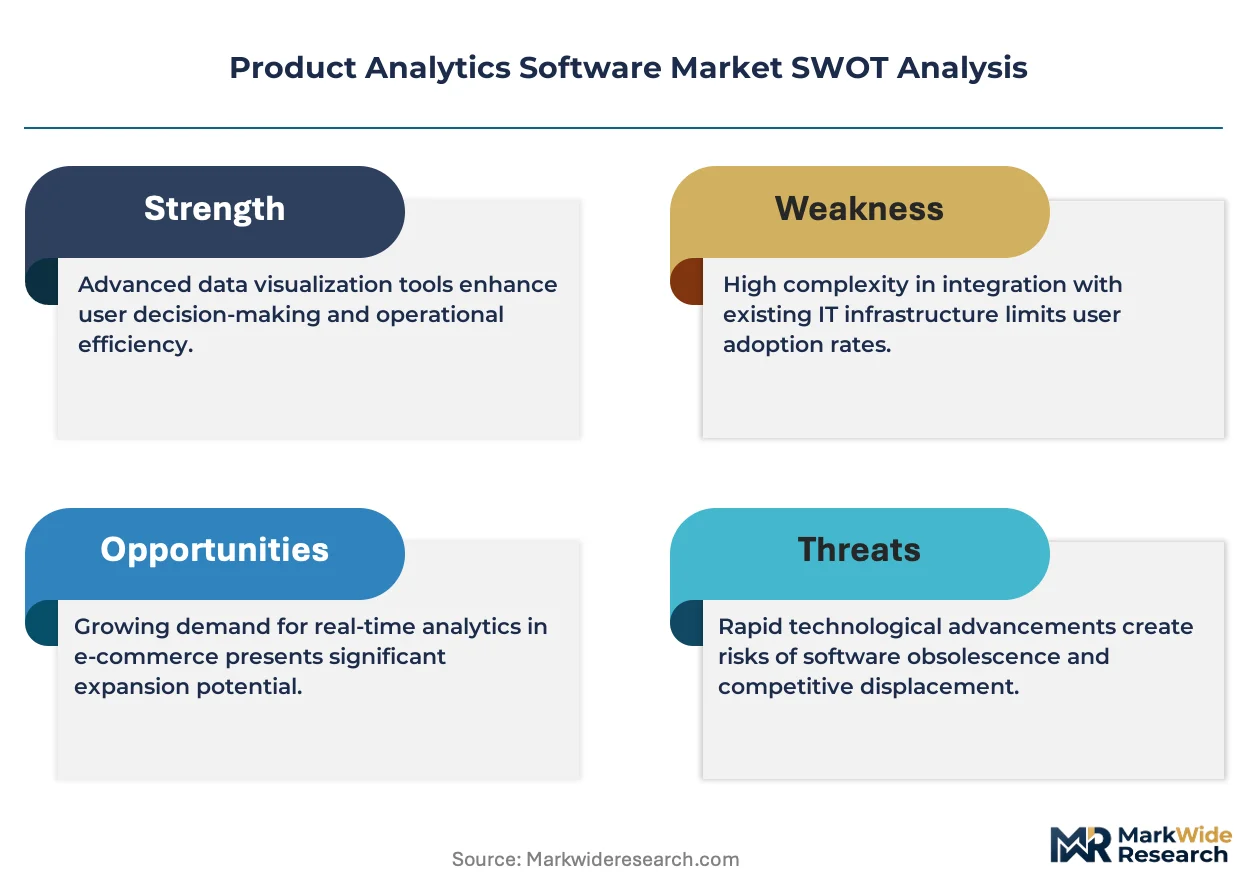
- E-commerce funnel optimization:Online merchants demand granular behavioral telemetry to reduce cart abandonment and improve lifetime value calculations, driving platform subscriptions.
- GDPR Article 30 documentation:European enterprises require automated record-keeping of processing activities, expanding procurement criteria to include native compliance tooling.
- Real-time event streaming:Sub-second latency processing enables product teams to intervene during active user sessions rather than post-hoc analysis.
Market Restraints
- Cross-border data transfer friction:Schrems II rulings invalidate Privacy Shield mechanisms, forcing redundant infrastructure deployment across jurisdictions.
- Elastic compute cost volatility:Cloud-native architectures expose vendors to hyperscaler pricing swings that compress gross margins unpredictably.
- SQL literacy scarcity:Product managers lacking query language proficiency create adoption bottlenecks that slow time-to-value realization.
Strategic Opportunities
- Healthcare SaaS in the United States:HIPAA-covered entities represent underpenetrated demand as clinical workflow platforms seek patient engagement analytics.
- Federated learning architectures:Privacy-preserving model training across decentralized datasets addresses GDPR constraints without centralizing sensitive records.
- Embedded analytics partnerships:White-label SDK distribution through vertical SaaS platforms opens channel access to mid-market buyers.
Industry Challenges
- ISO 27001 certification timelines:Enterprise security assessments require 12-18 month audit cycles that delay contract execution.
- Legacy warehouse integration:On-premises data infrastructure at incumbent enterprises demands costly connector development and maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Product Analytics Software Market |
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $49.82 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Web Analytics, Mobile Analytics, Social Media Analytics, Predictive Analytics Deployment: On-premises, Cloud-based, Hybrid, SaaS End User: Retail, E-commerce, Healthcare, Software Development Solution: Customer Insights, Market Research, Performance Tracking, A/B Testing |
| Companies Covered | Amplitude, Mixpanel, Pendo, Heap, PostHog, FullStory, Google Analytics, LogRocket, Gainsight PX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Product Analytics Software Market Strategic Shifts
Behavioral data infrastructure is undergoing architectural transformation as real-time processing, algorithmic accountability mandates, and buyer procurement sophistication reshape competitive requirements.
Automated event capture is converging with differential privacy techniques to enable comprehensive instrumentation without exposing individual user identities. Mid-market SaaS vendors are adopting these capabilities fastest, compressing the competitive window for manual instrumentation approaches. The structural consequence is collapsing differentiation around ease-of-deployment claims as privacy-preserving automation becomes table stakes.
The EU AI Act's risk classification framework is mandating algorithmic impact assessments for high-risk automated decision systems. Vendors serving European financial services and healthcare verticals must now maintain audit trails of model training data and inference logs. Product analytics platforms with native explainability layers are capturing procurement preference in Germany and France ahead of enforcement deadlines.
Consolidated procurement of analytics infrastructure is displacing point-solution buying as enterprises reduce vendor sprawl. Platform teams at technology companies are bundling product analytics with data warehouse and customer data platform contracts. This concentration is most visible in the United States, where procurement offices prioritize single-vendor accountability over best-of-breed feature depth.
Product Analytics Software Market Segmentation
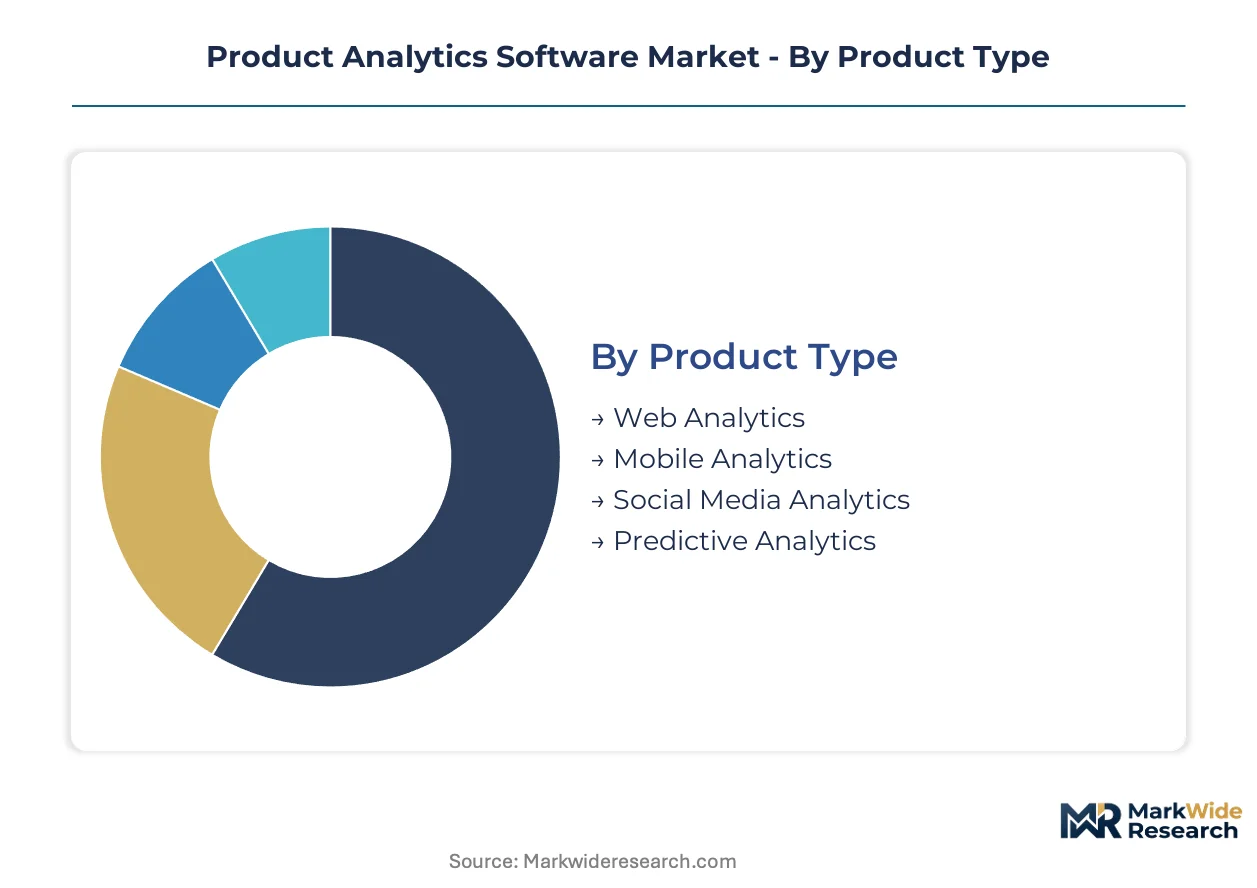
Product analytics software segments diverge sharply in infrastructure requirements and compliance burdens. Vendors must align R&D allocation with the capital intensity and regulatory exposure of each category.
Product Type:
Capital intensity varies dramatically across analytics modalities, with real-time streaming architectures demanding substantially greater compute investment than batch-processed alternatives.
- Predictive Analytics:Machine-learning pipelines require GPU clusters and continuous model retraining infrastructure. Healthcare systems in the United States prioritize these capabilities for patient churn forecasting, though HIPAA audit trails inflate deployment costs.
- Web Analytics:Browser-based event capture leverages mature JavaScript instrumentation with minimal proprietary hardware. E-commerce platforms in Germany and France drive procurement volume as GDPR documentation requirements elevate vendor selection criteria.
- Mobile Analytics:SDK-based telemetry across iOS and Android ecosystems.
- Social Media Analytics:API-dependent data ingestion from platform-specific endpoints.
Web analytics absorbs the bulk of installed capacity; predictive analytics is expanding most quickly.
Deployment:
Margin profiles compress as buyers shift from perpetual licenses toward consumption-based billing models.
- Cloud-based:Elastic compute environments eliminate upfront server procurement while exposing vendors to hyperscaler pricing volatility. European enterprises mandate regional data residency, forcing redundant infrastructure deployment across Frankfurt, Dublin, and Stockholm availability zones.
- SaaS:Multi-tenant architectures concentrate development overhead across customer bases. United States mid-market SaaS companies prefer native integrations with existing cloud data warehouses, accelerating procurement cycles.
- On-premises:Dedicated hardware installations at buyer facilities.
- Hybrid:Split architectures with sensitive data on-site and analytics workloads in cloud.
SaaS deployments dominate new contract volume; cloud-based configurations are climbing the fastest.
End User:
Regulatory complexity fragments addressable market economics across verticals.
- E-commerce:Cart abandonment tracking and lifetime value modeling demand sub-second latency pipelines. Merchants in the United Kingdom and Netherlands prioritize automated consent management to satisfy GDPR enforcement.
- Healthcare:HIPAA-covered entities require encrypted data lineage and business associate agreements. Clinical workflow platforms in the United States represent underpenetrated demand as patient engagement analytics mature.
- Retail:In-store and digital channel integration for unified customer profiles.
- Software Development:Product-led growth instrumentation for feature adoption measurement.
E-commerce absorbs the bulk of installed capacity; healthcare is gaining share fastest.
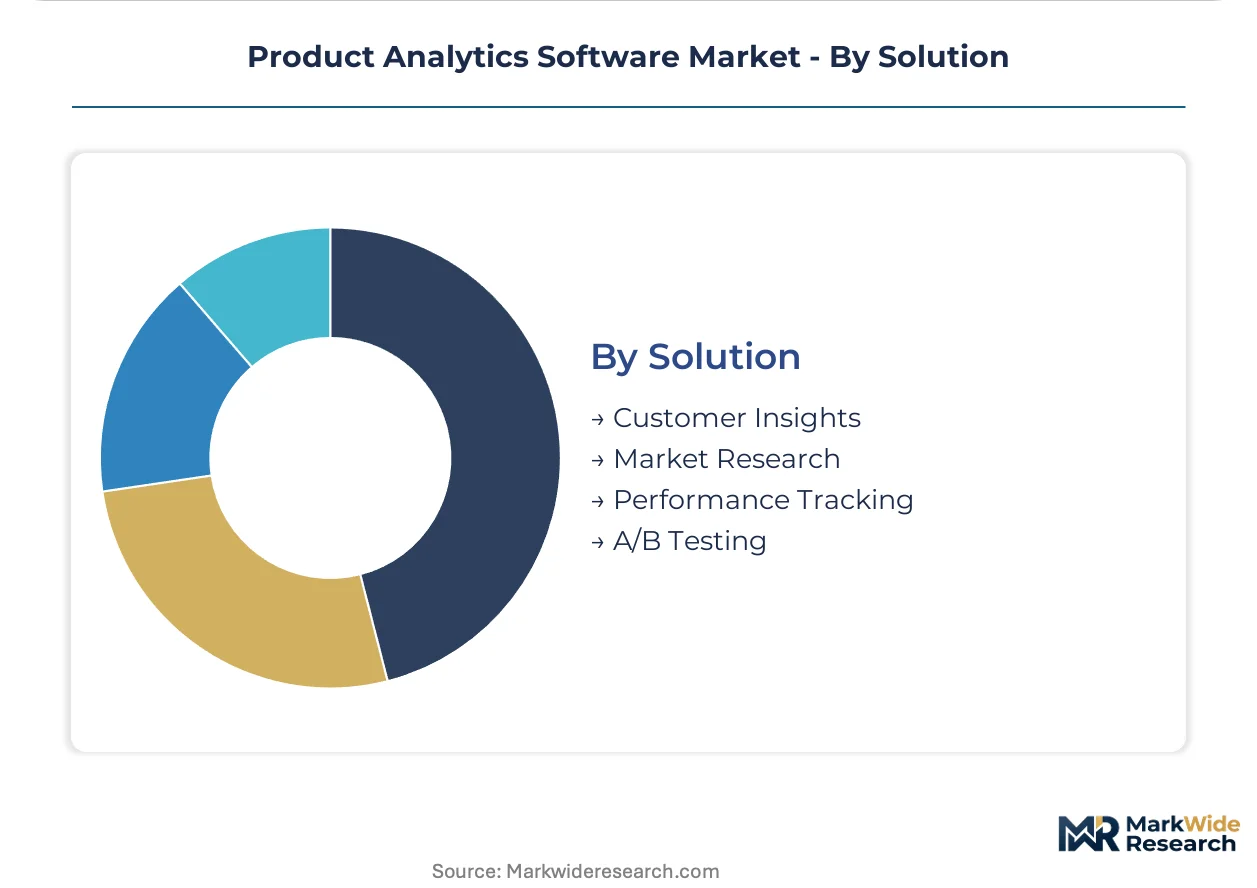
Solution:
Feature bundling strategies determine competitive positioning against point-solution alternatives.
- Customer Insights:Unified profile construction across touchpoints requires identity resolution infrastructure at scale. Financial services buyers in France demand algorithmic explainability layers to preempt EU AI Act scrutiny.
- A/B Testing:Statistical inference engines with multi-armed bandit optimization. Technology companies in the United States embed these capabilities into continuous deployment pipelines, compressing experiment cycle times.
- Market Research:Survey integration and panel management for external data augmentation.
- Performance Tracking:Dashboard-centric KPI monitoring for executive reporting.
Customer insights absorbs the bulk of installed capacity; A/B testing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise SaaS procurement in the United States absorbs the largest share of product analytics platform spending. European regulatory complexity elevates compliance tooling requirements. Asia-Pacific markets are accelerating cloud-first adoption.
United States
HIPAA-covered health systems and mid-market SaaS vendors drive platform subscriptions. The FTC enforces data minimization standards that elevate vendor security assessments. Silicon Valley technology companies bundle product analytics with data warehouse contracts, compressing procurement cycles.
Germany
Industrial software manufacturers and automotive OEMs demand algorithmic explainability for automated decision systems. The EU AI Act mandates audit trails for high-risk analytics deployments. Munich and Stuttgart clusters concentrate procurement offices prioritizing ISO 27001-certified vendors.
United Kingdom
E-commerce merchants and fintech platforms seek real-time funnel optimization capabilities. GDPR enforcement through the Information Commissioner's Office elevates consent-management requirements. London's financial services sector drives demand for predictive churn modeling with native compliance documentation.
France
Luxury retail brands and insurance groups require cross-channel customer insights with differential privacy safeguards. The CNIL mandates granular purpose limitation for behavioral data processing. Paris-based enterprise buyers prioritize platforms with embedded record-of-processing automation.
India
Domestic SaaS startups and IT services exporters adopt cloud-native analytics for product-led growth instrumentation. The Digital Personal Data Protection Act establishes consent frameworks that reshape vendor selection criteria. Bangalore and Hyderabad technology corridors concentrate mid-market platform deployments.
Product Analytics Software Market Competitive Environment
United States vendors anchor the premium tier; European specialists hold compliance-forward positions. The market exhibits moderate concentration with tiered differentiation around deployment velocity and regulatory tooling. Strategic archetypes include real-time streaming specialists, automated capture platforms, and embedded analytics providers. Dominant competitive moves encompass federated learning partnerships and vertical SDK distribution.
Within the automated instrumentation tier, Heap and PostHog exemplify approaches that reduce manual engineering burdens. Amplitude occupies a position among R&D-intensive vendors building explainability layers for regulatory scrutiny. These three companies represent distinct responses to the tension between deployment speed and compliance documentation requirements.
| Leading Market Players |
|---|
| Amplitude |
| Mixpanel |
| Pendo |
| Heap |
| PostHog |
| FullStory |
| Google Analytics |
| LogRocket |
| Gainsight PX |
| Others |
Value Chain & Pricing Dynamics
GDPR Article 30 record-keeping mandates gate qualified supply for European deployments while compressing margin structures across all tiers. Vendors lacking native compliance automation face exclusion from procurement shortlists in Germany and France, forcing premium pricing for certified alternatives.
Pricing Analysis
Short lead-time deployments command substantial premiums as HIPAA-covered health systems in the United States accelerate procurement cycles. Subscription tiers stratify across enterprise, growth, and starter levels with ISO 27001 certification and regional data residency as primary price differentiation drivers. Cost compression in the mid-market tier intensifies as automated event capture commoditizes deployment speed claims. E-commerce platforms in the United Kingdom exhibit highest price sensitivity; clinical workflow vendors in the United States show lowest sensitivity due to compliance-driven vendor consolidation.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale buyer demand while embedded SDK distribution reaches mid-market SaaS platforms through vertical partnerships. Infrastructure concentration spans the United States, Ireland, and Germany as hyperscaler regions anchor compute supply. GPU clusters for predictive model training and encrypted storage arrays for HIPAA compliance draw from specialized hardware suppliers. Single-source vulnerability in cloud hyperscaler pricing exposes vendor margins to unpredictable compression. Distribution runs through value-added resellers in regulated verticals and direct sales teams in technology-native buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Product analytics software has become a vertical-integration race as vendors pursue upstream control over data warehouse and customer data platform layers to capture consolidated procurement budgets.
For Market Incumbents: Acquire federated learning infrastructure capabilities to preempt EU AI Act enforcement timelines. Deepen backward integration into identity resolution engines to reduce third-party dependency costs. Automated capture specialists threaten margin pools; defend through native explainability layer investments that satisfy German automotive OEM procurement criteria. For New Entrants and Emerging Players: Begin with HIPAA-covered clinical workflow platforms in the United States as the most penetrable segment lacking incumbent saturation. White-label SDK distribution through vertical SaaS platforms offers channel access without direct enterprise sales overhead. Target mid-market e-commerce merchants in the Netherlands seeking GDPR-compliant alternatives to legacy instrumentation. For Investors and Strategic Acquirers: Consolidated procurement announcements from United States technology companies are the leading indicator that platform bundling is accelerating vendor displacement. Long-term viability favors vendors with multi-vertical compliance automation and regional infrastructure deployment. Watch for EU AI Act high-risk system designations as the signal for regulatory-driven consolidation windows.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Partnership | Privacy-preserving model training satisfies GDPR constraints without centralizing sensitive European health records. |
| Vertical SDK Distribution | White-label embedded analytics opens channel access to mid-market SaaS platforms lacking in-house data infrastructure. |
| Regional Infrastructure Deployment | Frankfurt and Dublin availability zones address Schrems II data residency mandates for EU enterprise buyers. |
| Explainability Layer Development | Native algorithmic audit trails preempt EU AI Act scrutiny for high-risk financial services deployments in France. |
| Healthcare SaaS Integration | HIPAA-aligned data lineage captures underpenetrated demand from clinical workflow platforms in the United States. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with CTOs, IT procurement officers, platform engineers, and channel partners combined with SEC filings, hyperscaler capex disclosures, and GDPR enforcement databases. Bottom-up deployment volume estimates triangulated against top-down enterprise SaaS spending patterns.
Data-stream reconciliation across event-stream processing volumes, subscription contract values, and compliance certification databases shaped the analytical framework. Segmentation dimensions modeled include deployment architecture, organization size, vertical regulatory exposure, integration complexity, and regional adoption pattern. CAGRs derived from elasticity-adjusted growth curves incorporating cloud infrastructure expansion rates and e-commerce platform formation trends.
Underlying measurement precision varies by segment; cloud-based SaaS deployments carry tighter precision than on-premises alternatives due to disclosed hyperscaler revenue attribution. Forecasts reflect assumptions regarding regulatory enforcement timelines and enterprise procurement consolidation behavior. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Subscription Billing Software Market
Software & Services
Indonesia IT Services Market
Software & Services
CAM Software Market
Software & Services
Global Policy Management Software Market
Software & Services
Business Spend Management (BSM) Software Market
Software & Services
Scanning and Migration Software Market
Software & Services
Image Analysis Software Market
Software & Services
MRP Software Market
Software & Services
Global PPC Software Market
Software & Services
Hypervisor Market
Software & Services
Mindfulness Meditation Application Market
Software & Services
3D Animation Production Software Market
Software & Services
Saas-Based SCM Market
Software & Services
Trading Software Market
Software & Services
Global Journal App Market
Software & Services
Mobile Application Testing Services (MATS) Market