
 Classified Platform Market | 2026-2036
Classified Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Classified Platform Market Outlook
The split between premium verified listings and unverified commodity posts is repositioning how platforms monetize trust. Carousell leverages its mobile-first design to dominate Southeast Asian peer-to-peer commerce. OLX Group anchors its strength across emerging markets through localized marketplace operations. Adevinta differentiates by sustaining vertical specialization in real estate and automotive segments across Europe.
A classified platform is a digital marketplace infrastructure that enables users to post, search, and transact goods or services through structured listings, typically featuring category taxonomy, search indexing, and messaging protocols. These systems serve commercial purposes by reducing information asymmetry between buyers and sellers across fragmented local and national markets. Specialty Classifieds currently lead margin capture where vertical depth commands higher advertiser willingness to pay, while Mobile Apps represent the fastest-expanding platform type as smartphone penetration drives session frequency. The Freemium revenue model occupies the largest user base but Transaction Fees are extracting more value per completed sale as platforms embed payment and escrow functions.
The EU Digital Services Act and GDPR impose content moderation and data handling obligations that reshape platform operating costs across Europe. India's BIS framework for digital commerce and the country's emerging platform liability rules are tightening market access standards for foreign operators. China's SAMR antitrust enforcement against dominant internet platforms constrains how 58.com and similar services structure merchant relationships. Stakeholders must monitor how fragmented regulatory regimes fragment platform architecture and force region-specific compliance investments.
Market Dynamics
The classified platform sector is undergoing fundamental restructuring as mobile-first interfaces displace desktop-centric architectures, compressing user acquisition costs while fragmenting monetization models across peer-to-peer and commercial seller segments.
Growth Catalysts
- India's BIS Digital Marketplace Guidelines:Standardized trust frameworks for platform verification are accelerating formalization of informal commerce, expanding addressable seller bases in high-growth emerging markets.
- Smartphone Penetration in Southeast Asia:Mobile session frequency among small business listers is driving platform infrastructure investments toward lightweight, low-bandwidth listing tools.
- EU Digital Services Act:Content moderation obligations are creating competitive moats for compliant operators, advantaging established platforms over undercapitalized entrants in European markets.
Market Restraints
- Input Cost Volatility:Cloud infrastructure and payment processing fees constitute rising shares of platform operating expenditure, squeezing freemium-model unit economics.
- Supply Concentration Risk:Dominance of Google and Apple mobile ecosystems creates gatekeeper dependency for app-distributed classified services, exposing revenue to policy unilateralism.
- Technical Limitation:Cross-border payment settlement latency and currency friction constrain seamless transaction enablement in multi-currency emerging markets.
Strategic Opportunities
- Underpenetrated Rural India:Tier-3 and Tier-4 city merchant digitization remains nascent, offering first-mover advantages for vernacular-language platform localization.
- Automotive Vertical Deepening:Inspection-standardization and financing-embedded listings represent unmonetized value pools within vehicle classifieds.
- AI-Image Recognition Convergence:Automated listing generation from smartphone photography is automating seller onboarding friction, compressing time-to-first-listing.
Industry Challenges
- Content Moderation Workforce Scaling:Platform accountability regimes require human-in-the-loop trust-and-safety teams, creating talent bottlenecks in non-English language markets.
- Legacy System Integration:Enterprise classified advertisers demand API compatibility with established ERP and inventory management systems, extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Classified Platform Market |
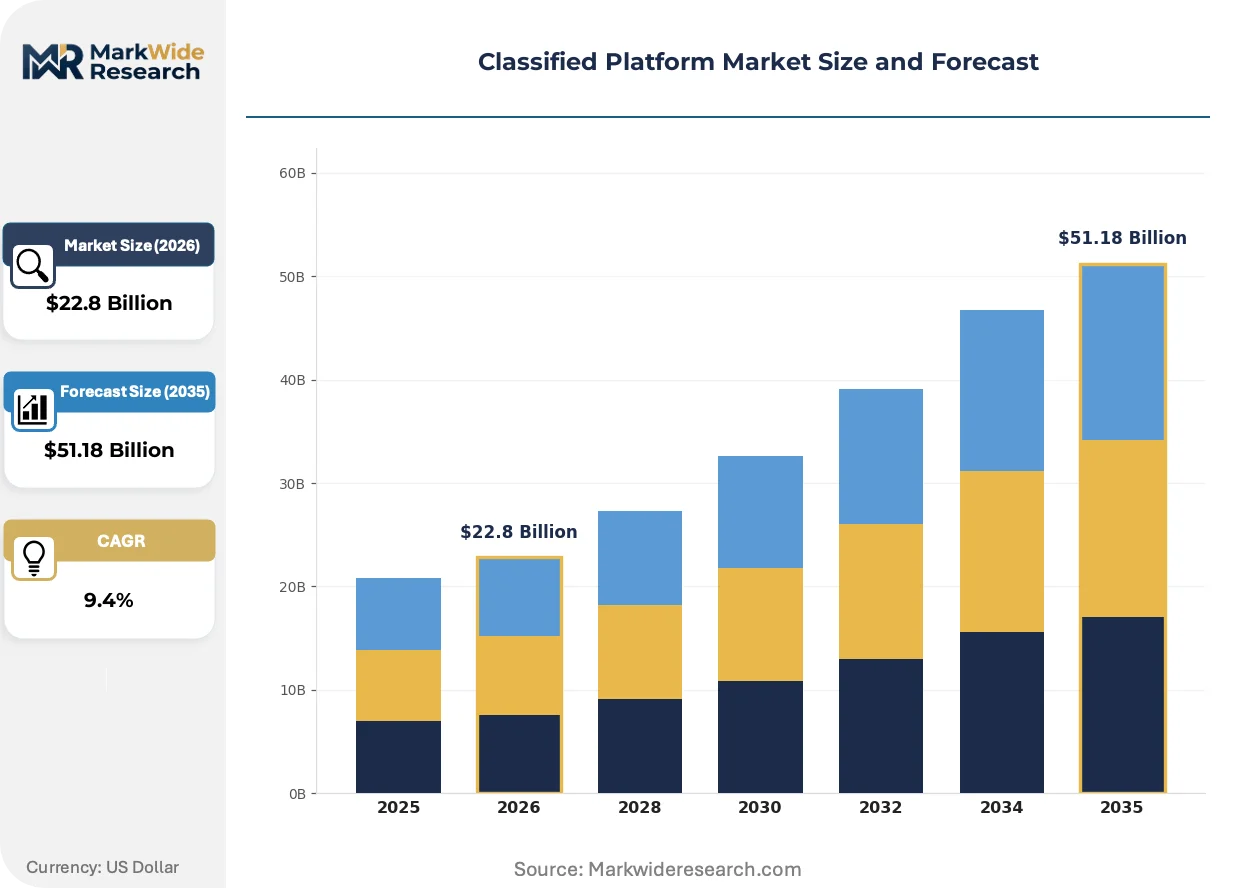
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $51.18 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: General Classifieds, Specialty Classifieds, Auctions, Listings End User: Individuals, Small Businesses, Enterprises, Non-Profits Revenue Model: Freemium, Subscription, Advertisement, Transaction Fees Platform Type: Web-Based, Mobile Apps, Social Media, Aggregators |
| Companies Covered | Carousell, CarTrade Tech, Adevinta, Trade Me, 58.com, OLX Group (Prosus), Zoopla, Dubizzle Group, Craigslist, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Classified Platform Market Strategic Shifts
Artificial intelligence and embedded financial services are converging to transform how classified platforms capture transaction value, shifting revenue from advertising exposure to completed commerce enablement.
Computer vision and natural language processing are automating listing creation, with sellers capturing product images that auto-populate structured descriptions, pricing suggestions, and category tags. Small merchants in India and Indonesia are adopting these tools fastest, reducing professional photography dependencies. This compression of listing friction is automating platform onboarding at scale, expanding seller bases beyond digitally fluent early adopters.
GDPR and the EU Digital Services Act are mandating algorithmic transparency and traceable content moderation decisions, elevating compliance infrastructure to competitive differentiator status. Platforms serving European users must now maintain auditable recommendation systems and rapid illegal-content takedown protocols. Real estate and automotive verticals face heightened scrutiny given high-value transaction risks and consumer protection sensitivities.
Buyers are migrating toward transaction-complete platforms that embed payment escrow, shipping coordination, and dispute resolution, displacing pure discovery models. This unbundling of classifieds from fulfillment is compressing platform switching costs while raising capital intensity requirements. Southeast Asian markets exhibit this behavioral shift most acutely, where super-app ecosystems have conditioned users to expect seamless commerce closure.
Classified Platform Market Segmentation
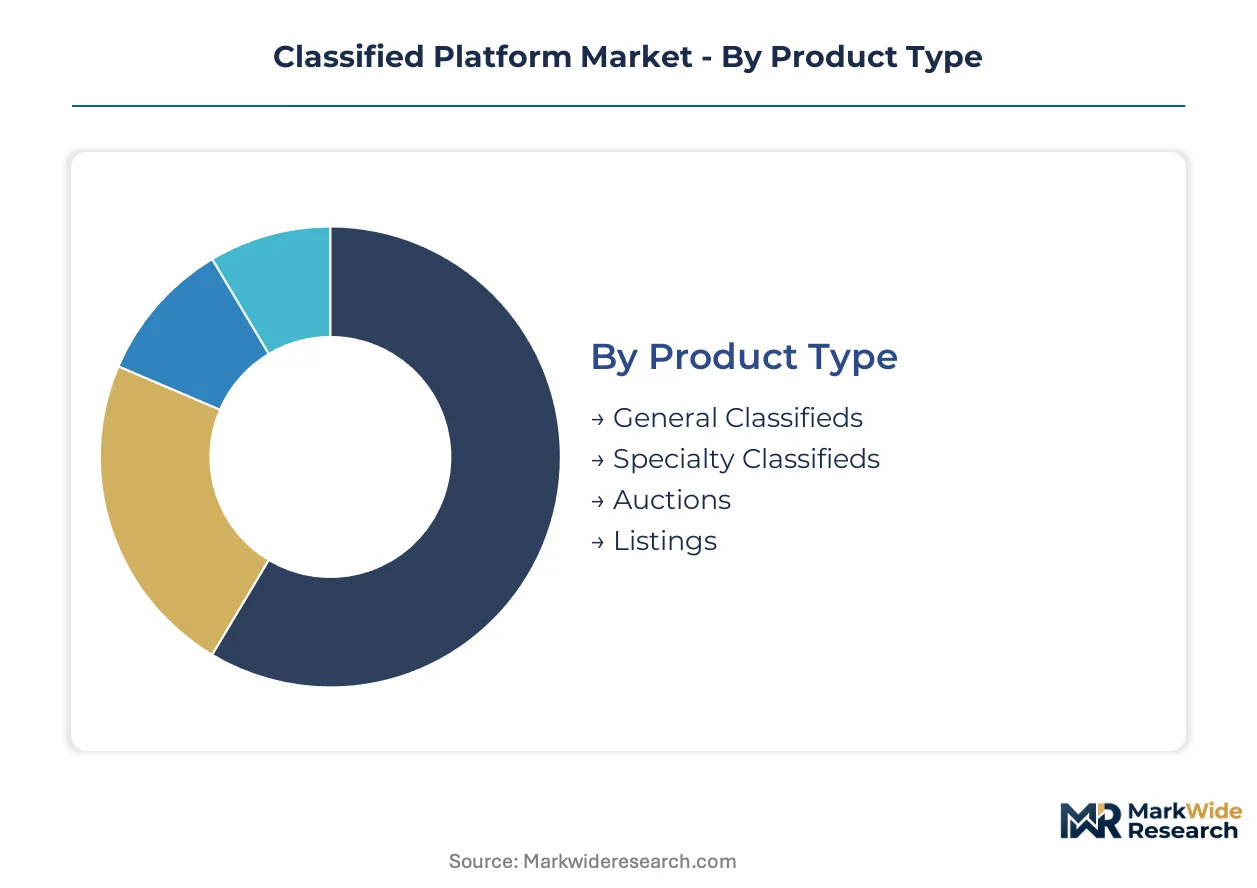
Classified platform operators must align infrastructure investments with divergent user behaviors and monetization physics across listing formats. Segmentation reveals where transaction economics favor embedded payments versus advertising exposure.
Product Type:
Buyers select platforms based on listing specificity and seller verification depth rather than discovery breadth alone.
- General Classifieds:Horizontal marketplaces host unverified peer-to-peer listings across categories without transaction facilitation. India's OLX and 58.com in China dominate volume through lightweight onboarding and minimal seller qualification.
- Specialty Classifieds:Vertical platforms enforce category-specific standards—automotive inspections, real estate documentation—that command premium placement fees. European automotive and property verticals concentrate advertiser willingness-to-pay where trust mechanisms reduce transaction risk.
- Auctions:Time-bound competitive bidding formats concentrate price discovery for collectible and industrial equipment segments.
- Listings:Fixed-price catalog formats persist in B2B procurement and professional services matching.
General Classifieds leads on scale; Specialty Classifieds leads on momentum.
End User:
Monetization yield varies sharply by seller sophistication and inventory scale.
- Individuals:Casual sellers generate session volume but resist paid promotion, requiring platforms to extract value through advertising impressions rather than listing fees.
- Small Businesses:Merchant digitization across Southeast Asia drives recurring subscription adoption where inventory management tools justify recurring platform expenditure.
- Enterprises:Large retailers demand API integration and programmatic listing management, extending sales cycles but securing multi-year contract value.
- Non-Profits:Mission-driven listings operate on donated or subsidized placement terms, contributing network effects without direct revenue.
Individuals anchor user base scale; Small Businesses anchor revenue expansion velocity.
Revenue Model:
Platform architecture determines which revenue mechanism captures transaction value without seller defection.
- Freemium:Free basic listings with paid promotion upgrades capture the largest addressable user base. Unit economics strain under cloud infrastructure and content moderation cost inflation.
- Subscription:Recurring fees from high-volume sellers stabilize cash flow in B2B verticals where inventory turnover justifies fixed platform expenditure.
- Advertisement:Display and native advertising monetizes browsing sessions from non-transacting visitors, requiring scale thresholds that favor established incumbents.
- Transaction Fees:Percentage-based commission on completed sales aligns platform incentives with seller success. Embedded payment and escrow functions raise capital intensity but expand revenue per sale.
Freemium dominates user acquisition; Transaction Fees dominates value extraction per sale.
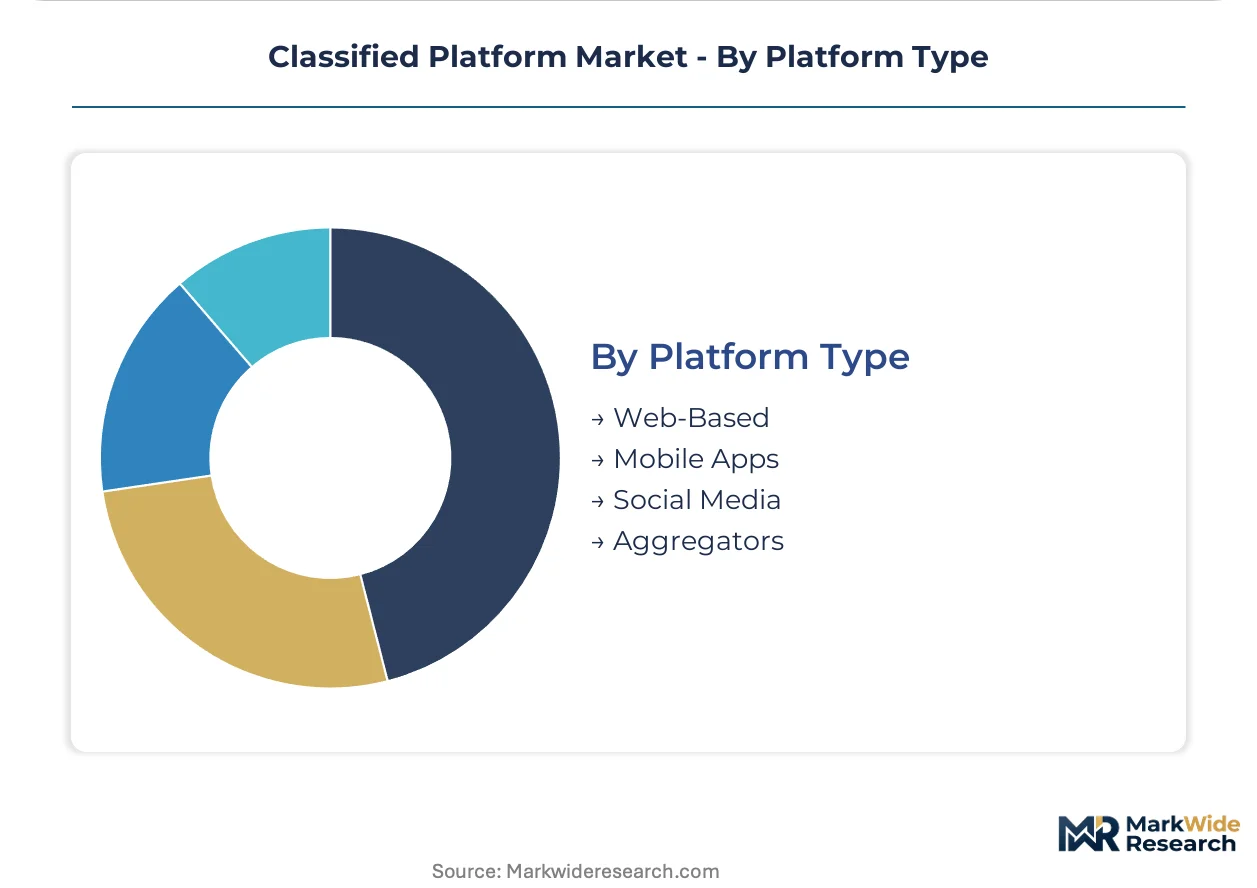
Platform Type:
Distribution channel selection constrains development cost, user acquisition economics, and regulatory exposure.
- Web-Based:Desktop-optimized platforms retain enterprise seller preference where complex listing creation and bulk upload tools demand screen real estate.
- Mobile Apps:Smartphone-native interfaces dominate Southeast Asian peer-to-peer commerce. Session frequency advantages compress discovery-to-contact latency for spontaneous purchase decisions.
- Social Media:Marketplace functions embedded within messaging and content platforms leverage pre-authenticated identity graphs but surrender pricing control to platform owners.
- Aggregators:Meta-search and inventory consolidation services capture demand-side traffic without holding seller relationships directly.
Web-Based retains B2B concentration; Mobile Apps gains share fastest in consumer-facing segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Developer talent pools in Bangalore, Singapore, and Shenzhen anchor platform engineering capacity across three continents. These clusters concentrate mobile-first product teams and machine learning infrastructure. Regulatory divergence now forces parallel compliance architectures rather than unified global stacks.
India
Tier-3 city merchant digitization and vernacular-language onboarding drive user expansion beyond metropolitan centers. BIS digital marketplace guidelines mandate seller verification protocols that elevate trust infrastructure costs. Bangalore anchors product development for CarTrade Tech and OLX Group, where automotive and general classifieds compete for dominance.
China
Super-app ecosystem conditioning creates user expectations for seamless payment-embedded transactions. SAMR antitrust enforcement constrains how 58.com structures merchant relationships and data usage. Shenzhen and Beijing clusters concentrate AI-image recognition engineering for automated listing generation.
Germany
Enterprise classified advertisers demand API compatibility with established ERP systems, extending platform sales cycles. GDPR and the EU Digital Services Act impose auditable recommendation systems and rapid takedown protocols. Berlin hosts Adevinta's European automotive vertical specialization alongside real estate trust-mechanism development.
United States
Minimalist interface design persists in legacy horizontal marketplaces resisting feature bloat. Section 230 liability frameworks contrast sharply with European content moderation mandates. Craigslist maintains operational presence in San Francisco despite mobile-first competitive pressure from Southeast Asian imports.
Singapore
Cross-border payment settlement latency drives demand for localized escrow infrastructure in multi-currency Southeast Asian trade. Carousell leverages mobile-first design dominance across peer-to-peer commerce corridors. The city-state serves as regional headquarters for platform expansion into Indonesia, Malaysia, and Philippines markets.
Classified Platform Market Competitive Environment
Capital-heavy full-stack platforms compete with asset-light discovery-only operators for transaction-value capture. The sector exhibits tiered concentration: dominant horizontal incumbents, vertical specialists commanding premium placement fees, and mobile-native challengers compressing onboarding friction. Three archetypes define positioning: trust-verified premium listers, volume-driven freemium aggregators, and transaction-complete commerce enablers. Consolidation through vertical acquisition and embedded finance partnerships represents the dominant competitive dynamic.
Among mobile-native challengers, Carousell exemplifies the asset-light, mobile-first archetype that has captured Southeast Asian peer-to-peer commerce. OLX Group anchors emerging market horizontal dominance through localized operations across multiple continents. Adevinta occupies the European vertical specialist position, sustaining real estate and automotive segment depth where inspection standardization commands advertiser willingness-to-pay.
| Leading Market Players |
|---|
| Carousell |
| CarTrade Tech |
| Adevinta |
| Trade Me |
| 58.com |
| OLX Group (Prosus) |
| Zoopla |
| Dubizzle Group |
| Craigslist |
| Others |
Value Chain & Pricing Dynamics
The EU Digital Services Act's content moderation mandates gate qualified supply for premium-tier platform access, forcing compliance investments that stratify pricing power between verified and unverified listing tiers across European markets.
Pricing Analysis
The bundled-vs-unbundled service split defines how classified platforms capture value. Three-tier pricing structure across premium, standard, and economy levels segments seller willingness-to-pay by verification depth and placement prominence. Price differentiation hinges on trust-mechanism certification and geographic delivery cost for cross-border transactions. Cost compression in freemium tiers is intensifying because cloud infrastructure and payment processing fees inflate operating expenditure. Small businesses show highest price sensitivity, while enterprise advertisers accept premium rates for API-integrated inventory management.
Supply Chain Analysis
India's BIS digital marketplace guidelines and local-content-rule pressures are reshaping sourcing for trust infrastructure and verification services. Engineering talent concentrates in India, Singapore, and Germany, drawing from specialized developer pools for mobile-first platform architecture. Raw material dependencies center on cloud compute capacity, payment gateway infrastructure, and AI-image recognition licensing. Single-source vulnerability runs through Google and Apple mobile ecosystems as distribution gatekeepers. Distribution runs through app store channels and direct mobile web access, with regional escrow providers handling multi-currency settlement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers geographic-arbitrage value through divergent regulatory compliance costs between EU-mandated trust infrastructure and Southeast Asia's lighter-touch mobile-first expansion paths.
For Market Incumbents: Deepen vertical specialization in automotive and real estate segments where inspection standardization commands premium placement fees. Invest in backward integration of payment escrow and dispute resolution to capture transaction-fee revenue from discovery-only competitors. Defend against mobile-native challengers by compressing onboarding friction through AI-image recognition tools. Prioritize certification investment for EU Digital Services Act compliance to sustain European market access. For New Entrants and Emerging Players: Enter via Tier-3 and Tier-4 Indian cities where vernacular-language platform localization remains nascent. Target small business merchant digitization across Indonesia and Philippines as the most penetrable segment. Pursue white-label trust infrastructure partnerships to bypass capital-intensive compliance buildout. Leverage lightweight, low-bandwidth listing tools as the primary go-to-market angle for bandwidth-constrained emerging markets. For Investors and Strategic Acquirers: Roll-up economics work for vertical specialists because fragmented regional compliance architectures prevent global platform consolidation. Focus acquisition targets on automotive and real estate classifieds with embedded financing capabilities. Monitor AI-image recognition adoption rates as the inflection signal for seller onboarding cost compression. Long-term viability favors transaction-complete platforms over discovery-only models across the analysis window.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Finance Integration | Payment escrow and lending partnerships transform advertising platforms into transaction-complete commerce enablers. |
| Vernacular Localization | Tier-3 city merchant onboarding in India expands addressable seller bases beyond English-fluent metropolitan centers. |
| AI-Image Recognition Deployment | Automated listing generation from smartphone photography compresses time-to-first-listing for small merchants. |
| Vertical Acquisition | Automotive inspection and real estate documentation specialists command premium placement fees from risk-averse advertisers. |
| Compliance Infrastructure Investment | EU Digital Services Act auditable systems create competitive moats against undercapitalized European entrants. |
Study Parameters
Direct dialogue with platform product managers, trust-and-safety operations leads, mobile engineering directors, and small business merchant listers grounded qualitative findings in operational reality. Secondary validation drew from SEC filings of listed platform operators, App Annie mobile session data, BIS digital marketplace guideline documents, and EU Digital Services Act implementation guidance. Bottom-up and top-down triangulation cross-checked seller base estimates against advertising revenue disclosures and payment processing volume indicators.
Bottom-up modeling of individual country markets by platform type, revenue model, and end-user segment converged with top-down macroeconomic scaling across the projection horizon. Segmentation dimensions modeled included product type, end-user sophistication tier, revenue mechanism, and platform distribution channel alongside regional regulatory cluster intensity. CAGRs were derived from fitted growth curves anchored to disclosed user base expansion and monetization yield improvements. Forecast inputs incorporated smartphone penetration trajectories and cloud infrastructure cost inflation assumptions.
Inputs from platform operator disclosures and regulatory filing databases were available through the study window; gaps in private company financials and emerging market transaction volumes introduce uncertainty bands around Southeast Asian and Tier-3 Indian projections. Forecasts reflect documented assumptions regarding mobile session frequency growth and compliance cost pass-through rates. Regulatory enforcement intensity and payment gateway pricing shifts represent primary revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Digital Painting Software Market
Software & Services
Global Recipe Apps Market
Software & Services
Federal Government Software Market
Software & Services
Japan IT Services Market
Software & Services
Adaptive Learning Software Market
Software & Services
HR Management Software (Personnel and Organization) Market
Software & Services
BIM Objects Software Market
Software & Services
Problem Management Software Market
Software & Services
3D Animation Production Software Market
Software & Services
Waterway Transportation Software Solutions Market
Software & Services
Global Data Quality Software Market
Software & Services
Global Printing Software Market
Software & Services
Global Bug Tracking Software Market
Software & Services
GCC Human Capital Management Software Market
Software & Services
Mobile Application Stores Market
Software & Services
Spend Analysis Software Market