
 Tenant Billing System Market | 2026-2036
Tenant Billing System Market Size, Share, and Industry Trends Forecast 2026-2036
Tenant Billing System Market Analytics
Fragmentation among mid-size property owners is repositioning vendor priorities toward scalable, self-service onboarding tools. Yardi Systems leverages its vertical software stack to dominate enterprise-grade deployments. RealPage sustains channel control through embedded utility data partnerships. MRI Software LLC anchors its position with deep accounting system integrations.
A tenant billing system automates utility allocation, rent invoicing, and payment collection across multi-occupancy properties, typically integrating submeter hardware data with general ledger APIs to eliminate manual meter reads and reconciliation delays. Cloud-based solutions now lead product type adoption as property managers prioritize remote accessibility and zero-maintenance infrastructure. Subscription-based pricing models capture the fastest expansion by aligning vendor revenue with customer success metrics and reducing upfront capital barriers.
ISO 50001 energy management standards and the EU Energy Efficiency Directive shape product specifications across European deployments, while the US EPA ENERGY STAR program and state-level public utility commission rules drive submetering accuracy requirements in North America. Stakeholders must monitor evolving data privacy frameworks and interoperability mandates that will determine which platforms retain technical relevance.
Market Dynamics
API-first cloud architectures are compressing deployment timelines from months to weeks, forcing incumbent vendors to re-architect legacy platforms or cede mid-market share to agile challengers.
Growth Catalysts
- ISO 50001 certification mandates:European commercial landlords face audit requirements that automated billing platforms satisfy through embedded energy tracking dashboards.
- Submetering hardware cost curves:LoRaWAN and NB-IoT module prices have dropped below utility-scale deployment thresholds, enabling retrofits in aging Class B and C properties.
- Remote property management normalization:Distributed asset portfolios now require centralized billing oversight, driving demand for zero-touch reconciliation systems.
Market Restraints
- Cloud infrastructure concentration:AWS, Azure, and GCP control over 80 percent of property management SaaS hosting, creating single-point-of-failure exposure for billing continuity.
- Utility data access fragmentation:North American investor-owned utilities maintain proprietary meter data formats that resist standardized API integration.
- Semiconductor supply volatility:Submetering device lead times for specialized ADC chips fluctuate with automotive and industrial demand cycles.
Strategic Opportunities
- Australia regulatory modernization:State-level mandatory disclosure schemes for commercial building energy performance create first-mover advantage for compliant platform vendors.
- AI-driven anomaly detection:Machine learning models trained on consumption patterns enable predictive maintenance bundles that expand vendor revenue per property.
- Embedded finance integration:Buy-now-pay-later functionality for tenant utility arrears opens new fee-based revenue streams without balance sheet exposure.
Industry Challenges
- Legacy ERP integration complexity:On-premise accounting systems in established property portfolios resist cloud-native billing data flows without expensive middleware development.
- Cybersecurity certification timelines:SOC 2 Type II and ISO 27001 audits require 6-12 month implementation cycles that delay enterprise sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tenant Billing System Market |
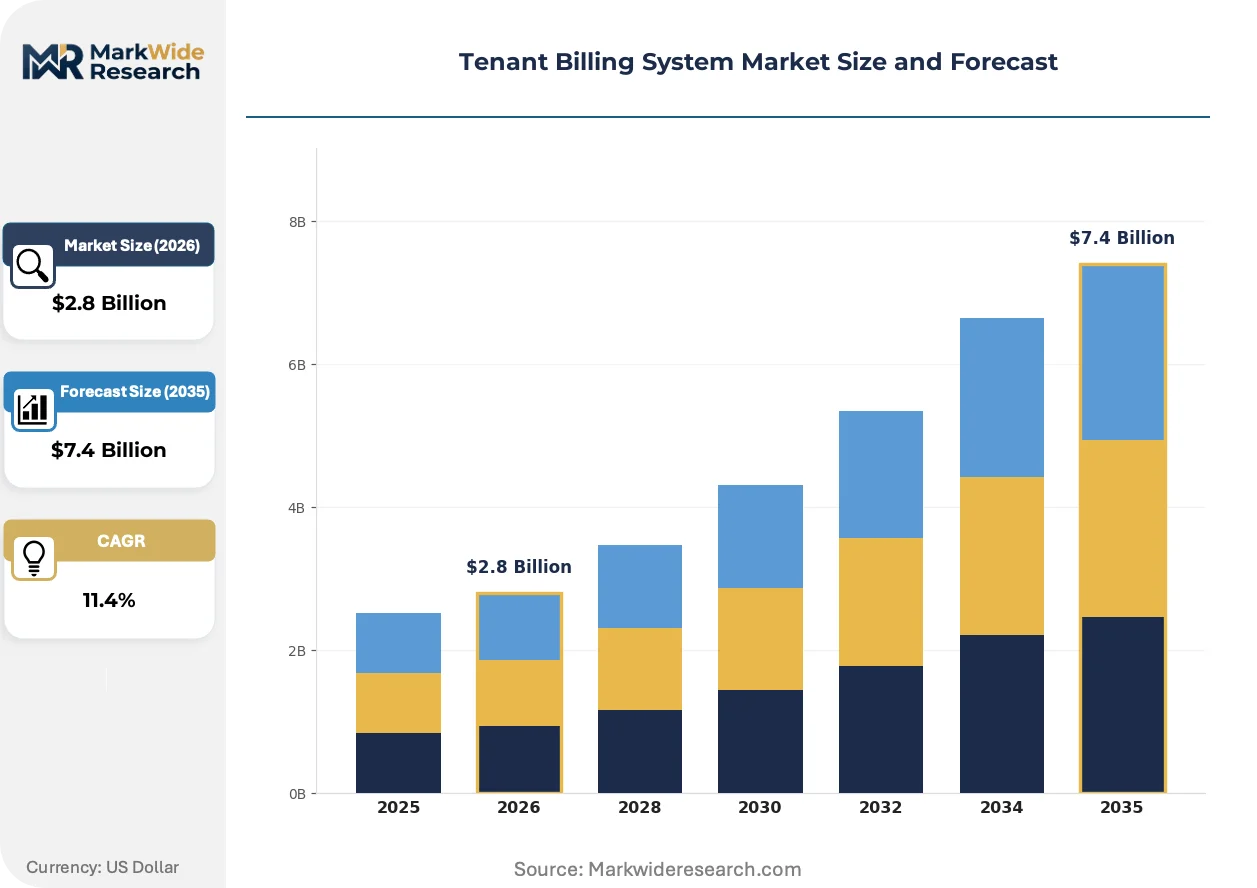
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based Solutions, On-Premise Solutions, Integrated Software, Mobile Applications End User: Property Management Companies, Real Estate Agencies, Landlords, Tenants Pricing Model: Subscription-Based, One-Time Purchase, Freemium, Pay-As-You-Go Deployment Type: Single-Tenant, Multi-Tenant, Hybrid, Dedicated |
| Companies Covered | Yardi Systems, Inc., RealPage, Inc., MRI Software LLC, AppFolio, Inc., Buildium, Enertiv, Inc., Utility Management Solutions, Inc., Accuenergy Inc., Energy Hippo, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tenant Billing System Market Evolving Landscape
Real-time data infrastructure is replacing batch-processing architectures across property technology stacks, compressing the gap between consumption events and invoice generation.
Serverless billing computation is overtaking provisioned virtual machine deployments by eliminating capacity planning overhead and scaling elastically with meter data ingestion volumes. Mid-size property management firms with 500-5,000 units are adopting this architecture fastest, drawn by consumption-based pricing that aligns costs with portfolio growth. The shift is overtaking traditional three-year infrastructure contracts and forcing vendors to rebuild margin models around per-transaction economics.
The EU Energy Efficiency Directive's recast requirements mandate hourly granularity for building-level energy reporting in commercial properties above specific floor area thresholds. This regulatory pressure is accelerating submetering refresh cycles and disqualifying platforms that cannot ingest 15-minute interval data. German and French deployment specifications now explicitly require EN 16247-compliant energy audit trails that native cloud billing systems provide more readily than retrofitted legacy tools.
Self-service onboarding portals are displacing traditional implementation-led deployments as property managers prioritize immediate configuration autonomy over white-glove setup. Channel partners and value-added resellers face margin compression as direct vendor relationships capture recurring revenue previously shared through intermediaries. This pattern concentrates in the United States, where property management software procurement has shifted toward product-led growth motions borrowed from adjacent fintech verticals.
Tenant Billing System Market Segmentation
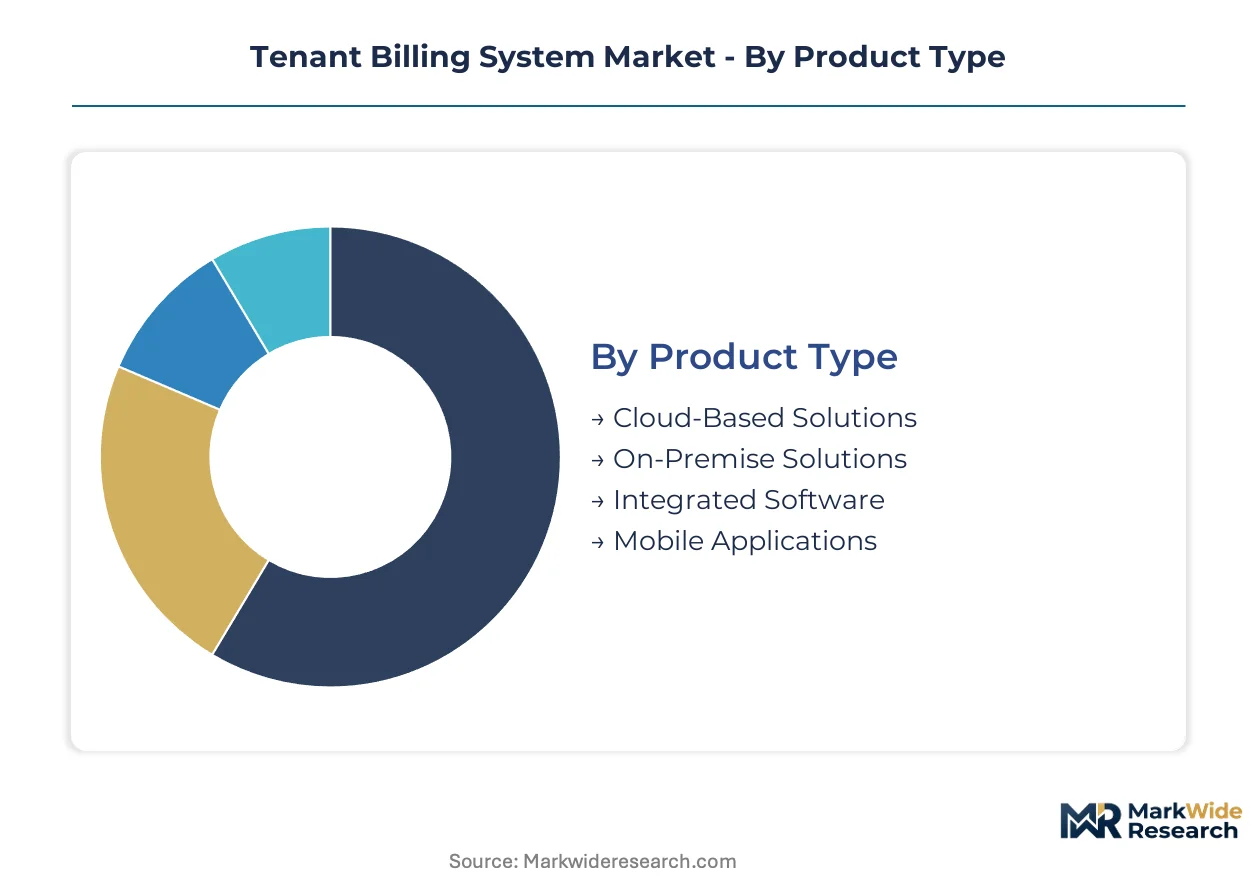
Segmentation in tenant billing systems reveals how procurement decisions split across technical architecture, customer scale, and commercial flexibility. Property managers select platforms based on portfolio complexity, regulatory exposure, and existing software investments rather than feature checklists alone.
Product Type:
Upgrade cycles in property technology now compress from decade-long ERP refreshes to 2-3 year cloud migrations as remote management requirements reshape infrastructure priorities.
- Cloud-Based Solutions:These platforms deliver meter data ingestion, invoice generation, and payment processing through browser-based dashboards with zero local server maintenance. Demand clusters among mid-size property management firms operating distributed portfolios across multiple states, driven by ISO 27001 compliance requirements that cloud-native architectures satisfy faster than retrofitted legacy systems.
- On-Premise Solutions:Deployed within customer data centers with direct control over submeter hardware integration and general ledger synchronization. Class A commercial landlords in Germany and France specify these deployments to satisfy EN 16247 audit trail mandates and GDPR data residency rules that resist multi-tenant cloud architectures.
- Integrated Software:Billing modules embedded within broader property management suites connecting rent rolls, maintenance ticketing, and utility allocation in unified databases.
- Mobile Applications:Tenant-facing interfaces for consumption visibility, payment submission, and dispute management, typically white-labeled under property manager brands.
Volume placements concentrate in Cloud-Based Solutions; the faster expansion belongs to Mobile Applications as tenant experience expectations migrate from fintech verticals.
End User:
Customer type determines contract value, implementation complexity, and retention mechanics across fundamentally different organizational purchasing behaviors.
- Property Management Companies:Third-party operators managing portfolios on behalf of institutional owners, requiring multi-property dashboards and automated reconciliation across hundreds of buildings. These customers in the United States drive API-first procurement specifications that compress vendor selection cycles.
- Real Estate Agencies:Brokerage-adjacent operators handling billing for smaller multi-family properties on behalf of dispersed individual investors. Australian state-level mandatory disclosure schemes for commercial building energy performance create compliance pressure that shapes their platform requirements.
- Landlords:Direct owners of rental properties ranging from single buildings to small portfolios, typically price-sensitive and requiring self-service configuration without implementation fees.
- Tenants:End-recipients of billing information rather than direct purchasers, though their app usage patterns and payment preferences increasingly influence landlord platform selection.
Contract values peak with Property Management Companies; Real Estate Agencies represent the volume frontier as regulatory compliance spreads beyond institutional portfolios.
Pricing Model:
Commercial structure alignment separates vendors capturing recurring revenue from those trapped in one-time license dependencies.
- Subscription-Based:Monthly or annual fees tied to unit count, meter volume, or transaction throughput with embedded support and feature updates. This model dominates among cloud-native vendors in the United States where property managers prioritize operational expenditure classification over capital budget requests.
- One-Time Purchase:Perpetual licenses with annual maintenance fees, still preferred by on-premise deployments in regulated European markets where multi-year amortization matches depreciation schedules.
- Freemium:Tiered entry points with basic utility allocation free and advanced features—submeter integration, automated late fees, custom branding—unlocked at paid tiers.
- Pay-As-You-Go:Consumption-based pricing where fees scale with actual invoice generation volume rather than portfolio size, attracting variable-occupancy properties like student housing and short-term corporate accommodations.
Revenue stability favors Subscription-Based; Pay-As-You-Go climbs fastest among flexible-occupancy segments recovering from pandemic-era vacancy volatility.
Deployment Type:
Architecture isolation requirements split between efficiency-seeking multi-tenant efficiency and risk-averse dedicated infrastructure.
- Single-Tenant:Isolated software instances serving one customer with dedicated database and compute resources, specified by healthcare-adjacent property owners in the United States facing HIPAA-aligned data segregation requirements.
- Multi-Tenant:Shared infrastructure with logical separation between customers, delivering vendor operational leverage that enables lower price points and faster feature rollout. This architecture captures mid-market expansion in Australia and Germany where standardization outweighs customization demands.
- Hybrid:Combinations placing sensitive billing data on-premise while leveraging cloud analytics and tenant-facing portals, bridging compliance and accessibility for established portfolios with legacy ERP investments.
- Dedicated:Physically isolated cloud resources within specific regions, satisfying data residency mandates from French CNIL guidance and emerging Middle Eastern regulatory frameworks.
Operational efficiency centers on Multi-Tenant; Hybrid deployments gain share fastest among institutional owners modernizing aging on-premise installations without full cloud migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center capacity in Northern Virginia anchors North American cloud infrastructure expansion for property technology platforms. Submarine cable landings in Portugal and Spain feed European latency requirements for real-time billing systems. Submetering hardware manufacturing clusters in Shenzhen and Dongguan supply cost-competitive IoT modules worldwide.
United States
Multi-state property management firms operating 10,000-plus units drive API-first procurement specifications that compress vendor selection cycles. The EPA ENERGY STAR program mandates granular energy disclosure for commercial buildings over 25,000 square feet. Dallas-Fort Worth and Atlanta metropolitan clusters concentrate third-party property management headquarters deploying centralized billing oversight.
Germany
Class A commercial landlords specify isolated deployments to satisfy EN 16247 audit trail mandates and GDPR data residency requirements. The EU Energy Efficiency Directive recast mandates hourly granularity for building-level energy reporting above specific floor area thresholds. Frankfurt and Munich financial districts host institutional asset managers modernizing legacy ERP installations through hybrid cloud architectures.
Australia
State-level mandatory disclosure schemes for commercial building energy performance create first-mover advantage pressure for compliant platform vendors. The National Australian Built Environment Rating System establishes benchmarking requirements that automated billing dashboards satisfy. Sydney and Melbourne central business districts concentrate retrofit activity in aging Class B office stock seeking submetering upgrades.
France
CNIL guidance on financial data residency drives specifications for dedicated cloud resources within national boundaries. The tertiary sector decree mandates consumption disclosure for commercial leases above defined surface thresholds. Paris Île-de-France hosts property technology procurement decisions for pan-European institutional portfolios requiring GDPR-aligned data segregation.
United Kingdom
Brokerage-adjacent operators handling billing for dispersed individual investors prioritize self-service configuration without implementation fees. The Minimum Energy Efficiency Standards framework establishes compliance deadlines that automated tracking satisfies. London and Southeast England concentrate flexible-occupancy properties like student housing and corporate accommodations adopting pay-as-you-go pricing models.
Tenant Billing System Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue embedded finance and AI-driven anomaly detection bundles. The vendor base stratifies across enterprise-grade suite providers, vertical specialists in utility data integration, and agile challengers with serverless architectures. Three archetypes dominate: full-stack property management platforms, standalone billing specialists with deep submeter hardware partnerships, and API-native challengers attacking mid-market share. Consolidation pressure manifests through strategic acquisitions of IoT data aggregators and geographic expansion into regulatory-mandated markets like Australia.
Within the enterprise-tier, Yardi Systems, Inc. and RealPage, Inc. exemplify full-stack incumbents leveraging vertical software depth to dominate large-scale deployments. MRI Software LLC occupies a position anchoring accounting system integration requirements for institutional owners. AppFolio, Inc. represents the agile challenger archetype with cloud-native architectures compressing implementation timelines.
| Leading Market Players |
|---|
| Yardi Systems, Inc. |
| RealPage, Inc. |
| MRI Software LLC |
| AppFolio, Inc. |
| Buildium |
| Enertiv, Inc. |
| Utility Management Solutions, Inc. |
| Accuenergy Inc. |
| Energy Hippo, Inc. |
| Others |
Value Network & Pricing Analysis
Serverless billing computation architectures are compressing infrastructure costs for mid-size property managers while simultaneously concentrating compute-layer dependency on AWS, Azure, and GCP hyperscalers. This technical transition simultaneously enables consumption-based vendor pricing and creates single-point-of-failure exposure that buyers must price into continuity planning.
Pricing Analysis
Warranty and service bundling separates enterprise-tier subscriptions with SOC 2 compliance support from stripped-down SaaS tiers lacking implementation assistance. Three-tier pricing structure across premium, standard, and economy levels tracks deployment complexity and audit trail depth. Price differentiation hinges on ISO 27001 certification status and submeter hardware integration scope. Cost compression in the economy tier is intensifying because self-service onboarding portals eliminate professional services revenue. Small landlords with under 500 units exhibit highest price sensitivity; institutional owners with 10,000-plus units prioritize compliance over cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for specialized ADC chips powering submetering devices, while China dominates LoRaWAN and NB-IoT module fabrication. The supply chain draws from Shenzhen and Dongguan manufacturing clusters for cost-competitive IoT hardware, German precision sensor suppliers for Class A commercial specifications, and US-based cloud infrastructure for data processing layers. Semiconductor supply volatility tied to automotive demand cycles creates lead time instability. Distribution runs through direct vendor relationships displacing traditional value-added resellers as self-service procurement gains traction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where EN 16247 audit mandates and GDPR data residency rules erect technical barriers that filter out undercapitalized challengers. Regulatory certification timelines create moats protecting incumbent positions.
For Market Incumbents: Anticipate API-native challengers compressing mid-market sales cycles through product-led growth motions. Defensive consolidation should prioritize acquisition of IoT data aggregators to deepen submeter hardware integration capabilities. Channel control through embedded utility data partnerships remains essential as direct vendor relationships capture recurring revenue previously shared through intermediaries. For New Entrants and Emerging Players: Class B and C property owners in aging Australian office stock represent an underserved buyer archetype with unmet submetering retrofit demand. White-space targets include student housing operators seeking pay-as-you-go pricing flexibility and Real Estate Agencies navigating state-level mandatory disclosure schemes. A compliance-first go-to-market angle targeting ENERGY STAR disclosure requirements opens procurement doors faster than feature comparisons. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by full-stack property management platforms seeking vertical extension into utility data integration. Long-term viability favors vendors with serverless architectures and embedded finance capabilities that expand revenue per property beyond core billing functions. The signal to watch is regulatory adoption velocity for hourly energy reporting granularity across EU member states.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Compresses deployment timelines from months to weeks for mid-market property managers. |
| Submeter Hardware Partnership | Secures preferential LoRaWAN module allocation amid semiconductor supply volatility. |
| Embedded Finance Launch | Opens fee-based revenue streams through buy-now-pay-later utility arrears functionality. |
| AI Anomaly Detection Bundle | Expands vendor revenue per property via predictive maintenance service attachments. |
| Geographic Expansion into Australia | Captures first-mover advantage under state-level mandatory energy disclosure schemes. |
Research Methodology
Independent corroboration across property technology executives, submeter hardware manufacturers, and institutional asset managers underwrites the qualitative findings. Primary interviews with CTOs at multi-state property management firms, integration specialists at utility data aggregators, and procurement leads at Class A commercial landlords combined with secondary validation. Secondary sources include EPA ENERGY STAR disclosure databases, EU Energy Efficiency Directive implementation reports, and hyperscaler SaaS revenue disclosures. Bottom-up unit economics modeling and top-down market sizing triangulate volume estimates.
Comparable-period anchoring to historical cloud migration cycles and submetering hardware refresh timelines structured the forecast window. The analytical framework models deployment type, customer scale tier, and pricing model flexibility across the projection horizon. CAGRs derive from segment-level adoption curves weighted by regulatory mandate implementation schedules. Forecast inputs incorporate utility data access fragmentation patterns and ISO 50001 certification penetration rates by geography.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor supply volatility and evolving data privacy framework interpretations. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Feedback Management Software Market
Software & Services
Global Manufacturing Operations Management (MOM) Software Market
Software & Services
Background Removal Software Market
Software & Services
RFP Software Market
Software & Services
Global Online Form Builder Software Market
Software & Services
Global Nosql Software Market
Software & Services
Enterprise Software Market
Software & Services
Account Reconciliation Software Market
Software & Services
US Content Services Platform Market
Software & Services
Non-Profit Donation Software Market
Software & Services
Global Mobile User Interface Services Market
Software & Services
Mind Mapping Software Market
Software & Services
Construction Project Management Software Market
Software & Services
Salon Booking Software Market
Software & Services
Database Monitoring Software Market
Software & Services
Architectural Rendering Software Market