
 Workflow Management Software (WMS) Market | 2026-2036
Workflow Management Software (WMS) Market Size, Share, and Industry Trends Forecast 2026-2036
Workflow Management Software (WMS) Market Analytics
Mid-market professional services firms are rotating toward integrated workflow platforms as their primary technology investment, displacing standalone project tools that dominated earlier procurement cycles. Asana leverages its template marketplace to sustain engagement across creative agencies and marketing departments. monday.com anchors its position through verticalized product bundles tailored to construction and real estate workflows. Nintex competes in the process automation layer where enterprises require deep connector libraries to legacy systems.
Workflow management software orchestrates sequential and parallel business processes through configurable rule engines, visual process designers, and real-time status dashboards that integrate with enterprise data repositories. The primary commercial purpose centers on reducing manual handoffs, eliminating process bottlenecks, and generating audit trails for operational compliance. Cloud-based deployment leads current uptake as organizations prioritize elastic scaling and reduced infrastructure overhead, while hybrid configurations capture growing interest from financial services and government verticals with strict data residency requirements. Task automation solutions within the solution segment attract disproportionate R&D investment as vendors embed AI-driven routing and predictive escalation capabilities.
FDA 21 CFR Part 11 shapes validation requirements for workflow systems handling electronic records in pharmaceutical and medical device manufacturing, while HIPAA governs access controls and audit logging for healthcare deployments. The EU AI Act imposes risk-classification obligations on workflow platforms deploying automated decision-making, compelling vendors to build explainability features and human-in-the-loop checkpoints. Stakeholders must evaluate whether their vendor's compliance roadmap aligns with emerging sector-specific mandates before committing to multi-year enterprise agreements.
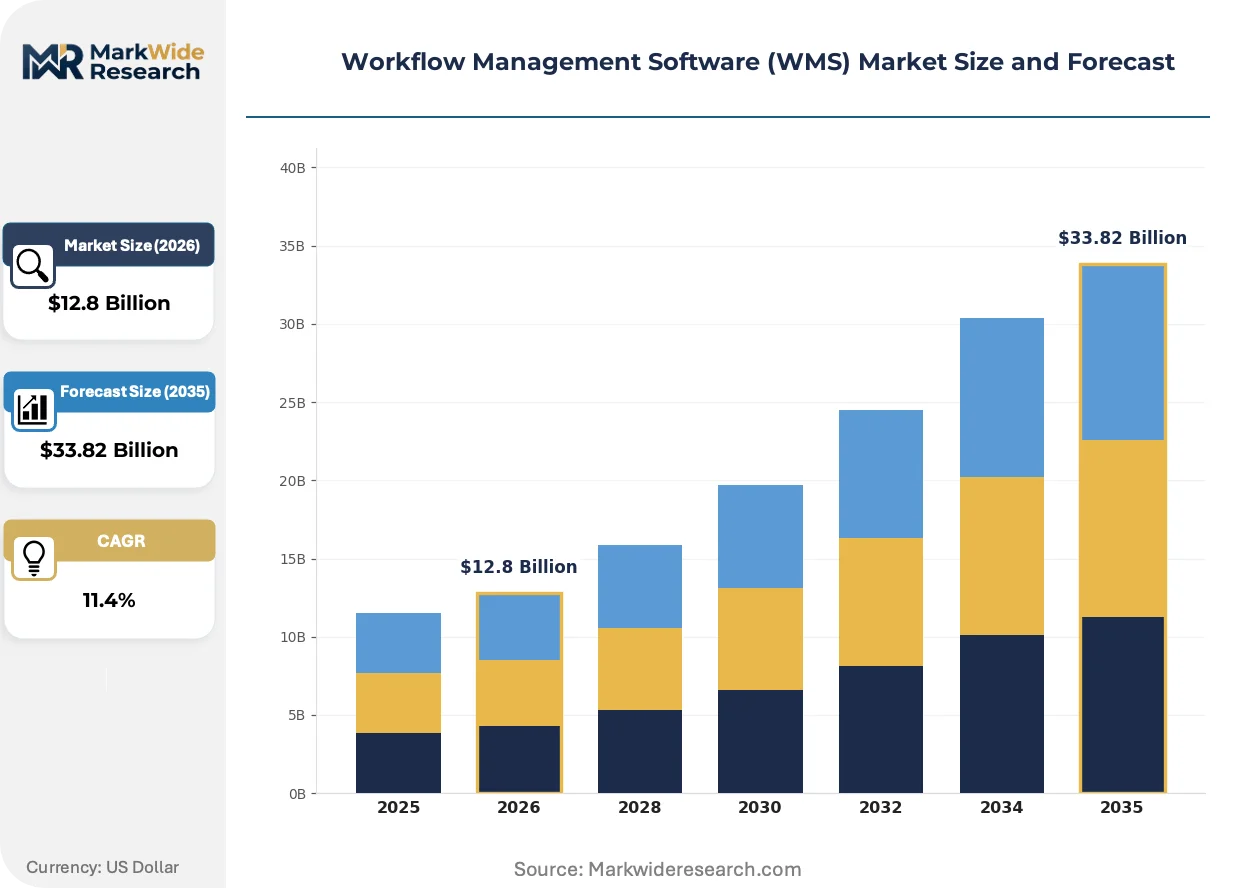
Market Dynamics
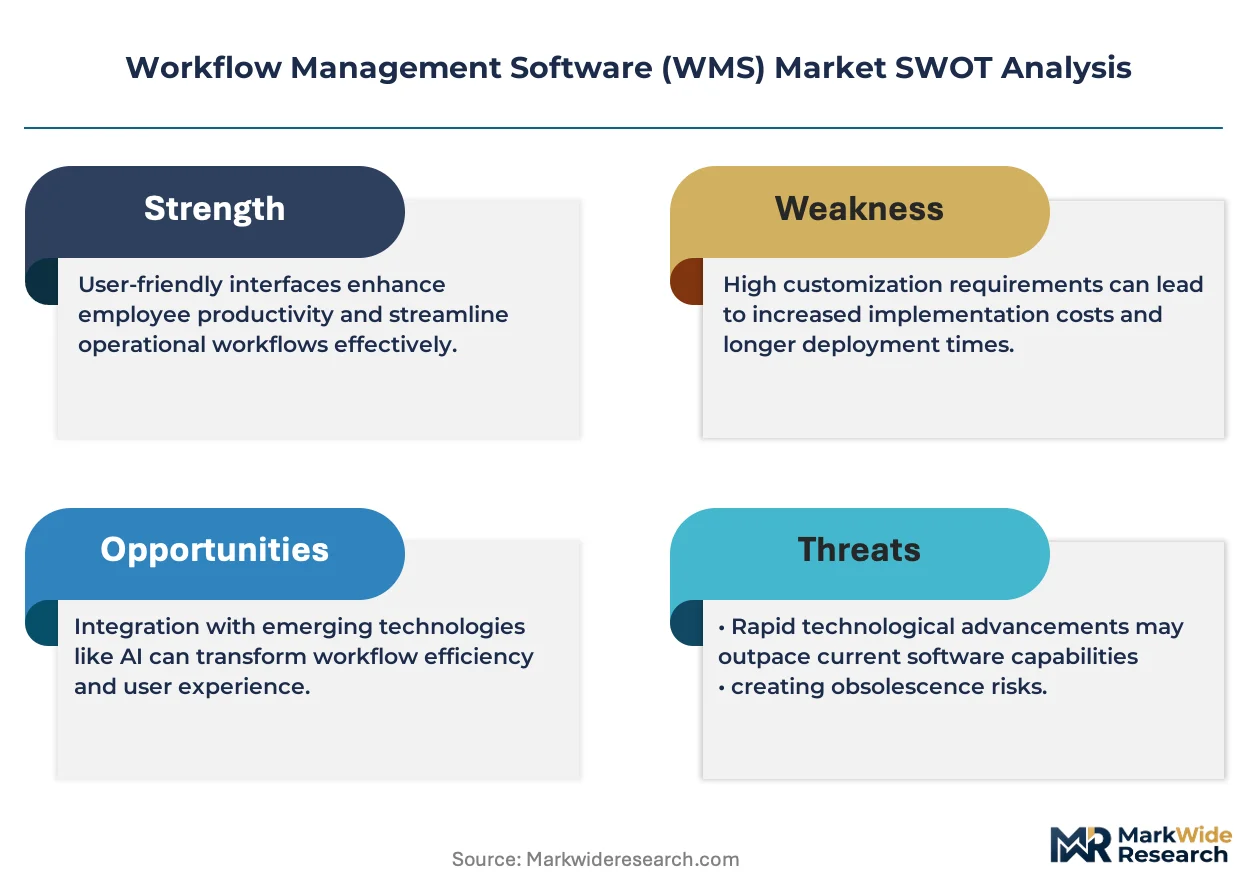
AI-driven process orchestration is compressing deployment cycles for enterprise workflow platforms, forcing vendors to embed predictive routing and explainable decision engines ahead of compliance mandates.
Growth Catalysts
- Federal digital transformation mandates:United States agencies are accelerating cloud migration timelines, creating immediate procurement windows for compliant workflow infrastructure.
- EU AI Act risk classification:European enterprises must retrofit automated decision systems with human-in-the-loop checkpoints, generating replacement demand for explainable workflow platforms.
- Healthcare billing automation:HIPAA-covered entities are consolidating patient intake and revenue cycle operations onto unified workflow stacks to reduce manual handoff errors.
Market Restraints
- Legacy system integration costs:Deep connector development for mainframe and on-premise ERP environments consumes disproportionate R&D resources relative to cloud-native deployments.
- Data residency compliance fragmentation:Financial services and government verticals face conflicting sovereignty requirements across Germany, France, and Switzerland, complicating multi-tenant architectures.
- Substitution by low-code platforms:Microsoft Power Platform and ServiceNow workflow modules capture mid-market spend that previously flowed to standalone WMS vendors.
Strategic Opportunities
- Construction vertical bundling:Project-based contractors in Australia and Canada lack tailored workflow tools for subcontractor coordination and compliance documentation.
- ISO 9001 quality management convergence:Integrated platforms combining workflow orchestration with audit trail generation capture quality-conscious manufacturing spend in Japan and South Korea.
- API-first distribution:Embedded workflow engines sold through Salesforce AppExchange and AWS Marketplace reduce customer acquisition costs for specialized process automation vendors.
Industry Challenges
- Process mining expertise scarcity:Enterprise implementations require analysts fluent in Celonis or UiPath process intelligence, talent concentrated among Big Four consultancies.
- FDA 21 CFR Part 11 validation timelines:Pharmaceutical deployments demand 12-18 month qualification periods for electronic signature and audit trail functionality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Workflow Management Software (WMS) Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $33.82 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS End User: Healthcare, Manufacturing, Retail, Professional Services Solution: Task Automation, Document Management, Collaboration Tools, Analytics Industry Vertical: Education, Construction, Telecommunications, Government |
| Companies Covered | monday.com, Wrike, Asana, Smartsheet, Nintex, Kissflow, Pipefy, Screendragon, Adobe Workfront, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Workflow Management Software (WMS) Market Evolving Landscape
Workflow platforms are converging with adjacent automation layers, blurring traditional boundaries between task management, robotic process automation, and business process management suites.
Agentic AI orchestration is miniaturizing complex multi-step approvals into autonomous sub-processes that execute without human intervention. Healthcare payers in the United States are piloting these systems for claims adjudication, compressing cycle times from days to hours. The technology is miniaturizing the functional scope of traditional business analyst roles while elevating demand for AI governance specialists.
The EU AI Act's risk-based classification system is forcing workflow vendors to build transparency dashboards and override mechanisms for high-risk automated decisions. Pharmaceutical manufacturers deploying batch release workflows must now document algorithmic logic for EMA inspectors. German and French enterprises are prioritizing vendors with pre-built compliance templates over configurable but unvalidated alternatives.
Mid-market buyers are unbundling implementation services from software licenses, preferring fixed-fee system integrators over vendor professional services. This procurement pattern is most pronounced among United States professional services firms with 200-2,000 employees, where CFOs demand cost certainty for digital transformation budgets. Channel partners with vertical certifications are capturing margin that previously accrued to platform vendors.
Workflow Management Software (WMS) Market Segmentation
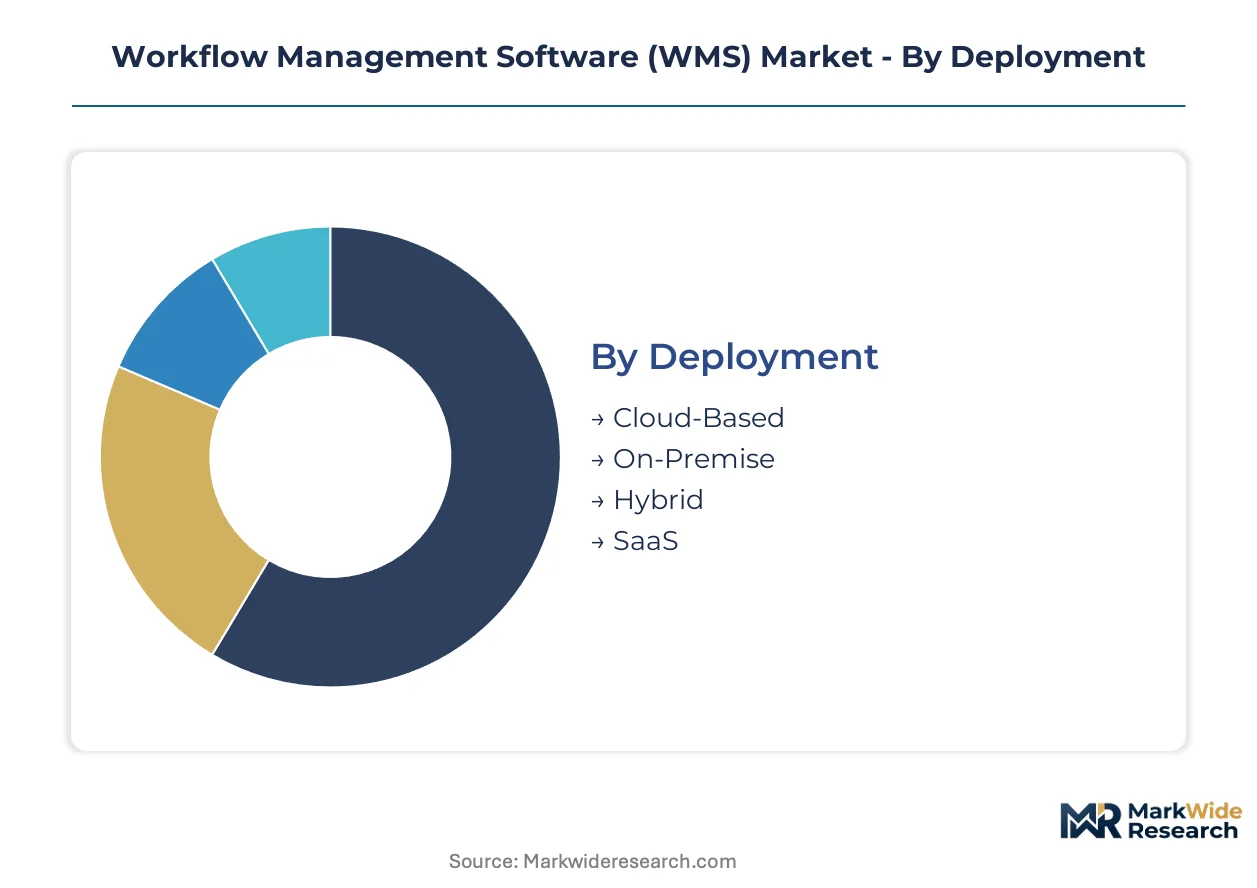
Workflow management software vendors compete across four distinct segmentation axes that determine pricing power, implementation complexity, and customer lifetime value. Deployment mode dictates infrastructure requirements and data residency compliance. End-user concentration shapes vertical sales specialization and regulatory exposure.
Deployment:
Cloud-native configurations face intensifying substitution pressure from hyperscaler-embedded workflow modules, while hybrid architectures command premium pricing for sovereignty-sensitive buyers.
- Cloud-Based:Multi-tenant architectures with elastic compute scaling dominate mid-market procurement. United States federal agencies under cloud-first mandates are consolidating spend here, though HIPAA-covered entities demand business associate agreements with enhanced audit provisions.
- Hybrid:Split-stack configurations separate orchestration logic from sensitive data repositories. Financial services firms in Germany and Switzerland prioritize this model to satisfy Bundesbank and FINMA data localization requirements without sacrificing SaaS agility.
- On-Premise:Air-gapped installations persist in defense and classified government environments.
- SaaS:Subscription delivery with API-first integration layers captures marketing and creative agency demand.
Cloud-Based deployments anchor the volume base while Hybrid configurations gain share at the steepest rate.
End User:
Cost tier stratification separates enterprise-grade compliance investments from departmental productivity tools.
- Healthcare:HIPAA-governed platforms with FDA 21 CFR Part 11 validation for electronic signatures. Hospital systems in the United States are consolidating patient intake and revenue cycle workflows onto unified stacks to eliminate manual handoff errors in billing operations.
- Professional Services:Project-based orchestration with time-tracking and client billing integration. Mid-market firms with 200-2,000 employees in the United States are rotating toward integrated platforms as primary technology investments.
- Manufacturing:ISO 9001-aligned audit trail generation for quality management convergence.
- Retail:Seasonal workforce scaling and omnichannel fulfillment coordination.
Healthcare anchors the volume base while Professional Services expands most quickly as billable-hour optimization drives procurement urgency.
Solution:
Application depth determines whether platforms capture standalone budget or become absorbed into broader automation suites.
- Task Automation:AI-driven routing engines with predictive escalation capabilities attract disproportionate R&D investment. Healthcare payers in the United States are piloting agentic orchestration for claims adjudication, compressing cycle times from days to hours.
- Document Management:Version control and approval workflows with e-signature integration. Construction firms in Australia and Canada require subcontractor coordination and compliance documentation capabilities that generic tools lack.
- Collaboration Tools:Real-time status dashboards and threaded communication layers.
- Analytics:Process mining integration with Celonis or UiPath intelligence for bottleneck identification.
Task Automation anchors the volume base while Analytics climbs the fastest as process intelligence becomes a competitive necessity.
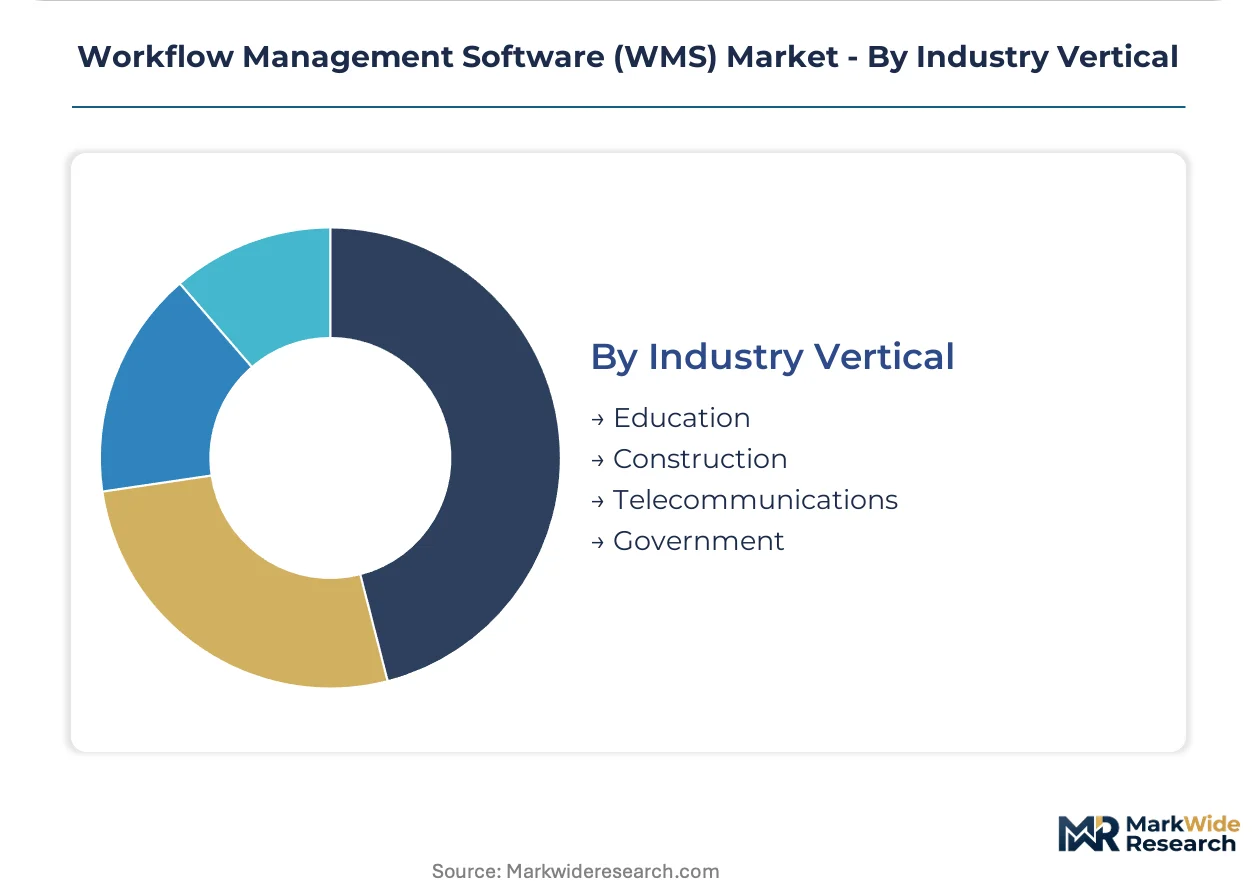
Industry Vertical:
Supply concentration in government and telecommunications creates captive vendor relationships resistant to price compression.
- Government:FedRAMP-authorized or equivalent national security-cleared deployments. United States federal agencies under accelerated digital transformation mandates are creating immediate procurement windows for compliant infrastructure.
- Construction:Project-based billing with subcontractor compliance documentation and lien waiver tracking. Australian and Canadian contractors lack tailored tools for coordination across dispersed job sites.
- Education:Student information system integration and grant compliance workflows.
- Telecommunications:Network operations center coordination and field service dispatch.
Government anchors the volume base while Construction shows the steepest expansion trajectory as infrastructure investment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers concentrate in jurisdictions with stringent compliance mandates and federal procurement acceleration. Cloud migration timelines and AI governance requirements are reshaping vendor selection criteria across major economies.
United States
Federal agencies under digital transformation mandates are consolidating cloud-first workflow procurement. HIPAA-covered entities in hospital systems demand FDA 21 CFR Part 11 validation for electronic signature workflows. The Boston-Cambridge corridor anchors healthcare payer adoption of agentic AI claims adjudication.
Germany
Industrial manufacturers prioritize ISO 9001-aligned audit trail generation for quality management convergence. The EU AI Act imposes risk-classification obligations requiring human-in-the-loop checkpoints in automated decision systems. Bavarian automotive suppliers are retrofitting batch release workflows with explainability dashboards for EMA inspection readiness.
United Kingdom
Professional services firms with 200-2,000 employees are unbundling implementation services from software licenses. GDPR compliance requirements shape data residency specifications for hybrid deployments. London's financial services cluster drives demand for split-stack configurations separating orchestration logic from sensitive repositories.
Japan
Manufacturing quality-conscious spend is converging toward platforms combining workflow orchestration with audit trail generation. METI industrial digitization programs accelerate SME cloud adoption. The Nagoya-Chubu industrial corridor represents concentrated demand for ISO-aligned document management workflows.
Australia
Construction contractors lack tailored tools for subcontractor coordination across dispersed job sites. Federal infrastructure investment is accelerating project-based billing platform procurement. Sydney and Melbourne anchor demand for compliance documentation capabilities that generic productivity tools fail to address.
Workflow Management Software (WMS) Market Competitive Landscape
Player mix skews toward cloud-native SaaS vendors with vertical specialization layers. The competitive set fragments across task management generalists, process automation specialists, and work management platforms with embedded collaboration tools. Strategic archetypes include template-marketplace aggregators, vertical-bundle providers, and API-first embedded engines. Dominant competitive moves encompass vertical acquisition to capture sector-specific workflows and partnership channel development to displace vendor professional services revenue.
Among Israel-based collaboration specialists, monday.com anchors the construction and real estate vertical bundle tier. Asana occupies a position exemplifying template-marketplace aggregators sustaining creative agency engagement. Nintex represents the deep-connector process automation archetype targeting enterprise legacy system integration requirements.
| Leading Market Players |
|---|
| monday.com |
| Wrike |
| Asana |
| Smartsheet |
| Nintex |
| Kissflow |
| Pipefy |
| Screendragon |
| Adobe Workfront |
| Others |
Value Network & Pricing Analysis
FDA 21 CFR Part 11 validation requirements gate both vendor qualification and price differentiation in workflow management software, forcing pharmaceutical buyers to pay premiums for compliant platforms while excluding uncertified suppliers from regulated deployments. HIPAA-covered entities in hospital systems face parallel compliance barriers that compress procurement pools and sustain pricing power among qualified vendors.
Pricing Analysis
Cloud-native SaaS tiers command subscription premiums over legacy on-premise licensing, while hybrid deployments extract 40-60% price uplifts from financial services firms with Bundesbank and FINMA data localization mandates. Price differentiation rests on FedRAMP authorization tier and vertical-specific template depth, with government buyers showing lowest sensitivity due to mandate-driven procurement urgency. Cost compression in mid-market SaaS intensifies as Microsoft Power Platform and ServiceNow workflow modules absorb standalone vendor demand.
Supply Chain Analysis
API gateway congestion in hyperscaler marketplaces underwrites distribution bottlenecks for specialized workflow vendors seeking embedded placement. Supply concentrates in Israel, the United States, and Ireland for collaboration-platform engineering talent, while connector development for legacy ERP systems draws from India and Eastern European outsourcing hubs. Single-source vulnerability persists in AI model training data for predictive routing engines. Distribution runs through Salesforce AppExchange, AWS Marketplace, and direct enterprise sales teams with vertical certifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among United States federal agencies and mid-market professional services firms with 200-2,000 employees, compressing vendor margins and unbundling implementation services from software licenses.
For Market Incumbents: Consolidate vertical template libraries through targeted acquisition of construction and healthcare-specialized workflow tools. Deepen FedRAMP and HIPAA certification moats to defend against Microsoft Power Platform substitution. Anchor channel partner programs with fixed-fee system integrators to recapture margin lost to unbundled procurement.
For New Entrants and Emerging Players: Construction subcontractor coordination gaps in Australia and Canada offer white-space entry with compliance documentation bundles. ISO 9001-aligned audit trail convergence in Japanese manufacturing presents the most penetrable quality-management segment. Pursue API-first distribution through AWS Marketplace to bypass direct sales cost structures.
For Investors and Strategic Acquirers: EU AI Act risk-classification deadlines reshape the acquisition landscape toward explainable AI workflow engines with pre-built compliance templates. Target verticalized mid-cap specialists with construction or healthcare revenue concentration above 40%. Monitor EMA inspection readiness dashboards as the signal for pharmaceutical workflow replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Vertical Template Acquisition | Captures construction and healthcare sector-specific workflow logic from specialized vendors. |
| FedRAMP Authorization Investment | Unlocks United States federal agency procurement windows under accelerated cloud migration mandates. |
| API-First Embedded Distribution | Reduces customer acquisition costs through Salesforce AppExchange and AWS Marketplace placement. |
| EU AI Act Compliance Pre-Build | Accelerates European enterprise sales cycles with explainability dashboards and human-in-the-loop checkpoints. |
| Channel Partner Certification Program | Displaces vendor professional services revenue with fixed-fee system integrator relationships. |
Research Methodology
The analysis maps cloud-native SaaS, hybrid deployment, and on-premise workflow configurations, each validated through CTOs, IT procurement officers, platform engineers, and channel partners with vertical certifications. Primary interview data triangulates against SEC filings, hyperscaler capex disclosures, AppExchange marketplace metrics, and hospital procurement databases. Bottom-up vendor revenue estimates and top-down enterprise IT spend allocation converge across deployment mode, organization size, vertical industry, and regional adoption pattern segments.
Consistency checks validate volume and value outputs against external benchmarks throughout the projection horizon. The analytical framework models deployment mode, end-user concentration, solution depth, and industry vertical dimensions. CAGRs derive from segment-level growth rate synthesis with AI governance compliance timelines and federal procurement acceleration curves as key forecast inputs.
Forecasts assume regulatory continuity in FDA 21 CFR Part 11, HIPAA, and EU AI Act enforcement; material policy shifts would require re-modeling. Cloud migration pace among United States agencies and EMA inspection stringency for pharmaceutical batch release workflows represent specific risk factors. Practitioners should keep alternative scenarios live as AI Act implementation guidance and federal budget appropriations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Gamification Software Market
Software & Services
Fire Software Market
Software & Services
Pet Tracking Software Market
Software & Services
Hypervisor Market
Software & Services
Online Paint Editor App Market
Software & Services
Asia-Pacific Digital Signage Software Market
Software & Services
Parametric Design Software Market
Software & Services
Plant Design Software Market
Software & Services
Customer Revenue Optimization Software Market
Software & Services
Global Diagram Software Market
Software & Services
Global Disclosure Management Software Market
Software & Services
Global Sales Engagement Platform Market
Software & Services
Online Donation Software Market
Software & Services
Clustering Software Market
Software & Services
Global Cloud-Based Call Center Software Market
Software & Services
Performing Arts Software Market