
 Lead Scoring Software Market | 2026-2036
Lead Scoring Software Market Size, Share, and Industry Trends Forecast 2026-2036
Lead Scoring Software Market Foresight
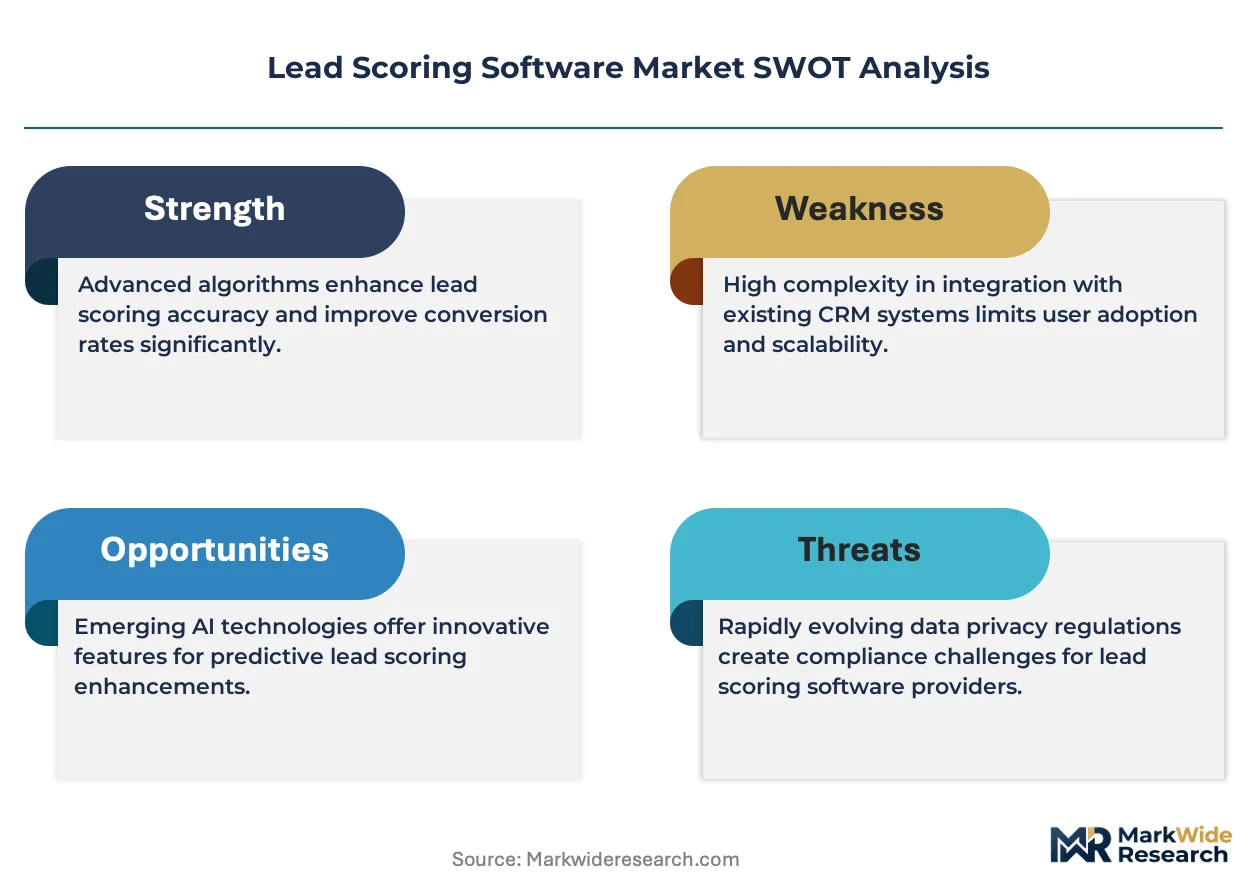
GDPR and the EU AI Act is realigning how vendors process behavioral signals for scoring models, forcing explicit consent architectures into product design. Salesforce leverages its CRM dominance to anchor scoring modules within existing enterprise workflows. HubSpot competes through freemium-to-paid conversion tools that embed scoring for mid-market SaaS buyers. 6sense differentiates via intent-data layering that combines first-party CRM signals with third-party research consumption patterns.
Lead scoring software applies statistical models and machine learning algorithms to rank prospects by conversion probability, typically processing demographic fit, engagement velocity, and intent signal strength through scoring engines that output numeric grades or tiered labels. Cloud-based deployment leads the market due to faster implementation cycles and lower infrastructure overhead for revenue operations teams, while API integration represents the fastest-growing segment as enterprises demand real-time data flows between scoring engines and existing martech stacks. On-premises solutions retain share in financial services and defense-adjacent sectors where data residency requirements override flexibility preferences.
The US Federal Trade Commission scrutinizes opaque algorithmic scoring under Section 5 unfair-practice authority, while California's Consumer Privacy Act grants individuals rights to know how automated systems evaluate their data. ISO 27001 certification has become a baseline procurement filter for enterprise buyers evaluating vendor security postures. Stakeholders must monitor how emerging state privacy laws fragment compliance requirements across jurisdictions and determine whether to build adaptive consent frameworks or retreat to narrower geographic markets.
Market Dynamics
GDPR and the EU AI Act are forcing vendors to rebuild consent architectures and algorithmic transparency into scoring engines, transforming product roadmaps and procurement criteria across enterprise SaaS buyers.
Growth Catalysts
- Intent-data fusion:First-party CRM signals combined with third-party research consumption patterns enable precision targeting for B2B technology vendors.
- ISO 27001 certification:Enterprise procurement teams mandate baseline security postures, filtering vendor shortlists to certified providers.
- San Francisco metro cluster:Dense concentration of B2B SaaS headquarters generates concentrated demand for native scoring integrations.
Market Restraints
- Algorithmic opacity scrutiny:FTC Section 5 enforcement against unfair automated practices creates legal exposure for black-box scoring models.
- Cloud infrastructure concentration:Dependency on hyperscale providers concentrates operational risk for real-time scoring workloads.
- Third-party cookie deprecation:Browser privacy changes degrade behavioral signal quality for intent-based scoring layers.
Strategic Opportunities
- API-first deployment:Real-time data flows between scoring engines and martech stacks represent the fastest-growing integration segment.
- Financial services on-premises:Data residency requirements in banking and defense-adjacent sectors sustain demand for non-cloud solutions.
- California Consumer Privacy Act:Individual rights to automated decision explanation create premium market for transparent scoring architectures.
Industry Challenges
- MLOps talent scarcity:Revenue operations teams lack personnel to maintain predictive model performance across drift and retraining cycles.
- Legacy CRM migration friction:Enterprises face integration complexity when embedding scoring modules into decades-old database schemas.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lead Scoring Software Market |
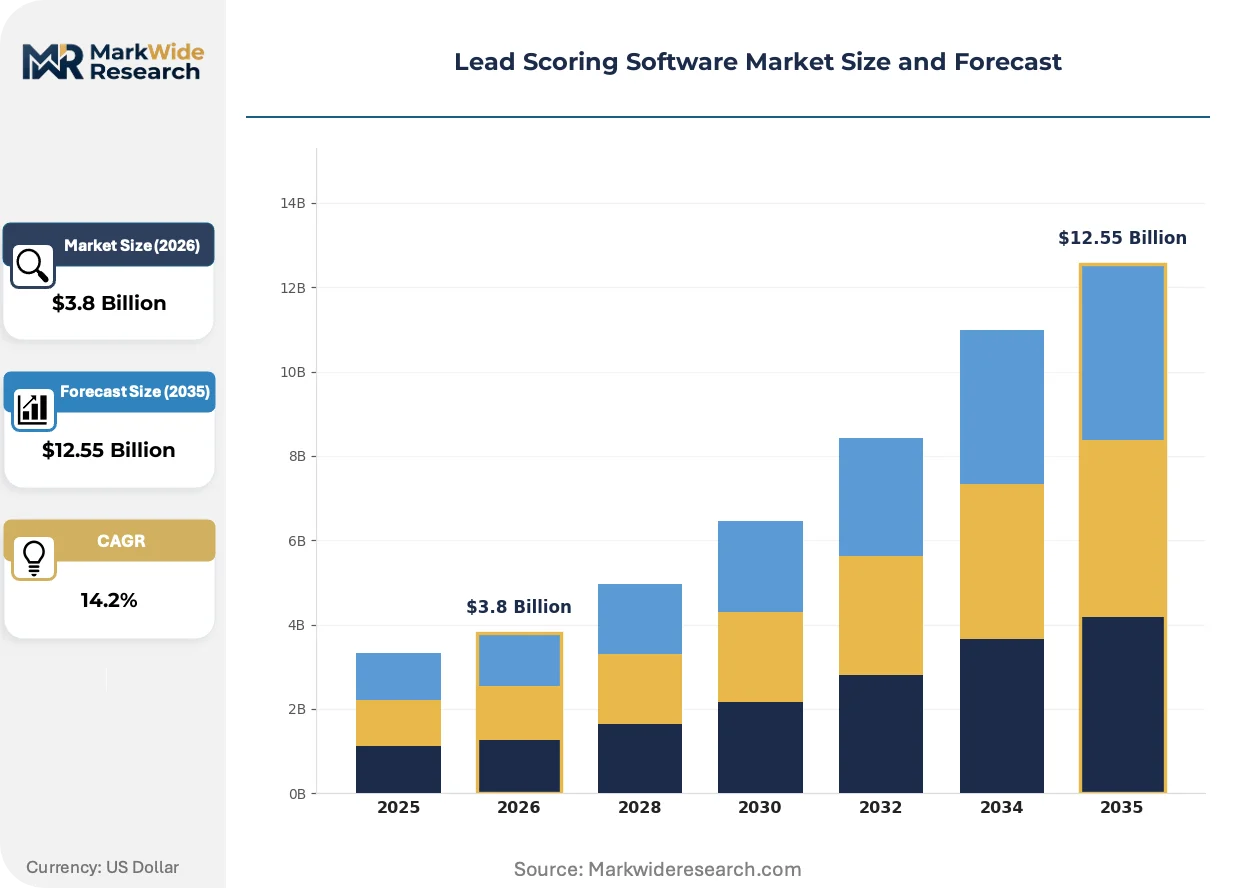
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Multi-Tenant Application: B2B Marketing, Sales Automation, Customer Relationship Management, Email Campaigns Target Audience: Small Enterprises, Medium Enterprises, Large Corporations, Startups Integration Level: API Integration, CRM Integration, Data Import, Custom Solutions |
| Companies Covered | HubSpot, Salesforce, Apollo, Clearbit, MadKudu, 6sense, Default, SalesMind AI, Pipedrive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lead Scoring Software Market Shifts & Advancements
Predictive scoring architectures are undergoing fundamental reconstruction as privacy regulations and buyer expectations converge, compressing vendor differentiation cycles and elevating transparency as a competitive weapon.
Generative AI is rewriting how scoring models synthesize unstructured engagement data. Revenue operations teams at mid-market SaaS vendors adopt natural language processing to extract buying signals from email threads and call transcripts. The technology is rewriting competitive positioning by collapsing the gap between intent detection and actionable outreach timing.
The EU AI Act's risk-tier classification system imposes documentation burdens on high-stakes automated decision systems. Vendors serving European enterprises must maintain technical files and human oversight protocols for scoring algorithms affecting credit or employment outcomes. Financial services procurement teams in Germany and France now prioritize providers with pre-built compliance mappings.
Enterprise buyers are compressing vendor evaluation cycles from annual RFPs to continuous scoring capability assessments. Mid-market technology companies replace single-vendor relationships with modular best-of-breed stacks. This pattern is most visible in Boston's enterprise software corridor, where revenue operations leaders pilot multiple scoring engines simultaneously before standardization.
Lead Scoring Software Market Segmentation
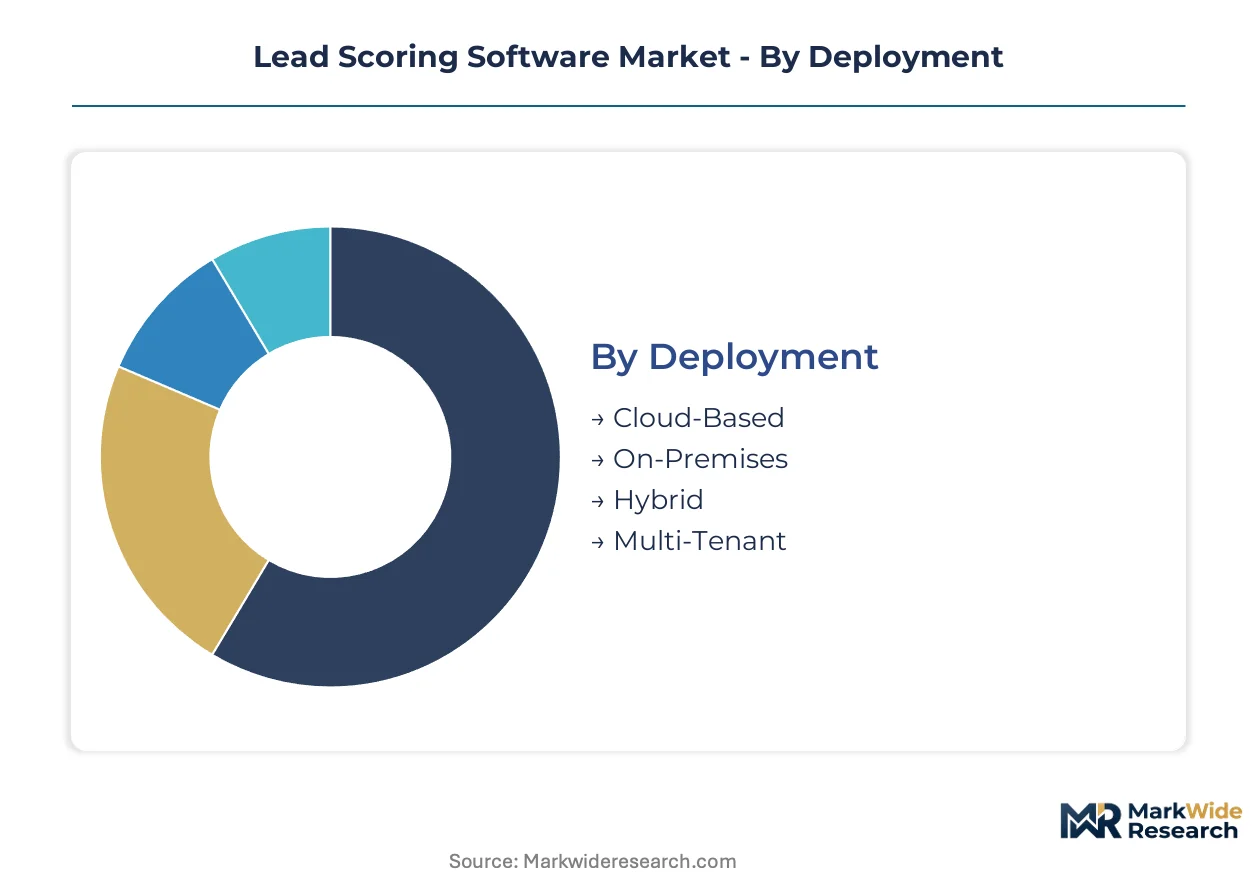
Lead scoring software buyers select deployment models and integration architectures based on data residency mandates, existing martech investments, and revenue operations maturity. Segmentation reveals how vendor capabilities align with organizational constraints across enterprise size and compliance exposure.
Deployment:
Enterprise procurement teams weight total cost of ownership against data sovereignty requirements when selecting infrastructure models.
- Cloud-Based:SaaS delivery eliminates server procurement and maintenance overhead for revenue operations teams. Demand concentrates among mid-market SaaS vendors in the San Francisco metro area seeking rapid implementation without capital expenditure.
- On-Premises:Self-hosted installations maintain physical data control within organizational firewalls. Financial services institutions in Frankfurt and defense contractors in Arlington prioritize this model to satisfy regulatory data residency mandates.
- Hybrid:Split architectures process sensitive scoring logic locally while leveraging cloud elasticity for compute-intensive model training. German automotive suppliers adopt this approach to balance GDPR compliance with AI performance requirements.
- Multi-Tenant:Shared infrastructure instances reduce per-customer operational costs for vendors serving high volumes of smaller accounts. Australian B2B marketing agencies favor this model for cost-efficient client portfolio management.
Cloud-Based leads on scale; API-forward Hybrid configurations gain share fastest among regulated European enterprises.
Application:
Functional deployment patterns reflect how deeply scoring engines embed within existing revenue workflows.
- B2B Marketing:Campaign orchestration platforms apply predictive grades to prioritize account-based marketing spend. Technology vendors in Boston's enterprise corridor integrate these capabilities with intent-data layers for precision targeting.
- Sales Automation:CRM-native scoring modules surface prospect priority within daily seller workflows. Salesforce's ecosystem dominance drives concentrated adoption among North American enterprise technology sellers.
- Customer Relationship Management:Unified customer data platforms incorporate scoring across post-sale expansion and retention motions. Japanese manufacturing exporters deploy these systems to identify cross-sell opportunities in distributor networks.
- Email Campaigns:Message personalization engines leverage engagement velocity signals to trigger sequence advancement. Mid-market SaaS providers in Toronto use this application to automate nurture path progression.
Sales Automation leads on current penetration; B2B Marketing shows the steepest expansion trajectory as account-based strategies mature.
Target Audience:
Organizational scale determines feature complexity requirements and pricing tolerance for scoring infrastructure.
- Small Enterprises:Simplified scoring templates with pre-built model configurations reduce technical barriers. Regional professional services firms in Manchester select these solutions for limited revenue operations staffing.
- Medium Enterprises:Configurable scoring engines balance customization depth with manageable implementation scope. Dutch logistics technology companies represent concentrated demand for this tier.
- Large Corporations:Enterprise-grade platforms support multi-region deployments with centralized governance. Swiss pharmaceutical multinationals mandate these capabilities for compliance across affiliate operations.
- Startups:Freemium-entry products enable scoring adoption before formal revenue operations function establishment. Venture-backed SaaS founders in Bangalore leverage these tools to demonstrate sales efficiency metrics to investors.
Large Corporations lead on absolute spending; Startups expand most quickly as seed-stage companies prioritize data-driven go-to-market validation.
Integration Level:
Technical architecture choices reflect enterprise demands for real-time data fluidity versus controlled batch processing.
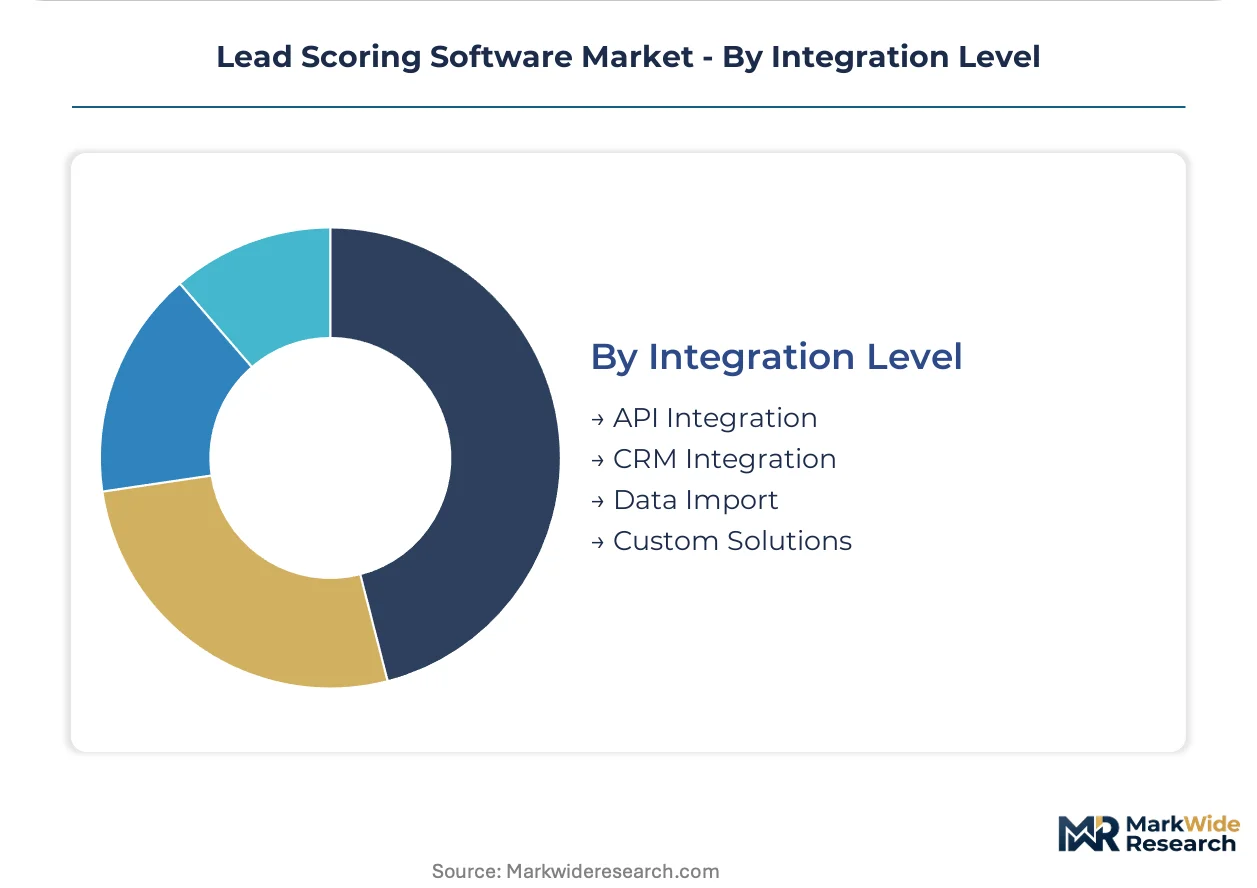
- API Integration:RESTful and GraphQL endpoints enable synchronous scoring updates across distributed martech stacks. Singaporean fintech platforms require sub-second latency for in-app lead qualification experiences.
- CRM Integration:Native connectors embed scoring outputs directly within Salesforce, HubSpot, or Microsoft Dynamics interfaces. This pattern dominates procurement criteria for US-based enterprise software buyers.
- Data Import:Scheduled batch uploads from spreadsheets or data warehouses serve organizations with legacy system constraints. Italian industrial equipment distributors rely on this method for quarterly list refreshes.
- Custom Solutions:Bespoke integration development addresses unique data schemas or proprietary internal systems. Israeli cybersecurity vendors commission these builds to connect scoring engines with classified threat intelligence databases.
CRM Integration leads on deployment volume; API Integration climbs the fastest as real-time personalization requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Revenue operations talent clusters in the San Francisco Bay Area, Boston, and London anchor enterprise software demand for predictive scoring infrastructure.
United States
Venture-backed SaaS vendors in San Francisco and Boston metro areas drive concentrated procurement of cloud-native scoring engines. The FTC applies Section 5 unfair-practice authority to scrutinize opaque algorithmic decision systems. Seattle's enterprise technology corridor hosts multiple vendors embedding real-time scoring into CRM workflows for mid-market buyers.
Germany
Automotive suppliers and industrial equipment manufacturers in Stuttgart and Munich demand hybrid deployment models balancing GDPR compliance with AI performance. The EU AI Act imposes documentation burdens and human oversight protocols on high-stakes automated scoring systems. Frankfurt's financial services sector sustains on-premises installation preferences for data residency compliance.
United Kingdom
London's fintech and B2B SaaS clusters prioritize API-first scoring integrations for real-time personalization. The Information Commissioner's Office enforces GDPR-derived transparency requirements for automated decision-making. Manchester's professional services firms adopt simplified scoring templates to compensate for limited revenue operations staffing.
India
Bangalore's venture-backed startup ecosystem leverages freemium scoring tools to demonstrate sales efficiency metrics to investors. The Digital Personal Data Protection Act establishes consent frameworks for behavioral signal processing. Hyderabad's enterprise IT services corridor generates demand for configurable scoring engines serving mid-market technology exporters.
Japan
Tokyo-based manufacturing exporters deploy CRM-integrated scoring to identify cross-sell opportunities in distributor networks. METI guidelines on AI governance influence procurement criteria for automated decision systems. Osaka's industrial automation sector sustains demand for on-premises solutions where data sovereignty concerns override cloud preferences.
Lead Scoring Software Market Competitive Landscape
Capital-heavy platform producers compete with asset-light specialized vendors across the scoring software landscape. The vendor base segments into three tiers: comprehensive CRM-native suites, standalone predictive analytics specialists, and API-first infrastructure providers. Strategic differentiation converges on M&A activity absorbing intent-data capabilities and partnership networks embedding scoring into adjacent revenue operations tools.
Within the CRM-native tier, Salesforce and HubSpot anchor enterprise and mid-market positioning respectively, while 6sense occupies a specialized position layering third-party intent signals with first-party behavioral data. These three exemplify divergent archetypes: platform incumbents leveraging workflow integration, freemium converters optimizing self-serve adoption, and data fusion specialists commanding premium positioning through signal enrichment.
| Leading Market Players |
|---|
| HubSpot |
| Salesforce |
| Apollo |
| Clearbit |
| MadKudu |
| 6sense |
| Default |
| SalesMind AI |
| Pipedrive |
| Others |
Supply & Pricing Matrix
Enterprise procurement teams' ISO 27001 certification mandates are compressing vendor shortlists to certified providers, forcing supply-side consolidation around compliance-ready infrastructure and elevating pricing power for security-validated platforms.
Pricing Analysis
Bundled CRM-native scoring modules command premium positioning against unbundled API-first infrastructure. Three-tier pricing structure across enterprise, mid-market, and startup tiers differentiates by integration depth and model customization scope. Pricing pressure stems from freemium conversion economics as venture-backed entrants subsidize customer acquisition. Small enterprises exhibit highest price sensitivity; large corporations prioritize compliance over cost.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Singapore anchor cloud infrastructure delivery for latency-sensitive scoring workloads. Compute resources draw from hyperscale providers in Virginia, Frankfurt, and Singapore data center clusters. Single-source vulnerability concentrates in NVIDIA GPU supply for model training acceleration. Distribution runs through direct vendor sales and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in lead scoring software rests on API-first infrastructure commoditizing compute costs while premium tiers capture value from compliance-validated deployments.
For Market Incumbents: Anchor platform positioning through native CRM workflow integration to defend against modular best-of-breed displacement. Invest in GDPR and EU AI Act pre-built compliance mappings to capture financial services procurement in Germany and France. Prioritize M&A absorption of intent-data specialists to maintain signal enrichment differentiation. For New Entrants and Emerging Players: Systems integrators and boutique revenue operations consultancies represent underexploited channel pathways into mid-market SaaS buyers. White-space concentrates in hybrid deployment configurations for regulated European automotive and industrial equipment manufacturers. Pursue vertical-specific scoring templates as the primary go-to-market wedge. For Investors and Strategic Acquirers: Asymmetric upside sits with API-first infrastructure providers serving real-time personalization requirements at Singaporean fintech platforms and London B2B SaaS clusters. Long-term viability favors vendors with adaptive consent architectures spanning fragmented US state privacy regimes. Monitor FTC Section 5 enforcement patterns as an inflection signal for transparency-premium pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Architecture Pre-Build | EU AI Act documentation protocols secure German automotive procurement decisions. |
| Intent-Data Specialist Acquisition | Third-party research consumption patterns deepen signal enrichment for B2B technology vendors. |
| API-First Platform Expansion | Sub-second latency scoring captures Singaporean fintech real-time qualification demand. |
| Hybrid Deployment Development | Split cloud-local architectures satisfy GDPR requirements for Stuttgart automotive suppliers. |
| Revenue Operations Talent Partnership | MLOps capability gaps at mid-market SaaS vendors create services attach opportunities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement captured perspectives from revenue operations leaders, CRM platform engineers, enterprise procurement officers, and compliance specialists at SaaS vendors. Secondary validation drew from SEC filings, hyperscaler infrastructure capex disclosures, EU regulatory documentation, and martech stack adoption surveys. Bottom-up deployment modeling and top-down market sizing triangulated volume estimates.
Segment-weighting applied deployment model, organization size, integration complexity, and regional regulatory intensity as core dimensions across the analysis window. CAGRs derived from fitted growth curves against historical adoption patterns and forward procurement intention surveys. Model inputs incorporated third-party cookie deprecation timelines, GDPR enforcement variance across national data protection authorities, and CRM migration friction coefficients.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act implementation rigor and US state privacy law fragmentation. Forecasts reflect documented assumptions about enterprise cloud migration velocity and intent-data signal quality evolution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Application Release Automation Market
Software & Services
Global Self-Service BI Market
Software & Services
Test Automation Market
Software & Services
Mobile Tracking Software Market
Software & Services
Pure Play Software Testing Market
Software & Services
API Testing Market
Software & Services
Auto Software Market
Software & Services
Financial Corporate Performance Management (FCPM) Software Market
Software & Services
Automotive Customization Software Market
Software & Services
Batch Management Software Market
Software & Services
Global OKR Software Market
Software & Services
Computer Software Market
Software & Services
Global Gym Software Market
Software & Services
In-Memory Data Grids Software Market
Software & Services
Human Resource Management Software Market
Software & Services
Identity Resolution Software Market