
 Spain Data Center Processor Market | 2026-2036
Spain Data Center Processor Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Data Center Processor Market Insights
Cloud computing is restructuring procurement patterns across Spanish data center operators. AMD leverages its EPYC architecture to compete in high-performance virtualization workloads. NVIDIA anchors AI training demand through GPU-dense deployments in Iberian hyperscale facilities. Intel Corporation sustains broad enterprise presence with x86-compatible server processors for on-premises legacy infrastructure.
Data center processors are semiconductor devices engineered to execute computational workloads within centralized server facilities, typically fabricated on advanced process nodes below seven nanometers for thermal efficiency and throughput density. Their primary purpose is to power enterprise applications ranging from transactional databases to neural network inference. GPU segments command premium positioning as AI operations expand, while CPU deployments retain volume leadership across conventional virtualization tasks. FPGA adoption concentrates in research institutions requiring reconfigurable logic for specialized data analytics pipelines.
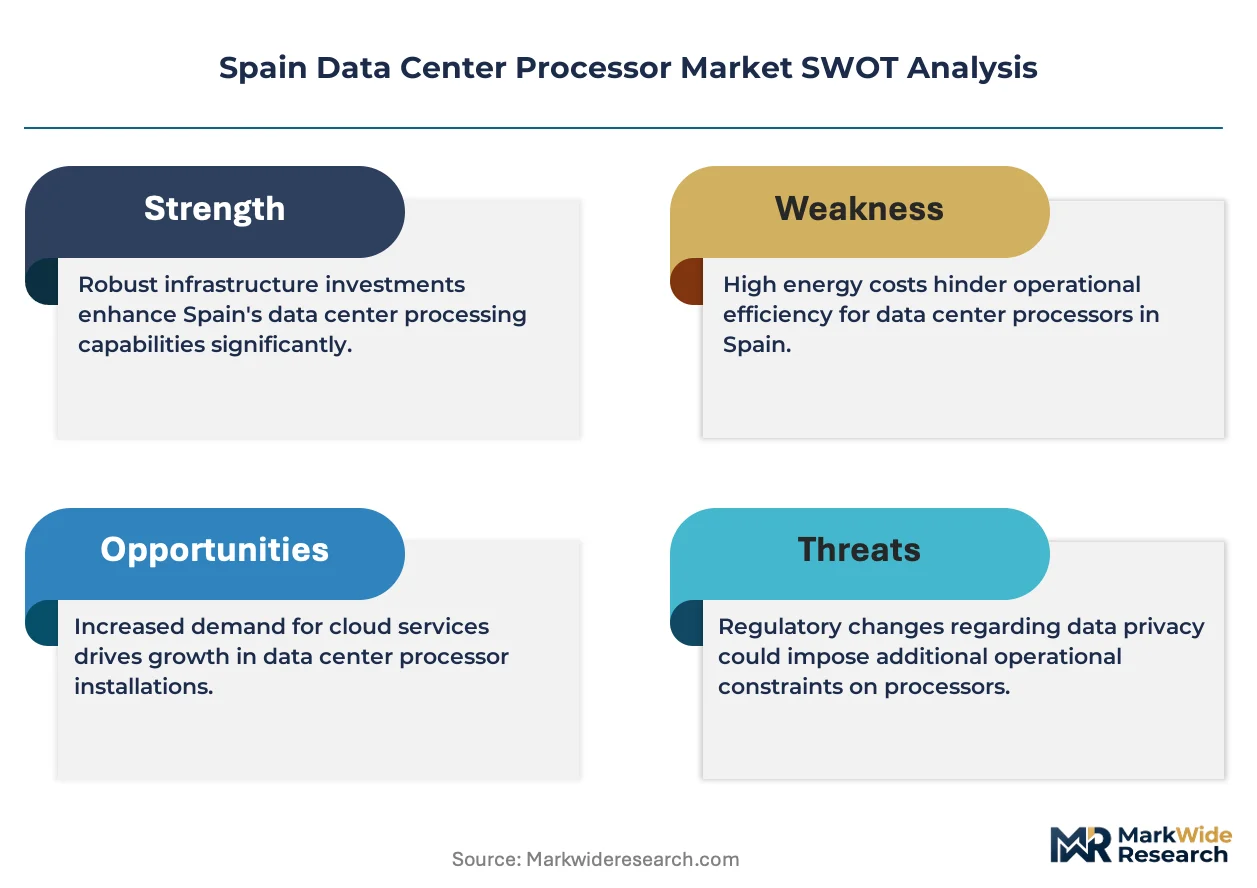
Spain's National Security Scheme and BIS-aligned standards shape certification requirements for processors handling sensitive government data. The country's central bank and data protection authority enforce localization mandates that influence chip procurement decisions for financial services deployments. Stakeholders must monitor how EU AI Act risk classifications alter hardware qualification pathways for automated decision-making workloads.
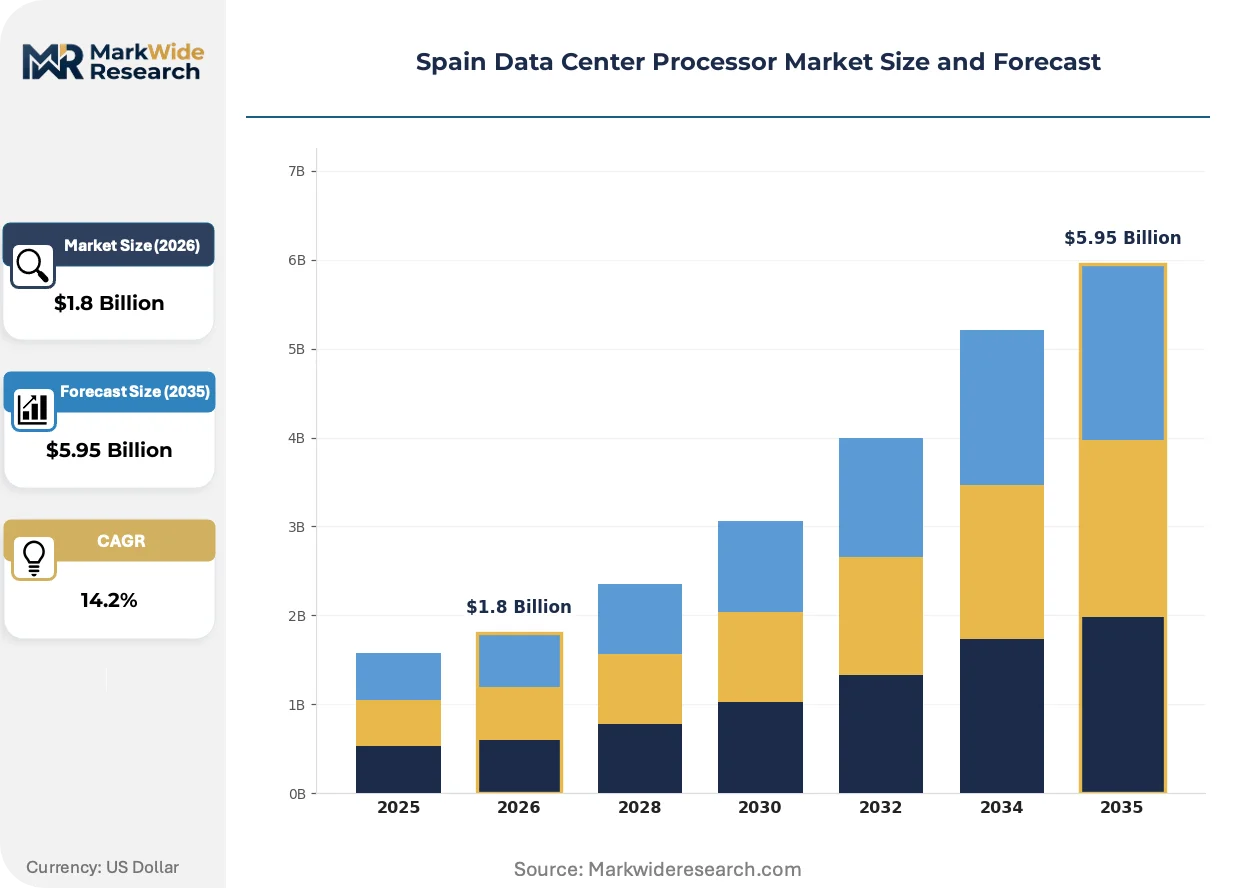
Market Dynamics
AI training workloads are redrawing procurement priorities across Spanish data center operators, compressing upgrade cycles and tilting capital allocation toward GPU-dense architectures. The National Security Scheme certification requirements simultaneously tighten data sovereignty compliance, forcing hardware qualification pathways that favor localized supply chain verification.
Growth Catalysts
- EU AI Act risk classifications:High-risk automated decision-making mandates are accelerating hardware qualification investments among financial services operators in Madrid and Barcelona.
- Hyperscale facility clustering:Cloud service providers concentrate procurement near renewable energy corridors, particularly in the Madrid digital hub where wind and solar infrastructure reduces operational carbon intensity.
- Neural network inference expansion:Edge AI deployments across Catalonia's manufacturing belt are pulling specialized accelerator chips into regional colocation facilities.
Market Restraints
- Advanced node supply concentration:Fabrication capacity below five nanometers concentrates in East Asian foundries, exposing Spanish deployments to geopolitical transit risks and allocation quotas.
- BIS-aligned export controls:Dual-use technology restrictions complicate procurement of certain high-bandwidth memory controllers for AI training clusters.
- Power density thermal limits:Legacy Madrid facilities face physical retrofit constraints when accommodating 700-watt GPU racks, capping immediate upgrade potential.
Strategic Opportunities
- Andalusian greenfield development:Seville's emerging data center corridor offers uncooled power capacity and streamlined municipal permitting for hyperscale builds.
- FPGA-NPU convergence:Reconfigurable logic paired with neural processing units creates white space for research institutions requiring workload-specific acceleration.
- CSRD disclosure mandates:Corporate sustainability reporting requirements position low-carbon processor procurement as a competitive differentiator for enterprise colocation providers.
Industry Challenges
- Chip-level security certification:Common Criteria evaluation timelines for processors handling classified government data extend 18-24 months, compressing product refresh windows.
- Legacy x86 integration friction:Enterprise migrations to ARM-based cloud-native architectures face application refactoring costs and compatibility validation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Data Center Processor Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CPU, GPU, FPGA, ASIC Operations: Cloud Computing, Virtualization, Data Analytics, AI End User: Enterprise, Government, Research Institutions, Service Providers Deployment Model: On-Premises, Hybrid Cloud, Public Cloud, Managed Services |
| Companies Covered | Intel Corporation, AMD, NVIDIA, Arm Holdings, Qualcomm, IBM, Fujitsu Limited, Huawei Technologies, Ericsson, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Data Center Processor Market Trends and Innovations
Computational specialization is fragmenting the homogeneous server processor market into workload-optimized silicon categories. Spanish operators now segment procurement across training, inference, and conventional virtualization rather than standardizing on single architectures.
Chiplet-based modular designs are automating the disaggregation of memory controllers, I/O die, and compute cores into mix-and-match configurations. Iberian hyperscale facilities adopt these architectures to tailor power-performance ratios for specific AI pipelines. The approach is automating procurement flexibility while compressing time-to-deployment for custom silicon configurations.
Spain's National Security Scheme and BIS-aligned standards are tightening supply chain provenance documentation for processors in critical infrastructure. Hardware vendors must now certify manufacturing origin and firmware integrity through accredited evaluation facilities. Financial services deployments in Madrid face the steepest compliance burdens, with several operators establishing dedicated security engineering functions.
Leasing models for AI training clusters are displacing capital purchase arrangements among mid-size Spanish enterprises. Colocation providers bundle bare-metal GPU access with power and cooling, converting fixed infrastructure costs to operational expenditure. This shift concentrates most visibly among Barcelona-based fintech operators seeking burst capacity without facility ownership.
Spain Data Center Processor Market Segmentation
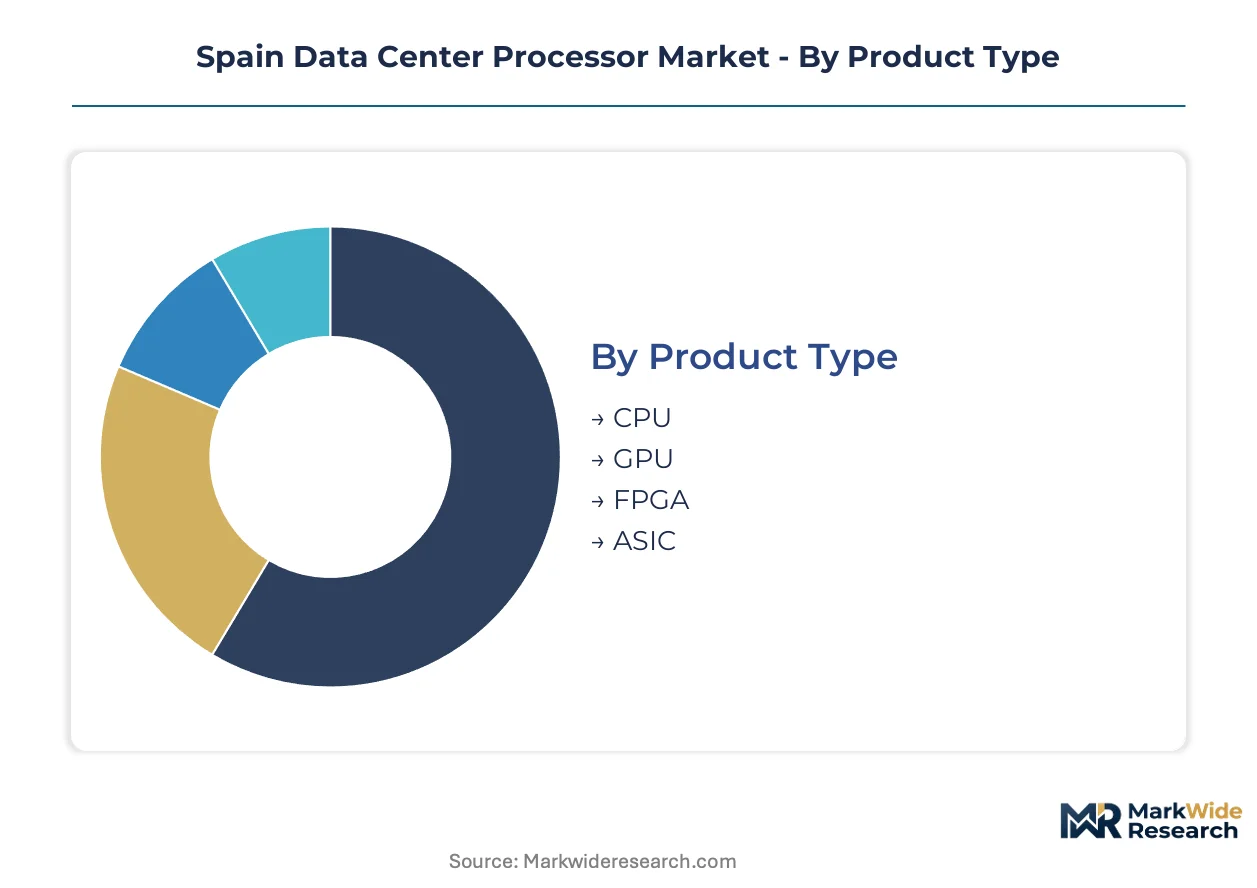
Processor procurement patterns in Spain diverge sharply across workload types, with capital allocation shifting from general-purpose compute toward specialized silicon for AI training. Segmentation reveals how hyperscale operators, government compliance mandates, and research funding priorities carve distinct demand pools across the Iberian data center landscape.
Product Type:
Capital intensity escalates dramatically from programmable general-purpose chips toward fixed-function AI accelerators, with foundry costs and thermal infrastructure driving deployment economics.
- CPU:x86 and ARM-based central processors handle transactional databases and legacy enterprise applications across Madrid's financial services clusters. Demand concentrates in hybrid cloud deployments where compatibility requirements slow migration timelines.
- GPU:NVIDIA and AMD graphics processors dominate neural network training workloads with dense floating-point throughput. Barcelona hyperscale facilities prioritize these chips for generative AI model development, constrained by 700-watt rack power limits in older Madrid buildings.
- FPGA:Reconfigurable logic from Xilinx and Intel adapts to protocol-specific data analytics in Catalan research networks.
- ASIC:Google TPUs and custom inference accelerators reduce per-query energy for deployed machine learning services.
CPU absorbs the bulk of installed capacity; GPU is expanding most quickly.
Operations:
Application type determines silicon selection, with latency-tolerant batch processing favoring different architectures than real-time inference.
- Cloud Computing:Multi-tenant virtualization demands high core-count processors with robust memory bandwidth. Madrid's digital hub corridor concentrates procurement for public cloud regions serving Iberian enterprise customers.
- Virtualization:Container orchestration and legacy VM consolidation drive EPYC and Xeon deployments in enterprise colocation facilities. Cost-sensitive operators in Valencia favor refurbished server fleets for this workload tier.
- Data Analytics:Columnar database acceleration pulls high-memory configurations into banking and telecommunications deployments.
- AI:Training clusters require GPU-dense racks with liquid cooling, while inference spreads across edge locations in manufacturing zones.
Virtualization retains the largest installed base; AI commands the steepest expansion trajectory.
End User:
Procurement authority and compliance burden vary sharply across buyer categories, with government mandates adding 18-24 month qualification timelines.
- Enterprise:Banking and telecommunications operators in Madrid and Barcelona drive volume procurement for private cloud infrastructure. Banco de España localization requirements constrain supplier selection for core banking systems.
- Government:National Security Scheme certification mandates firmware provenance documentation for processors handling classified data. Defense and intelligence deployments concentrate in restricted facilities with air-gapped supply chains.
- Research Institutions:Barcelona Supercomputing Center and university clusters prioritize peak theoretical performance over energy efficiency for competitive grant applications.
- Service Providers:Colocation and bare-metal hosting operators aggregate fragmented enterprise demand into volume procurement contracts.
Enterprise accounts dominate revenue contribution; government represents the most restrictive qualification pathway.
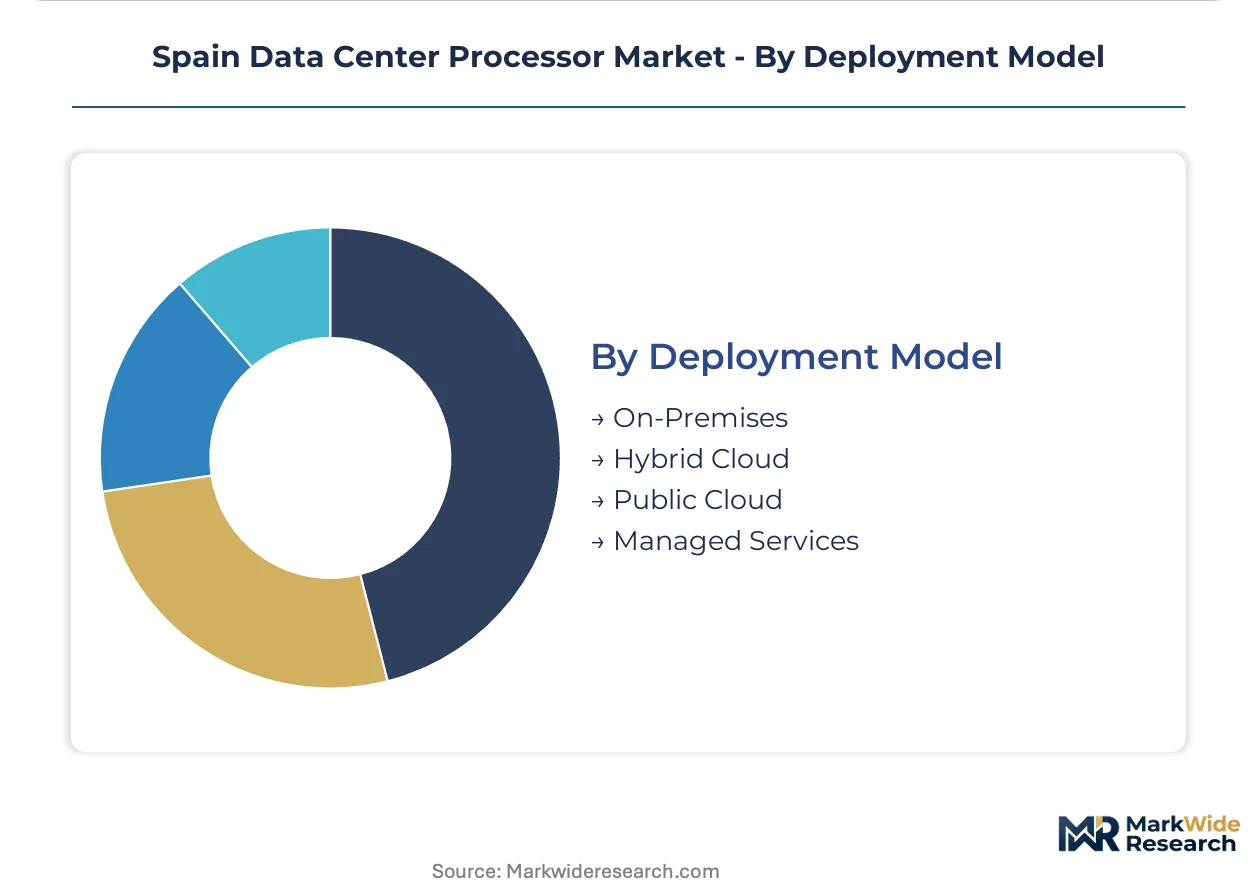
Deployment Model:
Infrastructure ownership structure determines refresh cadence and silicon flexibility, with capital-light models accelerating technology adoption.
- On-Premises:Legacy enterprise data centers in Madrid's financial district retain x86 standardization due to application refactoring costs. Five-to-seven-year depreciation cycles delay AI accelerator adoption.
- Hybrid Cloud:Burst capacity requirements split workloads between owned infrastructure and public cloud regions. Iberian manufacturers in Catalonia use this model for seasonal demand spikes.
- Public Cloud:AWS, Azure, and GCP regions in Spain procure at hyperscale volume with direct foundry relationships. Renewable energy requirements concentrate new builds near wind corridors in Aragon.
- Managed Services:Outsourced infrastructure operators assume hardware refresh risk for mid-size enterprises seeking operational expenditure conversion.
Public Cloud captures the fastest-growing infrastructure investment; On-Premises retains the largest depreciated asset base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain produces negligible semiconductor fabrication capacity yet consumes advanced processors at accelerating rates through hyperscale cloud deployments and enterprise data center expansion. This production-consumption asymmetry forces Spanish operators to navigate East Asian foundry allocation quotas and EU import compliance frameworks. Regional demand clusters concentrate where renewable energy infrastructure supports dense compute loads.
Madrid
Spain's capital anchors the Iberian digital infrastructure corridor with the highest concentration of hyperscale facilities and financial services data centers. The National Security Scheme mandates firmware provenance documentation for processors handling classified government workloads, extending hardware qualification timelines. Madrid's digital hub clusters near wind and solar generation assets in the surrounding region, reducing carbon intensity for GPU-dense AI training deployments.
Catalonia
Barcelona drives GPU procurement for generative AI model development through cloud region expansions by major service providers. The Catalan government promotes advanced digital infrastructure through regional innovation funding aligned with EU digital sovereignty objectives. Edge AI deployments across the manufacturing belt in Girona and Tarragona pull specialized inference accelerators into regional colocation facilities serving industrial automation workloads.
Basque Country
Bilbao and San Sebastián host research-intensive computing deployments requiring FPGA-based reconfigurable logic for specialized analytics pipelines. The Basque Science and Technology Network funds high-performance computing infrastructure with stringent energy efficiency requirements. Local supercomputing centers prioritize peak theoretical performance configurations for competitive European grant applications in materials science and climate modeling.
Andalusia
Seville's emerging data center corridor offers uncooled power capacity and streamlined municipal permitting that attracts hyperscale greenfield investments. The Junta de Andalucía administers regional incentives for renewable-powered digital infrastructure under Spain's Recovery and Resilience Plan. New facilities near the Guadalquivir Valley position to serve burst capacity demand from North African connectivity routes and submarine cable landings.
Valencia
The port city's logistics and manufacturing base sustains demand for cost-optimized server processors in enterprise colocation environments. Valencia's regional government promotes digital transformation subsidies that accelerate refresh cycles among mid-size enterprises. Refurbished server fleets dominate procurement patterns here, with operators prioritizing x86 compatibility over leading-edge silicon for conventional virtualization workloads.
Spain Data Center Processor Market Competitive Landscape
Top-tier vendors anchor premium-tier positioning through direct foundry relationships and full-stack AI acceleration platforms, while second-tier specialists occupy reconfigurable logic and ARM-based efficiency segments. The vendor base stratifies across three tiers: integrated device manufacturers with captive fabrication, fabless semiconductor designers reliant on contract foundries, and intellectual property licensors enabling custom silicon development. Strategic archetypes include training-focused GPU specialists, inference-optimized efficiency players, and legacy x86 compatibility providers. Competitive dynamics center on chiplet architecture licensing partnerships and sovereign cloud certification pre-qualification programs.
Within the integrated device manufacturing tier, Intel Corporation anchors x86-compatible server processor supply for Spanish enterprise on-premises deployments. NVIDIA occupies the training acceleration vector through GPU-dense architectures deployed across Iberian hyperscale facilities. AMD represents the multi-architecture challenger position with EPYC-based virtualization workloads and expanding AI inference presence. These three entities exemplify how vendor selection in Spain increasingly splits across workload-specific procurement rather than standardized platform commitments.
| Leading Market Players |
|---|
| Intel Corporation |
| AMD |
| NVIDIA |
| Arm Holdings |
| Qualcomm |
| IBM |
| Fujitsu Limited |
| Huawei Technologies |
| Ericsson |
| Others |
Pricing and Supply Chain Analysis
GPU-dense AI training procurement from Iberian hyperscale operators is forcing foundry allocation negotiations that compress margins on advanced node silicon while elevating spot-market premiums for high-bandwidth memory controllers.
Pricing Analysis
Short lead-time premiums dominate procurement negotiations as Spanish operators compete for constrained five-nanometer foundry slots against global AI cluster demand. Three-tier pricing structure across premium certified, standard qualified, and economy refurbished tiers reflects National Security Scheme compliance burdens and volume scale differentials. Cost compression in legacy x86 CPU tiers is intensifying because refurbished server fleets from Valencia operators flood secondary channels. Mid-size enterprises in managed services arrangements prove most price-sensitive; government classified workloads show least sensitivity due to 18-24 month qualification lock-in.
Supply Chain Analysis
Photoresist supply rests on Japanese specialty chemical producers Shin-Etsu and JSR, while extreme-ultraviolet lithography equipment draws exclusively from ASML's Dutch manufacturing. Silicon wafer supply concentrates in Japan's Shin-Etsu and Sumco alongside Germany's Siltronic. CoWoS packaging capacity anchors in Taiwan's TSMC facilities. Single-source vulnerability around EUV scanner maintenance contracts exposes Spanish deployments to extended downtime risk. Distribution runs through authorized distributors with direct foundry allocation rather than spot commodity markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's data center processor market sits in an architecture-transition phase as GPU-dense AI training clusters displace homogeneous x86 virtualization standardization.
For Market Incumbents: Extend firmware provenance documentation capabilities to compress National Security Scheme evaluation timelines that currently stretch 18-24 months. Secure direct foundry allocation agreements for five-nanometer capacity before East Asian competitors lock multi-year supply. ARM-based cloud-native entrants threaten x86 legacy lock-in among Barcelona fintech operators. For New Entrants and Emerging Players: Capture Andalusian greenfield hyperscale procurement as Seville's uncooled power capacity attracts AWS and Azure expansion bids. Target FPGA-NPU convergence segments in Basque Country research networks where reconfigurable logic demand outpaces incumbent supply. Lead with bare-metal GPU leasing models that convert capital expenditure to operational expenditure for mid-size Catalan manufacturers. For Investors and Strategic Acquirers: Re-rating potential sits with sovereign-cloud-certified chip distributors given EU AI Act risk classification mandates that accelerate hardware qualification investments. Long-term viability favors specialists with Common Criteria evaluation pre-qualification and direct TSMC allocation relationships. Watch hyperscale capex guidance revisions as the primary inflection indicator for foundry allocation tightness.| Strategic Initiative | Industry Significance |
|---|---|
| Chiplet Architecture Licensing | Enables Iberian hyperscale facilities to customize power-performance ratios for specific AI training pipelines. |
| National Security Scheme Pre-Certification | Compresses 18-24 month hardware qualification timelines for processors handling classified government data. |
| Direct Foundry Allocation Agreements | Secures five-nanometer capacity ahead of East Asian competitors in constrained advanced node markets. |
| Bare-Metal GPU Leasing Models | Converts fixed infrastructure costs to operational expenditure for Barcelona fintech burst capacity demand. |
| Andalusian Greenfield Development | Positions uncooled power capacity near Guadalquivir Valley submarine cable landings for North African connectivity. |
Research Methodology
Independent corroboration across hyperscale facility operators, semiconductor distributor procurement leads, and data center engineering directors underwrites the qualitative findings. Primary interviews with cloud region expansion managers, colocation provider CTOs, and National Security Scheme certification auditors combined with secondary validation from SEC hyperscaler capex disclosures, EU AI Act regulatory filings, and Banco de España localization mandates. Bottom-up installation base surveys and top-down foundry allocation estimates triangulate market sizing.
Rate-of-change decomposition separates volume growth from value migration across the analysis window. Segmentation dimensions modeled include processor architecture type, workload application, end-user category, and deployment ownership structure. CAGRs derive from fitted growth curves against hyperscale facility commissioning timelines and enterprise refresh cycle compression. Forecast inputs incorporate renewable energy corridor development pace and EU chip sovereignty funding disbursement patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to East Asian foundry allocation quotas and BIS-aligned export control expansion. Forecasts reflect documented assumptions around hyperscale capex continuity and National Security Scheme certification timeline stability. Geopolitical transit disruption and advanced node supply concentration warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Europe 8- Bit Microcontroller Market
Chipset and Processors
Automotive Image Signal Processor Market
Chipset and Processors
Automotive Chip Market
Chipset and Processors
Self-Learning Neuromorphic Chip Market
Chipset and Processors
Japan Data Center Processor Market
Chipset and Processors
Artificial Intelligence (AI) Chipsets Market
Chipset and Processors
Battery Monitoring IC Market
Chipset and Processors
G Fast Chipset Market
Chipset and Processors
Global Deep Learning Chipset Market
Chipset and Processors
Automotive Battery Management System (BMS) Chip Market
Chipset and Processors
Global Merchant Embedded Computing Market
Chipset and Processors
Deep Learning Chip Market
Chipset and Processors
Power Over Ethernet (Poe) Chipsets Market
Chipset and Processors
Microserver Market
Chipset and Processors
VR Gaming Hardware Chipsets Market
Chipset and Processors
Global Digital Light Processing Chipset Market