
 China Data Center Processor Market | 2026-2036
China Data Center Processor Market Size, Share, and Industry Trends Forecast 2026-2036
China Data Center Processor Market Insights
Hyperscaler procurement consolidation is restructuring supply relationships across China's data center ecosystem. NVIDIA Corporation leverages its CUDA software moat to sustain pricing power for AI training workloads. Hygon anchors domestic x86 alternatives through licensed architecture production. Intel Corporation competes by extending its ecosystem partnerships with local server OEMs.
Data center processors are integrated circuits designed to execute computational workloads in centralized server environments, typically fabricated on advanced nodes with TDP ratings spanning 75W to 500W and optimized for parallel thread execution or vector operations. CPU and GPU categories dominate current shipment volumes, with ASIC segments recording the fastest trajectory as custom AI accelerators displace general-purpose silicon in training clusters. Liquid cooling solutions command premium positioning as power density thresholds exceed air-cooled limits in high-compute deployments.
MIIT sets domestic content benchmarks for government and critical infrastructure procurement, while GB standards define electromagnetic compatibility and energy efficiency thresholds for data center equipment. NMPA-aligned data localization requirements shape processor sourcing decisions for healthcare and financial cloud deployments. Stakeholders must monitor foundry capacity allocation between domestic and foreign design houses as geopolitical licensing shifts alter supply security calculations.
Market Dynamics
MIIT's domestic semiconductor substitution mandates are forcing a bifurcation in procurement channels, splitting hyperscaler demand between licensed foreign architecture and indigenous instruction-set development.
Growth Catalysts
- AI Training Cluster Expansion:Cloud service providers are commissioning purpose-built silicon for large language model workloads, pulling accelerator demand ahead of general-purpose server refresh cycles.
- MIIT Localization Mandates:Government procurement quotas for critical infrastructure now require verified domestic content thresholds, redirecting public sector spending toward local foundry output.
- Greater Bay Area Hub Concentration:Shenzhen and Guangzhou data center buildouts are creating demand density that justifies dedicated supply chain investments from processor vendors.
Market Restraints
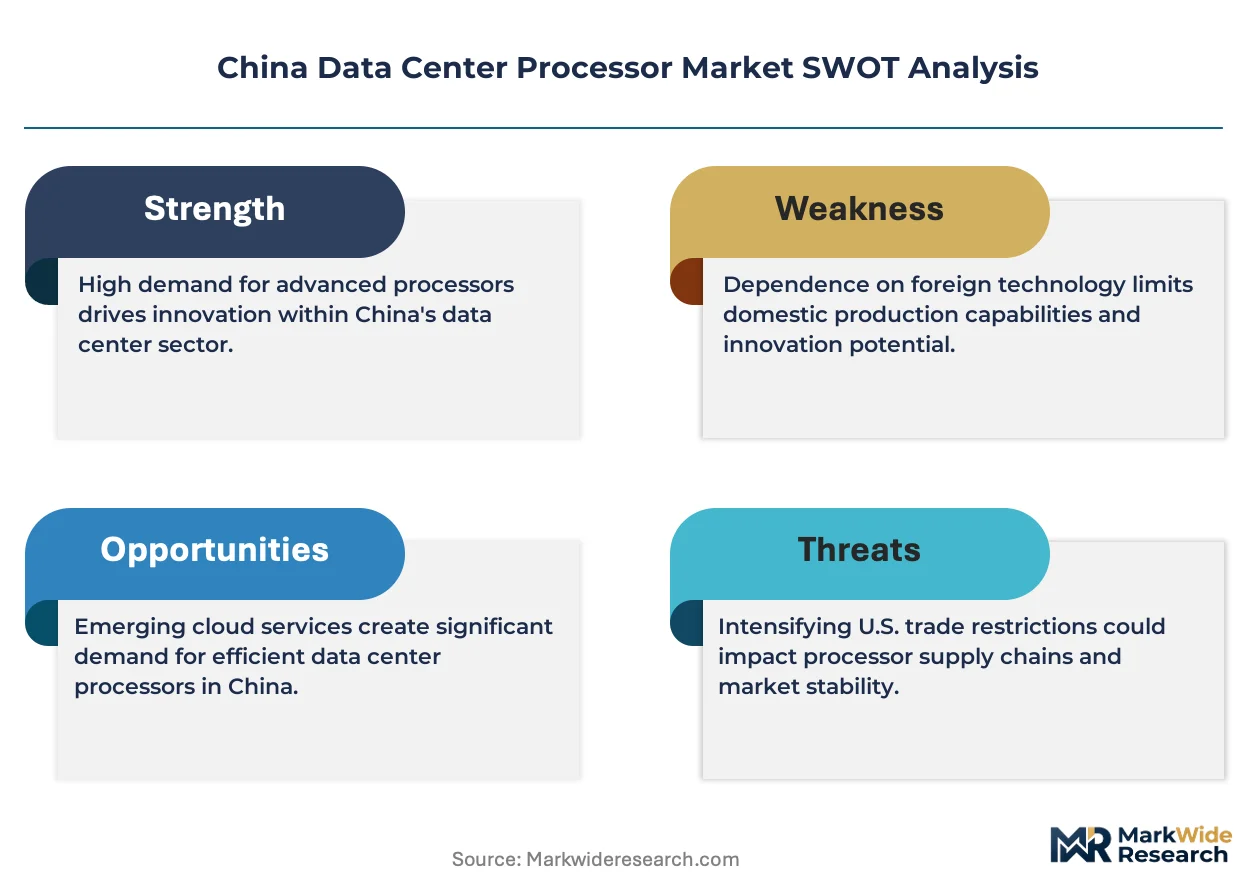
- Advanced Node Access Constraints:Export licensing restrictions on sub-7nm fabrication equipment limit domestic foundries to mature process nodes for high-performance designs.
- CoWoS Packaging Bottleneck:TSMC's chip-on-wafer-on-substrate capacity concentration in Taiwan creates single-point-of-failure risk for AI accelerator shipments.
- HBM Supply Concentration:SK Hynix and Samsung control over 95 percent of high-bandwidth memory output, constraining domestic accelerator yield rates.
Strategic Opportunities
- Western China Expansion:Chengdu and Chongqing data center zones offer land and power cost arbitrage for training clusters with relaxed latency requirements.
- GB 40879 Compliance Services:Energy efficiency certification consulting represents a service attach opportunity as operators face mandatory PUE disclosure requirements.
- Chiplet Interconnect Standards:Open die-to-die protocols enable modular accelerator designs that bypass monolithic reticle limits on available process nodes.
Industry Challenges
- EDA Tool Licensing Complexity:Restricted access to advanced simulation and verification software extends domestic processor design cycles by 8-14 months.
- Liquid Cooling Retrofit Integration:Existing air-cooled facilities require structural reinforcement and plumbing reconfiguration to support 500W+ TDP deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Data Center Processor Market |
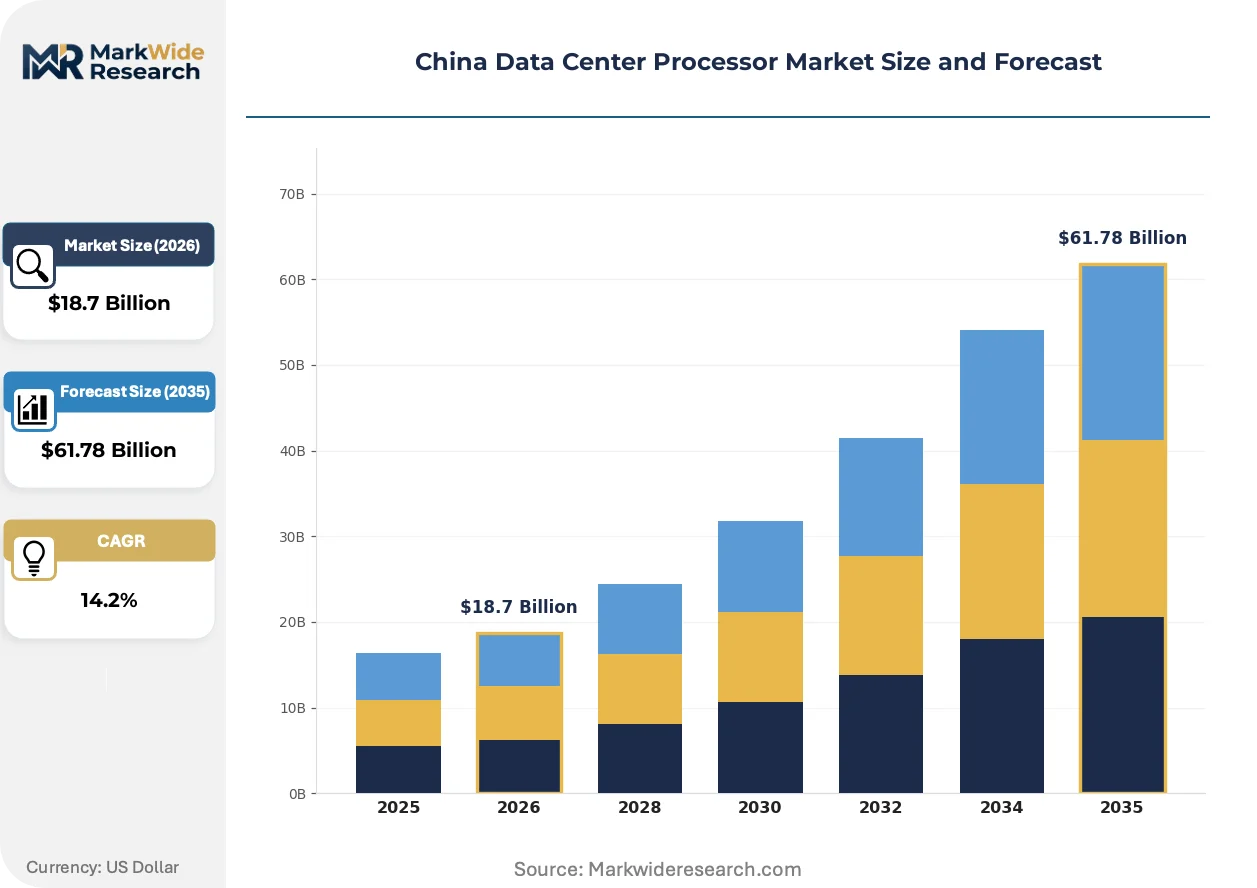
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Processor Type: CPU, GPU, FPGA, ASIC Power Rating: Low Power, Mid Power, High Power, Ultra High Power Form Factor: Rack-Optimized, Blade, Modular, Custom Cooling Solution: Air Cooling, Liquid Cooling, Immersion Cooling, Hybrid Cooling |
| Companies Covered | Intel Corporation, NVIDIA Corporation, Advanced Micro Devices Inc., Ampere Computing, Arm Ltd., Hygon, Xilinx Inc., Achronix Semiconductor Corporation, Kunlun Chip, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Data Center Processor Market Trends and Innovations
Processor architectures are fragmenting along workload-specific lines as general-purpose silicon yields to domain-optimized designs for AI inference and training.
Chiplet-based packaging is decentralizing monolithic die manufacturing by partitioning compute, memory, and I/O functions into separately fabricated tiles. Hyperscalers including ByteDance and Alibaba Cloud are qualifying multi-vendor chiplet assemblies for internal workloads. This modularity is decentralizing supply risk across multiple foundry relationships rather than concentrating it in single-die yield rates.
MIIT's updated GB standards for data center energy efficiency now mandate real-time power usage effectiveness monitoring and annual disclosure for facilities exceeding 3,000 rack positions. Operators in Beijing-Tianjin-Hebei must demonstrate PUE below 1.3 for new construction permits. Financial services firms are responding by procuring processors with workload-aware frequency scaling to meet disclosure thresholds without infrastructure replacement.
Cloud service providers are unbundling bare-metal accelerator access from managed platform services, allowing AI startups to lease GPU clusters without committing to full instance contracts. This consumption model is displacing three-year reserved instance purchasing in the Yangtze River Delta startup ecosystem. Healthcare and autonomous driving developers in Shanghai and Hangzhou represent the earliest adopters of this fractional capacity model.
China Data Center Processor Market Segmentation
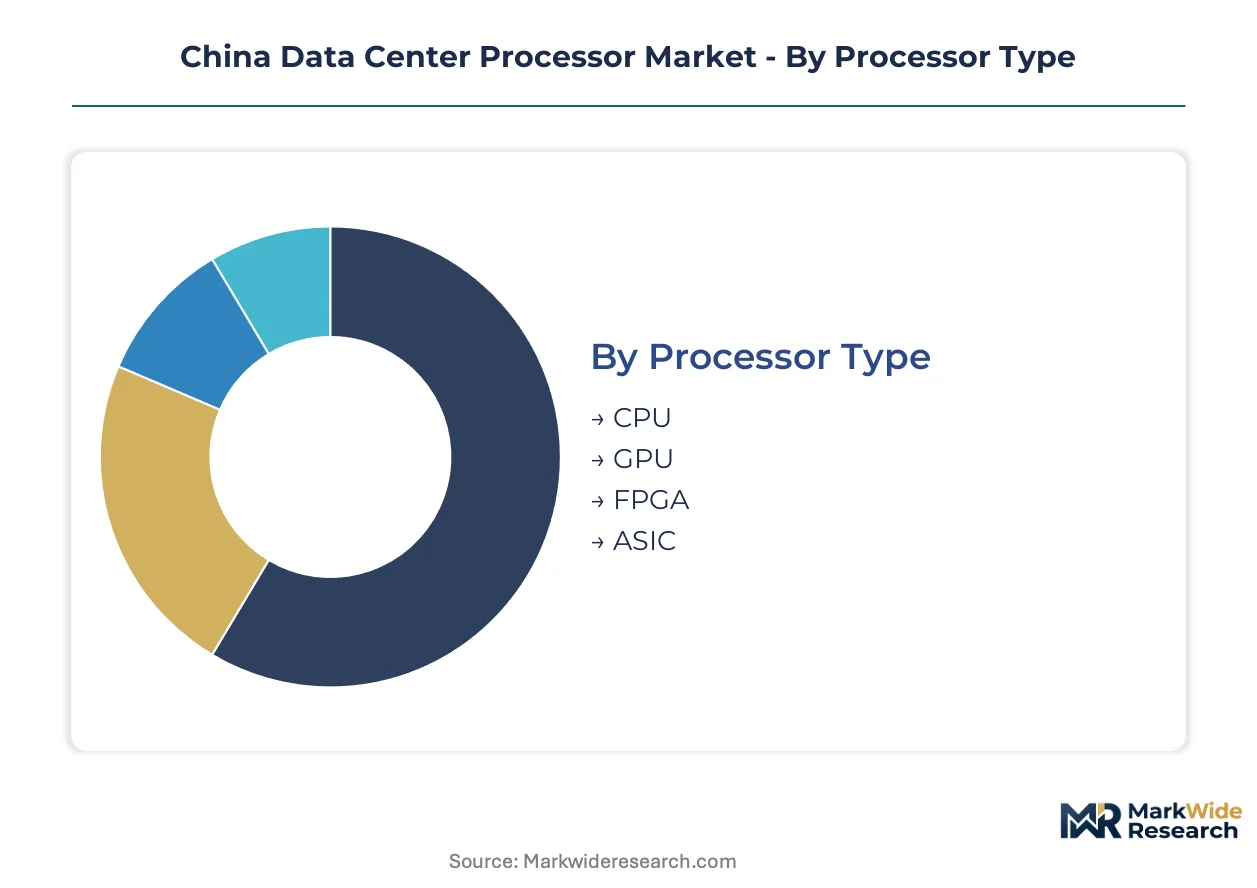
Processor segmentation in China reveals divergent sourcing strategies across workload types and infrastructure maturity levels. Procurement decisions increasingly hinge on power density thresholds and localization compliance rather than raw compute benchmarks alone.
Processor Type:
Volume shipments concentrate in general-purpose silicon, while premium pricing accrues to specialized accelerators for AI training clusters.
- CPU:x86 and ARM-based designs handle virtualization, database, and general cloud workloads across Beijing-Tianjin-Hebei facilities. MIIT procurement quotas favor domestic x86 licensing arrangements for government cloud deployments.
- GPU:Parallel vector architectures dominate AI training and inference in Yangtze River Delta hyperscale facilities. CUDA software ecosystems sustain NVIDIA's position despite export licensing restrictions on flagship accelerators.
- FPGA:Reconfigurable logic serves low-latency financial trading and network function virtualization in Shanghai and Shenzhen exchanges.
- ASIC:Domain-specific accelerators from ByteDance and Alibaba Cloud displace general-purpose silicon for recommendation engine and search indexing workloads.
Today's leader: GPU. Tomorrow's challenger: ASIC.
Power Rating:
Facility infrastructure maturity determines feasible thermal envelopes, splitting procurement between retrofit-constrained and greenfield-optimized deployments.
- Low Power:75W to 150W TDP processors serve edge aggregation nodes and legacy facility retrofits in tier-2 cities. Air-cooled deployments in Chengdu and Chongqing favor this bracket to avoid structural reinforcement costs.
- Mid Power:150W to 300W designs balance performance-per-watt for general-purpose cloud instances. Alibaba Cloud and Tencent Cloud standardize here for mainstream compute offerings.
- High Power:300W to 450W accelerators require direct-to-chip liquid cooling in Greater Bay Area training clusters. Baidu's Kunlun chips and Huawei's Ascend 910 compete in this envelope.
- Ultra High Power:450W-plus TDP processors demand immersion or two-phase cooling systems available only in purpose-built facilities. Supply concentrates in TSMC CoWoS-packaged AI accelerators for frontier model training.
Mid Power captures current volume. High Power commands expanding share.
Form Factor:
Deployment density targets and serviceability requirements shape chassis selection across state-owned enterprise and hyperscaler procurement channels.
- Rack-Optimized:Standard 19-inch configurations serve enterprise private clouds and government data centers with three-to-five-year refresh cycles. MIIT certification requirements favor this form factor for audit traceability.
- Blade:High-density enclosures consolidate compute for financial services in Shanghai Lujiazui and Beijing Financial Street facilities. Hot-swappable modules minimize downtime for trading platform maintenance windows.
- Modular:Disaggregated server architectures separate compute, memory, and storage into independently upgradeable subsystems. ByteDance deploys these for TikTok recommendation engine scaling.
- Custom:Bespoke mechanical designs accommodate proprietary accelerator form factors from domestic AI chip vendors. Supply chain fragmentation complicates spare parts logistics for these configurations.
Rack-Optimized dominates procurement volume. Modular designs gain traction fastest.
Cooling Solution:
GB 40879 PUE mandates and power density trajectories are forcing infrastructure decisions that lock in thermal management approaches for decade-long facility lifecycles.
- Air Cooling:Conventional raised-floor designs persist in legacy facilities and low-density enterprise deployments. Beijing-Tianjin-Hebei operators face permit denials for new air-cooled construction exceeding 1.3 PUE targets.
- Liquid Cooling:Direct-to-chip cold plates handle 300W-plus processors in Yangtze River Delta AI training facilities. Coolant distribution unit supply bottlenecks extend deployment timelines by four to eight months.
- Immersion Cooling:Dielectric fluid submersion enables 500W-plus rack densities for frontier model training in Shenzhen and Hangzhou greenfield builds. Fire safety certification delays constrain domestic adoption.
- Hybrid Cooling:Mixed air-liquid architectures bridge retrofit scenarios where partial infrastructure upgrade suffices. Western China expansion zones favor this approach for cost-containment during initial buildout phases.
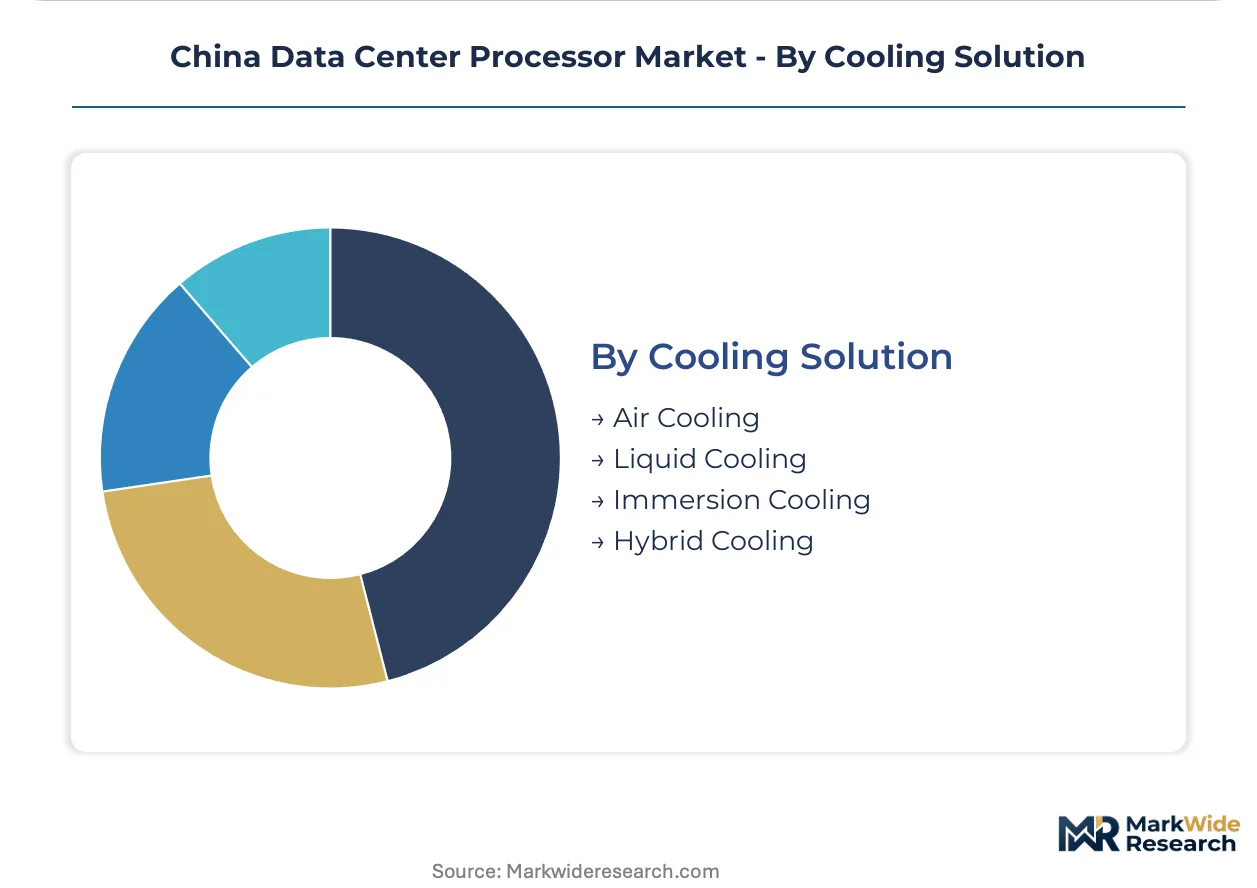
Liquid Cooling leads new deployments. Immersion Cooling shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's data center processor demand concentrates in three metropolitan clusters where engineering talent pools from Tsinghua University, Shanghai Jiao Tong University, and South China University of Technology feed semiconductor design and facility operations.
Beijing-Tianjin-Hebei
MIIT's localization mandates redirect government cloud procurement toward domestic x86 licensing arrangements. GB 40879 energy efficiency thresholds now require PUE below 1.3 for new construction permits in this corridor. Beijing's Zhongguancun software cluster anchors state-owned enterprise data center buildouts with verified domestic content thresholds.
Yangtze River Delta
Shanghai and Hangzhou hyperscalers commission purpose-built AI accelerators for large language model training workloads. NMPA-aligned data localization requirements shape processor sourcing for healthcare cloud deployments in this zone. Suzhou and Wuxi foundry satellites supply advanced packaging capacity for domestic accelerator designs.
Greater Bay Area
Shenzhen and Guangzhou data center buildouts create demand density justifying dedicated supply chain investments from processor vendors. SAMR antitrust oversight influences cloud provider procurement consolidation patterns across Guangdong province. Dongguan mechanical clusters manufacture liquid cooling distribution units for 300W-plus deployments.
Sichuan-Chongqing
Chengdu and Chongqing zones offer land and power cost arbitrage for training clusters with relaxed latency requirements. Western China expansion benefits from relaxed MIIT permitting timelines compared to eastern seaboard constraints. Chongqing's Liangjiang New Zone hosts domestic chiplet assembly pilot lines for modular accelerator designs.
Shandong Peninsula
Qingdao and Jinan facilities serve financial services backup and disaster recovery workloads with mid-power processor standardization. Provincial dual carbon goals accelerate coal-free power purchase agreements for data center operators. Yantai port logistics handle HBM memory module imports for domestic accelerator assembly.
China Data Center Processor Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across China's data center processor procurement channels. The vendor base splits between licensed foreign architecture holders and indigenous instruction-set developers. Three archetypes dominate: CUDA-ecosystem incumbents, domestic x86 licensees, and custom AI accelerator designers. Competitive moves concentrate on foundry capacity reservation and chiplet interconnect standard coalition-building.
Within the licensed-foreign-architecture tier, Intel Corporation and NVIDIA Corporation occupy positions shaped by export licensing restrictions and software ecosystem moats. Hygon anchors domestic alternatives through licensed x86 production arrangements. These three exemplify the bifurcation MIIT mandates have forced upon hyperscaler procurement channels.
| Leading Market Players |
|---|
| Intel Corporation |
| NVIDIA Corporation |
| Advanced Micro Devices Inc. |
| Ampere Computing |
| Arm Ltd. |
| Hygon |
| Xilinx Inc. |
| Achronix Semiconductor Corporation |
| Kunlun Chip |
| Others |
Pricing and Supply Chain Analysis
MIIT's dual carbon goals gate qualified supply and premium-tier pricing access for domestic accelerator vendors. GB 40879 PUE mandates force operators to liquid-cooled designs, segmenting procurement between certified premium silicon and air-cooled economy alternatives.
Pricing Analysis
Bare-metal unbundling from managed platform services is fragmenting procurement contracts across Yangtze River Delta hyperscalers. Three-tier pricing structure across premium liquid-cooled, standard direct-to-chip, and economy air-cooled levels reflects certification grade and cooling infrastructure investment. Cost compression in mid-power brackets is intensifying because domestic foundry output scales on mature nodes. AI training clusters show least price sensitivity; edge aggregation nodes in tier-2 cities show most.
Supply Chain Analysis
Regional distribution centers in Dongguan and Suzhou anchor hub-and-spoke patterns for liquid cooling distribution units. Taiwan, South Korea, and USA concentrate advanced node fabrication and CoWoS packaging capacity. HBM memory, EUV lithography equipment, and advanced EDA software licenses constitute critical input dependencies. Single-source vulnerability in TSMC's CoWoS capacity creates chokepoint risk for AI accelerator shipments. Distribution runs through direct foundry relationships for hyperscalers and tiered distributor networks for state-owned enterprises.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MIIT's semiconductor substitution mandates compound procurement complexity, with NMPA-aligned data sovereignty requirements driving sustained localization investment across healthcare and financial cloud deployments.
For Market Incumbents: Deepen foundry capacity reservations with domestic packaging satellites to offset CoWoS concentration risk. Secure chiplet interconnect standard coalitions before open protocols fragment accelerator compatibility. Threat of indigenous instruction-set developers looms as Hygon scales licensed x86 alternatives. For New Entrants and Emerging Players: Cloud marketplace listings offer low-friction customer acquisition for fractional GPU capacity providers. Western China expansion zones present the most penetrable geography given relaxed MIIT permitting timelines. Target healthcare AI developers in Chengdu with workload-specific accelerator designs. For Investors and Strategic Acquirers: Roll-up economics work for modular cooling subsystem specialists because facility retrofit cycles concentrate procurement decisions in 18-month windows. Five-to-ten year viability hinges on domestic foundry node advancement. Watch HBM supply diversification signals as inflection indicator for domestic accelerator yield rates.| Strategic Initiative | Industry Significance |
|---|---|
| Chiplet Interconnect Coalition | Open die-to-die protocols enable modular designs bypassing monolithic reticle limits at SMIC. |
| Western China Foundry Satellite | Chengdu and Chongqing packaging capacity reduces CoWoS dependency for mid-power accelerators. |
| Liquid Cooling CDU Manufacturing | Dongguan mechanical clusters capture value from GB 40879 PUE mandate compliance. |
| Healthcare Cloud Localization | NMPA-aligned data sovereignty requirements redirect processor sourcing for Shanghai medical AI. |
| EDA Tool Licensing Negotiation | Extended design cycles from restricted simulation access compress domestic processor time-to-market. |
Research Methodology
Direct dialogue with cloud procurement officers, foundry operations managers, data center facility engineers, and MIIT policy researchers grounded qualitative assessment. Secondary validation drew from hyperscaler capex disclosures, MIIT GB standard filings, customs import records for lithography equipment, and TSMC capacity allocation announcements. Bottom-up shipment estimates triangulated against top-down infrastructure investment flows.
Segmentation outputs across processor type, power rating, form factor, and cooling solution dimensions structured the analytical framework. CAGRs derived from facility buildout pipelines, localization mandate phase-in schedules, and AI training cluster commissioning timelines. Foundry capacity allocation between domestic and foreign design houses, plus chiplet assembly yield trajectories, fed forecast sensitivity analysis.
Export licensing restriction expansion, HBM supply disruption, and domestic node yield shortfalls are the dominant revision risks. Forecasts reflect documented assumptions on foundry equipment access and procurement quota enforcement. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Germany Data Center Processor Market
Chipset and Processors
Indonesia Data Center Processor Market
Chipset and Processors
China Automotive Microcontroller Market
Chipset and Processors
South Korea Edge AI Processor Market
Chipset and Processors
Latin America Neuromorphic Chip Market
Chipset and Processors
Automotive Gateway Chips Market
Chipset and Processors
Global Multimedia Chipsets Market
Chipset and Processors
Edge Artificial Intelligence Chips Market
Chipset and Processors
Processor Chip Market
Chipset and Processors
Cloud AI Chipsets Market
Chipset and Processors
High-Performance Dual-Core Processor Market
Chipset and Processors
Global Smartcard MCU Market
Chipset and Processors
X86 Architecture CPU Market
Chipset and Processors
AI Chipsets Market
Chipset and Processors
Power Architecture Market
Chipset and Processors
DNA Sequencing Chip Market