
 XRF Analyzer Market | 2026-2036
XRF Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
XRF Analyzer Market Outlook
The EU Green Deal is pivoting XRF procurement toward mercury and cadmium screening protocols across imported electronics supply chains. Thermo Fisher Scientific leverages its fluorescence detector supply chain to sustain dominance in laboratory-grade benchtop configurations. Bruker anchors European demand through its compliance testing service networks. Hitachi High-Tech competes in East Asian manufacturing corridors with localized calibration support.
An XRF analyzer bombards samples with primary X-ray radiation and measures secondary fluorescent emission to determine elemental composition, typically detecting elements from sodium through uranium at parts-per-million sensitivity. These instruments serve industrial quality assurance, environmental remediation, and forensic trace-evidence analysis. Handheld configurations lead unit shipments due to field-deployable battery architectures, while wavelength-dispersive technology captures premium margin pools in research laboratories requiring sub-ppm resolution. Energy-dispersive systems grow fastest in metal recycling yards where rapid alloy identification determines scrap valuation.
REACH substance restrictions and RoHS directives in Europe compel manufacturers to certify elemental compliance across product lifecycles. The EPA and OSHA in the United States enforce workplace lead and silica exposure limits that drive portable analyzer deployment at demolition and mining sites. China's GB standards and dual carbon goals tighten emissions monitoring requirements for heavy metal discharge. Stakeholders must monitor evolving battery material regulations as lithium-cobalt supply chains face intensified due diligence obligations.
Market Dynamics
The XRF analyzer market pivots on tightening elemental compliance mandates across battery material supply chains, where lithium-cobalt due diligence obligations force rapid deployment of portable verification systems at extraction and refining nodes.
Growth Catalysts
- EU Green Deal mercury protocols:Imported electronics supply chains face mandatory cadmium and mercury screening at European ports, accelerating energy-dispersive system procurement by customs laboratories and third-party testing houses.
- RoHS substance restrictions:European manufacturers must certify elemental compliance across product lifecycles, creating recurring demand for benchtop analyzers in quality assurance departments and contract manufacturing facilities.
- Ore grade verification intensity:Mining operations in Chile and Australia deploy portable units for real-time assay confirmation, reducing reliance on centralized laboratory turnaround and enabling on-site metallurgical decisions.
Market Restraints
- Detector material supply concentration:High-purity silicon drift detectors and silicon pin diodes concentrate among limited East Asian component suppliers, exposing manufacturers to single-source fragility and extended lead times.
- Radioisotope source regulatory friction:Curium-244 and americium-241 sealed sources face transport and disposal restrictions under national nuclear regulatory frameworks, complicating handheld unit distribution and end-of-life management.
- Optical emission spectrometry substitution:Laboratory environments requiring ultra-trace detection below XRF detection limits increasingly deploy ICP-MS and OES systems for sub-ppm resolution in high-value alloy certification.
Strategic Opportunities
- India PLI scheme battery manufacturing:Production-linked incentives for domestic lithium-ion cell manufacturing create demand for in-process cobalt and nickel verification at gigafactory quality control stations.
- Artificial intelligence spectrum interpretation:Machine learning algorithms trained on alloy libraries are integrating with portable analyzers to reduce operator training requirements and enable autonomous material classification in scrap yards.
- Extended producer responsibility mandates:Circular economy directives in multiple jurisdictions compel electronics recyclers to document hazardous element removal, opening service contract opportunities for analyzer deployment with automated reporting.
Industry Challenges
- Certified reference material scarcity:Accurate calibration for rare earth element quantification in permanent magnet recycling requires matrix-matched standards that lack commercial availability, delaying method validation.
- Field technician radiation safety training:Handheld unit operators require recurring dosimetry monitoring and sealed source handling certification, creating operational overhead and workforce qualification bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | XRF Analyzer Market |
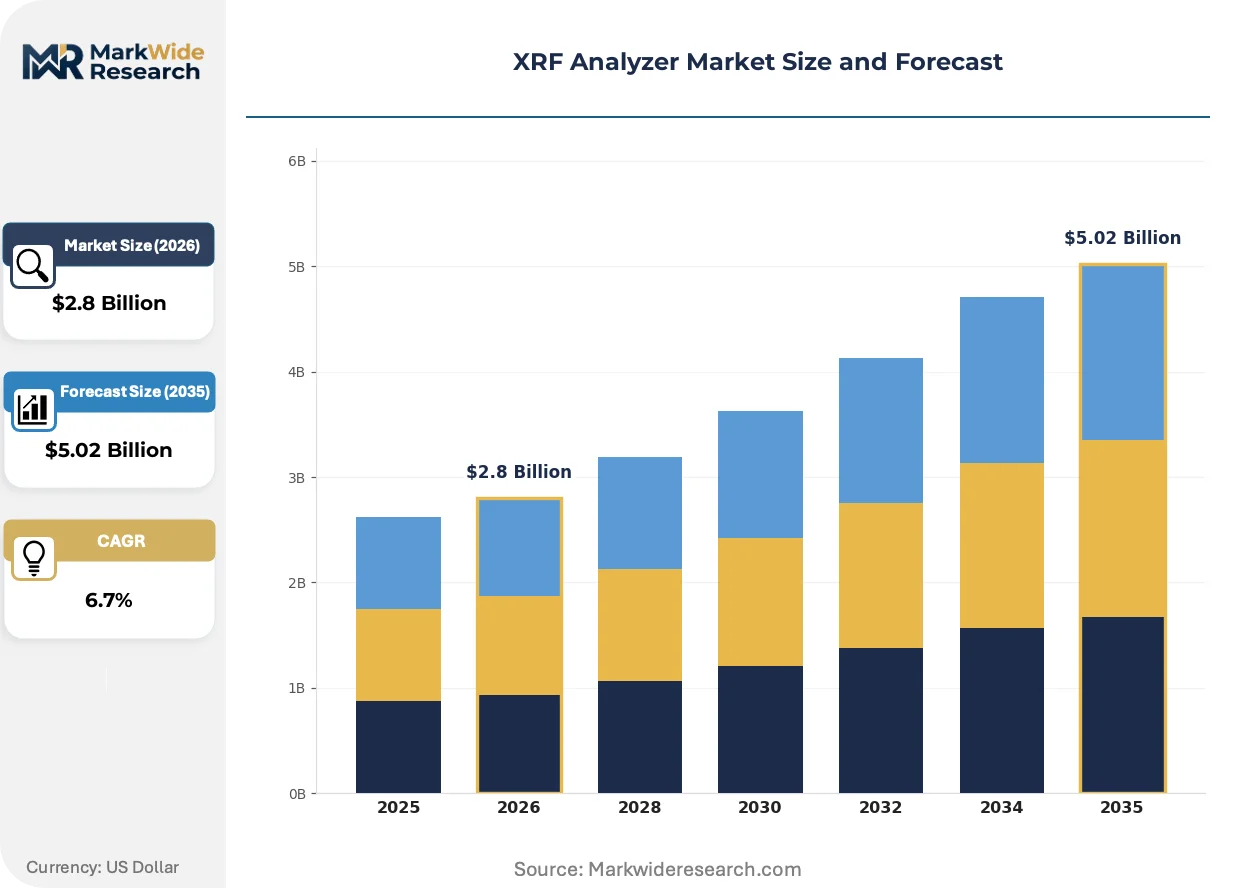
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchtop, Portable, Handheld, Field End User: Mining, Environmental, Metal Recycling, Forensics Technology: Wavelength Dispersive, Energy Dispersive, Laser-induced, X-ray Tube Application: Material Analysis, Quality Control, Compliance Testing, Research |
| Companies Covered | Thermo Fisher Scientific, Olympus Corporation, Hitachi High-Tech, Shimadzu Corporation, HORIBA Ltd., Bruker, Malvern Panalytical Ltd., SPECTRO Analytical Instruments GmbH, Rigaku Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
XRF Analyzer Market Strategic Shifts
Detector architecture miniaturization and cloud-connected calibration databases are compressing the performance gap between portable and laboratory systems, enabling decentralized analytical capabilities at extraction and manufacturing points previously served by centralized laboratories.
Silicon drift detectors with thermoelectric cooling are integrating into handheld platforms previously limited to silicon pin architectures, extending elemental range toward lighter elements including magnesium and aluminum. Mining operators in Australia and Chile adopt these upgraded units for on-site bauxite and laterite nickel verification, compressing assay turnaround from days to minutes and eliminating sample transport logistics.
REACH substance restrictions and RoHS directives in Europe compel manufacturers to deploy energy-dispersive systems for hazardous element screening across imported component supply chains. The ECHA SCIP database requirements for article-level substance disclosure intensify demand for rapid bromine and lead detection in plastic and polymer matrices, shifting procurement priority toward analyzers with integrated compliance reporting software.
Asset-light service models are displacing capital purchase patterns among mid-tier metal recyclers, with third-party testing houses deploying analyzers at customer facilities under per-sample or subscription arrangements. This channel innovation concentrates most visibly in East Asian electronics manufacturing corridors, where supply chain compliance mandates proliferate and recyclers lack capital for in-house instrument acquisition.
XRF Analyzer Market Segmentation
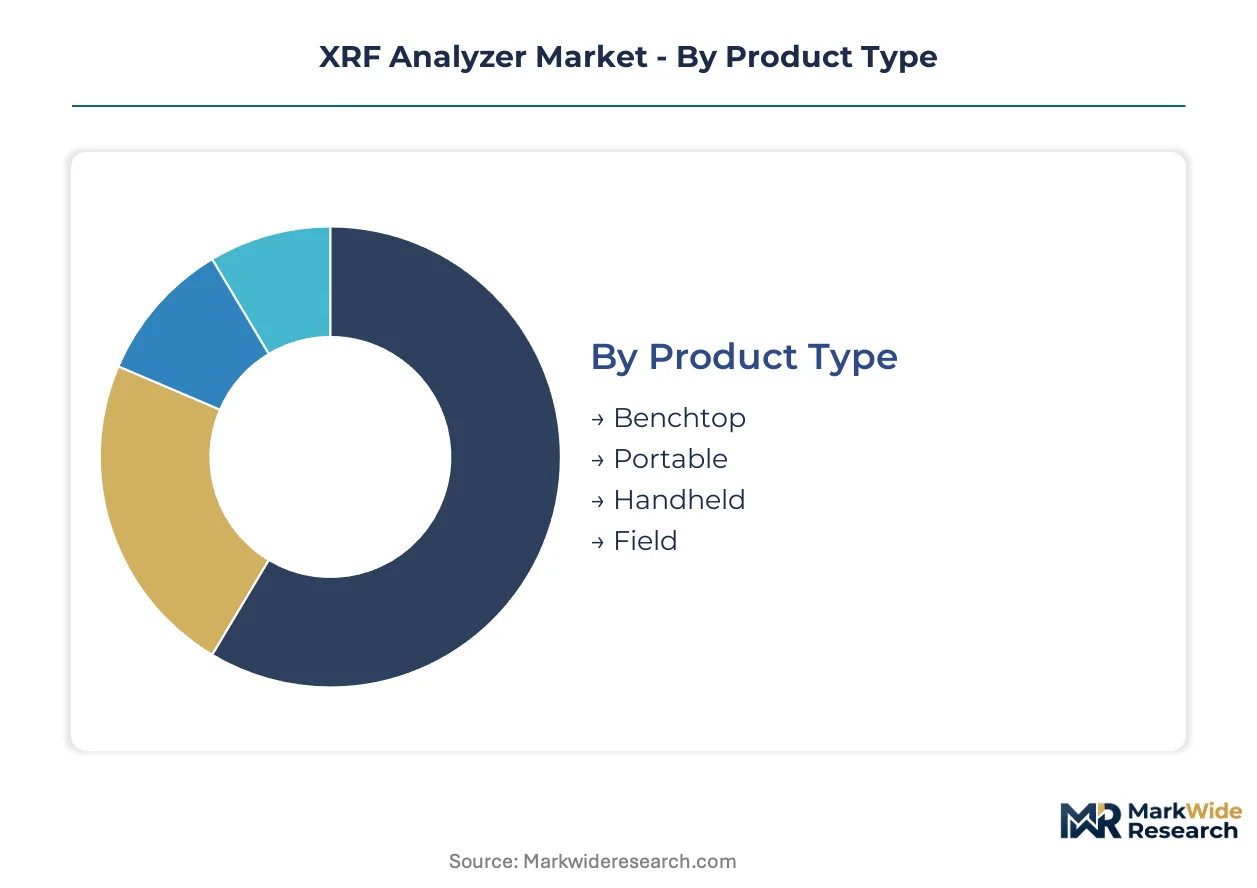
Portable configurations dominate unit shipments through battery-powered field architectures, while wavelength-dispersive systems command premium margins in research settings requiring sub-ppm resolution. Segmentation reveals divergent procurement patterns between decentralized mining operations and centralized laboratory environments.
Product Type:
Handheld units capture the highest volume, while benchtop systems retain the premium pricing tier.
- Handheld:Battery-powered units with silicon drift detectors enable real-time ore grade verification at Chilean and Australian extraction sites. Mining operators deploy these for immediate metallurgical decisions without centralized laboratory delays. Demand concentrates where sample transport logistics prove prohibitive.
- Benchtop:Laboratory-grade configurations with wavelength-dispersive optics deliver sub-ppm resolution for high-value alloy certification. European compliance testing houses procure these for RoHS substance verification under REACH mandates. Thermoelectric cooling architectures extend elemental range toward lighter elements.
- Portable:Mid-tier systems balance mobility with analytical precision for environmental remediation teams.
- Field:Ruggedized enclosures withstand dust and moisture at demolition sites monitoring EPA lead exposure limits.
Mature deployment sits with benchtop systems in centralized laboratories. Newer deployment is concentrated in handheld units at extraction and recycling nodes.
End User:
Mining and metal recycling drive volume procurement, while forensics applications sustain specialized margins.
- Mining:Chilean copper and Australian iron ore operations deploy portable XRF for real-time blast-hole assay and stockpile management. On-site verification eliminates centralized laboratory turnaround, compressing decision cycles from days to minutes. Laterite nickel and bauxite applications expand with silicon drift detector upgrades.
- Metal Recycling:Scrap yards in East Asian manufacturing corridors leverage rapid alloy identification for valuation and sorting. Machine learning spectrum interpretation reduces operator training requirements and enables autonomous material classification. Per-sample service models proliferate among capital-constrained mid-tier recyclers.
- Environmental:EPA and OSHA enforcement of workplace silica and lead limits drives portable deployment at US demolition sites.
- Forensics:Trace-evidence laboratories require certified reference materials for evidentiary chain-of-custody protocols.
Volume procurement clusters in mining and recycling. Specialized margins persist in forensics where certification requirements create switching costs.
Technology:
Energy-dispersive systems expand most quickly, while wavelength-dispersive technology anchors the performance premium.
- Energy Dispersive:Silicon drift detectors with solid-state electronics enable rapid elemental screening without moving optical components. EU customs laboratories deploy these for mercury and cadmium inspection of imported electronics under Green Deal protocols. Integrated compliance reporting software addresses ECHA SCIP database requirements.
- Wavelength Dispersive:Crystal diffraction optics separate fluorescent lines with superior resolution for research-grade quantification. Sub-ppm detection limits serve high-value permanent magnet recycling and rare earth element verification. Method validation delays persist due to matrix-matched standard scarcity.
- Laser-induced:Emerging architectures target specific applications requiring minimal sample preparation.
- X-ray Tube:Sealed sources face transport restrictions under national nuclear regulatory frameworks, complicating distribution.
Established laboratories retain wavelength-dispersive systems for resolution-critical applications. Deployment is climbing the fastest in energy-dispersive configurations for compliance screening and field verification.
Application:
Quality control and compliance testing concentrate procurement, while research applications sustain instrument longevity.
- Compliance Testing:RoHS and REACH mandates compel European manufacturers to certify hazardous element absence across product lifecycles. Energy-dispersive systems with automated reporting satisfy ECHA disclosure requirements for article-level substance tracking. Third-party testing houses deploy asset-light service models at customer facilities.
- Quality Control:India's PLI scheme for domestic lithium-ion manufacturing creates demand for in-process cobalt and nickel verification at gigafactory stations. Real-time screening prevents contaminated batches from entering cell assembly. Calibration drift management remains critical for process control validity.
- Material Analysis:Alloy identification and coating thickness measurement serve general industrial quality assurance.
- Research:Academic and government laboratories pursue method development for novel matrices and trace-element protocols.
Recurring revenue concentrates in compliance testing with mandate-driven replacement cycles. Research applications exhibit longest instrument lifecycles but lowest annual procurement volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chile's Atacama Desert mining corridors drive portable XRF deployment for real-time copper ore assay, compressing centralized laboratory turnaround from days to minutes at extraction sites.
Chile
State-owned Codelco and private operators deploy handheld units across the Atacama and Antofagasta regions for blast-hole verification and stockpile management. The Mining Ministry's environmental discharge standards tighten heavy metal monitoring requirements at tailings facilities. Antofagasta city hosts calibration service networks supporting on-site metallurgical decisions without sample transport logistics.
Australia
Iron ore majors in Western Australia's Pilbara region adopt silicon drift detector upgrades for bauxite and laterite nickel verification. The Department of Industry, Science and Resources enforces workplace silica exposure limits under model WHS regulations. Perth-based equipment distributors maintain rapid-response service contracts across remote mine sites where laboratory access proves prohibitive.
China
Electronics manufacturers in the Yangtze River Delta and Pearl River Delta corridors deploy energy-dispersive systems for RoHS compliance screening. GB standards and dual carbon goals intensify emissions monitoring for heavy metal discharge from plating facilities. Shenzhen's recycling clusters adopt machine-learning-integrated analyzers for autonomous scrap classification under extended producer responsibility mandates.
Germany
Automotive suppliers and testing houses in Bavaria and Baden-Württemberg procure benchtop wavelength-dispersive systems for high-value alloy certification. REACH substance restrictions and RoHS directives compel manufacturers to certify elemental compliance across product lifecycles. Stuttgart's compliance testing networks anchor European demand for automated reporting software addressing ECHA SCIP database requirements.
India
Gigafactory construction in Gujarat and Tamil Nadu under the PLI scheme creates demand for in-process cobalt and nickel verification at quality control stations. The Bureau of Indian Standards tightens battery material specifications as domestic lithium-ion cell manufacturing scales. Chennai's electronics manufacturing clusters deploy rental-service analyzer models under capital-constrained procurement patterns.
XRF Analyzer Market Competitive Environment
Premium-margin players sit above commodity-margin players across detector architecture sophistication and calibration service depth. Laboratory-grade benchtop configurations concentrate among diversified analytical instrument conglomerates with fluorescence detector supply chain control. Three archetypes dominate: integrated scientific conglomerates with captive detector fabrication, specialized spectroscopy houses with compliance testing service networks, and regional fabricators with localized calibration support. Competitive moves center on artificial intelligence spectrum interpretation integration and asset-light service model expansion into mid-tier metal recycling yards.
Within the integrated scientific conglomerate tier, Thermo Fisher Scientific and Bruker occupy positions defined by fluorescence detector supply chain leverage and European compliance testing service density. Hitachi High-Tech exemplifies the regional specialist archetype with localized calibration support in East Asian manufacturing corridors. Olympus Corporation and Shimadzu Corporation represent diversified precision instrument manufacturers with spectroscopy portfolio breadth spanning laboratory and field-deployable configurations.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Olympus Corporation |
| Hitachi High-Tech |
| Shimadzu Corporation |
| HORIBA Ltd. |
| Bruker |
| Malvern Panalytical Ltd. |
| SPECTRO Analytical Instruments GmbH |
| Rigaku Corporation |
| Others |
Value Chain & Pricing Dynamics
Detector engineering talent concentrates in Bavaria and Baden-Württemberg, where specialized workforce costs widen the spread between laboratory-grade benchtop premiums and handheld economy tiers. German calibration expertise anchors value-based pricing for wavelength-dispersive systems, while East Asian manufacturing corridors compress silicon drift detector costs through scale.
Pricing Analysis
Throughput-linked pricing anchors premium tiers, with benchtop wavelength-dispersive systems commanding value-based rates tied to sample-per-hour capacity and uptime guarantees. Pricing stratifies across certified-reference-material tiers, ISO 17025 calibration protocols, and bundled service contracts. Cost compression in handheld segments intensifies as silicon pin diode commoditization accelerates. Metal recyclers exhibit highest price sensitivity, while forensic laboratories accept premium rates for chain-of-custody certification.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Singapore, and Shanghai orchestrate hub-and-spoke fulfillment for detector modules and calibration standards. High-purity silicon drift detectors draw from Japanese and South Korean wafer fabrication, while thermoelectric cooling assemblies source from Chinese thermal management specialists. Single-source vulnerability concentrates in curium-244 sealed source supply under national nuclear regulatory frameworks. Distribution runs through authorized service networks with localized radiation safety certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Detector material supply concentration and regulatory compliance burdens are forcing consolidation among mid-tier fabricators lacking captive component sourcing.
For Market Incumbents: Hedge against silicon drift detector supply fragility through backward integration into wafer-level partnerships or long-term offtake agreements with Japanese and South Korean suppliers. Reinforce service network density in Chilean mining corridors and Australian Pilbara operations where remote-site calibration contracts create switching costs. Counter optical emission spectrometry substitution threats by embedding machine learning spectrum interpretation into portable platforms. For New Entrants and Emerging Players: Begin with asset-light service models targeting capital-constrained mid-tier metal recyclers in India's emerging gigafactory corridors, offering per-sample or subscription arrangements rather than instrument sales. White-space sits with AI-integrated handheld units for autonomous scrap classification where operator training bottlenecks constrain incumbent deployment. Partner with third-party testing houses for channel access rather than building direct sales infrastructure. For Investors and Strategic Acquirers: The window for entry favors specialized spectroscopy houses with compliance testing service networks and regional calibration expertise. Long-term viability hinges on fluorescence detector supply chain control or exclusive distribution rights in high-growth extraction corridors. Monitor ECHA SCIP database enforcement intensity as inflection indicator for European compliance testing demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| AI Spectrum Interpretation Integration | Machine learning algorithms reduce operator training requirements for scrap yard autonomous classification. |
| Backward Integration into Detector Supply | Captive silicon drift detector sourcing mitigates single-source fragility from East Asian component suppliers. |
| Asset-Light Service Model Expansion | Per-sample and subscription arrangements unlock capital-constrained mid-tier recycler segments. |
| Localized Calibration Network Buildout | Regional service density in remote mining corridors creates switching costs against competitor displacement. |
| Compliance Reporting Software Bundling | Integrated ECHA SCIP database automation addresses REACH substance disclosure mandates for European manufacturers. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with instrument engineering directors, mining site metallurgists, compliance testing laboratory managers, and aftermarket service heads. Bottom-up triangulation cross-referenced unit shipment data from customs authorities with top-down validation against capital expenditure disclosures from diversified scientific instrument conglomerates. SEC 10-K filings, ECHA substance registration databases, and mining ministry environmental compliance reports provided secondary validation layers.
Granularity-level modeling deployed product-type segmentation at the detector architecture level, technology segmentation distinguishing energy-dispersive from wavelength-dispersive configurations, and end-user segmentation capturing mining, recycling, and environmental enforcement deployment patterns. CAGRs derived from regression analysis against ore grade verification intensity indices and battery material supply chain due diligence obligation trajectories. Forecast inputs incorporated PLI scheme gigafactory construction timelines and EU Green Deal mercury protocol enforcement schedules.
Underlying measurement precision varies by segment; wavelength-dispersive laboratory systems carry tighter precision than handheld field-deployable units due to calibration standard availability. Forecasts reflect assumptions regarding regulatory enforcement continuity and detector component supply stability. Periodic stress-testing of base assumptions is recommended against semiconductor fabrication capacity constraints and nuclear regulatory framework evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Fluorescence Spectroscopy Market
Analytical Instruments
Seawater Refractometers Market
Analytical Instruments
ICP-OES Spectrometer Market
Analytical Instruments
Cleanroom Particle Counters Market
Analytical Instruments
Laser-Induced Breakdown Spectroscopy Market
Analytical Instruments
Microanalysis Sample Preparation Systems Market
Analytical Instruments
Global Fixed Zirconia Oxygen Analyzer Market
Analytical Instruments
Gas Analyzer Market
Analytical Instruments
Global Raman Spectroscopy Market
Analytical Instruments
Complexion Analysis System Market
Analytical Instruments
Spectroscopy Equipment and Supplies Market
Analytical Instruments
Real-Time Spectrum Analysis Market
Analytical Instruments
Power Device Analyzer Market
Analytical Instruments
Flame Ionization Detectors Market
Analytical Instruments
Melt Flow Meter Market
Analytical Instruments
Conductivity Analyzers Market