
 North America Liquid Chromatography Devices Market | 2026-2036
North America Liquid Chromatography Devices Market Size, Share, and Industry Trends Forecast 2026-2036
North America Liquid Chromatography Devices Market Analytics
Biopharmaceutical contract research organizations is rebalancing procurement patterns across North America, shifting from fragmented academic buyers toward consolidated biotech manufacturing networks. Waters Corporation anchors its position through deep specialization in mass spectrometry-coupled systems for protein characterization. Thermo Fisher Scientific leverages its channel density to sustain instrument placement across Canadian environmental laboratories. Agilent Technologies competes on method transferability between quality control and research workflows.
Liquid chromatography devices separate complex chemical mixtures by differential partitioning between a mobile phase and a stationary phase, achieving resolution down to picogram-per-milliliter detection limits when paired with ultraviolet or mass spectrometry detectors. These systems serve as the analytical backbone for drug purity verification, environmental contaminant quantification, and food safety screening across regulated industries. HPLC instruments occupy the mature revenue core with replacement-driven sales, while UPLC platforms capture margin expansion through reduced solvent consumption and faster throughput. Reversed phase technology dominates routine pharmaceutical quality control, though size exclusion chromatography gains traction in monoclonal antibody aggregation analysis for biologics manufacturers.
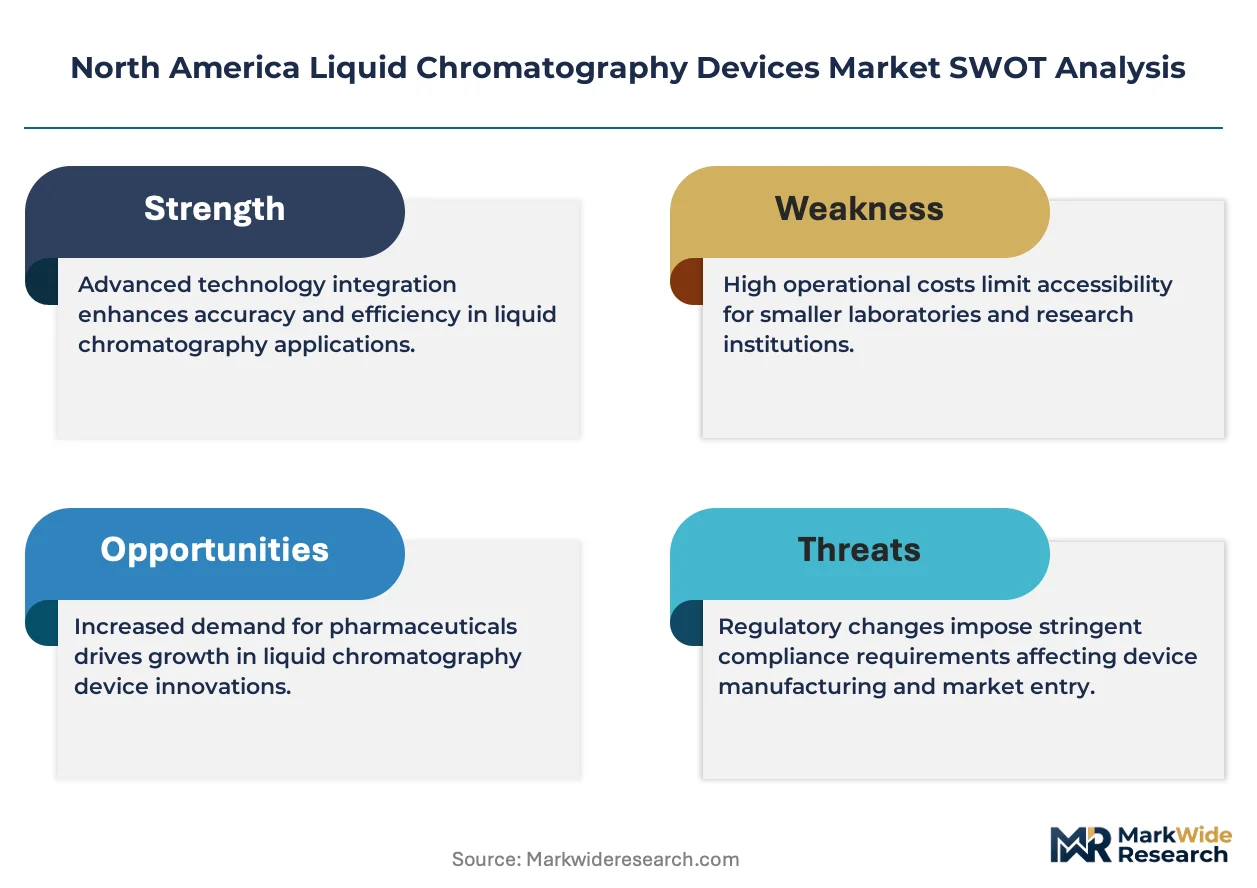
FDA current good manufacturing practice requirements and USP General Chapter revisions mandate validated analytical methods, compelling pharmaceutical end users to upgrade legacy chromatography infrastructure. EPA methods for drinking water and wastewater monitoring similarly shape detector specifications and column chemistries for environmental compliance laboratories. Stakeholders must weigh total cost of ownership against method transfer complexity when evaluating platform migrations between HPLC and UPLC architectures.
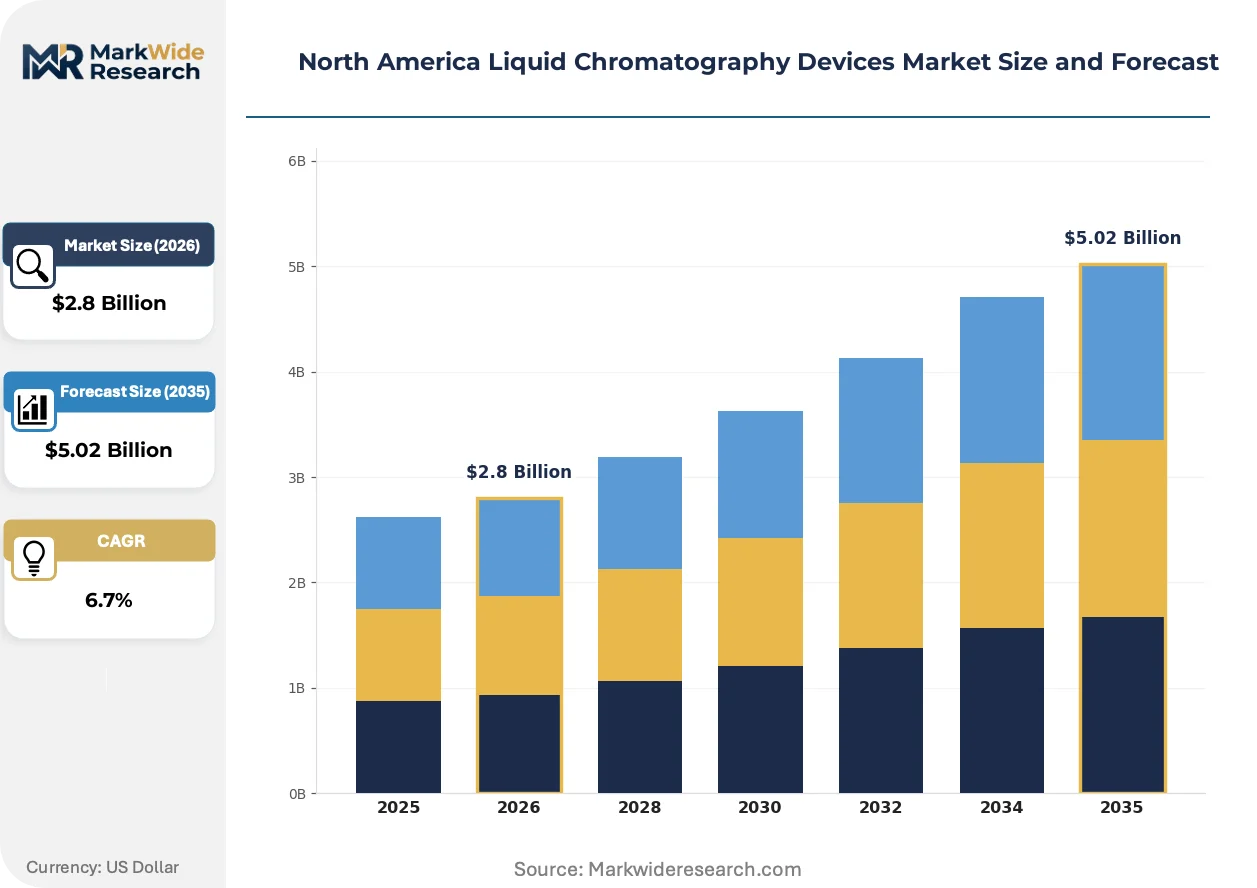
Market Dynamics
FDA quality standards and USP method modernization are compressing instrument replacement cycles across pharmaceutical quality control laboratories. Biopharmaceutical contract manufacturers are consolidating analytical testing capacity into regional hubs, reshaping procurement patterns toward volume-negotiated framework agreements.
Growth Catalysts
- USP General Chapter Revisions:Updated chromatography method validation requirements are compelling pharmaceutical manufacturers to upgrade legacy HPLC infrastructure with UPLC-compatible platforms.
- Biologics Manufacturing Expansion:Monoclonal antibody and cell therapy production growth across the Boston-Cambridge corridor is driving demand for size exclusion chromatography systems.
- Environmental Compliance Testing:EPA drinking water and wastewater monitoring mandates are expanding detector specifications and column chemistry upgrades at state and municipal laboratories.
Market Restraints
- Helium Supply Concentration:Mass spectrometry detector dependence on helium imports from Qatar and Algeria creates input cost volatility and allocation risk for LC-MS system operators.
- Method Transfer Complexity:Validation burden between HPLC and UPLC architectures extends deployment timelines and increases qualification costs for quality control laboratories.
- Academic Budget Constraints:Public university research funding compression in the United States and Canada limits replacement purchases of mid-tier systems.
Strategic Opportunities
- Canadian Environmental Laboratory Network:Provincial water authority consolidation in Ontario and British Columbia creates procurement scale for multi-system framework contracts.
- Continuous Manufacturing Integration:Real-time release testing requirements for pharmaceutical continuous processing lines are opening demand for process analytical technology-enabled chromatography.
- AI-Assisted Peak Integration:Machine learning algorithms for automated chromatogram interpretation are reducing analyst time per sample and enabling 24-hour operational coverage.
Industry Challenges
- Analytical Chemist Talent Pipeline:Specialized training in mass spectrometry method development and regulatory documentation is scarce across the Research Triangle Park cluster and Midwest manufacturing belt.
- Legacy System Interoperability:Data integrity requirements under FDA 21 CFR Part 11 are forcing costly LIMS integration projects for mixed-vendor chromatography fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Liquid Chromatography Devices Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HPLC, UPLC, SFC, GC Technology: Reversed Phase, Normal Phase, Ion Exchange, Size Exclusion End User: Pharmaceutical, Biotechnology, Environmental, Food & Beverage Application: Quality Control, Research, Method Development, Clinical Testing |
| Companies Covered | Waters Corporation, Thermo Fisher Scientific Inc., Agilent Technologies Inc., Shimadzu Corporation, PerkinElmer Inc., Gilson Incorporated, Bio-Rad Laboratories Inc., Merck KGaA, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Liquid Chromatography Devices Market Evolving Landscape
Instrument miniaturization and cloud-connected diagnostics are restructuring how analytical laboratories deploy and maintain chromatography assets. Vendors are repositioning around total cost of ownership rather than capital equipment margins.
Micro-flow liquid chromatography is electrifying protein characterization workflows in biopharmaceutical development. Early adopters at contract research organizations in Massachusetts and North Carolina are replacing conventional nanoflow systems. This technology is electrifying sensitivity thresholds for low-abundance biomarker detection while reducing solvent consumption by an order of magnitude.
FDA current good manufacturing practice enforcement and USP General Chapter 621 revisions are tightening method validation documentation requirements. Pharmaceutical quality control laboratories must now demonstrate equivalence across instrument platforms during technology transfers. Small-molecule generic manufacturers in New Jersey and Puerto Rico are responding by standardizing on single-vendor UPLC architectures to reduce qualification burden.
Service contract unbundling is fragmenting how laboratories procure chromatography support. Preventive maintenance and qualification services are separating from original equipment manufacturer all-inclusive agreements. Third-party service providers are capturing aftermarket revenue in the Great Lakes industrial corridor where multi-vendor instrument parks complicate single-source support relationships.
North America Liquid Chromatography Devices Market Segmentation
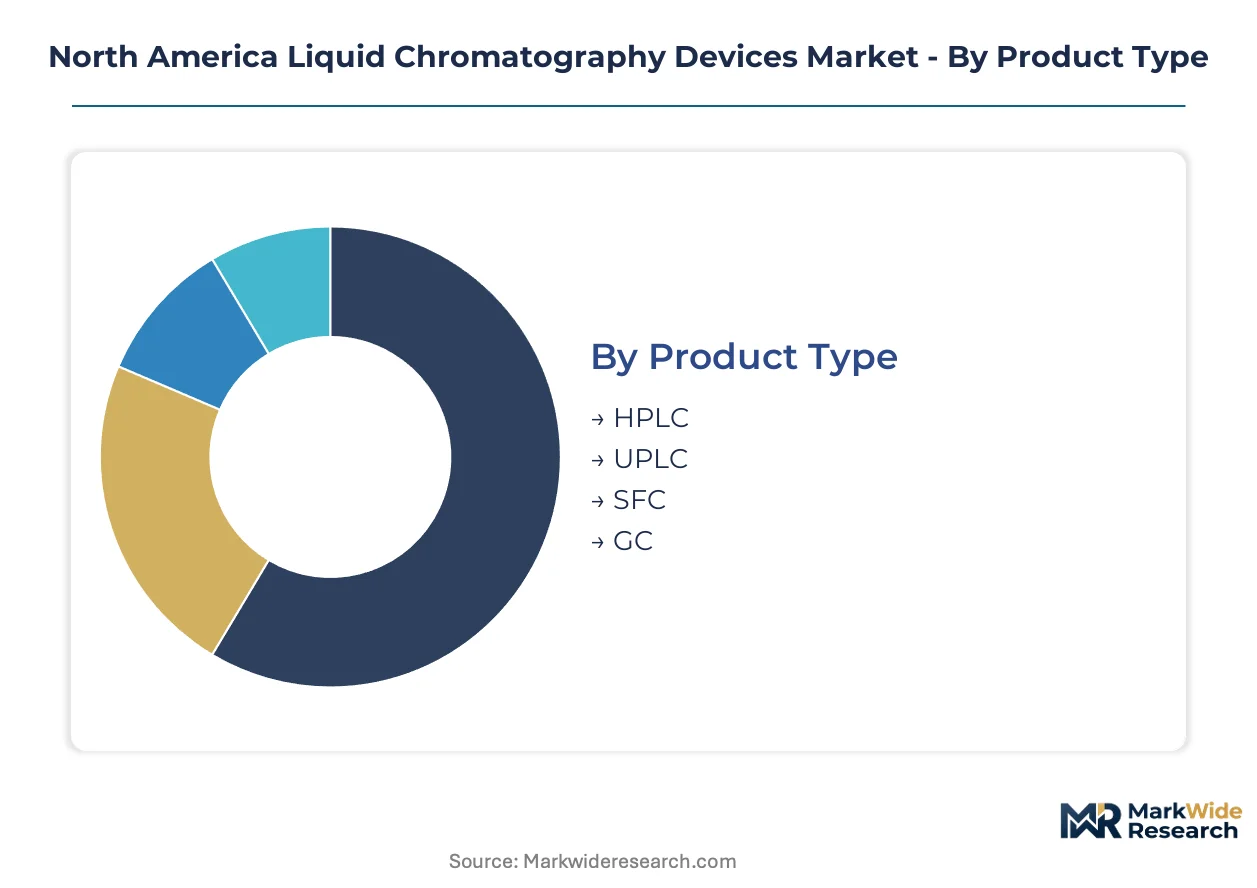
Liquid chromatography device purchasing in North America diverges sharply across regulatory environments, throughput requirements, and total cost thresholds. Understanding these fault lines reveals where instrument vendors can defend premium positioning versus where price competition dominates.
Product Type:
Buyers in this category separate by solvent consumption tolerance, sample throughput needs, and legacy method compatibility obligations.
- HPLC:High-performance liquid chromatography systems operate at standard pressures up to 600 bar using 3-5 micron particle columns. Pharmaceutical quality control laboratories across New Jersey and Puerto Rico anchor replacement demand as FDA method validation requirements compress instrument lifecycles.
- UPLC:Ultra-performance liquid chromatography platforms leverage sub-2-micron particles and pressures exceeding 15,000 psi to achieve 5-10x faster separations. Biopharmaceutical contract manufacturers in the Boston-Cambridge corridor prioritize UPLC acquisitions to reduce solvent costs and accelerate batch release timelines.
- SFC:Supercritical fluid chromatography uses carbon dioxide as the primary mobile phase for chiral separations and preparative purifications.
- GC:Gas chromatography systems serve volatile compound analysis at environmental compliance laboratories and petrochemical testing facilities.
HPLC leads volumes today; UPLC is gaining share fastest.
Technology:
Chromatographic mode selection tracks directly with analyte polarity, molecular weight distribution, and ionic state of target compounds.
- Reversed Phase:Non-polar stationary phases paired with polar aqueous-organic mobile phases dominate routine pharmaceutical quality control for small-molecule drug substances. Generic manufacturers in the Research Triangle Park cluster standardize on reversed phase methods to streamline technology transfers between contract laboratories.
- Size Exclusion:Porous stationary phases separate molecules by hydrodynamic volume rather than chemical affinity. Monoclonal antibody producers across Massachusetts and North Carolina drive demand for size exclusion systems to monitor protein aggregation and fragment species under FDA biologics guidance.
- Normal Phase:Polar stationary phases with non-polar mobile phases resolve geometric isomers and lipid-soluble vitamins.
- Ion Exchange:Charged stationary phases separate proteins, nucleotides, and ionic small molecules based on electrostatic interactions.
Reversed phase anchors current installed base; size exclusion is expanding most quickly.
End User:
Capital allocation authority and procurement sophistication vary dramatically across institutional buyer types.
- Pharmaceutical:Branded and generic drug manufacturers operate under FDA current good manufacturing practice mandates that dictate validated analytical methods. Quality control laboratories at facilities across the Midwest manufacturing belt and Puerto Rico account for the largest instrument placement volumes through multi-year framework agreements.
- Biotechnology:Cell therapy and gene therapy developers require specialized chromatography for complex biologics characterization. Emerging biotechs in Cambridge and San Diego concentrate demand for high-sensitivity mass spectrometry-coupled systems despite compressed funding environments.
- Environmental:State and municipal water authorities execute EPA-mandated contaminant monitoring programs.
- Food & Beverage:Safety testing laboratories and ingredient suppliers deploy chromatography for pesticide residue and mycotoxin quantification.
Pharmaceutical buyers command the largest procurement budgets; biotechnology end users are scaling fastest.
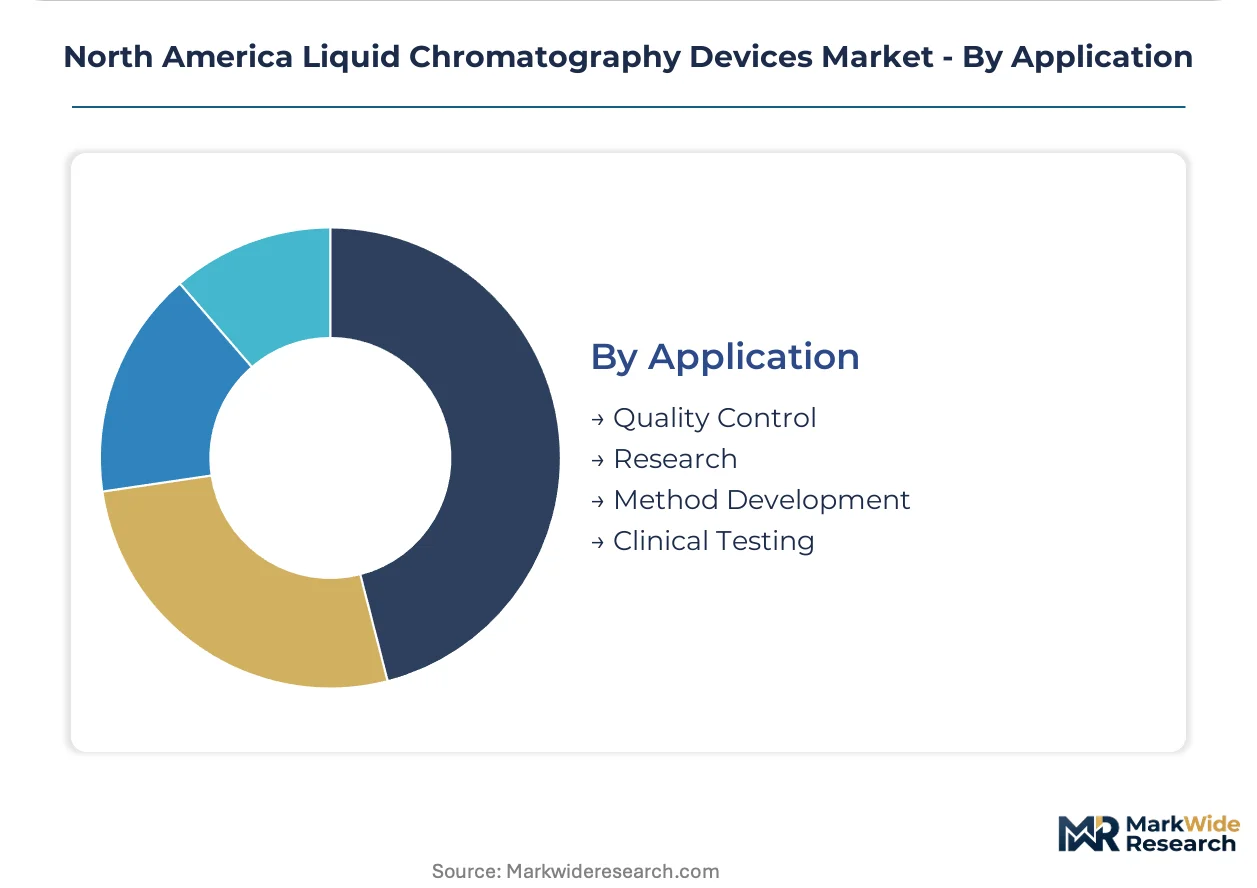
Application:
Workflow purpose determines instrument specification, software validation requirements, and service contract intensity.
- Quality Control:Validated release testing procedures demand 21 CFR Part 11 compliant data integrity and instrument qualification documentation. Pharmaceutical manufacturing sites across the United States and Canada prioritize UPLC standardization to reduce method transfer burden between production facilities.
- Research:Discovery-phase method exploration tolerates higher experimental failure rates and flexible software configurations. Academic medical centers and contract research organizations in Texas and Pennsylvania sustain demand for modular HPLC platforms with interchangeable detectors.
- Method Development:Analytical chemists optimize separation conditions prior to validation and technology transfer.
- Clinical Testing:Diagnostic laboratories apply chromatography for therapeutic drug monitoring and newborn screening programs.
Quality control absorbs the majority of current spending; research applications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States biopharmaceutical clusters outpace Canadian environmental laboratories in instrument density per capita, though both markets face converging regulatory pressures from FDA and Health Canada quality mandates.
United States
Boston-Cambridge biotech corridor and Research Triangle Park drive monoclonal antibody production capacity expansion. FDA current good manufacturing practice enforcement compresses HPLC replacement cycles at New Jersey and Puerto Rico generic manufacturing sites. Midwest manufacturing belt quality control laboratories consolidate procurement through multi-year framework agreements with instrument vendors.
Canada
Provincial water authority consolidation in Ontario and British Columbia creates procurement scale for environmental compliance testing networks. Health Canada and PMRA pharmaceutical regulations align with FDA validation standards, accelerating UPLC adoption at Toronto-area contract research organizations. Alberta energy sector laboratories maintain steady GC-LC replacement demand for petrochemical contaminant monitoring.
Mexico
FDA-registered maquiladora pharmaceutical facilities near Tijuana and Mexicali upgrade analytical infrastructure to meet USP method validation requirements. COFEPRIS regulatory harmonization with FDA standards drives instrument standardization at Mexico City metro area quality control laboratories. Northern border states concentrate demand for high-throughput UPLC systems serving cross-border contract manufacturing.
North America Liquid Chromatography Devices Market Competitive Landscape
United States-based conglomerates anchor one tier; Japanese and European specialists hold differentiated positions in detector technology and column chemistry. Market structure tilts toward consolidated procurement relationships, with three to five vendors capturing majority share in pharmaceutical quality control segments. Strategic archetypes include full-stack analytical platform providers, mass spectrometry-coupled system specialists, and service-intensive regional distributors. Dominant competitive moves center on multi-year service contract bundling and method transfer qualification partnerships with contract manufacturing organizations.
Among United States-based platform providers, Waters Corporation and Thermo Fisher Scientific exemplify contrasting archetypes: one anchors deep specialization in mass spectrometry-coupled protein characterization, while the other leverages channel density across Canadian environmental networks. Agilent Technologies occupies a position emphasizing method transferability between research and quality control workflows. Shimadzu Corporation represents the Japanese specialist tier with concentrated presence in academic and industrial research segments.
| Leading Market Players |
|---|
| Waters Corporation |
| Thermo Fisher Scientific Inc. |
| Agilent Technologies Inc. |
| Shimadzu Corporation |
| PerkinElmer Inc. |
| Gilson Incorporated |
| Bio-Rad Laboratories Inc. |
| Merck KGaA |
| Danaher Corporation |
| Others |
Value Network & Pricing Analysis
Helium procurement costs for mass spectrometry detectors cascade through LC-MS system pricing tiers, with Qatar and Algeria supply concentration elevating premium instrument price floors while compressing margins on mid-range HPLC platforms at North American pharmaceutical quality control laboratories.
Pricing Analysis
Capacity additions in Chinese column manufacturing are reshaping price floors for consumables, pressuring legacy premium positioning. Three-tier pricing structure across enterprise-grade UPLC, validated HPLC, and entry-level academic systems separates total cost of ownership calculations. Pricing pressure stems from unbundled service contracts fragmenting aftermarket revenue pools. Generic manufacturers in Puerto Rico exhibit highest price sensitivity; biologics developers in Massachusetts prioritize throughput over capital cost.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific component origins is elevating landed costs for sub-2-micron particle columns and high-pressure pump assemblies. Manufacturing concentrates in Germany, Japan, and Massachusetts for precision fluidics; China dominates silica particle and bonded-phase chemistry production. Supply chain risk centers on single-source vulnerability for specialized mass spectrometry ion sources. Distribution runs through direct field service organizations for pharmaceutical accounts and regional distributors for academic and environmental laboratory segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 21 CFR Part 11 enforcement acts as a regulatory compounder, with data integrity mandates accelerating replacement cycles across legacy instrument fleets and consolidating procurement authority toward vendors with validated compliance documentation.
For Market Incumbents: Extend service contract bundling into multi-year qualification partnerships with contract manufacturing organizations facing USP General Chapter 621 revision deadlines. Deepen backward integration into consumables manufacturing to capture recurring revenue streams threatened by third-party column suppliers. Anchor defensive positioning against emerging AI-assisted peak integration vendors through embedded software licensing. For New Entrants and Emerging Players: EPA drinking water method updates in the United States open a window for specialized detector configurations at consolidated Ontario and British Columbia provincial water authorities. Target underpenetrated Canadian environmental laboratory networks with portable UPLC platforms designed for field-deployable contaminant screening. Pursue go-to-market partnerships with third-party service providers unbundling from OEM maintenance agreements in the Great Lakes industrial corridor. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-vendor instrument parks complicate single-source support relationships and drive LIMS integration project costs. Long-term viability favors platform providers with captive consumables revenue and regulatory documentation depth over pure-play hardware manufacturers. Monitor AI-assisted chromatogram interpretation adoption rates at Massachusetts contract research organizations as inflection signal for workflow automation disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Documentation Partnership | FDA 21 CFR Part 11 compliance bundling secures multi-year pharmaceutical quality control contracts. |
| Consumables Backward Integration | In-house column chemistry production captures recurring revenue threatened by third-party suppliers. |
| AI-Assisted Software Licensing | Machine learning peak integration modules differentiate instrument platforms at contract research organizations. |
| Environmental Laboratory Consolidation | Provincial water authority framework agreements in Ontario create procurement scale for multi-system vendors. |
| Service Contract Unbundling Response | Independent qualification partnerships capture aftermarket revenue from fragmented multi-vendor instrument parks. |
Research Methodology
Direct dialogue with analytical chemistry directors, pharmaceutical quality control managers, biopharmaceutical procurement leads, and environmental laboratory supervisors grounded qualitative findings. Secondary validation drew from FDA 483 observation databases, USP General Chapter revision dockets, EPA method update notices, and Health Canada regulatory guidance documents. Bottom-up instrument placement tallies triangulated against top-down market sizing from vendor revenue disclosures and trade association equipment surveys.
Bottom-up modeling segmented demand across product type, chromatographic mode, end-user institution, and application workflow, then aggregated across the projection horizon. Analytical framework incorporated replacement cycle dynamics tied to FDA cGMP enforcement intensity, USP method validation burden, and biologics manufacturing capacity expansion in named regional clusters. CAGRs derived from instrument lifecycle compression rates and solvent consumption cost savings driving UPLC migration economics.
Revisions become necessary when helium supply allocation disruptions, USP General Chapter implementation delays, or AI-assisted workflow adoption acceleration materialize beyond modeled scenarios. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Thermoluminescent Dosimeter (TLD) System Market
Analytical Instruments
Visualization Instruments for MIS Market
Analytical Instruments
Europe Handheld Spectrum Analyzer Market
Analytical Instruments
Single Cell Analysis System Market
Analytical Instruments
North America Analytical Instrumentation Market
Analytical Instruments
Real-Time Spectrum Analysis Market
Analytical Instruments
Power Device Analyzer Market
Analytical Instruments
Near-Infrared Spectroscopy Market
Analytical Instruments
AFM Probe Market
Analytical Instruments
Europe Surface Analysis Market
Analytical Instruments
Energy Dispersive X-Ray Spectrometer Market
Analytical Instruments
Potentiometric Titrators Market
Analytical Instruments
TDLAS Moisture Analyzers Market
Analytical Instruments
Lab-On-A-Chip Device Market
Analytical Instruments
Surface Plasmon Resonance (SPR) System Market
Analytical Instruments
Handheld XRF Analyzers Market