
 Thermogravimetric Analyzer Market | 2026-2036
Thermogravimetric Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Thermogravimetric Analyzer Market Analytics
The divergence between premium and commodity tiers is hardening around microbalance sensitivity and software integration depth. TA Instruments leverages captive sensor manufacturing to sustain precision advantages at the high end. NETZSCH-Gerätebau GmbH anchors its position through specialized high-temperature configurations for ceramics research. Shimadzu Corporation competes on modular platform architectures that reduce per-lab capital commitment.
A thermogravimetric analyzer measures mass change in a sample as temperature varies under controlled atmospheric conditions, typically achieving resolution to 0.1 microgram with heating rates spanning 0.1 to 100 Kelvin per minute. Its primary purpose spans polymer decomposition profiling, pharmaceutical excipient stability validation, and composite thermal endurance certification. Simultaneous thermal analysis platforms command premium positioning by combining TGA with differential scanning calorimetry in single instrument footprints. Dynamic heating protocols are displacing static isothermal methods in pharmaceutical quality control workflows. Cloud-based delivery modes remain nascent but attract early adopters in multi-site food safety networks seeking centralized data governance.
The FDA enforces thermal characterization standards through ICH Q1A stability testing guidelines that mandate validated analytical methods for new drug submissions. EPA methods 8260 and 8270 indirectly shape TGA demand by requiring thermal validation of sorbent materials used in volatile organic compound analysis. ISO 11358 provides the foundational calibration protocol that manufacturers must demonstrate for CE marking access under EU MDR pathways for in-vitro diagnostic adjacent equipment. Stakeholders must weigh instrument interoperability standards against the risk of stranded capital as laboratory information management systems evolve toward API-first architectures.
Market Dynamics
Pharmaceutical quality mandates are compressing analytical validation timelines while materials science institutes expand high-throughput thermal screening capacity. The ICH Q1A stability testing framework now requires documented thermal characterization for excipient compatibility studies, forcing laboratories to upgrade legacy instrumentation.
Growth Catalysts
- ICH Q1A Stability Testing:The FDA enforces thermal characterization data for generic drug approvals, expanding TGA procurement in United States pharmaceutical laboratories.
- Ceramics Research Clusters:Germany's materials science institutes maintain dense instrumentation networks that sustain replacement demand for high-temperature analyzer configurations.
- Polymer Decomposition Profiling:Composite manufacturers in aerospace supply chains require thermal endurance certification for carbon-fiber matrix qualification.
Market Restraints
- Platinum Thermocouple Volatility:Precious metal input costs fluctuate with mining supply disruptions, pressuring sensor replacement economics.
- Microbalance Manufacturing Concentration:Precision subcomponent fabrication concentrates in specialized European and Japanese supply bases, creating single-source vulnerabilities.
- High-Vacuum System Complexity:Ultra-high purity atmosphere control requires maintenance protocols that extend instrument downtime beyond acceptable thresholds for high-throughput facilities.
Strategic Opportunities
- Cloud-Based Data Governance:Multi-site food safety networks in North America are piloting centralized thermal data repositories for cross-facility compliance monitoring.
- Simultaneous Thermal Analysis Convergence:TGA-DSC platform integration reduces capital footprint per analytical workstation in contract research organizations.
- India's PLI Scheme for Pharmaceuticals:Domestic drug manufacturing incentives are accelerating analytical equipment localization in Mumbai and Hyderabad clusters.
Industry Challenges
- Thermal Analysis Specialist Shortage:Universities produce insufficient graduates trained in kinetic modeling and instrument calibration protocols.
- LIMS Integration Friction:API-first laboratory information management architectures risk stranding capital in instruments with proprietary data formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermogravimetric Analyzer Market |
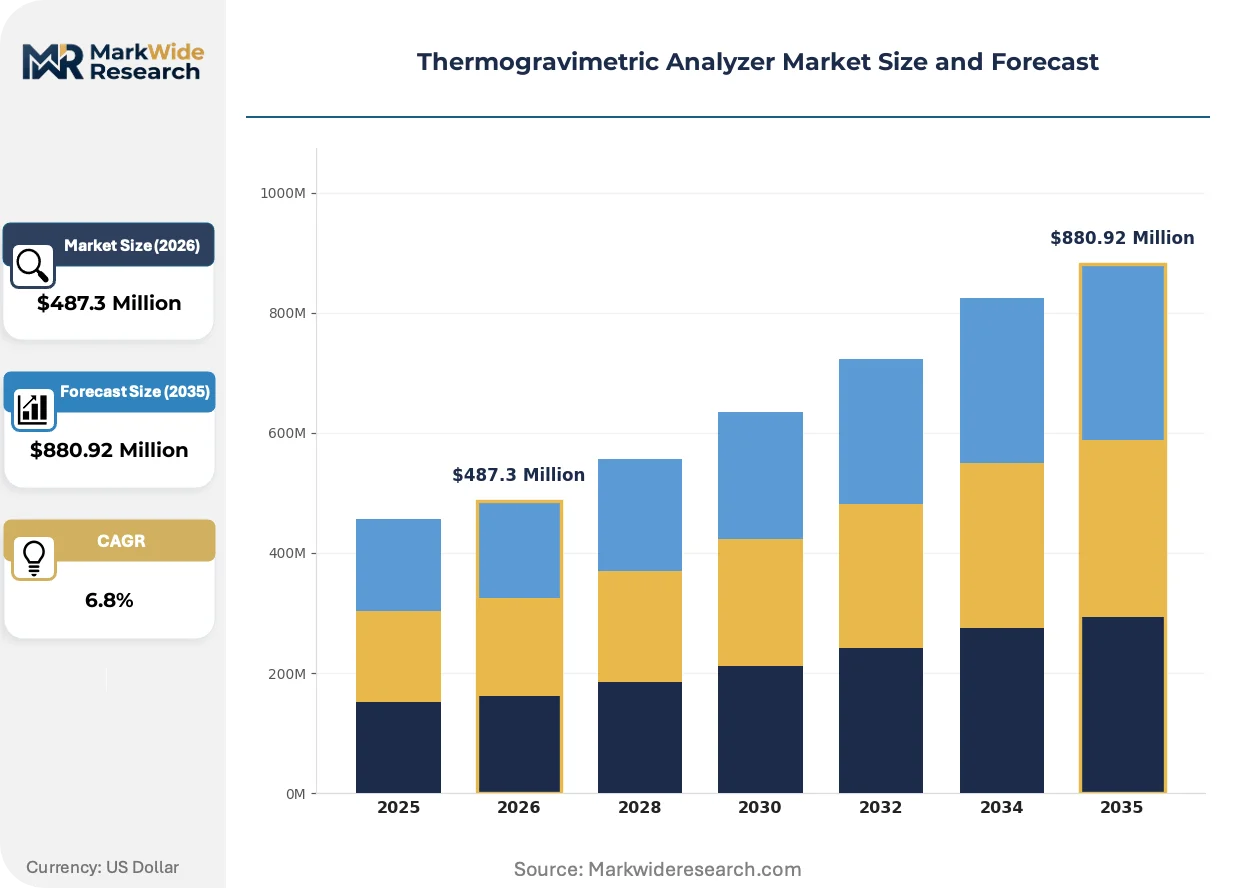
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static, Dynamic, Simultaneous, Differential End User: Pharmaceuticals, Food & Beverage, Materials Science, Education Technology: Microbalance, Robotic Automation, Software Integration, Digital Interfaces Delivery Mode: On-Premise, Cloud-Based, Hybrid, Portable |
| Companies Covered | TA Instruments, Mettler Toledo, PerkinElmer, Shimadzu Corporation, NETZSCH-Gerätebau GmbH, Hitachi High-Tech Corporation, Rigaku Corporation, Setaram Instrumentation, Linseis Messgeräte GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermogravimetric Analyzer Market Evolving Landscape
Instrument architectures are consolidating multiple thermal techniques while regulatory data integrity requirements reshape software roadmaps. Vendors now compete on interoperability depth rather than isolated sensitivity specifications.
Simultaneous thermal analysis platforms are unifying TGA with differential scanning calorimetry in single footprints. Pharmaceutical quality control laboratories in the United States are adopting these integrated systems to compress validation timelines. The technology is unifying decomposition profiling with heat capacity measurement, eliminating redundant sample preparation steps and reducing per-test labor allocation.
REACH substance registration requirements in Europe mandate thermal stability documentation for polymer additives and flame retardants. Chemical manufacturers must submit validated TGA data for substances above one-ton annual production thresholds. The regulation is forcing mid-sized compounders to outsource thermal analysis or acquire in-house capability, expanding the contract testing services segment.
Service unbundling is separating hardware procurement from calibration and maintenance contracts in academic procurement. University core facilities now negotiate multi-vendor service agreements independent of initial capital purchases. This pattern is most visible in United States research institutions where shared instrumentation grants require transparent lifecycle cost documentation.
Thermogravimetric Analyzer Market Segmentation
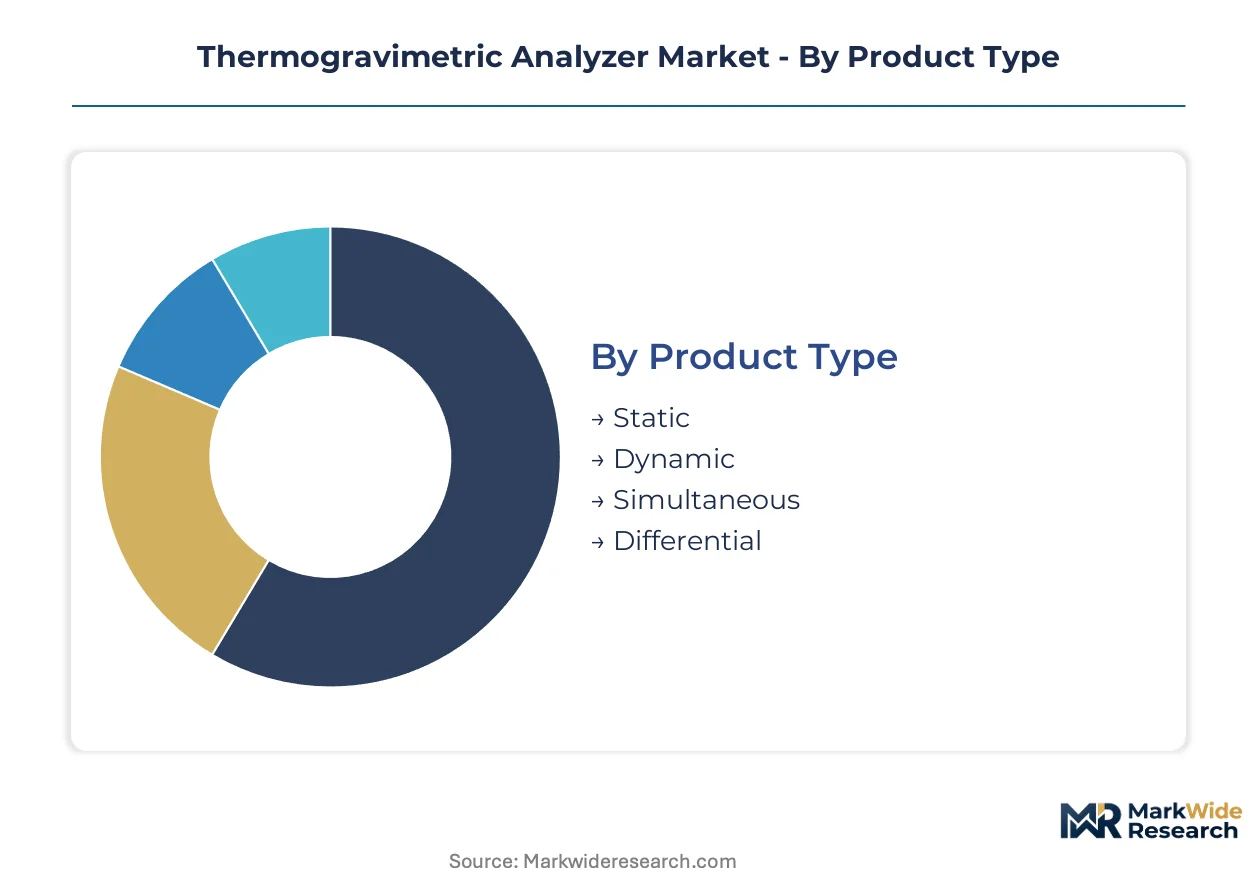
Thermogravimetric analyzer procurement patterns diverge sharply across product architectures and end-use environments. Capital deployment priorities vary from high-precision research configurations to modular platforms suited for high-throughput quality control workflows.
Product Type:
Capital intensity peaks with simultaneous thermal analysis platforms that unify multiple measurement techniques in single footprints. Static and dynamic configurations occupy lower investment tiers with narrower functional scope.
- Static:Isothermal mass measurement at fixed temperature setpoints serves excipient stability screening in United States pharmaceutical laboratories. FDA enforcement of ICH Q1A documentation requirements sustains replacement cycles for legacy units in generic drug testing facilities.
- Dynamic:Programmable heating protocols from ambient to 1000°C enable polymer decomposition profiling for aerospace composite certification. Materials science institutes in Germany favor these configurations for ceramics matrix characterization where heating rate precision determines data validity.
- Simultaneous:Combined TGA-DSC architectures reduce per-workstation capital burden in contract research organizations. Integration eliminates redundant sample preparation and compresses validation timelines for multi-parameter thermal characterization.
- Differential:Comparative measurement against reference standards supports high-sensitivity kinetic analysis in academic research settings. Requires specialized operator training that limits deployment outside core facilities.
Most installed capacity flows through Dynamic configurations. Expansion is steepest in Simultaneous platforms.
End User:
Application requirements dictate instrument specification tiers, with regulatory compliance intensity varying substantially across verticals.
- Pharmaceuticals:Excipient compatibility studies and drug stability validation demand validated analytical methods under FDA ICH Q1A guidelines. United States generic drug manufacturers face compressed procurement timelines as documentation requirements tighten.
- Food & Beverage:Moisture content analysis and thermal degradation profiling support shelf-life determination and safety certification. Multi-site networks in North America pilot cloud-based data governance for cross-facility compliance monitoring.
- Materials Science:High-temperature configurations serve ceramics and metallurgy research clusters in Germany. Dense instrumentation networks sustain replacement demand for specialized furnace designs exceeding 1500°C operational thresholds.
- Education:University core facilities negotiate multi-vendor service agreements independent of capital purchases. Shared instrumentation grants require transparent lifecycle cost documentation.
Pharmaceutical laboratories command the highest specification premiums. Food safety networks are expanding most quickly.
Technology:
Precision differentiation concentrates in subcomponent engineering, with microbalance manufacturing bottlenecks constraining supply elasticity.
- Microbalance:Resolution to 0.1 microgram determines measurement fidelity for pharmaceutical excipient analysis. Fabrication concentrates in specialized European and Japanese supply bases, creating single-source vulnerabilities.
- Robotic Automation:Automated sample handling reduces labor allocation in high-throughput screening environments. Materials science institutes deploy these systems for unattended overnight thermal profiling.
- Software Integration:API-first architectures enable laboratory information management system connectivity. Risk of stranded capital rises for instruments with proprietary data formats.
- Digital Interfaces:Touchscreen control panels and remote monitoring capabilities reduce operator training burden. Cloud-enabled variants attract early adopters in distributed food safety networks.
Microbalance systems anchor the premium tier. Software integration capabilities are gaining share fastest.
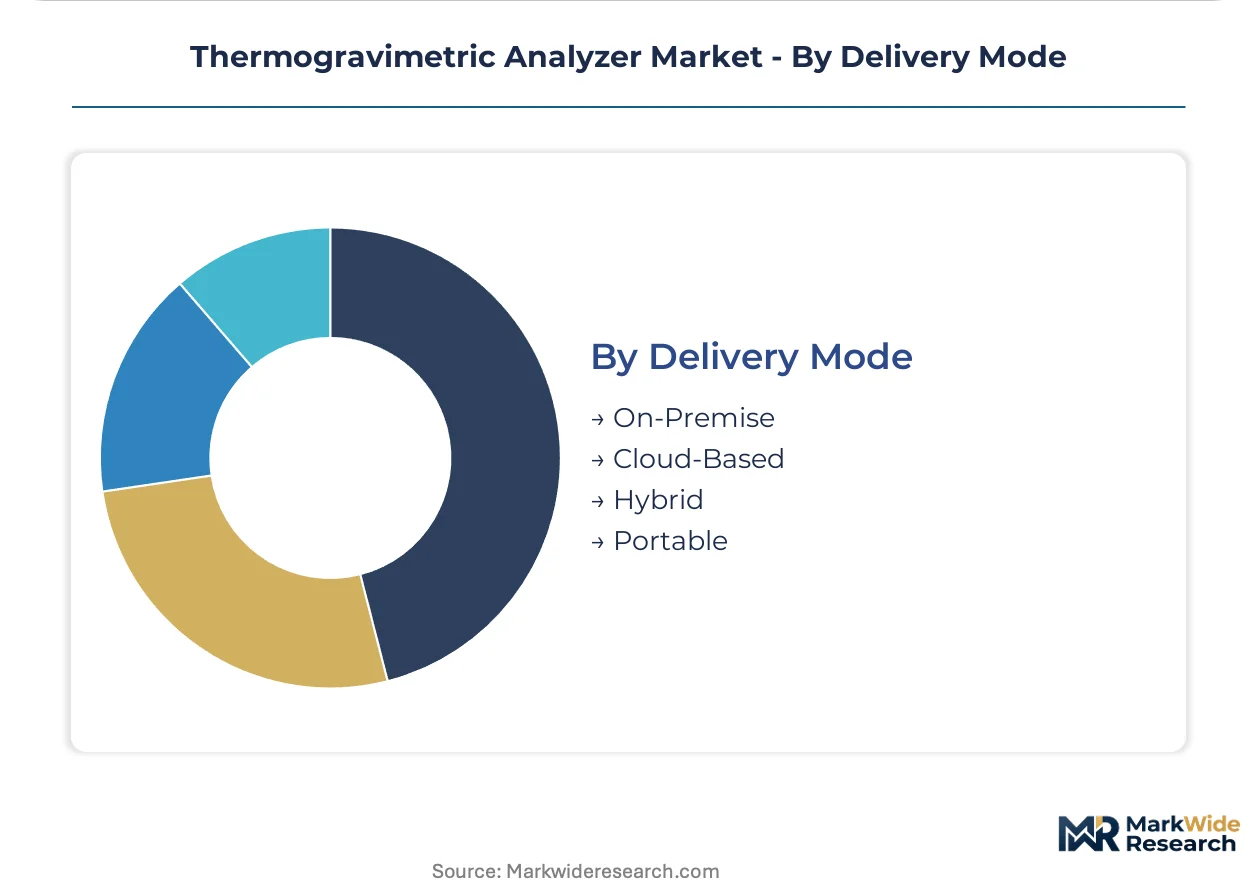
Delivery Mode:
Deployment architecture shapes total cost of ownership through infrastructure requirements and maintenance protocol complexity.
- On-Premise:Traditional capital acquisition with localized data storage dominates pharmaceutical quality control laboratories. Regulatory audit requirements favor physical data custody over third-party hosting.
- Cloud-Based:Centralized thermal data repositories enable multi-site compliance monitoring. North American food safety networks pilot these configurations for cross-facility governance.
- Hybrid:Local instrument control with cloud-based analytics balances data sovereignty and collaboration needs. Contract research organizations favor this architecture for client confidentiality.
- Portable:Field-deployable units support on-site polymer characterization in aerospace supply chains. Reduced sensitivity specifications limit application to screening rather than certification-grade measurement.
On-Premise systems retain the largest installed base. Cloud-Based delivery is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized thermal analysis technicians concentrate in Germany's materials science corridors and the United States' pharmaceutical manufacturing belts, anchoring regional demand density for precision instrumentation.
United States
FDA enforcement of ICH Q1A stability testing guidelines drives pharmaceutical laboratories in New Jersey and Massachusetts to upgrade thermal characterization capabilities. Generic drug manufacturers face compressed validation timelines as documentation requirements tighten for excipient compatibility studies. The Boston-Cambridge research corridor sustains dense clusters of contract testing facilities requiring high-throughput TGA-DSC platforms.
Germany
Materials science institutes in Bavaria and Baden-Württemberg maintain instrumentation networks exceeding 1500°C operational thresholds for ceramics matrix research. REACH substance registration mandates thermal stability documentation from polymer compounders in the Rhine-Ruhr industrial zone. The NETZSCH-Gerätebau GmbH manufacturing base in Selb anchors regional supply chain concentration for high-temperature furnace configurations.
Japan
PMDA quality guidelines for pharmaceutical submissions align with ICH thermal characterization standards, expanding procurement in Osaka and Tokyo pharmaceutical corridors. METI funding for advanced materials research supports ceramics and composite development programs at national institutes. The Nagoya manufacturing belt sustains replacement demand for precision microbalance systems in automotive supplier quality labs.
India
CDSCO tightening of generic drug approval documentation accelerates TGA procurement in Mumbai and Hyderabad pharmaceutical clusters. The PLI scheme for domestic drug manufacturing incentivizes analytical equipment localization in Gujarat and Karnataka. Bangalore's materials research institutes deploy dynamic heating configurations for aerospace composite qualification programs.
China
NMPA stability testing requirements for innovative drug submissions expand thermal analysis demand in Shanghai and Suzhou pharmaceutical zones. MIIT funding for advanced ceramics research supports high-temperature analyzer deployment in the Yangtze River Delta. The Beijing-Tianjin-Hebei corridor concentrates materials science instrumentation for battery thermal characterization in electric vehicle supply chains.
Thermogravimetric Analyzer Market Competitive Landscape
Top-tier vendors anchor precision instrumentation tiers, while mid-scale fabricators compete on modular platform architectures. The vendor base stratifies around microbalance manufacturing concentration in European and Japanese supply bases. Three archetypes dominate: captive sensor manufacturers sustaining resolution advantages, specialized high-temperature configuration providers, and modular platform architects reducing per-lab capital commitment. Geographic expansion and technology licensing represent the dominant competitive vectors as laboratories demand API-first software integration.
Among German-based precision manufacturers, NETZSCH-Gerätebau GmbH and Linseis Messgeräte GmbH exemplify the specialized high-temperature configuration archetype. TA Instruments represents the captive sensor manufacturing tier, leveraging in-house microbalance production to sustain measurement fidelity advantages. Shimadzu Corporation occupies a position within the modular platform segment, reducing capital barriers for high-throughput screening environments. These three anchors illustrate the competitive divergence around sensitivity specifications versus deployment flexibility.
| Leading Market Players |
|---|
| TA Instruments |
| Mettler Toledo |
| PerkinElmer |
| Shimadzu Corporation |
| NETZSCH-Gerätebau GmbH |
| Hitachi High-Tech Corporation |
| Rigaku Corporation |
| Setaram Instrumentation |
| Linseis Messgeräte GmbH |
| Others |
Value Network & Pricing Analysis
Precision microbalance fabrication specialists in Bavaria and Nagoya anchor labor-cost differentials that widen pricing spreads between premium research-grade systems and modular quality-control platforms. Pharmaceutical laboratories in New Jersey and Massachusetts absorb premium pricing for validated ICH Q1A-compliant configurations, while contract research organizations in emerging clusters negotiate aggressive capital-per-workstation metrics.
Pricing Analysis
Service unbundling separates hardware procurement from calibration and maintenance contracts, creating transparent lifecycle cost documentation that academic core facilities exploit during shared instrumentation grant negotiations. Three-tier pricing structure across premium, standard, and economy levels stratifies around microbalance sensitivity, software integration depth, and after-sales bundling intensity. Cost compression in the standard tier is intensifying because mid-scale fabricators compete on modular platform architectures that reduce per-lab capital commitment. Contract research organizations exhibit the highest price sensitivity due to client billing rate constraints, while materials science institutes in Germany demonstrate the lowest sensitivity given grant-funded replacement cycles for high-temperature furnace configurations.
Supply Chain Analysis
Freight cost volatility for precision subcomponents shipped from specialized European and Japanese supply bases amplifies total landed cost uncertainty for North American and Asian end-users. Microbalance manufacturing concentrates in Germany and Japan, while high-temperature furnace fabrication anchors in Bavaria and Selb. Platinum thermocouple supply draws from South African mining operations and Russian refining capacity, exposing sensor replacement economics to commodity price swings. Single-source vulnerability in precision subcomponent fabrication creates structural risk for instrument manufacturers dependent on captive European sensor suppliers. Distribution runs through authorized technical distributors with certified service capabilities, though direct procurement from manufacturers is gaining share in pharmaceutical quality control segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The thermogravimetric analyzer market functions as a stable compounder anchored by regulatory mandates that perpetuate replacement demand regardless of macroeconomic cyclicality. ICH Q1A stability testing requirements and REACH substance registration frameworks institutionalize thermal characterization as non-discretionary expenditure.
For Market Incumbents: Cement precision advantages through captive sensor manufacturing investments that sustain microbalance resolution leadership against modular platform competitors. Deepen vertical integration into high-temperature furnace configurations to defend margin position against specialized German manufacturers. Prioritize API-first software architectures that mitigate LIMS integration friction and reduce stranded capital risk for pharmaceutical laboratory customers.
For New Entrants and Emerging Players: Capture cloud-based data governance white space in North American multi-site food safety networks where centralized compliance monitoring creates service-revenue attach opportunities. Target India's PLI scheme pharmaceutical clusters in Mumbai and Hyderabad with localized assembly partnerships that bypass import duty structures. Pursue simultaneous thermal analysis platform gaps in contract research organizations seeking capital footprint reduction.
For Investors and Strategic Acquirers: Laboratory instrumentation conglomerates with existing thermal analysis portfolios are the most active acquirer in this space, seeking software integration capabilities and regional service networks. The 5-10 year viability window favors precision subcomponent specialists with defensible manufacturing know-how in microbalance fabrication. Monitor CDSCO and NMPA documentation requirement tightening as inflection indicators for accelerated procurement in Indian and Chinese pharmaceutical clusters.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microbalance Manufacturing | Captive sensor production sustains resolution advantages against modular competitors in pharmaceutical segments. |
| API-First Software Architecture Development | LIMS interoperability reduces stranded capital risk as laboratory information systems evolve toward open data standards. |
| Cloud-Based Data Governance Platform Launch | Centralized thermal data repositories enable multi-site food safety compliance monitoring across North American networks. |
| High-Temperature Furnace Configuration Expansion | Specialized ceramics research demand in German materials science institutes sustains replacement cycle premiums. |
| Regional Service Network Partnership | Localized calibration and maintenance capabilities reduce instrument downtime below acceptable thresholds for high-throughput facilities. |
Research Methodology
Coverage spans the United States, Germany, Japan, India, and China, with primary inputs from each region's pharmaceutical manufacturing belts and materials science research corridors. The analysis combines primary interviews with thermal analysis specialists, laboratory procurement managers, regulatory affairs directors at instrument manufacturers, and university core facility directors with secondary validation from FDA guidance documents, ECHA REACH substance registrations, ISO 11358 calibration protocols, and SEC filings from listed instrumentation companies. Bottom-up instrument shipment tracking and top-down research expenditure allocation models were triangulated to establish market sizing.
Granularity-level modeling disaggregated revenue across product type, end user, technology, and delivery mode dimensions, with additional segmentation by regional regulatory cluster and certification tier. CAGRs were derived through regression analysis of historical procurement patterns against regulatory mandate implementation timelines. Forecast inputs incorporated ICH Q1A enforcement intensity, PLI scheme localization incentives, and ceramics research funding trajectories without specifying annual milestones.
Platinum price volatility, thermocouple supply disruptions, and API-first LIMS migration pace are the dominant revision risks that could alter trajectory assumptions. Stakeholders should weight assumptions against their own operating context and instrument replacement cycle visibility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Laser Probe Market
Analytical Instruments
TDLAS Moisture Analyzers Market
Analytical Instruments
Global Laboratory Electronic Balance Market
Analytical Instruments
Digital Multichannel Analyzer Market
Analytical Instruments
Coating Thickness Measurement Instruments Market
Analytical Instruments
Laser-Based Gas Analyzers Market
Analytical Instruments
Modular Instruments Market
Analytical Instruments
EPR (ESR) Spectrometer Market
Analytical Instruments
Handheld Laser Measuring Instrument Market
Analytical Instruments
Near-Infrared Spectroscopy Market
Analytical Instruments
Surface Plasmon Resonance Instrument Market
Analytical Instruments
Semiconductor X-Ray Diffractometers Market
Analytical Instruments
Global Fixed Zirconia Oxygen Analyzer Market
Analytical Instruments
Automatic Polarimeter Market
Analytical Instruments
Automated Microplate Handling Systems Market
Analytical Instruments
Europe Mass Spectroscopy Market