
 Laser Probe Market | 2026-2036
Laser Probe Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Probe Market Outlook
Market Context
Capital-intensity divergence between integrated manufacturers and probe specialists is rotating competitive dynamics across the Laser Probe Market. Bausch & Lomb Incorporated leverages backward integration into optical fiber sourcing to sustain margin stability across ophthalmology channels. Iridex Corporation anchors its position through specialized R&D intensity in photocoagulation probe architectures. Lumenis Ltd. competes by extending manufacturing scale across multiple clinical laser platforms.
Technical Definition and Segment Structure
A laser probe is a fiber-optic or free-space delivery device that channels coherent light from a laser source to a target material or tissue, typically operating at wavelengths from ultraviolet through near-infrared with core diameters ranging from 50 to 1000 micrometers depending on power density requirements. Its primary industrial and commercial purpose spans precision material processing, non-destructive testing, and minimally invasive surgical interventions where controlled energy deposition determines functional outcomes. Optical fiber probes occupy the largest installed base across manufacturing facilities due to standardized connector interfaces and established replacement cycles, while Raman spectroscopy probes represent the fastest-expanding technology segment as pharmaceutical quality control mandates tighten. Handheld probes concentrate margin pools in healthcare institutions where ergonomic design and disposable sheath compatibility command pricing premiums over benchtop configurations.
Regulatory Environment
FDA 510(k) pathways govern U.S. market entry for surgical laser probes, while EU MDR and CE marking requirements impose expanded clinical evidence burdens on European manufacturers. Japan's PMDA maintains distinct biocompatibility testing protocols for fiber materials contacting ocular tissue. Stakeholders must monitor evolving harmonization gaps between FDA and PMDA sterilization validation standards to avoid duplicated compliance expenditures.
Market Dynamics
EU MDR compliance timelines and FDA 510(k) pathway compression are forcing manufacturers to front-load clinical evidence generation, reshaping capital allocation across surgical laser probe development cycles.
Growth Catalysts
- Fiber-coupled probe adoption:Healthcare institutions in Germany and Japan are expanding procurement of these devices for retinal surgery, driven by precision requirements in ophthalmology.
- EU MDR harmonization pressure:Expanded clinical evidence mandates are accelerating consolidation among manufacturers capable of absorbing regulatory compliance costs.
- Raman spectroscopy probe demand:Pharmaceutical quality control mandates are tightening across manufacturing facilities, pulling specialized probe configurations into quality assurance workflows.
Market Restraints
- Optical fiber input concentration:Specialized silica and fluoride glass supply chains concentrate among Japanese and German specialty chemical producers, exposing margin stability to geographic sourcing risk.
- PMDA sterilization validation:Japan's distinct biocompatibility testing protocols for fiber materials contacting ocular tissue create duplicated compliance expenditures for multinational manufacturers.
- Benchtop configuration substitution:Lower-cost stationary laser delivery systems threaten handheld probe pricing premiums in research laboratory settings.
Strategic Opportunities
- Disposable sheath compatibility:Ergonomic handheld probe designs commanding pricing premiums in healthcare institutions create white space for single-use accessory ecosystems.
- ISO 13485 convergence:Harmonization between FDA and international quality management standards is compressing certification timelines for manufacturers with existing medical device portfolios.
- Photocoagulation architecture specialization:Convergence of diode laser sources with adaptive optics is opening surgical applications beyond traditional retinal intervention.
Industry Challenges
- Fiber optic splicing expertise scarcity:Precision alignment of sub-100 micrometer core diameters requires specialized technician training that outpaces workforce development in manufacturing hubs.
- Legacy laser platform integration:Connector interface standardization gaps between established surgical laser systems and next-generation probe architectures force costly adapter development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Probe Market |
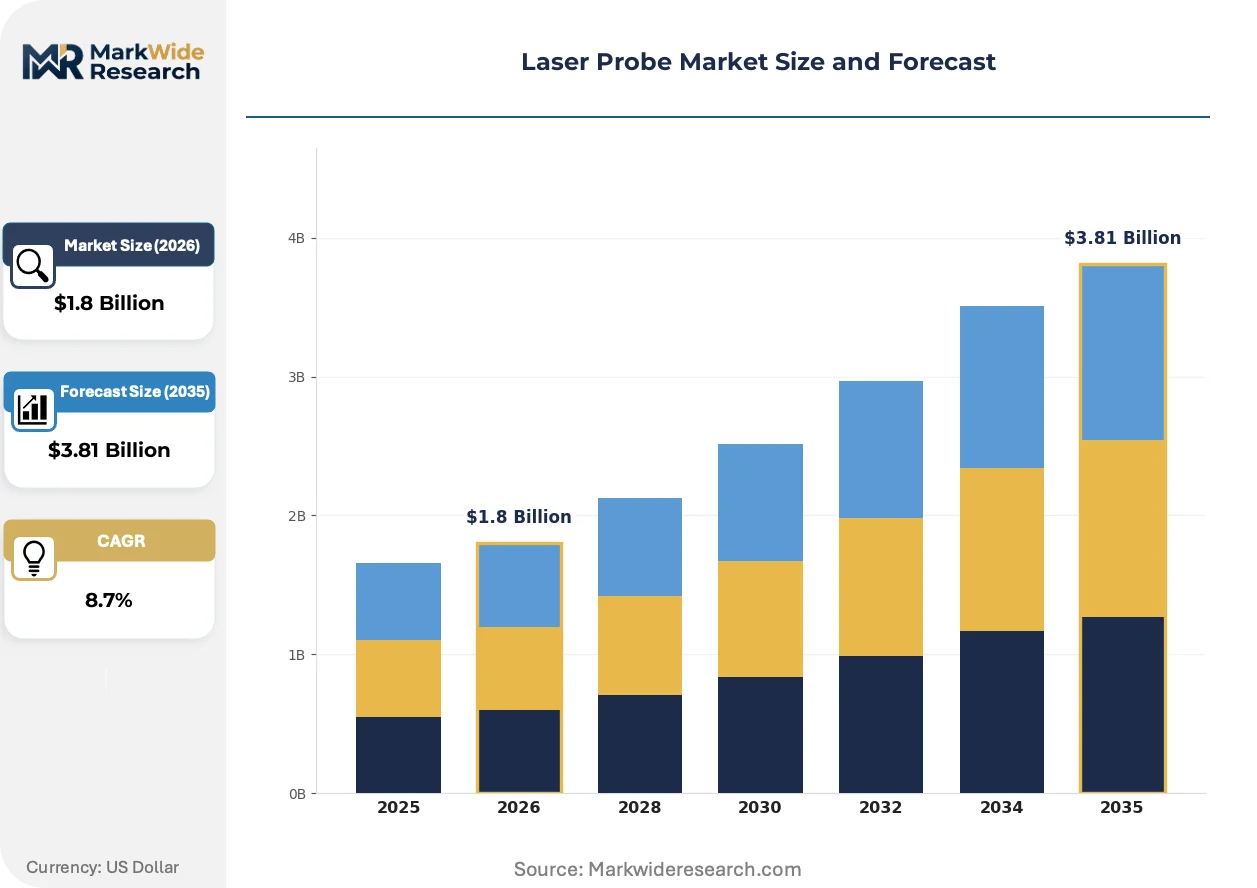
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Fiber Probes, Handheld Probes, Fiber-Coupled Probes, Multimode Probes Technology: Time-Domain Reflectometry, Frequency-Domain Reflectometry, Laser-Induced Breakdown Spectroscopy, Raman Spectroscopy End User: Manufacturing Facilities, Research Laboratories, Healthcare Institutions, Educational Institutes Application: Material Characterization, Surface Inspection, Biomedical Applications, Environmental Monitoring |
| Companies Covered | Bausch & Lomb Incorporated, REIMERS & JANSSEN GmbH, Iridex Corporation, Transonic, ADInstruments, Lumenis Ltd., FCI, OphthalMed LLC, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Probe Market Strategic Shifts
Probe architecture evolution is compressing replacement cycles while regulatory evidence burdens are redistributing competitive advantage toward vertically integrated manufacturers with captive clinical trial capabilities.
Multicore fiber technology is bifurcating surgical laser probe design paradigms. These structures enable simultaneous diagnostic imaging and therapeutic energy delivery through single insertion points. Ophthalmology clinics in the United States and Japan are piloting these configurations for combined optical coherence tomography guidance with photocoagulation. The technology is bifurcating procurement patterns between premium integrated systems and modular upgrade paths.
EU MDR Article 10 technical documentation requirements are expanding clinical evaluation obligations for Class IIa surgical devices. Manufacturers must now submit systematic literature reviews and post-market surveillance plans prior to CE marking renewal. European probe specialists with limited quality management infrastructure face disproportionate compliance cost absorption relative to diversified medical device conglomerates.
After-sales service unbundling is reshaping buyer-supplier relationships in research laboratory segments. Institutions are negotiating probe-only procurement separate from maintenance contracts and calibration services. This pattern concentrates in German academic medical centers with centralized biomedical engineering departments capable of in-house optical alignment verification.
Laser Probe Market Segmentation
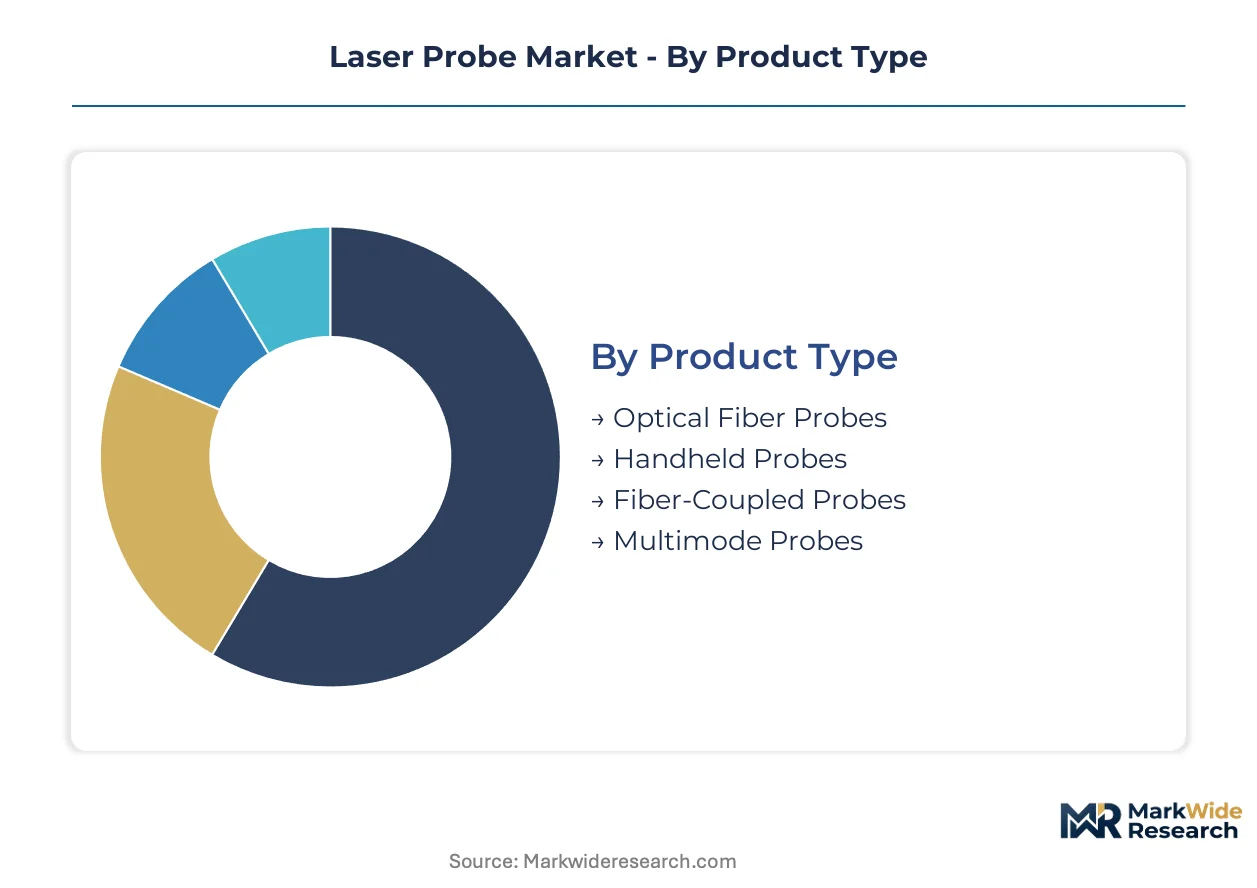
Laser probe procurement channels diverge sharply by segment. Healthcare institutions favor handheld and fiber-coupled configurations through specialized surgical distributors, while manufacturing facilities source optical fiber probes via industrial automation channels. Research laboratories drive multimode and spectroscopy probe demand through direct OEM relationships.
Product Type:
Channel mix varies dramatically across probe configurations. Handheld probes flow through medical device distributors with bundled service contracts. Optical fiber probes move through industrial supply chains with standardized connector specifications.
- Optical Fiber Probes:Silica-core delivery devices with standardized SMA or FC connector interfaces dominate manufacturing facility procurement for material processing and welding applications. Demand concentrates in German automotive component plants where fiber replacement cycles align with preventive maintenance schedules.
- Handheld Probes:Ergonomic pistol-grip or pen-style housings designed for intraoperative manipulation command premium pricing in ophthalmology clinics. Procurement in United States academic medical centers increasingly separates device purchase from disposable sheath supply agreements.
- Fiber-Coupled Probes:Pre-aligned assemblies integrating delivery fiber with focusing optics serve diode and solid-state laser systems in Japanese retinal surgery suites.
- Multimode Probes:Large-core designs tolerating higher power densities find application in industrial cutting systems across German metal fabrication facilities.
By volume, optical fiber probes lead. By growth pace, fiber-coupled probes are climbing the fastest.
Technology:
Cost tier stratification separates mature reflectometry methods from emerging spectroscopy platforms. Time-domain systems occupy economy positioning. Raman configurations command premium pricing tied to pharmaceutical compliance mandates.
- Time-Domain Reflectometry:Pulsed laser-based fault location in fiber optic cables represents established infrastructure for telecommunications maintenance. Deployment concentrates in legacy network operations where capital replacement cycles extend beyond ten years.
- Raman Spectroscopy:Inelastic light scattering detection enables molecular fingerprinting without sample preparation, driving adoption in United States pharmaceutical quality control laboratories facing FDA process analytical technology mandates.
- Frequency-Domain Reflectometry:Continuous-wave modulation techniques offer improved spatial resolution for submarine cable fault location in Japanese coastal infrastructure.
- Laser-Induced Breakdown Spectroscopy:Plasma emission analysis supports rapid elemental screening in German scrap metal sorting facilities.
Time-domain reflectometry holds the largest installed base. Raman spectroscopy is gaining share fastest.
End User:
Customer type determines margin structure and purchasing authority concentration. Healthcare institutions centralize procurement through value analysis committees. Manufacturing facilities delegate to plant engineering.
- Healthcare Institutions:Ophthalmology clinics and ambulatory surgery centers in Japan and Germany drive fiber-coupled probe procurement for photocoagulation procedures. PMDA and EU MDR compliance requirements filter supplier qualification to established medical device manufacturers.
- Manufacturing Facilities:Automotive, electronics, and metal processing plants in Germany represent volume demand for optical fiber probes integrated with automated welding and marking systems.
- Research Laboratories:University and government facilities in the United States source specialized multimode and spectroscopy probes through National Science Foundation equipment grants.
- Educational Institutes:Technical training programs in Japan acquire entry-level reflectometry systems for photonics curriculum.
Manufacturing facilities generate highest unit volumes. Healthcare institutions deliver steepest expansion trajectory.
Application:
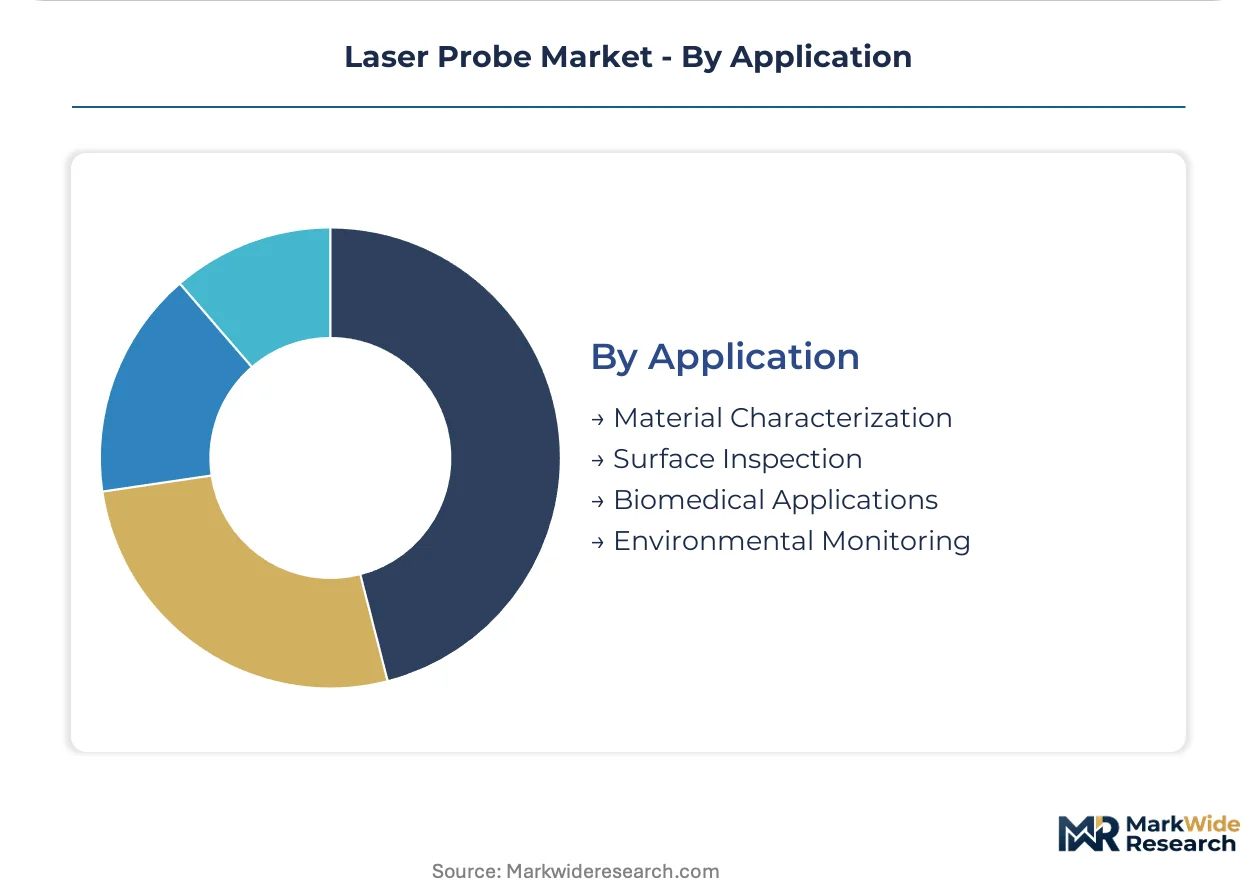
Application maturity separates established industrial quality control from emerging biomedical frontiers. Surface inspection and material characterization represent stable replacement demand. Biomedical applications attract venture funding for novel probe architectures.
- Biomedical Applications:Retinal photocoagulation, dermatological lesion treatment, and interstitial thermotherapy require sterile-compatible probe designs with precise energy deposition control. Japanese ophthalmology clinics pilot multicore fiber configurations combining diagnostic imaging with therapeutic delivery.
- Material Characterization:Grain structure analysis and coating thickness measurement in German steel production facilities drive Raman and LIBS probe deployment.
- Surface Inspection:Weld seam verification and coating defect detection support optical fiber probe replacement cycles in automotive assembly plants.
- Environmental Monitoring:Remote sensing and water quality analysis applications in United States regulatory compliance programs utilize specialized probe configurations.
Material characterization leads by current revenue. Biomedical applications show the fastest growth pace.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in laser probe components tilt toward net importing in biomedical applications while manufacturing-oriented probe categories generate surplus positions in German and Japanese production hubs.
United States
FDA 510(k) clearance pathways compress product launch timelines for surgical probe manufacturers targeting ophthalmology clinics. Academic medical centers in Boston and the Research Triangle pilot multicore fiber configurations for combined diagnostic-therapeutic applications. Procurement concentration in Medicare-reimbursed ambulatory surgery centers filters supplier qualification to established device manufacturers with captive clinical trial infrastructure.
Germany
EU MDR Article 10 technical documentation requirements expand clinical evaluation obligations for Class IIa surgical devices entering Baden-Württemberg and Bavaria manufacturing corridors. Automotive component plants in Stuttgart and Munich drive optical fiber probe demand for automated welding systems. Fiber replacement cycles align with preventive maintenance schedules in metal fabrication facilities concentrated along the Rhine-Ruhr industrial belt.
Japan
PMDA sterilization validation protocols for fiber materials contacting ocular tissue create compliance barriers for multinational manufacturers without localized biocompatibility testing infrastructure. Retinal surgery suites in Tokyo and Osaka expand procurement of fiber-coupled probes for photocoagulation procedures. METI funding programs support domestic specialty chemical producers maintaining concentrated supply positions in silica and fluoride glass input chains.
China
NMPA medical device registration pathways for imported laser probes extend review timelines relative to domestic manufacturers with established quality management certifications. Yangtze River Delta electronics assembly plants source optical fiber probes for precision marking applications. Shanghai and Shenzhen research institutes acquire Raman spectroscopy configurations through National Natural Science Foundation equipment grants.
Switzerland
Swissmedic conformity assessment procedures for active implantable and surgical devices maintain stringent evidentiary standards for probe manufacturers seeking market entry. Precision optics clusters in the Lake Geneva region and Zurich host contract manufacturers supplying fiber alignment subassemblies to German medical device OEMs. Federal procurement frameworks for university hospital networks concentrate demand evaluation through centralized value analysis committees.
Laser Probe Market Competitive Environment
Concentration sits with diversified medical device conglomerates and specialized ophthalmology equipment manufacturers rather than industrial automation suppliers. Three to five entities control the majority of surgical probe revenue pools through backward integration into optical fiber sourcing or captive R&D intensity in photocoagulation architectures. Competitive moves cluster around M&A absorption of fiber splicing expertise and strategic partnerships with diode laser source manufacturers.
Within the diversified medical device tier, Bausch & Lomb Incorporated and Novartis AG exemplify conglomerate positioning through medical device portfolio breadth. Among specialized probe manufacturers, Iridex Corporation and Lumenis Ltd. occupy positions defined by surgical laser platform focus. REIMERS & JANSSEN GmbH represents German precision engineering origin through its GmbH structure. These entities anchor competitive dynamics without exclusive segment lock-in.
| Leading Market Players |
|---|
| Bausch & Lomb Incorporated |
| REIMERS & JANSSEN GmbH |
| Iridex Corporation |
| Transonic |
| ADInstruments |
| Lumenis Ltd. |
| FCI |
| OphthalMed LLC |
| Novartis AG |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day optical fiber lead times from Japanese and German specialty chemical producers concentrate pricing power upstream while compressing margin buffers for probe assemblers lacking backward integration into silica and fluoride glass sourcing.
Pricing Analysis
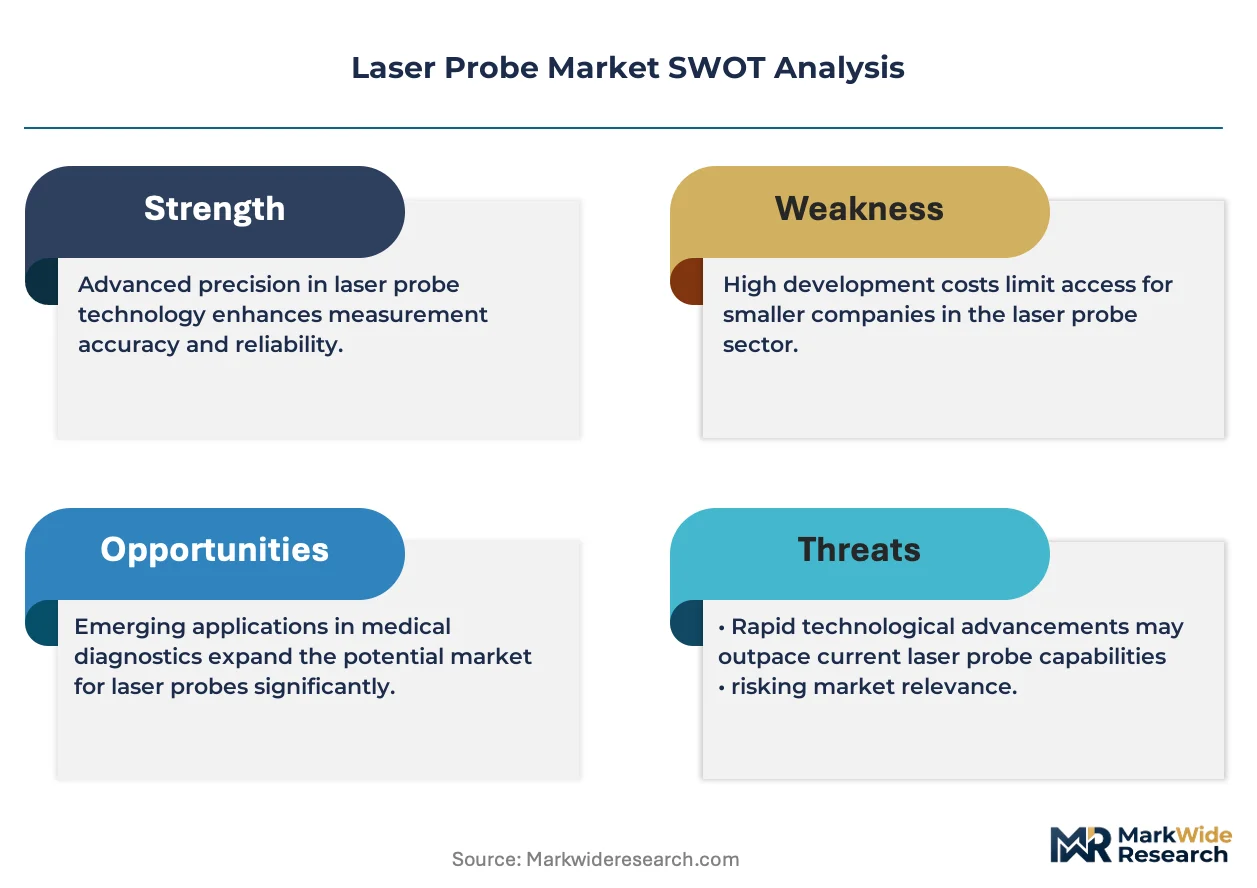
Configured-to-order pricing for fiber-coupled surgical probes commands 40-60% premiums over standard optical fiber probe configurations. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA 510(k) certification tier and ISO 13485 quality management maturity. Pricing pressure stems from EU MDR compliance cost absorption forcing margin compression among non-integrated manufacturers. Research laboratories exhibit highest price sensitivity due to after-sales service unbundling, while Japanese ophthalmology clinics show lowest sensitivity given PMDA-validated supplier qualification constraints.
Supply Chain Analysis
Strategic stockpiling of specialty silica and fluoride glass inputs dominates procurement behavior among German and Japanese probe manufacturers facing single-source vulnerability in optical fiber precursor supply. Raw material dependencies center on high-purity silica from Japanese producers, fluoride glass from German specialty chemical corridors, and precision splicing equipment from Swiss precision optics clusters. Tariff exposure on Chinese-sourced connector hardware creates downstream cost volatility. Distribution runs through medical device distributors for healthcare channels and industrial automation suppliers for manufacturing segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fiber optic splicing expertise scarcity constrains manufacturing scale-up across all tiers, making technician training infrastructure and captive alignment capabilities the decisive competitive moat.
For Market Incumbents: Consolidate fiber splicing expertise through targeted acquisition of German and Japanese precision alignment specialists before workforce development gaps widen. Deepen backward integration into optical fiber sourcing to defend margin stability against silica supply concentration. Prioritize captive clinical trial infrastructure for EU MDR Article 10 compliance acceleration.
For New Entrants and Emerging Players: Differentiate on disposable sheath compatibility for ergonomic handheld probe configurations where incumbent accessory ecosystems remain underdeveloped. Target United States research laboratories with unbundled probe-only procurement patterns. Pursue direct OEM relationships with National Science Foundation grant-funded institutions bypassing distributor margin extraction.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regulatory evidence burdens disproportionately burden non-integrated probe specialists relative to diversified medical device conglomerates. Acquisition target archetype: mid-tier European manufacturers with quality management infrastructure gaps but established CE marking histories. Watch FDA-PMDA sterilization validation harmonization progress as inflection indicator for compliance cost redistribution.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Fiber Sourcing | Mitigates Japanese-German supply concentration and stabilizes input cost volatility for probe assemblers. |
| EU MDR Article 10 Compliance Investment | Compresses CE marking renewal timelines and filters competitor qualification among European probe specialists. |
| Multicore Fiber Architecture Development | Captures premium positioning in Japanese and United States ophthalmology clinics piloting diagnostic-therapeutic convergence. |
| Disposable Sheath Ecosystem Buildout | Creates recurring revenue attachment to handheld probe installations in healthcare institutions separating device and accessory procurement. |
| Precision Splicing Technician Training Programs | Addresses workforce development gaps that outpace manufacturing hub expansion in fiber alignment capabilities. |
Study Parameters
Cross-validation between primary interviews with ophthalmology clinic procurement directors, biomedical engineering heads at academic medical centers, and fiber optic splicing technicians anchors the qualitative findings. Secondary validation draws from FDA 510(k) clearance databases, EU MDR technical documentation filings, PMDA sterilization validation records, and German automotive component plant maintenance schedules. Bottom-up demand modeling from probe replacement cycles and top-down market sizing from laser system OEM shipment data complete the triangulation.
Sensitivity analysis across fiber-coupled, handheld, and optical fiber probe configurations tests forecast robustness over the projection horizon. Segmentation dimensions modeled include product architecture, end-user procurement authority concentration, application maturity, and regional regulatory cluster. CAGRs derive from replacement cycle compression rates and clinical evidence burden trajectories. Industry-specific inputs incorporate EU MDR harmonization timelines and PMDA biocompatibility protocol evolution.
Material uncertainties — regulatory pathway delays, specialty glass supply disruptions, sterilization standard divergence — sit outside the modeled envelope. Forecasts reflect assumptions about compliance cost absorption capacity and technician training pipeline throughput. Revision becomes warranted when FDA-PMDA harmonization progress or multicore fiber adoption rates cross threshold inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Europe Handheld Spectrum Analyzer Market
Analytical Instruments
Life Science and Analytical Instruments Market
Analytical Instruments
Global TOC Analyzer Market
Analytical Instruments
Europe Surface Analysis Market
Analytical Instruments
Digital Multichannel Analyzer Market
Analytical Instruments
Global Q-TOF Mass Spectrometry Market
Analytical Instruments
Global Fluorescence Spectrophotometer Market
Analytical Instruments
Ultraviolet (UV) Analyzer Market
Analytical Instruments
Global Particle Counters Market
Analytical Instruments
EPR (ESR) Spectrometer Market
Analytical Instruments
Energy Dispersive X-Ray Spectrometer Market
Analytical Instruments
Elemental Analyzer Market
Analytical Instruments
Mass Spectroscopy Market
Analytical Instruments
Surface Plasmon Resonance (SPR) System Market
Analytical Instruments
Infrared Thermometers Market
Analytical Instruments
Flame Ionization Detectors Market