
 Benchtop Ph Meters Market | 2026-2036
Benchtop Ph Meters Market Size, Share, and Industry Trends Forecast 2026-2036
Benchtop Ph Meters Market Analysis
ISO 17025 laboratory accreditation is unwinding competitive dynamics across the benchtop pH meter landscape, favoring suppliers with documented calibration traceability and certified quality management systems. Mettler Toledo leverages its analytical balance heritage to anchor premium positioning in pharmaceutical QC laboratories. Hanna Instruments competes aggressively on price-performance ratios in educational and environmental testing segments. Metrohm sustains technical credibility through integrated titration-pH workflows that reduce operator training burdens.
Benchtop pH meters are electrochemical instruments that measure hydrogen ion activity in aqueous solutions, typically achieving resolution of 0.01 pH units with temperature compensation via integrated ATC probes. These devices serve as foundational quality control tools across process industries where solution chemistry directly affects product specifications, safety margins, and regulatory compliance outcomes. Digital meters dominate installed bases due to microprocessor-driven stability algorithms and data logging capabilities that analog architectures cannot replicate. Glass electrode technology leads in absolute volume terms, though ISFET sensors are gaining traction in food industry applications where glass breakage risk and maintenance frequency drive total cost of ownership calculations. Water testing applications command the largest share of end-user demand, reflecting persistent regulatory pressure on municipal utilities and industrial discharge permits.
EPA Method 150.1 and ISO 10523 define permissible measurement uncertainty and calibration protocols that shape product design priorities and aftermarket service revenue streams. FDA 21 CFR Part 11 compliance requirements in pharmaceutical manufacturing push vendors toward sealed electrode housings, audit-trail software, and electronic signature capture. EMA's GMP Annex 15 qualification guidelines extend these demands across European production facilities. Stakeholders must weigh electrode replacement economics against emerging solid-state sensor platforms that promise reduced drift and extended calibration intervals.
Market Dynamics
ISO 17025 accreditation requirements are compressing vendor qualification timelines while amplifying demand for documented calibration traceability chains across pharmaceutical and environmental testing laboratories.
Growth Catalysts
- EU Drinking Water Directive:Tightened parametric compliance mandates in Germany, France, and the Netherlands are accelerating municipal water testing laboratory instrument refresh cycles.
- CDSCO pharmaceutical quality control:Mandatory GMP compliance across Indian generic drug manufacturing is driving systematic replacement of analog pH meters with digital units featuring audit-trail capabilities.
- ISFET solid-state sensors:Food processing facilities are adopting chip-based pH measurement platforms to eliminate glass electrode breakage risks in high-throughput production environments.
Market Restraints
- Electrode supply concentration:Specialized glass membrane manufacturing concentrates in Germany and Japan, exposing buyers to extended lead times during supply disruptions.
- Reference electrolyte cost volatility:Potassium chloride and silver chloride precursor prices fluctuate with agricultural and photographic chemical demand cycles.
- Calibration labor intensity:FDA 21 CFR Part 11 compliance requires documented two-point calibration protocols that consume operator hours and consumables budgets.
Strategic Opportunities
- Brazilian environmental monitoring:ANVISA and state-level environmental agencies are expanding laboratory accreditation programs that mandate digital pH measurement infrastructure.
- Titration-pH workflow integration:Automated sample handling systems that combine potentiometric titration with inline pH monitoring are reducing training burdens in contract testing laboratories.
- Cloud-connected calibration management:Subscription-based remote monitoring services are replacing on-site service contracts for distributed pharmaceutical manufacturing networks.
Industry Challenges
- Metrology technician scarcity:ISO 17025-accredited laboratories face recruitment gaps for personnel capable of executing uncertainty calculations and managing reference standard chains.
- Legacy LIMS integration:Digital benchtop meters with proprietary data formats require middleware development to connect with established laboratory information management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Benchtop Ph Meters Market |
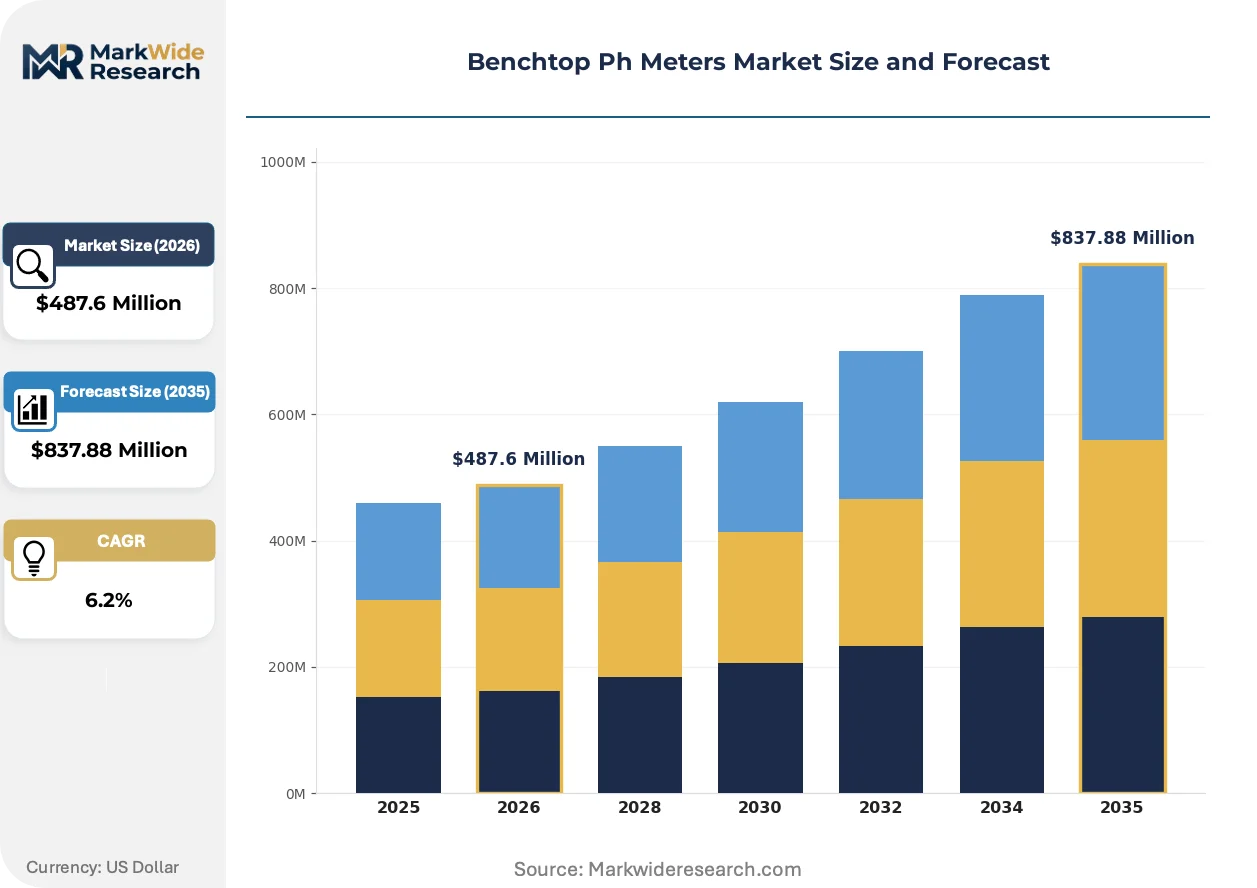
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $837.88 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Meters, Digital Meters, Portable Meters, Specialty Meters End User: Laboratories, Educational Institutions, Environmental Agencies, Food Industry Technology: Glass Electrode, ISFET, Combination Electrode, Electrochemical Application: Water Testing, Soil Testing, Industrial Processes, Chemical Analysis |
| Companies Covered | Mettler Toledo, Thermo Fisher Scientific, Hanna Instruments, HORIBA, Metrohm, Agilent Technologies, Hach Company, Danaher Corporation, Xylem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Benchtop Ph Meters Market Emerging Trajectories
Electrode architecture, regulatory data integrity mandates, and procurement centralization are converging to redefine competitive differentiation beyond base measurement accuracy specifications.
ISFET solid-state pH sensors are displacing traditional glass electrodes in food and beverage processing lines where frequent CIP/SIP thermal cycling degrades glass membrane performance. Dairy cooperatives in Wisconsin and cheese manufacturers in Wisconsin are deploying chip-based probes to eliminate production downtime from electrode replacement. This displacement is compressing aftermarket revenue streams for traditional electrode suppliers while opening sensor replacement markets to semiconductor fabrication specialists.
EMA's GMP Annex 15 qualification guidelines are extending FDA-style data integrity requirements across European pharmaceutical production facilities. Manufacturers must now implement electronic signature capture and audit trails for all critical quality control measurements including pH. German and Swiss contract manufacturing organizations are prioritizing benchtop meters with sealed firmware architectures that prevent undocumented configuration changes.
Consolidated procurement through group purchasing organizations is concentrating buying power among multi-site laboratory networks. University research consortia and hospital systems in the United States are negotiating enterprise pricing agreements that bundle instruments, electrodes, and calibration services under single-supplier contracts. This concentration is marginalizing smaller regional distributors and favoring vendors with direct service infrastructure in major metropolitan clusters.
Benchtop Ph Meters Market Segmentation
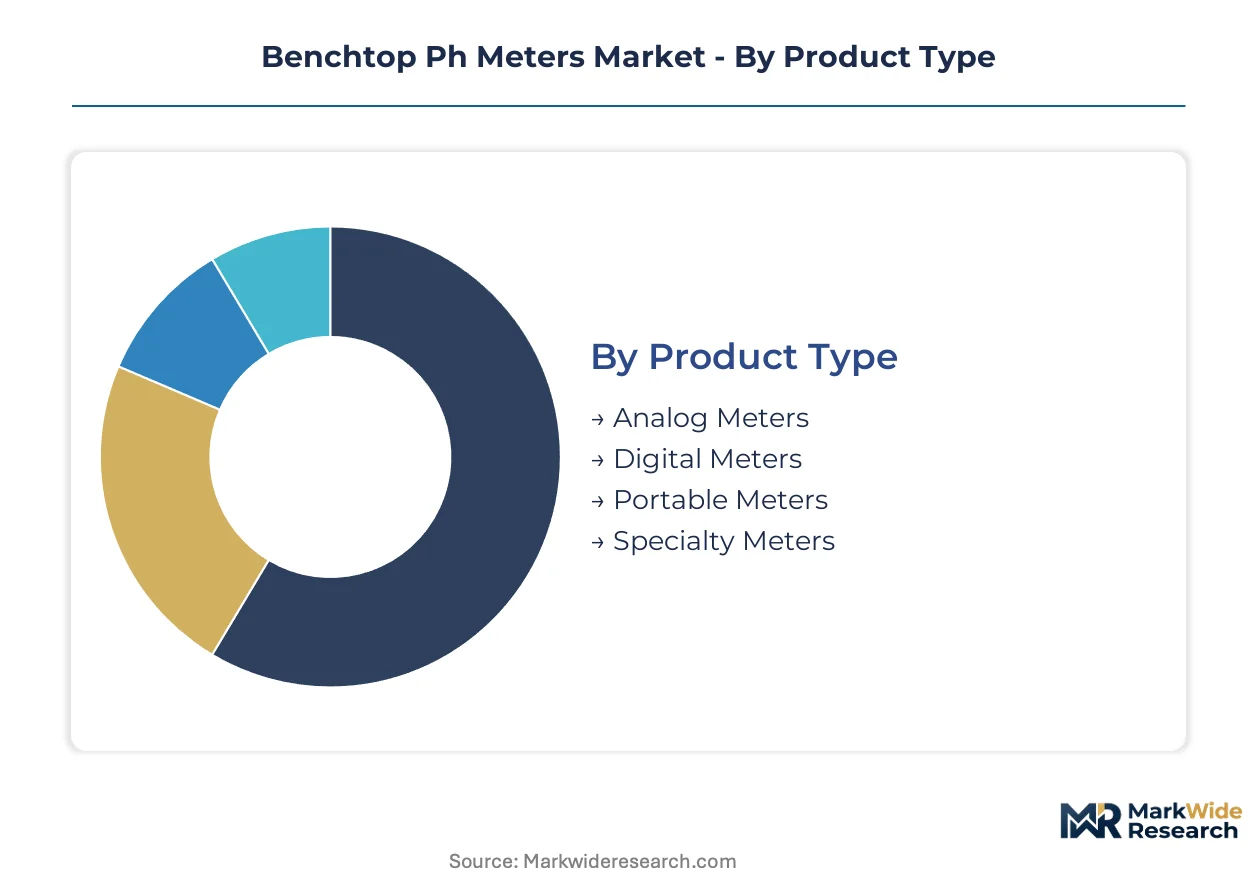
Benchtop pH meter procurement patterns diverge sharply across user environments, with pharmaceutical QC laboratories prioritizing audit-trail compliance while food processors optimize for thermal cycling durability. Understanding these segment boundaries clarifies where technology investments concentrate and which specifications command pricing premiums.
Product Type:
Margin pools concentrate in digital architectures where firmware-sealed configurations and calibration management software sustain recurring service revenue streams.
- Digital Meters:Microprocessor-driven stability algorithms enable 0.01 pH resolution with integrated ATC compensation and data logging. Demand concentrates in CDSCO-regulated pharmaceutical laboratories across India where FDA 21 CFR Part 11 compliance mandates audit-trail capabilities and electronic signature capture.
- Specialty Meters:Purpose-built instruments for high-purity water or extreme pH ranges incorporate specialized electrode housings and temperature compensation curves. German water testing laboratories expanding under tightened EU Drinking Water Directive parametric requirements drive procurement of these precision-focused units.
- Analog Meters:Simple needle-display instruments persist in budget-constrained educational settings and legacy industrial installations.
- Portable Meters:Battery-powered field units sacrifice resolution for mobility in environmental sampling and remote site monitoring.
The dominant share belongs to Digital Meters, while Specialty Meters is closing the gap fastest.
End User:
Volume concentration tracks regulatory enforcement intensity, with accredited laboratories representing the core installed base refresh cycle.
- Laboratories:ISO 17025-accredited analytical facilities require documented calibration traceability chains and certified quality management systems. Municipal water testing laboratories in Germany, France, and the Netherlands are accelerating instrument replacement under tightened EU Drinking Water Directive mandates.
- Food Industry:Dairy cooperatives in Wisconsin and cheese manufacturers deploy ISFET solid-state sensors to eliminate production downtime from glass electrode breakage during CIP/SIP thermal cycling.
- Environmental Agencies:State-level regulators in Brazil expanding ANVISA-mandated laboratory accreditation programs drive digital infrastructure procurement.
- Educational Institutions:University research consortia negotiate enterprise pricing agreements bundling instruments, electrodes, and calibration services.
Laboratories command the dominant share, though Food Industry adoption is expanding most quickly as solid-state platforms mature.
Technology:
Electrode architecture choices directly determine total cost of ownership calculations across high-throughput production environments.
- Glass Electrode:Traditional hydrogen ion-selective membranes manufactured in Germany and Japan achieve measurement stability through established reference electrolyte chemistry. These dominate absolute volume terms despite fragility constraints in food processing applications.
- ISFET:Ion-sensitive field-effect transistor sensors fabricated through semiconductor processes eliminate breakage risk and extend calibration intervals. Food processing facilities adopt these chip-based platforms where frequent thermal cycling degrades conventional glass performance.
- Combination Electrode:Integrated reference and measuring half-cells simplify maintenance in routine industrial applications.
- Electrochemical:Broad category encompassing potentiometric and amperometric detection schemes in specialized analytical configurations.
Glass Electrode retains the dominant share, while ISFET platforms are gaining share fastest in food and beverage processing lines.
Application:
Regulatory pressure intensity varies dramatically by matrix type, with aqueous testing facing the most stringent parametric compliance requirements.
- Water Testing:EPA Method 150.1 and ISO 10523 define permissible measurement uncertainty and calibration protocols. Municipal utilities and industrial discharge permit holders across Germany, the Netherlands, and France face persistent regulatory pressure driving instrument refresh cycles.
- Industrial Processes:Chemical manufacturing and pharmaceutical production require inline and at-line pH monitoring for batch release decisions. EMA GMP Annex 15 qualification guidelines extend FDA-style data integrity requirements across European contract manufacturing organizations.
- Chemical Analysis:Research and development laboratories employ benchtop meters for formulation characterization and stability testing.
- Soil Testing:Agricultural extension services and environmental remediation contractors measure extract pH for nutrient management and contamination assessment.
Water Testing holds the dominant share, though Industrial Processes is climbing the fastest as pharmaceutical manufacturing quality control requirements tighten globally.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical quality control laboratories and municipal water testing facilities concentrate procurement across distinct national regulatory environments. Each geography presents divergent compliance timelines and infrastructure maturity levels.
Germany
Municipal water testing laboratories in Berlin, Hamburg, and the Ruhr industrial cluster are accelerating instrument replacement cycles. The EU Drinking Water Directive's tightened parametric compliance mandates drive demand for digital benchtop pH meters with documented calibration traceability. Bavarian pharmaceutical contract manufacturers under EMA GMP Annex 15 guidelines prioritize sealed firmware architectures.
India
CDSCO-mandated pharmaceutical quality control requirements are systematically displacing analog pH meters across generic drug manufacturing facilities. Mumbai-Pune and Hyderabad-Vizag pharmaceutical clusters lead instrument refresh cycles. The country's national pharmaceutical regulator enforces audit-trail capabilities and electronic signature capture for critical quality control measurements.
United States
University research consortia and hospital systems negotiate enterprise pricing agreements bundling instruments, electrodes, and calibration services. FDA 21 CFR Part 11 compliance requirements push pharmaceutical manufacturers toward cloud-connected calibration management platforms. Wisconsin dairy cooperatives deploy ISFET solid-state sensors to eliminate glass electrode breakage during CIP/SIP thermal cycling.
Brazil
ANVISA and state-level environmental agencies are expanding laboratory accreditation programs that mandate digital pH measurement infrastructure. São Paulo and Rio de Janeiro testing facilities face procurement deadlines for ISO 17025-compliant equipment. The country's national health surveillance agency drives standardization across environmental monitoring networks.
Japan
Specialized glass membrane manufacturing concentrates in Osaka and Tokyo industrial corridors, exposing buyers to extended lead times during supply disruptions. METI-supported quality infrastructure programs reinforce calibration traceability requirements across pharmaceutical and food testing laboratories. Yokohama-based analytical instrument distributors maintain direct service infrastructure for multi-site laboratory networks.
Benchtop Ph Meters Market Vendor Landscape
Player mix skews toward diversified analytical instrument conglomerates with established laboratory distribution channels. The market exhibits tiered concentration with premium positioning anchored by heritage metrology brands and aggressive price-performance competition in educational and environmental segments. Three archetypes dominate: precision measurement specialists leveraging analytical balance credibility, diversified life science conglomerates with bundled workflow solutions, and focused electrochemical instrument manufacturers competing on total cost of ownership. Strategic moves center on titration-pH workflow integration and cloud-connected calibration management services.
Among Swiss precision measurement specialists, Mettler Toledo and Metrohm occupy positions that exemplify premium-tier positioning through integrated workflow solutions. Hanna Instruments represents the focused electrochemical instrument archetype competing aggressively on price-performance ratios. These three companies anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Mettler Toledo |
| Thermo Fisher Scientific |
| Hanna Instruments |
| HORIBA |
| Metrohm |
| Agilent Technologies |
| Hach Company |
| Danaher Corporation |
| Xylem |
| Others |
Supply Flow & Price Mechanics
Specialized glass membrane manufacturing concentrates in Osaka and Tokyo industrial corridors, creating scale economies that anchor price floors for premium electrode tiers while compressing margins on standard digital meters. German and Japanese suppliers leverage captive reference electrolyte chemistry to defend premium positioning against price-aggressive competitors in educational and environmental segments.
Pricing Analysis
Cost-plus contracts with potassium chloride and silver chloride indexation dominate electrode supply agreements, exposing buyers to agricultural and photographic chemical demand cycles. Three-tier pricing structure across pharmaceutical-grade, laboratory-standard, and educational-economy levels separates audit-trail-compliant units from basic digital meters. Pricing pressure stems from consolidated procurement through university research consortia and hospital systems negotiating bundled service contracts. Educational institutions exhibit highest price sensitivity, while pharmaceutical QC laboratories prioritize calibration traceability over unit cost.
Supply Chain Analysis
Inbound logistics costs from Yokohama and Hamburg ports fluctuate with container availability on Asia-Europe trade lanes, extending lead times for specialized electrode assemblies. Glass membrane fabrication draws from German and Japanese manufacturing bases, while reference electrolyte precursors source from agricultural chemical suppliers in India and China. Single-source vulnerability concentrates in specialized glass formulations for high-purity water applications. Distribution runs through analytical instrument distributors with direct service infrastructure in major metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-connected calibration management services are expanding faster than hardware unit sales, converting capital expenditure into recurring revenue streams that improve customer lifetime value metrics across pharmaceutical manufacturing networks.
For Market Incumbents: Compound service attach rates by bundling electrode replacement subscriptions with firmware-sealed audit-trail configurations that lock out unauthorized configuration changes. Integrate titration-pH workflows to reduce operator training burdens in contract testing laboratories facing metrology technician scarcity. Defend against ISFET solid-state sensor displacement by extending calibration interval guarantees for glass electrode platforms in pharmaceutical applications where regulatory familiarity sustains incumbent preference. For New Entrants and Emerging Players: Lead with ISFET chip-based platforms targeting Wisconsin dairy cooperatives and Brazilian environmental monitoring laboratories where glass electrode breakage risk and ANVISA accreditation deadlines create procurement urgency. White-space exists in food processing CIP/SIP thermal cycling applications and state-level Brazilian testing facilities facing ISO 17025 equipment mandates. Pursue semiconductor fabrication partnerships to bypass established glass membrane supply concentration. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors electrochemical instrument specialists with cloud-connected service infrastructure over hardware-only manufacturers. Long-term viability hinges on recurring revenue attachment rates rather than unit shipment growth. Target acquisition archetypes include regional distributors with established pharmaceutical QC laboratory relationships and ISFET sensor developers with food industry validation data. Watch for EMA GMP Annex 15 enforcement intensity across European contract manufacturing organizations as inflection indicator for audit-trail compliance demand.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Calibration Management | Subscription services replace on-site contracts for CDSCO-regulated pharmaceutical networks in India. |
| ISFET Sensor Platform Development | Solid-state chips eliminate glass breakage risk in Wisconsin dairy CIP/SIP thermal cycling environments. |
| Titration-pH Workflow Integration | Automated sample handling reduces training burdens in ISO 17025-accredited contract testing laboratories. |
| Electrode Supply Backward Integration | In-house reference electrolyte production buffers potassium chloride price volatility from agricultural demand cycles. |
| Brazilian Laboratory Accreditation Expansion | ANVISA-mandated digital infrastructure procurement creates demand concentration in São Paulo and Rio de Janeiro. |
Methodological Framework
The analysis maps digital meter architectures, ISFET sensor platforms, and specialty precision instruments, each validated through laboratory directors, pharmaceutical QC managers, and environmental testing officers. Primary interviews with metrology technicians, aftermarket service heads, and analytical instrument procurement leads combined with secondary validation from EPA Method 150.1 documentation, ISO 10523 calibration protocols, and EMA GMP Annex 15 qualification guidelines. Bottom-up unit shipment estimates triangulated against top-down addressable market calculations.
Consistency checks validated volume and value outputs against customs data for electrode component trade flows and pharmaceutical capital expenditure disclosures across the analysis window. Segmentation modeling incorporated product type, end-user environment, electrode technology, and application matrix dimensions. CAGRs derived from instrument refresh cycle analysis, regulatory compliance timeline acceleration, and substitution elasticity between glass and solid-state sensor platforms.
Forecasts assume regulatory continuity in FDA 21 CFR Part 11, EMA GMP Annex 15, and CDSCO pharmaceutical quality control regimes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Global UV Spectroscopy Market
Analytical Instruments
Coating Thickness Measurement Instruments Market
Analytical Instruments
Flame Spectrometers Market
Analytical Instruments
Electron Probe Microanalyzers (EPMA) Market
Analytical Instruments
North America Analytical Instrumentation Market
Analytical Instruments
Global TOC Analyzer Market
Analytical Instruments
Digital Multichannel Analyzer Market
Analytical Instruments
Spectrometry Market
Analytical Instruments
Battery Analyzer Market
Analytical Instruments
Thermogravimetric Analyzer Market
Analytical Instruments
Asia-Pacific Dissolved Gas Analyzer Market
Analytical Instruments
X-Ray Fluorescence Analyzer Market
Analytical Instruments
Global Scanning Probe Microscopes (Spm) Market
Analytical Instruments
Lab-On-A-Chip Device Market
Analytical Instruments
Europe Handheld Spectrum Analyzer Market
Analytical Instruments
Headspace Gas Analyzers Market